
 US Over the Counter Drugs Market | 2026-2036
US Over the Counter Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
US Over the Counter Drugs Market Insights
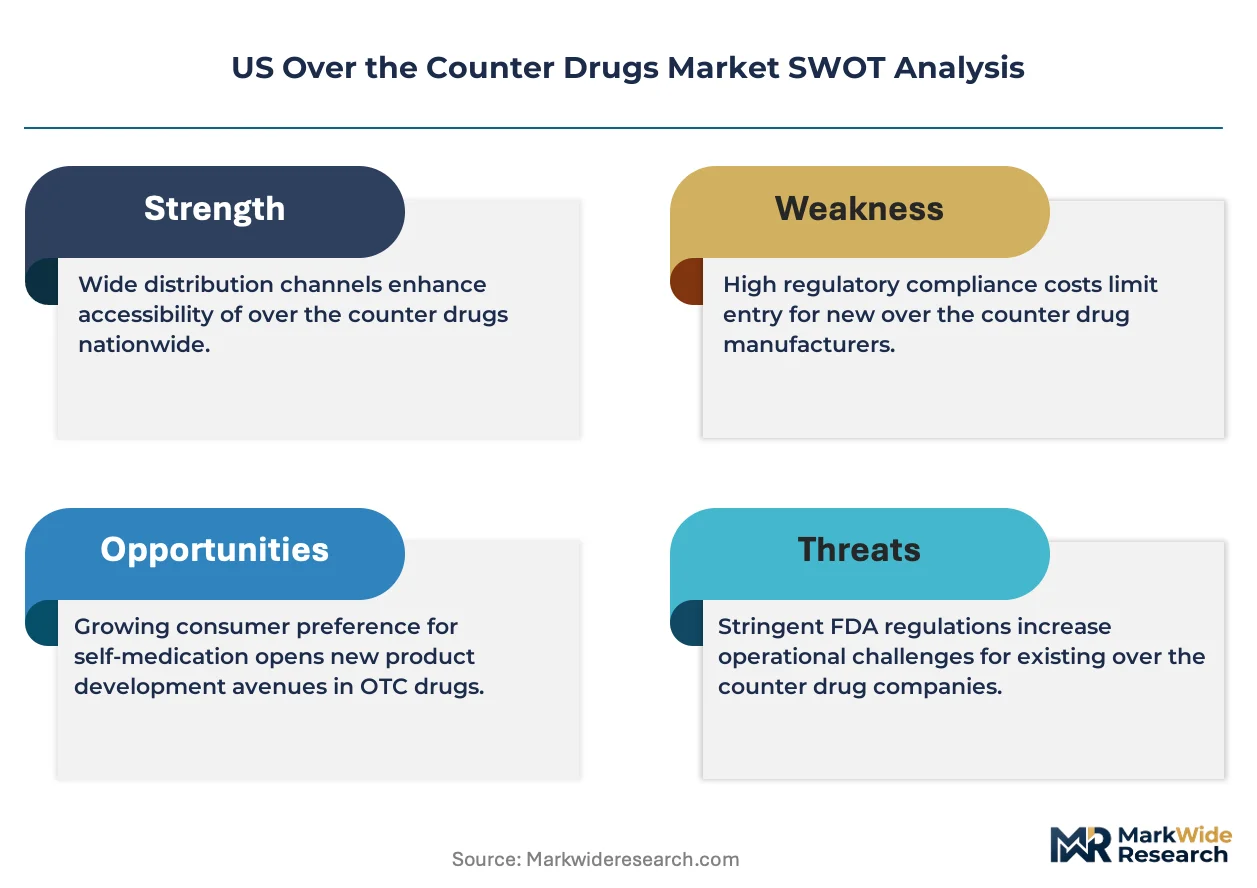
FDA OTC monograph reform is realigning the cost-of-entry calculus for new market participants by replacing the rulemaking process with administrative orders. Johnson & Johnson Services Inc. leverages its brand strength across pain relievers and digestive aids to sustain shelf presence in major retail chains. Bayer AG anchors its position through R&D intensity in aspirin-based cardiovascular OTC extensions. Sanofi S.A. competes aggressively in allergy treatments with seasonal marketing campaigns.
Over the counter drugs comprise non-prescription pharmaceutical formulations containing active ingredients such as acetaminophen, ibuprofen, loratadine, or bismuth subsalicylate, manufactured through direct compression, wet granulation, or liquid filling processes, and intended for self-diagnosed conditions without physician supervision. Pain relievers occupy the largest revenue pool due to chronic condition prevalence and repeat purchase frequency, while online retailers represent the fastest-growing distribution channel as pharmacy benefit managers and telehealth platforms steer consumers toward digital fulfillment. Cold and flu medications retain mature, weather-dependent demand patterns concentrated in Q4 and Q1 purchasing cycles.
FDA OTC monograph reform, EPA manufacturing facility standards, and state-level pharmacy board regulations collectively shape product labeling, active ingredient concentrations, and channel access requirements across the United States. These frameworks elevate compliance costs for entrants but reinforce incumbent advantages through established quality systems and legal teams. Stakeholders must monitor pending monograph finalizations and state telehealth prescribing rules to anticipate which ingredient categories will shift between prescription and OTC status.
Market Dynamics
FDA OTC monograph reform is compressing approval timelines for active ingredients while simultaneously elevating compliance infrastructure requirements, creating asymmetric advantages for established manufacturers with dedicated regulatory affairs divisions.
Growth Catalysts
- Aging demographics:Adults over 65 represent the highest per-capita OTC consumption cohort, with self-medication for chronic pain and digestive conditions driving repeat purchase cycles in suburban and rural pharmacy networks.
- Telehealth integration:State-level expansions of pharmacist prescribing authority under collaborative practice agreements are channeling symptom assessments toward OTC recommendations rather than physician referrals.
- EPA manufacturing standards:Streamlined environmental compliance pathways for OTC facilities are reducing facility upgrade costs, particularly for solid-dose tablet operations in the Southeast and Midwest.
Market Restraints
- Active ingredient supply concentration:Bulk acetaminophen and ibuprofen API production concentrates in Chinese and Indian chemical parks, exposing formulators to shipping lane disruptions and tariff volatility.
- Monograph finalization delays:Pending FDA administrative orders for sunscreen and cough-cold ingredients have frozen category innovation, forcing R&D budgets toward already-cleared therapeutic areas.
- Private label substitution:Retailer-owned brands in analgesics and antacids are capturing shelf space through identical active-ingredient positioning at 30-40% price discounts.
Strategic Opportunities
- Pharmacy desert penetration:Independent dollar stores and convenience chains in rural Texas, Mississippi, and Alabama represent underserved distribution nodes for single-unit pain reliever and allergy SKUs.
- CBD-hemp ingredient convergence:State-permitted topical formulations combining menthol with hemp-derived compounds are creating new pain relief subcategories outside federal monograph jurisdiction.
- IRA preventive care alignment:Medicare Advantage plan incentives for non-prescription chronic condition management are opening reimbursement-adjacent channels for aspirin and fiber supplement programs.
Industry Challenges
- Regulatory affairs talent scarcity:Experienced FDA submission specialists command premium salaries, constraining mid-tier manufacturers' ability to navigate monograph reform complexity.
- Legacy packaging line retrofit costs:Child-resistant compliance upgrades and sustainable material transitions require seven-figure capital commitments per facility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Over the Counter Drugs Market |
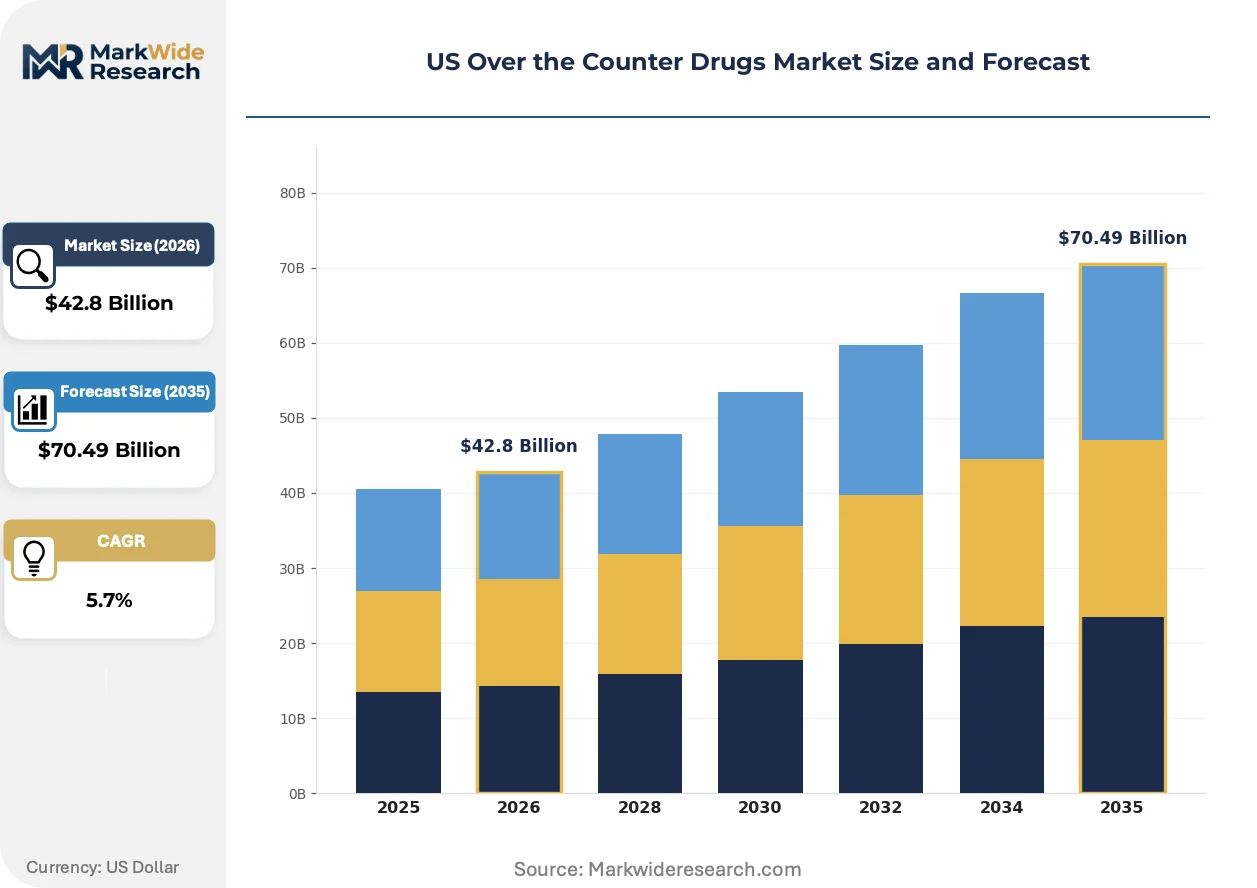
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cold & Flu Medications, Allergy Treatments, Digestive Aids Formulation: Tablets, Liquid, Capsules, Powders Distribution Channel: Pharmacies, Supermarkets, Convenience Stores, Online Retailers End User: Adults, Children, Elderly, Caregivers |
| Companies Covered | Johnson & Johnson Services Inc., Bayer AG, Sanofi S.A., GlaxoSmithKline PLC (Haleon), Pfizer Inc., Reckitt Benckiser Group plc, Kenvue Brands LLC, Novartis AG, Boehringer Ingelheim, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Over the Counter Drugs Market Trends and Innovations
Digital diagnostic tools and direct-to-consumer fulfillment models are fragmenting traditional pharmacy-centric purchase journeys, while ingredient transparency demands are reshaping formulation disclosure standards.
Continuous manufacturing technology is expanding into solid-dose OTC production, replacing batch processing with real-time quality release systems. Johnson & Johnson and Perrigo have piloted modular powder-to-tablet lines that compress changeover times from days to hours. This shift is enabling smaller production runs for regional SKUs and seasonal variants without sacrificing FDA compliance rigor.
The FDA's OTC monograph reform finalized through administrative order procedures is eliminating the notice-and-comment rulemaking bottleneck for new active ingredients. Category-specific final orders for sunscreen and cough-cold combinations remain pending, but the procedural framework has already accelerated antacid and laxative ingredient clearances. Manufacturers with pre-submission meeting histories are exploiting this pathway to secure competitive timing advantages.
Subscription-based replenishment models for chronic-use categories are displacing episodic retail purchasing among urban millennials and Gen X households. Amazon Pharmacy and CVS CarePass are bundling allergy and pain reliever auto-shipments with telehealth consultations. This pattern concentrates most visibly in coastal metropolitan markets where same-day delivery infrastructure supports just-in-time household inventory management.
US Over the Counter Drugs Market Segmentation
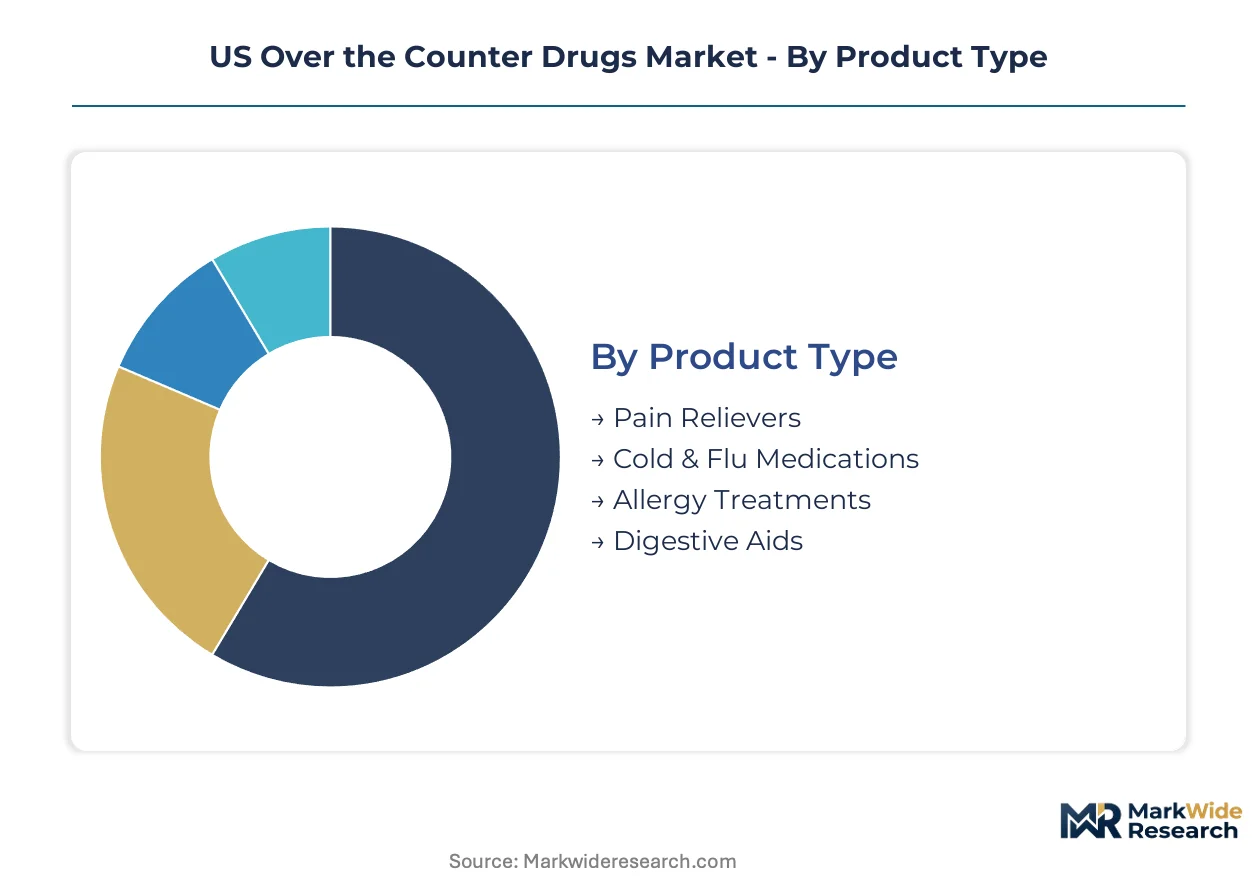
Segmentation in the US OTC drugs market reveals how formulation choices and channel strategies align with distinct consumer self-medication behaviors. Manufacturers calibrate supply chain investments based on which product-formulation-channel combinations generate repeat purchase velocity versus episodic demand spikes.
Product Type:
Active ingredient sourcing concentration in Chinese and Indian chemical parks shapes competitive dynamics across therapeutic categories, with formulators building inventory buffers differently by segment risk exposure.
- Pain Relievers:Non-prescription analgesics containing acetaminophen, ibuprofen, or naproxen sodium dominate pharmacy shelf space and household medicine cabinets. Demand concentrates in suburban and rural pharmacy networks across Texas, Florida, and North Carolina, where chronic condition prevalence and limited primary care access sustain repeat purchase cycles among aging adults.
- Cold & Flu Medications:Multi-symptom relief formulations combining decongestants, antihistamines, and cough suppressants exhibit pronounced seasonality tied to viral circulation patterns. Q4 and Q1 purchasing cycles concentrate in Midwest and Northeast metropolitan areas, where indoor congregation during winter months accelerates transmission and stockpiling behavior.
- Allergy Treatments:Second-generation antihistamines and intranasal corticosteroid sprays target seasonal and perennial allergic rhinitis.
- Digestive Aids:Antacids, H2 blockers, proton pump inhibitors, and laxatives address GERD and irregularity conditions.
Pain relievers absorb the bulk of installed capacity; online retailers are expanding most quickly into allergy and digestive subscription programs.
Formulation:
Manufacturing equipment specialization creates cost tier differentiation, with continuous processing lines commanding premium capital deployment versus batch operations.
- Tablets:Direct compression and wet granulation processes yield solid-dose products with extended stability profiles and precise dose uniformity. Southeast and Midwest production facilities concentrate output for national distribution, leveraging EPA streamlined compliance pathways to minimize facility upgrade costs.
- Liquid:Suspensions and solutions accommodate pediatric and geriatric populations with swallowing difficulties, requiring distinct filling lines and preservative systems.
- Capsules:Gelatin and vegetable-based shells encase powders or granules for taste masking and modified release.
- Powders:Effervescent and bulk formulations serve sports nutrition and rapid-dissolution applications.
Tablets command the majority of production line investments; liquid formulations are climbing fastest in pediatric and elder care segments.
Distribution Channel:
Channel access requirements vary by state pharmacy board regulations, with front-store placement versus behind-counter positioning shaping fulfillment economics.
- Pharmacies:Chain and independent drugstores maintain pharmacist consultation availability and insurance adjacency for FSA/HSA transactions. Mississippi, Alabama, and rural Texas pharmacy deserts are driving independent dollar store partnerships to extend single-unit SKU penetration.
- Supermarkets:Mass merchandisers leverage high-traffic locations for impulse and planned replenishment purchases.
- Convenience Stores:Limited assortment formats prioritize immediate-need analgesics and emergency cold relief.
- Online Retailers:Amazon Pharmacy and CVS CarePass bundle auto-shipment with telehealth consultations, concentrating in coastal metropolitan markets with same-day delivery infrastructure.
Pharmacies retain the largest share of fulfillment volume; online retailers are gaining share fastest through subscription model adoption.
End User:
Dosage precision requirements and child-resistant packaging mandates segment manufacturing complexity and regulatory submission pathways.
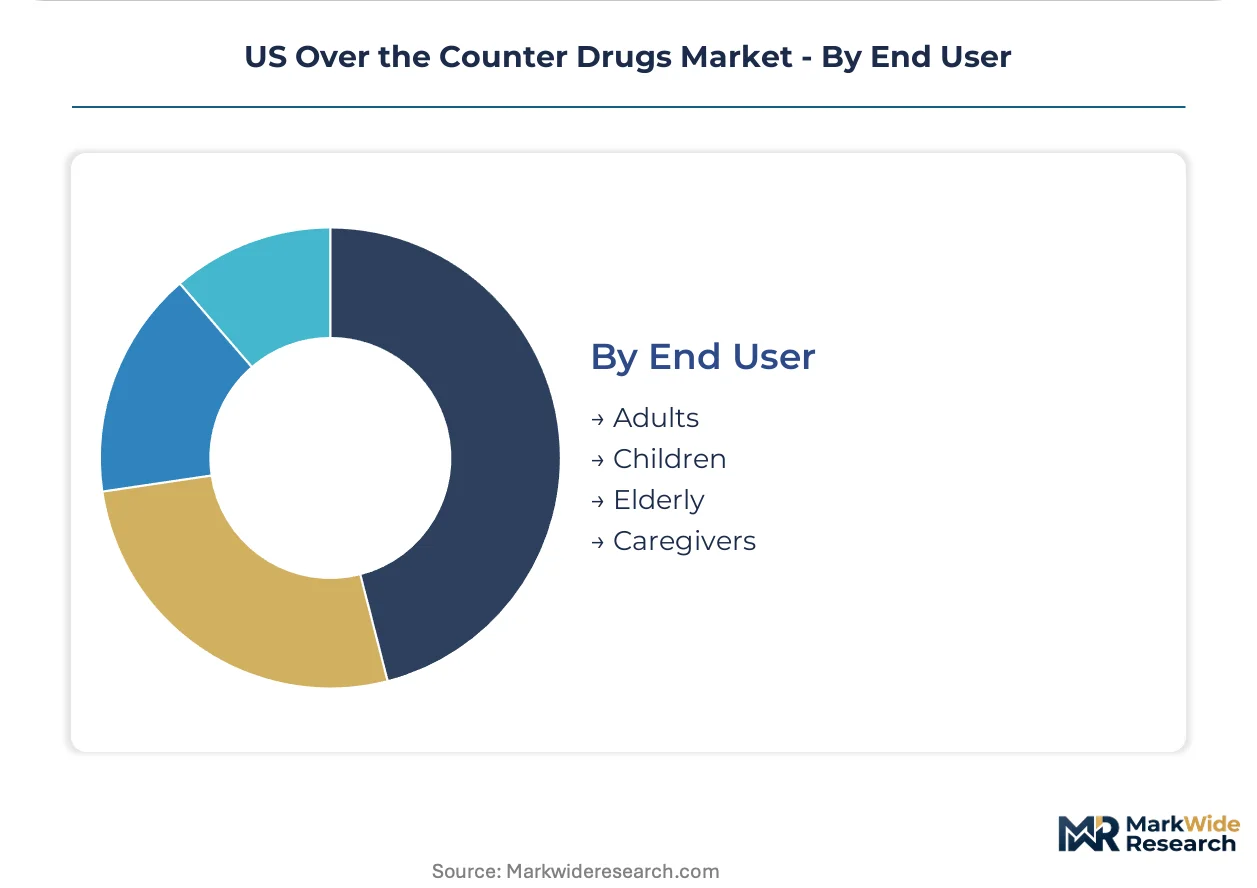
- Adults:Standard-strength formulations for self-diagnosed conditions constitute the baseline demand pool across all therapeutic categories.
- Children:Weight-based dosing formulations and palatability modifications require dedicated production lines and FDA pediatric labeling compliance.
- Elderly:Adults over 65 generate the highest per-capita consumption rates for pain relievers and digestive aids, with polypharmacy considerations driving pharmacist-guided selection in Medicare Advantage-aligned channels.
- Caregivers:Institutional and family purchasers buying on behalf of dependent populations.
Elderly users account for the dominant consumption intensity; caregiver-purchased products are expanding most quickly through IRA preventive care alignment programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in Mississippi and Alabama drive manufacturing concentration through state tax abatements and workforce training grants. Southeast pharmacy deserts accelerate rural distribution network expansion.
Southeast
Adults over 65 in Mississippi, Alabama, and rural Texas generate the highest per-capita OTC consumption for pain relievers and digestive aids. FDA OTC monograph reform enables faster ingredient clearances for regional formulators. Independent dollar stores in the Mississippi Delta partner with distributors to place single-unit analgesic SKUs in pharmacy desert zones.
Texas
Chronic condition prevalence and limited primary care access sustain repeat purchase cycles for acetaminophen and ibuprofen products. EPA streamlined compliance pathways reduce facility upgrade costs for solid-dose tablet operations. Houston and Dallas-Fort Worth production clusters supply national distribution networks with direct compression and wet granulation capacity.
Midwest
Q4 and Q1 cold and flu medication stockpiling concentrates in Chicago, Detroit, and Cleveland metropolitan areas. State-level expansions of pharmacist prescribing authority channel symptom assessments toward OTC recommendations. Continuous manufacturing pilot lines in Ohio and Indiana compress changeover times from days to hours for seasonal variants.
Northeast
Coastal metropolitan markets in New York, Boston, and Philadelphia concentrate subscription-based allergy and pain reliever auto-shipments. Medicare Advantage plan incentives for non-prescription chronic condition management open reimbursement-adjacent channels. Amazon Pharmacy and CVS CarePass bundle telehealth consultations with same-day delivery infrastructure.
Pacific
California's aging demographic drives demand for geriatric-friendly liquid formulations and child-resistant packaging compliance. State pharmacy board regulations shape front-store versus behind-counter positioning for decongestant and cough suppressant products. Los Angeles and San Francisco distribution hubs serve as entry points for API shipments from Asian chemical parks.
US Over the Counter Drugs Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across therapeutic categories, creating a tiered structure with asymmetric resource deployment. Consolidation pressure intensifies as FDA monograph reform elevates compliance infrastructure requirements beyond mid-tier capabilities. Three archetypes dominate: multinational healthcare conglomerates with regulatory affairs divisions, consumer health pure-plays with pharmacy chain relationships, and private-label manufacturers with retailer-owned brand contracts. M&A activity targets specialized formulation capabilities, while strategic partnerships secure API supply buffers against shipping lane disruptions.
Among diversified healthcare conglomerates, Johnson & Johnson Services Inc. and Bayer AG exemplify archetypes leveraging brand strength across multiple therapeutic categories. Sanofi S.A. occupies a position within the allergy and seasonal medication specialist tier. These entities anchor competitive dynamics through established quality systems and legal teams that navigate monograph reform complexity.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Bayer AG |
| Sanofi S.A. |
| GlaxoSmithKline PLC (Haleon) |
| Pfizer Inc. |
| Reckitt Benckiser Group plc |
| Kenvue Brands LLC |
| Novartis AG |
| Boehringer Ingelheim |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up specialty manufacturers now dominate mid-tier OTC production, compressing working capital cycles while enforcing disciplined contract pricing that ties ingredient cost pass-throughs to quarterly API index movements. This ownership pattern concentrates pricing power among entities with captive distribution networks across pharmacy chains and dollar-store channels.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent above spot inventory pricing separate emergency replenishment orders from scheduled contract volumes. Three-tier pricing structure across premium, standard, and economy levels stratifies by brand recognition and pharmacist recommendation intensity. Price differentiation hinges on FDA monograph compliance tier and regional delivery cost differentials. Private-label substitution in analgesics and antacids is intensifying cost compression, with retailer-owned brands capturing shelf space at thirty to forty percent discounts. Institutional buyers through Medicare Advantage channels exhibit lowest price sensitivity, while independent dollar-store purchasers in pharmacy deserts demonstrate highest elasticity.
Supply Chain Analysis
Returns and expired-product reverse logistics flow through specialized pharmaceutical waste handlers, with DEA-controlled substance protocols adding compliance layers to non-controlled OTC categories. Bulk acetaminophen and ibuprofen API production concentrates in Chinese and Indian chemical parks, exposing formulators to shipping lane disruptions and tariff volatility. Raw material dependencies center on acetaminophen, ibuprofen, and loratadine active ingredients, with excipient sourcing from European specialty chemical suppliers. Single-source vulnerability in Asian API supply creates structural risk exposure. Distribution runs through wholesale drug distributors to pharmacy chains, with direct-to-consumer e-commerce channels expanding fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure intensifies as FDA monograph reform elevates compliance infrastructure requirements beyond mid-tier capabilities, forcing weaker players toward exit or acquisition.
For Market Incumbents: Anchor market position through backward integration into API supply buffers and dedicated regulatory affairs divisions capable of navigating administrative order procedures. Invest in continuous manufacturing pilot lines to compress changeover times for seasonal variants. Defensive priority rests on securing pharmacist prescribing authority partnerships under collaborative practice agreements before state-level expansions mature. For New Entrants and Emerging Players: Begin with pharmacy desert penetration in rural Texas, Mississippi, and Alabama, where independent dollar stores represent underserved distribution nodes for single-unit analgesic SKUs. Target CBD-hemp topical formulations combining menthol with hemp-derived compounds, operating outside federal monograph jurisdiction. Go-to-market angle emphasizes direct-store-delivery partnerships bypassing wholesale distributor markups. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-tier manufacturers with established quality systems but constrained regulatory bandwidth in the Southeast, where Opportunity Zone tax abatements reduce facility acquisition costs. Long-term viability across the five-to-ten year window hinges on monograph finalization timing advantages. Signal to monitor: FDA administrative order publication velocity for sunscreen and cough-cold categories as inflection indicator for R&D budget reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Division Expansion | Dedicated FDA submission specialists accelerate monograph reform navigation versus outsourced consulting models. |
| Continuous Manufacturing Scale-Up | Modular powder-to-tablet lines enable regional SKU production without sacrificing compliance rigor. |
| Pharmacy Desert Distribution Partnership | Independent dollar store alliances extend single-unit penetration where chain pharmacy presence is absent. |
| API Supply Buffer Accumulation | Inventory hedging against Chinese and Indian chemical park disruption protects formulation continuity. |
| Subscription Model Platform Launch | Auto-shipment bundling with telehealth consultations captures urban millennial and Gen X household loyalty. |
Research Methodology
Multi-period observation of FDA monograph reform implementation, EPA facility compliance pathways, and state-level pharmacy board regulation changes anchored the trend analysis, supplemented by interviews with regulatory affairs directors, chain pharmacy procurement managers, API sourcing specialists, and telehealth platform operators. Secondary validation drew from FDA administrative order dockets, EPA enforcement and compliance history databases, state pharmacy board rulemaking records, and wholesale drug distributor financial disclosures. Bottom-up facility capacity assessments triangulated against top-down therapeutic category consumption estimates.
Input-output matrix framing connected active ingredient supply concentration to formulation capacity utilization and channel fulfillment velocity across the projection horizon. Segmentation dimensions modeled include product type, formulation, distribution channel, and end-user demographics, with regional regulatory cluster variations. CAGRs were derived through demand elasticity modeling and replacement rate analysis. Forecast inputs incorporated aging demographic consumption intensity curves and telehealth integration adoption patterns.
Monograph finalization delays, API supply chain disruption events, and state-level telehealth prescribing rule reversals are the dominant revision risks to modeled outcomes. Practitioners should monitor FDA administrative order publication schedules and shipping lane tariff developments for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
PDE Inhibitors Market
Pharmaceuticals
Ophthalmic Drugs Market
Pharmaceuticals
Glioblastoma Treatment Drugs Market
Pharmaceuticals
US Pharmacy Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Hospital Pharmaceuticals Market
Pharmaceuticals
Structured Product Label Management Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Naproxen Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting (CINV) Treatment Market
Pharmaceuticals
Asia-Pacific Fatty Bases for Suppositories Market
Pharmaceuticals
Chemotherapy Induced Anemia Market
Pharmaceuticals
Large Volume Parenteral (LVP) Market
Pharmaceuticals
Toxoid Vaccines Market
Pharmaceuticals
Global Cancer Vaccines Drug Pipeline Market