
 Global Diphenhydramine Market | 2026-2036
Global Diphenhydramine Market Size, Share, and Industry Trends Forecast 2026-2036
Global Diphenhydramine Market Foresight
REACH compliance is rebalancing raw material sourcing costs for European diphenhydramine producers, forcing reformulation investments that smaller API houses struggle to fund. GlaxoSmithKline leverages its vertically integrated antihistamine portfolio to absorb these regulatory costs without margin erosion. Johnson & Johnson anchors North American shelf presence through pharmacy chain exclusivity agreements. Sanofi competes aggressively in private-label liquid formulations across European retail consortia.
Diphenhydramine is an ethanolamine-class histamine H1 receptor antagonist with anticholinergic and sedative properties, typically synthesized via benzhydryl ether intermediates and standardized to 98% minimum purity for pharmaceutical use. It functions primarily as an over-the-counter antiemetic, antihistamine, and hypnotic agent in both oral and parenteral delivery systems. Tablet and capsule formats still occupy the largest revenue share due to manufacturing scale and consumer familiarity, though liquid solutions are gaining fastest among pediatric and geriatric populations who face swallowing difficulties. The allergic rhinitis therapy area sustains the deepest margin pools because of seasonal repeat-purchase behavior and brand loyalty, while insomnia indications show accelerating growth driven by self-medication trends in stressed urban demographics.
The FDA maintains strict bioequivalence standards for generic diphenhydramine entrants under its ANDA pathway, while the EMA's updated MDR requirements for excipient safety documentation are lengthening approval timelines for European market access. India's CDSCO enforces BIS purity benchmarks on imported API that filter out substandard Asian suppliers. Stakeholders must monitor evolving anticholinergic risk warnings from WHO and national regulators, as label restrictions could reshape permissible indications and channel access without warning.
Market Dynamics
REACH compliance is rebalancing raw material sourcing costs for European diphenhydramine producers, forcing reformulation investments that smaller API houses struggle to fund while vertically integrated majors absorb these regulatory costs without margin erosion.
Growth Catalysts
- Anticholinergic labeling scrutiny:FDA tightening of bioequivalence standards under the ANDA pathway is filtering out substandard generic entrants and protecting quality-compliant manufacturers.
- Geriatric swallowing difficulties:Liquid solution formats are gaining fastest among pediatric and geriatric populations who face tablet ingestion challenges, expanding addressable patient populations.
- India:CDSCO enforcement of BIS purity benchmarks on imported API is filtering out substandard Asian suppliers and creating procurement advantages for certified producers.
Market Restraints
- Benzhydryl ether intermediate volatility:Feedstock cost fluctuations for ethanolamine-class synthesis inputs compress margins for non-integrated API manufacturers.
- EMA MDR documentation:Updated excipient safety requirements are lengthening approval timelines for European market access, freezing out capital-constrained entrants.
- Melatonin substitution:Natural sleep aid alternatives are capturing insomnia-indication share among wellness-focused urban demographics.
Strategic Opportunities
- Private-label liquid formulations:European retail consortia present white-space for contract manufacturers with flexible filling capabilities and pediatric dosing expertise.
- WHO anticholinergic risk warnings:Evolving label restrictions could reshape permissible indications and channel access, rewarding early compliance investments.
- Self-medication trends:Stressed urban demographics in Asia-Pacific markets are accelerating over-the-counter hypnotic adoption without prescription requirements.
Industry Challenges
- ANDA bioequivalence testing:FDA statistical power requirements demand larger trial cohorts, extending certification timelines for generic entrants.
- Legacy batch record systems:Integration complexity with electronic data integrity standards is forcing mid-tier manufacturers into disruptive ERP migrations.
- Excipient qualification:Novel formulation vehicles require toxicology dossiers that strain regulatory affairs staffing at specialized API houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Diphenhydramine Market |
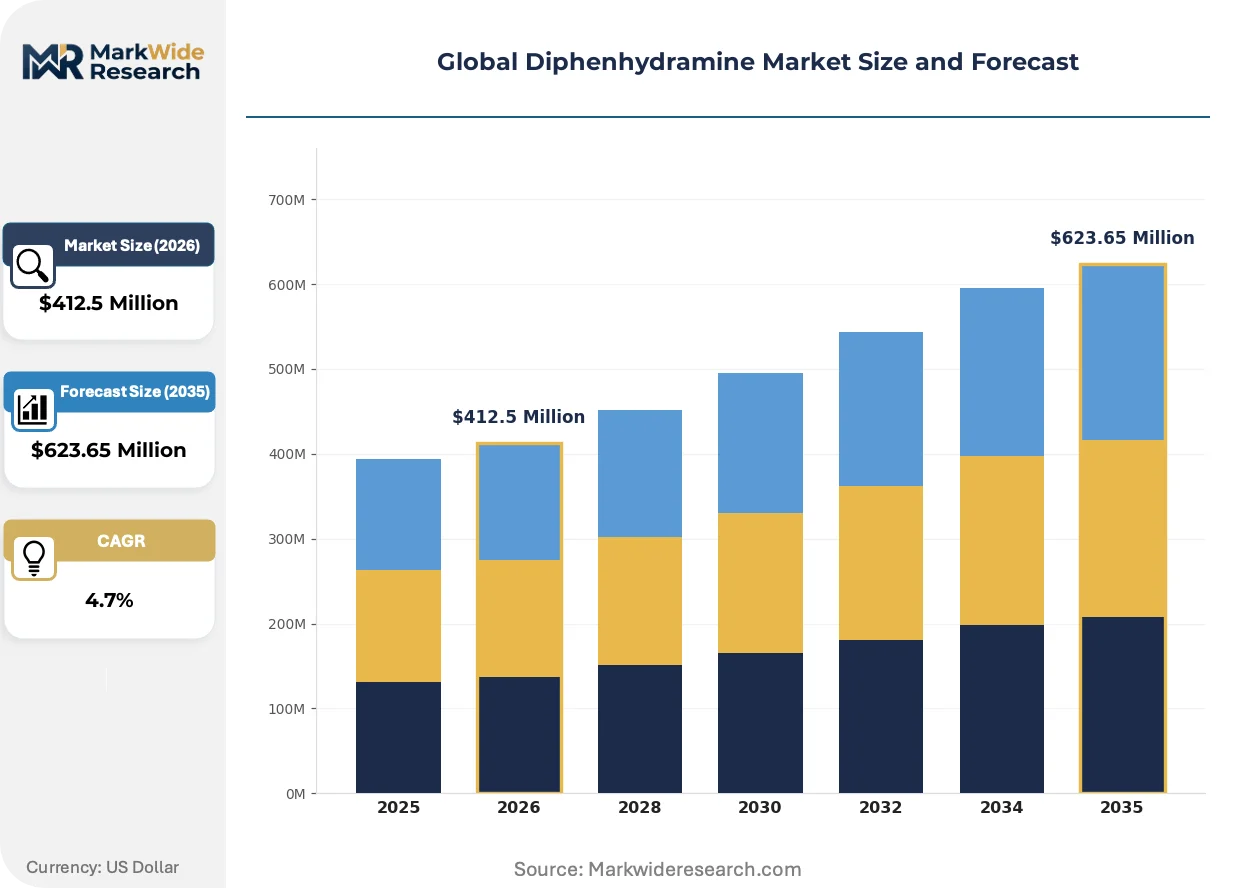
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $623.65 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Liquid Solutions, Topical Creams, Injectables Therapy Area: Allergic Rhinitis, Insomnia, Motion Sickness, Anaphylaxis, Cough Suppression End User: Pharmacies, Hospitals, Clinics, Nursing Homes, Home Care Providers Distribution Channel: Retail Pharmacies, Online Pharmacy, Wholesale Distributors, Direct Hospital Supply, Mail Order |
| Companies Covered | GlaxoSmithKline, Merck & Co., Johnson & Johnson, Fresenius, Teva Pharmaceutical Industries, Pfizer, Sanofi, PAI Pharma, Bayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Diphenhydramine Market Shifts & Advancements
Continuous manufacturing technologies are reshaping diphenhydramine API production economics, compressing batch cycle times while quality-by-design protocols reduce regulatory filing burdens for reformulated delivery systems.
Hot-melt extrusion for solid dispersions is overtaking conventional wet granulation for diphenhydramine tablet production. Pediatric formulation specialists in Germany and the Netherlands are adopting this solvent-free processing at accelerating pace. The technology is enabling immediate-release profiles with reduced pill burden, compressing competitive differentiation around dissolution performance.
EMA's updated MDR requirements for excipient safety documentation are lengthening approval timelines for European market access. Manufacturers must now submit comprehensive toxicological profiles for novel formulation vehicles previously grandfathered under older directives. Liquid solution and orodispersible tablet categories face the steepest compliance ramps, with several mid-tier houses withdrawing pending applications rather than funding expanded dossiers.
Direct-to-consumer pharmacy channels are displacing traditional wholesale distribution for sleep-aid indications in the United States. Amazon Pharmacy and CVS Caremark are capturing prescription-to-OTC switch volumes through subscription auto-refill models. This behavioral shift concentrates most visibly among stressed urban demographics aged 25-45, where convenience premiums override brand loyalty in repeat-purchase decisions.
Global Diphenhydramine Market Segmentation
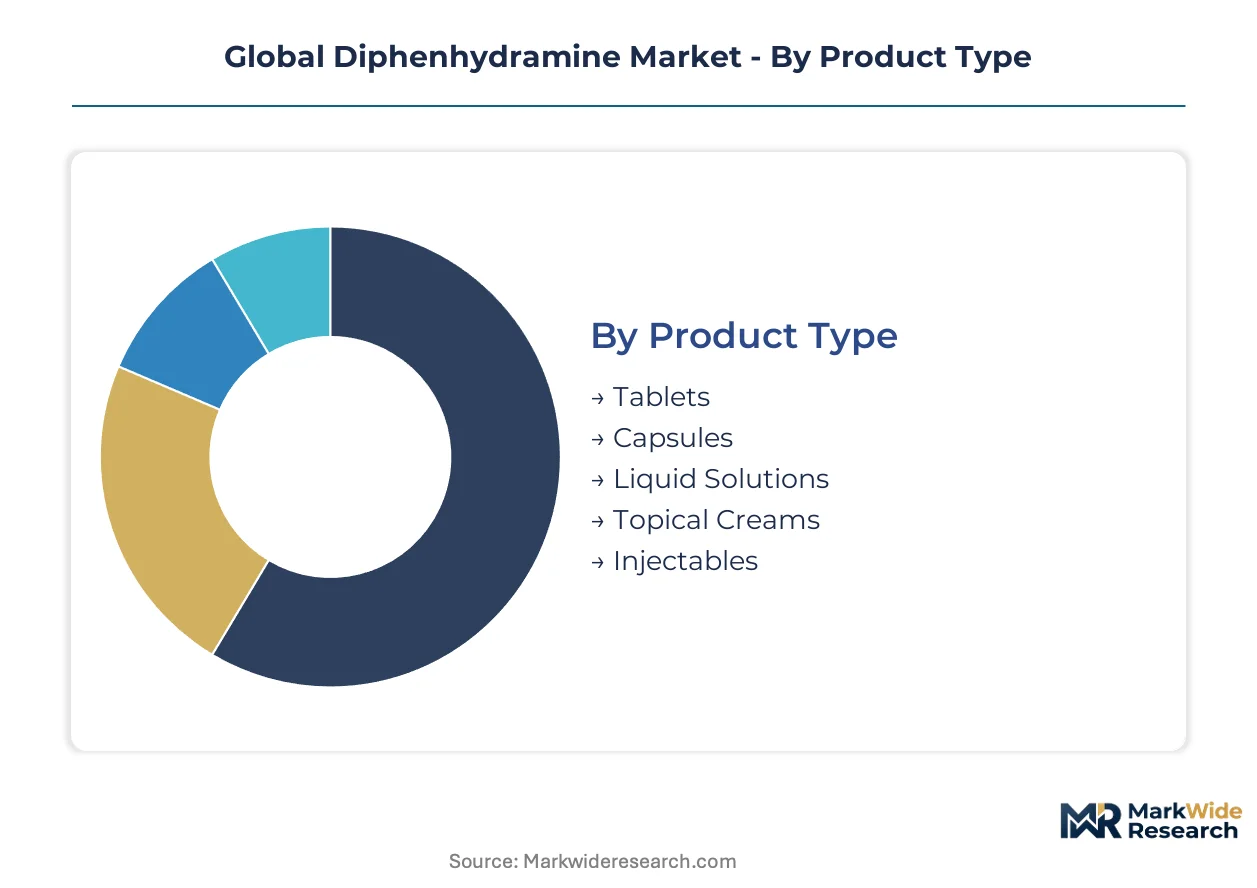
Diphenhydramine's formulation diversity demands granular segmentation to capture divergent margin structures and regulatory pathways. Each category reveals distinct competitive dynamics between established oral formats and emerging delivery systems.
Product Type:
Technical specifications around bioavailability and onset timing differentiate competitive positioning across solid and liquid formats.
- Tablets:Compressed formulations with standardized dissolution profiles dominate manufacturing scale economics. Demand concentrates in United States retail pharmacy chains where FDA bioequivalence standards favor high-volume ANDA filers with established quality dossiers.
- Liquid Solutions:Aqueous or syrup-based suspensions enable dose titration for weight-variable populations. Pediatric and geriatric applications in Germany and the Netherlands are climbing fastest as swallowing difficulties drive format substitution.
- Capsules:Gelatin or HPMC shells mask bitter active pharmaceutical ingredient taste for improved compliance. Hospital procurement in India favors this format for inpatient antiemetic protocols.
- Topical Creams:Transdermal absorption limits systemic anticholinergic exposure for localized pruritus. Dermatology clinics in France and Spain represent concentrated prescribing.
- Injectables:Parenteral solutions for acute anaphylaxis require sterile manufacturing suites with isolator technology. Emergency department formularies in Japan and South Korea sustain specialized production runs.
Mature deployment sits with Tablets. Newer deployment is concentrated in Liquid Solutions.
Therapy Area:
Clinical indication determines reimbursement status and direct-to-consumer accessibility across regulated markets.
- Allergic Rhinitis:Seasonal demand spikes create predictable revenue cycles tied to pollen monitoring networks. United States pharmacy chains stockpile inventory ahead of March-May peaks, with repeat-purchase behavior sustaining brand loyalty.
- Insomnia:Self-medication trends among stressed urban demographics in Brazil and Mexico are expanding over-the-counter hypnotic adoption. Melatonin substitution pressure is reshaping permissible marketing claims.
- Motion Sickness:Antiemetic applications concentrate in travel retail channels and cruise line medical facilities. Transdermal scopolamine competition limits growth in this indication.
- Anaphylaxis:Emergency use authorization requirements restrict distribution to hospital and ambulance settings. EpiPen substitution dynamics affect stocking decisions.
- Cough Suppression:Combination formulations with dextromethorphan face DEA scheduling scrutiny in United States markets. Multi-symptom cold products sustain volume in mass retail.
Revenue concentration favors Allergic Rhinitis. Volume expansion is accelerating in Insomnia.
End User:
Procurement sophistication varies sharply between institutional buyers and dispersed retail channels.
- Pharmacies:Community and chain dispensaries handle the majority of over-the-counter transactions. CVS and Walgreens exclusivity agreements in United States markets concentrate shelf placement power.
- Hospitals:Formulary committees enforce therapeutic substitution protocols that favor lowest-unit-cost suppliers. Injectable presentations dominate acute care procurement.
- Clinics:Outpatient facilities prioritize single-dose packaging for sample distribution and trial initiation. Allergy specialist practices drive seasonal prescription-to-OTC conversion.
- Nursing Homes:Long-term care facilities require crushable or liquid formulations for dysphagia management. Medicare Part D reimbursement shapes purchasing patterns.
- Home Care Providers:Visiting nurse organizations and hospice services demand unit-dose compliance packaging. Palliative sedation protocols sustain parenteral demand.
Institutional procurement maturity sits with Hospitals. Patient-directed acquisition is expanding fastest through Pharmacies.
Distribution Channel:
Channel selection determines margin capture and regulatory compliance burden for manufacturers.
- Retail Pharmacies:Brick-and-mortar dispensaries maintain dominant volume share through immediate fulfillment. United States independents and chains collectively anchor physical access.
- Online Pharmacy:Amazon Pharmacy and CVS Caremark subscription models are capturing prescription-to-OTC switch volumes. Auto-refill convenience premiums override brand loyalty among urban demographics aged 25-45.
- Wholesale Distributors:McKesson and AmerisourceBergen maintain inventory buffers for seasonal demand spikes. Cold chain requirements for liquid formulations constrain network eligibility.
- Direct Hospital Supply:Manufacturer-to-facility contracts eliminate distributor markups for high-volume institutional purchasers. Group purchasing organizations aggregate negotiating leverage.
- Mail Order:90-day supply fulfillment reduces per-unit dispensing costs for chronic users. Medicare Part D plans incentivize this channel for maintenance therapy.
Traditional infrastructure sits with Wholesale Distributors. Digital migration is advancing fastest through Online Pharmacy.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in India and pharmaceutical clusters in Germany concentrate active pharmaceutical ingredient production, while FDA-registered facilities in the United States dominate finished dosage form manufacturing. Tax incentives in Gujarat and Bavaria accelerate capital deployment for ethanolamine-class synthesis operations.
United States
Direct-to-consumer pharmacy channels and subscription auto-refill models sustain volume leadership in sleep-aid applications. FDA bioequivalence standards under the ANDA pathway filter substandard generic entrants and protect quality-compliant manufacturers. New Jersey and North Carolina host the densest concentrations of sterile injectable manufacturing for acute anaphylaxis protocols.
Germany
Pediatric formulation specialists in Baden-Württemberg adopt hot-melt extrusion technologies for immediate-release tablet production. EMA updated MDR requirements for excipient safety documentation lengthen approval timelines and freeze out capital-constrained entrants. Frankfurt-Rhine-Main clusters house vertically integrated antihistamine portfolios that absorb regulatory costs without margin erosion.
India
CDSCO enforcement of BIS purity benchmarks on imported API filters out substandard Asian suppliers and creates procurement advantages for certified producers. Pharmaceutical special economic zones in Gujarat and Telangana offer 15-year tax holidays for greenfield API investments. Hyderabad-Visakhapatnam corridor dominates contract manufacturing for European private-label liquid formulations.
Japan
PMDA sterile manufacturing requirements sustain specialized production runs for emergency department injectable presentations. METI incentives for continuous manufacturing technologies compress batch cycle times for domestic API producers. Kansai region Osaka-Kobe pharmaceutical clusters lead adoption of quality-by-design protocols for reformulated delivery systems.
Brazil
Self-medication trends among stressed urban demographics in São Paulo and Rio de Janeiro accelerate over-the-counter hypnotic adoption without prescription requirements. ANVISA regulatory alignment with FDA bioequivalence standards streamlines pathway for generic liquid solution entrants. São Paulo state pharmaceutical parks concentrate private-label manufacturing for Latin American retail consortia.
Global Diphenhydramine Market Competitive Landscape
United States producers anchor one tier; European specialists hold formulation expertise advantages. The vendor base separates between vertically integrated majors with captive API supply and mid-tier houses dependent on external sourcing. Three archetypes dominate: global diversified pharmaceuticals with antihistamine portfolios, regional contract manufacturers with flexible filling capabilities, and specialized API houses focused on ethanolamine-class chemistry. Competitive moves concentrate on strategic partnerships for distribution access and portfolio diversification into pediatric dosage formats.
Within the vertically integrated tier, GlaxoSmithKline and Johnson & Johnson exemplify archetypes that absorb regulatory compliance costs without margin erosion. Sanofi occupies a position among European-based formulators competing aggressively in private-label liquid formulations. Teva Pharmaceutical Industries represents the generic-specialist archetype navigating FDA statistical power requirements for ANDA certification.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Merck & Co. |
| Johnson & Johnson |
| Fresenius |
| Teva Pharmaceutical Industries |
| Pfizer |
| Sanofi |
| PAI Pharma |
| Bayer |
| Others |
Supply & Pricing Matrix
EMA excipient documentation mandates are compressing procurement timelines for European liquid formulation buyers, forcing suppliers to absorb toxicology testing costs or lose formulary placement and driving price stratification between compliant and non-compliant producers.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with hospital systems paying 15-25% above spot for guaranteed sterile injectable availability during allergy season peaks. Three-tier pricing structure across GMP-certified, FDA-registered, and standard-grade suppliers reflects quality dossier depth and audit history. Pricing pressure stems from melatonin substitution in insomnia segments, eroding brand premiums among wellness-focused demographics. Price-sensitive retail chains in Brazil and Mexico drive volume discounts, while Japanese emergency departments show lowest sensitivity due to life-critical application.
Supply Chain Analysis
Dual-sourcing requirements from United States hospital group purchasing organizations mandate qualified secondary suppliers for parenteral presentations, fragmenting volume across domestic sterile manufacturers and Indian API houses. Active pharmaceutical ingredient production concentrates in India, China, and Germany, with benzhydryl ether intermediates drawing from specialized ethanolamine chemical suppliers in Gujarat and Bavaria. Single-source vulnerability sits with isolator technology providers for aseptic filling. Distribution runs through McKesson and AmerisourceBergen for wholesale, with Amazon Pharmacy auto-refill capturing direct-to-consumer sleep-aid volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory compliance costs are forcing mid-tier API houses toward exit or acquisition, consolidating competitive terrain around vertically integrated majors with captive toxicology and regulatory affairs capabilities.
For Market Incumbents: Lock in pediatric liquid formulation capacity through flexible filling line investments in Hyderabad-Visakhapatnam corridor, securing European private-label contracts before MDR documentation deadlines filter out competitors. Acquire distressed mid-tier houses with approved ANDA dossiers to expand generic tablet market share without FDA statistical power delays. Melatonin substitution threat demands insomnia indication repositioning toward acute allergic rhinitis co-prescription protocols. For New Entrants and Emerging Players: Enter via Brazilian and Mexican over-the-counter hypnotic segments where ANVISA alignment with FDA standards streamlines generic pathway without prescription requirements. Target nursing home dysphagia management with crushable tablet or liquid dose compliance packaging, exploiting Medicare Part D reimbursement tailwinds. Go-to-market angle emphasizes unit-dose convenience premiums over brand heritage for stressed urban demographics aged 25-45. For Investors and Strategic Acquirers: The window for entry favors CDSCO-certified Indian API producers with BIS purity benchmarks and established European formulation partnerships. Long-term viability hinges on backward integration into benzhydryl ether intermediates to insulate margin from feedstock volatility. Signal to watch: WHO anticholinergic risk warning upgrades that trigger label restrictions and reshape permissible indications without warning.| Strategic Initiative | Industry Significance |
|---|---|
| Hot-Melt Extrusion Adoption | German pediatric specialists compress dissolution timelines using solvent-free processing for immediate-release profiles. |
| CDSCO Certification Investment | Indian API houses secure procurement advantages as BIS purity benchmarks filter substandard Asian competitors. |
| Private-Label Liquid Expansion | European retail consortia open white-space for contract manufacturers with pediatric dosing expertise. |
| Continuous Manufacturing Transition | Japanese METI incentives compress batch cycle times while quality-by-design protocols reduce regulatory filing burdens. |
| Direct-to-Consumer Channel Buildout | Amazon Pharmacy and CVS Caremark subscription models capture prescription-to-OTC switch volumes through auto-refill convenience. |
Research Methodology
Multi-period observation of FDA ANDA approval timelines, EMA MDR submission withdrawals, and seasonal inventory build patterns anchored the trend analysis, supplemented by interviews with regulatory affairs directors at generic pharmaceutical firms, formulary committee chairs at United States hospital systems, procurement managers at European retail pharmacy consortia, and toxicology specialists at German pediatric formulation houses. Secondary validation drew from FDA Orange Book filings, EMA public assessment reports, CDSCO import alerts, ClinicalTrials.gov bioequivalence study registrations, and SEC 10-K disclosures from vertically integrated majors. Bottom-up volume modeling across dosage forms triangulated against top-down value estimates from wholesale distributor data.
Segment-weighting applied therapy area splits by reimbursement status and direct-to-consumer accessibility, crossed with distribution channel migration rates toward online pharmacy subscription models. Formulation type, geographic regulatory cluster, and end-user procurement sophistication formed the dimensional framework. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points. Forecast inputs incorporated pollen monitoring network seasonal patterns, melatonin substitution elasticity estimates, and anticholinergic risk warning probability assessments.
Revisions become necessary when WHO or national regulators escalate anticholinergic labeling restrictions, when REACH compliance cost trajectories exceed reformulation investment capacity, or when major retail pharmacy chains consolidate shelf placement power through exclusivity renegotiations. A model refresh is warranted upon material change in FDA statistical power requirements for ANDA bioequivalence testing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Indonesia Oral Anti-Diabetic Drug Market
Pharmaceuticals
3D Printing Drug Market
Pharmaceuticals
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market
Pharmaceuticals
Global Hemostasis and Tissue Sealing Agents Market
Pharmaceuticals
Angiopoietin Inhibitors Therapeutic Market
Pharmaceuticals
Cerumenolytic Agents Market
Pharmaceuticals
Germany Pharmaceutical Cold Chain Logistics Market
Pharmaceuticals
China Plasma Protein Therapeutics Market
Pharmaceuticals
Pancrelipase Market
Pharmaceuticals
Carglumic Acid Market
Pharmaceuticals
Hyoscine-N-Butyl Bromide Market
Pharmaceuticals
Advanced Therapy Medicinal Products (Atmps) Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Metaxalone Market
Pharmaceuticals
H2-Receptor Antagonists Market
Pharmaceuticals
Leukotriene Modifiers Market