
 Metoprolol Tartrate Market | 2026-2036
Metoprolol Tartrate Market Size, Share, and Industry Trends Forecast 2026-2036
Metoprolol Tartrate Market Analysis
Maintenance contracts for therapeutic equivalence monitoring is shifting how generic manufacturers monetize metoprolol tartrate beyond unit sales. Novartis AG anchors its position through backward integration into active pharmaceutical ingredient supply. Teva Pharmaceutical Industries competes on manufacturing scale across multiple dosage strengths. Aurobindo Pharma specializes in immediate-release formulations for cost-sensitive hospital buyers.
Metoprolol tartrate is a selective beta-1 adrenergic receptor antagonist with the chemical formula (±)-1-(isopropylamino)-3-[p-(2-methoxyethyl)phenoxy]-2-propanol L-(+)-tartrate salt, administered orally or intravenously to reduce heart rate and myocardial contractility in hypertension and angina management. The therapy area dimension shows cardiovascular disorders occupying the largest volume share due to chronic prescription patterns, while extended-release capsules represent the fastest-growing product type as patient adherence programs favor less frequent dosing regimens. Hospital end users dominate procurement through centralized formularies, though homecare channels are gaining traction with telehealth-integrated prescription refills.
The FDA enforces bioequivalence standards under ANDA pathways that determine which generic entrants gain market access, while the EPA regulates pharmaceutical manufacturing discharge limits that raise compliance costs for API producers. The EMA's variation assessment procedures for formulation changes create additional validation hurdles for European suppliers. Stakeholders must monitor how tightening environmental compliance intersects with pricing pressure on commoditized cardiovascular generics.
Market Dynamics
The Metoprolol Tartrate Market is being fundamentally restructured by the FDA's tightening bioequivalence standards for generic beta-blockers, which are filtering the supplier base and forcing manufacturers to invest in therapeutic equivalence monitoring infrastructure rather than competing solely on unit price.
Growth Catalysts
- Aging demographics in the United States:Hypertension prevalence among adults over 65 sustains chronic prescription volumes for immediate-release formulations. Hospital systems prioritize cardiovascular disease management in value-based care contracts.
- Extended-release formulation adoption:Patient adherence programs favor less frequent dosing regimens. Homecare channels integrate telehealth-enabled prescription refills for chronic therapy maintenance.
- EPA discharge compliance investments:Environmental regulations on pharmaceutical manufacturing effluent raise barriers for marginal API producers. Surviving suppliers capture volume from exiting competitors.
Market Restraints
- Active pharmaceutical ingredient supply concentration:Backward-integrated manufacturers control key tartrate salt precursors. Generic entrants face captive supply constraints from dominant API producers.
- ANDA pathway validation timelines:The FDA's bioequivalence study requirements extend regulatory approval cycles. Development costs for generic entrants compress margin profiles before commercial launch.
- Extended-release metoprolol succinate substitution:Once-daily alternatives displace immediate-release tartrate prescriptions in outpatient settings. Formulary preference shifts reduce addressable volume for tartrate-specific suppliers.
Strategic Opportunities
- Centralized hospital procurement expansion:Health system formulary consolidation favors suppliers with multi-strength manufacturing scale. Contract manufacturing for private-label hospital brands opens new revenue streams.
- Telehealth-integrated homecare channels:Remote patient monitoring platforms enable direct-to-patient refill logistics. Chronic disease management programs bypass traditional pharmacy distribution.
- Maintenance contract monetization:Therapeutic equivalence monitoring services generate recurring revenue beyond unit sales. Generic manufacturers transition from product vendors to compliance partners.
Industry Challenges
- Bioanalytical method transfer complexity:CROs face capability gaps in validating BE studies for polymorphic tartrate salts. Study failure rates delay ANDA submissions.
- Legacy ERP integration with track-and-trace systems:DSCSA compliance requires serialization infrastructure upgrades. Small generic manufacturers struggle with capital allocation for compliance technology.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metoprolol Tartrate Market |
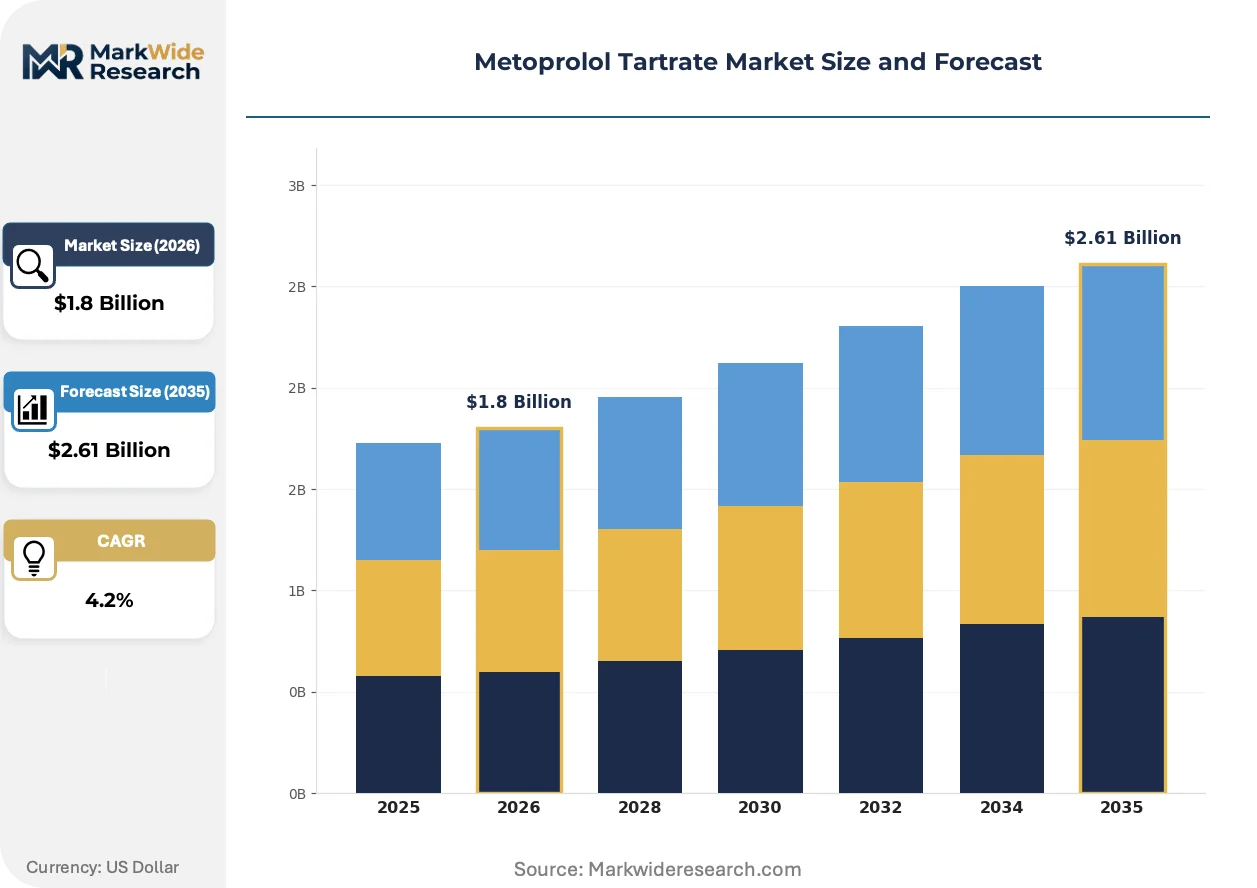
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Injectable, Extended-release Capsules, Oral Solution Therapy Area: Cardiovascular Disorders, Hypertension, Arrhythmias, Heart Failure End User: Hospitals, Clinics, Homecare, Pharmacies Formulation: Immediate-release, Sustained-release, Combination Therapy, Antihypertensive |
| Companies Covered | Novartis AG, AstraZeneca, Teva Pharmaceutical Industries, Sun Pharmaceutical Industries, Dr. Reddy's Laboratories, Aurobindo Pharma, Viatris, Changzhou Siyao Pharmacy Limited Company, Torrent Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metoprolol Tartrate Market Emerging Trajectories
Continuous manufacturing technologies are displacing batch processing in beta-blocker API synthesis, while regulatory data integrity requirements and patient adherence program designs are reshaping competitive differentiation beyond price.
Continuous flow chemistry for tartrate salt synthesis is expanding into commercial-scale metoprolol production. Novartis and Teva have retrofitted legacy batch facilities with modular reaction units that reduce solvent waste and improve polymorphic control. This technology is expanding into cost-sensitive hospital supply contracts by enabling real-time release testing that accelerates batch certification.
The FDA's enhanced data integrity guidance under 21 CFR Part 11 is forcing generic manufacturers to upgrade electronic batch records and audit trail systems. Facilities with legacy paper-based quality systems face warning letter risk that blocks ANDA approvals. European suppliers navigating EMA variation assessment procedures are investing in preemptive change control systems to avoid post-approval modification delays.
Hospital buyers are consolidating cardiology therapeutic categories under single-source contracts with adherence-linked outcomes metrics. Traditional wholesaler distribution faces disintermediation as health systems direct-source from manufacturers with integrated patient support programs. This pattern is most visible in United States integrated delivery networks that combine formulary control with remote monitoring infrastructure for chronic hypertension management.
Metoprolol Tartrate Market Segmentation
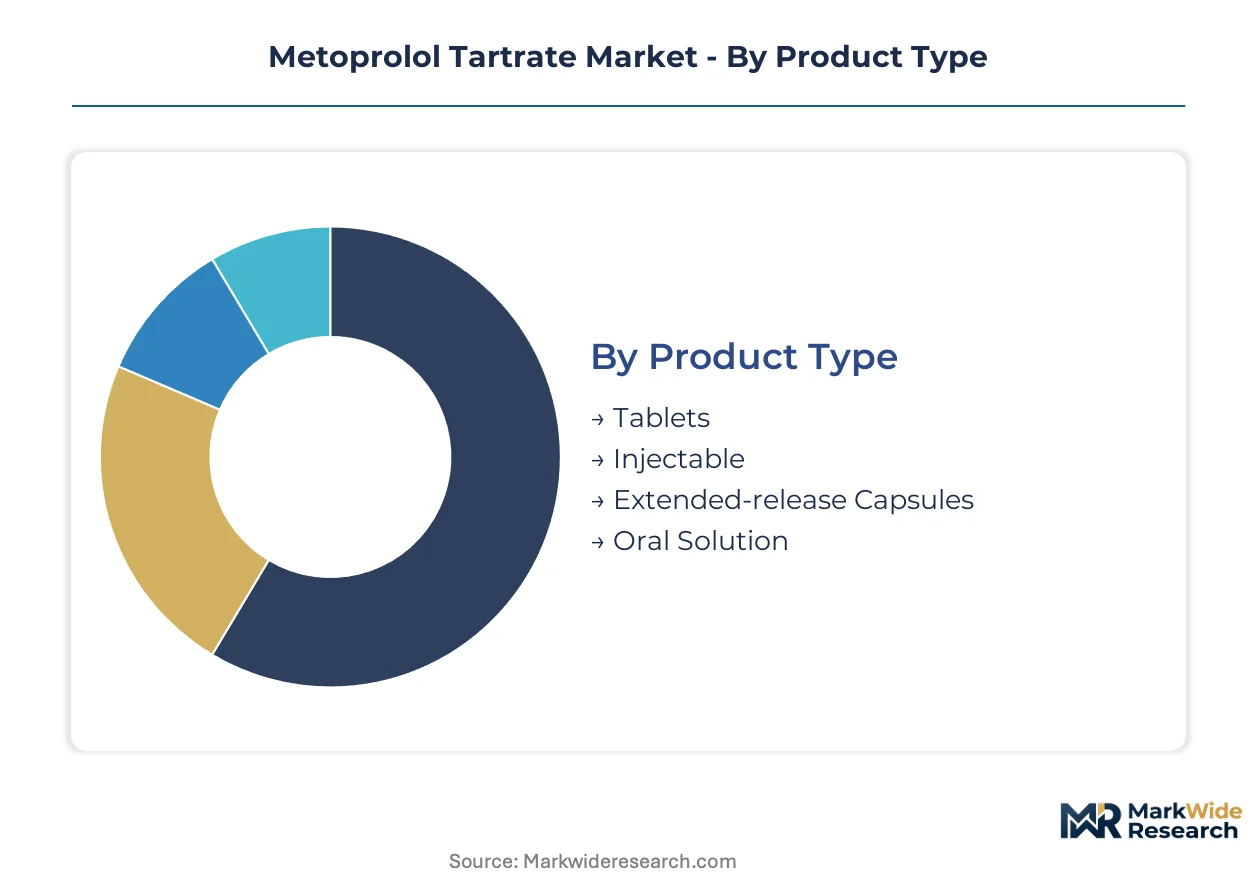
Segmentation in the metoprolol tartrate market reveals how formulation science, clinical setting requirements, and patient adherence economics create divergent procurement patterns. Understanding these divisions exposes where pricing power concentrates and where commoditization pressures dominate.
Product Type:
Pharmacokinetic profiles and administration routes determine reimbursement tiers and manufacturing complexity across dosage forms.
- Tablets:Compressed metoprolol tartrate with standard 25mg, 50mg, and 100mg strengths dominates outpatient dispensing volumes. Hospital formularies in the United States negotiate multi-year contracts for immediate-release tablets as first-line hypertension therapy, though generic saturation compresses per-unit margins.
- Extended-release Capsules:Polymeric matrix formulations enable once-daily dosing that improves patient compliance metrics in value-based care contracts. Homecare channels in the United States are expanding fastest here as telehealth platforms integrate automatic refill programs for chronic cardiovascular maintenance.
- Injectable:Intravenous tartrate solutions for acute myocardial infarction and perioperative arrhythmia control require sterile manufacturing suites and cold chain logistics. Hospital emergency departments and cardiac catheterization labs represent the concentrated demand node.
- Oral Solution:Liquid formulations serve pediatric populations and patients with dysphagia, manufactured in smaller batch sizes with flavor masking requirements. Compounding pharmacies and specialized long-term care facilities drive procurement.
Tablets lead on scale; extended-release capsules lead on momentum.
Therapy Area:
Clinical indication determines prescriber specialty, reimbursement coding, and competitive substitution risk from alternative beta-blocker classes.
- Cardiovascular Disorders:Broad angina and post-myocardial infarction prophylaxis applications sustain the largest chronic prescription base. United States cardiology practices prioritize metoprolol tartrate for its established mortality benefit in secondary prevention protocols.
- Hypertension:Essential hypertension management competes directly with ACE inhibitors and calcium channel blockers in step-care algorithms. Clinic-based prescribers in the United States face formulary restrictions that favor generic substitution to metoprolol succinate in many health systems.
- Arrhythmias:Rate control in atrial fibrillation and ventricular ectopy requires precise titration that favors immediate-release flexibility. Electrophysiology specialists in tertiary centers drive concentrated demand for rapid dose adjustment capabilities.
- Heart Failure:Off-label use in reduced ejection fraction patients competes with carvedilol and bisoprolol in guideline-directed medical therapy. Hospital discharge protocols in the United States increasingly substitute extended-release alternatives for outpatient adherence.
Cardiovascular disorders command volume concentration; heart failure faces the steepest competitive substitution pressure.
End User:
Procurement authority and patient touchpoint frequency create distinct channel economics and service requirements.
- Hospitals:Centralized pharmacy and therapeutics committees control formulary placement through competitive bidding and therapeutic interchange policies. United States integrated delivery networks leverage multi-hospital purchasing volume to extract price concessions and compliance service bundling.
- Homecare:Direct-to-patient delivery models bypass traditional wholesale distribution through specialty pharmacy networks. Remote patient monitoring platforms in the United States enable adherence tracking that justifies premium pricing for extended-release formulations.
- Clinics:Outpatient cardiology and internal medicine practices rely on 340B pricing and group purchasing organization contracts. Sample programs and patient assistance foundations influence prescriber brand loyalty in generic-saturated markets.
- Pharmacies:Retail chains and independent dispensers face reimbursement compression from pharmacy benefit managers that drive generic substitution toward lowest-net-cost alternatives. United States Medicare Part D formularies increasingly require prior authorization for non-preferred beta-blocker selections.
Hospitals lead on contract value; homecare leads on channel expansion velocity.
Formulation:
Release kinetics and combination strategies differentiate therapeutic positioning and manufacturing investment requirements.
- Immediate-release:Rapid dissolution profiles enable precise dose titration for acute hemodynamic control. Hospital protocols in the United States favor this flexibility for perioperative and emergency department applications where rapid onset matters.
- Sustained-release:Matrix or reservoir systems extend absorption windows to 12-24 hours, improving patient compliance in chronic maintenance. FDA bioequivalence standards for these modified-release forms create higher barriers to generic entry than immediate-release alternatives.
- Combination Therapy:Fixed-dose combinations with hydrochlorothiazide or other antihypertensives reduce pill burden and improve adherence metrics. United States payers increasingly require step therapy failure on monotherapy before approving combination products.
- Antihypertensive:Standalone beta-blocker positioning competes in crowded therapeutic classes where clinical guidelines have downgraded beta-blocker priority in uncomplicated hypertension. Generic manufacturers emphasize cost minimization over clinical differentiation.
Immediate-release leads on volume ubiquity; sustained-release leads on technical barrier height.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States sustains larger prescription volumes than Germany, though both markets face tightening bioequivalence standards that filter generic supplier bases differently.
United States
Aging demographics and hypertension prevalence among adults over 65 drive chronic prescription volumes for immediate-release formulations. The FDA enforces bioequivalence standards under ANDA pathways that determine which generic entrants gain market access. Hospital systems in the Midwest and Southeast prioritize cardiovascular disease management in value-based care contracts, consolidating procurement under integrated delivery networks.
Germany
Hospital procurement of cardiology therapies expands as health systems prioritize chronic disease management through centralized formularies. The EMA's variation assessment procedures for formulation changes create validation hurdles for European suppliers. Manufacturing clusters in North Rhine-Westphalia and Bavaria house API producers investing in continuous flow chemistry to meet environmental compliance under REACH regulations.
India
Cost-sensitive hospital buyers in South Asia sustain demand for immediate-release generic formulations. CDSCO approval timelines and export-oriented manufacturing incentives shape competitive positioning. API production concentrates in Gujarat and Telangana, where manufacturers retrofit facilities with therapeutic equivalence monitoring infrastructure to serve regulated markets.
China
Domestic pharmaceutical consumption rises with expanded health insurance coverage for chronic cardiovascular conditions. NMPA bioequivalence requirements for generic beta-blockers extend regulatory approval cycles. Manufacturing capacity clusters in Jiangsu and Zhejiang provinces, where producers face EPA-equivalent discharge limits on pharmaceutical effluent that raise compliance costs.
Switzerland
Specialty pharmaceutical manufacturing and precision formulation capabilities anchor regional supply for high-barrier modified-release products. Swissmedic oversees stringent quality standards that favor established manufacturers with integrated patient support programs. Basel and Zurich house backward-integrated producers controlling active pharmaceutical ingredient supply chains for European hospital networks.
Metoprolol Tartrate Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with originators retaining premium positioning in extended-release niches while generic fabricators capture volume in commoditized immediate-release tablets. The supplier base concentrates around three strategic archetypes: backward-integrated API producers, multi-strength manufacturing scale operators, and cost-focused hospital contract specialists. Competitive moves center on therapeutic equivalence monitoring service bundling and continuous manufacturing technology licensing rather than pure price competition.
Among Swiss-based pharmaceutical conglomerates, Novartis AG anchors the originator tier through captive supply of active pharmaceutical ingredients. Israeli and Indian generic specialists occupy distinct volume positions: Teva Pharmaceutical Industries exemplifies multi-strength manufacturing scale across dosage forms, while Aurobindo Pharma represents the cost-sensitive hospital contract archetype specializing in immediate-release formulations. These three entities illustrate how geographic origin and corporate structure map to divergent competitive strategies in a market reshaped by regulatory compliance requirements.
| Leading Market Players |
|---|
| Novartis AG |
| AstraZeneca |
| Teva Pharmaceutical Industries |
| Sun Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Aurobindo Pharma |
| Viatris |
| Changzhou Siyao Pharmacy Limited Company |
| Torrent Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Backward integration into active pharmaceutical ingredient production anchors both supply security and pricing power for metoprolol tartrate manufacturers. Novartis and Teva control captive tartrate salt precursor supplies, insulating their margin positions from raw material volatility while hospital buyers face limited alternative sourcing.
Pricing Analysis
Capacity additions in India and China are reshaping price floors for immediate-release tablet formulations. Three-tier pricing structure across premium extended-release, standard immediate-release tablets, and economy oral solutions stratifies the market. Cost compression in commoditized tablet strengths intensifies as ANDA approvals multiply, though hospital procurement committees demonstrate lowest price sensitivity for sterile injectable presentations where supply reliability dominates.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's NMPA localization requirements are reshaping sourcing patterns for regulated market exports. API production concentrates in India, China, and Switzerland, with the sector drawing from isopropylamine, methoxyethyl phenol, and L-tartaric acid feedstocks. Single-source vulnerability in tartrate salt precursor supply creates concentration risk. Distribution runs through hospital GPO contracts and specialty pharmacy networks for direct-to-patient channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The metoprolol tartrate market represents a late-cycle quality story where FDA bioequivalence enforcement and EMA variation procedures favor manufacturers with preemptive compliance infrastructure. Hospital buyers are shifting procurement criteria toward therapeutic equivalence monitoring capabilities rather than unit cost alone.
For Market Incumbents: Deploy continuous manufacturing retrofits to capture EPA discharge compliance advantages and accelerate batch release timelines. Consolidate API supply relationships through long-term offtake agreements with Gujarat and Telangana producers to neutralize captive supply threats from backward-integrated competitors. Defend formulary positions by bundling telehealth-integrated adherence programs with extended-release capsule contracts. For New Entrants and Emerging Players: Cost-sensitive hospital buyers in South Asia present the most penetrable entry point for immediate-release generic formulations. Target CDSCO-approved manufacturers seeking ANDA pathway partnerships for regulated market access. White-space exists in oral solution formats for pediatric and dysphagia populations where compounding pharmacy relationships enable premium positioning away from tablet commoditization. For Investors and Strategic Acquirers: Consolidation pressure builds where small generic manufacturers face DSCSA serialization infrastructure costs and legacy ERP replacement burdens. Mid-cap specialists with therapeutic equivalence monitoring capabilities and FDA warning letter-free facilities represent priority acquisition targets. Watch for inflection signals in FDA ANDA approval velocity for sustained-release formulations, which would indicate regulatory pathway clarity and margin expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Retrofit | EPA discharge compliance and real-time release testing accelerate hospital contract capture. |
| Therapeutic Equivalence Monitoring Service Launch | FDA bioequivalence standards transform generic manufacturers into compliance partners with recurring revenue. |
| Extended-Release Formulation Development | Patient adherence programs favor once-daily dosing that commands premium hospital formulary placement. |
| Telehealth-Integrated Homecare Channel Partnership | Remote patient monitoring platforms bypass traditional pharmacy distribution for chronic therapy maintenance. |
| API Supply Backward Integration | Tartrate salt precursor control insulates margins from raw material volatility and supply disruption. |
Methodological Framework
Direct dialogue with pharmaceutical manufacturing executives, regulatory affairs directors, hospital formulary managers, and API procurement specialists grounded the qualitative foundation. Secondary validation drew from FDA ANDA filings, EMA variation assessment procedures, CDSCO approval databases, and EPA pharmaceutical effluent discharge records. Bottom-up prescription volume modeling and top-down therapeutic category sizing were cross-referenced for triangulation.
Segment-level projections across the analysis window reflect dosage form, therapy area, end-user channel, and regional regulatory cluster dimensions. CAGRs were derived from historical prescription trajectory analysis and adjusted for FDA bioequivalence study requirement impacts. Forecast inputs incorporated continuous manufacturing adoption curves and hospital GPO contract renewal patterns.
Underlying measurement precision varies by segment; extended-release capsules and injectable formulations carry tighter precision than commoditized immediate-release tablets due to concentrated manufacturer bases. Forecasts reflect assumptions regarding ANDA approval timelines and EPA enforcement intensity that could revise trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Infliximab Market
Pharmaceuticals
Performance Enhancing Drugs Market
Pharmaceuticals
Anti-Radiation Drugs Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Global Anti-Infective Agents Market
Pharmaceuticals
Oxycodone Market
Pharmaceuticals
Drug-Loaded Oral Thin Films Market
Pharmaceuticals
Normal Saline for Parenteral Use Market
Pharmaceuticals
Hepatitis Therapeutics Market
Pharmaceuticals
Gabapentin Market
Pharmaceuticals
Indobufen API Market
Pharmaceuticals
Latin America Generic Injectables Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Vaginal Antifungals Market
Pharmaceuticals
Acne Drugs Market