
 Global Zika Vaccines Market | 2026-2036
Global Zika Vaccines Market Size, Share, and Industry Trends Forecast 2026-2036
Global Zika Vaccines Market Foresight
mRNA platforms are restructuring cost structures across the Zika vaccine pipeline by replacing conventional egg-based production with cell-free synthesis systems. Moderna Inc. leverages its infectious disease mRNA infrastructure to accelerate platform adaptability. Bharat Biotech International Ltd. anchors its position through domestic manufacturing scale and established cold-chain distribution across endemic zones. Pfizer Inc. competes via lipid nanoparticle formulation expertise transferred from its COVID-19 program.
Zika vaccines are prophylactic immunological preparations designed to induce neutralizing antibodies against Zika virus envelope proteins, typically manufactured through recombinant DNA technology or nucleic acid amplification in bioreactor systems, with stability requirements dictating ultra-cold or standard refrigerated storage profiles depending on platform. Their primary purpose is preventing congenital Zika syndrome and Guillain-Barré syndrome in populations exposed to Aedes aegypti vectors. DNA-based candidates occupy the fastest-expanding pipeline segment due to thermostability advantages that simplify last-mile distribution in tropical climates. Protein subunit approaches dominate current Phase II trials because established adjuvant systems reduce regulatory uncertainty. Live attenuated platforms face structural headwinds from pregnancy-contraindication concerns that limit target population breadth.
FDA breakthrough therapy designation and EMA priority medicines status create divergent approval timelines that shape regional launch sequencing and manufacturing investment decisions. WHO prequalification standards dictate cold-chain compliance benchmarks that filter out platform technologies lacking thermal stability below minus twenty degrees Celsius. Brazil's ANVISA and India's CDSCO maintain accelerated review pathways for epidemic-threat vaccines, though local clinical trial requirements extend registration timelines. Stakeholders must monitor Phase III readouts and vector surveillance data to time manufacturing commitments before outbreak cycles trigger emergency procurement protocols.
Market Dynamics
mRNA platform standardization is compressing development timelines and redistributing manufacturing investment toward cell-free synthesis infrastructure, fundamentally altering how vaccine economics scale across tropical corridors.
Growth Catalysts
- WHO Prequalification Pathways:Streamlined emergency-use frameworks accelerate procurement authorization for vector-borne disease candidates in endemic zones.
- Aedes Surveillance Program Expansion:Brazil's Ministry of Health and Southeast Asian vector-control agencies are expanding preventive immunization protocols ahead of outbreak cycles.
- Thermostable DNA Platforms:Ambient-temperature stability eliminates ultra-cold chain requirements, unlocking last-mile distribution in rural tropical regions lacking minus-eighty infrastructure.
Market Restraints
- Pregnancy Contraindication Limitations:Live-attenuated platform candidates face structural exclusion from core target populations due to reproductive-age safety restrictions.
- Adjuvant Supply Concentration:Squalene and lipid nanoparticle precursor manufacturing clusters in European and North American chemical corridors create input vulnerability.
- Phase III Trial Cost Burden:Seroprevalence variability across endemic geographies forces multi-site enrollment that inflates per-patient trial expenditure.
Strategic Opportunities
- Combination Zika-Dengue Formulations:Shared Aedes aegypti vector ecology creates white space for tetravalent or pentavalent arbovirus candidates addressing co-circulation patterns.
- India CDSCO Accelerated Review:Domestic manufacturers gain regulatory tailwind through epidemic-threat fast-track pathways that compress registration timelines.
- Point-of-Care Cold-Chain Bypass:Lyophilized subunit presentations enable direct-to-clinic distribution models that disintermediate centralized pharmacy networks.
Industry Challenges
- Correlates of Protection Uncertainty:Lack of validated immunological surrogate endpoints complicates Phase III trial design and regulatory endpoint negotiation with FDA and EMA.
- Vector Surveillance Data Fragmentation:Inconsistent national reporting standards for Aedes density and Zika seroprevalence obscure demand forecasting for manufacturing scale-up decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Zika Vaccines Market |
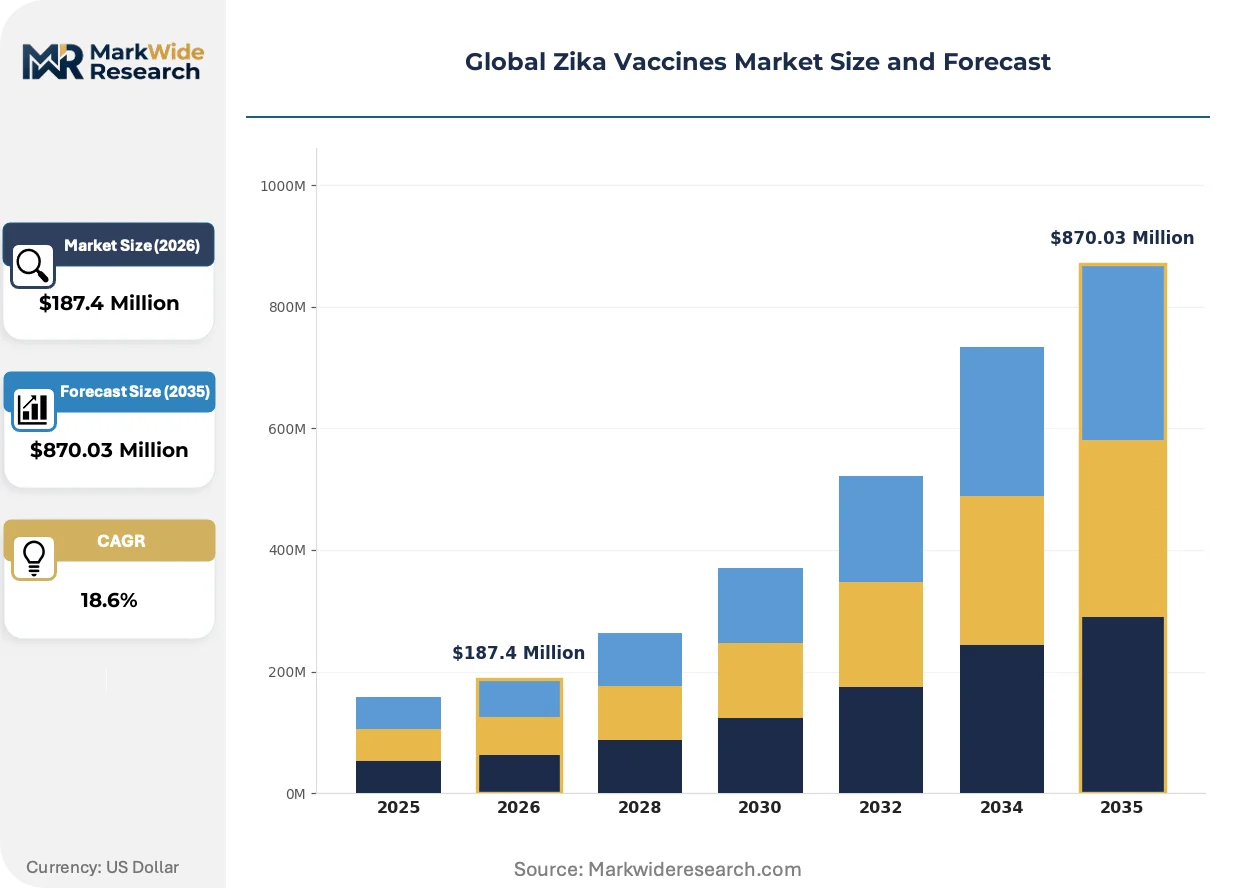
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vaccine Type: Live Attenuated, Inactivated, DNA-based, Protein Subunit, Viral Vector Target Population: Pregnant Women, Infants, Adults, Elderly, Travelers Administration Route: Intramuscular, Subcutaneous, Intradermal, Oral, Nasal End User: Public Health Agencies, Hospitals, Research Institutes, Travel Clinics, Military Medical Units |
| Companies Covered | Moderna Inc., Pfizer Inc., Valneva SE, Johnson & Johnson, GlaxoSmithKline, Takeda Pharmaceutical, Bharat Biotech International Ltd., Inovio Pharmaceuticals Inc., Sanofi Pasteur, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Zika Vaccines Market Shifts & Advancements
Synthetic biology and nucleic acid delivery systems are collapsing the traditional vaccine development paradigm, compressing preclinical-to-clinic timelines while introducing new manufacturing complexity.
Self-amplifying mRNA (sa-mRNA) constructs are rewriting dose-response economics in the Zika pipeline by enabling lower antigen mass per immunization. Brazilian immunization programs and Southeast Asian procurement agencies are evaluating sa-mRNA candidates for inclusion in arbovirus combination schedules. The technology is rewriting platform competitiveness by reducing per-dose manufacturing cost while maintaining neutralizing antibody titers comparable to conventional mRNA.
EMA's Priority Medicines (PRIME) designation and FDA Breakthrough Therapy pathways are creating divergent approval timelines that shape regional launch sequencing. Manufacturers must navigate parallel rolling-review submissions with distinct data-package expectations for each regulator. DNA-based candidates with thermostability advantages are prioritizing Brazil's ANVISA and India's CDSCO pathways where cold-chain infrastructure gaps favor platform selection.
Public health agencies are consolidating procurement through Pan American Health Organization (PAHO) and WHO pooled purchasing mechanisms that compress price negotiation windows and demand volume guarantees. Direct manufacturer-to-government contracting is displacing traditional distributor networks in Brazil, Colombia, and Thailand. This concentration is most visible in Southeast Asian ministries of health that are centralizing arbovirus vaccine acquisition under single-tender frameworks.
Global Zika Vaccines Market Segmentation
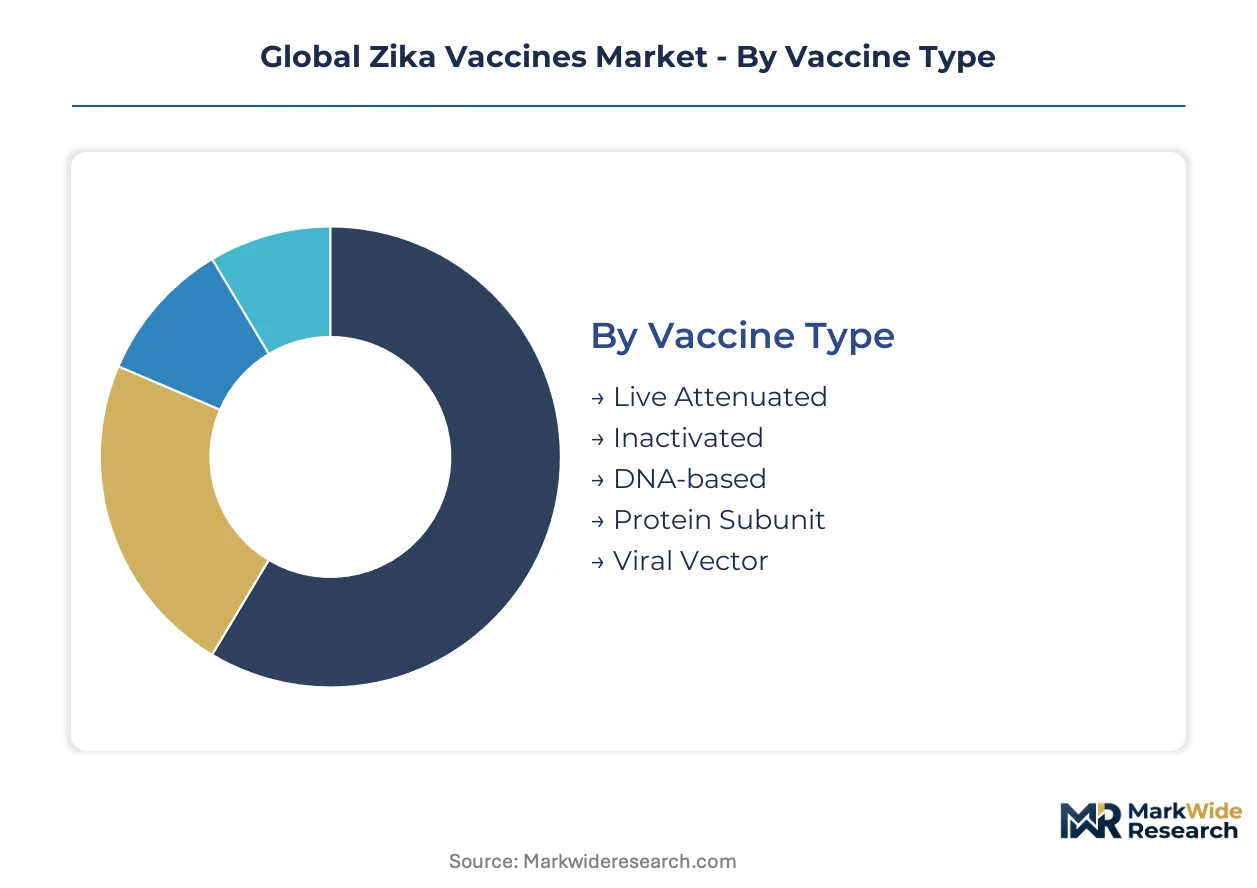
Zika vaccine procurement patterns diverge sharply across platform technologies, population risk profiles, and distribution infrastructure. Manufacturers must align pipeline candidates with specific cold-chain capabilities, regulatory pathways, and target demographics concentrated in tropical corridors.
Vaccine Type:
Platform selection determines thermal stability requirements, manufacturing capital intensity, and access to accelerated regulatory pathways across Brazil, India, and Southeast Asian markets.
- Live Attenuated:Replication-competent formulations induce durable cellular immunity but carry pregnancy contraindications that restrict deployment among women of reproductive age. Brazil's ANVISA maintains heightened pharmacovigilance protocols for live arbovirus candidates. Demand concentrates in military medical units and adult male cohorts where safety restrictions prove manageable.
- DNA-based:Plasmid vectors demonstrate ambient-temperature stability exceeding twelve months, eliminating ultra-cold infrastructure requirements. India's CDSCO fast-track pathway prioritizes thermostable platforms for rural distribution. Procurement from Southeast Asian public health agencies is climbing fastest as last-mile cold-chain gaps persist.
- Inactivated:Whole-virus formulations rely on established adjuvant systems and conventional refrigerated storage. Manufacturing scales through egg-based or cell-culture infrastructure common to influenza production networks.
- Protein Subunit:Purified envelope protein candidates dominate Phase II trial activity due to predictable immunogenicity profiles and established regulatory precedents from dengue vaccine development.
- Viral Vector:Adenovirus and vesicular stomatitis virus platforms leverage prior Ebola and COVID-19 manufacturing investments, though pre-existing immunity to common vector serotypes complicates dose optimization.
DNA-based platforms lead volumes today; DNA-based platforms are gaining share fastest across tropical corridor procurement.
Target Population:
Risk stratification by reproductive status, age, and travel exposure shapes immunization program design and pricing negotiations with national health ministries.
- Pregnant Women:Congenital Zika syndrome prevention represents the highest-value indication, driving premium pricing for platforms with demonstrated safety in first-trimester exposure. Brazil's Ministry of Health prioritizes preconception immunization protocols. Demand concentrates in urban coastal municipalities with established Aedes surveillance.
- Adults:Reproductive-age cohorts in endemic zones require flexible scheduling around pregnancy planning, favoring single-dose or rapid-schedule platforms. Travel clinics in the United States and European Union represent concentrated procurement for pre-departure immunization.
- Infants:Pediatric indications remain underdeveloped due to seroprevalence uncertainty and ethical constraints on placebo-controlled trials in vulnerable populations.
- Elderly:Immunosenescence considerations favor adjuvanted formulations or higher antigen doses, with demand fragmented across research protocols rather than routine immunization programs.
- Travelers:Time-limited protection needs and price sensitivity favor single-dose platforms with rapid onset, though current pipeline candidates require multi-dose schedules that constrain market penetration.
Adults lead volumes today; pregnant women segments are expanding most quickly as safety data accumulates.
Administration Route:
Delivery mechanism selection intersects with cold-chain infrastructure, healthcare worker training requirements, and patient compliance patterns across diverse clinical settings.
- Intramuscular:Deltoid injection remains the standard for protein subunit and inactivated formulations, requiring trained healthcare personnel and generating sharps waste management costs. Hospital networks in Thailand and Colombia maintain preference for this route due to established workflow integration.
- Intradermal:Reduced antigen dose requirements and potential for microarray patch delivery are attracting investment from programs targeting rural health posts with limited cold-chain reach.
- Subcutaneous:Alternative injection site for live attenuated candidates, with absorption kinetics influencing reactogenicity profiles in tropical climates.
- Oral:Thermostable enteric formulations remain preclinical, though mucosal immunity induction could eliminate cold-chain requirements entirely.
- Nasal:Aerosol delivery platforms face technical barriers to consistent dosing but offer potential for mass immunization campaigns without needle infrastructure.
Intramuscular routes dominate procurement today; intradermal platforms show steepest expansion trajectory as microarray technologies mature.
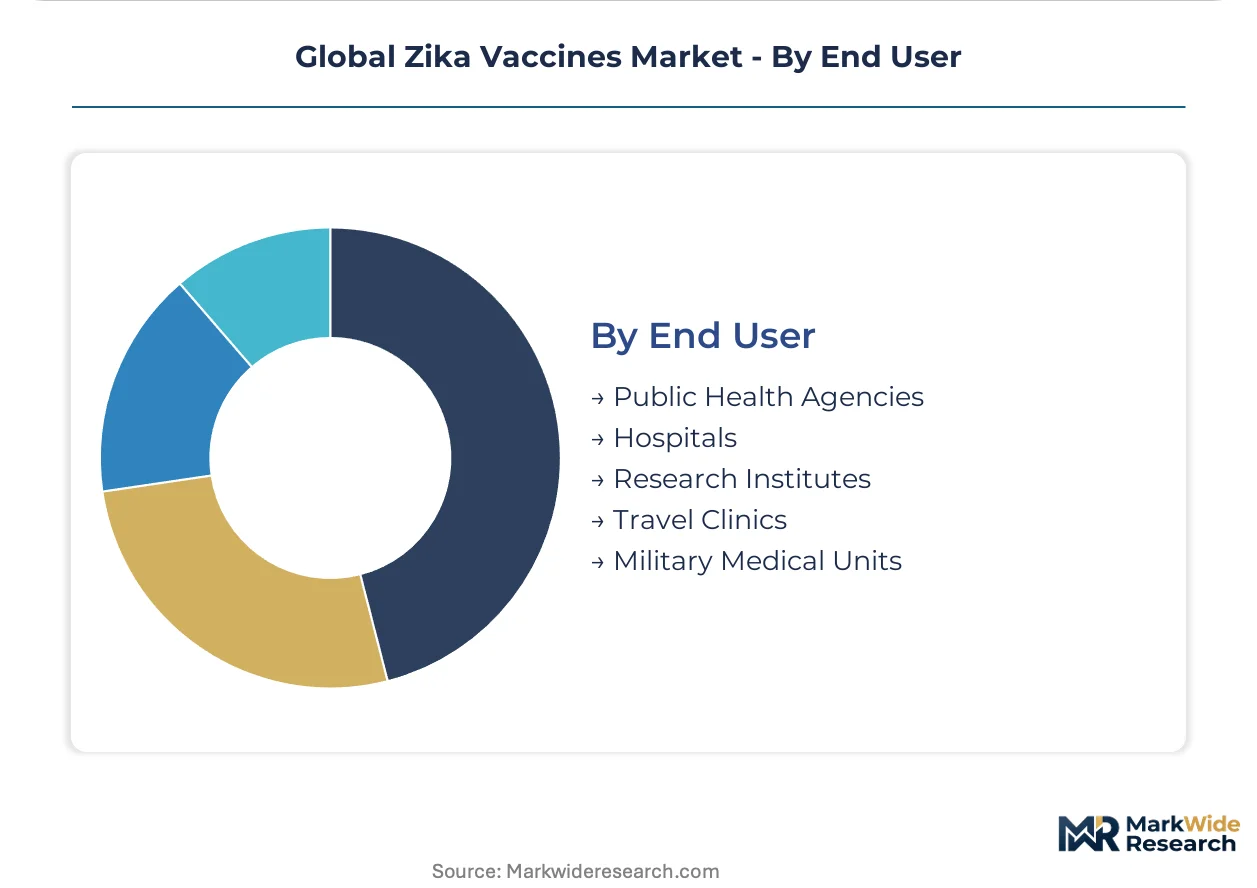
End User:
Institutional purchasing power and procurement centralization are restructuring distribution economics away from fragmented private channels toward consolidated public tenders.
- Public Health Agencies:Brazil's Ministry of Health and Thailand's Department of Disease Control command volume guarantees that reshape manufacturing scale decisions. PAHO pooled purchasing mechanisms compress price negotiation windows and demand multi-year supply commitments.
- Hospitals:Maternity and infectious disease units in urban Brazilian and Colombian medical centers represent concentrated demand for preconception and prenatal immunization protocols.
- Research Institutes:NIH, Fiocruz, and Mahidol University maintain sponsored trial networks that influence platform selection through investigator-initiated study design.
- Travel Clinics:Private outpatient settings in the United States and European Union serve pre-departure travelers with limited reimbursement coverage, constraining price elasticity.
- Military Medical Units:US Department of Defense and Brazilian Armed Forces maintain stockpiling protocols for deployment to endemic zones, with procurement insulated from civilian regulatory timelines.
Public health agencies lead volumes today; research institutes are gaining share fastest as trial networks expand across endemic geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's São Paulo-Rio de Janeiro corridor anchors vaccine procurement volumes through ANVISA-coordinated national immunization programs targeting Aedes-endemic municipalities.
Brazil
ANVISA maintains accelerated review pathways for epidemic-threat vaccines while the Ministry of Health expands preconception immunization protocols in coastal urban centers. Fiocruz anchors domestic clinical trial networks across Rio de Janeiro and São Paulo states. Manufacturing investment concentrates in the São Paulo biocluster where Bharat Biotech International Ltd. and domestic partners scale thermostable platform production.
United States
FDA breakthrough therapy designation compresses development timelines for mRNA candidates targeting travelers and military medical units. NIH-sponsored investigator networks span Maryland, Massachusetts, and California research corridors. Moderna Inc. leverages infectious disease infrastructure in Cambridge, Massachusetts while Inovio Pharmaceuticals Inc. anchors DNA platform development in San Diego.
India
CDSCO fast-track pathways prioritize thermostable platforms for rural distribution networks lacking ultra-cold infrastructure. Bharat Biotech International Ltd. scales manufacturing from its Hyderabad facilities while supplying Southeast Asian procurement agencies through established cold-chain partnerships. Clinical trial activity concentrates at AIIMS Delhi and CMC Vellore.
Thailand
The Department of Disease Control centralizes arbovirus vaccine acquisition under single-tender frameworks favoring combination Zika-Dengue candidates. Mahidol University maintains sponsored trial networks across Bangkok and surrounding provinces. Procurement from public health agencies climbs as vector surveillance programs expand in Chiang Mai and Khon Kaen provinces.
United Kingdom
Valneva SE leverages Scottish manufacturing assets while pursuing EMA priority medicines designation for inactivated platform candidates. Research institutes in Oxford and London coordinate Phase II enrollment across European trial networks. Regulatory strategy emphasizes parallel rolling-review submissions with distinct data-package expectations for FDA and EMA pathways.
Global Zika Vaccines Market Competitive Landscape
Strategic partnerships dominate the current landscape as developers seek manufacturing scale and regulatory expertise beyond internal capabilities. The vendor base clusters around platform technology specialists with prior arbovirus or emerging infectious disease experience. Three archetypes define competitive positioning: mRNA platform standardizers leveraging COVID-19 infrastructure, thermostable DNA specialists targeting tropical distribution gaps, and established vaccine multinationals with adjuvant formulation depth. M&A activity and technology licensing agreements represent the primary competitive moves reshaping pipeline control.
Within the mRNA platform tier, Moderna Inc. and Pfizer Inc. occupy positions reflecting lipid nanoparticle expertise transferred from prior pandemic programs. Bharat Biotech International Ltd. anchors the thermostable DNA specialist archetype through domestic manufacturing scale and Southeast Asian distribution reach. Valneva SE exemplifies the multinational inactivated platform approach with European regulatory engagement and Scottish production assets.
| Leading Market Players |
|---|
| Moderna Inc. |
| Pfizer Inc. |
| Valneva SE |
| Johnson & Johnson |
| GlaxoSmithKline |
| Takeda Pharmaceutical |
| Bharat Biotech International Ltd. |
| Inovio Pharmaceuticals Inc. |
| Sanofi Pasteur |
| Others |
Supply & Pricing Matrix
Platform thermostability divergence between ultra-cold mRNA and ambient-stable DNA formulations manifests in divergent pricing architectures and supply chain capital requirements across Brazil, India, and Southeast Asian procurement corridors. Manufacturers of lipid nanoparticle-dependent candidates absorb cold-chain infrastructure costs that DNA platform competitors bypass, compressing net margins in tropical distribution zones while enabling premium positioning in travel clinic segments.
Pricing Analysis
Input-cost pass-through from squalene and lipid nanoparticle precursor markets intensifies pricing pressure on mRNA and protein subunit tiers, while DNA platforms draw from plasmid manufacturing inputs with more stable chemical supply bases. Three-tier pricing structure across WHO-prequalified, national-regulatory-approved, and research-grade supply levels separates institutional procurement from private travel clinic channels. Price differentiation hinges on cold-chain certification grade and multi-dose vial efficiency. Margins are tightening due to PAHO pooled purchasing concentration. Public health agencies in Brazil and Thailand exhibit highest price sensitivity; military medical units and research institutes demonstrate lowest elasticity.
Supply Chain Analysis
WHO prequalification and FDA breakthrough therapy certification gates filter supplier eligibility, concentrating active pharmaceutical ingredient manufacturing in the United States, India, and European bioclusters. Plasmid DNA production draws from E. coli fermentation capacity in Hyderabad and Boston corridors; lipid nanoparticle formulation rests on chemical precursor supply from German and Swiss specialty chemical producers. Single-source vulnerability in adjuvant squalene supply from European marine extraction creates concentration risk. Distribution runs through PAHO and WHO centralized procurement mechanisms that disintermediate traditional pharmaceutical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
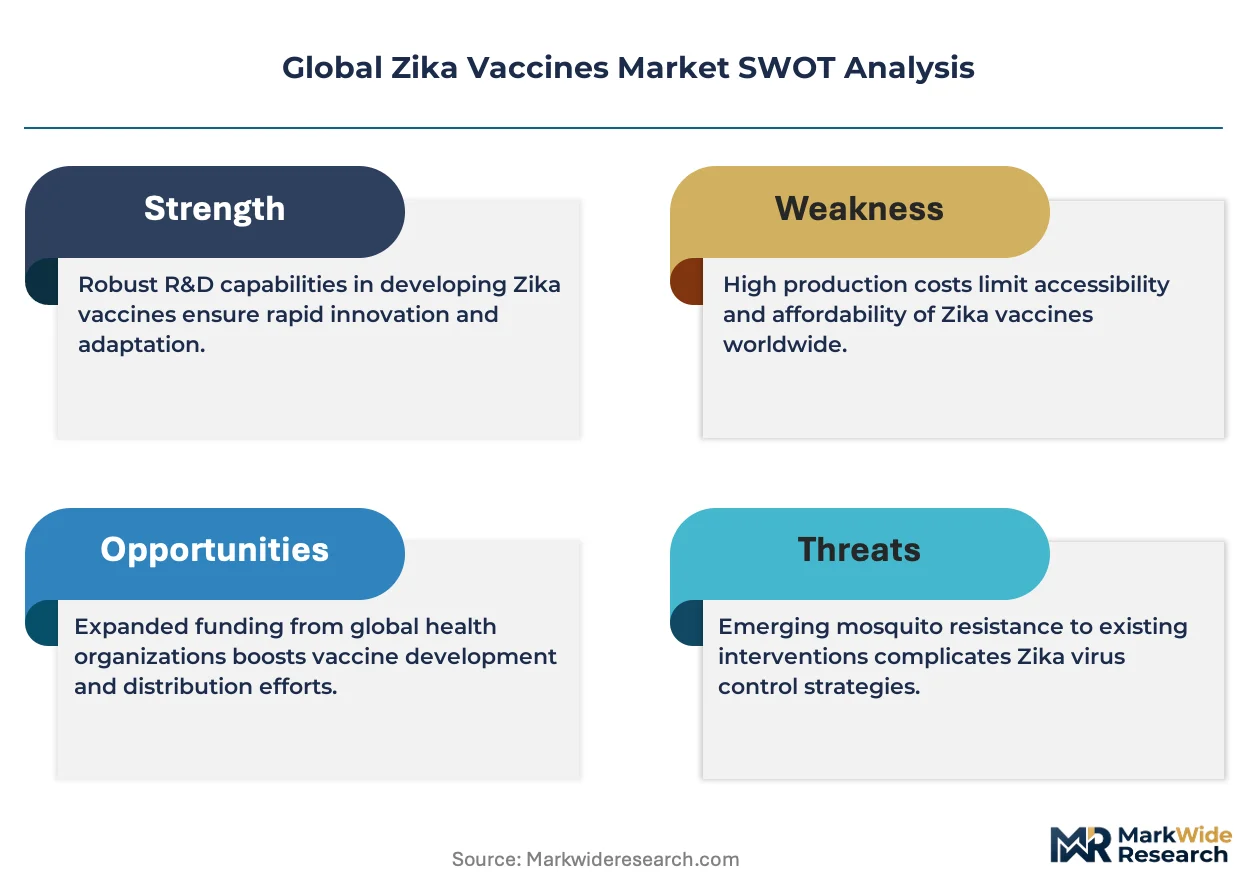
The Global Zika Vaccines Market functions as a stable compounder anchored by endemic vector ecology that perpetuates recurring outbreak cycles and sustained public health procurement budgets across tropical corridor nations.
For Market Incumbents: Cement platform leadership by securing WHO prequalification status ahead of competitor submissions, locking in multi-year PAHO supply agreements. Backward integration into plasmid manufacturing or lipid nanoparticle formulation insulates margin compression from chemical precursor volatility. Threats concentrate in thermostable DNA platform entrants targeting India's CDSCO pathway with lower cold-chain capital requirements. For New Entrants and Emerging Players: Direct government contracting portals in Brazil, Colombia, and Thailand represent the most penetrable route for bypassing established distributor relationships. White-space targets include combination Zika-Dengue formulations addressing co-circulation patterns and point-of-care lyophilized presentations eliminating pharmacy network dependency. Go-to-market positioning should emphasize ambient-tability credentials for rural tropical distribution gaps. For Investors and Strategic Acquirers: Consolidation pressure builds where Phase III trial networks require manufacturing scale beyond internal capitalization. Long-term viability favors platform-agnostic developers with regulatory expertise across FDA, EMA, and WHO pathways simultaneously. Acquisition targets cluster around thermostable DNA specialists with established Southeast Asian distribution partnerships. Signal to watch: ANVISA and CDSCO accelerated approval designations triggering manufacturing scale-up commitments.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Submission | Unlocks PAHO pooled procurement access for endemic zone volume guarantees. |
| Manufacturing Scale-Up in Hyderabad | Leverages India's CDSCO fast-track pathway and established cold-chain partnerships. |
| Combination Vaccine Development | Addresses Zika-Dengue co-circulation patterns in Brazilian and Southeast Asian vector programs. |
| Lyophilized Formulation Investment | Enables point-of-care distribution bypassing centralized pharmacy networks. |
| Regulatory Parallel Track Strategy | Accelerates market entry through simultaneous FDA breakthrough and EMA PRIME engagement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with vaccine development executives, regulatory affairs leads at ANVISA and CDSCO, formulary directors at Brazil's Ministry of Health, and hospital procurement managers in Thai public health systems with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and WHO prequalification databases. Bottom-up platform adoption modeling and top-down procurement budget triangulation anchored volume estimates.
Comparable-period anchoring referenced historical arbovirus vaccine development timelines and outbreak cycle patterns across the projection horizon. Segmentation dimensions modeled include vaccine platform type, target population risk profile, administration route, and regional regulatory cluster. CAGRs derived from epidemiological surveillance data correlation with immunization program expansion trajectories. Forecast inputs incorporated vector density indices and seroprevalence survey trends without year-specific anchoring.
Phase III readout delays, vector surveillance data fragmentation, and adjuvant supply disruptions are the dominant revision risks to modeled adoption curves. Forecasts reflect documented assumptions on regulatory pathway timing and procurement centralization momentum. A model refresh is warranted upon material change in WHO prequalification queue sequencing or ANVISA accelerated review designation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Depression Drugs Market
Pharmaceuticals
Efinaconazole Market
Pharmaceuticals
Global Rx to OTC Switches Market
Pharmaceuticals
Sodium Aescinate Market
Pharmaceuticals
Global Prefilled Syringes Drug Molecules Market
Pharmaceuticals
Global Ethical Pharmaceuticals Market
Pharmaceuticals
New Zealand Diabetes Drugs Market
Pharmaceuticals
Latin America Sodium-Glucose Cotransport-2 (SGLT-2) Inhibitor Market
Pharmaceuticals
Europe Vaccines Market
Pharmaceuticals
Global Self-Administered Drugs Market
Pharmaceuticals
Gardasil (HPV Vaccine) Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
France Diabetes Drugs Market
Pharmaceuticals
Adapalene Market