
 Radiation Protection Cabins Market | 2026-2036
Radiation Protection Cabins Market Size, Share, and Industry Trends Forecast 2026-2036
Radiation Protection Cabins Market Analytics
Hospital procurement of radiation protection cabins is shifting toward integrated diagnostic-imaging suites as healthcare systems consolidate radiology services. Mirion Technologies leverages its nuclear instrumentation heritage to anchor positions in research facility and power plant segments. MAVIG GmbH specializes in medical-grade shielding solutions that sustain premium positioning across European hospital networks. Nelco competes on manufacturing scale for concrete-based fixed installations serving industrial radiography users.
Radiation protection cabins are engineered enclosures incorporating lead, steel, or composite shielding layers designed to attenuate ionizing radiation exposure for personnel and adjacent spaces, typically achieving attenuation ratings specified by IEC 60513 for medical applications. Fixed cabins fabricated with lead-lined steel walls dominate current hospital infrastructure spending, while modular units represent the fastest-growing configuration as facilities pursue reconfigurable shielding for multi-modal imaging suites. Composite material cabins command narrower volume but higher margin pools where weight reduction enables ceiling-suspended or retrofit installations in older buildings.
The FDA enforces 21 CFR 1020.32 performance standards for diagnostic x-ray systems that directly specify shielding requirements for operator protection areas, while the EU Medical Device Regulation mandates notified body involvement for cabin systems classified as Class I or IIa accessories. OSHA ionizing radiation standards under 29 CFR 1910.96 establish workplace exposure limits that drive industrial user replacement cycles. Stakeholders must monitor evolving IEC and ISO standards for composite shielding validation protocols as non-lead materials gain regulatory traction.
Market Dynamics
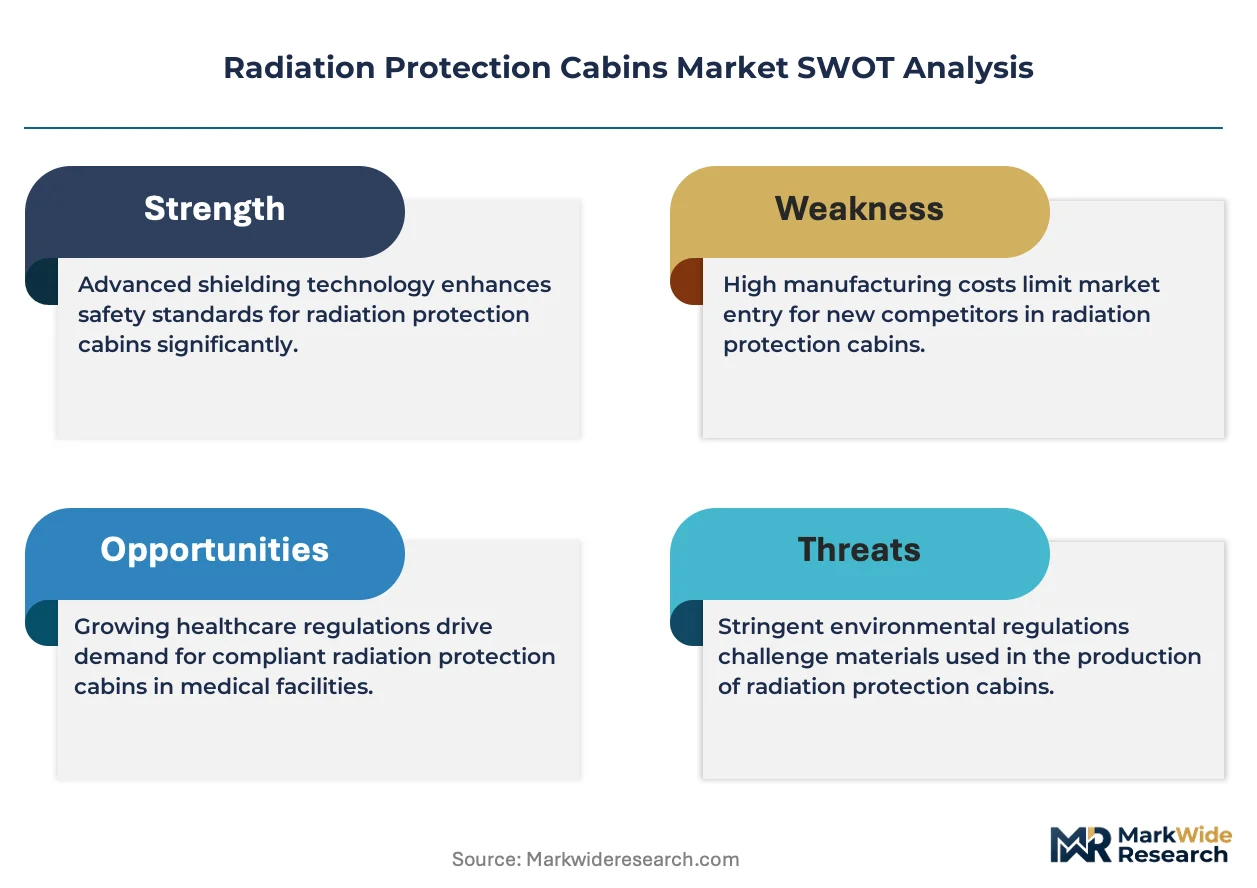
Hospital consolidation into integrated diagnostic networks is compressing procurement timelines and demanding reconfigurable shielding architectures that span multiple imaging modalities within single facilities.
Growth Catalysts
- EU Medical Device Regulation:The MDR's stricter conformity assessment for Class IIa cabin accessories is accelerating replacement cycles across European hospital networks as older installations lose certification validity.
- Multi-modal imaging suites:Healthcare systems consolidating radiology, cardiology, and oncology services into unified diagnostic centers require shielding solutions serving PET-CT, angiography, and linear accelerator combinations.
- Lead composite materials:Polymer-lead hybrid shielding achieving equivalent attenuation at 40% weight reduction is enabling ceiling-suspended installations in structurally constrained Japanese and German facilities.
Market Restraints
- Lead price volatility:Primary lead smelter concentration in China creates input cost instability for traditional lead-lined steel cabin fabricators.
- Concrete fixed-installation inertia:Industrial radiography users in shipbuilding and aerospace maintain sunk-cost attachment to permanent concrete bunkers, slowing modular adoption.
- IEC 60513 validation gaps:Incomplete international standards for non-lead composite attenuation testing create regulatory friction delaying product certification.
Strategic Opportunities
- India hospital infrastructure:Greenfield medical city developments in Hyderabad and Chennai lack legacy shielding investments, enabling direct specification of modular composite cabins.
- Research isotope handling:Cyclotron and radiopharmaceutical production facilities require specialized cabin configurations with integrated HVAC and waste handling systems.
- OSHA 29 CFR 1910.96 enforcement:Intensified industrial workplace inspection regimes in the United States are triggering compliance-driven replacement of aging radiography enclosures.
Industry Challenges
- Radiation health physics specialization:Shortage of certified medical health physicists capable of specifying attenuation requirements for multi-vendor imaging suites extends design consultation timelines.
- Legacy building structural assessment:Retrofit installations in pre-1990 hospital infrastructure require costly engineering surveys to verify floor loading for lead-shielded modular units.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiation Protection Cabins Market |
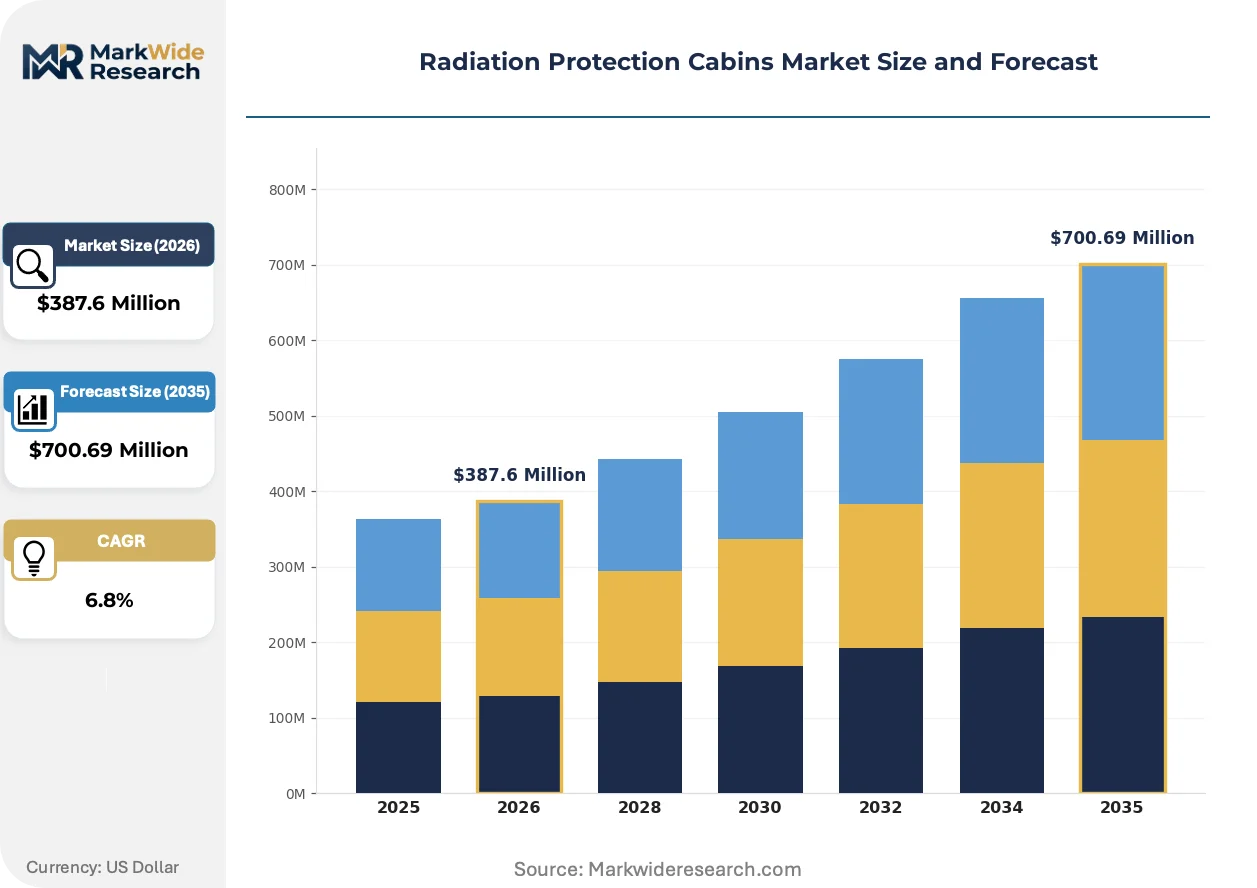
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Cabins, Fixed Cabins, Modular Units, Specialized Rooms Material: Lead, Steel, Concrete, Composite Materials End User: Hospitals, Research Facilities, Nuclear Power Plants, Industrial Users Application: Diagnostic Imaging, Radiation Therapy, Laboratory Research, Nuclear Medicine |
| Companies Covered | Mirion Technologies, Marswell Group of Companies, MAVIG GmbH, Gaven Industries, Marshield, Burlington Medical, Nelco, ETS-Lindgren, Ray-Bar Engineering, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiation Protection Cabins Market Evolving Landscape
Shielding material science and regulatory validation protocols are converging to displace century-old lead-dependent architectures across medical and industrial radiation containment applications.
Tungsten-polymer composite shielding is modularizing fixed-installation dominance in diagnostic imaging. The material achieves NCRP Report No. 147 attenuation equivalency at reduced mass, enabling hospital engineering teams to suspend enclosures from standard ceiling grids. Siemens Healthineers and GE Healthcare imaging suite deployments in Germany and Japan are specifying these composites for PET-CT bunkers where floor loading constraints previously prohibited lead construction.
REACH authorization timelines for lead compounds are compressing substitution investment horizons across European manufacturing. The ECHA sunset date approaching for certain lead applications is forcing cabin fabricators to accelerate tungsten and bismuth composite R&D programs. German shielding specialists MAVIG and nuclear research facilities at Forschungszentrum Jülich are collaborating on validated non-lead attenuation protocols ahead of regulatory deadlines.
Integrated service contracts bundling shielding design, installation, and dosimetry monitoring are displacing discrete equipment procurement in United States hospital systems. Tenet Healthcare and HCA Healthcare procurement frameworks now specify multi-year shielding performance guarantees rather than capital equipment purchases. This shift concentrates vendor relationships with full-service radiation safety firms capable of underwriting ongoing compliance liability.
Radiation Protection Cabins Market Segmentation
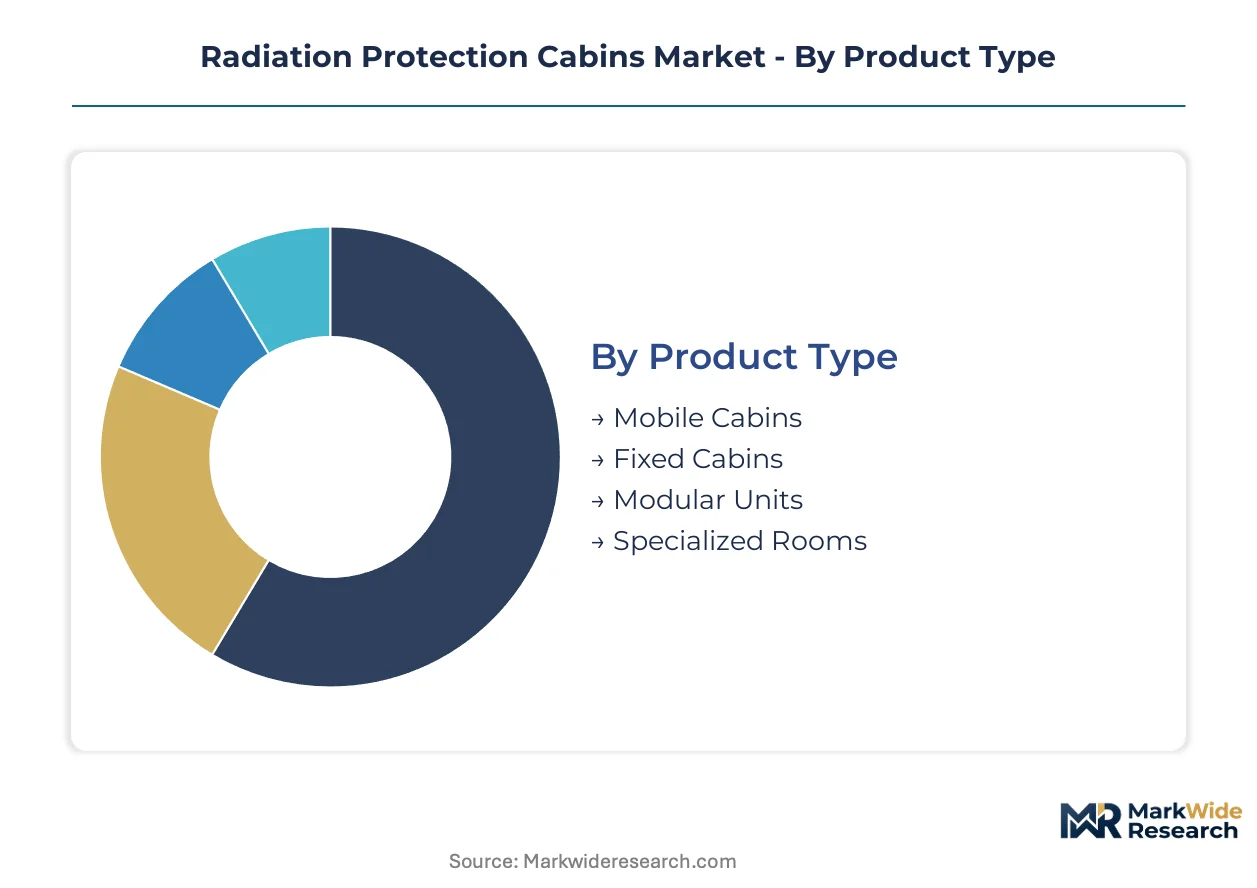
Radiation protection cabin specifications diverge sharply across medical, industrial, and research deployments, with regulatory pathways dictating material choices and architectural configurations. Procurement patterns cluster around installation permanence, shielding performance tiers, and end-user compliance maturity.
Product Type:
Mobile cabins require FDA 510(k) clearance for diagnostic use, while fixed installations trigger EU MDR Class IIa notified body assessment for operator protection accessories.
- Mobile Cabins:Self-contained shielded enclosures mounted on casters or motorized bases, typically achieving 1-2mm lead equivalence. Demand concentrates in United States outpatient imaging centers where OSHA 29 CFR 1910.96 drives temporary shielding for contract radiography services.
- Fixed Cabins:Permanent lead-lined steel or concrete structures integrated into building architecture. German hospital networks absorb dominant volume as EU MDR replacement cycles accelerate decommissioning of uncertified legacy installations.
- Modular Units:Prefabricated panel systems enabling rapid reconfiguration. Japanese facilities specify these for PET-CT suite renovations where floor loading limits prohibit monolithic construction.
- Specialized Rooms:Custom-engineered enclosures with integrated HVAC, interlocks, and waste handling. Research isotope handling at cyclotron facilities demands these configurations.
Leading the category by volume: Fixed Cabins. Growing fastest: Modular Units.
Material:
Material selection maps directly to weight-bearing capacity, attenuation equivalence requirements, and REACH authorization timelines for lead compounds.
- Lead:Traditional shielding metal specified in IEC 60513, now facing substitution pressure from ECHA sunset dates. Still dominates concrete-fixed industrial radiography bunkers in United States shipyards.
- Steel:Structural substrate for lead-lined medical cabins, with fabrication concentrated in German and Japanese metalworking clusters serving hospital procurement frameworks.
- Concrete:High-density barite or magnetite aggregate achieving mass attenuation for industrial gamma radiography. Aerospace NDT facilities in France and Germany maintain sunk-cost attachment to permanent bunkers.
- Composite Materials:Tungsten-polymer or bismuth-resin hybrids achieving NCRP Report No. 147 equivalence at reduced mass. Ceiling-suspended diagnostic suites in structurally constrained Japanese and German hospitals drive specification.
Lead retains volume dominance. Composite materials expand most quickly on regulatory substitution mandates.
End User:
End-user sophistication determines whether procurement emphasizes capital equipment purchase or bundled service contracts with ongoing compliance liability.
- Hospitals:Integrated diagnostic networks consolidating radiology, cardiology, and oncology services. United States health systems now specify multi-year shielding performance guarantees rather than discrete equipment purchases.
- Research Facilities:Cyclotron and radiopharmaceutical production sites requiring specialized configurations with waste handling integration. Forschungszentrum Jülich and comparable European nuclear research centers anchor demand.
- Nuclear Power Plants:Maintenance and outage support cabins for reactor vessel inspection. Mirion Technologies serves this segment through nuclear instrumentation heritage.
- Industrial Users:Shipbuilding, aerospace, and pipeline inspection operations. OSHA enforcement intensity in United States manufacturing triggers compliance-driven replacement cycles.
Hospitals command the largest revenue pool. Research facilities show steepest expansion trajectory on radiopharmaceutical production growth.
Application:
Application-specific shielding requirements vary by photon energy spectrum, occupancy factors, and adjacent space utilization.
- Diagnostic Imaging:X-ray and CT operator protection cabins governed by FDA 21 CFR 1020.32 performance standards. German and Japanese hospital radiology departments absorb dominant installation share.
- Radiation Therapy:Linear accelerator bunkers requiring megavoltage attenuation. Concrete or steel-reinforced lead construction dominates given structural loading requirements.
- Laboratory Research:Isotope handling enclosures with integrated containment. European research facilities lead specification of modular composite alternatives ahead of REACH deadlines.
- Nuclear Medicine:PET-CT and SPECT shielding where tungsten-polymer composites enable ceiling suspension in retrofit installations.
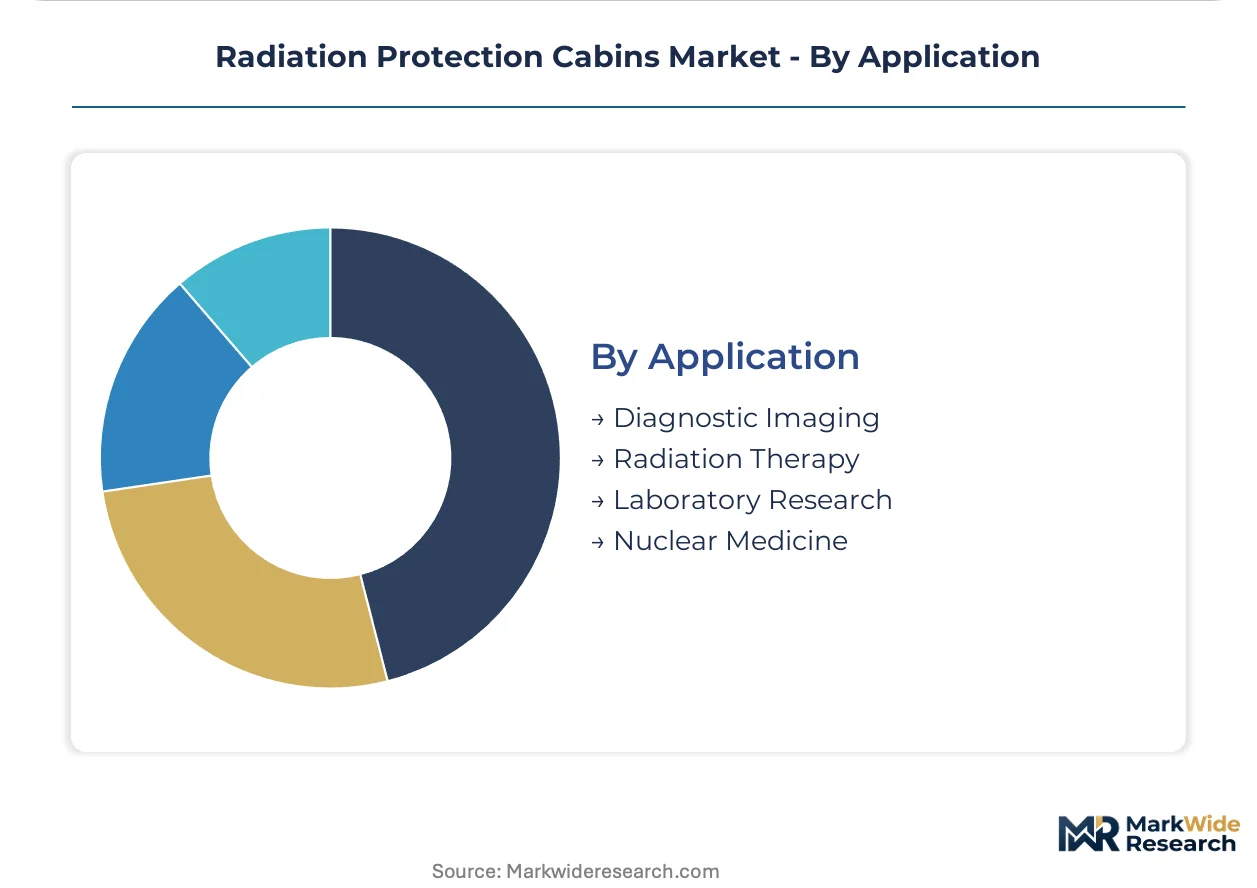
Diagnostic Imaging leads by installed base. Nuclear Medicine gains share fastest on PET-CT deployment expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Jebel Ali Free Zone in Dubai concentrates Middle Eastern distribution for radiation shielding components, while special economic zones in Shenzhen and Chennai anchor Asia-Pacific manufacturing clusters for medical-grade enclosures.
United States
OSHA enforcement intensification under 29 CFR 1910.96 triggers compliance-driven replacement of aging radiography enclosures across manufacturing facilities. The FDA maintains 21 CFR 1020.32 performance standards for diagnostic x-ray shielding that shape procurement specifications. Houston's Texas Medical Center and Boston's Longwood Medical Area absorb dominant volumes of fixed cabin installations for consolidated diagnostic networks.
Germany
EU MDR Class IIa notified body requirements accelerate decommissioning of uncertified legacy installations across hospital networks. ECHA REACH authorization timelines for lead compounds compress substitution investment horizons for domestic fabricators. The Forschungszentrum Jülich nuclear research cluster and Munich's hospital procurement consortia drive specification of tungsten-polymer composite alternatives ahead of regulatory deadlines.
Japan
METI building code constraints on floor loading capacities in urban facilities drive ceiling-suspended composite cabin adoption. PMDA alignment with IEC 60513 standards governs medical device accessory classification for shielding enclosures. Osaka's PET-CT renovation pipeline and Tokyo's diagnostic imaging consolidation projects concentrate modular unit demand in structurally constrained metropolitan hospitals.
India
Greenfield medical city developments in Hyderabad and Chennai lack legacy shielding investments, enabling direct specification of modular composite cabins. CDSCO medical device rules increasingly reference IEC shielding standards for imported diagnostic equipment enclosures. The Gujarat pharmaceutical manufacturing corridor and Bangalore's research institution cluster generate parallel demand for specialized isotope-handling configurations.
United Kingdom
NHS England diagnostic imaging consolidation programs compress procurement timelines for reconfigurable shielding architectures spanning multi-modal suites. MHRA post-Brexit regulatory alignment with EU MDR transitional provisions affects cabin accessory conformity assessment pathways. London's Guy's and St Thomas' NHS Foundation Trust and Manchester's radiology network procurement frameworks exemplify outcome-based shielding performance contracting.
Radiation Protection Cabins Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with medical-grade shielding favoring established European names while industrial radiography tolerates price-driven fabrication. The vendor base concentrates around three tiers: full-service radiation safety firms underwriting compliance liability, component-scale metalworkers supplying lead-lined substrates, and composite material specialists capturing premium retrofit opportunities. Dominant competitive moves include strategic partnerships bundling design-installation-dosimetry services and geographic expansion through distributor networks in underpenetrated Asian hospital markets.
Among German and Japanese fabrication clusters, MAVIG GmbH exemplifies the medical-grade shielding specialist archetype, while Mirion Technologies occupies a position bridging nuclear instrumentation heritage with research facility containment requirements. Nelco represents the scale-driven industrial segment serving permanent concrete bunker demand in United States shipbuilding and aerospace non-destructive testing operations.
| Leading Market Players |
|---|
| Mirion Technologies |
| Marswell Group of Companies |
| MAVIG GmbH |
| Gaven Industries |
| Marshield |
| Burlington Medical |
| Nelco |
| ETS-Lindgren |
| Ray-Bar Engineering |
| Others |
Value Network & Pricing Analysis
Certified medical health physicists concentrated in Germany and Japan command wage premiums that compress pricing spreads between premium modular composite cabins and economy-grade lead-lined fixed installations. Labor-cost differentials between these specialist clusters and emerging fabrication centers in India widen tiered pricing structures for equivalent shielding performance specifications.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent separate urgent replacement orders from standard-schedule procurement in European hospital networks. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade under EU MDR Class IIa pathways and after-sales service bundling. Cost compression in economy-grade lead-lined steel cabins is intensifying because primary lead smelter concentration in China transmits commodity volatility directly to fabricator margins. Industrial radiography buyers in United States shipyards exhibit highest price sensitivity, while research facilities at Forschungszentrum Jülich demonstrate lowest sensitivity given compliance-liability underwriting requirements.
Supply Chain Analysis
Lead supply rests on Chinese primary smelting capacity, German specialty steel fabrication clusters, and Japanese tungsten-polymer composite processing facilities. Raw material dependencies span lead ingots, high-density barite aggregates for concrete formulations, and tungsten powder for attenuation-equivalent composites. Single-source vulnerability in Chinese lead concentrate creates tariff exposure and price transmission risk for traditional cabin fabricators. Distribution runs through hospital procurement consortia in Germany, GPO frameworks in United States health systems, and direct specification by nuclear research facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified shielding engineering capacity constraints prop pricing power for certified fabricators, as EU MDR notification body bottlenecks extend certification timelines beyond twelve months.
For Market Incumbents: Deploy backward integration into tungsten-polymer composite substrate production to secure non-lead supply chains ahead of ECHA REACH sunset dates. Accelerate notified body relationship investments to compress EU MDR Class IIa certification cycles for modular cabin accessories. Defensive positioning against emerging Indian fabricators requires locking multi-year performance guarantees with United States health system GPOs. For New Entrants and Emerging Players: Begin with greenfield medical city developments in Hyderabad and Chennai where legacy shielding absence enables direct composite cabin specification without displacement costs. Target cyclotron facility configurations with integrated HVAC and waste handling systems as the most penetrable research segment. Pursue partnership-based go-to-market models with established European shielding design firms to transfer regulatory validation expertise. For Investors and Strategic Acquirers: Re-rating potential sits with full-service radiation safety firms underwriting compliance liability given OSHA enforcement intensification and bundled service contract displacement of capital equipment procurement. Long-term viability favors vendors with vertical control over composite material supply and in-house health physics certification capabilities. Monitor ECHA authorization timeline acceleration as the inflection signal for lead substitution investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Composite Material R&D Partnership | MAVIG GmbH collaboration with Forschungszentrum Jülich accelerates non-lead attenuation protocol validation ahead of regulatory deadlines. |
| Integrated Service Contract Expansion | Tenet Healthcare and HCA Healthcare frameworks concentrate vendor relationships through multi-year shielding performance guarantees. |
| Modular Unit Manufacturing Scale-Up | Japanese facilities specify prefabricated panel systems for PET-CT renovations where floor loading limits prohibit monolithic construction. |
| Research Facility Specialization | Cyclotron and radiopharmaceutical production sites demand custom configurations with integrated containment and waste handling systems. |
| Geographic Distribution Network Buildout | Jebel Ali Free Zone in Dubai concentrates Middle Eastern component distribution for underpenetrated hospital markets. |
Research Methodology
Multi-period observation of hospital procurement database entries, GPO contract awards, and regulatory filing timelines anchored the trend analysis, supplemented by interviews with biomedical engineers, hospital purchasing committee members, radiation safety officers, and shielding fabricator technical directors. Secondary validation drew from FDA 510(k) clearances, EU MDR notified body certificates, ECHA REACH authorization documents, and IEC 60513 standard revision drafts. Bottom-up cabin installation tracking across German, Japanese, and United States hospital networks triangulated against top-down health system capital expenditure disclosures.
Input-output matrices mapped shielding material flows through primary lead smelters, specialty steel fabricators, and composite polymer processors to end-use installations across diagnostic imaging, radiation therapy, and research applications. Segmentation dimensions modeled encompassed product type permanence, material attenuation equivalence tier, end-user compliance maturity, and application-specific photon energy requirements. CAGRs were derived from regression analysis of historical installation volumes against regulatory enforcement intensity and healthcare infrastructure investment cycles.
Lead price volatility, ECHA authorization timeline acceleration, and IEC 60513 validation protocol finalization are the dominant revision risks that could compress or extend projected adoption curves for non-lead composite alternatives. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Conducted Energy Weapons Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Monitoring and Dosimeter Badges Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Law Enforcement and Military Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market