
 Active Protection System Market | 2026-2036
Active Protection System Market Size, Share, and Industry Trends Forecast 2026-2036
Active Protection System Market Analysis
Defense procurement consolidation among NATO member states is recalibrating supplier relationships toward fewer, larger platform integrators. Rheinmetall AG leverages its ground vehicle systems expertise to anchor European hard kill protection programs. Saab AB competes through sensor fusion architectures that integrate radar and infrared detection layers. Rafael Advanced Defense Systems Ltd. dominates Israel-centric trophy system deployments while extending partnerships with US armor modernization efforts.
An active protection system constitutes an integrated defensive suite that detects, tracks, and neutralizes incoming threats through kinetic interceptors, directed energy, or electronic disruption before impact, typically operating within reaction windows under 100 milliseconds against anti-tank guided missiles and rocket-propelled grenades. Hard kill systems currently occupy the largest value share due to ammunition costs and platform integration complexity, while electronic countermeasures represent the fastest-expanding technology segment as non-kinetic alternatives reduce collateral damage and logistics burden. Laser-based detection architectures are displacing legacy infrared-only configurations in next-generation designs.
The US Department of Defense mandates MIL-STD-810 environmental qualification and STANAG 4569 survivability standards for all ground platform protection suites, while NATO's NIAG studies establish interoperability frameworks for multinational force integration. The EU's European Defence Fund and Permanent Structured Cooperation mechanisms are redirecting member state procurement toward certified European suppliers. Stakeholders must monitor evolving STANAG revisions and US Army combat vehicle modernization milestone decisions to align R&D timelines with funded program requirements.
Market Dynamics
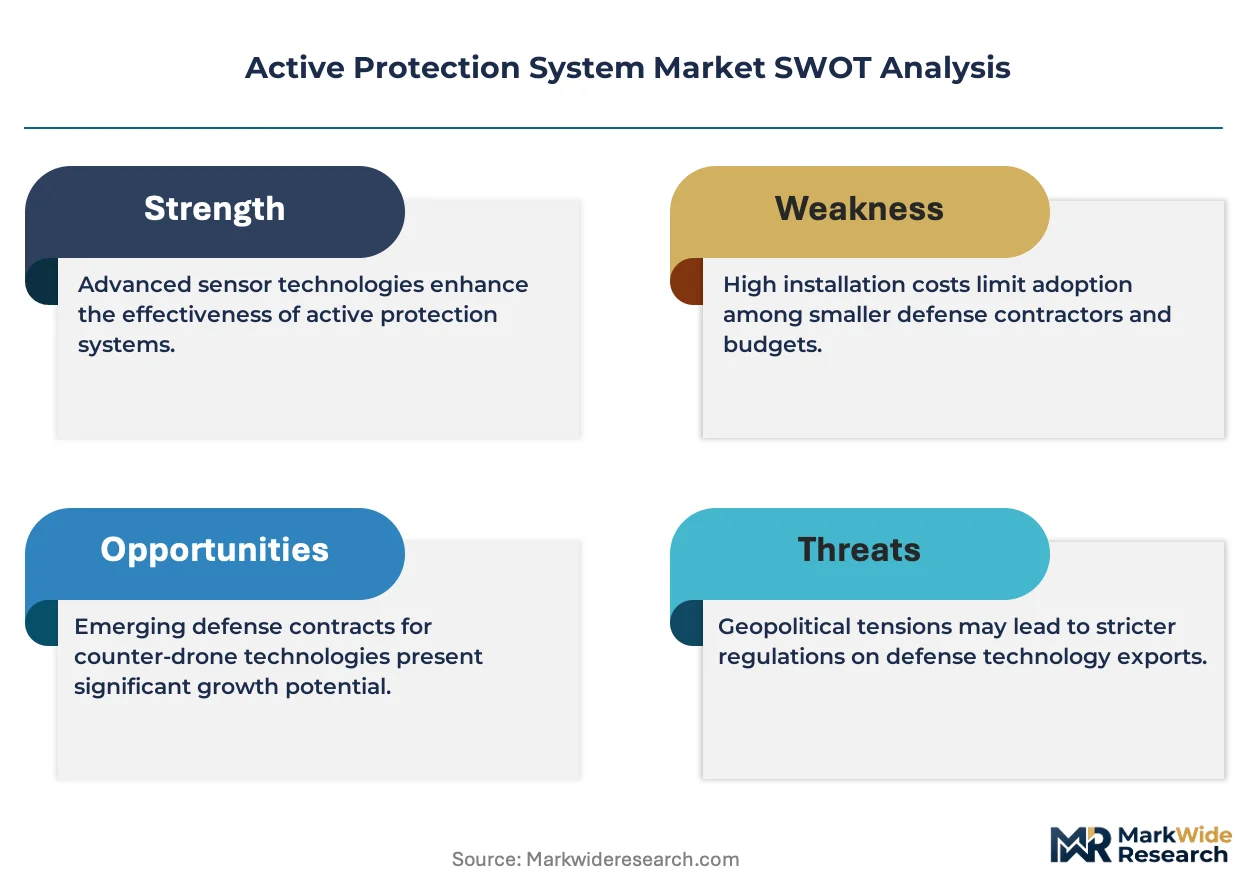
Layered survivability architectures are compressing procurement timelines as NATO members accelerate armor modernization cycles. Hard kill integration complexity and soft kill electronic warfare convergence are forcing platform integrators to consolidate subsystem suppliers.
Growth Catalysts
- MIL-STD-810 Qualification Mandates:The US Department of Defense's environmental testing requirements for ground vehicle protection suites are standardizing procurement specifications across allied defense programs.
- Directed Energy Maturation:Solid-state laser interceptors are reducing ammunition logistics burdens while expanding reaction windows against hypersonic threats.
- NATO Capability Targets:European member states are redirecting procurement budgets toward certified hard kill platforms under Permanent Structured Cooperation mechanisms.
Market Restraints
- Specialized Component Concentration:Gallium nitride semiconductor fabrication for radar front-ends concentrates in East Asian foundries, creating single-source vulnerabilities.
- STANAG Revision Lag:Interoperability testing protocols for multinational force integration trail field deployment schedules by 18-24 months.
- Kinetic Interceptor Cost Structure:Defeat mechanism ammunition represents 60-70% of lifetime system cost, constraining training utilization rates.
Strategic Opportunities
- Urban Operations Doctrine:Collateral damage mitigation requirements in dense terrain are accelerating non-kinetic electronic countermeasure adoption.
- Sensor Fusion Convergence:Integration of millimeter-wave radar with quantum cascade infrared detectors is enabling all-weather threat classification.
- Modular Open Systems Architecture:US Army combat vehicle modernization programs are mandating government reference designs that reduce vendor lock-in.
Industry Challenges
- Millisecond-Scale Algorithm Validation:Machine learning-based threat classification requires extensive live-fire datasets that conflict with ammunition cost constraints.
- Platform Electromagnetic Compatibility:Active protection radar emissions must coexist with tactical communications and electronic warfare suites without mutual interference.
- Skilled Systems Integration Talent:Cross-disciplinary expertise spanning RF engineering, real-time software, and armor mechanics remains scarce in defense labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Active Protection System Market |
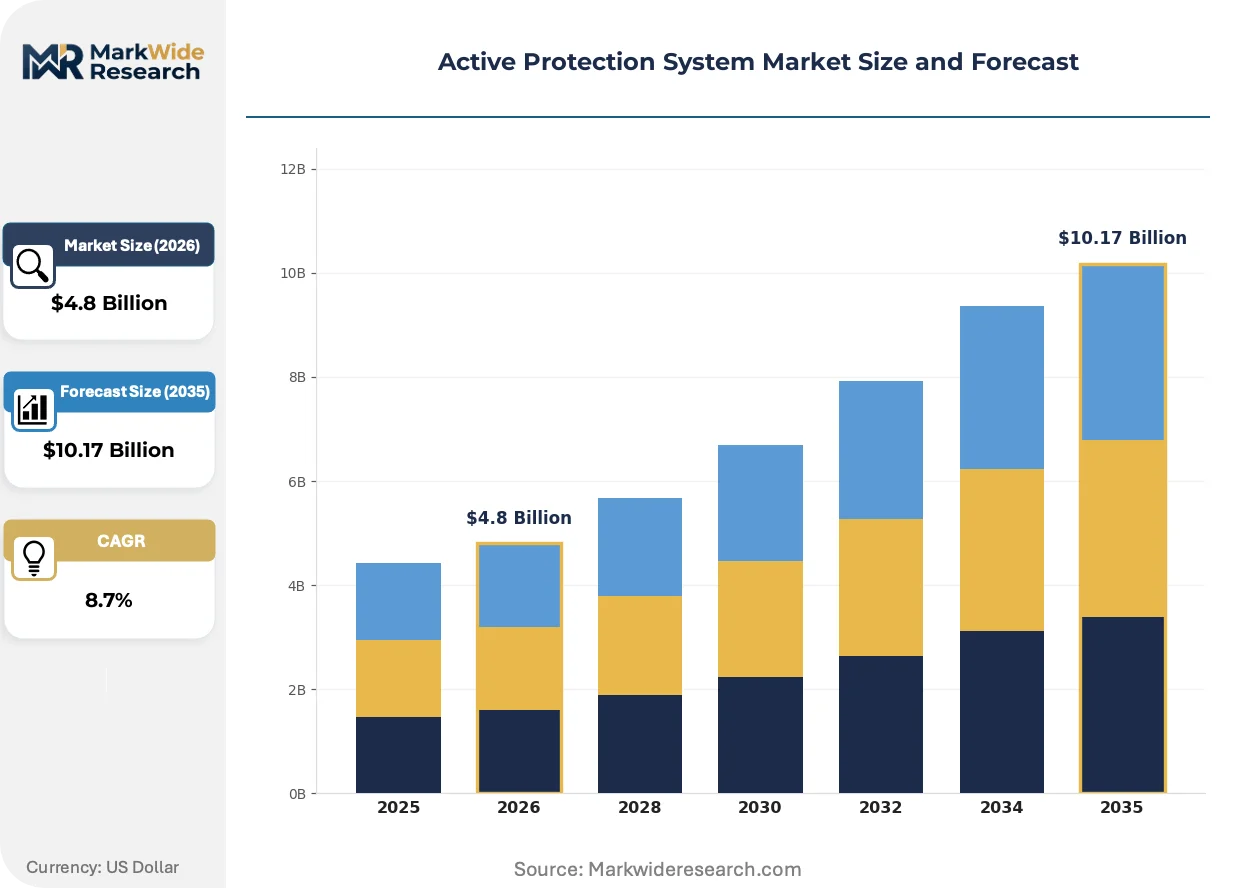
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Kill Systems, Hard Kill Systems, Electronic Countermeasures, Jammers Technology: Laser Systems, Radar Systems, Infrared Systems, Acoustic Systems End User: Military, Aerospace, Automotive, Homeland Security Application: Defense, Surveillance, Border Security, VIP Protection |
| Companies Covered | Rheinmetall AG, Saab AB, Raytheon Technologies Corporation, Rafael Advanced Defense Systems Ltd., ASELSAN A.Ş., Airbus Group, Artis, LLC, Elbit Systems Ltd., BAE Systems plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Active Protection System Market Emerging Trajectories
Detection and defeat architectures are converging toward unified sensor-to-shooter loops. Three developments are compressing reaction timelines while expanding threat coverage.
Dual-band electro-optical/infrared seekers are rewriting threat identification protocols. These sensors fuse short-wave and long-wave infrared signatures to defeat multispectral decoys. Israeli and US armor programs are fielding prototypes with sub-50 millisecond classification latency. The technology is compressing the gap between detection and interceptor launch authorization.
EU Green Deal defense procurement amendments are mandating lifecycle carbon accounting for platform protection suites. European Defence Fund allocations now prioritize systems with reduced rare earth content and recyclable thermal battery packs. Hard kill manufacturers are responding with tungsten-based penetrator alternatives to depleted uranium.
Performance-based logistics contracts are displacing traditional spares-and-maintenance arrangements. Platform integrators now guarantee availability rates rather than selling component replacements. This shift concentrates risk with original equipment manufacturers while aligning supplier incentives with operational readiness metrics. The model is most advanced in US Army Stryker and Bradley modernization programs.
Active Protection System Market Segmentation
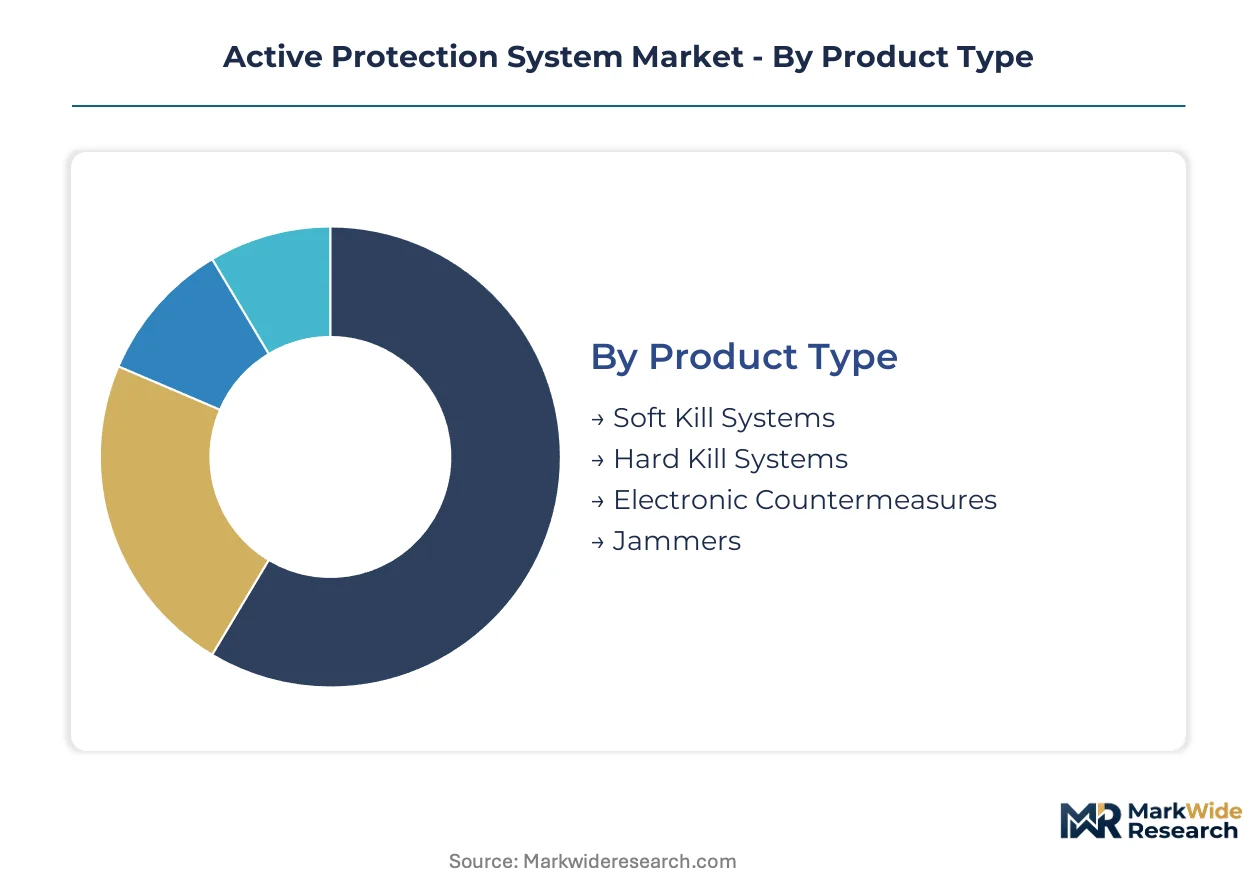
Active protection system procurement divides across threat defeat mechanisms, detection architectures, and operational domains. Platform integrators configure subsystem combinations based on mission profiles, environmental constraints, and rules of engagement governing kinetic versus non-kinetic responses.
Product Type:
Threat neutralization methods segment by physical interaction mode with incoming projectiles.
- Hard Kill Systems:Kinetic interceptors physically destroy threats through explosive fragmentation or impact projectiles. NATO armor modernization programs in Germany, Poland, and the United States concentrate procurement here due to effectiveness against tandem warheads. Ammunition logistics and collateral damage risks constrain training utilization.
- Soft Kill Systems:Electronic disruption and decoy deployment confuse threat guidance without physical destruction. Israeli and French urban operations doctrine accelerates adoption where civilian proximity limits explosive intercept. Reduced ammunition burden supports higher readiness rates.
- Electronic Countermeasures:Radio-frequency jamming severs command links in radio-controlled threats.
- Jammers:Directional interference systems target specific frequency bands used by anti-tank guided missiles.
Hard Kill Systems lead on scale; Soft Kill Systems lead on momentum.
Technology:
Detection layer specifications determine reaction timelines and all-weather performance.
- Radar Systems:Millimeter-wave and phased-array architectures provide range and velocity data regardless of lighting conditions. US Army combat vehicle modernization mandates radar as primary detection for next-generation platforms. Gallium nitride component supply concentration in East Asian foundries creates procurement vulnerabilities.
- Infrared Systems:Quantum cascade and staring-array detectors classify threats through thermal signatures. Swedish and Israeli programs prioritize infrared for passive operation that avoids electromagnetic emission detection. Atmospheric attenuation limits performance in precipitation.
- Laser Systems:Solid-state and fiber laser configurations enable directed energy defeat.
- Acoustic Systems:Gunfire and launch detection arrays provide cueing data in asymmetric threat environments.
Radar Systems anchor current procurement volumes; Infrared Systems gain share fastest in urban doctrine applications.
End User:
Operational environment dictates protection architecture requirements and certification standards.
- Military:Ground combat vehicles, naval vessels, and rotary-wing platforms requiring STANAG 4569 or MIL-STD-810 qualification. US Department of Defense and NATO member state procurement dominates segment value with multi-billion dollar platform modernization cycles.
- Homeland Security:Critical infrastructure and convoy protection for domestic security agencies. EU member state border agencies and US Customs and Border Protection expand procurement for vehicle-borne threat mitigation.
- Aerospace:Fixed-wing transport and special mission aircraft protection suites.
- Automotive:Civilian armored vehicle retrofits for executive protection.
Military end users command procurement scale; Homeland Security end users show steepest expansion trajectory.
Application:
Mission profiles determine threat spectrum coverage and engagement rule constraints.
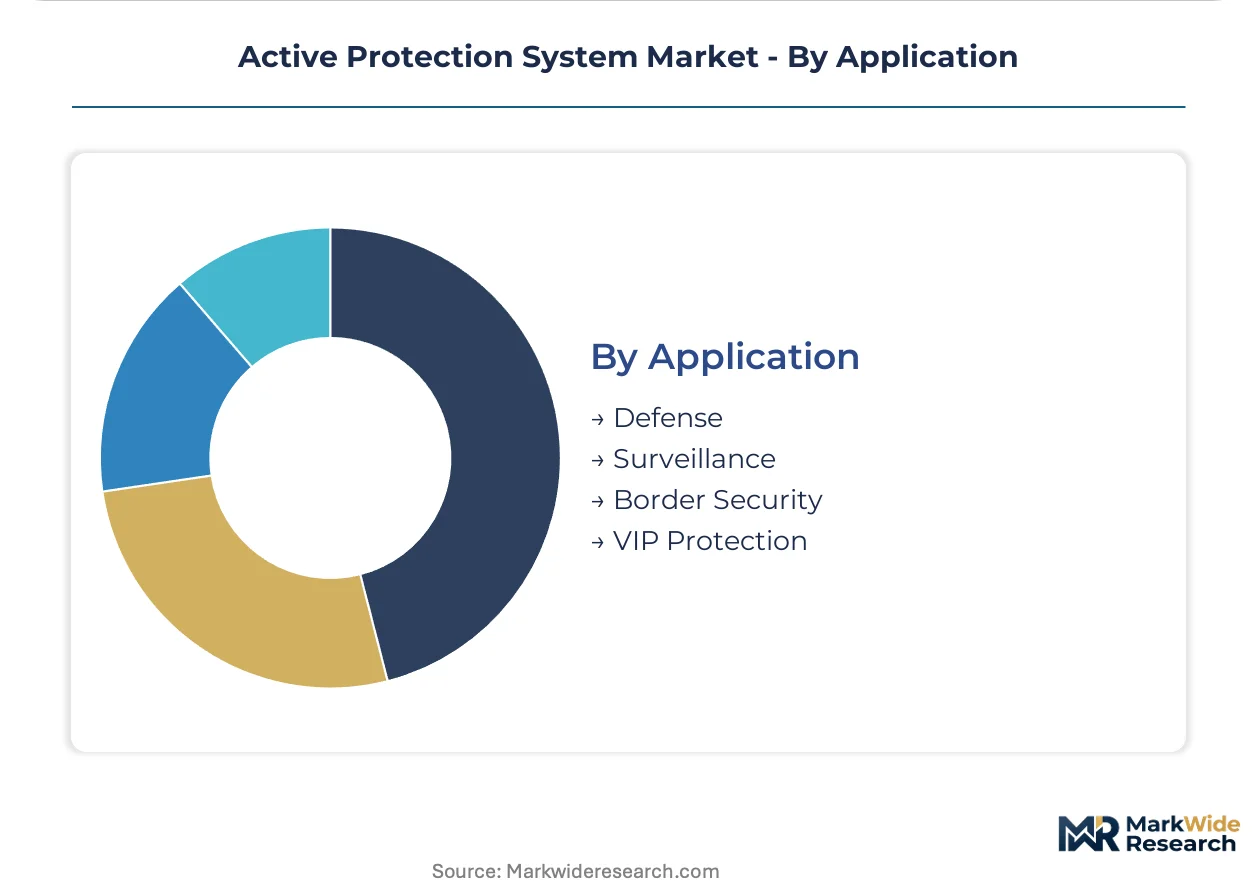
- Defense:Maneuver warfare and combined arms operations against peer adversaries. US Army and Marine Corps ground vehicle programs plus NATO readiness initiatives concentrate investment in layered hard-soft kill architectures.
- Border Security:Static and mobile checkpoint protection against improvised explosive devices and rocket attacks. Saudi Arabia and Turkey deploy systems along contested frontiers where asymmetric threats predominate.
- Surveillance:Sensor platform self-protection during reconnaissance missions.
- VIP Protection:Motorcade and fixed-site security for government officials.
Defense applications absorb majority procurement; Border Security applications climb fastest amid regional instability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense engineering talent clusters in Germany, Israel, and the United States anchor active protection system development. These concentrations concentrate millimeter-wave radar expertise, directed energy physics, and real-time software engineering. Procurement patterns follow military modernization cycles and alliance interoperability mandates.
United States
The US Army's combat vehicle modernization programs drive layered hard-soft kill procurement. MIL-STD-810 environmental qualification and STANAG 4569 survivability standards govern all ground platform protection suites. Engineering talent concentrates around Detroit Arsenal in Michigan and Aberdeen Proving Ground in Maryland, where platform integrators validate subsystem integration.
Germany
Rheinmetall AG anchors European hard kill protection programs through ground vehicle systems expertise. The EU's European Defence Fund and Permanent Structured Cooperation mechanisms redirect procurement toward certified European suppliers. Industrial activity clusters in Düsseldorf and Unterlüß, where subsystem suppliers consolidate around platform integrators.
Israel
Rafael Advanced Defense Systems Ltd. dominates trophy system deployments while extending partnerships with US armor modernization efforts. Israeli urban operations doctrine accelerates soft kill adoption where civilian proximity limits explosive intercept. Development concentrates in Haifa and the Tel Aviv metropolitan corridor.
Turkey
ASELSAN A.Ş. leverages domestic defense industrial base expansion to capture regional procurement. Border security applications climb fastest amid regional instability and contested frontier deployments. Manufacturing and R&D activity centers in Ankara and Istanbul, with growing integration into NATO interoperability frameworks.
Sweden
Saab AB competes through sensor fusion architectures integrating radar and infrared detection layers. Swedish programs prioritize passive infrared operation that avoids electromagnetic emission detection. Engineering expertise concentrates in Linköping and Stockholm, where quantum cascade detector development advances.
Active Protection System Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across the active protection system value chain. The market structure tilts toward consolidation as platform integrators compress supplier tiers to manage hard kill integration complexity. Three archetypes dominate: diversified defense conglomerates with ground vehicle heritage, sensor-focused electronics specialists, and state-affiliated national champions. M&A activity concentrates subsystem suppliers into fewer hands, while strategic partnerships bridge capability gaps in directed energy and machine learning-based threat classification.
Within the diversified conglomerate tier, Rheinmetall AG and Raytheon Technologies Corporation exemplify platform-anchored integrators with transatlantic reach. Saab AB occupies a position among sensor fusion specialists leveraging Nordic electronics heritage. These three represent contrasting geographic and technological positioning archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Rheinmetall AG |
| Saab AB |
| Raytheon Technologies Corporation |
| Rafael Advanced Defense Systems Ltd. |
| ASELSAN A.Ş. |
| Airbus Group |
| Artis, LLC |
| Elbit Systems Ltd. |
| BAE Systems plc |
| Others |
Supply Flow & Price Mechanics
NATO platform modernization programs concentrate procurement authority among defense ministries and prime integrators, compressing supplier margins through performance-based logistics contracts that guarantee availability rates rather than component sales. This buyer consolidation shifts pricing power toward vehicle OEMs while forcing subsystem vendors to absorb lifecycle cost risks.
Pricing Analysis
Hardware-software bundling versus unbundled spares procurement separates premium integrated suites from economy retrofit kits. Three-tier pricing structure across platform-integrated, vehicle-retrofit, and component-only levels reflects STANAG 4569 certification grade and ammunition logistics inclusion. Cost compression in training ammunition is intensifying because kinetic interceptor rounds represent sixty to seventy percent of lifetime system cost. Homeland security agencies show highest price sensitivity due to constrained procurement budgets, while military end users prioritize operational availability over unit economics.
Supply Chain Analysis
Direct-to-OEM channels handle defense ministry demand, while tiered distribution serves aftermarket retrofit and international procurement. Gallium nitride semiconductor fabrication concentrates in Taiwan, South Korea, and Japan, creating single-source dependencies for radar front-end components. Tungsten penetrator supply draws from Chinese and Russian mining operations, with alternative sourcing from Canadian and Australian deposits. Tariff exposure on rare earth processing creates structural vulnerability for European and US manufacturers. Distribution runs through prime defense contractors with captive integration capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Defense industrial base arbitrage between European subsidy mechanisms and US procurement scale offers cost advantages for suppliers establishing dual-qualification pathways. The EU's European Defence Fund co-financing reduces R&D burden relative to sole-source US development.
For Market Incumbents: Hedge gallium nitride supply exposure through qualification of alternative foundry sources in Japan and the United States. Consolidate sensor fusion software stacks to reduce algorithm validation costs that conflict with ammunition expenditure constraints. Lock in performance-based logistics contracts with NATO platform integrators before modular open systems architecture mandates erode proprietary integration advantages.
For New Entrants and Emerging Players: Digital-channel demonstration programs offer lowest-friction entry into homeland security procurement, where border agencies lack dedicated APS evaluation expertise. Target acoustic and passive infrared detection subsystems for asymmetric threat environments in Turkey and Saudi Arabia. Pursue STANAG 4569 pre-certification through European Defence Fund research partnerships to bypass prime contractor gatekeeping.
For Investors and Strategic Acquirers: Platform integrators with ground vehicle heritage are the most active acquirers in this space, seeking sensor fusion and directed energy capabilities. Five-to-ten year viability hinges on successful transition from kinetic to non-kinetic defeat mechanisms. Monitor US Army combat vehicle modernization milestone decisions as the critical inflection signal for procurement volume direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Directed Energy Maturation | Solid-state laser interceptors reduce ammunition logistics burden for NATO armor programs. |
| Sensor Fusion Convergence | Millimeter-wave radar integration with quantum cascade infrared enables all-weather threat classification. |
| Modular Open Systems Architecture | US Army reference designs reduce vendor lock-in and compress subsystem supplier margins. |
| Performance-Based Logistics Contracts | Availability guarantees shift lifecycle risk to original equipment manufacturers. |
| Dual-Qualification Pathway Development | Simultaneous MIL-STD-810 and STANAG certification expands addressable procurement pools. |
Methodological Framework
Bottom-up platform modernization modeling reconciled against top-down defense procurement tracking forms the analytical core of this study. Primary interviews with program executive officers at defense ministries, platform integration engineers at ground vehicle OEMs, subsystem procurement leads, and military requirements specialists informed demand-side assumptions. Secondary validation drew from NATO capability target documents, US Department of Defense budget justification materials, EU Permanent Structured Cooperation implementation reports, and national defense industrial strategy filings. Triangulation between end-user demand signals and supplier capacity announcements anchors volume estimates.
Historical defense procurement trendlines establish baseline spending patterns across hard kill, soft kill, and electronic countermeasure categories. Segmentation modeling spans threat defeat mechanism, detection architecture technology, operational domain application, and end-user type, with geographic procurement cluster as an additional dimension. CAGRs derive from weighted alignment of funded program timelines with technology maturation curves. Hypersonic threat response requirements and urban operations doctrine shifts serve as key forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for directed energy interceptors would alter the outlook if solid-state laser reliability exceeds projected thresholds. Forecasts reflect documented assumptions regarding NATO member state defense spending commitments and US Army modernization schedule adherence. Periodic stress-testing of base assumptions is recommended given STANAG revision lag and geopolitical procurement volatility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
China Premium Motorcycle Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Biometric Gun Safe Market
Safety Equipment and Personal Protective Equipment (PPE)
Armoured Thermocouple Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Safety Lancet Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Pest Control Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
US Safety Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market