
 Law Enforcement and Military Clothing Market | 2026-2036
Law Enforcement and Military Clothing Market Size, Share, and Industry Trends Forecast 2026-2036
Law Enforcement and Military Clothing Market Analytics
Market Context
NIJ Standard-0101.07 is expanding the cost-of-entry calculus for ballistic garment suppliers by mandating enhanced backface deformation testing and stricter multi-hit protocols. Point Blank Enterprises leverages in-house armor integration to sustain its position in domestic law enforcement channels. W. L. Gore & Associates differentiates through membrane technology leadership in weather-resistant duty shells. Safariland competes across the full tactical ensemble, from holster systems to outerwear, anchoring its revenue in federal agency contracts.
Technical Definition and Segments
Law enforcement and military clothing encompasses engineered textile systems designed for force protection, environmental survivability, and operational identity, typically integrating aramid fibers such as Kevlar for ballistic panels and Gore-Tex laminates for waterproof-breathable membranes in outer shells. The primary purpose is to reduce physical threat exposure while maintaining mobility and thermoregulation across variable climates and mission profiles. Tactical gear and flame-retardant functionality represent the fastest-expanding margin pools, driven by SWAT team modernization and wildland firefighting crossover demand, while cotton-blend uniforms remain a mature volume category with compressed pricing. Kevlar-reinforced accessories occupy a specialized niche where premium positioning survives due to limited qualified suppliers.
Regulatory Frame
FDA oversight applies to certain antimicrobial textile treatments used in extended-wear duty garments, while OSHA respiratory protection standards indirectly shape hood and face-covering specifications for riot-control applications. The NIJ maintains the dominant certification regime for ballistic-resistant clothing in the United States, with its compliance mark functioning as a de facto gatekeeper for municipal procurement eligibility. Stakeholders must monitor pending revisions to flame-resistance testing protocols and the potential harmonization of military and law enforcement specifications to capture consolidated volume opportunities.
Market Dynamics
The NIJ Standard-0101.07 revision is compressing supplier margins by mandating multi-hit ballistic testing and backface deformation protocols that disqualify legacy panel architectures. Domestic armor integrators must rebuild testing infrastructure or exit municipal procurement channels entirely.
Growth Catalysts
- Wildland Firefighting Crossover:Municipal fire departments in California and Australia are adopting flame-resistant duty shells originally engineered for tactical law enforcement, expanding addressable volume beyond traditional police budgets.
- NIJ Certification Expansion:The updated ballistic resistance standard is forcing municipal agencies to accelerate uniform replacement cycles, creating pull-through demand for integrated garment systems.
- Aramid Fiber Innovation:Next-generation Kevlar weaves with reduced backface signature are enabling thinner, lighter ballistic panels that sustain mobility ratings across extended wear periods.
Market Restraints
- DuPont Supply Concentration:Kevlar fiber production concentrates in Richmond, Virginia and Northern Ireland facilities, exposing garment assemblers to single-source risk during geopolitical disruptions or force majeure events.
- Ballistic Testing Cost Burden:NIJ-certified laboratory testing for multi-hit protocols runs between fifteen and twenty-five thousand dollars per design iteration, erecting capital barriers for mid-tier domestic suppliers.
- Technical Limitation in Breathability:Current Gore-Tex laminate architectures trade waterproof integrity against vapor transmission rates, creating thermoregulation failures in humid subtropical deployment zones.
Strategic Opportunities
- Canadian Municipal Expansion:Royal Canadian Mounted Police modernization programs are consolidating provincial procurement under federal standards, opening volume contracts for qualified US-based armor integrators.
- Antimicrobial Textile Mandates:FDA-cleared silver-ion treatments for extended-wear garments are creating premium positioning opportunities in correctional and detention facility channels.
- Smart Textile Convergence:Embedded biometric sensors for heart rate and core temperature monitoring are converging with flame-resistant base layers, enabling real-time physiological tracking for tactical command units.
Industry Challenges
- Ballistic Materials Engineering Talent Scarcity:The specialized knowledge base for aramid weave architecture and trauma-distribution modeling concentrates among retiring cohorts at DuPont and Teijin, constraining supplier R&D velocity.
- NIJ Certification Timeline Compression:Backlogs at certified testing laboratories now extend eight to fourteen months, delaying product launches and freezing working capital in pre-certified inventory.
Report Scope
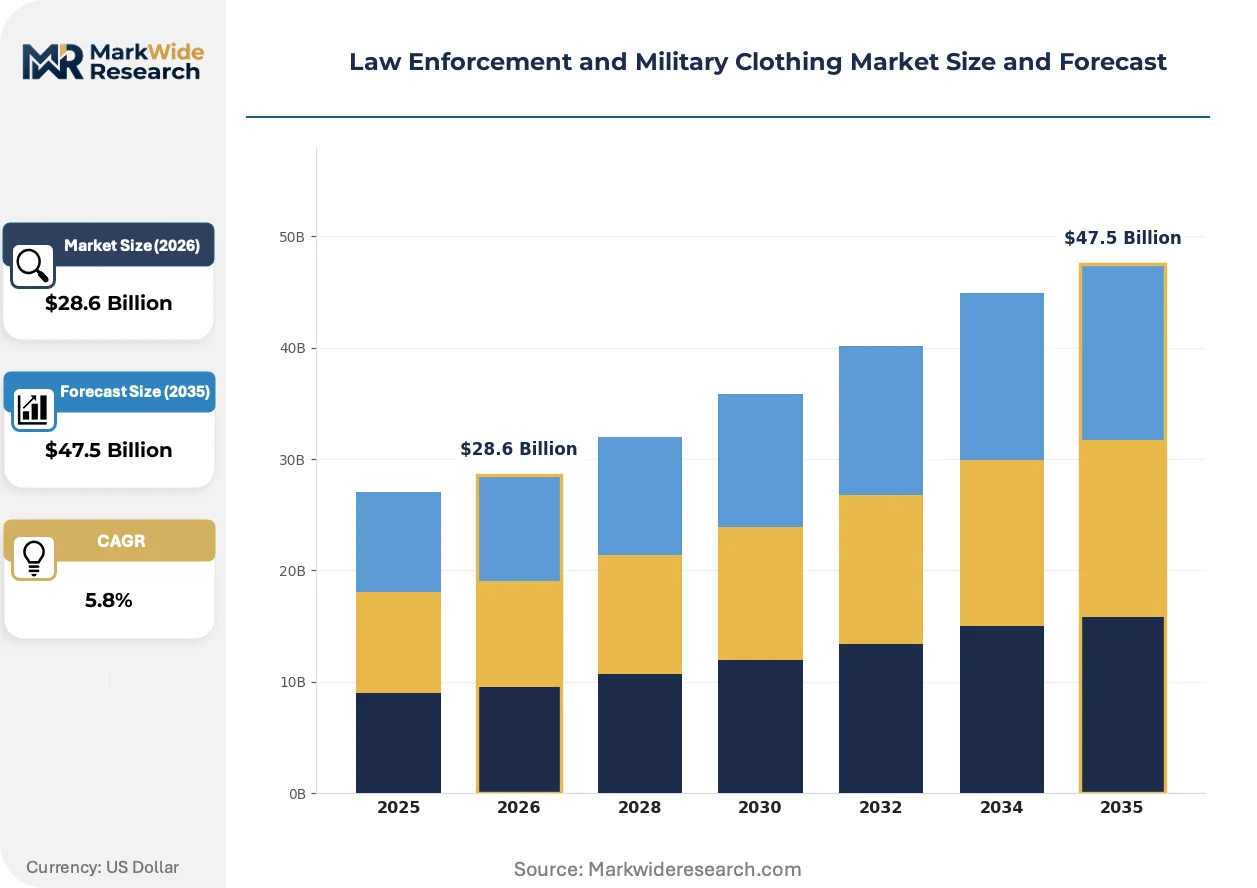
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Law Enforcement and Military Clothing Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Uniforms, Tactical Gear, Footwear, Accessories Material: Cotton, Polyester, Nylon, Kevlar Functionality: Weather Resistance, Flame Retardant, Camouflage, High Visibility End User: Police Forces, Military Personnel, Security Agencies, Swat Teams |
| Companies Covered | Point Blank Enterprises, Inc., Safariland, LLC, W. L. Gore & Associates, Inc., Propper, Elbeco (LION Group, Inc.), Fechheimer, 5.11 Tactical, Massif, Galls, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Law Enforcement and Military Clothing Market Evolving Landscape
Active materials science is displacing passive protection architectures across tactical garment systems. Three developmental trajectories dominate current engineering investment: fiber-level ballistic enhancement, regulatory harmonization between military and law enforcement specifications, and procurement consolidation under federal agency frameworks.
Shear-thickening fluid (STF) treatments for Kevlar fabrics are converging with traditional woven ballistic panels to produce flexible armor systems that harden on impact while maintaining drape and ventilation in static posture. SWAT units in Texas and Florida are piloting STF-enhanced vests for high-risk warrant service, with early adoption compressing the performance gap between soft armor and rigid plate carriers. The technology is converging with moisture-wicking base layer architectures to create unified garment systems that eliminate the layering friction of legacy configurations.
REACH regulation amendments in the European Union are restricting per- and polyfluoroalkyl substance (PFAS) content in waterproof-breathable membranes, forcing reformulation of Gore-Tex laminates and comparable fluoropolymer-based duty shells. Industrial consequence includes accelerated R&D timelines for silicone-based and hydrocarbon alternative chemistries that must replicate hydrostatic head performance without fluorinated compounds. German federal police procurement channels are most affected, with Bundespolizei technical specifications now requiring PFAS-free certification for new outerwear contracts.
Multi-agency cooperative purchasing agreements are consolidating municipal law enforcement uniform procurement under federal contract vehicles such as the General Services Administration schedule. The shift displaces fragmented city-by-city bidding processes with centralized specification-setting that favors suppliers with existing federal certifications. California and New York state police agencies are most visible in this transition, with both jurisdictions migrating county-level purchasing authority to state-administered master agreements that reduce administrative overhead but compress vendor diversity.
Law Enforcement and Military Clothing Market Segmentation
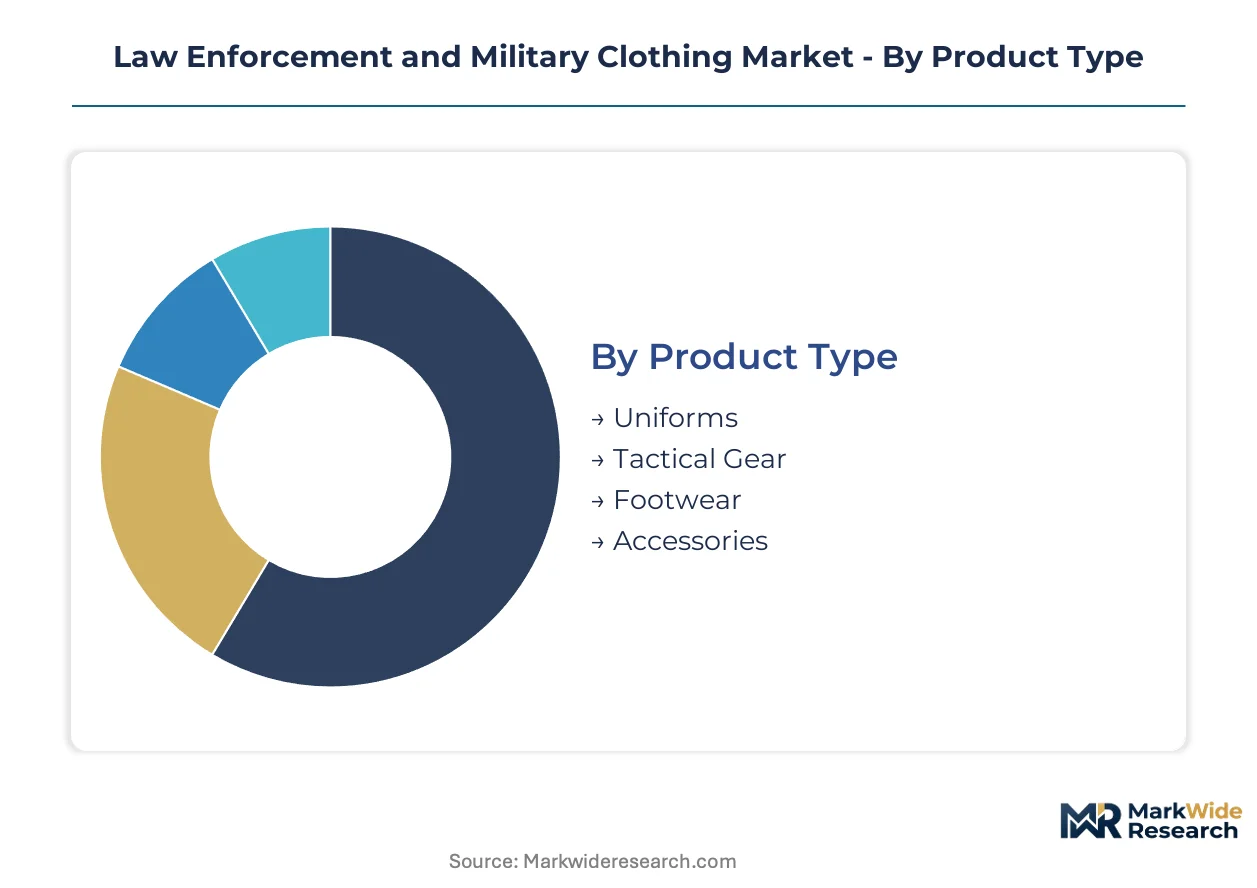
Segmentation in law enforcement and military clothing reveals distinct capital requirements, certification barriers, and procurement pathways that determine supplier viability. Material choices and functional specifications drive compliance costs, while end-user categories dictate volume concentration and replacement cycles.
Product Type:
Capital intensity peaks in ballistic-integrated garment systems requiring NIJ-certified laboratory infrastructure and trauma-testing protocols. Tiered investment thresholds separate municipal uniform suppliers from federal tactical contractors.
- Tactical Gear:Shear-thickening fluid treatments and multi-hit ballistic panels demand specialized weave engineering and backface deformation testing. Procurement concentrates in federal agency contracts and specialized police tactical units across Texas and Florida, where SWAT modernization programs accelerate replacement cycles.
- Uniforms:Cotton-blend and synthetic duty wear represents high-volume, low-margin production with compressed pricing and established supplier relationships. Municipal police departments sustain replacement demand through standardized color and insignia specifications.
- Footwear:Combat and patrol boots require molded sole architectures and abrasion-resistant leather or synthetic uppers.
- Accessories:Kevlar-reinforced gloves, belts, and duty pouches occupy specialized niches with limited qualified suppliers.
Most installed capacity flows through Uniforms. Expansion is steepest in Tactical Gear.
Material:
Raw material selection determines ballistic performance, environmental survivability, and regulatory compliance exposure across garment architectures.
- Kevlar:Aramid fiber weaving for ballistic panels and trauma distribution requires DuPont-certified processing equipment and specialized lamination protocols. Production concentrates in Richmond, Virginia and Northern Ireland facilities, exposing garment assemblers to single-source concentration risk.
- Nylon:High-tenacity yarns for load-bearing webbing and abrasion-resistant shell layers support tactical gear durability requirements. Demand clusters in federal defense outlays and municipal police modernization programs.
- Polyester:Moisture-wicking base layers and durable outer shells balance cost and performance for standard duty wear.
- Cotton:Natural fiber blends for ceremonial and low-intensity patrol applications remain price-sensitive volume categories.
Supply security concerns concentrate procurement attention on Kevlar. Reformulation investment is accelerating fastest in Nylon alternatives.
Functionality:
Functional specifications segment the market by threat environment, climate exposure, and visibility requirements that shape textile engineering priorities.
- Flame Retardant:Aramid and modacrylic fiber blends for wildland firefighting crossover and tactical flash-fire protection require specialized finishing and certification. California and Australian municipal fire departments are adopting duty shells originally engineered for law enforcement, expanding addressable volume.
- Weather Resistance:Gore-Tex and comparable waterproof-breathable membranes face REACH-mandated PFAS restrictions in European procurement, forcing silicone-based alternative development. German Bundespolizei specifications now require fluoropolymer-free certification.
- Camouflage:Patterned textiles for military concealment and specialized law enforcement operations.
- High Visibility:Retroreflective and fluorescent treatments for traffic control and emergency response visibility.
Regulatory pressure is compressing Weather Resistance supplier margins. Flame Retardant applications are climbing the fastest.
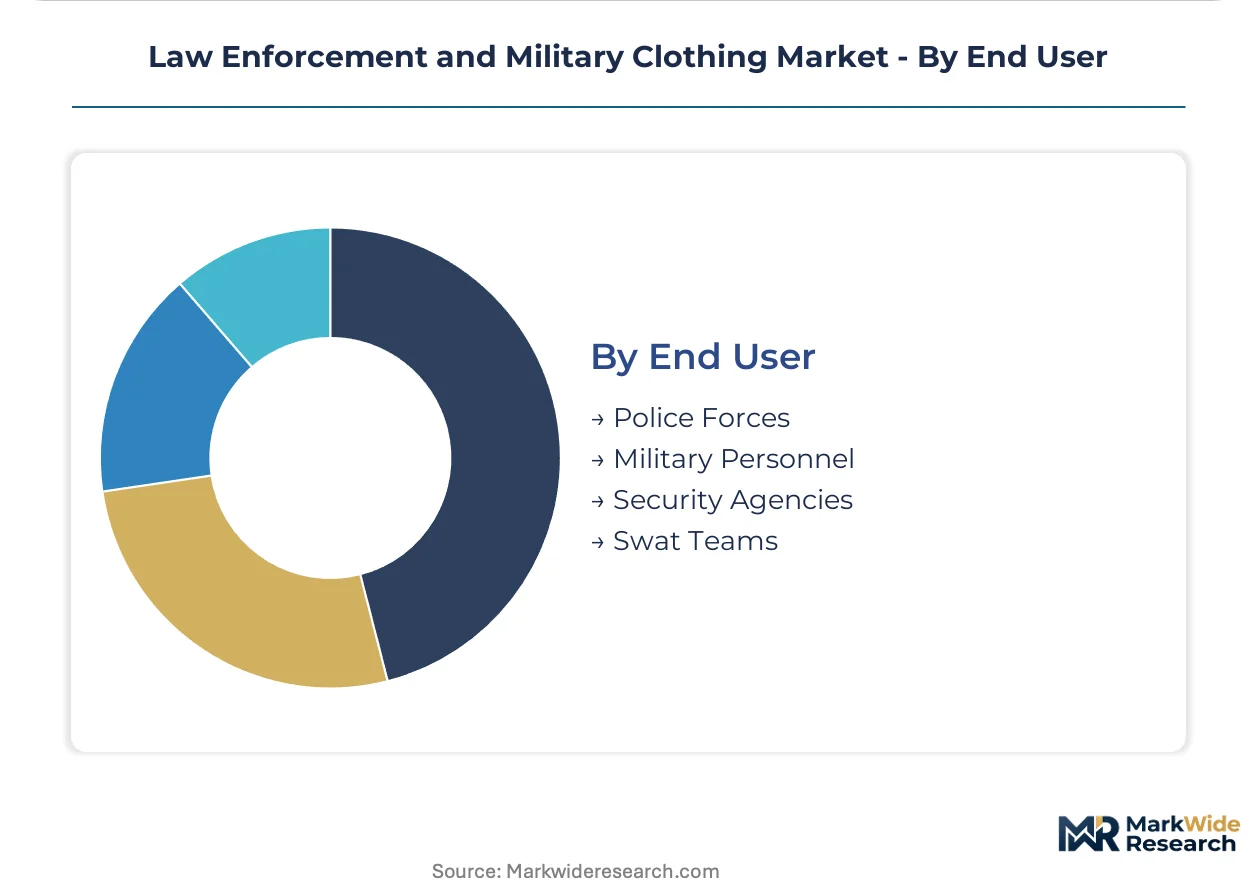
End User:
Customer categories determine specification stringency, contract scale, and procurement centralization trends that reshape competitive access.
- Police Forces:Municipal and state agencies drive standardized uniform volume with consolidated purchasing under General Services Administration schedules. California and New York state agencies are migrating county-level authority to state-administered master agreements.
- Military Personnel:Federal defense outlays sustain integrated ensemble procurement with harmonized specification development across branches.
- Swat Teams:Specialized tactical units command premium positioning for threat-specific garment systems.
- Security Agencies:Private and government contract security operates with variable specification requirements and price-sensitive procurement.
Procurement consolidation is concentrating volume through Police Forces. Technology integration is advancing most rapidly in Swat Teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered modern tactical garment engineering during the 1990s NIJ standardization era, establishing Richmond, Virginia as the global center for aramid fiber weaving and ballistic panel lamination.
United States
Federal defense outlays and municipal police modernization programs sustain uniform replacement cycles across Texas and Florida SWAT units. The NIJ Standard-0101.07 revision mandates enhanced backface deformation testing that disqualifies legacy suppliers. Richmond, Virginia anchors Kevlar fiber production with DuPont-certified processing facilities serving domestic armor integrators.
Germany
The Bundespolizei drives demand for PFAS-free waterproof-breathable membranes under amended REACH restrictions. ECHA regulatory pressure forces reformulation of fluoropolymer-based duty shells for federal police procurement. Bavaria hosts specialized textile finishing operations adapting silicone-based alternatives to replicate hydrostatic head performance.
Canada
Royal Canadian Mounted Police modernization consolidates provincial procurement under federal standards, opening volume contracts for qualified armor integrators. Health Canada antimicrobial textile oversight shapes extended-wear garment specifications for correctional facilities. Ontario manufacturing clusters supply aramid-reinforced accessories to municipal agencies migrating from fragmented city-by-city bidding.
Australia
Municipal fire departments in New South Wales and Victoria adopt flame-resistant duty shells originally engineered for tactical law enforcement, expanding wildland firefighting crossover volume. The TGA regulates certain antimicrobial treatments in extended-wear detention garments. Melbourne textile engineering firms pilot aramid-modacrylic blends for dual-use thermal protection systems.
United Kingdom
Metropolitan Police Service procurement shifts toward integrated ensemble specifications harmonizing with Ministry of Defence tactical standards. UKCA marking requirements post-Brexit create parallel certification pathways for ballistic garment suppliers. Manchester industrial zones concentrate cut-and-sew operations serving consolidated Home Office contract vehicles.
Law Enforcement and Military Clothing Market Competitive Landscape
The competitive structure tilts toward vertically integrated armor specialists controlling in-house ballistic panel lamination. Domestic suppliers face capital barriers from NIJ-certified laboratory testing requirements, while mid-tier municipal uniform vendors confront margin compression from consolidated federal procurement. Two strategic archetypes dominate: fiber-integrated specialists with captive aramid processing and membrane-technology leaders in weather-resistant shells. Competitive moves center on certification infrastructure rebuilding and multi-agency cooperative purchasing agreement capture.
Among US-based armor integrators, Point Blank Enterprises and Safariland exemplify the vertically integrated archetype, with the former representing in-house ballistic panel production and the latter anchoring full-tactical-ensemble positioning across federal agency channels. W. L. Gore & Associates occupies the membrane-technology tier, its name signaling Delaware-origin fluoropolymer expertise now navigating REACH-mandated PFAS reformulation. These three entities illustrate how certification depth and material science specialization determine procurement access under tightening NIJ protocols.
| Leading Market Players |
|---|
| Point Blank Enterprises, Inc. |
| Safariland, LLC |
| W. L. Gore & Associates, Inc. |
| Propper |
| Elbeco (LION Group, Inc.) |
| Fechheimer |
| 5.11 Tactical |
| Massif |
| Galls, LLC |
| Others |
Value Network & Pricing Analysis
Federal agency procurement consolidation under General Services Administration schedules compresses municipal vendor diversity while concentrating pricing power among NIJ-certified armor integrators. This buyer-archetype concentration enforces contract-based long-term offtake structures that tether unit economics to certification maintenance costs and multi-hit ballistic testing investments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates federal tactical contractors from municipal uniform suppliers and commoditized cotton-blend vendors. Price differentiation centers on NIJ certification tier and volume scale, with SWAT modernization programs in Texas and Florida commanding premium positioning for multi-hit ballistic panels. Cost compression in the municipal uniform tier intensifies because consolidated state master agreements in California and New York reduce administrative overhead while squeezing mid-tier margins. Correctional facility procurement demonstrates the highest price sensitivity, whereas federal tactical units exhibit minimal elasticity for threat-specific garment systems.
Supply Chain Analysis
Regional distribution centers in Richmond, Virginia and Northern Ireland anchor hub-and-spoke patterns for Kevlar fiber deployment to domestic armor assemblers. Geographic supply concentration in the United States, Northern Ireland, and Germany shapes raw material access, with aramid weaving, Gore-Tex membrane lamination, and silicone-based alternative development as critical inputs. Single-source vulnerability in DuPont-certified Richmond facilities exposes garment assemblers to force majeure disruptions. Distribution runs through federal contract vehicles and state-administered master agreements that displace fragmented city-by-city bidding.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as wildland firefighting crossover demand and NIJ Standard-0101.07 certification requirements shift procurement toward premium flame-resistant and ballistic-integrated specifications.
For Market Incumbents: To counter margin compression from consolidated federal procurement, armor integrators should rebuild NIJ-certified laboratory infrastructure to sustain municipal eligibility while capturing Royal Canadian Mounted Police modernization volume through Health Canada-aligned antimicrobial textile positioning. For New Entrants and Emerging Players: Launch via direct engagement with Australian municipal fire departments adopting law enforcement-engineered flame-resistant duty shells, exploiting the wildland firefighting crossover segment where specification transfer creates penetrable white space without legacy ballistic certification burdens. For Investors and Strategic Acquirers: Defense contractors with federal agency relationships are the most active acquirer in this space, targeting vertically integrated armor specialists with captive Kevlar processing and existing GSA schedule presence as the most viable long-term holdings; watch for REACH-mandated PFAS reformulation completion in German Bundespolizei procurement as the inflection signal for membrane-technology valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| NIJ Laboratory Infrastructure Rebuild | Multi-hit ballistic testing capability secures municipal procurement eligibility under Standard-0101.07 protocols. |
| PFAS-Free Membrane Reformulation | Silicone-based alternatives unlock German federal police contracts under amended REACH restrictions. |
| Wildland Firefighting Crossover Expansion | California and Australian municipal fire departments adopt tactical law enforcement flame-resistant architectures. |
| Smart Textile Biometric Integration | Embedded heart rate sensors converge with flame-resistant base layers for real-time tactical command tracking. |
| Canadian Federal Procurement Capture | Royal Canadian Mounted Police consolidation opens volume contracts for qualified US armor integrators. |
Research Methodology
Multiple input streams — primary interviews with ballistic materials engineers, municipal procurement officers, and federal contract administrators, alongside secondary validation through NIJ certification records, GSA schedule disclosures, and REACH regulatory filings — were reconciled through bottom-up and top-down triangulation across the analysis window.
Historical shipment patterns were cross-referenced against panel input from aramid fiber suppliers and membrane technology developers to anchor projections. Segmentation dimensions modeled include product type, material architecture, functional specification, and end-user category, with CAGRs derived from replacement cycle analysis and procurement consolidation trajectories. Shear-thickening fluid adoption curves and PFAS reformulation timelines served as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under geopolitical disruptions to Richmond Kevlar production or extended NIJ laboratory backlogs. Forecasts reflect documented assumptions regarding federal defense outlay continuity and municipal modernization program funding. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Static Safety Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Blast Monitoring Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Protection Glasses Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Machine Safeguarding Solution Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Connection Devices Market
Safety Equipment and Personal Protective Equipment (PPE)
Global above-The-Neck PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Seat Belt Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Tactical Vest Market