
 Safety Eyewear Market | 2026-2036
Safety Eyewear Market Size, Share, and Industry Trends Forecast 2026-2036
Safety Eyewear Market Intelligence
The EN 166 standard for personal eye protection in Europe is repositioning market access requirements for all manufacturers. This directive sets stringent performance criteria for optical quality and mechanical strength, raising the barrier to entry. Honeywell International Inc. leverages its extensive materials science research to develop compliant, high-performance lens technologies. In parallel, 3M Company sustains its market leadership through a vast distribution network and strong brand equity within industrial safety procurement channels across multiple countries.
Safety eyewear comprises devices engineered to shield the wearer's eyes from workplace hazards. Products are typically manufactured from high-impact polycarbonate, which provides superior resistance to projectiles and blunt force as defined by impact rating tests. The primary function is to prevent eye injuries from flying debris, chemical splashes, dust, and harmful radiation in industrial and laboratory settings. Protective glasses represent the largest product category by volume, driven by broad adoption in construction. Specialized goggles and face shields command higher margins, with demand concentrated in chemical processing and mining applications.
Compliance with standards from the US Occupational Safety and Health Administration (OSHA) and adherence to Europe's CE marking protocols are non-negotiable for market participants. These regulatory frameworks mandate the use of certified eyewear in specific occupations and dictate minimum performance levels for impact resistance and splash protection. Future competitive advantage will depend on the ability to integrate sustainable materials and smart features, such as heads-up displays, without compromising on certified protection or user comfort.
Market Dynamics
The global market's trajectory is fundamentally shaped by the increasing stringency of occupational safety regulations. Mandates from bodies like OSHA in the United States and the frameworks governing CE marking in Europe create a non-negotiable floor for product performance and market access.
Growth Catalysts
- Stringent Regulations:Heightened enforcement of workplace safety laws by regulators, particularly in the manufacturing and construction sectors across North America and Europe, mandates the use of certified personal protective equipment.
- Advanced Materials:The development of high-performance polycarbonate composites and advanced lens coatings enhances durability, scratch resistance, and anti-fog capabilities, improving user acceptance and replacement cycles.
- Industrialization in Emerging Economies:Rapid industrial expansion in countries like India and Brazil, coupled with a growing awareness of occupational hazards, is creating new demand centers for protective eyewear.
Market Restraints
- Counterfeit Products:The prevalence of low-cost, non-compliant, and counterfeit safety eyewear, particularly in markets with lax enforcement, erodes market value and poses significant risks to end-users.
- User Compliance:Resistance to wearing safety eyewear due to discomfort, poor fit, or fogging remains a persistent barrier, limiting the effective protection provided and the full market potential.
- Cost Sensitivity:In price-sensitive industries or among small-to-medium enterprises, the higher upfront cost of certified, high-performance eyewear can lead to under-investment in adequate protection.
Strategic Opportunities
- Smart Eyewear Integration:Incorporating heads-up displays, augmented reality overlays, and sensor technology into protective frames creates high-value products for specialized applications in logistics, maintenance, and healthcare.
- Sustainable Materials:Developing safety eyewear from recycled or bio-based polymers offers a path to differentiation for manufacturers targeting corporations with strong environmental, social, and governance mandates.
- Prescription Safety Eyewear:Expanding capabilities to provide customized prescription (Rx) safety glasses at scale addresses a significant and underserved portion of the workforce, particularly in aging industrial economies.
Industry Challenges
- Navigating Global Standards:Manufacturers face significant cost and complexity in certifying products across multiple international standards, such as ANSI Z87.1 in the US, EN 166 in Europe, and CSA Z94.3 in Canada.
- Customization at Scale:The logistical complexity of managing supply chains for prescription safety eyewear, which requires individual fitting and lens fabrication, presents a major operational hurdle.
- Balancing Comfort and Protection:The engineering challenge of designing eyewear that is lightweight, comfortable for all-day wear, and aesthetically appealing without compromising on certified impact and splash resistance is continuous.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safety Eyewear Market |
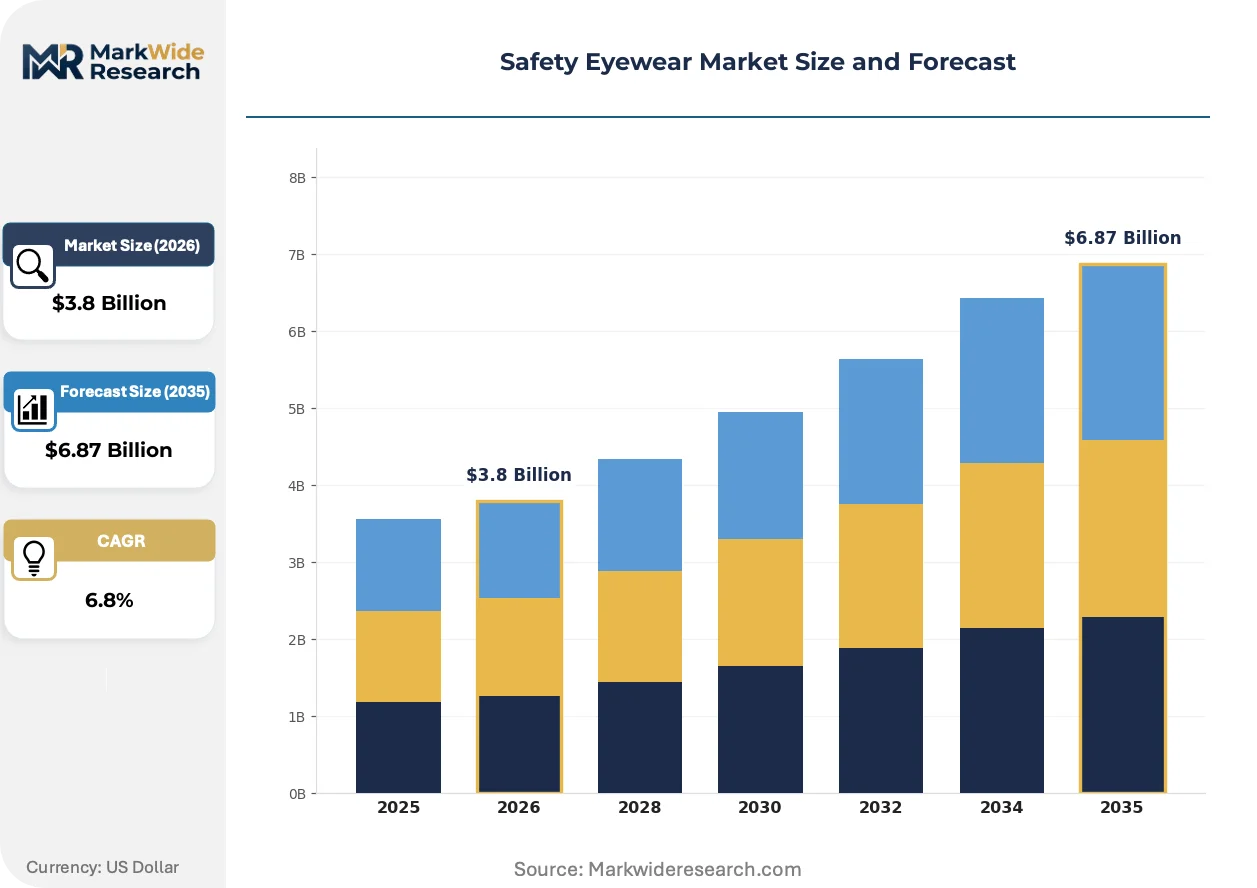
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protective Glasses, Goggles, Face Shields, Welding Helmets, Visors Technology: Anti-Fog, UV Protection, Scratch Resistance, Polarized Lenses, Photochromic Application: Construction, Manufacturing, Laboratory, Mining, Chemical Processing End User: Technicians, Safety Officers, Engineers, Maintenance Staff, Quality Inspectors |
| Companies Covered | 3M Company, Honeywell International Inc., Uvex Group, Bolle Safety, Pyramex Safety Products LLC, Radians Inc., Gateway Safety Inc., MSA Safety Inc., MCR Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safety Eyewear Market Strategic Shifts & Innovations
The market is evolving beyond basic impact resistance toward a model where enhanced functionality, user-centric design, and material science converge. This shift prioritizes not just compliance, but also wearer comfort and productivity, redefining performance expectations for modern safety eyewear.
Advanced lens coatings that combine multiple properties like anti-fog, anti-scratch, and photochromic capabilities are becoming standard. These technologies are seeing rapid adoption in dynamic work environments like construction and utilities where workers move between indoor and outdoor settings. This focus on adaptive performance is overtaking the previous market standard of static, single-function lens treatments, compelling a re-evaluation of product value.
Europe's EN 166 standard, along with its specific sub-designations, continues to set a high bar for mechanical strength and optical quality. The regulation forces continuous investment in materials research and quality control, effectively raising the barrier to entry for non-compliant goods. The specialized goggles segment, used in chemical and laboratory environments, is most directly impacted, requiring manufacturers to validate resistance against specific liquid splash and fine dust particle threats.
A notable behavioral shift is the increasing influence of worker preference in equipment selection, moving away from a purely top-down procurement model. This consumerization is disrupting the traditional focus on cost and compliance alone, forcing manufacturers to compete on comfort, style, and fit. The trend is most pronounced in the construction and light manufacturing sectors in North America, where "worker choice" programs empower individuals to select from a catalog of approved styles.
Safety Eyewear Market Segmentation
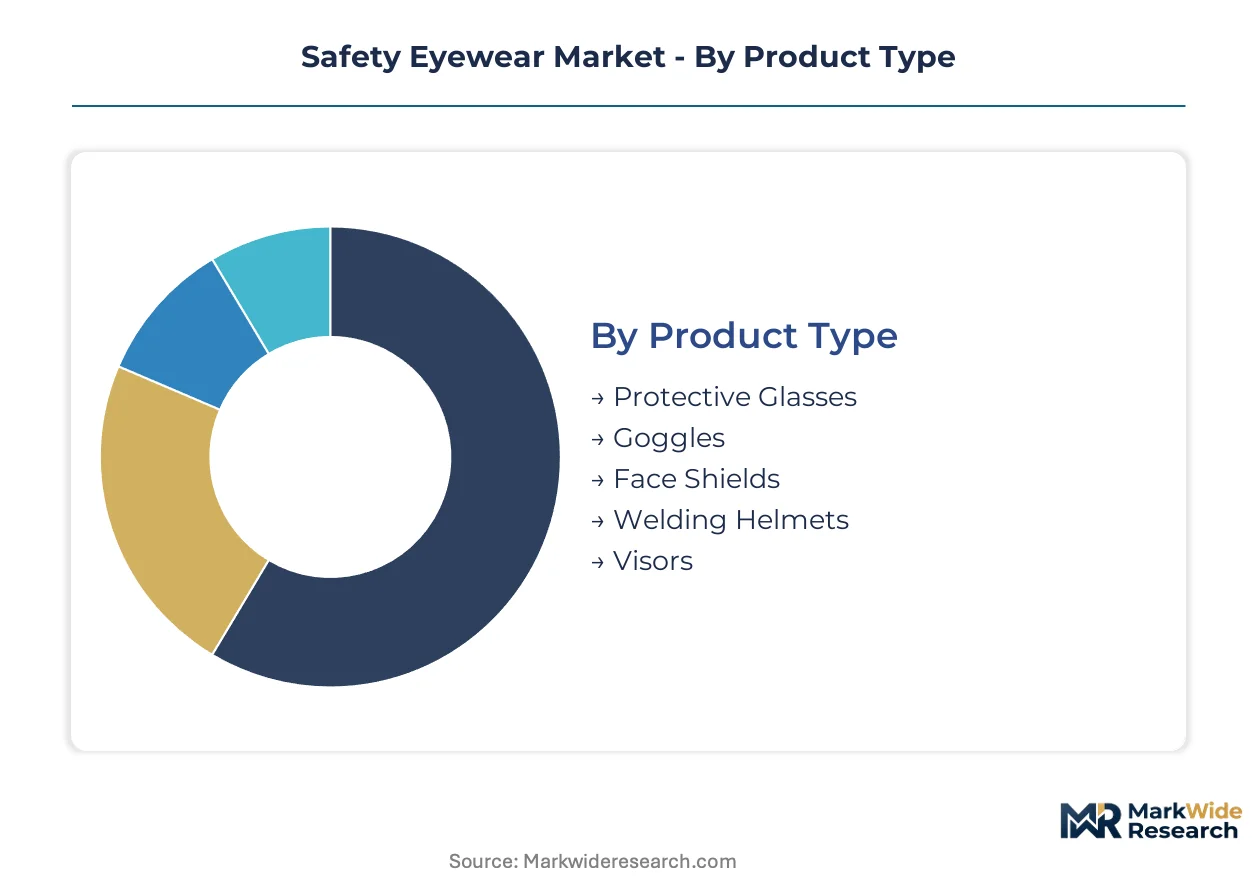
The safety eyewear market categorizes products and technologies to address diverse occupational hazards and user requirements. Understanding these segments helps manufacturers align product development with specific industry needs and regulatory compliance. Each segment reflects distinct performance criteria and market dynamics, influencing investment and innovation strategies.
Product Type:
High-capital investments in safety eyewear production frequently target segments offering specialized protection and advanced material integration.
- Protective Glasses:These devices typically feature impact-resistant polycarbonate lenses and lightweight frames, designed for general industrial use. Demand concentrates in the construction sector across North America due to broad OSHA mandates for eye protection.
- Goggles:Goggles provide a sealed fit around the eyes, offering enhanced protection against splashes, dust, and fine particles, often featuring indirect ventilation. Their primary deployment is in chemical processing plants in Germany, where EN 166 standards require comprehensive splash resistance.
- Face Shields:Face shields offer full-face protection from impact, splashes, and radiant heat, often used in conjunction with primary eye protection.
- Welding Helmets:Specialized helmets integrate dark filters to protect against intense light and UV radiation during welding operations.
- Visors:Visors attach to hard hats, providing additional facial protection without fully enclosing the head.
Protective Glasses absorb the bulk of installed capacity; Face Shields are expanding most quickly.
Technology:
The cost tier for safety eyewear technologies reflects both the complexity of the lens treatment and its perceived value to the end-user.
- Anti-Fog:These lens coatings prevent condensation buildup, ensuring clear vision in humid or rapidly changing temperature environments. Manufacturers focus on improving user comfort and reducing replacement frequency in sectors like manufacturing in India.
- Scratch Resistance:Durable lens coatings extend the lifespan of eyewear by minimizing surface damage from abrasive contact, crucial for maintaining optical clarity. This technology is vital for construction workers in Brazil, where harsh environments accelerate wear and tear.
- UV Protection:Lenses are treated to block harmful ultraviolet radiation, protecting eyes during outdoor work or in environments with UV light sources.
- Polarized Lenses:These lenses reduce glare from reflective surfaces, enhancing visual comfort and clarity for outdoor workers.
- Photochromic:Lenses automatically adjust their tint based on UV light exposure, providing adaptable protection for workers moving between indoor and outdoor settings.
Anti-Fog lens treatments dominate product specifications; Photochromic capabilities are gaining share fastest.
Application:
Application segments are primarily differentiated by the volume of units required and the specific hazards present in the work environment.
- Construction:This sector requires high volumes of impact-resistant eyewear to protect against flying debris, dust, and UV radiation on job sites. Regulatory bodies like OSHA in the US drive consistent demand for certified products.
- Manufacturing:Manufacturing environments demand protective eyewear to guard against projectiles, chemical splashes, and dust from machinery and processes. Compliance with EN 166 is critical for automotive plants in Europe.
- Laboratory:Laboratories require eyewear resistant to chemical splashes and fine particulate matter, often with specialized optical clarity.
- Mining:Mining operations necessitate robust eyewear capable of withstanding extreme impact, dust, and harsh environmental conditions.
- Chemical Processing:This application demands eyewear with superior chemical splash resistance and robust sealing against hazardous fumes.
Construction applications generate the largest volume demand; Chemical Processing exhibits the steepest expansion trajectory.
End User:
End-user segmentation categorizes demand based on professional roles and their specific interaction with workplace hazards.
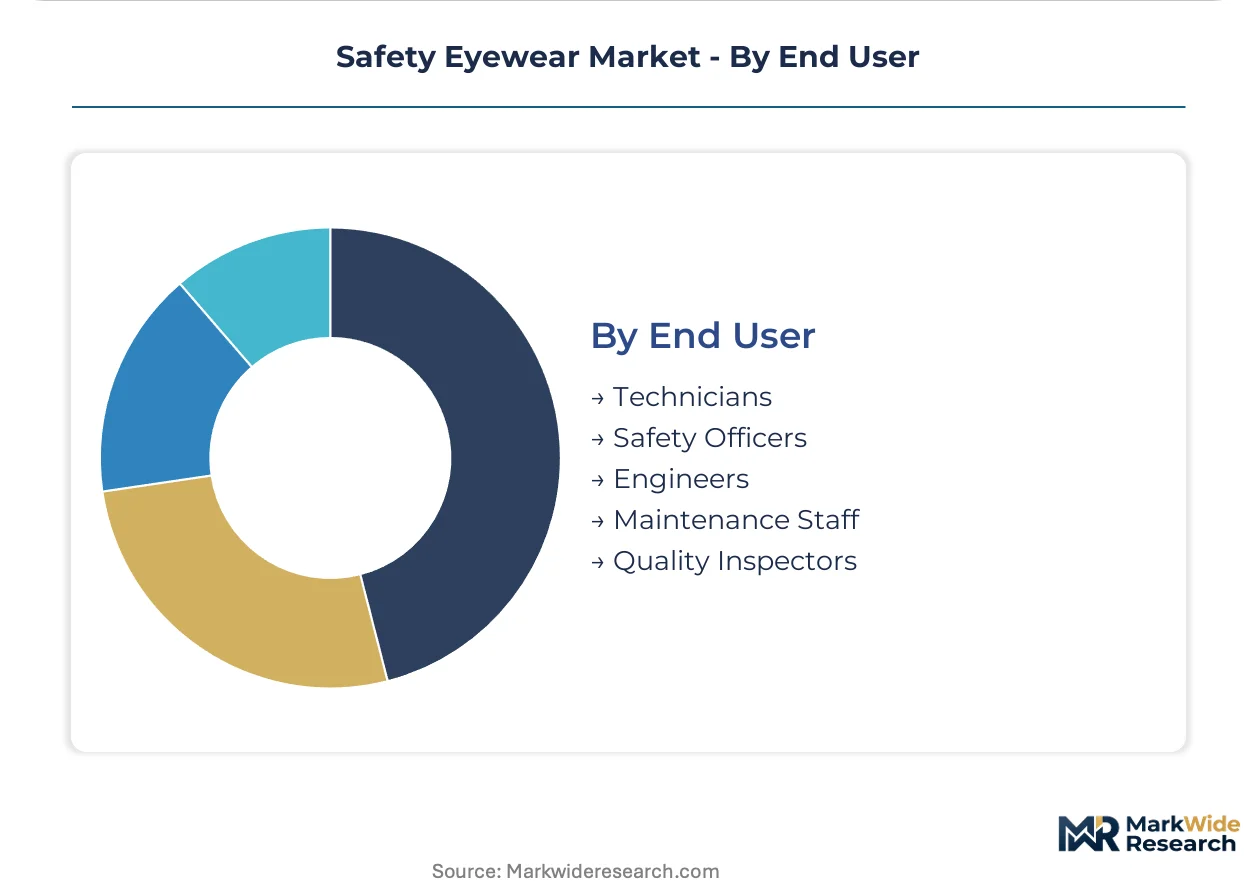
- Technicians:This broad category includes maintenance, repair, and operational staff who require general-purpose eye protection for daily tasks. Their diverse roles in manufacturing across China necessitate adaptable eyewear solutions.
- Safety Officers:These professionals are responsible for implementing and enforcing safety protocols, often influencing the procurement of certified eyewear for entire workforces. Their role in adhering to local regulations like CSA Z94.3 in Canada is critical.
- Engineers:Engineers in design, testing, and field supervision roles require eye protection tailored to specific project hazards.
- Maintenance Staff:Workers performing equipment upkeep and repair need durable eyewear resistant to impact and chemical exposure.
- Quality Inspectors:These individuals require clear, distortion-free vision for detailed work, often combined with basic impact protection.
Technicians represent the largest user group; Quality Inspectors are demonstrating the most rapid growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand-side concentration for safety eyewear reflects the distribution of heavy industries and the enforcement of occupational safety standards across key global economies. Industrialized nations with mature regulatory bodies drive consistent demand, while emerging markets present significant growth opportunities due to increasing industrialization.
United States
The construction and manufacturing sectors generate substantial demand for impact-resistant safety eyewear in the United States. OSHA mandates for eye protection drive consistent procurement of certified products. Major automotive manufacturing centers in Michigan require robust eye protection for assembly line workers.
Germany
Stringent EN 166 standards for personal eye protection significantly shape the market in Germany, particularly in chemical processing and automotive industries. High-tech manufacturing facilities in Bavaria prioritize advanced lens technologies for their workforce. The chemical industry in the Rhine-Main region requires specialized splash-resistant goggles.
India
Rapid industrial expansion and growing awareness of occupational hazards contribute to rising demand for protective eyewear in India. BIS standards are increasingly influencing product specifications and procurement decisions. Manufacturing clusters around Pune are seeing increased adoption of safety eyewear across various industrial applications.
China
China's vast manufacturing sector, with its large technician workforce, represents a significant market for adaptable safety eyewear solutions. GB standards for industrial safety are continuously evolving, pushing for higher performance requirements. Industrial zones in Guangdong province drive substantial volume demand for general-purpose safety glasses.
Brazil
Growth in the construction sector and challenging working conditions in industries like mining fuel demand for durable safety eyewear in Brazil. ANVISA regulations provide guidelines for personal protective equipment, influencing market access. Mining operations in Minas Gerais necessitate specialized protective gear for extreme environments.
Safety Eyewear Market Key Industry Players
North American producers anchor one tier; European specialists hold another, creating a diverse market structure for safety eyewear. The market exhibits a tiered structure, with global conglomerates operating alongside specialized regional suppliers. Strategic archetypes include global integrators, niche technology providers, and cost-effective volume manufacturers. Portfolio diversification and strategic partnerships are dominant competitive moves.
Within the global integrator archetype, 3M Company and Honeywell International Inc. exemplify broad product portfolios and extensive distribution networks. These companies leverage their established brand equity and materials science expertise to meet diverse industrial safety needs across multiple geographies. Uvex Group, a European specialist, emphasizes high-performance products and compliance with stringent regional standards, particularly for specialized applications.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| Uvex Group |
| Bolle Safety |
| Pyramex Safety Products LLC |
| Radians Inc. |
| Gateway Safety Inc. |
| MSA Safety Inc. |
| MCR Safety |
| Others |
Cost & Logistics Intelligence
Heightened enforcement of workplace safety laws by regulators, particularly OSHA in the US and EN 166 in Europe, drives demand for certified safety eyewear. This necessitates responsive supply chains capable of delivering compliant products, influencing overall market pricing.
Pricing Analysis
Volume sales of general-purpose protective glasses generate lower margins, while specialized goggles and smart eyewear command premium pricing. The pricing model primarily operates on a per-unit transactional basis, with differentiation driven by EN 166 certification levels and advanced lens coating technologies. Pricing pressure in the high-volume segment stems from intense competition among manufacturers. Small-to-medium enterprises exhibit higher price sensitivity compared to large industrial corporations.
Supply Chain Analysis
Dual-sourcing requirements for critical components enhance supply chain resilience for large industrial buyers. Production of polycarbonate resins, a key input, concentrates in Asia, particularly China and Taiwan, alongside specialized lens coating facilities. The supply chain relies on these regions for core material inputs, creating a structural risk from commodity price volatility. Distribution runs through a network of industrial safety distributors and specialized equipment providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The safety eyewear market is supply-constrained, with specialized lens coating capacity, particularly for anti-fog and photochromic treatments, creating a bottleneck. This limited capacity props up pricing for high-performance products.
For Market Incumbents: Anticipate continued pressure from counterfeit products by strengthening certification investment and enhancing materials science R&D. Diversify manufacturing footprint to mitigate geopolitical risks and secure raw material supply for high-impact polycarbonate. Consolidate market position through strategic acquisitions of niche technology providers. Invest in user-centric design to counter discomfort-driven non-compliance.
For New Entrants and Emerging Players: E-commerce platforms offer a direct-to-worker channel to target the underserved prescription safety eyewear segment. Focus on specialized applications like smart eyewear integration for logistics or healthcare, where existing solutions are less mature. Penetrate the construction and light manufacturing sectors by offering stylish, comfortable options through worker choice programs. Leverage agile manufacturing to customize products for specific regional standards.
For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with proven capabilities in advanced materials and smart eyewear integration. Long-term viability rests on companies capable of navigating evolving global standards and delivering customized solutions at scale. Target firms with strong intellectual property in anti-fog or photochromic lens technologies. A key signal to watch is the increasing M&A activity in augmented reality overlay companies.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Expanding high-performance lens coating capacity in Europe addresses rising demand for EN 166 compliant products. |
| Product Launch | Launching new smart eyewear with augmented reality overlays creates high-value products for specialized industrial applications. |
| Strategic Partnership | Partnering with vision care providers expands distribution for customized prescription safety eyewear in North America. |
| R&D Investment | Investing in bio-based polycarbonate research aligns with environmental, social, and governance mandates from large corporations. |
| Certification Enhancement | Achieving CSA Z94.3 certification in Canada broadens market access for protective glasses in construction. |
Research Approach
Document review covered regulatory filings, industry association reports, and trade publications, complemented by interviews with industry stakeholders. Primary research engaged safety officers, procurement managers, R&D engineers, and end-users across various industrial sectors. This approach triangulated insights from both bottom-up market observations and top-down strategic perspectives for the safety eyewear market.
Historical market data was cross-referenced against expert panel input to establish a robust analytical framework across the analysis window. The model segmented demand by product type, technology, application, end-user, and regional regulatory frameworks. Compound Annual Growth Rates were derived by analyzing historical trends and projected impacts of regulatory changes and material science breakthroughs.
The model holds under current occupational safety regulatory environments and projected material supply stability. Forecasts reflect these assumptions, but significant shifts in global economic conditions or disruptive material innovations could alter market dynamics. Deviation in new regulatory mandates would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Barricade Tape Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Seat Belt System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Collision Avoidance System Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Guards Market
Safety Equipment and Personal Protective Equipment (PPE)
Gas Detection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Bicycle Safety Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market
Safety Equipment and Personal Protective Equipment (PPE)
United States Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Process Safety Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Cryogenic PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Riot Control Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Diving and Survival Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Powered Air Purifying Respirator (PAPR) Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Mask Market