
 Europe Safety Connection Devices Market | 2026-2036
Europe Safety Connection Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Safety Connection Devices Market Foresight
CE marking under the EU Machinery Directive is rotating the competitive field, forcing smaller suppliers toward third-party certification investments they cannot absorb. Siemens AG anchors the German market through captive distribution and in-house production of safety-rated fieldbus modules. Schneider Electric Company differentiates via modular architectures that simplify retrofit installations in aging French automotive plants. Rockwell Automation Inc. competes by leveraging its GuardLogix platform to bridge North American safety protocols with European EN ISO standards.
Europe Safety Connection Devices encompass electromechanical and electronic components engineered to IEC 61508 and EN ISO 13849 functional safety standards, with rated switching capacities between 6A and 10A and response times under 10 milliseconds for emergency stop circuits. These devices isolate hazardous energy, monitor guard doors, and transmit safety signals across machine zones in automated environments. Safety controllers and relays lead product category revenue due to mandatory redundancy requirements in Category 3 and Category 4 safety architectures. Wired technology still dominates installation value, though IoT-enabled segments are gaining traction where predictive maintenance contracts justify wireless infrastructure costs. Manufacturing end users represent the deepest buyer pool, particularly in metalworking and packaging lines where machinery density demands distributed safety I/O.
The EU Green Deal and F-Gas Regulation are reshaping material specifications for sealed housings and contact materials in safety connection devices. ECHA's REACH restrictions on cadmium and lead in electrical contacts are forcing reformulation of relay terminal alloys, adding qualification cycles that favor incumbent suppliers with dedicated metallurgy labs. Germany's KBA and France's ANSM both influence sector-specific safety interpretations for automotive and pharmaceutical machinery, creating overlapping compliance layers. Stakeholders must monitor whether the EU AI Act extends safety integrity requirements to algorithmically controlled connection logic in next-generation systems.
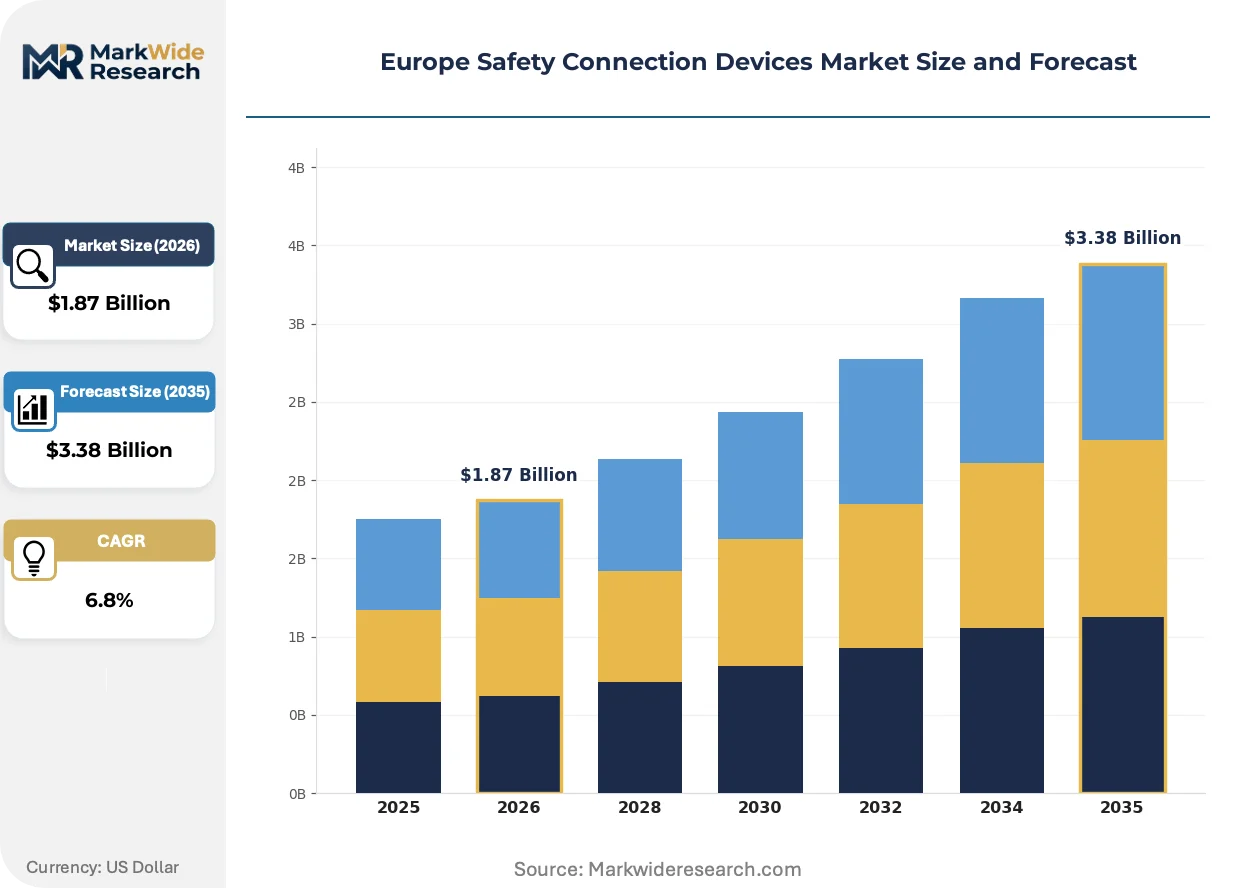
Market Dynamics
EU Green Deal compliance timelines are forcing simultaneous reformulation of contact alloys and housing materials across the European safety device supply base, compressing qualification cycles and concentrating procurement among suppliers with captive metallurgy capabilities.
Growth Catalysts
- Automotive Electrification Mandates:Germany's KBA safety interpretations for battery assembly lines mandate redundant safety I/O architectures, expanding demand for Category 4 safety controllers in Stuttgart and Wolfsburg production corridors.
- REACH Restrictions on Heavy Metals:ECHA's cadmium and lead limitations in electrical contacts are accelerating qualification of silver-nickel and gold-plated alternatives, favoring incumbent relay manufacturers with dedicated alloy development labs.
- French Pharmaceutical Machinery Retrofit Wave:ANSM guidance on isolator and containment line safety is driving replacement of mechanical interlocks with networked safety modules in Lyon and Strasbourg pharmaceutical clusters.
Market Restraints
- Raw Material Concentration Risk:Palladium and rhodium for high-reliability contacts concentrate in South African and Russian supply channels, exposing European manufacturers to price volatility and sanctions-related sourcing friction.
- CE Marking Certification Burden:Updated EU Machinery Directive conformity assessment procedures require third-party notified body involvement for Category 4 safety architectures, adding 6-12 month qualification timelines that smaller suppliers cannot absorb.
- Wireless Safety Protocol Maturity Gap:IEC 61508-certified wireless safety transmission remains limited to SIL 2 applications, constraining deployment in Category 3 and 4 architectures where wired redundancy still dominates.
Strategic Opportunities
- Polish Industrial Corridor Expansion:Automotive and appliance manufacturing growth in Lower Silesia and Greater Poland regions lacks mature safety system integrators, creating first-mover advantage for certified device distributors establishing local technical support.
- EU AI Act Safety Integrity Extension:Anticipated algorithmic control requirements for safety-critical connection logic will demand new certification frameworks, positioning early movers with embedded AI-capable safety controllers.
- Predictive Maintenance Contract Bundling:IoT-enabled safety modules with vibration and temperature sensing are enabling outcome-based service models in German metalworking lines, shifting revenue from hardware to uptime-guarantee contracts.
Industry Challenges
- Functional Safety Engineering Talent Scarcity:IEC 61508 and EN ISO 13849 certification expertise concentrates among aging specialists in Munich and Paris consulting pools, constraining system integrator expansion.
- Legacy Fieldbus Integration Complexity:German automotive plants running PROFIsafe and French facilities on CIP Safety require protocol translation gateways, adding engineering cost and failure modes to retrofit projects.
- Dual-Chemistry Contact Qualification Overlap:Manufacturers must simultaneously qualify lead-free alloys for EU REACH compliance and maintain legacy cadmium-bearing production for export markets, duplicating test matrices and inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Safety Connection Devices Market |
| Market Size in 2026 | $1.87 Billion |
| Market Size in 2035 | $3.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relays, Circuit Breakers, Emergency Stops, Safety Controllers End User: Manufacturing, Construction, Automotive, Chemical Technology: Wired, Wireless, IoT-Enabled, Optical Installation Type: Fixed, Portable, Integrated, Modular |
| Companies Covered | ABB Ltd., Siemens AG, Rockwell Automation Inc., Honeywell International Inc., Schneider Electric Company, Bihl+Wiedemann GmbH, Murrelektronik, Lumberg Automation, Mouser Electronics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Safety Connection Devices Market Shifts & Advancements
Safety connection architectures are fragmenting along protocol lines while material science and service model innovation create new competitive dimensions. Three developments are restructuring procurement patterns and technical roadmaps.
Modular safety I/O systems with distributed intelligence are decomposing traditional centralized safety controller architectures. Automotive OEMs in Bavaria and Baden-Württemberg are deploying these systems at pilot scale, reducing wiring density by enabling safety logic execution at the edge. This decomposition is compressing margins for legacy safety PLC suppliers while elevating fieldbus module specialists with embedded certification expertise.
ECHA's REACH Annex XVII restrictions on cadmium in electrical contacts entered enforcement phase in 2024, forcing reformulation of relay terminal alloys across the European supply base. Silver-nickel and gold-palladium alternatives require redesigned contact geometry to maintain switching reliability, extending qualification cycles for safety-rated devices. German automotive suppliers and French packaging machinery builders are absorbing these costs fastest due to captive metallurgy partnerships.
Buyer preference is consolidating around certified system integrators with in-house functional safety engineering rather than component distributors. German chemical processors and Italian metalworking lines are selecting safety device suppliers based on TÜV-certified integration capability, not product specifications alone. This consolidation is most visible in the Rhine-Ruhr industrial corridor, where end users are reducing vendor counts from twelve to three qualified system partners.
Europe Safety Connection Devices Market Segmentation
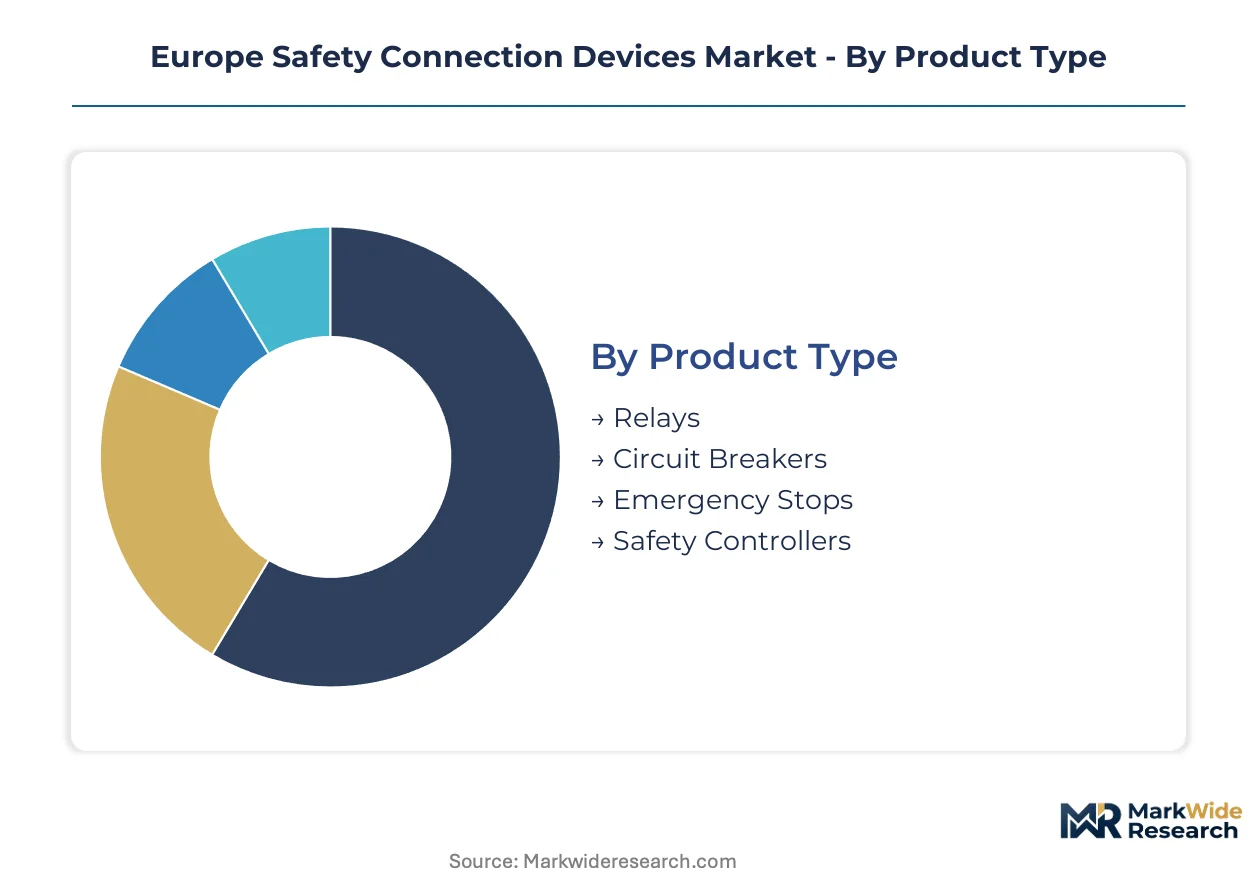
Segmentation in the Europe Safety Connection Devices Market reveals divergent growth mechanics across product architectures, end-use verticals, and connectivity modes. Procurement patterns cluster around regulatory compliance tiers and retrofit complexity, with German automotive OEMs and French pharmaceutical builders driving specification divergence.
Product Type:
German automotive corridors consume safety controllers and relays at domestic scale, while circuit breakers and emergency stops serve export machinery builders across Eastern Europe and North Africa.
- Safety Controllers:These units execute Category 3 and Category 4 safety logic with redundant processing channels certified to EN ISO 13849. Demand concentrates in Stuttgart and Wolfsburg battery assembly lines where KBA interpretations mandate redundant I/O architectures for high-voltage handling zones.
- Relays:Electromechanical and solid-state variants provide force-guided contact redundancy for emergency stop chains. ECHA REACH restrictions on cadmium and lead contacts are accelerating silver-nickel alloy qualification in German relay manufacturing clusters.
- Circuit Breakers:Motor-protective and safety-monitoring breakers isolate hazardous energy during fault conditions.
- Emergency Stops:Latching mushroom-head devices with positive-break contacts remain mandatory for machinery guard door circuits.
Safety controllers command the established base. The steepest expansion runs through relays as contact alloy reformulation cycles complete.
End User:
Cost tier stratification separates premium-certified system integrators serving German automotive from economy-tier distributors supplying Polish appliance manufacturing.
- Automotive:Battery assembly and powertrain lines in Bavaria and Baden-Württemberg specify Category 4 safety architectures with distributed intelligence modules. OEM captive integration teams are reducing external vendor counts from twelve to three qualified partners.
- Manufacturing:Metalworking and packaging machinery density in the Rhine-Ruhr corridor demands distributed safety I/O for zone-to-zone signal transmission.
- Chemical:Process safety integrity requirements in Ludwigshafen and Antwerp clusters favor wired PROFIsafe implementations over wireless alternatives.
- Construction:Mobile machinery and tower crane applications drive portable safety module demand with IP67 sealing requirements.
Automotive end users command the established base. Manufacturing is expanding most quickly through predictive maintenance contract bundling in metalworking lines.
Technology:
Volume concentration favors wired installations, though margin expansion concentrates in IoT-enabled segments where vibration and temperature sensing justifies wireless infrastructure premiums.
- Wired:Copper-based fieldbus and point-to-point safety circuits dominate Category 3 and 4 architectures. German automotive plants running PROFIsafe and French facilities on CIP Safety require protocol translation gateways, adding engineering complexity to retrofit projects.
- IoT-Enabled:Embedded sensors transmit diagnostic data to cloud platforms for predictive maintenance contracting. German metalworking lines are shifting revenue models from hardware sales to uptime-guarantee service agreements.
- Wireless:SIL 2-certified safety transmission remains limited, constraining deployment in higher-integrity architectures.
- Optical:Fiber-optic safety signal transmission serves electromagnetic interference environments in welding and induction heating zones.
Wired technology commands the established base. IoT-enabled modules are gaining share fastest through outcome-based service model adoption.
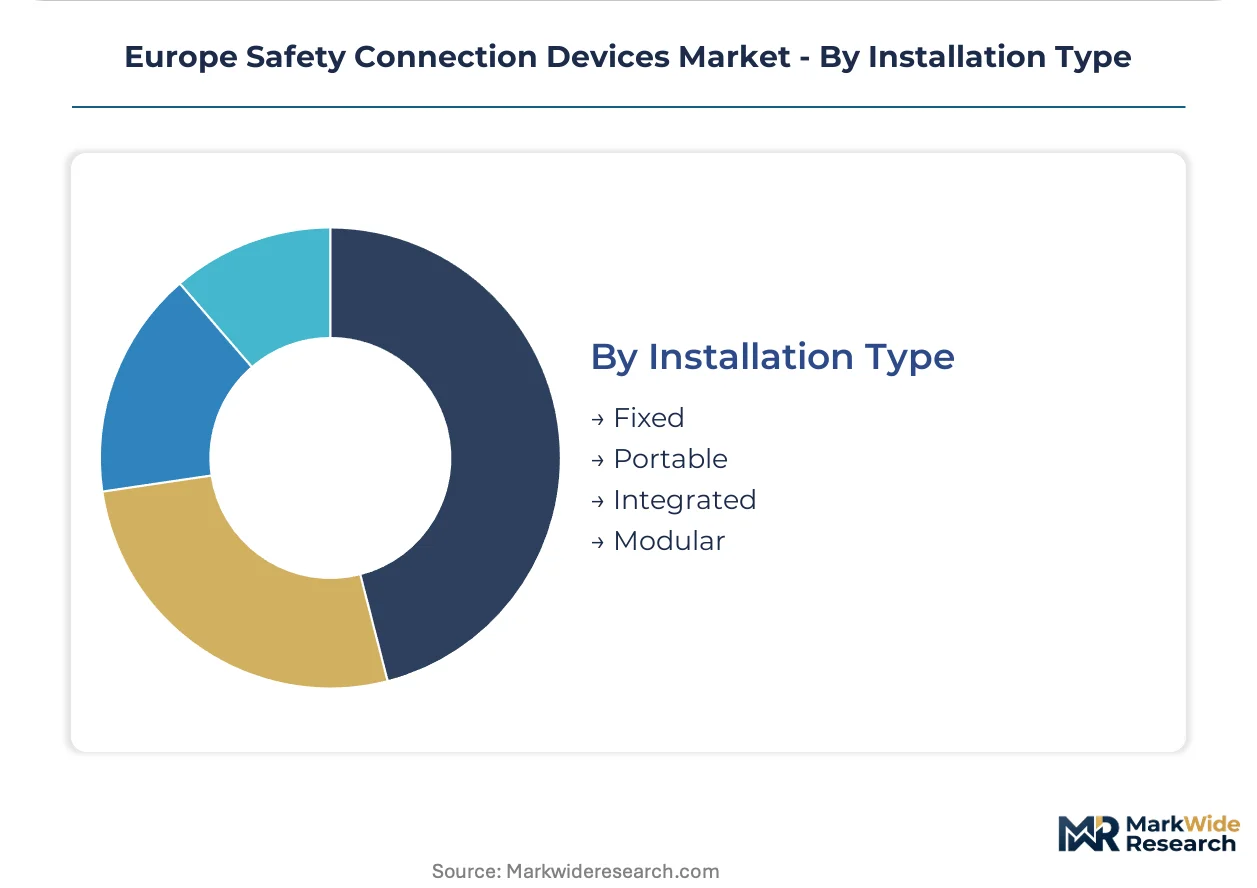
Installation Type:
Customer type stratification separates OEM machinery builders specifying integrated safety from system integrators preferring modular retrofit architectures.
- Modular:Distributed safety I/O with edge intelligence reduces wiring density in aging French automotive plants. Schneider Electric's modular architectures are capturing retrofit share through simplified DIN-rail mounting and certified plug-in connectivity.
- Fixed:Hardwired safety controllers and relay panels dominate greenfield machinery builds with centralized cabinet architectures.
- Portable:Mobile safety pendants and wireless enabling switches serve construction and logistics machinery with temporary safeguarding needs.
- Integrated:Embedded safety logic within servo drives and motion controllers compresses panel space in compact machinery designs.
Fixed installations command the established base. Modular systems are climbing the fastest as distributed intelligence decomposes legacy centralized architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway and Germany's dense autobahn network underpin Europe's industrial safety corridor, channeling component flows between manufacturing clusters from Stuttgart to Lyon.
Germany
Bavarian battery assembly lines and Wolfsburg powertrain plants specify Category 4 safety architectures with distributed intelligence modules. KBA safety interpretations for high-voltage handling zones mandate redundant I/O configurations. Stuttgart's automotive OEMs are consolidating vendor counts from twelve suppliers to three qualified system integrators with TÜV-certified engineering capability.
France
Pharmaceutical machinery builders in Lyon and Strasbourg clusters replace mechanical interlocks with networked safety modules under ANSM isolator guidance. Île-de-France packaging OEMs favor modular DIN-rail architectures for aging plant retrofits. CIP Safety protocol adoption in Renault supply chains creates specification divergence from German PROFIsafe implementations.
Italy
Lombardy metalworking lines and Emilia-Romagna packaging machinery density drive distributed safety I/O procurement for zone-to-zone signal transmission. CE marking conformity assessment timelines compress vendor selection toward notified-body-certified integrators. Turin automotive suppliers are bundling predictive maintenance contracts with IoT-enabled safety module deployments.
Poland
Lower Silesia automotive plants and Greater Poland appliance manufacturing lack mature safety system integrators, creating first-mover openings for certified distributors establishing local technical support. EU Machinery Directive compliance obligations accelerate as Polish machinery exports face German and French buyer certification requirements. Wrocław industrial zones show fastest uptake of modular retrofit architectures.
Netherlands
Rotterdam-Antwerp chemical corridor favors wired PROFIsafe implementations over wireless alternatives for process safety integrity. Port machinery electrification and inland shipping automation drive IP67-sealed portable safety module demand. Eindhoven's high-tech systems sector incubates edge-intelligence safety I/O pilots for semiconductor equipment applications.
Europe Safety Connection Devices Market Competitive Landscape
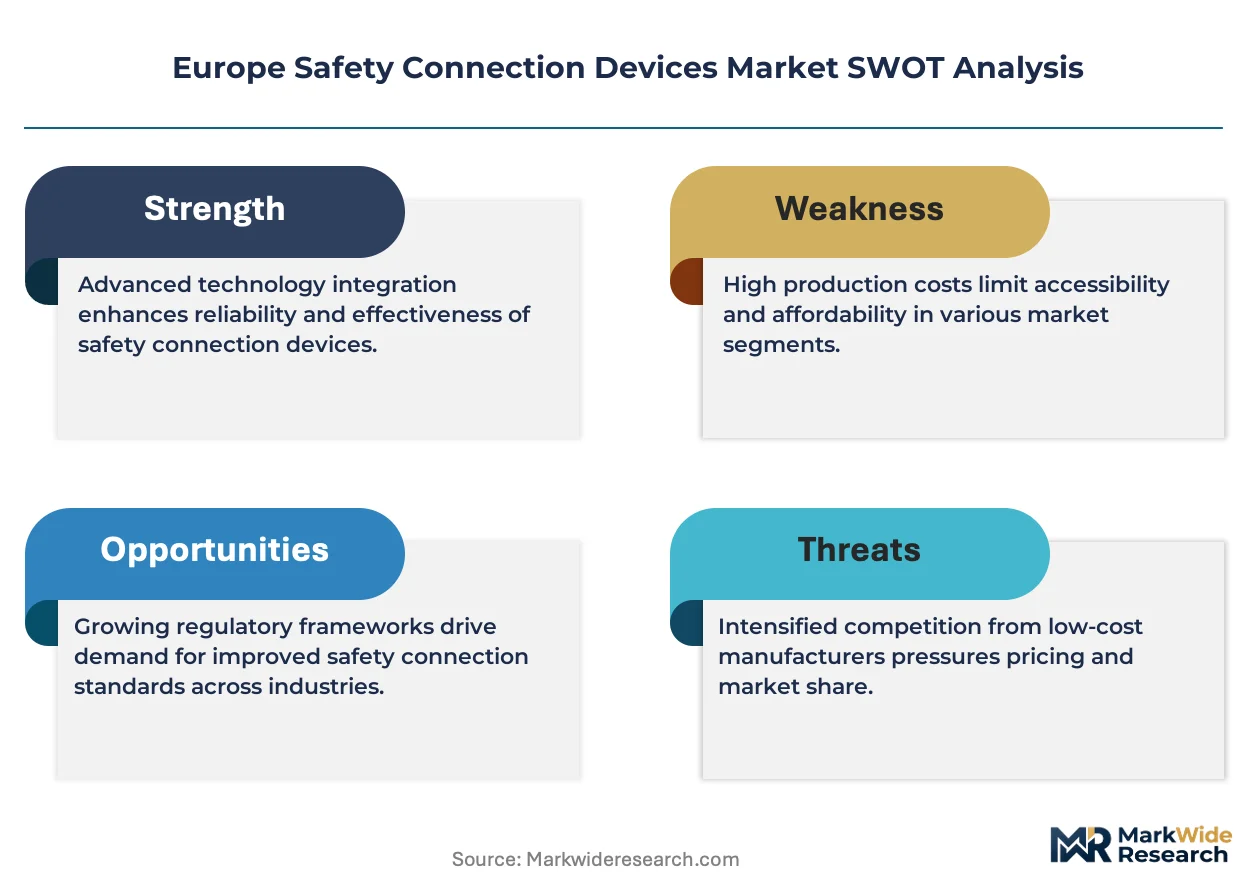
Listed leaders compete with private specialists across certification depth and captive metallurgy capability, producing a tiered structure where scale-driven conglomerates anchor volume segments while family-owned engineering houses capture retrofit niches. Siemens AG and ABB Ltd. dominate through in-house production of safety-rated fieldbus modules and captive distribution networks. Three archetypes define positioning: integrated conglomerates with captive metallurgy labs, modular architecture specialists simplifying retrofit installations, and North American protocol bridge providers. Competitive moves concentrate on strategic partnerships with automotive OEMs and vertical integration into alloy development to absorb REACH qualification cycles.
Within the integrated conglomerate tier, Siemens AG anchors the German market through captive distribution and in-house safety-rated fieldbus production. Schneider Electric Company exemplifies the modular architecture specialist archetype, occupying a position in French automotive retrofit segments. Rockwell Automation Inc. represents the North American protocol bridge category, leveraging its GuardLogix platform to span EN ISO standards. Bihl+Wiedemann GmbH sits within the private specialist tier of German safety I/O providers.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Rockwell Automation Inc. |
| Honeywell International Inc. |
| Schneider Electric Company |
| Bihl+Wiedemann GmbH |
| Murrelektronik |
| Lumberg Automation |
| Mouser Electronics |
| Others |
Supply & Pricing Matrix
Capacity utilization at German relay manufacturing clusters shapes both supply concentration and price floors for safety-rated contact alloys. Scale economies in captive metallurgy labs allow incumbents to absorb ECHA REACH qualification cycles while smaller suppliers face margin compression from third-party certification investments.
Pricing Analysis
Certification level creates the primary spread across the European safety device market. Three-tier pricing structure across TÜV-certified premium, standard CE-marked, and economy-tier uncertified levels dominates procurement. Price differentiation hinges on EN ISO 13849 Category 4 compliance and captive alloy development capability. Cost compression in standard-tier relays is intensifying because REACH-driven silver-nickel reformulation raises material costs. Polish appliance manufacturers show highest price sensitivity; German automotive OEMs prioritize certification over unit cost.
Supply Chain Analysis
Germany and France anchor safety controller and relay fabrication for European industrial automation. Palladium and rhodium for high-reliability contacts draw from South African and Russian supply channels, exposing manufacturers to sanctions-related sourcing friction. Single-source vulnerability concentrates in noble metal refining. Distribution runs through certified system integrators with TÜV engineering capability rather than component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated automotive OEMs reducing vendor counts from twelve suppliers to three qualified system integrators. This consolidation compresses margins for undifferentiated component vendors.
For Market Incumbents: Consolidate metallurgy partnerships to absorb ECHA REACH qualification cycles and defend against modular architecture specialists capturing French retrofit share. Prioritize backward integration into silver-nickel alloy development. Lock in TÜV-certified engineering talent pools in Munich and Paris to maintain integration capability differentiation.
For New Entrants and Emerging Players: Differentiate on predictive maintenance contract bundling with IoT-enabled safety modules in German metalworking lines. Target Poland's Lower Silesia automotive corridor where certified system integrators remain scarce. Pursue local technical support partnerships rather than direct distribution to overcome buyer preference for qualified integration partners.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors modular safety I/O specialists with embedded edge intelligence over legacy centralized PLC architectures. Long-term viability rests on capturing retrofit waves in aging French pharmaceutical plants and Italian packaging machinery. Watch for EU AI Act algorithmic safety integrity requirements as inflection indicator for embedded AI-capable controller demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Metallurgy Lab Investment | Absorbs ECHA REACH qualification cycles and protects margin structure against reformulation costs. |
| Modular Safety I/O Platform Launch | Captures French automotive retrofit demand through simplified DIN-rail mounting architectures. |
| Predictive Maintenance Contract Bundling | Shifts revenue from hardware sales to uptime-guarantee service agreements in German metalworking. |
| Polish Technical Support Expansion | Establishes first-mover position in undersupplied Lower Silesia automotive corridor. |
| EU AI Act Compliance Pathway | Positions early movers for algorithmic safety integrity requirements in next-generation controllers. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at German automotive OEMs, safety system integrators in the Rhine-Ruhr corridor, procurement leads at French pharmaceutical machinery builders, and TÜV certification specialists. These perspectives were refined against secondary validation from ECHA regulatory filings, EU Machinery Directive conformity assessment databases, SEC 10-K disclosures from listed automation suppliers, and Cefic chemical industry safety reports. Bottom-up demand modeling across end-use verticals was triangulated with top-down supply-side capacity estimates.
Variance decomposition across product type, end-use vertical, technology mode, and installation architecture shaped the analytical framework. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated KBA safety interpretation timelines for battery assembly lines and ANSM pharmaceutical machinery guidance enforcement patterns.
Material uncertainties — REACH restriction expansion, palladium supply disruption, wireless safety protocol certification delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and alloy qualification cycle completion. Recalibration cycles align with material shifts in EU AI Act implementation and automotive electrification mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
South America Protective Coating Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Emergency Showers Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Anti-Vibration Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safety Switches Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Eye Wear Market
Safety Equipment and Personal Protective Equipment (PPE)
Driving Protection Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Tube and Dressing Securement Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa Intrinsically Safe Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Machine Guarding Fence Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Mirrors Market
Safety Equipment and Personal Protective Equipment (PPE)
Radiation Protection Cabins Market