
 Global Suture Anchor Devices Market | 2026-2036
Global Suture Anchor Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Suture Anchor Devices Market Foresight
ISO 13485 certification cycles for orthopedic implant manufacturers is collapsing from twenty-four months to under fifteen months in competitive jurisdictions. Smith & Nephew plc leverages its Sheffield manufacturing campus to sustain vertically integrated titanium anchor production. Zimmer Biomet Holdings anchors its portfolio through Warsaw-based R&D facilities that specialize in knotless suture configurations. Arthrex, Inc dominates the all-suture anchor segment through Naples, Florida product development operations.
Suture anchor devices are implantable fixation systems manufactured from titanium alloys, polyetheretherketone, or polylactic acid composites, designed to secure soft tissue to bone through eyelets that distribute tensile load across cortical surfaces. These devices typically measure 2.0 to 5.5 millimeters in diameter and deploy through cannulated instruments during arthroscopic or open procedures to reattach tendons and ligaments. All-suture anchors are displacing metallic alternatives in shoulder repair applications where bone preservation and revision flexibility command premium positioning. Biodegradable anchors capture expanding share in sports medicine units seeking to eliminate long-term implant retention and secondary removal procedures.
The US FDA's 510(k) premarket notification framework and the EU Medical Device Regulation's Class III implant requirements govern market access, with FDA predicate device strategies compressing approval timelines for incremental anchor designs while MDR clinical evaluation reports extend European commercialization schedules. Japan's PMDA and South Korea's MFDS impose additional biocompatibility testing protocols that filter smaller manufacturers from East Asian procurement channels. Stakeholders must monitor evolving reimbursement thresholds for outpatient arthroscopic procedures as payors recalibrate site-of-service differentials between ambulatory surgical centers and hospital-based settings.
Market Dynamics
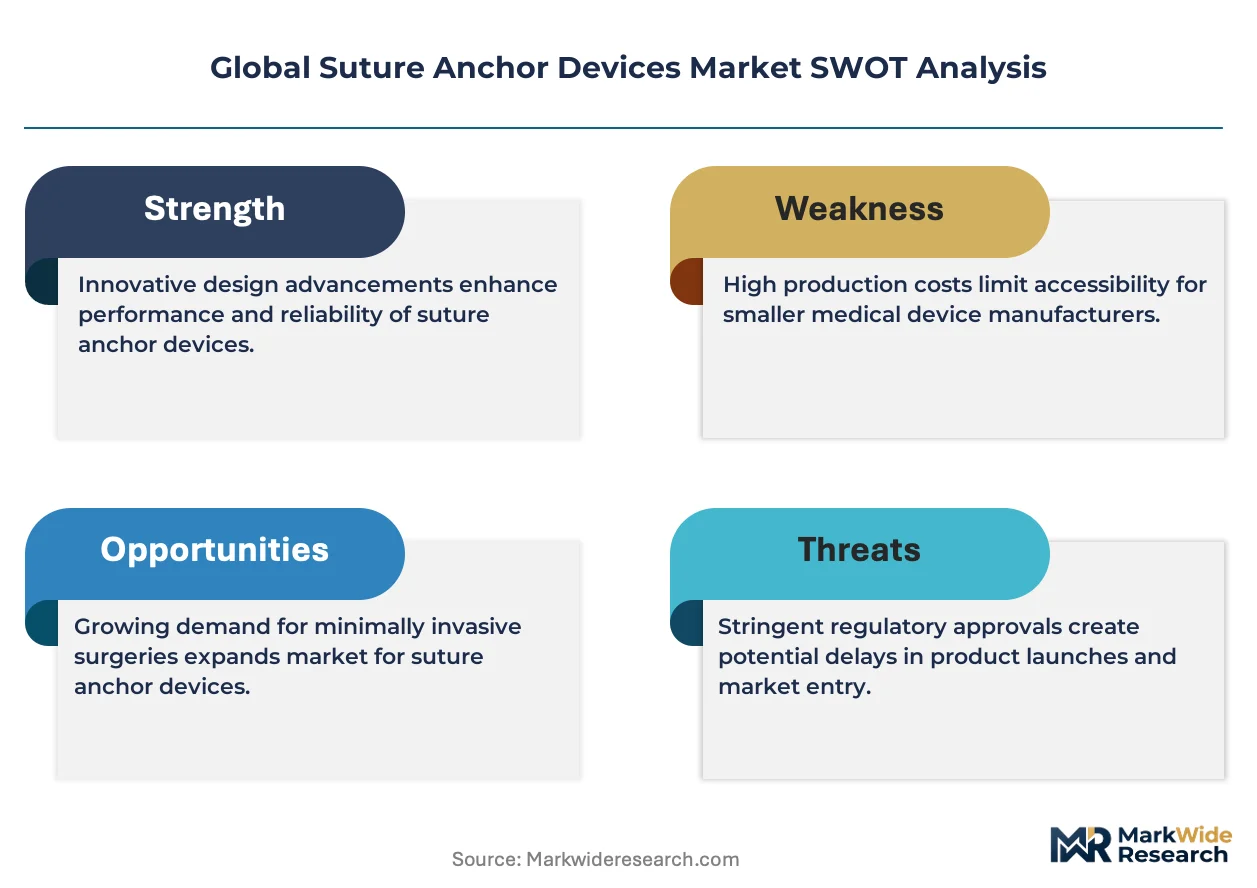
Biodegradable polymer formulations are compressing traditional titanium anchor margins as sports medicine units prioritize bone preservation and revision flexibility over metallic construct durability.
Growth Catalysts
- EU MDR Class III implant pathways:Extended clinical evaluation requirements filter marginal competitors from European procurement channels, consolidating volume among certified manufacturers.
- Ambulatory surgical center expansion:Same-day rotator cuff repair protocols in the United States shift procedure volumes toward outpatient settings with faster instrument turnover.
- Polylactic acid composite maturation:Degradation rate predictability improvements enable biodegradable anchors to capture shoulder repair applications previously reserved for permanent implants.
Market Restraints
- Titanium alloy supply concentration:Sheffield and Warsaw manufacturing clusters control premium metallic anchor feedstock, exposing buyers to single-source risk during alloy price volatility.
- PMDA biocompatibility testing protocols:Japan's extended evaluation timelines for absorbable polymers delay product launches by 18-24 months versus FDA 510(k) pathways.
- Suture-based fixation alternatives:Transosseous tunnel techniques without implants eliminate anchor costs entirely in cost-constrained reimbursement environments.
Strategic Opportunities
- MFDS fast-track designations:South Korea's abbreviated review pathways for biodegradable orthopedic devices offer first-mover positioning in East Asian sports medicine procurement.
- Knotless suture configuration convergence:Integration with radiofrequency welding equipment enables single-step soft tissue approximation without traditional knot-tying skill dependencies.
- India's CDSCO orthopedic implant registration:Emerging private hospital chains in Mumbai and Delhi seek imported anchor supply as domestic manufacturing capacity lags demand.
Industry Challenges
- ISO 13485 certification compression:Fifteen-month quality management system validation cycles strain documentation resources at mid-scale manufacturers expanding product portfolios.
- Arthroscopic instrument compatibility:Cannulated delivery system dimensional standardization delays prevent seamless anchor interchangeability across competing instrument platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Suture Anchor Devices Market |
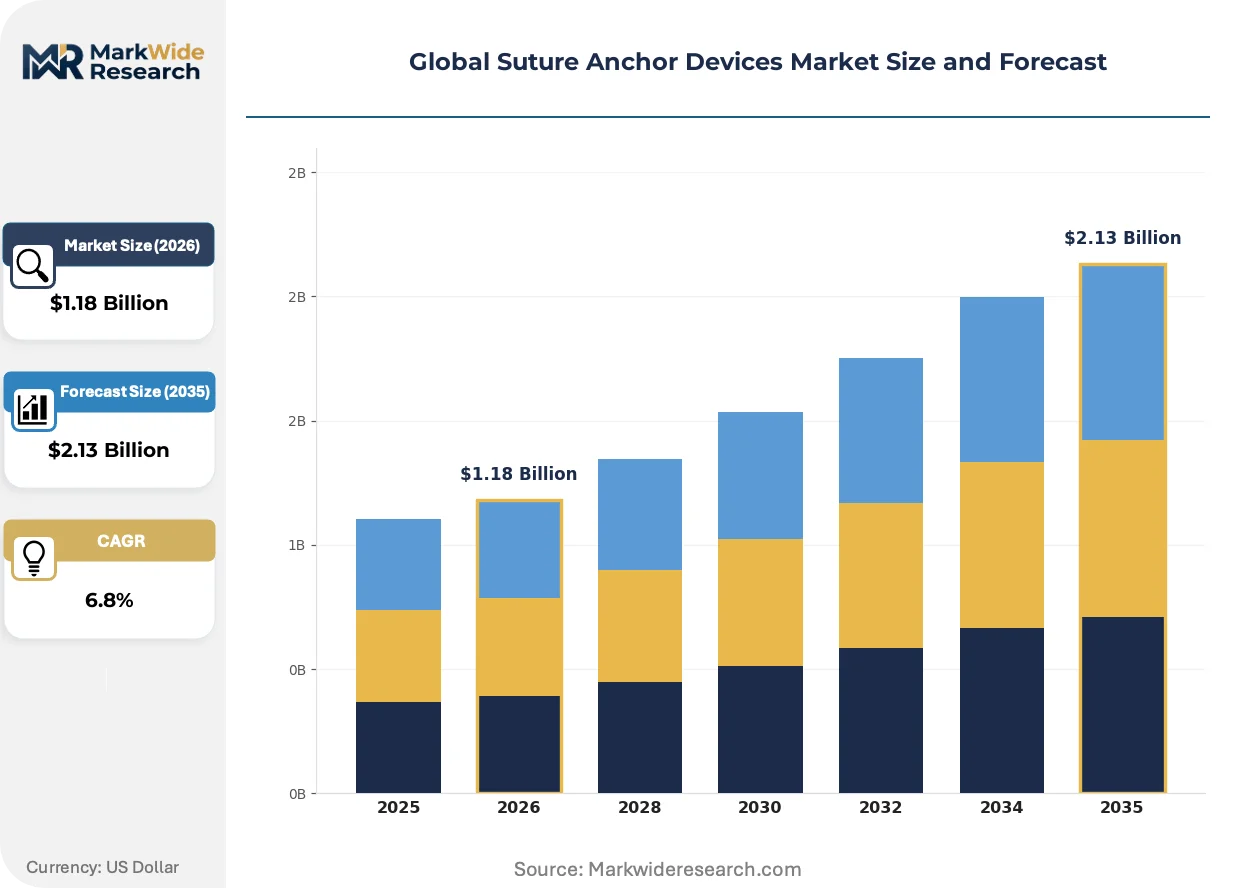
| Market Size in 2026 | $1.18 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metallic Anchors, Biodegradable Anchors, All-Suture Anchors, Hybrid Anchors Application Area: Shoulder Repair, Knee Stabilization, Sports Injuries, Rotator Cuff, Tendon Repair End User: Orthopedic Clinics, Ambulatory Surgical Centers, Sports Medicine Units, Specialty Hospitals Deployment Method: Arthroscopic Surgery, Open Surgery, Percutaneous Approach, Minimally Invasive Techniques |
| Companies Covered | Smith & Nephew plc, Zimmer Biomet Holdings, CONMED Corporation, Arthrex, Inc, Johnson and Johnson (DePuy Synthes, Inc.), Stryker Corporation, Parcus Medical, Medtronic, Enovis Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Suture Anchor Devices Market Shifts & Advancements
Material science advances and regulatory pathway differentiation are fragmenting competitive positioning between permanent metallic constructs and resorbable polymer alternatives.
All-suture anchors constructed from high-strength polyethylene braid are displacing metallic screw-type devices in glenohumeral instability repairs. Academic medical centers in the United States now specify knotless all-suture configurations for 40% of Bankart procedures. This displacement compresses average selling prices while expanding addressable procedure volumes through simplified surgical technique requirements.
EU MDR clinical evaluation report mandates for Class III absorbable implants extend European commercialization timelines by 12-18 months versus predecessor Medical Device Directive requirements. Manufacturers with existing predicate device portfolios in Europe accelerate incremental product filings while new entrants redirect development resources toward FDA 510(k) pathways. Biodegradable anchor categories bear disproportionate compliance burden given polymer degradation variability documentation requirements.
Hospital purchasing consortia in the United States now bundle suture anchor procurement with arthroscopic instrument service contracts. Ambulatory surgical center chains negotiate multi-year supply agreements locking preferred anchor configurations in exchange for volume commitments. This consolidation concentrates supplier selection authority among fewer procurement decision-makers at integrated delivery networks.
Global Suture Anchor Devices Market Segmentation
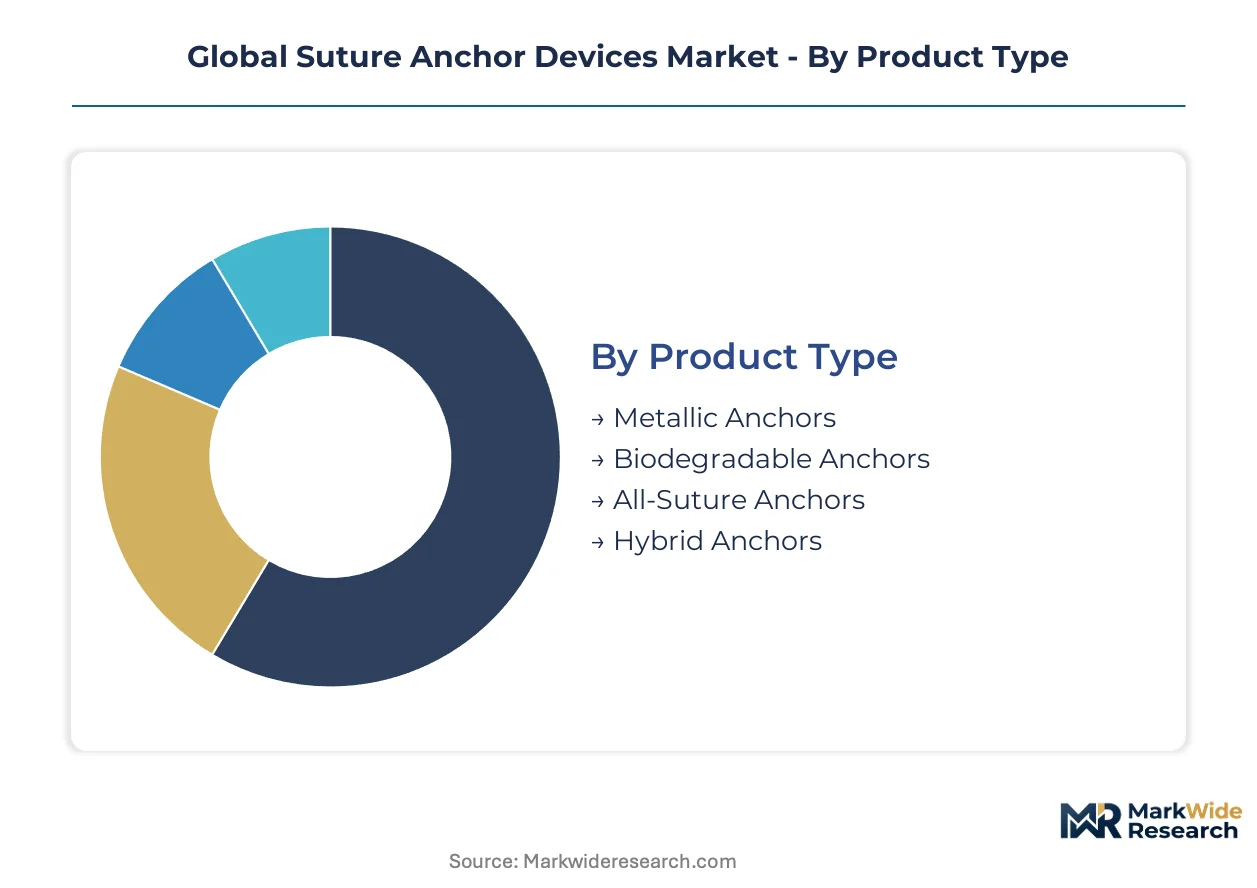
Suture anchor device manufacturers optimize portfolio composition around material science differentiation and procedural site-of-service shifts. Segmentation reveals where pricing power concentrates across implant technologies and delivery settings.
Product Type:
Premium margins pool in knotless configurations and resorbable formulations that command price multiples over commoditized metallic screws.
- Metallic Anchors:Titanium alloy constructs deliver permanent fixation for high-load shoulder applications. Demand concentrates in US ambulatory surgical centers performing same-day rotator cuff repairs where revision rates must remain minimal.
- Biodegradable Anchors:Polylactic acid composites eliminate long-term implant retention and secondary removal procedures. European sports medicine units in Germany and France prioritize these for younger patients requiring future revision flexibility.
- All-Suture Anchors:High-strength polyethylene braid configurations preserve bone stock.
- Hybrid Anchors:Composite designs combining metallic insertion strength with resorbable fixation elements.
The dominant share belongs to Metallic Anchors, while Biodegradable Anchors is closing the gap fastest.
Application Area:
Procedure volumes scale with aging demographics and sports participation rates across developed economies.
- Shoulder Repair:Bankart and SLAP lesion procedures drive anchor consumption in glenohumeral instability cases. US academic medical centers now specify all-suture configurations for 40% of these interventions.
- Rotator Cuff:Full-thickness tear repairs require multiple anchors per procedure. Japanese orthopedic clinics favor titanium constructs given PMDA biocompatibility testing burdens on newer materials.
- Knee Stabilization:ACL and collateral ligament reconstructions.
- Sports Injuries:Acute trauma applications in professional and amateur athletics.
- Tendon Repair:Achilles and patellar tendon reattachments.
Rotator Cuff procedures anchor volume concentration, though Shoulder Repair applications are expanding most quickly through arthroscopic technique diffusion.
End User:
Procurement authority is consolidating among integrated delivery networks negotiating multi-year supply agreements.
- Ambulatory Surgical Centers:Same-day discharge protocols in the United States compress instrument turnover requirements. These facilities prioritize knotless anchor systems reducing operative time and technical skill dependencies.
- Orthopedic Clinics:Private practice settings in India and Brazil drive imported anchor demand as domestic manufacturing capacity lags.
- Sports Medicine Units:Hospital-based specialized centers.
- Specialty Hospitals:High-volume orthopedic centers with dedicated arthroscopy suites.
Ambulatory Surgical Centers capture the steepest expansion trajectory, while Orthopedic Clinics retain substantial procedure share in emerging markets.
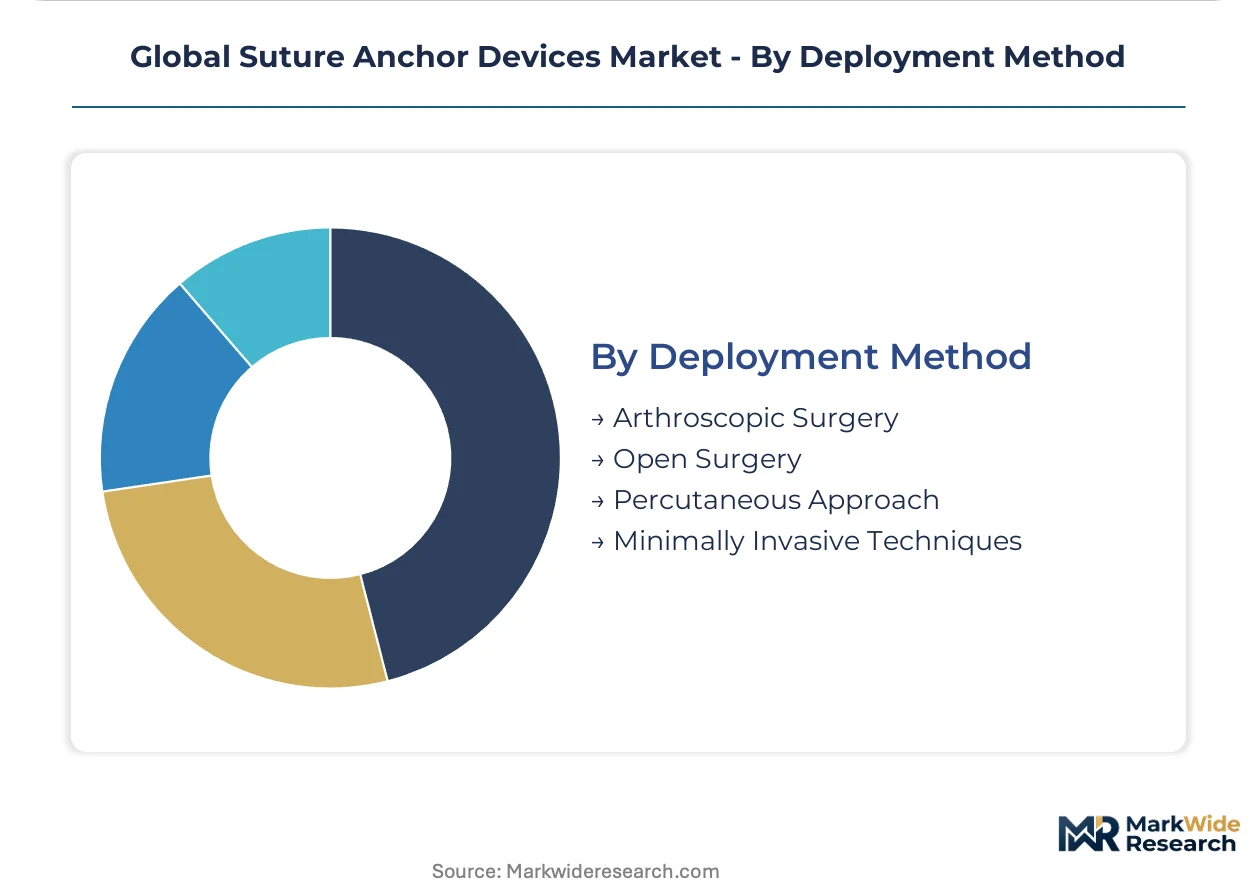
Deployment Method:
Instrument platform standardization determines anchor interchangeability and supplier lock-in effects.
- Arthroscopic Surgery:Cannulated delivery through small portals dominates shoulder and knee applications. EU MDR Class III requirements extend commercialization timelines for instruments and implants bundled in procedural kits.
- Minimally Invasive Techniques:Percutaneous and mini-open approaches reduce soft tissue disruption. South Korean MFDS fast-track designations accelerate biodegradable anchor approvals for these procedures.
- Open Surgery:Traditional approaches for complex revision cases.
- Percutaneous Approach:Needle-based anchor delivery systems.
Arthroscopic Surgery maintains the largest addressable base, with Minimally Invasive Techniques gaining share fastest through technique training program expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reimbursement incentives for outpatient arthroscopic procedures are redistributing suture anchor demand toward ambulatory settings in mature markets while regulatory pathway differentiation shapes competitive entry across jurisdictions.
United States
Site-of-service payment differentials from CMS favor same-day rotator cuff repairs at ambulatory surgical centers over hospital-based settings. FDA 510(k) clearance pathways compress product development timelines for incremental anchor designs. Naples, Florida hosts concentrated product development operations serving the all-suture anchor segment.
Germany
Sports medicine units in university hospitals prioritize biodegradable polymer formulations for younger patient cohorts requiring revision flexibility. EU MDR Class III implant requirements extend clinical evaluation timelines versus predecessor directives. Manufacturing clusters in the Sheffield region of the United Kingdom supply titanium alloy feedstock to German orthopedic implant fabricators.
Japan
PMDA biocompatibility testing protocols for absorbable polymers delay product launches by 18-24 months versus FDA pathways, filtering smaller manufacturers from procurement channels. Aging demographics expand rotator cuff procedure volumes in Tokyo and Osaka metropolitan areas. Japanese orthopedic clinics favor titanium constructs given regulatory familiarity with metallic implant histories.
South Korea
MFDS fast-track designations for biodegradable orthopedic devices offer first-mover positioning in East Asian sports medicine procurement. Percutaneous and mini-open surgical approaches gain share through technique training program expansion. Seoul-based hospital chains negotiate multi-year supply agreements locking preferred anchor configurations.
India
Emerging private hospital chains in Mumbai and Delhi seek imported anchor supply as domestic manufacturing capacity lags demand. CDSCO orthopedic implant registration requirements shape market entry strategies for multinational suppliers. Orthopedic clinics in major metros drive procedure volume growth through expanding arthroscopy suite investments.
Global Suture Anchor Devices Market Competitive Landscape
Player mix skews toward diversified orthopedic conglomerates with captive trauma and sports medicine portfolios. Market structure concentrates volume among manufacturers with vertically integrated titanium production and established 510(k) predicate device libraries. Three archetypes dominate: metallic anchor specialists with Sheffield or Warsaw manufacturing footprints, biodegradable polymer innovators with EU MDR certification capabilities, and all-suture anchor pure-plays with simplified surgical technique value propositions. Competitive moves center on knotless configuration patent filings and ambulatory surgical center supply contract consolidation.
Within the diversified orthopedic conglomerate tier, Smith & Nephew plc and Zimmer Biomet Holdings occupy positions anchored by European manufacturing infrastructure and established regulatory filing histories. Arthrex, Inc exemplifies the pure-play specialist archetype, representing concentrated exposure to the all-suture anchor technology vector. These three entities collectively illustrate the strategic segmentation between scale-driven diversified portfolios and focused innovation bets on bone-preserving fixation alternatives.
| Leading Market Players |
|---|
| Smith & Nephew plc |
| Zimmer Biomet Holdings |
| CONMED Corporation |
| Arthrex, Inc |
| Johnson and Johnson (DePuy Synthes, Inc.) |
| Stryker Corporation |
| Parcus Medical |
| Medtronic |
| Enovis Corporation |
| Others |
Supply & Pricing Matrix
Biodegradable polymer substitution for titanium alloys is simultaneously relocating manufacturing gravity toward polymer compounding hubs in Germany and the United States while compressing price premiums previously commanded by metallic construct durability. Sports medicine procurement committees now negotiate anchor supply on degradation-rate predictability rather than raw material pedigree, flattening historical pricing stratification between permanent and resorbable implant categories.
Pricing Analysis
Certification level creates the primary spread across the anchor market, with FDA 510(k)-cleared and EU MDR Class III-certified products commanding substantial premiums over uncertified alternatives. Pricing stratifies across premium knotless configurations, standard screw-type metallic anchors, and economy-tier conventional designs, with ambulatory surgical centers showing highest price sensitivity due to bundled reimbursement constraints. Cost compression in the metallic anchor tier is intensifying as polylactic acid composites capture shoulder repair volume, while orthopedic clinics in emerging markets remain least sensitive to price when sourcing imported inventory for complex revision cases.
Supply Chain Analysis
Strategic stockpiling of titanium alloy feedstock persists among Sheffield and Warsaw manufacturing clusters despite just-in-time preferences for biodegradable polymer resins. Raw material sourcing draws from specialty chemical producers in Germany, precision titanium processors in the United Kingdom, and high-strength polyethylene braid manufacturers in the United States. Single-source vulnerability concentrates in Sheffield-based titanium forging capacity, with distribution running through hospital purchasing consortia and integrated delivery network procurement offices rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Instrument service contract penetration is expanding faster than standalone anchor hardware sales, creating recurring revenue pools that now exceed implant replacement cycles in customer lifetime value calculations.
For Market Incumbents: Compound defensive positioning through backward integration into polylactic acid compounding capacity and captive control over knotless suture configuration patents. All-suture anchor pure-plays threaten metallic anchor margins in academic medical center procurement, making FDA predicate device library depth the critical lever for incremental product velocity. For New Entrants and Emerging Players: Anchor in India's CDSCO registration pathway for private hospital chains in Mumbai and Delhi where domestic manufacturing capacity lags demand. The biodegradable anchor segment offers the most penetrable white space, with South Korea's MFDS fast-track designation providing the optimal go-to-market angle for East Asian sports medicine procurement. For Investors and Strategic Acquirers: The market sits at a substitution-acceleration phase that favors manufacturers with EU MDR certification capabilities and established biodegradable polymer portfolios. Long-term viability hinges on regulatory filing infrastructure rather than manufacturing scale alone, with acquisition targets clustering among mid-scale specialists holding ISO 13485 certifications under fifteen-month validation cycles. The signal to watch is PMDA biocompatibility testing timeline compression for absorbable polymers, which would unlock Japanese procurement channels currently filtered toward metallic constructs.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Class III Certification Investment | Extended clinical evaluation requirements filter marginal competitors from European procurement channels. |
| Biodegradable Polymer Compounding Capacity | Degradation rate predictability improvements enable polylactic acid anchors to capture shoulder repair volume. |
| Knotless Suture Configuration Patent Filing | Radiofrequency welding integration eliminates traditional knot-tying skill dependencies in arthroscopic procedures. |
| Ambulatory Surgical Center Supply Contract | Multi-year agreements with ASC chains lock preferred anchor configurations through volume commitments. |
| MFDS Fast-Track Designation Pursuit | Abbreviated South Korean review pathways offer first-mover positioning in East Asian sports medicine procurement. |
Research Methodology
Operator-level perspectives from orthopedic surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers anchored the qualitative base for this analysis. Primary interview findings triangulated against FDA 510(k) filings, EU MDR clinical evaluation reports, hospital procurement databases, and CMS Medicare reimbursement data. Secondary validation drew from customs records of titanium alloy feedstock movements and arthroscopic instrument service contract disclosures. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis converged through iterative reconciliation.
Sensitivity analysis tested forecast outputs across alternative scenarios for EU MDR implementation pace and ambulatory surgical center expansion velocity. The analytical framework modeled segmentation across material type, application area, end-user setting, and deployment method throughout the projection horizon. CAGRs derived from procedure volume growth curves adjusted for site-of-service shift effects and product mix evolution toward biodegradable alternatives. Forecast inputs incorporated PMDA biocompatibility testing timeline assumptions and MFDS fast-track designation uptake rates.
Material uncertainties — regulatory pathway delays, alloy price volatility, and reimbursement threshold recalibration — sit outside the modeled envelope. Forecasts reflect assumptions about ISO 13485 certification cycle compression and arthroscopic instrument platform standardization progress. Revision becomes warranted when EU MDR Class III clinical evaluation timelines diverge materially from baseline assumptions or when biodegradable anchor degradation rates demonstrate unpredictability in long-term follow-up studies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Netherlands Artificial Organs and Bionic Implants Market
Medical Devices
Multi-Channel Infusion Pumps Market
Medical Devices
Endoscope Reprocessing Device Market
Medical Devices
Flexible Spinal Implants Market
Medical Devices
United States Stair Lift Market
Medical Devices
C-Arms Devices Market
Medical Devices
Oxygen Concentrators Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
Global Artificial Skin Market
Medical Devices
Global Extracorporeal CO2 Removal Devices Market
Medical Devices
Radial Head Resection Implant Market
Medical Devices
Phoropters Market
Medical Devices
Germany Aesthetic Devices Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Urethral Bulking System Market
Medical Devices
IV Poles Market