
 Military Training Aircraft Market | 2026-2036
Military Training Aircraft Market Size, Share, and Industry Trends Forecast 2026-2036
Military Training Aircraft Market Outlook
South Korea is tilting regional supply dynamics through Korea Aerospace Industries' T-50 trainer family production expansion. Boeing sustains technology leadership through integrated ground-based training systems linked to its aircraft platforms. Hindustan Aeronautics Limited anchors indigenous supply with its HTT-40 basic trainer program for the Indian Air Force. Leonardo competes in the advanced jet segment with its M-346 Master platform serving European and Middle Eastern operators.
Military training aircraft are fixed-wing platforms designed to develop pilot competencies across basic, advanced, and tactical instruction phases, typically incorporating dual controls, ejection seats, and aerodynamic configurations forgiving to novice aviators. Their primary purpose is to bridge ab initio flight instruction and frontline combat aircraft operation while minimizing attrition costs. Advanced trainer and jet trainer categories command premium positioning as air forces prioritize platforms capable of replicating fourth- and fifth-generation fighter handling characteristics. Simulator-based and hybrid systems segments accelerate as defense budgets seek to reduce per-hour live flight costs without compromising certification standards.
Defense procurement standards set by NATO's Air Force Armaments Group shape cross-border interoperability requirements for trainer platforms and associated simulators. The FAA and EASA certification frameworks for military derivative aircraft influence design specifications even where formal civil type certificates are not pursued. National offset policies and local content mandates in countries including India, South Korea, and Turkey redirect contract awards toward domestic assembly or technology transfer arrangements. Stakeholders must monitor how live-versus-synthetic training hour ratios evolve under each major air force's revised syllabus standards.
Market Dynamics
Live-pilot certification mandates under NATO's evolving training standards are compressing simulator substitution timelines while sustaining demand for actual flight hours, creating a bifurcated procurement environment where air forces balance cost reduction against regulatory compliance.
Growth Catalysts
- Fleet modernization programs:Southeast Asian air forces are expanding pilot training infrastructure to support fighter procurement pipelines, directly lifting trainer aircraft orders across basic and advanced categories.
- Indigenous capability mandates:India's PLI scheme and domestic content requirements are redirecting procurement toward local assembly, accelerating Hindustan Aeronautics Limited's HTT-40 production scale-up.
- Simulator-integrated live training:The FAA's military derivative certification framework is enabling hybrid syllabus designs that preserve live flight hour minimums while embedding synthetic training systems.
Market Restraints
- Turbofan engine supply concentration:Single-source dependencies on Honeywell and Rolls-Royce powerplants for advanced jet trainers create delivery timeline vulnerability and pricing leverage for suppliers.
- Extended airframe certification cycles:EASA's military derivative validation protocols add 18-24 months to platform entry-into-service, compressing fleet replacement windows for aging trainer inventories.
- Simulator fidelity substitution ceiling:Fifth-generation fighter sensor fusion and high-angle-of-attack handling characteristics exceed current synthetic environment replication limits, capping simulator penetration in advanced training phases.
Strategic Opportunities
- Underpenetrated African markets:Anglophone and Francophone air forces operate aging fleets with limited indigenous maintenance capability, creating openings for turnkey training system packages with embedded technical support.
- Converged live-virtual-constructive architectures:Integration of AI-generated adversary behaviors with physical aircraft and networked simulators enables force-level training scenarios previously requiring full squadron deployment.
- Offset-driven production localization:Turkey's national content requirements and technology transfer stipulations are compelling OEMs to establish final assembly lines and component sourcing within national borders.
Industry Challenges
- Experienced military test pilot scarcity:Platform development programs require cleared personnel with fourth-generation fighter backgrounds, creating recruitment bottlenecks that extend development timelines for new trainer variants.
- Legacy simulator integration complexity:Air forces operating mixed fleets of 1980s-era and modern training systems face interoperability gaps that demand costly middleware development for syllabus continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Military Training Aircraft Market |
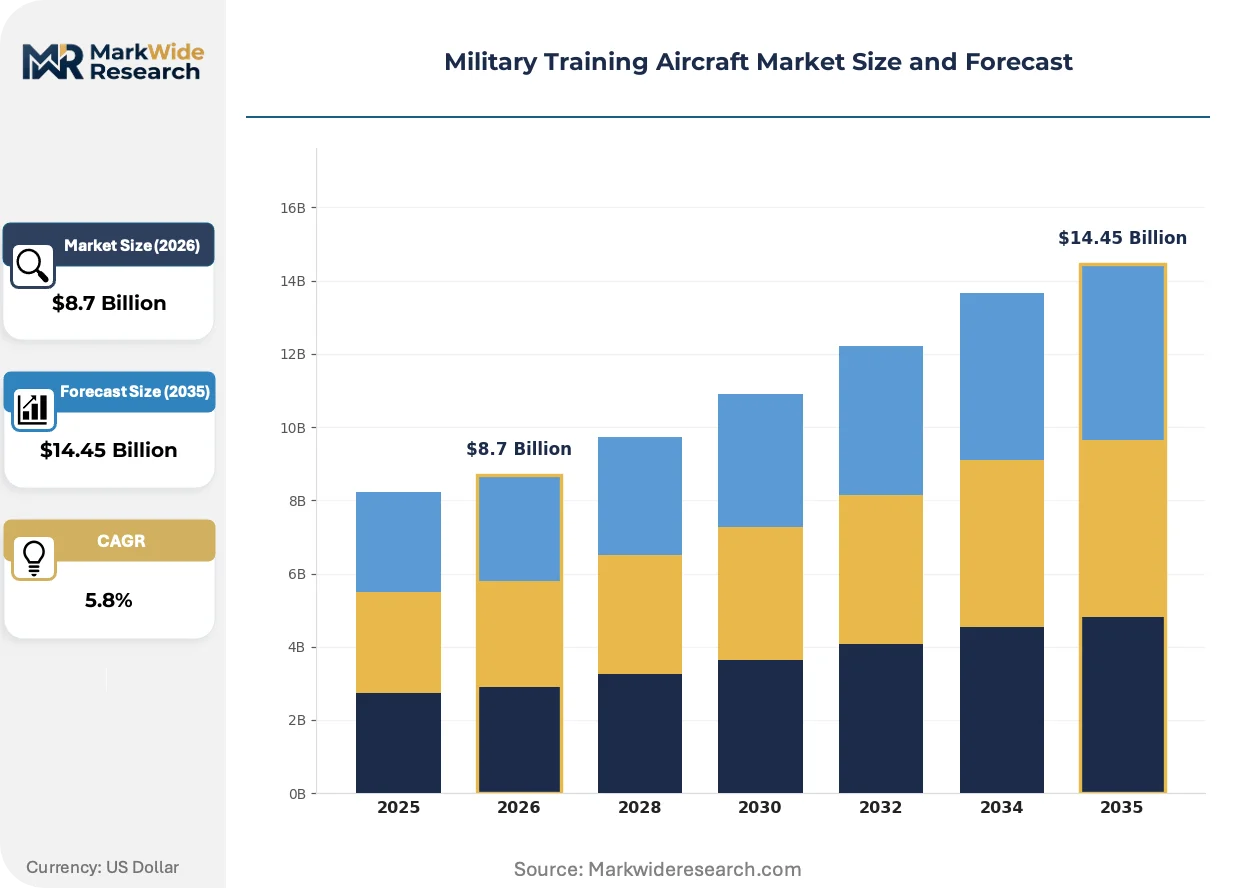
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Aircraft Type: Basic Trainer, Advanced Trainer, Jet Trainer, Multi-Role Trainer Technology: Simulator-Based, Live Training, Virtual Reality, Hybrid Systems End User: Government Agencies, Private Operators, Military Organizations, Training Schools Application: Initial Flight Training, Tactical Training, Instructor Training, Checkout Training |
| Companies Covered | Korea Aerospace Industries Ltd., Hindustan Aeronautics Limited, The Boeing Company, Bombardier Inc., Airbus SE, Leonardo S.p.A., Pilatus Aircraft Ltd., United Aircraft Building Corporation, Textron Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Military Training Aircraft Market Strategic Shifts
Training system architectures are converging toward networked environments where individual aircraft, simulators, and synthetic battle spaces operate as unified instructional ecosystems rather than discrete platforms.
Embedded sensor telemetry and edge computing hardware are digitizing real-time performance analytics delivery to instructors and students during live flight operations. The US Air Force's Pilot Training Next initiative is deploying these capabilities across its T-7A Red Hawk introduction. This digitizing of instructional feedback loops is compressing skill acquisition timelines and enabling competency-based progression rather than hour-based certification.
REACH registration requirements for military aircraft operating in European civil airspace are forcing design modifications to trainer platforms that share aerodromes with commercial traffic. Manufacturers must now incorporate emission monitoring and chemical substance disclosure into airframe development cycles. Advanced jet trainers with higher-thrust turbofan engines face disproportionate compliance burden, redirecting R&D expenditure toward exhaust treatment and materials substitution.
Air forces are unbundling training system procurement from aircraft acquisition, separating simulator purchases, maintenance contracts, and syllabus development into distinct competitive tenders. This fragmentation is displacing traditional prime contractor turnkey arrangements. The Royal Australian Air Force's Lead-in Fighter Training System restructuring exemplifies this pattern, with separate awards for aircraft, ground-based training, and sustainment services.
Military Training Aircraft Market Segmentation
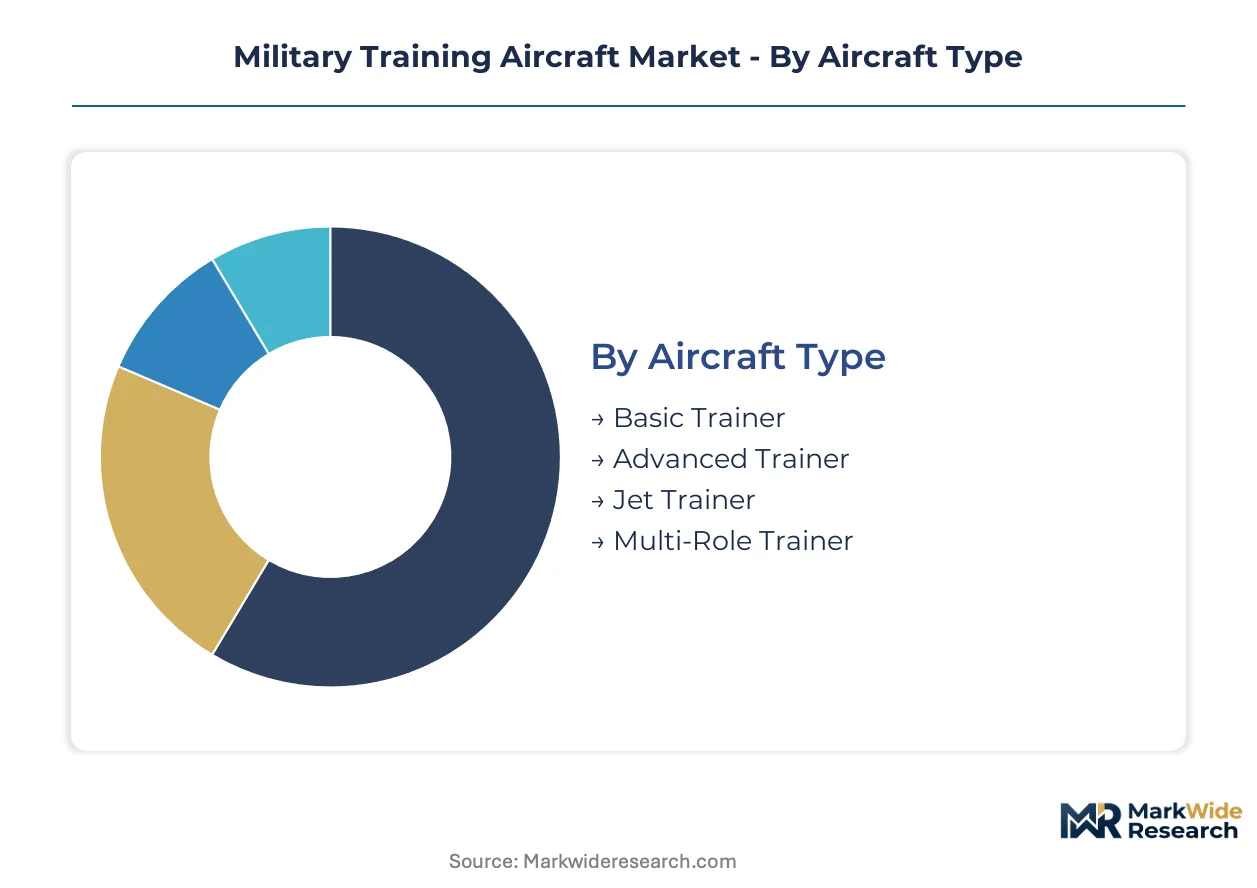
Military training aircraft procurement patterns diverge sharply across platform categories, with sustainment contracts and simulator integration driving lifetime value calculations more than airframe unit costs alone. Understanding these segment boundaries clarifies why some OEMs prioritize avionics packages over airframe innovation.
Aircraft Type:
After-sales-service intensity peaks in advanced jet categories where engine overhaul intervals and avionics refresh cycles compress maintenance revenue recognition timelines.
- Basic Trainer:Piston-engine or turboprop platforms with forgiving stall characteristics and simplified cockpit layouts serve ab initio instruction. India's HTT-40 procurement under indigenous capability mandates concentrates demand in this tier, with HAL anchoring regional supply through domestic assembly lines.
- Advanced Trainer:High-subsonic jet platforms replicate fourth-generation fighter handling for lead-in fighter training. South Korea's T-50 family production expansion captures regional orders from air forces modernizing pilot pipelines ahead of F-35 or KF-21 fleet inductions.
- Jet Trainer:Supersonic-capable platforms with integrated sensor suites bridge to frontline combat aircraft. Demand clusters in European and Middle Eastern operators seeking NATO interoperability certification.
- Multi-Role Trainer:Combat-capable derivatives with weapons carriage and tactical systems support operational conversion. Turkey's national content requirements redirect procurement toward domestic final assembly with technology transfer stipulations.
Advanced Trainer holds the largest share; momentum sits with Multi-Role Trainer as operational conversion cost pressures intensify.
Technology:
Cost tier stratification separates premium integrated ecosystems from discrete simulator purchases, with hybrid architectures commanding pricing premiums.
- Simulator-Based:High-fidelity synthetic environments replicate cockpit procedures and emergency scenarios without airframe wear. FAA military derivative certification frameworks enable these systems to substitute for live hours within defined syllabus ratios.
- Live Training:Actual flight hours in dedicated trainer airframes remain mandatory for pilot certification under evolving NATO standards. Live-pilot certification requirements sustain demand despite per-hour cost premiums over synthetic alternatives.
- Virtual Reality:Immersive head-mounted displays and motion platforms deliver procedural training at reduced infrastructure footprint. The US Air Force's Pilot Training Next initiative deploys these capabilities for competency-based progression.
- Hybrid Systems:Networked architectures integrating physical aircraft, simulators, and AI-generated adversary behaviors enable force-level training scenarios. Royal Australian Air Force restructuring unbundles these procurements from aircraft acquisition into distinct competitive tenders.
Live Training commands installed base volume; Hybrid Systems are climbing the fastest as air forces seek to reduce per-hour costs without compromising certification standards.
End User:
Customer type determines procurement route, with government tenders subject to offset negotiations and private operators prioritizing operational flexibility.
- Government Agencies:National air forces and defense ministries operating under civil service procurement rules. India's PLI scheme redirects awards toward domestic assembly with local content mandates.
- Private Operators:Contracted training providers delivering pilot instruction as outsourced service. These entities prioritize fleet standardization and simulator-to-live ratios that minimize capital deployment.
- Military Organizations:Unified combatant commands with organic training wings. NATO's Air Force Armaments Group standards shape cross-border interoperability requirements for these operators.
- Training Schools:Dedicated military aviation academies with syllabus development autonomy. REACH registration requirements for European civil airspace access force design modifications to shared-aerodrome operations.
Military Organizations dominate procurement volume; Training Schools are gaining share fastest as competency-based certification models proliferate.
Application:
Application focus determines platform specification, with tactical training demanding sensor replication that basic instruction does not require.
- Initial Flight Training:Ab initio instruction covering basic aircraft handling, navigation, and emergency procedures. Southeast Asian air force expansion drives fleet procurement for this entry segment.
- Tactical Training:Air-to-air and air-to-ground mission rehearsal with representative threat environments. Fifth-generation fighter sensor fusion characteristics exceed current synthetic environment replication limits.
- Instructor Training:Qualification programs for pilot instructors requiring dual-control proficiency and pedagogical certification. Experienced military test pilot scarcity creates recruitment bottlenecks for platform development supporting this segment.
- Checkout Training:Type conversion and currency maintenance for qualified pilots transitioning between aircraft families. EASA military derivative validation protocols add certification timeline burden for new platform entry.
Initial Flight Training represents the deepest installed base; Tactical Training shows steepest expansion trajectory as fighter fleet modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Airframe assembly and propulsion integration concentrate in defense-industrial clusters across five nations, with each jurisdiction applying distinct certification and offset frameworks that reshape contract award patterns.
United States
The US Air Force's T-7A Red Hawk program and Pilot Training Next initiative drive advanced trainer demand. FAA military derivative certification protocols enable hybrid live-synthetic syllabus designs. Seattle and St. Louis host Boeing's integrated training system development, linking ground-based simulators to aircraft platforms.
South Korea
Korea Aerospace Industries scales T-50 family production to capture regional orders from air forces modernizing ahead of F-35 inductions. MFDS certification alignment supports export qualification to Southeast Asian operators. Sacheon anchors final assembly and flight test operations for the trainer family.
India
The Indian Air Force's HTT-40 procurement accelerates under PLI scheme domestic content mandates. DGFT offset policies redirect contract awards toward HAL's Bangalore and Nasik facilities. Indigenous capability requirements compress import dependency for basic trainer categories.
Italy
Leonardo's M-346 Master production serves European and Middle Eastern operators seeking NATO interoperability certification. EASA military derivative validation protocols extend platform entry timelines by 18-24 months. Veneto region assembly lines integrate advanced avionics for lead-in fighter training.
United Kingdom
The Royal Air Force's procurement unbundles training systems from aircraft acquisition into distinct competitive tenders. UK Defence and Security Industrial Strategy prioritizes sovereign capability in simulator-integrated architectures. BAE Systems and QinetiQ clusters in Lancashire and Wiltshire develop networked synthetic environments.
Military Training Aircraft Market Competitive Environment
State-affiliated aerospace conglomerates and diversified defense primes split the market between indigenous capability mandates and cross-border turnkey supply. Consolidation pressure intensifies as air forces unbundle procurement packages. Two archetypes dominate: vertically integrated national champions serving domestic demand under offset rules, and export-oriented platforms seeking NATO interoperability certification. Capacity expansion and strategic partnerships constitute the primary competitive vectors.
Within the state-affiliated tier, Korea Aerospace Industries and Hindustan Aeronautics Limited exemplify national champion positioning. Korea Aerospace Industries anchors regional supply from South Korean production bases. Hindustan Aeronautics Limited occupies a position shaped by India's PLI scheme and domestic assembly requirements. Leonardo S.p.A. represents the European prime archetype, competing across advanced jet segments with platforms serving interoperability-focused operators.
| Leading Market Players |
|---|
| Korea Aerospace Industries Ltd. |
| Hindustan Aeronautics Limited |
| The Boeing Company |
| Bombardier Inc. |
| Airbus SE |
| Leonardo S.p.A. |
| Pilatus Aircraft Ltd. |
| United Aircraft Building Corporation |
| Textron Inc. |
| Others |
Value Chain & Pricing Dynamics
The Incheon-to-Singapore air freight corridor channels turbine engine and avionics components from South Korean assembly lines to Southeast Asian operator bases, with fuel surcharge volatility compressing margins on basic trainer deliveries while amplifying price premiums for advanced jet platforms with embedded simulator integration.
Pricing Analysis
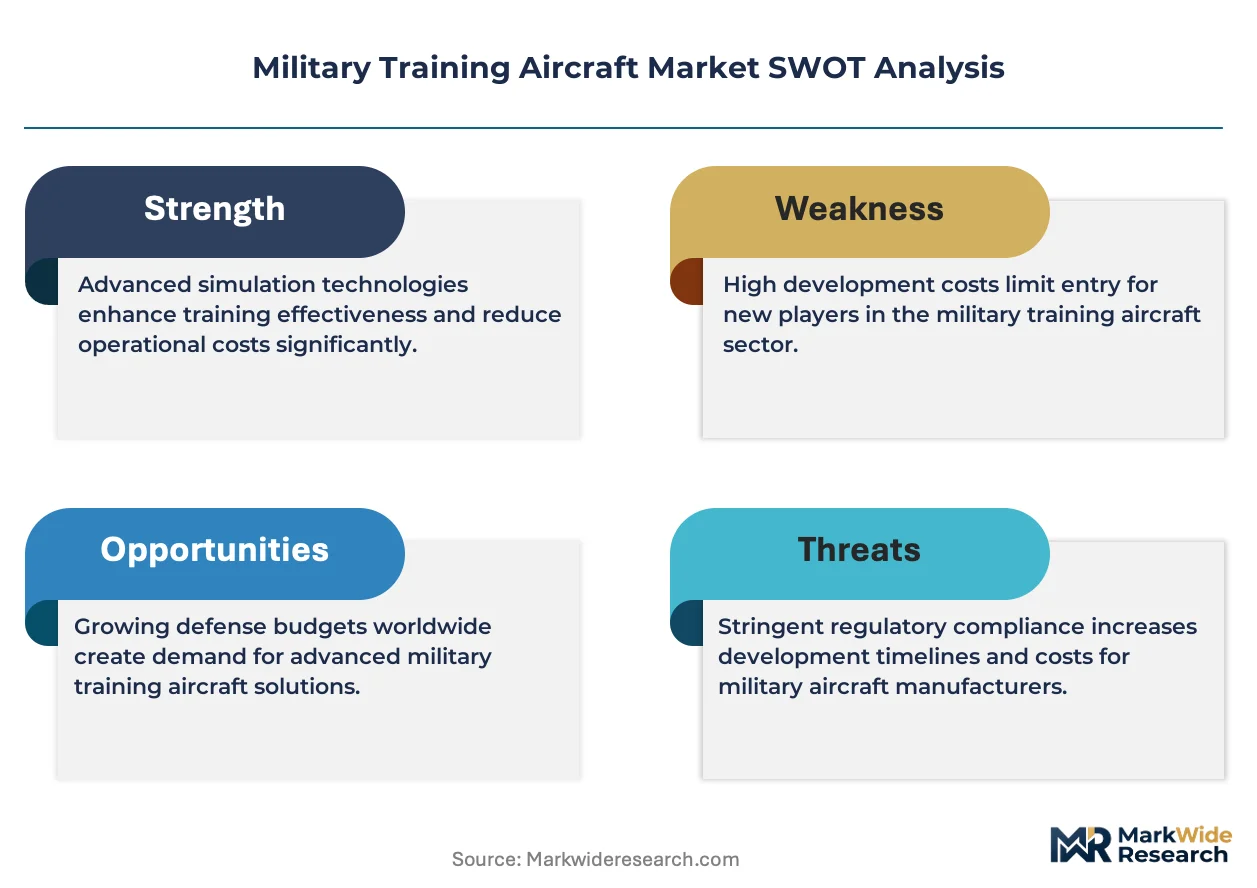
FAA military derivative certification protocols dictate the pricing tier structure across the Military Training Aircraft Market, separating premium integrated training ecosystems from discrete platform sales. Three-tier pricing structure across premium, standard, and economy levels stratifies by avionics complexity and after-sales bundling intensity. Cost compression in the basic trainer segment is intensifying because indigenous capability mandates in India and Turkey redirect procurement toward domestic assembly with technology transfer stipulations. Government agencies under civil service procurement rules exhibit highest price sensitivity, while private operators prioritize operational flexibility over unit cost minimization.
Supply Chain Analysis
Tariff exposure between the United States and European Union dominates supply chain risk calculus for advanced jet trainer programs dependent on cross-border avionics and engine component flows. Manufacturing gravity centers on South Korea, India, and Italy for final assembly, with propulsion systems drawing from Honeywell and Rolls-Royce production facilities in the United States and United Kingdom. Single-source dependencies on turbofan engine suppliers create delivery timeline vulnerability and pricing leverage concentration. Distribution runs through defense ministry procurement channels with offset negotiation layers, compressing direct OEM-to-operator contracting.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Military Training Aircraft Market is reshaping around converged live-virtual-constructive architectures, with the US Air Force's Pilot Training Next initiative establishing the regulatory and technological inflection point for competency-based certification models.
For Market Incumbents: Harden simulator-to-aircraft integration capabilities against unbundled procurement trends fragmenting traditional turnkey contracts. Lock in long-term sustainment revenue through embedded telemetry and edge computing hardware that digitizes real-time performance analytics. Anchor production capacity in jurisdictions with active indigenous capability mandates to capture offset-driven contract flow.
For New Entrants and Emerging Players: Establish a beachhead in the African basic trainer segment where aging fleets and limited indigenous maintenance capability create openings for turnkey training system packages. Target Anglophone and Francophone air forces with embedded technical support offerings that incumbent primes have underinvested in. Pursue partnerships with established engine suppliers to circumvent single-source certification bottlenecks.
For Investors and Strategic Acquirers: Simulator-integrated mid-tier specialists with FAA military derivative certification pathways represent the optimal acquisition target archetype for exposure to hybrid training system growth. Long-term viability hinges on positioning against the live-versus-synthetic training hour ratio evolution under revised NATO syllabus standards. Watch for EASA validation protocol streamlining as the signal indicating accelerated platform entry timelines and compressed fleet replacement windows.
| Strategic Initiative | Industry Significance |
|---|---|
| Simulator-Aircraft Integration Investment | Captures unbundled procurement flow as air forces separate training system from platform acquisition. |
| Indigenous Assembly Line Establishment | Qualifies for India's PLI scheme and Turkey's national content requirements redirecting contract awards. |
| FAA Military Derivative Certification Pathway | Enables hybrid live-synthetic syllabus designs preserving live flight hour minimums. |
| Turnkey Training System Packaging | Addresses African operator maintenance capability gaps with embedded technical support. |
| AI-Generated Adversary Behavior Development | Powers converged live-virtual-constructive architectures for force-level training scenarios. |
Study Parameters
The analysis maps basic trainer, advanced trainer, jet trainer, and multi-role trainer segments, each validated through procurement officers at national air forces, program managers at defense ministries, simulator integration specialists, and aftermarket service directors. Primary interviews with these stakeholders combined with secondary validation against FAA certification filings, EASA military derivative validation protocols, NATO Air Force Armaments Group standards, and national offset policy documentation. Bottom-up platform delivery tracking and top-down defense budget allocation analysis triangulate volume and value estimates.
Fixed assumptions across the projection horizon include sustained NATO live-pilot certification requirements, continued indigenous capability mandate enforcement in India and Turkey, and stable turbofan engine supplier market structure. Variable conditions tested include EASA validation timeline compression, simulator fidelity substitution ceiling breakthroughs for fifth-generation fighter characteristics, and African market penetration acceleration. Segmentation dimensions modeled encompass aircraft type, technology architecture, end user procurement route, and application phase. CAGRs derive from fleet replacement cycle analysis, pilot pipeline expansion rates, and per-hour cost reduction trajectories.
Stress conditions across fuel surcharge volatility, engine supplier consolidation, and REACH registration requirement expansion were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these documented assumptions with acknowledged sensitivity to regulatory protocol evolution and defense budget reallocation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Simulation and Training
Asia-Pacific Civil Aviation Simulators Market
Simulation and Training
Global Ship Bridge Simulators Market
Simulation and Training
Dynamic Flight Training Compartments Market
Simulation and Training
RADAR Simulator Market
Simulation and Training
Simulators Market
Simulation and Training
Civil Aerospace Simulation and Training Market
Simulation and Training
Air Traffic Control Simulator and Training Market
Simulation and Training
GNSS Simulators Market
Simulation and Training
Military Simulation Virtual Training Market
Simulation and Training
Flight Simulator Market
Simulation and Training
Europe Flight Training and Simulation Market
Simulation and Training
Live Laser-Based Training and Simulation Platforms Market
Simulation and Training
Middle East Civil Aviation Flight Training and Simulation Market
Simulation and Training
Helicopter Simulator Market
Simulation and Training
UAV Flight Training and Simulation Market
Simulation and Training
Military Aerospace Simulation and Training Market