
 Continuous Track Wheels Market | 2026-2036
Continuous Track Wheels Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Track Wheels Market Analysis
Aftermarket telematics and predictive maintenance subscriptions is consolidating how fleet operators procure continuous track wheels, shifting transactions from spot replacement to lifecycle service contracts. Titan International leverages its North American distribution network to anchor long-term service agreements with agricultural OEMs. Camso Inc. specializes in rubber-to-steel bonding technologies that differentiate its aftermarket track solutions from commodity competitors. Kalyani Strategic Systems Limited dominates military-grade track wheel supply for armored vehicle programs across South Asia.
Continuous track wheels are ground-engaging drive components comprising interlocking track segments, internal drive sprockets, and rubber or elastomeric bushings designed to distribute vehicle weight across soft or uneven terrain. Steel-reinforced rubber tracks typically operate at ground pressures below 15 psi, enabling flotation across marshy agricultural fields and loose mining overburden. Rubber tracks command the largest installed base in agriculture due to soil preservation mandates, while composite tracks represent the fastest-growing material category as carbon-fiber-reinforced compounds reduce unsprung mass. Mining applications concentrate the highest per-unit margin pools because extreme abrasion environments demand premium metallurgy and specialized polyurethane formulations.
The EPA enforces Tier 4 Final emissions limits that compel construction and agriculture OEMs to reduce machine weight, directly stimulating demand for lighter track wheel assemblies. ISO 3450 and SAE J1269 establish braking and dimensional standards that govern cross-border component interchangeability. REACH compliance in Europe restricts certain rubber plasticizers, forcing reformulation of track pad compounds. Stakeholders must monitor how evolving emissions thresholds and material restrictions reshape supplier qualification requirements and aftermarket parts compatibility across regulated jurisdictions.
Market Dynamics
Precision agriculture OEMs are consolidating procurement around lifecycle service contracts, compressing spot replacement volumes and elevating supplier qualification barriers for continuous track wheel manufacturers.
Growth Catalysts
- EPA Tier 4 Final emissions mandates:OEMs redesign undercarriage systems to reduce machine weight, directly stimulating demand for carbon-fiber-reinforced composite track assemblies in North American construction and agriculture equipment.
- GPS-guided tractor proliferation:Autonomous planting and harvesting systems require specialized rubber track geometries that minimize soil compaction while maintaining sub-inch positioning accuracy across variable terrain.
- Mining overburden intensity in Australia:Iron ore and coal operators in Western Australia and Queensland are compressing replacement cycles for polyurethane-bushed track systems due to abrasive silica content in surface deposits.
Market Restraints
- Steel price volatility:Reinforced track core manufacturing faces margin pressure from fluctuating hot-rolled steel coil costs, forcing OEMs to absorb input spikes or pass through to concentrated buyer bases.
- REACH rubber plasticizer restrictions:European compounders must reformulate track pad elastomers to eliminate restricted phthalates, extending R&D timelines and qualifying costs for EU market access.
- Interchangeability standard gaps:Incomplete adoption of ISO 3450 braking performance standards across Brazilian and Russian equipment fleets fragments aftermarket parts compatibility and traps inventory.
Strategic Opportunities
- Predictive maintenance platform integration:Telematics-enabled wear monitoring allows suppliers to convert transactional part sales into recurring revenue streams tied to guaranteed uptime contracts.
- Carbon-fiber composite track penetration:Unsprung mass reduction targets in high-horsepower agriculture tractors create opening for advanced material suppliers to displace conventional steel-reinforced rubber in premium segments.
- India defense modernization programs:Armored vehicle fleet upgrades under indigenous procurement mandates generate captive demand for military-grade track wheel assemblies with classified load-bearing specifications.
Industry Challenges
- Rubber-to-steel bonding technician scarcity:Specialized vulcanization expertise required for track segment manufacturing concentrates in legacy industrial regions, constraining capacity expansion for emerging market suppliers.
- Multi-jurisdiction certification complexity:Simultaneous EPA, REACH, and BIS compliance for global OEM supply contracts extends product validation timelines and fragments testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Track Wheels Market |
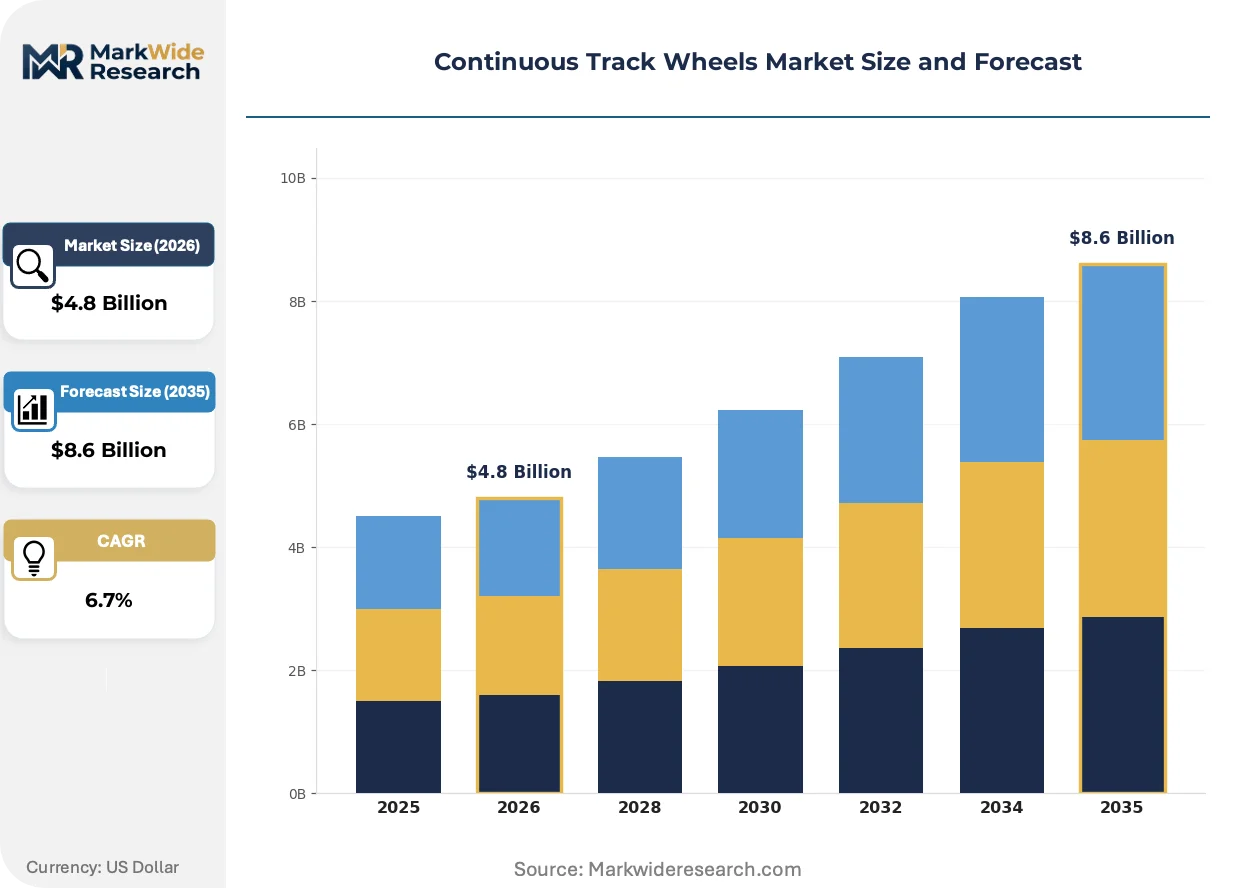
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Tracks, Steel Tracks, Composite Tracks, Hybrid Tracks Application: Agriculture, Construction, Mining, Forestry End User: OEMs, Distributors, Aftermarket Providers, Government Installation: On-Road, Off-Road, Industrial Sites, Military Applications |
| Companies Covered | TGL SP Industries Ltd., Titan International, Hamilton Caster & Mfg. Co., Van Halteren, Maxion Wheels, Kalyani Strategic Systems Limited, Hutchinson Industries, Inc., William Cook Holdings Limited, Camso Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Track Wheels Market Emerging Trajectories
Material science convergence with digital monitoring systems is redefining how continuous track wheels are specified, priced, and maintained across agriculture and mining equipment fleets.
Carbon-fiber-reinforced thermoplastic track segments are unifying structural load-bearing functions with embedded sensor channels for real-time wear telemetry. High-horsepower tractor OEMs in Germany and the United States are qualifying these assemblies for 2027 model year releases. This unification is compressing the traditional separation between mechanical component supply and telematics platform integration.
REACH compliance deadlines in the European Union are forcing rubber compounders to eliminate legacy plasticizers from track pad formulations. ECHA-registered alternatives require extended cure cycle validation, delaying new product introductions by 8-14 months. Mining equipment operators in Scandinavia are absorbing premium pricing for compliant assemblies to maintain fleet certification for EU project bidding.
Lifecycle service contracting is displacing spot procurement across North American agricultural OEM supply chains. Dealer networks now bundle track wheel replacement with predictive maintenance subscriptions, capturing margin that previously flowed to independent aftermarket distributors. This pattern is most pronounced in corn and soybean belt equipment fleets where downtime costs exceed part replacement economics.
Continuous Track Wheels Market Segmentation
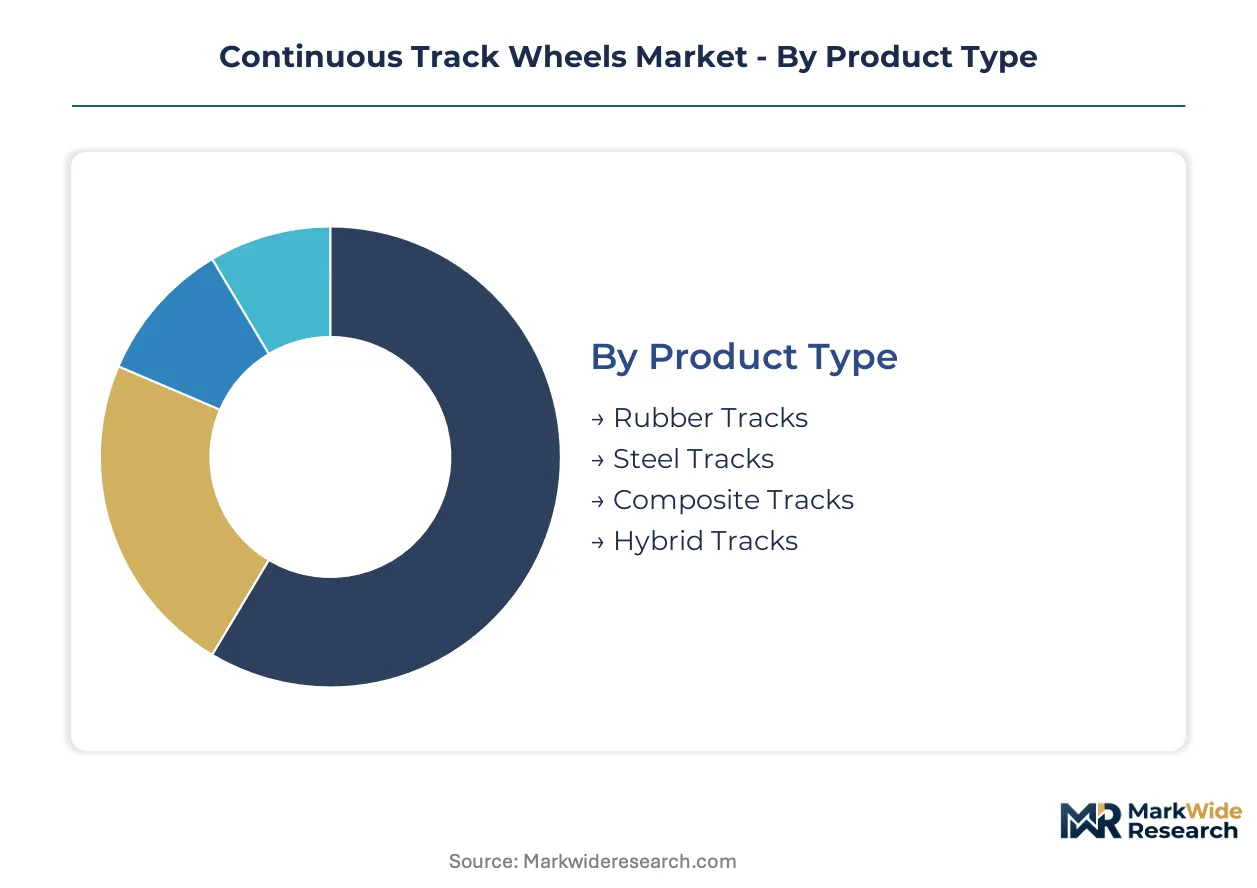
Continuous track wheel procurement patterns diverge sharply between high-volume agricultural replacement cycles and low-volume, specification-heavy mining installations. Segmentation reveals how material selection, distribution channel, and operating environment collectively determine margin structures and supplier qualification requirements.
Product Type:
Rubber tracks dominate installed base volumes while composite variants command premium positioning in weight-sensitive applications.
- Rubber Tracks:Steel-cord-reinforced elastomeric belts with internal drive lugs, operating at ground pressures below 15 psi for soil preservation compliance. Demand concentrates in Midwestern US corn and soybean operations where GPS-guided tractors require flotation across variable moisture conditions. EPA Tier 4 Final weight reduction mandates are pressuring OEMs to evaluate lighter alternatives despite rubber's cost advantage.
- Composite Tracks:Carbon-fiber-reinforced thermoplastic segments with embedded sensor channels for real-time wear telemetry. German and US high-horsepower tractor OEMs are qualifying these assemblies for upcoming model year releases, trading material cost for unsprung mass reduction and telematics integration.
- Steel Tracks:Cast link assemblies with hardened bushings and pins, specified for extreme abrasion environments where elastomeric compounds degrade rapidly.
- Hybrid Tracks:Multi-material constructions combining rubber ground pads with steel core structures, bridging durability and soil protection requirements.
Mature deployment sits with rubber tracks across established agricultural fleets. Newer deployment is concentrated in composite tracks where precision agriculture OEMs absorb premium pricing for weight and telemetry advantages.
Application:
Operating intensity and terrain abrasiveness determine replacement frequency and per-unit margin capture across end-use sectors.
- Agriculture:Soil compaction mandates in Brazil, Russia, and Australia drive specification of low-ground-pressure rubber track systems for large-scale grain operations. GPS-guided autonomous planting equipment requires specialized track geometries maintaining sub-inch positioning accuracy across undulating terrain.
- Mining:Iron ore and coal operations in Western Australia compress replacement cycles due to abrasive silica content in surface overburden. Polyurethane-bushed track systems command the highest per-unit margins as operators prioritize uptime over part cost in continuous extraction environments.
- Construction:EPA emissions compliance pressures OEMs toward lighter undercarriage assemblies in North American earthmoving equipment.
- Forestry:Steep slope harvesting in Nordic countries and Pacific Northwest demands specialized grouser patterns for traction on wet, uneven terrain.
Volume concentration favors agriculture replacement cycles. Margin concentration clusters in mining where downtime economics override procurement cost sensitivity.
End User:
Channel structure is bifurcating between consolidated OEM lifecycle contracts and fragmented independent aftermarket distribution.
- OEMs:Precision agriculture equipment manufacturers in Germany and the United States are consolidating procurement around guaranteed uptime agreements, compressing spot replacement volumes and elevating supplier qualification barriers for track wheel assemblies.
- Aftermarket Providers:Independent distributors face margin compression as dealer networks bundle track replacement with predictive maintenance subscriptions, capturing revenue previously flowing to non-captive channels.
- Distributors:Regional inventory positioning remains critical for emergency replacement in remote mining and agricultural locations.
- Government:Defense procurement in India generates captive demand for military-grade track wheel assemblies with classified load-bearing specifications under indigenous modernization mandates.
Procurement authority is concentrating with OEMs in agricultural supply chains. Aftermarket providers retain position in mining and government segments where specification complexity favors specialized technical support.
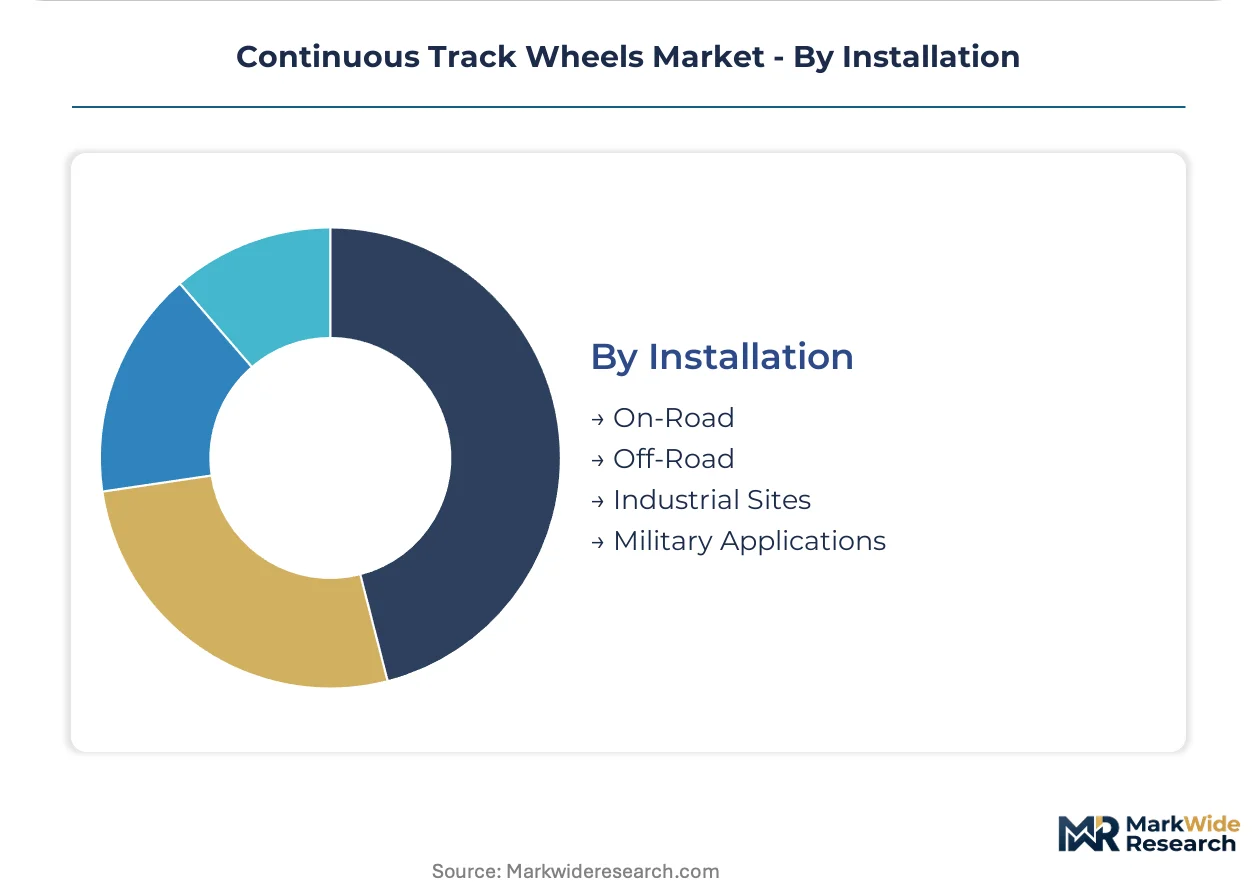
Installation:
Environmental exposure severity determines material specification and maintenance protocol differentiation.
- Off-Road:Unimproved terrain across Australian mining leases and Brazilian agricultural frontiers subjects track assemblies to impact loading, moisture ingress, and abrasive wear requiring reinforced construction.
- Military Applications:Armored vehicle programs in South Asia demand track systems validated for extreme temperature cycling, ballistic protection compatibility, and rapid field repairability.
- Industrial Sites:Confined quarry and processing environments impose dimensional constraints and contamination control requirements.
- On-Road:Limited applications in specialized transport equipment where rubber track systems reduce pavement damage during short-haul movements.
Specification maturity sits with off-road installations across commercial agriculture and mining. Military applications represent the most stringent qualification environment with classified performance requirements and extended validation timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peoria, Illinois anchors North American continuous track wheel demand through Caterpillar's engineering cluster and dense agricultural OEM procurement networks concentrated across the Midwest corn belt.
United States
EPA Tier 4 Final emissions standards compel construction and agriculture OEMs toward lighter track assemblies, stimulating demand for carbon-fiber-reinforced composites. The Department of Agriculture's precision agriculture grants accelerate GPS-guided tractor deployment across Iowa and Illinois. Peoria's engineering corridor concentrates R&D activity for next-generation undercarriage systems.
Germany
High-horsepower tractor manufacturers in Baden-Württemberg qualify carbon-fiber thermoplastic track segments for 2027 model releases, trading material cost for unsprung mass reduction. REACH compliance deadlines force rubber compounders to eliminate legacy plasticizers, extending validation timelines by 8-14 months. Stuttgart's automotive supplier ecosystem repurposes composite expertise for agricultural machinery applications.
Australia
Iron ore and coal operators in Western Australia compress replacement cycles for polyurethane-bushed track systems due to abrasive silica content in surface deposits. The country's mining safety regulator mandates uptime guarantees that elevate lifecycle service contracting over spot procurement. Perth's mining equipment cluster drives specification standards for extreme abrasion environments.
Brazil
Large-scale soybean and sugarcane operations in Mato Grosso and São Paulo states drive specification of low-ground-pressure rubber track systems for soil preservation compliance. ANVISA's agricultural equipment certification requirements create qualification barriers for imported assemblies. São Paulo's industrial corridor hosts regional distribution hubs serving South American replacement demand.
India
Defense modernization programs under indigenous procurement mandates generate captive demand for military-grade track wheel assemblies with classified load-bearing specifications. BIS certification requirements fragment aftermarket parts compatibility across state equipment fleets. Tamil Nadu's defense manufacturing cluster concentrates armored vehicle subsystem production for domestic and export programs.
Continuous Track Wheels Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a bifurcated structure where integrated foundry operations anchor premium mining segments while specialized compounders serve agricultural replacement cycles. The vendor base stratifies into three archetypes: steel-and-rubber bond specialists, composite material innovators, and defense-captive system integrators. Consolidation pressures concentrate in North American distribution networks as OEMs bundle lifecycle contracts. Geographic expansion and backward integration into rubber compounding represent dominant competitive vectors.
Among North American diversified manufacturers, Titan International occupies a position exemplifying scale-driven agricultural supply chain anchoring, while Camso Inc. represents rubber-to-steel bonding specialization. Kalyani Strategic Systems Limited sits within the defense-captive tier, anchoring military-grade supply for South Asian armored vehicle programs. These three entities illustrate how competitive positioning fragments across distinct qualification environments rather than converging on uniform product-market strategies.
| Leading Market Players |
|---|
| TGL SP Industries Ltd. |
| Titan International |
| Hamilton Caster & Mfg. Co. |
| Van Halteren |
| Maxion Wheels |
| Kalyani Strategic Systems Limited |
| Hutchinson Industries, Inc. |
| William Cook Holdings Limited |
| Camso Inc. |
| Others |
Supply Flow & Price Mechanics
Lifecycle service contracting by precision agriculture OEMs in Germany and the United States is compressing spot replacement volumes and forcing suppliers to absorb upfront certification costs, reshaping how margin pools distribute across transactional versus subscription-based revenue models.
Pricing Analysis
Margin tightening in standard-grade rubber tracks reflects hot-rolled steel coil volatility and REACH-driven reformulation costs. Three-tier pricing structure across premium composite, standard rubber, and economy remanufactured tiers separates telematics-integrated assemblies from commodity replacements. Cost compression accelerates in agricultural replacement cycles as dealer networks bundle predictive maintenance subscriptions. Mining operators show lowest price sensitivity, prioritizing polyurethane-bushed uptime guarantees over per-unit procurement economics.
Supply Chain Analysis
Rubber-to-steel bonding technician scarcity concentrates in legacy industrial regions of Germany and the United States, constraining capacity expansion for emerging market suppliers. Manufacturing gravity centers on India and China for steel-cord core production, with specialized vulcanization expertise anchored in North American and European industrial corridors. Raw material dependencies span carbon fiber feedstocks from Japan, specialized elastomer compounds from South Korea, and hardened steel alloys from domestic foundries. Single-source vulnerability sits with carbon-fiber thermoplastic precursor supply. Distribution runs through OEM captive networks in agriculture and specialized mining equipment dealers in Australia and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The continuous track wheels market is executing a material-science transition as carbon-fiber-reinforced thermoplastic segments displace conventional steel-reinforced rubber in high-horsepower precision agriculture applications, compressing the traditional separation between mechanical component supply and integrated telematics platforms.
For Market Incumbents: Extend rubber-to-steel bonding expertise into embedded sensor channel integration to defend against composite specialists capturing telematics-adjacent revenue. Secure backward integration into ECHA-registered plasticizer compounds to neutralize REACH compliance cost disadvantages against European compounders. Anchor long-term service agreements with Midwestern agricultural OEMs before dealer network consolidation completes. For New Entrants and Emerging Players: Capture replacement cycle compression in Australian mining operations by qualifying polyurethane-bushed assemblies for extreme silica abrasion environments. Target Brazilian soybean belt equipment fleets where ANVISA certification barriers trap incumbent inventory and create service gaps. Lead with predictive maintenance platform integration rather than commodity part pricing to bypass established distribution relationships. For Investors and Strategic Acquirers: Re-rating potential sits with defense-captive system integrators given India's indigenous armored vehicle procurement mandates and classified specification barriers to foreign competition. Long-term viability favors suppliers with demonstrated multi-jurisdiction certification capability spanning EPA, REACH, and BIS requirements. Watch for inflection in German OEM composite track qualification timelines as signal for material substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Fiber Composite Track Qualification | German and US tractor OEMs validate thermoplastic segments for 2027 model releases, trading material cost for unsprung mass reduction. |
| Predictive Maintenance Platform Integration | Telematics-enabled wear monitoring converts transactional part sales into recurring revenue streams tied to guaranteed uptime contracts. |
| REACH-Compliant Rubber Compound Reformulation | ECHA-registered plasticizer alternatives require extended cure cycle validation, delaying new product introductions by 8-14 months. |
| Lifecycle Service Contract Consolidation | Dealer networks bundle track wheel replacement with predictive maintenance subscriptions, capturing margin from independent aftermarket distributors. |
| Military-Grade Track System Certification | India's defense modernization programs generate captive demand for armored vehicle subsystems with classified load-bearing specifications. |
Methodological Framework
SEC 10-K filings, customs trade databases, and OEM technical specification sheets formed the secondary backbone for market sizing and competitive positioning. Primary fieldwork involved structured interviews with maintenance directors at Australian mining operations, procurement leads at German agricultural equipment manufacturers, aftermarket service heads at North American dealer networks, and rubber compounding technical directors. Bottom-up triangulation across replacement cycle frequencies and top-down validation against equipment fleet databases ensured dimensional consistency.
Historical trendline analysis across equipment utilization rates, material substitution patterns, and regulatory compliance cost trajectories informed projection frameworks. Segmentation modeling spanned product type, application intensity, end-user channel structure, and installation environment severity. CAGRs were derived from elasticity-adjusted equipment deployment curves and replacement cycle compression factors. Industry-specific inputs included EPA Tier 4 Final weight reduction mandates, REACH plasticizer restriction timelines, and precision agriculture GPS guidance adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to carbon fiber precursor supply disruptions, steel price volatility, and multi-jurisdiction certification harmonization progress. Forecasts reflect documented assumptions regarding equipment fleet growth, regulatory enforcement consistency, and material science advancement trajectories. Material deviation in German OEM composite qualification timelines or Indian defense procurement acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Passenger Tire Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Connected Tire Market
Tires and Wheels
Global OTR Tires Market
Tires and Wheels
Tire Protection Chains Market
Tires and Wheels
United States Tire Market
Tires and Wheels
Kuwait Tyres Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market
Tires and Wheels
Japan Tyre Market
Tires and Wheels
Tire Carousel Market
Tires and Wheels
Europe Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Truck and Bus Radial (TBR) Tire Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Tire Repair Patch Market
Tires and Wheels
High Performance Wheels Market