
 Contract Dose Manufacturing Market | 2026-2036
Contract Dose Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Contract Dose Manufacturing Market Outlook
The pharmaceutical outsourcing channel is reconfiguring as innovators shed captive manufacturing assets and redirect capital toward discovery platforms. Lonza Group leverages its global network of multi-product facilities to anchor high-potency API-to-dose integrated programs for oncology clients. Catalent competes through specialized oral delivery technologies that differentiate its solid dosage offerings from commodity tablet manufacturers. Samsung Biologics sustains one of the largest single-site biologics manufacturing footprints, extending its position into downstream fill-finish services for monoclonal antibodies.
Contract dose manufacturing encompasses the outsourced production of finished drug products in solid, liquid, or semi-solid formats, encompassing processes such as blending, granulation, compression, coating, and aseptic filling under validated conditions. The practice enables pharmaceutical innovators to access specialized containment infrastructure, validated cleaning protocols, and regulatory-compliant documentation without capital-intensive facility construction. Solid dosage forms occupy the largest service segment due to mature process knowledge and broad therapeutic applicability across cardiovascular and central nervous system indications. Continuous manufacturing represents the fastest-expanding technology category as regulators streamline approval pathways for real-time release testing and reduced batch failure rates. Liquid dosage forms command premium pricing in biologics due to stringent cold-chain requirements and specialized parenteral packaging competencies.
The FDA enforces Current Good Manufacturing Practice regulations through facility inspections and warning letter programs that directly determine market access for dose manufacturers serving US-bound products. EMA's revised Annex 1 on sterile manufacturing, effective across EU member states, mandates barrier isolation technology and enhanced environmental monitoring that reshape capital allocation for European contract manufacturers. India's CDSCO aligns with WHO prequalification standards to support export-oriented dose facilities targeting regulated markets. Stakeholders must monitor how regional divergence in data integrity enforcement and serialization mandates alters site selection criteria for multi-market product registrations.
Market Dynamics
Biopharmaceutical innovators are dismantling captive manufacturing infrastructure and redirecting capital toward discovery platforms, forcing contract dose manufacturers to absorb capacity risk while proving operational differentiation through specialized containment and integrated regulatory documentation services.
Growth Catalysts
- EMA's revised Annex 1:Mandatory barrier isolation technology for sterile manufacturing creates premium service tiers for European dose contractors with validated isolator infrastructure.
- Continuous manufacturing adoption:Real-time release testing capabilities compress batch cycle times and reduce failure rates for solid dosage producers investing in process analytical technology.
- India:CDMO clusters in Hyderabad and Ahmedabad scale dedicated potent compound facilities targeting export-oriented regulated markets with WHO prequalification alignment.
Market Restraints
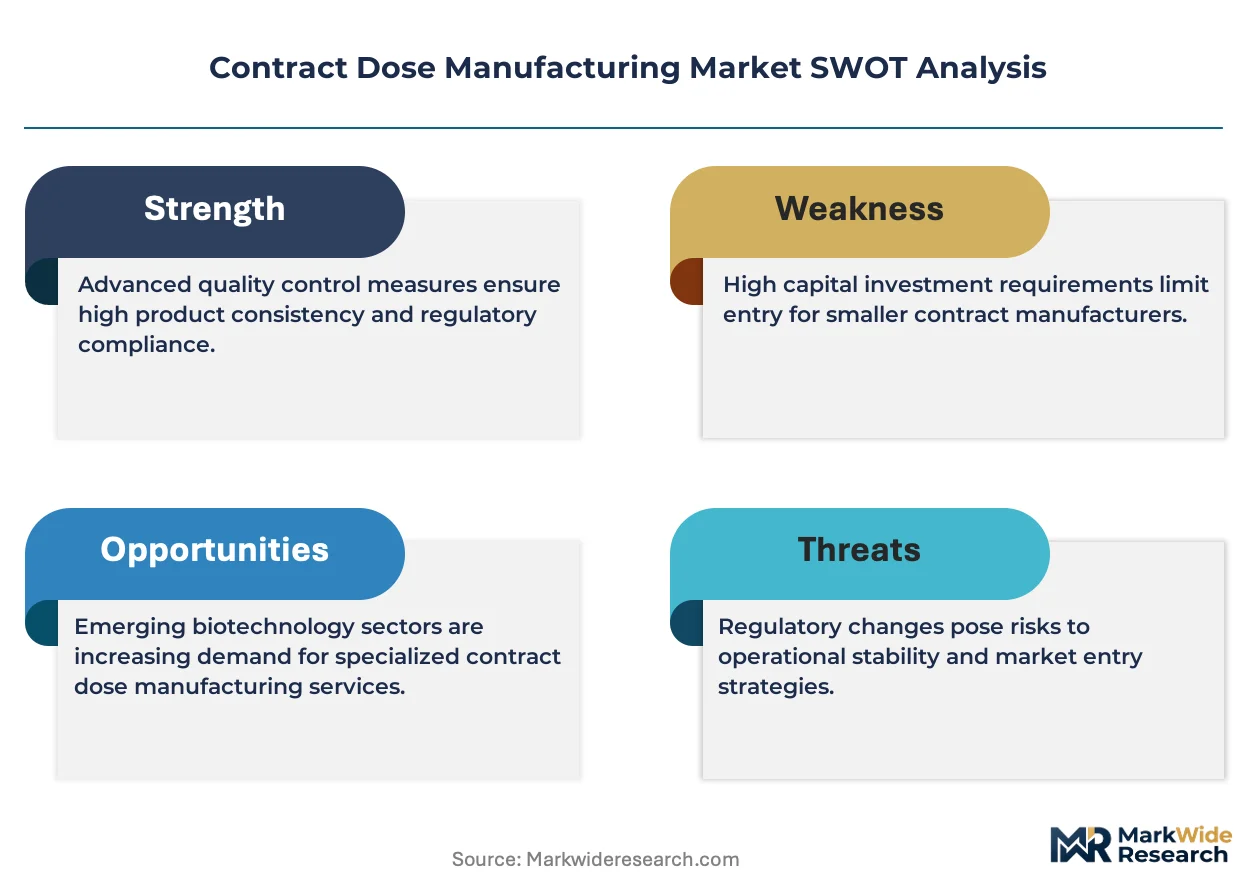
- Specialized containment capital intensity:High-potency API handling requires isolator technology and dedicated HVAC systems that strain mid-tier contractor balance sheets.
- Single-source excipient dependency:Concentrated supply of pharmaceutical-grade polymers and modified-release coatings from German and Japanese chemical suppliers creates input vulnerability.
- Cleaning validation bottlenecks:FDA scrutiny of carryover limits and residue detection methods extends campaign changeover timelines for multi-product facilities.
Strategic Opportunities
- Integrated API-to-dose programs:Convergence of high-potency synthesis and sterile fill-finish capabilities creates stickier client relationships and higher contract values.
- Cell and gene therapy dose formats:Aseptic processing of personalized viral vectors and lipid nanoparticles opens adjacent service lines beyond traditional small-molecule tablets.
- CDSCO export certification:India's alignment with WHO prequalification standards enables domestic dose manufacturers to supply PEPFAR and Global Fund procurement channels.
Industry Challenges
- Aseptic processing technician scarcity:Validated cleanroom behavior and environmental monitoring expertise command wage premiums that erode contractor margins.
- Legacy batch record systems:Paper-based documentation workflows impede real-time data integrity compliance with FDA's Quality Management Maturity program expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contract Dose Manufacturing Market |
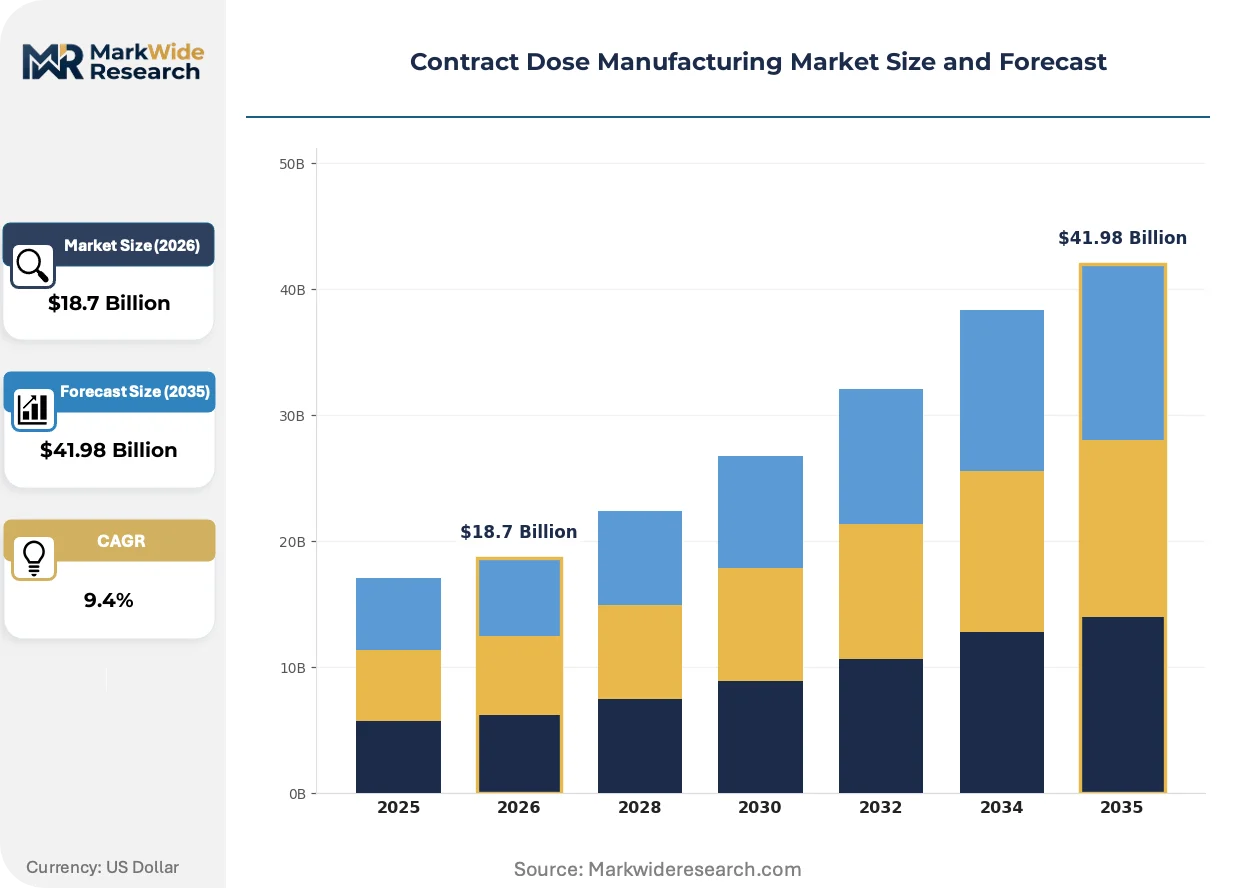
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Solid Dosage Forms, Liquid Dosage Forms, Semi-Solid Forms, Others End User: Pharmaceutical Companies, Biotechnology Firms, Contract Research Organizations, Academic Institutions Technology: Chemical Synthesis, Biotechnological Methods, Nanotechnology, Continuous Manufacturing Packaging Type: Bottles, Blisters, Sachets, Pouches |
| Companies Covered | Lonza Group, Catalent, Thermo Fisher Scientific, Samsung Biologics, Boehringer Ingelheim International GmbH, WuXi AppTec, Recipharm AB, Almac Group, CordenPharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contract Dose Manufacturing Market Strategic Shifts
Digital process control systems and modular facility designs are compressing the traditional boundaries between development-scale and commercial-scale manufacturing, enabling dose contractors to serve fragmented biologics portfolios with flexible capacity commitments.
Process analytical technology (PAT) platforms equipped with near-infrared spectroscopy and multivariate statistical process control are virtualizing traditional quality assurance workflows. Mid-sized dose manufacturers in Switzerland and Singapore deploy these systems to support real-time release testing for oral solid dosage clients. The technology is virtualizing batch record review cycles that previously required days of post-production documentation verification.
REACH chemical registration requirements in Europe are forcing reformulation of tablet coatings and controlled-release matrices containing legacy plasticizers. Dose manufacturers serving EU-bound products must validate alternative excipient suppliers and demonstrate equivalent dissolution profiles. Oral dosage contractors with established polymer science partnerships capture reformulation service revenue from innovators facing registration deadlines.
Biopharmaceutical procurement teams are consolidating supplier panels and demanding integrated regulatory dossier support from dose partners. Small-molecule innovators in Massachusetts and California now expect contract manufacturers to manage CMC section preparation and respond directly to agency information requests. This concentration of vendor relationships favors dose contractors with dedicated regulatory affairs functions over commodity tablet producers.
Contract Dose Manufacturing Market Segmentation
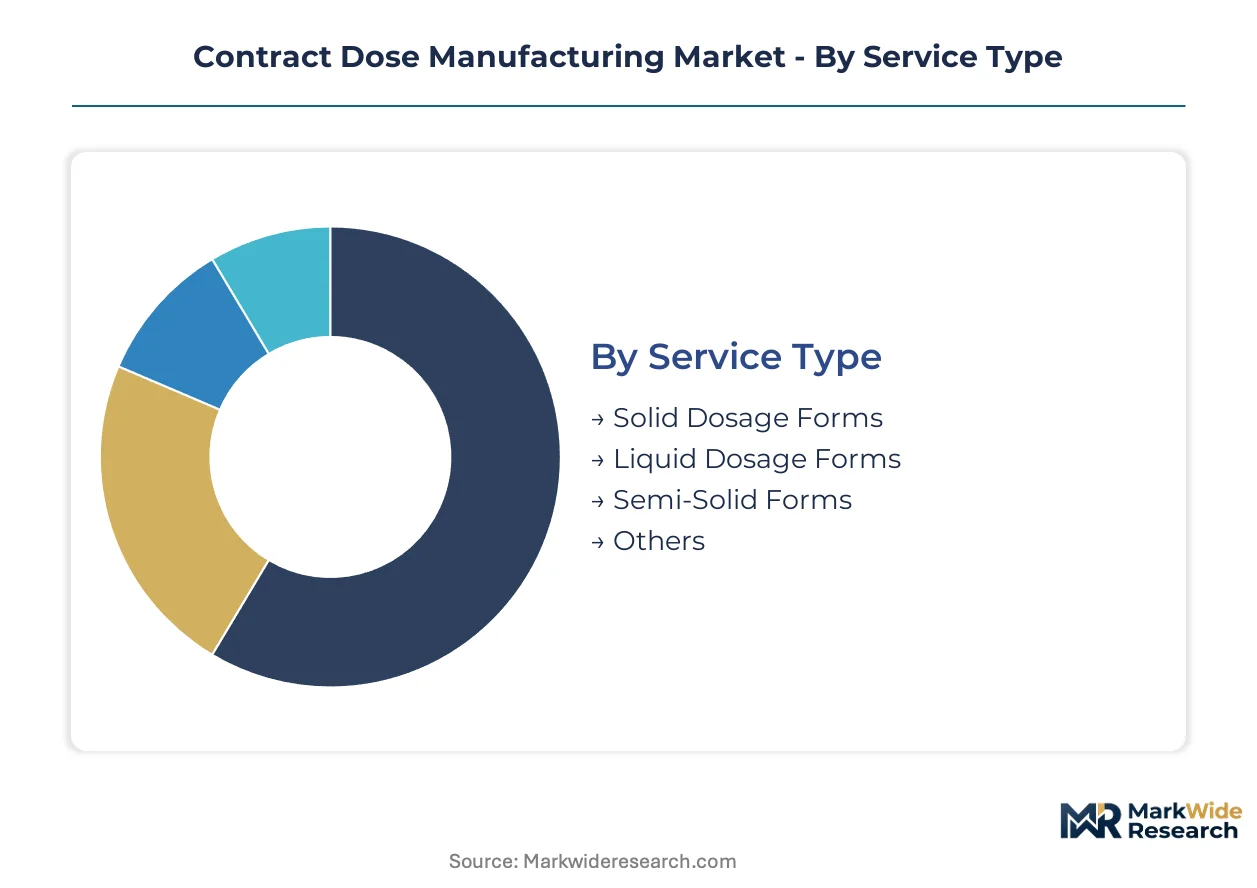
Contract dose manufacturing segments reflect divergent capital requirements, regulatory complexity, and client risk profiles. Service type determines facility infrastructure investment, while technology choice separates commodity processors from differentiated partners. Understanding these dimensions clarifies where margin pools concentrate and which capabilities command pricing power.
Service Type:
Cost tier stratification across service types separates high-volume commodity production from specialized containment-dependent formats requiring dedicated cleanroom infrastructure and validated cleaning protocols.
- Solid Dosage Forms:Tablets, capsules, and powders dominate commercial volumes due to mature process knowledge and lower per-unit manufacturing costs. Cardiovascular and central nervous system drug innovators in Massachusetts and California outsource compression and coating operations to avoid capital-intensive facility construction.
- Liquid Dosage Forms:Solutions, suspensions, and syrups command premium pricing driven by stringent cold-chain requirements and specialized parenteral packaging competencies. Biologics developers seeking aseptic fill-finish capacity for monoclonal antibodies concentrate demand with contractors possessing isolator technology and real-time environmental monitoring systems.
- Semi-Solid Forms:Creams, ointments, and gels serve dermatology and topical pain management indications with intermediate capital requirements between solids and sterile liquids.
- Others:Inhalation powders, transdermal patches, and novel delivery formats capture niche demand from specialty pharmaceutical innovators.
Solid dosage commands the established base. The steepest expansion runs through liquid dosage forms.
End User:
Customer type determines contract structure complexity, with large pharmaceutical companies demanding integrated regulatory dossier support while smaller biotechnology firms prioritize speed and flexibility.
- Pharmaceutical Companies:Large innovators dismantling captive manufacturing infrastructure seek multi-year capacity commitments and direct agency response capabilities. These clients consolidate supplier panels and expect contract manufacturers to manage CMC section preparation for FDA and EMA submissions.
- Biotechnology Firms:Venture-backed developers of monoclonal antibodies and cell therapies require rapid scale-up from clinical to commercial batches. CDMO clusters in Hyderabad and Ahmedabad capture this demand through dedicated potent compound facilities aligned with WHO prequalification standards.
- Contract Research Organizations:CROs managing integrated development programs source dose manufacturing as part of bundled service offerings to sponsor clients.
- Academic Institutions:University research centers and teaching hospitals require small-batch clinical trial material production with flexible changeover protocols.
Pharmaceutical companies anchor volume commitments. Biotechnology firms are expanding most quickly as capital flows toward discovery platforms.
Technology:
Process maturity separates established batch methods from emerging continuous platforms that compress cycle times and enable real-time release testing.
- Chemical Synthesis:Traditional small-molecule API conversion and formulation processes remain prevalent for generic solid dosage production.
- Biotechnological Methods:Cell culture and microbial fermentation underpin biologics dose manufacturing, requiring specialized containment and viral clearance validation.
- Nanotechnology:Lipid nanoparticle and nanocrystal formulations enable enhanced bioavailability for poorly soluble compounds.
- Continuous Manufacturing:PAT-equipped production lines with near-infrared spectroscopy and multivariate statistical process control virtualize traditional quality assurance workflows. Mid-sized dose manufacturers in Switzerland and Singapore deploy these systems to support real-time release testing for oral solid dosage clients.
Chemical synthesis retains the largest installed base. Continuous manufacturing is gaining share fastest as regulators streamline approval pathways.
Packaging Type:
Packaging configuration directly influences serialization compliance costs and supply chain security requirements across regulated markets.
- Bottles:HDPE and PET containers serve oral liquid and solid dosage formats with established filling lines and label application systems.
- Blisters:PVC and aluminum lidding dominates oral solid dosage presentation, with cold-form foil variants for moisture-sensitive compounds.
- Sachets:Single-unit powder and granule packaging captures demand in emerging markets and over-the-counter segments.
- Pouches:Flexible film packaging for semi-solid and liquid unit-dose formats supports patient compliance programs and hospital dispensing.
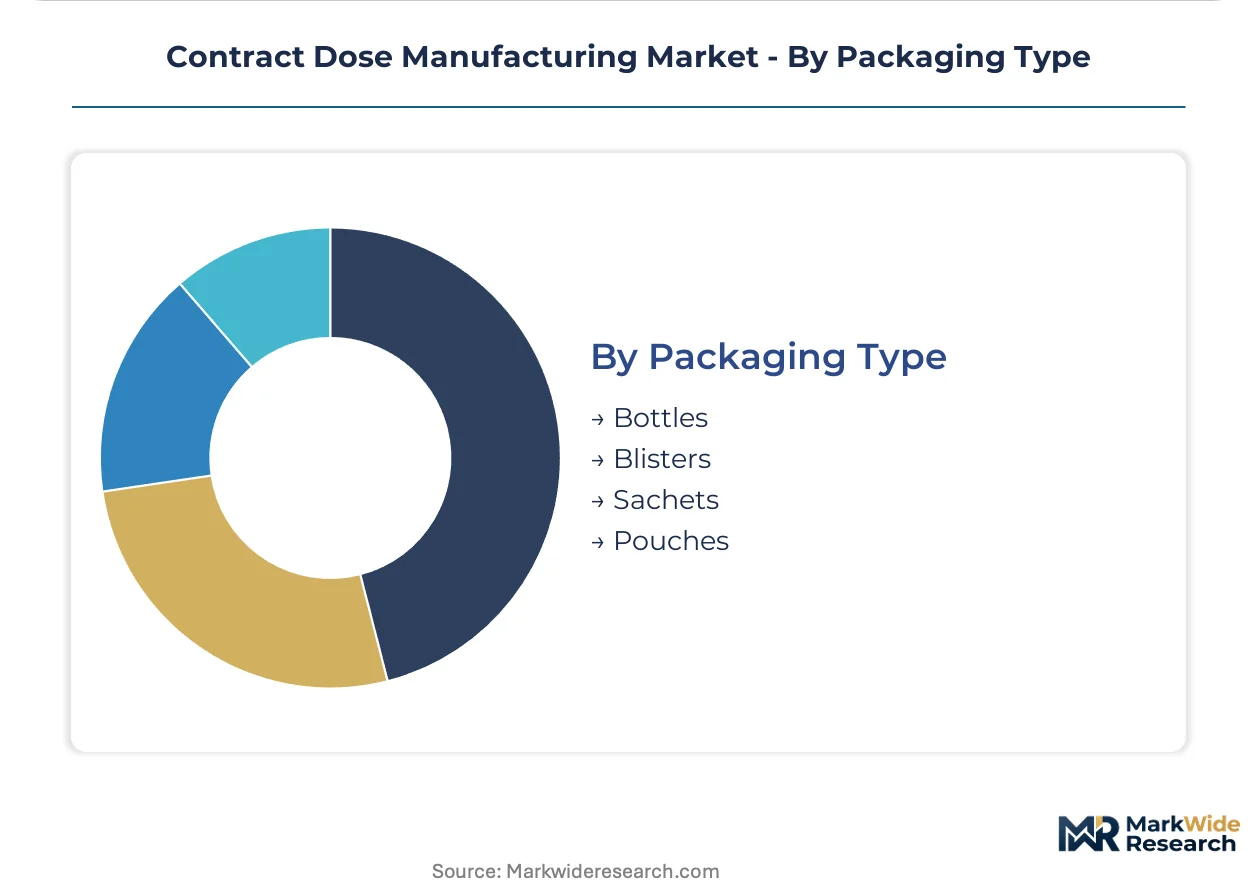
Blister packaging holds the dominant position. Pouch formats are climbing the fastest as unit-dose compliance packaging expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain logistics infrastructure underwrites European pharmaceutical distribution, while India's Dedicated Freight Corridors connect Hyderabad and Ahmedabad manufacturing clusters to export terminals. These transport assets determine where dose manufacturing capacity concentrates.
United States
Massachusetts and California biotech innovators outsource solid dosage compression and coating to avoid capital-intensive facility construction. FDA's Quality Management Maturity program raises compliance thresholds for sterile processing operations. Greater Boston hosts specialized containment facilities serving oncology clients with high-potency API handling requirements.
Germany
REACH chemical registration requirements force reformulation of tablet coatings and controlled-release matrices containing legacy plasticizers. EMA's revised Annex 1 mandates barrier isolation technology for sterile manufacturing across EU member states. The Rhine-Main region concentrates dose contractors with validated isolator infrastructure for parenteral products.
Switzerland
Mid-sized dose manufacturers deploy process analytical technology platforms with near-infrared spectroscopy for real-time release testing. Swissmedic maintains stringent oversight of multi-product facility cleaning validation protocols. Basel anchors integrated API-to-dose programs combining high-potency synthesis with sterile fill-finish capabilities.
India
CDSCO alignment with WHO prequalification standards enables domestic manufacturers to supply PEPFAR and Global Fund procurement channels. The Dedicated Freight Corridor links Hyderabad and Ahmedabad CDMO clusters to export-oriented regulated markets. These cities scale dedicated potent compound facilities targeting biologics dose formats.
Singapore
Biologics developers seeking aseptic fill-finish capacity concentrate demand with contractors possessing isolator technology and real-time environmental monitoring. The national pharmaceutical regulator enforces data integrity standards equivalent to FDA and EMA requirements. Tuas Biomedical Park hosts modular facility designs serving fragmented biologics portfolios.
Contract Dose Manufacturing Market Competitive Environment
On the supply side, the industry is consolidating around three strategic tiers. Global network operators with multi-continent facility footprints anchor high-value integrated programs. Regional specialists compete through differentiated delivery technologies or potent compound containment capabilities. Technology licensors and modular facility providers enable mid-tier entrants to bypass capital barriers. Dominant competitive moves include capacity expansion into emerging biologics clusters and strategic partnerships for cell and gene therapy dose formats.
Within the global network tier, Lonza Group and Catalent exemplify contrasting differentiation strategies. Thermo Fisher Scientific occupies a position spanning laboratory services through commercial dose manufacturing. Samsung Biologics anchors the large-scale biologics manufacturing segment with extension into downstream fill-finish services. These three entities represent how scale, technology specialization, and geographic concentration create distinct competitive positions.
| Leading Market Players |
|---|
| Lonza Group |
| Catalent |
| Thermo Fisher Scientific |
| Samsung Biologics |
| Boehringer Ingelheim International GmbH |
| WuXi AppTec |
| Recipharm AB |
| Almac Group |
| CordenPharma |
| Others |
Value Chain & Pricing Dynamics
German and Japanese chemical suppliers dominate pharmaceutical-grade polymer and modified-release coating supply, concentrating pricing power with excipient manufacturers and forcing dose contractors to absorb input volatility or pass through cost escalations via long-term offtake renegotiations.
Pricing Analysis
Volume-discount tiering structures separate large pharmaceutical innovators securing multi-year capacity commitments from biotechnology firms purchasing clinical-batch quantities at premium per-unit rates. Three-tier pricing stratification across isolator-certified sterile fill-finish, standard aseptic processing, and commodity solid dosage reflects containment complexity and regulatory audit intensity. Pricing pressure stems from mid-tier contractors competing for panel consolidation mandates from Massachusetts and California innovators. Large pharmaceutical companies exhibit lowest price sensitivity due to integrated regulatory dossier requirements, while academic institutions and small CROs face acute budget constraints.
Supply Chain Analysis
Export-control regimes limiting specialized isolator technology and barrier containment equipment flows from Switzerland and Germany constrain capacity expansion timelines for contractors in India and Singapore. Active pharmaceutical ingredient supply concentrates in India and China, with high-potency oncology compounds increasingly sourced from Hyderabad clusters. Pharmaceutical-grade excipients, stainless-steel processing equipment, and validated cleaning agents constitute critical input dependencies. Single-source vulnerability runs through German polymer suppliers for modified-release coatings. Distribution runs through cold-chain logistics networks anchored at Rotterdam and Mumbai ports, with Dedicated Freight Corridors linking Ahmedabad manufacturing to export terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Validated aseptic processing technicians and isolator-certified cleanroom engineers represent the scarcest capabilities, constraining expansion timelines for contractors competing on sterile fill-finish differentiation and compressing margins through wage-premium escalation.
For Market Incumbents: Pre-empt technician scarcity by embedding apprenticeship pipelines with Swiss and German technical institutes before wage inflation erodes sterile processing margins. Anchor capacity expansion in Hyderabad and Ahmedabad where CDSCO-WHO alignment supports export-oriented regulated market access. Defend against modular facility entrants by deepening backward integration into high-potency API synthesis. For New Entrants and Emerging Players: Build out cell and gene therapy dose format capabilities in Singapore's Tuas Biomedical Park, where national regulators enforce FDA-equivalent data integrity standards without incumbent capacity congestion. Target biotechnology firms in Massachusetts requiring rapid clinical-to-commercial scale-up for monoclonal antibody programs. Pursue technology licensing partnerships with Swiss PAT platform providers to bypass capital-intensive continuous manufacturing development. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier dose manufacturers possessing isolator infrastructure and underutilized potent compound capacity in India, where CDSCO export certification opens PEPFAR and Global Fund procurement channels. Long-term viability hinges on regulatory dossier preparation capabilities and direct agency response functions. Watch for FDA Quality Management Maturity program compliance deadlines as inflection indicators for contractor consolidation urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator Technology Deployment | EMA Annex 1 mandates barrier isolation for sterile manufacturing across EU member states. |
| Continuous Manufacturing Scale-Up | PAT-equipped lines with near-infrared spectroscopy enable real-time release testing for oral solids. |
| API-to-Dose Integration | Convergence of high-potency synthesis and fill-finish creates stickier client relationships. |
| Cell and Gene Therapy Adjacency | Aseptic processing of viral vectors and lipid nanoparticles opens beyond small-molecule tablets. |
| WHO Prequalification Alignment | CDSCO certification enables Indian manufacturers to supply PEPFAR and Global Fund channels. |
Study Parameters
Initial hypotheses were tested against primary input from regulatory affairs directors, sterile processing facility managers, biopharmaceutical procurement leads, and CDSCO compliance officers, then refined through secondary validation against FDA warning letter databases, EMA GMP inspection records, ClinicalTrials.gov manufacturing disclosures, and WHO prequalification facility lists. Bottom-up capacity utilization surveys across Hyderabad and Ahmedabad CDMO clusters were triangulated with top-down pharmaceutical outsourcing expenditure estimates from SEC filings.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling segmentation dimensions including dosage form complexity, containment tier certification, end-user scale archetype, and regional regulatory cluster alignment. CAGRs were derived from facility expansion announcements, capital expenditure disclosures, and validated capacity absorption rates. Forecast inputs incorporated EMA Annex 1 compliance timelines and FDA Quality Management Maturity program rollout assumptions.
Practitioners should monitor regulatory audit failure rates, isolator equipment delivery lead times, and excipient supplier concentration for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Trulicity Market
Pharmaceuticals
Hypertriglyceridemia Therapeutics Market
Pharmaceuticals
Veterinary Active Pharmaceutical Ingredients Manufacturing Market
Pharmaceuticals
Gastric Cancer Drugs Market
Pharmaceuticals
Anti-Inflammatory Analgesic and Antipyretic Drugs Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Chemotherapy-Induced Nausea and Vomiting Therapeutics Market
Pharmaceuticals
Candidiasis Therapeutics Market
Pharmaceuticals
In-Silico Drug Discovery Market
Pharmaceuticals
Global Oxytocin Market
Pharmaceuticals
Antihistamines Market
Pharmaceuticals
Short-Acting Insulin Market
Pharmaceuticals
Albinism Drugs Market
Pharmaceuticals
Urinary Antibacterial and Antiseptic Pharmaceuticals Market
Pharmaceuticals
Global Desmopressin Market
Pharmaceuticals
Europe Sodium-Dependent Glucose Cotransporter 2 Market