
 PXI SMU Market | 2026-2036
PXI SMU Market Size, Share, and Industry Trends Forecast 2026-2036
PXI SMU Market Analysis
Market Context
Gallium nitride is restructuring power electronics test economics as wide-bandgap devices displace silicon IGBTs in automotive and renewable energy inverters. Keysight Technologies leverages its RF measurement heritage to dominate high-frequency PXI SMU configurations for 5G baseband verification. National Instruments anchors its position through software-defined instrumentation platforms that integrate with LabVIEW ecosystems across aerospace and defense programs.
Technical Definition and Segment Structure
A PXI SMU (Source Measure Unit) is a modular instrument that combines precision voltage sourcing and current measurement in a single PXI chassis slot, typically achieving resolution below 100 fA and voltage accuracy within microvolts for semiconductor device characterization. Modular Instruments command the dominant revenue share due to chassis scalability in high-throughput production test, while High-Precision Sources capture concentrated margin pools from research institutions performing quantum device research. Digital Simulation technology leads unit shipments for automated device testing, whereas Remote Sensing capabilities are expanding fastest in automotive battery management system validation where kelvin connections eliminate lead resistance errors.
Regulatory Environment and Outlook
FCC equipment authorization rules in the United States and CE marking requirements under the EU Radio Equipment Directive shape PXI SMU demand by mandating pre-compliance electromagnetic compatibility testing for wireless devices. China's GB standards administered by MIIT and Japan's METI technical regulations further segment product certification requirements across major electronics manufacturing jurisdictions. Stakeholders must monitor evolving wide-bandgap semiconductor test standards from IEC and JEDEC committees, as these specifications directly determine the voltage and current range requirements that define next-generation PXI SMU hardware roadmaps.
Market Dynamics
Wide-bandgap semiconductor adoption is restructuring test equipment specifications as silicon carbide and gallium nitride devices demand higher voltage precision and faster switching characterization than legacy silicon-based workflows permit.
Growth Catalysts
- Automotive electrification mandates:Battery management system validation for electric vehicles requires kelvin-connected PXI SMU configurations to eliminate lead resistance errors in high-current cell testing.
- REACH and RoHS compliance deadlines:European electronics manufacturers are accelerating test throughput to certify lead-free solder joints and restricted substance compliance across wireless device portfolios.
- Taiwan and South Korea fab expansion:Semiconductor manufacturers in Hsinchu and Pyeongtaek are scaling wafer-level probe station installations that integrate modular source-measure units for parametric device extraction.
Market Restraints
- Precision analog component supply concentration:Ultra-low-noise operational amplifiers and hermetic relays for femtoampere measurement channels source predominantly from Japanese and German specialty suppliers.
- IEC 61010 safety certification costs:Third-party validation for high-voltage PXI SMU modules adds eighteen to twenty-four months to product release cycles and six-figure external testing expenditure.
- Silicon IGBT test equipment substitution:Existing rack-and-stack GPIB-based SMU systems in mature power electronics facilities delay modular PXI conversion despite superior throughput density.
Strategic Opportunities
- Quantum device research institutions:Cryogenic probe stations at national laboratories require specialized high-precision source-measure units operating at millikelvin temperatures with noise floors below ten femtoamperes.
- India's PLI scheme for electronics manufacturing:Contract manufacturers in Noida and Chennai are qualifying PXI-based test cells to meet domestic value-add requirements for smartphone and telecom equipment production.
- 5G mmWave baseband verification convergence:RF vector signal analyzers and precision DC SMUs are integrating into single PXI chassis configurations for transceiver characterization at FR2 frequency bands.
Industry Challenges
- Multi-physics simulation expertise scarcity:Test engineers capable of correlating thermal, electrical, and mechanical models for wide-bandgap device characterization command premium compensation and extended recruitment cycles.
- Legacy ATE software migration friction:Semiconductor fabs with decades of investment in proprietary test program sets face integration complexity when porting routines to LabVIEW or Python-based PXI environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PXI SMU Market |
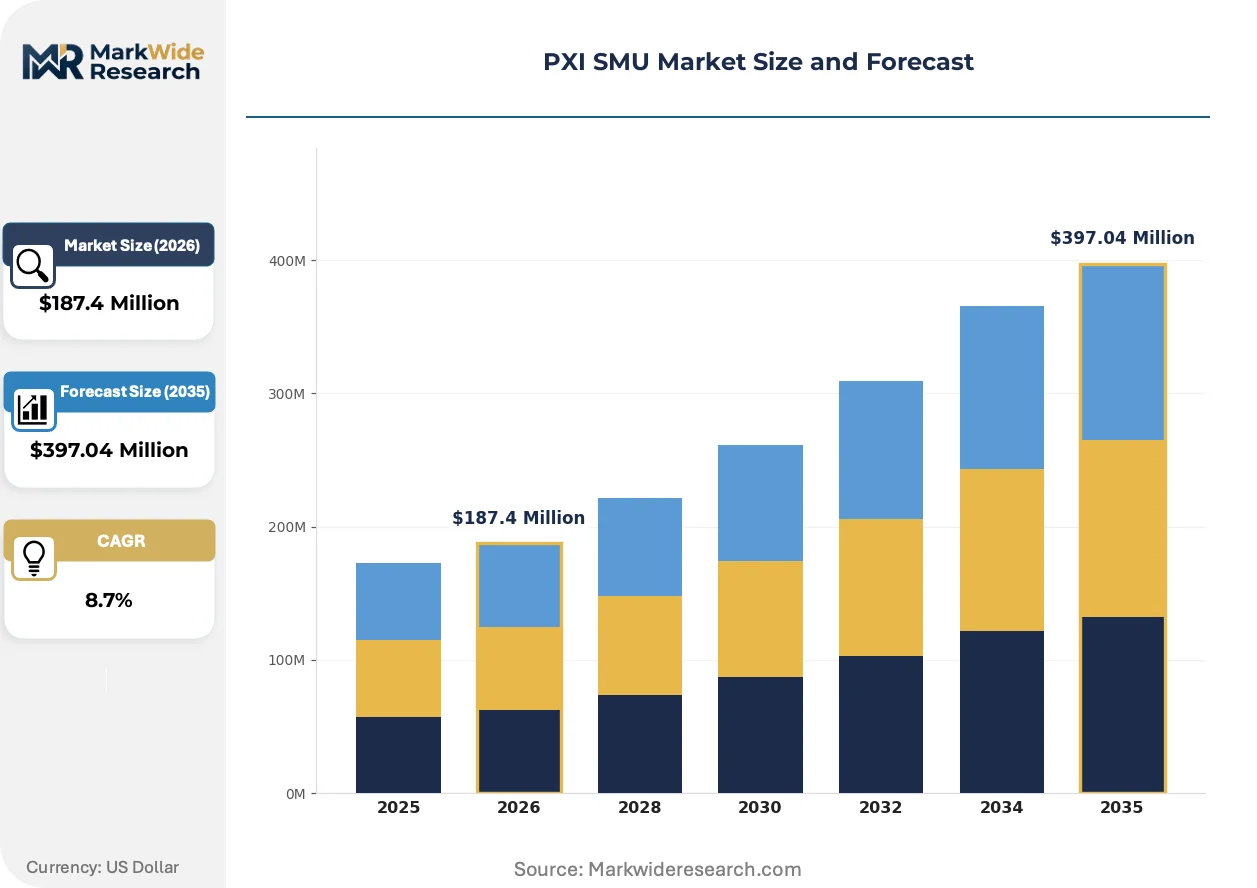
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Instruments, Bench-top Systems, High-Precision Sources, Low-Cost Solutions Technology: Digital Simulation, Real-Time Control, Analog Output, Remote Sensing End User: Aerospace, Automotive OEMs, Telecommunications, Research Institutions Application: Device Testing, Signal Generation, Power Management, Calibration |
| Companies Covered | VX Instruments, LitePoint, National Instruments, Tektronix, ADLINK Technology, Keysight Technologies, Marvin Test Solutions, Teradyne, Chroma ATE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PXI SMU Market Emerging Trajectories
Test instrumentation architectures are converging around software-defined platforms that decouple measurement hardware from fixed-function firmware, enabling field-upgradable capability expansion without chassis replacement.
Silicon carbide device qualification is integrating pulsed IV measurement modes with microsecond settling times to capture trapping effects in high-voltage power MOSFETs. Automotive tier-one suppliers in Germany and Japan are deploying these configurations for inverter module screening. The technology is integrating thermal chamber control loops directly into SMU sequencing engines, collapsing test cell footprint and eliminating synchronization latency between environmental and electrical subsystems.
The EU Radio Equipment Directive's 2024 cybersecurity annex is mandating pre-market vulnerability assessment documentation for wireless devices. PXI SMU manufacturers must now embed tamper-evident calibration certificates and secure firmware update mechanisms to maintain CE marking eligibility. Test houses in the Netherlands and Finland are expanding electromagnetic compatibility pre-compliance services to include these new documentation requirements.
Capital equipment purchasing committees are consolidating vendor relationships around single-source platform ecosystems rather than best-of-breed point instruments. Aerospace and defense contractors in the United States are specifying PXI chassis compatibility with existing software asset libraries as a primary evaluation criterion. This behavioral shift favors suppliers with decade-long driver maintenance commitments and backward-compatible module roadmaps over niche performance leaders with narrow interoperability.
PXI SMU Market Segmentation
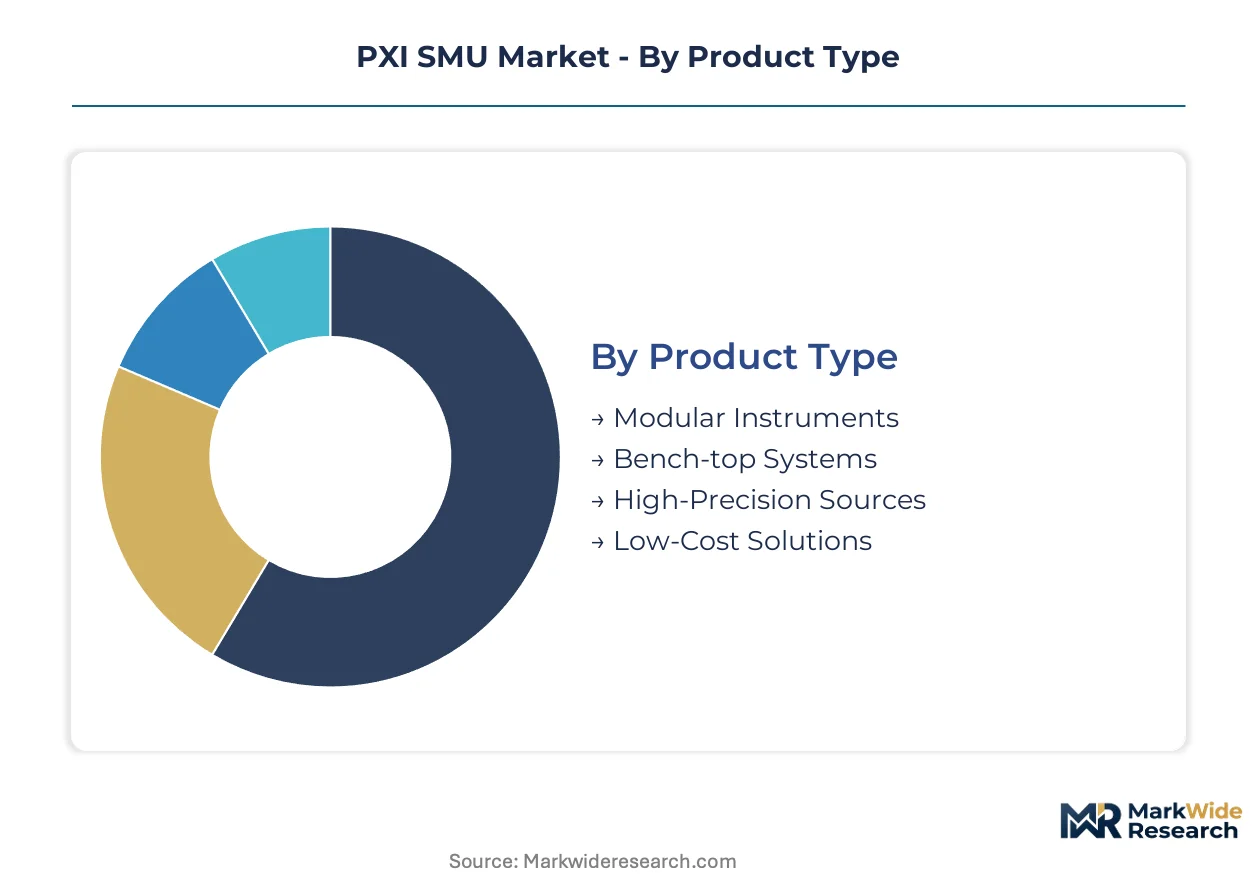
PXI SMU procurement cycles vary sharply across product architectures and precision tiers, with chassis-based modular systems commanding premium replacement schedules tied to semiconductor fab expansion timelines. Technology differentiation in sourcing and measurement modes determines upgrade urgency, while end-user verticals impose distinct validation protocols that reshape segment economics.
Product Type:
Replacement cycles accelerate where chassis scalability intersects with throughput-intensive production environments, compressing upgrade windows for modular configurations relative to fixed-form alternatives.
- Modular Instruments:These PXI chassis-integrated units achieve slot densities exceeding sixteen channels per rack, enabling parallel wafer-level testing. Taiwan Semiconductor Manufacturing and Samsung Foundry are expanding procurement for Hsinchu and Pyeongtaek facilities as 3nm process nodes demand higher channel counts per square meter of cleanroom footprint.
- High-Precision Sources:Achieving resolution below 100 femtoamperes with microvolt voltage accuracy, these units serve cryogenic quantum device characterization. National laboratories in the United States and Germany are driving demand as superconducting qubit research requires noise floors below ten femtoamperes at millikelvin temperatures.
- Bench-top Systems:Standalone instruments with integrated displays suit low-volume research workflows and educational laboratories where chassis infrastructure is unavailable.
- Low-Cost Solutions:Reduced-precision units target emerging market contract manufacturers qualifying basic parametric test for consumer electronics assembly.
Modular Instruments sits at the top of the volume ranking, with High-Precision Sources climbing the fastest.
Technology:
Measurement modality selection hinges on synchronization requirements between electrical stimulus and environmental control, with pulsed architectures gaining preference for wide-bandgap device characterization.
- Digital Simulation:Automated test sequences with programmable settling times dominate high-volume production lines. Automotive inverter manufacturers in Germany are adopting these configurations for silicon carbide MOSFET screening, where microsecond pulse widths capture trapping effects without thermal distortion.
- Remote Sensing:Kelvin connection architectures eliminate lead resistance errors through four-wire measurement topologies. Battery management system validation for electric vehicles in Japan and South Korea is expanding adoption as cell currents exceed 200 amperes in next-generation pack designs.
- Real-Time Control:Closed-loop feedback architectures synchronize SMU outputs with thermal chamber setpoints, collapsing test cell footprint for multi-physics characterization.
- Analog Output:Continuous waveform generation suits legacy device qualification where digital quantization noise compromises measurement integrity.
Digital Simulation leads absolute unit shipments, though Remote Sensing is expanding most quickly as electrification mandates tighten current measurement tolerances.
End User:
Vertical-specific certification requirements reshape procurement specifications, with defense and automotive programs imposing traceability standards that exclude general-purpose instrumentation.
- Automotive OEMs:Tier-one suppliers in Germany and Japan require IEC 61010 safety certification and tamper-evident calibration chains for battery cell testing. The EU Radio Equipment Directive's cybersecurity annex is mandating secure firmware update mechanisms for CE marking eligibility.
- Aerospace:Defense contractors in the United States specify PXI chassis compatibility with existing software asset libraries as a primary evaluation criterion, favoring suppliers with decade-long driver maintenance commitments.
- Telecommunications:5G baseband verification demands integration of RF vector signal analyzers with precision DC SMUs in single chassis configurations for FR2 frequency band characterization.
- Research Institutions:Cryogenic probe stations at national laboratories require specialized units operating at millikelvin temperatures, commanding concentrated margin pools despite low unit volumes.
Automotive OEMs anchor current procurement volume, while Research Institutions command the steepest expansion trajectory as quantum computing investment accelerates.
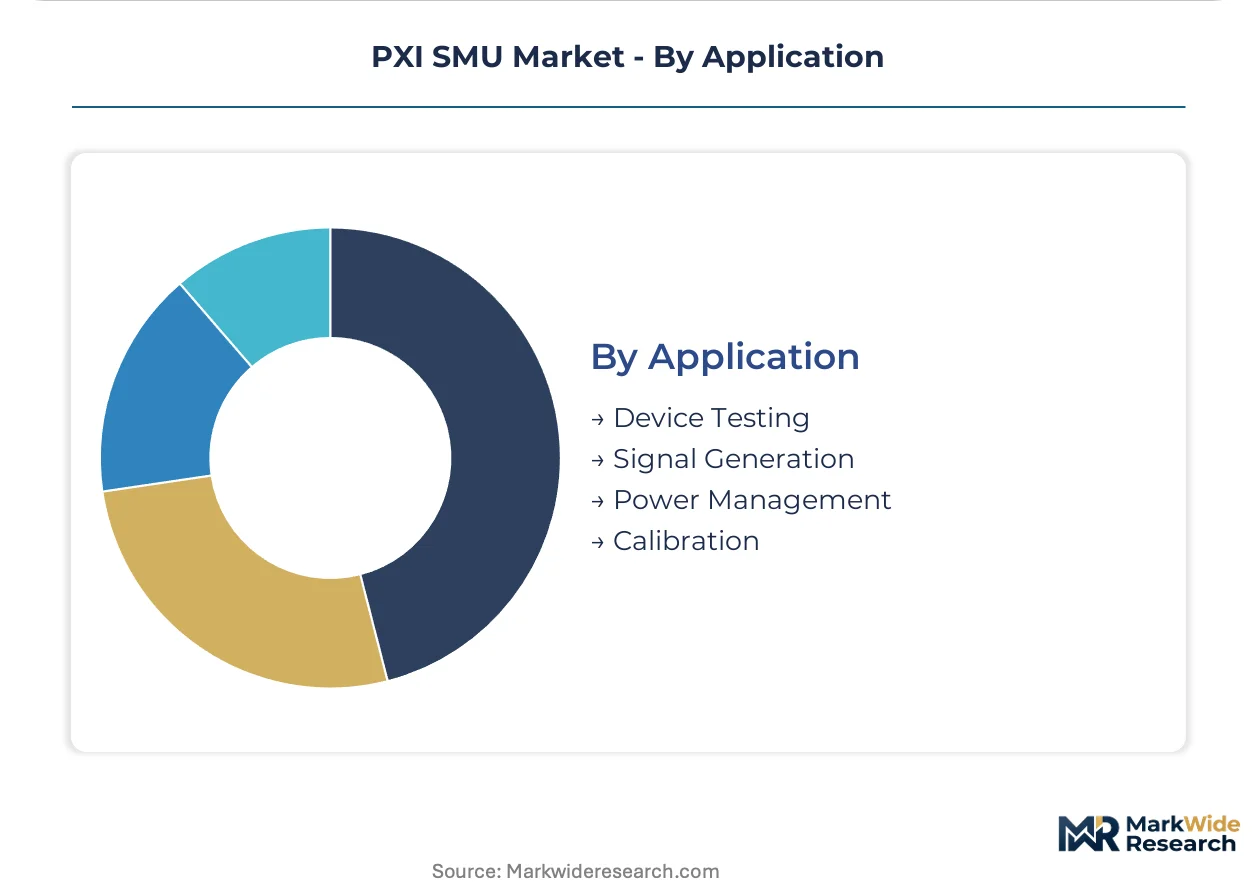
Application:
Test throughput requirements diverge across application modes, with production screening demanding parallel channel architectures that research calibration workflows cannot justify.
- Device Testing:Parametric extraction for semiconductor wafers requires femtoampere resolution and sub-microsecond settling times. Taiwan and South Korea fab expansions are scaling probe station installations that integrate modular source-measure units for process control monitoring.
- Power Management:Validation of wide-bandgap inverter modules integrates thermal chamber control loops directly into SMU sequencing engines. Automotive suppliers are deploying these configurations to eliminate synchronization latency between environmental and electrical subsystems.
- Signal Generation:Precision voltage sourcing for mixed-signal device verification demands tight integration with digital pattern generators.
- Calibration:Metrology-grade traceability requirements limit addressable supply base to vendors with accredited laboratory networks.
Device Testing holds the volume leadership position, with Power Management gaining share fastest as silicon carbide adoption restructures inverter validation protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park anchors PXI SMU procurement intensity as Taiwan Semiconductor Manufacturing scales 3nm wafer-level probe station installations. South Korea's Pyeongtaek cluster follows with Samsung Foundry expanding parametric test cell capacity. Japan's automotive tier-one suppliers and Germany's inverter manufacturers are restructuring test protocols for silicon carbide device qualification.
United States
National laboratories in New Mexico and Maryland drive cryogenic quantum device characterization demand with noise floors below ten femtoamperes. FCC equipment authorization rules mandate pre-compliance electromagnetic compatibility testing for wireless devices. Aerospace contractors in Southern California specify PXI chassis compatibility with existing software asset libraries as primary evaluation criteria.
China
MIIT-administered GB standards segment product certification requirements for domestic electronics manufacturing. Contract manufacturers in Shenzhen and Dongguan are qualifying PXI-based test cells to meet value-add requirements under the dual carbon goals framework. Yangtze River Delta fabs are expanding procurement for wide-bandgap semiconductor production lines.
Japan
METI technical regulations impose traceability standards that exclude general-purpose instrumentation from automotive battery management system programs. Tier-one suppliers in Nagoya and Toyota City require IEC 61010 safety certification with tamper-evident calibration chains. Kansai region manufacturers are deploying kelvin-connected configurations for cell currents exceeding 200 amperes.
Germany
REACH and RoHS compliance deadlines accelerate test throughput for lead-free solder joint certification across wireless device portfolios. Automotive inverter manufacturers in Munich and Stuttgart are adopting pulsed IV measurement modes with microsecond settling times. Bavarian test houses are expanding electromagnetic compatibility pre-compliance services to include EU Radio Equipment Directive cybersecurity annex requirements.
South Korea
Samsung Foundry's Pyeongtaek expansion scales modular source-measure unit integration for process control monitoring at 3nm nodes. MFDS-equivalent technical regulations shape medical device test equipment specifications. Seoul Capital Area battery manufacturers are validating next-generation pack designs with remote sensing architectures eliminating lead resistance errors.
PXI SMU Market Vendor Landscape
Global majors compete with regional champions across chassis scalability and software ecosystem integration. The vendor base clusters around three strategic archetypes: RF measurement heritage players leveraging high-frequency configurations, software-defined instrumentation platforms anchoring aerospace and defense programs, and automated test equipment specialists serving high-throughput production lines. Dominant competitive moves include strategic partnerships for thermal chamber integration and portfolio diversification into cryogenic measurement capabilities.
Within the precision-tier vector, Keysight Technologies and National Instruments occupy positions reflecting divergent platform philosophies. Chroma ATE exemplifies the scale-driven archetype serving high-volume electronics manufacturing clusters in East Asia. These three companies represent the spectrum from RF-integrated configurations to software-centric ecosystems and production-focused automation.
| Leading Market Players |
|---|
| VX Instruments |
| LitePoint |
| National Instruments |
| Tektronix |
| ADLINK Technology |
| Keysight Technologies |
| Marvin Test Solutions |
| Teradyne |
| Chroma ATE |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement committees in Germany and Japan concentrate purchasing power around chassis-scalable PXI SMU platforms, forcing tiered pricing separation between IEC 61010-certified premium configurations and uncertified economy alternatives. This buyer concentration amplifies cost pass-through volatility when precision analog component supply tightens.
Pricing Analysis
Ultra-low-noise operational amplifier and hermetic relay costs pass through directly to module pricing, with Japanese and German specialty suppliers commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels differentiates by certification grade and channel density. Pricing pressure stems from REACH and RoHS compliance acceleration compressing test house margins. Emerging market contract manufacturers exhibit highest price sensitivity, while cryogenic research institutions accept substantial premiums for femtoampere-resolution performance.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Taiwan Semiconductor Manufacturing and Samsung Foundry, while distributor networks serve mid-tier automotive and aerospace programs. Precision analog component fabrication concentrates in Japan and Germany, with final module assembly distributed across Malaysia and Mexico. Raw material dependencies include hermetic relay ceramics, ultra-stable metal film resistors, and low-thermal-EMF copper alloys. Single-source vulnerability for femtoampere-grade operational amplifiers creates structural risk. Distribution runs through authorized technical distributors with calibration certification capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds regulatory demand through the EU Radio Equipment Directive's cybersecurity annex, which mandates secure firmware architectures for CE marking eligibility and reshapes procurement specifications across wireless device test houses.
For Market Incumbents: Anchor platform ecosystem dominance through decade-long driver maintenance commitments that aerospace contractors specify as primary evaluation criteria. Deepen backward integration into precision analog component supply to mitigate Japanese and German supplier concentration. Defend against modular PXI substitution delays in mature power electronics facilities by embedding thermal chamber control loops directly into SMU sequencing engines. For New Entrants and Emerging Players: The premium-to-economy price-point gap in cryogenic measurement capabilities offers white-space entry for specialized high-precision source-measure units serving national laboratory quantum device programs. India's PLI scheme for electronics manufacturing presents the most penetrable geography, with Noida and Chennai contract manufacturers qualifying PXI-based test cells for domestic value-add requirements. Pursue software-defined instrumentation partnerships that integrate with Python-based automation workflows rather than legacy LabVIEW environments. For Investors and Strategic Acquirers: Automated test equipment specialists are the most active acquirer category in this space, consolidating thermal chamber integration capabilities and cryogenic measurement portfolios. Long-term viability centers on quantum computing investment trajectories and wide-bandgap semiconductor adoption curves. Monitor IEC and JEDEC committee draft specifications as the critical inflection signal, as these standards directly determine voltage and current range requirements for next-generation hardware roadmaps.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Platform Integration | Decouples measurement hardware from fixed-function firmware, enabling Keysight and National Instruments to field-upgrade capabilities without chassis replacement. |
| Thermal Chamber Control Loop Integration | Collapses test cell footprint for automotive inverter manufacturers in Munich and Stuttgart validating silicon carbide MOSFETs. |
| Cryogenic Measurement Capability Expansion | Captures concentrated margin pools from national laboratories in New Mexico and Maryland requiring noise floors below ten femtoamperes. |
| Secure Firmware Architecture Development | Maintains CE marking eligibility under EU Radio Equipment Directive cybersecurity annex for test houses in Netherlands and Finland. |
| Backward-Compatible Module Roadmapping | Preserves aerospace contractor software asset library investments across Southern California defense programs. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with test engineering directors at semiconductor fabs, procurement leads at automotive tier-one suppliers, platform architects at aerospace contractors, and calibration laboratory managers with secondary validation. Secondary sources included FCC equipment authorization filings, ECHA REACH registration databases, IEC and JEDEC committee draft specifications, and SEC 10-K disclosures from listed instrumentation vendors. Bottom-up segment sizing triangulated against top-down market reconstruction.
Segment-weighting across product type, technology, end user, and application dimensions shaped volume and value outputs throughout the forecast period. CAGRs derived from regression analysis against semiconductor capital expenditure cycles and wide-bandgap device adoption curves. Industry-specific inputs included wafer-level probe station installation data from Hsinchu and Pyeongtaek fab expansions, plus electric vehicle battery pack current specifications from Japanese and South Korean manufacturers.
Caveats apply where IEC 61010 safety certification timeline extensions or precision analog component supply disruptions could materially shift the outlook. Forecasts reflect documented assumptions regarding wide-bandgap semiconductor test standard finalization and quantum computing research funding trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
AI-Enabled Testing Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Global NVH Testing Market
Test and Measurement
Data Center Testing Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Mud Test Equipment Market
Test and Measurement
Radiation Effects Testing Market
Test and Measurement
High Voltage Testing Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Production Testing Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Fogging Tester Market
Test and Measurement
Leak Testing Market