
 North America Electronic Test and Measurement Market | 2026-2036
North America Electronic Test and Measurement Market Size, Share, and Industry Trends Forecast 2026-2036
North America Electronic Test and Measurement Market Insights
GaN is restructuring power amplifier test requirements as wide-bandgap semiconductors displace silicon in RF and power electronics validation. Keysight Technologies dominates high-frequency signal analyzer architectures for 5G and satellite communications. Tektronix Inc. anchors oscilloscope innovation with deep memory and real-time bandwidth leadership. Rohde & Schwarz GmbH & Co. KG competes in spectrum analyzer precision for aerospace and defense certification.
Electronic test and measurement encompasses instruments that characterize electrical signals across frequency, amplitude, and time domains, typically operating from DC through millimeter-wave bands with resolution down to femtosecond jitter. These systems verify conformance to IEEE, 3GPP, and IPC standards during product development and production. Oscilloscopes and spectrum analyzers lead revenue contribution as 5G deployment and automotive radar development sustain replacement cycles. Automated test technology is displacing manual bench setups in manufacturing quality control, while hybrid analog-digital architectures serve R&D environments requiring flexibility across measurement modes.
FCC equipment authorization rules mandate calibrated test data for wireless device market access, while NHTSA FMVSS validation protocols drive automotive electronics test investment. FDA electromagnetic compatibility requirements for medical devices add a third compliance layer shaping instrument demand. Stakeholders must weigh capital deployment timing against CHIPS Act facility buildout schedules and evolving DOE efficiency standards for power conversion test regimes.
Market Dynamics
GaN and SiC wide-bandgap semiconductors are forcing a wholesale rebuild of power electronics test protocols across automotive and aerospace validation labs, rendering legacy silicon-focused instrumentation obsolete before normal replacement cycles conclude.
Growth Catalysts
- CHIPS Act capital deployment:Federal funding mandates for domestic semiconductor fabrication are accelerating metrology equipment procurement across Texas and Arizona fabrication facilities.
- Electric vehicle powertrain validation:Battery management system and inverter testing requirements are intensifying across Michigan, California, and Ontario assembly operations.
- 5G millimeter-wave certification:FCC equipment authorization rules for sub-6 GHz and mmWave devices are sustaining spectrum analyzer replacement demand.
Market Restraints
- Specialized engineering labor scarcity:RF and high-speed digital test expertise concentrates in Silicon Valley and Boston corridors, constraining facility expansion elsewhere.
- Precision component import exposure:Cryogenic amplifiers and ultra-stable frequency references depend on single-source European and Japanese suppliers.
- Capital intensity threshold:Sub-terahertz vector network analyzers require seven-figure investments that freeze out mid-tier contract manufacturers.
Strategic Opportunities
- Mexico nearshoring test corridors:Automotive OEMs are establishing validation labs in Querétaro and Baja California to support just-in-time supply chains.
- Cloud-native instrument architectures:Software-defined test platforms with remote calibration management are penetrating R&D environments seeking OpEx flexibility.
- DOE efficiency standard alignment:Power conversion test regimes for solar inverters and EV chargers must verify compliance with federal energy conservation mandates.
Industry Challenges
- Multi-standard protocol fragmentation:5G-Advanced, Wi-Fi 7, and UWB coexistence testing demands simultaneous validation against incompatible certification frameworks.
- Calibration traceability complexity:NIST-traceable standards for femtosecond jitter measurement require specialized metrology lab partnerships that extend lead times.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Electronic Test and Measurement Market |
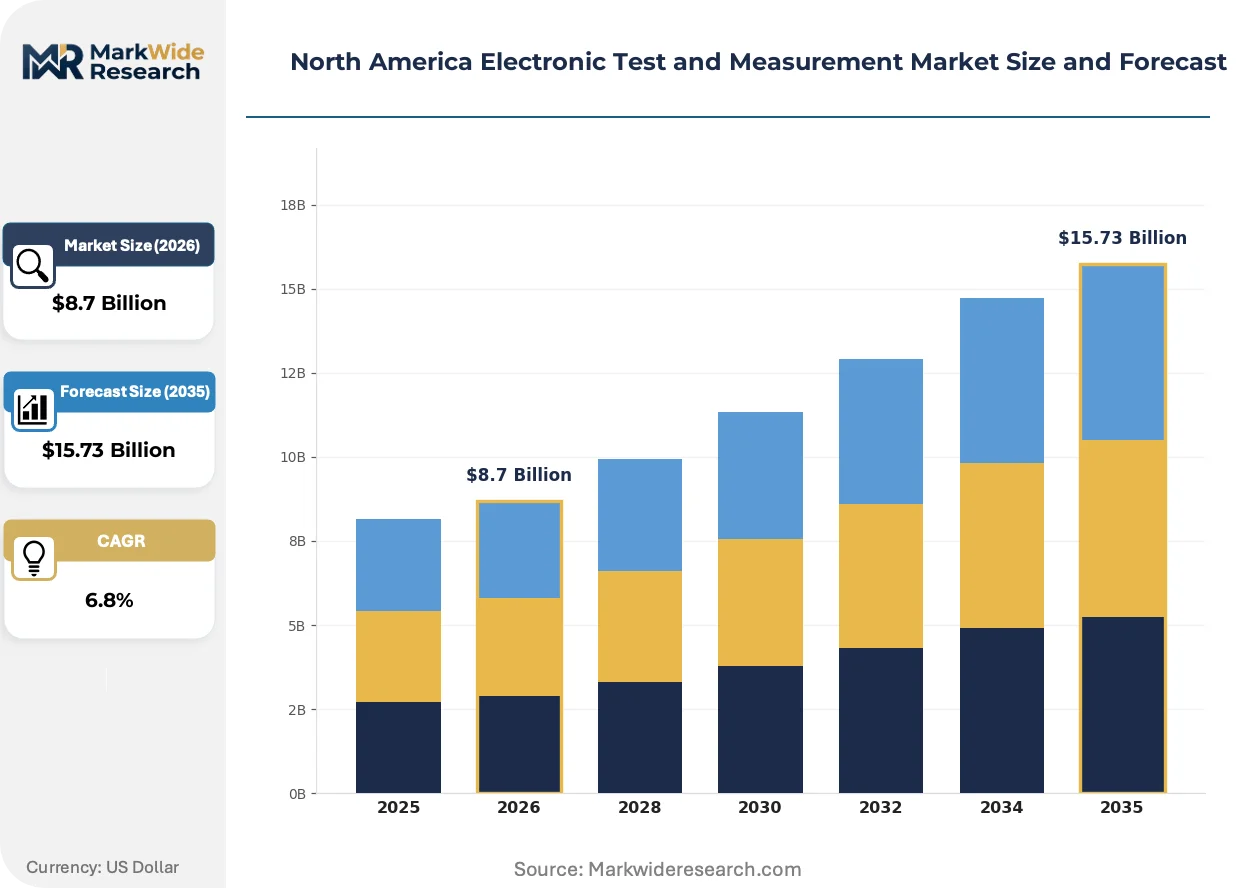
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oscilloscopes, Multimeters, Signal Analyzers, Spectrum Analyzers Technology: Analog, Digital, Hybrid, Automated End User: Telecommunications, Aerospace, Automotive, Education Application: Research & Development, Manufacturing, Quality Control, Maintenance |
| Companies Covered | Keysight Technologies, Tektronix Inc., Rohde & Schwarz GmbH & Co. KG, National Instruments Corporation, Fluke Corporation, Fortive Corporation, AMETEK Inc., Teledyne Technologies Incorporated, Yokogawa Test & Measurement Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Electronic Test and Measurement Market Trends and Innovations
Instrumentation architectures are fragmenting between high-performance R&D platforms and software-abstracted manufacturing cells, with artificial intelligence embedding into measurement interpretation and predictive maintenance workflows.
Software-defined radio technology is modularizing RF test system design, replacing discrete hardware signal generators with reprogrammable FPGA-based architectures. Automotive radar developers in Detroit and Austin are adopting these flexible platforms to compress validation cycles for 77-81 GHz sensors. The approach is modularizing supply chains by decoupling hardware acquisition from protocol-specific test routine development.
NHTSA FMVSS validation protocols for automated driving systems are mandating electromagnetic immunity test documentation that exceeds baseline FCC requirements. Automotive tier-1 suppliers must now demonstrate subsystem-level RF resilience across multiple threat scenarios. The regulation is most affecting lidar and camera module manufacturers in Ontario and California, which are investing in anechoic chamber capacity ahead of 2025 model year certifications.
Capital equipment purchasing is consolidating under centralized procurement functions at major semiconductor and automotive OEMs, displacing distributed engineering-led acquisition. Authorized distributors and manufacturer-direct enterprise teams are competing for sole-source agreements with multi-year calibration service bundles. This concentration is most visible across Arizona and Texas fab construction sites, where general contractors are negotiating master service agreements covering thousands of instrument seats.
North America Electronic Test and Measurement Market Segmentation
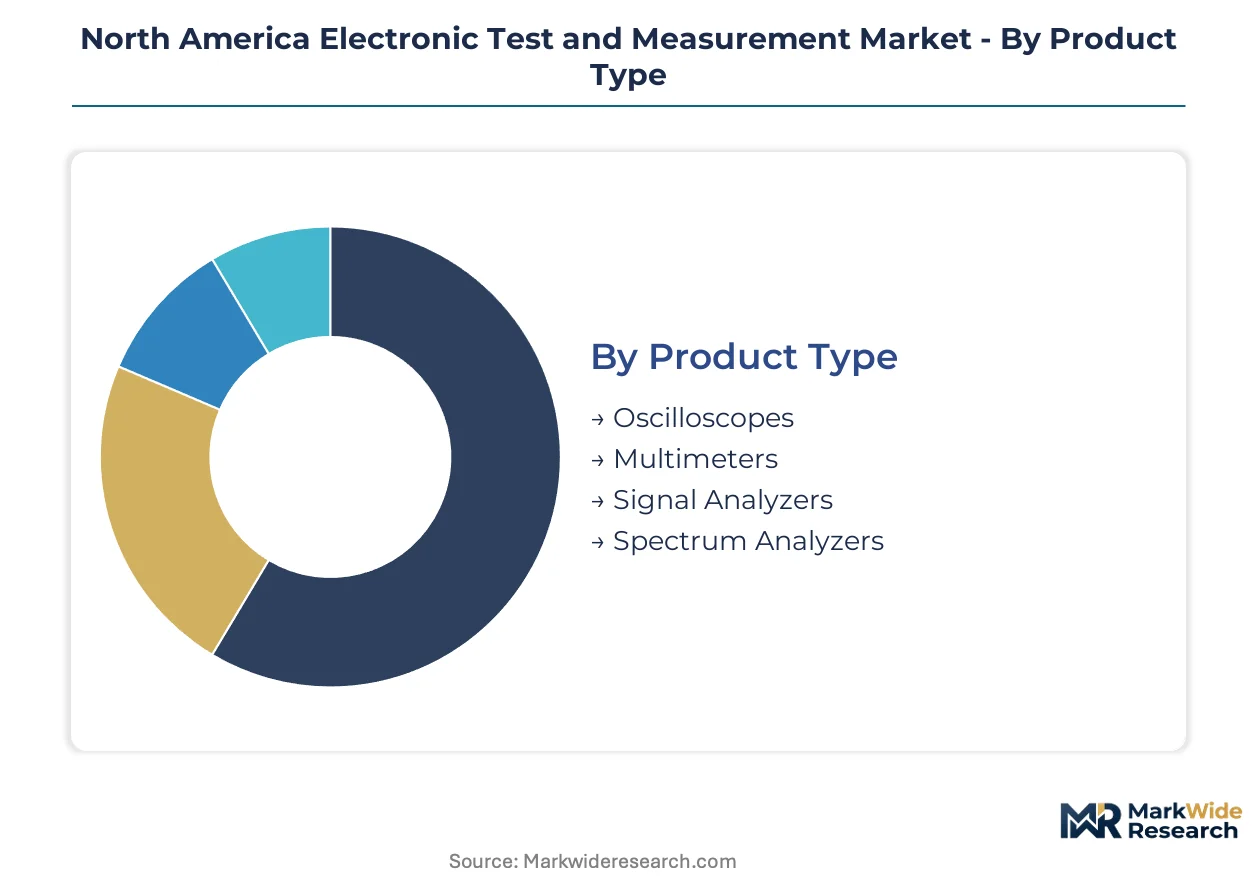
Test instrumentation purchasing patterns diverge sharply across end-use environments, with semiconductor fabs demanding multi-million-dollar metrology suites while contract manufacturers prioritize rapid throughput over precision. The CHIPS Act buildout across Texas and Arizona fabs is concentrating capital deployment into specific product categories and technology tiers.
Product Type:
Buyers differentiate primarily by signal domain requirements, with RF validation labs prioritizing frequency resolution and power electronics developers emphasizing time-domain precision.
- Oscilloscopes:Real-time bandwidth and deep memory architectures dominate R&D procurement in Detroit automotive radar labs and Austin semiconductor design centers. Keysight and Tektronix compete for socket position in 77-81 GHz sensor validation workflows where femtosecond jitter measurement is mandatory.
- Signal Analyzers:Vector signal analysis capability for 5G-Advanced and satellite communications certification sustains replacement demand among FCC equipment authorization test houses. Sub-6 GHz and mmWave modulation analysis requirements are forcing architecture upgrades in California and Ontario wireless labs.
- Spectrum Analyzers:Phase noise performance determines competitive positioning for aerospace and defense contractors in Arizona and Texas.
- Multimeters:Six-and-a-half-digit precision units anchor benchtop setups in education and maintenance environments.
Oscilloscopes lead volumes today; signal analyzers are gaining share fastest.
Technology:
Capital intensity and calibration complexity separate procurement tiers, with automated platforms commanding enterprise-wide deployment and analog instruments retaining niche flexibility.
- Automated:Software-defined architectures with remote calibration management are penetrating Michigan and Ontario automotive validation facilities seeking OpEx flexibility. Python and C# API accessibility allows test routine standardization across distributed manufacturing sites.
- Hybrid:Analog-digital architectures serve R&D environments in Silicon Valley and Boston corridors requiring measurement mode flexibility without full software abstraction. These platforms bridge legacy protocol support and emerging wide-bandgap semiconductor characterization.
- Digital:FPGA-based signal processing dominates high-volume manufacturing test cells in Mexico nearshoring corridors.
- Analog:Direct hardware control persists in education and troubleshooting applications where immediate signal visibility outweighs throughput.
Automated systems lead volumes today; hybrid platforms are expanding most quickly.
End User:
Regulatory compliance burden and certification timeline urgency shape purchasing authority, with automotive and aerospace buyers centralizing procurement under enterprise metrology functions.
- Automotive:NHTSA FMVSS validation protocols for automated driving systems mandate electromagnetic immunity documentation exceeding baseline FCC requirements. Tier-1 suppliers in Michigan and Ontario are investing in anechoic chamber capacity ahead of model year certifications for lidar and camera modules.
- Aerospace:DO-160 environmental testing and MIL-STD-461 compliance drive spectrum analyzer precision requirements among defense contractors in Arizona and California. ITAR-controlled calibration traceability constrains supplier selection to domestic or allied-country sources.
- Telecommunications:FCC equipment authorization rules sustain demand for calibrated test data among sub-6 GHz and mmWave device developers.
- Education:University labs in Texas and California prioritize cost-effective benchtop instrumentation for undergraduate instruction.
Automotive leads volumes today; aerospace is climbing the fastest.
Application:
Time-to-market pressure versus measurement precision requirements determines instrumentation architecture selection across the product lifecycle.
- Research & Development:Flexibility across measurement modes and protocol standards is paramount in semiconductor design centers and automotive radar development labs. Engineers demand rapid reconfiguration between 5G, Wi-Fi 7, and UWB coexistence testing without hardware swaps.
- Manufacturing:Throughput optimization and test cell integration dominate procurement criteria in Arizona and Texas fab construction sites. General contractors negotiate master service agreements covering thousands of instrument seats with multi-year calibration bundles.
- Quality Control:Automated pass-fail determination with statistical process control integration is standard in Mexico automotive supplier corridors.
- Maintenance:Portability and ruggedized construction prioritize field service applications in utility and transportation infrastructure.
Manufacturing leads volumes today; R&D is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas-Arizona semiconductor corridor is reshaping capital deployment patterns across the North American test and measurement landscape.
United States
CHIPS Act funding is accelerating metrology equipment procurement across Texas and Arizona fabrication facilities. FCC equipment authorization rules mandate calibrated test data for wireless device market access, sustaining spectrum analyzer demand. Detroit automotive radar labs and Austin semiconductor design centers are expanding 77-81 GHz sensor validation capacity.
Canada
Ontario's automotive tier-1 suppliers are investing in anechoic chamber capacity ahead of model year certifications for lidar and camera modules. Health Canada electromagnetic compatibility requirements for medical devices add a compliance layer shaping instrument demand. Toronto and Ottawa validation corridors are concentrating RF test expertise for aerospace and defense contractors.
Mexico
Automotive OEMs are establishing validation labs in Querétaro and Baja California to support just-in-time supply chains. The country's national trade and industrial development programs are incentivizing test infrastructure co-location with assembly operations. Mexico nearshoring corridors are prioritizing automated pass-fail determination with statistical process control integration.
North America Electronic Test and Measurement Market Competitive Landscape
Global majors compete with regional champions across technology tiers and end-use specializations. The vendor base stratifies between high-frequency R&D platforms and manufacturing-optimized cells. Three archetypes dominate: full-stack instrumentation houses, software-defined test specialists, and precision component suppliers. Competitive positioning hinges on multi-year calibration service bundles and sole-source enterprise agreements.
Within the full-stack instrumentation tier, Keysight Technologies and Tektronix Inc. exemplify high-frequency signal analyzer and oscilloscope leadership respectively. Rohde & Schwarz GmbH & Co. KG occupies a position representing spectrum analyzer precision for aerospace and defense certification. These anchors demonstrate how geographic origin and corporate structure shape competitive archetype representation across the North American market.
| Leading Market Players |
|---|
| Keysight Technologies |
| Tektronix Inc. |
| Rohde & Schwarz GmbH & Co. KG |
| National Instruments Corporation |
| Fluke Corporation |
| Fortive Corporation |
| AMETEK Inc. |
| Teledyne Technologies Incorporated |
| Yokogawa Test & Measurement Corporation |
| Others |
Pricing and Supply Chain Analysis
DOE efficiency standards for power conversion test regimes gate qualified supply and premium-tier pricing access, as calibration traceability to NIST-traceable femtosecond jitter standards constrains vendor qualification and justifies seven-figure instrument premiums.
Pricing Analysis
Input-cost pass-through from cryogenic amplifiers and ultra-stable frequency references anchors instrument pricing, with phase noise performance and femtosecond jitter resolution driving tiered premiums. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-grade spectrum analyzers from manufacturing-optimized cells. Cost compression in mid-tier contract manufacturing is intensifying because capital intensity thresholds freeze out sub-terahertz vector network analyzer procurement. Automotive OEMs exhibit highest price sensitivity due to centralized procurement consolidation, while aerospace defense contractors show lowest sensitivity given ITAR-controlled sole-source mandates.
Supply Chain Analysis
Dual-sourcing requirements for precision components mandate multi-supplier qualification across cryogenic amplifiers from European sources and ultra-stable frequency references from Japanese suppliers. Geographic supply concentration centers on Germany, Japan, and the United States for high-frequency signal analyzer architectures. Raw material dependencies include FPGA chipsets, specialized RF connectors, and precision quartz substrates. Single-source vulnerability persists in sub-terahertz calibration standards. Distribution runs through authorized distributors competing with manufacturer-direct enterprise teams for sole-source agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as GaN and SiC wide-bandgap semiconductor validation demands restructure procurement toward premium-specification metrology suites.
For Market Incumbents: Acquire calibration service infrastructure to lock in multi-year enterprise agreements before CHIPS Act facility buildouts conclude. Backward integration into NIST-traceable metrology lab partnerships defends against lead time extension threats. Channel control through sole-source master service agreements covering thousands of instrument seats at Texas and Arizona fab sites anchors replacement cycle capture. For New Entrants and Emerging Players: CHIPS Act capital deployment in the United States opens a window for software-defined test platforms with remote calibration management targeting Michigan and Ontario automotive validation facilities seeking OpEx flexibility. Mexico nearshoring corridors in Querétaro and Baja California represent the most penetrable geography. Python and C# API accessibility serves as the primary go-to-market angle for test routine standardization across distributed manufacturing sites. For Investors and Strategic Acquirers: Roll-up economics work for precision component specialists because single-source dependencies in cryogenic amplifiers and frequency references create captive supply value. The five-to-ten year viability window favors targets with ITAR-controlled calibration traceability and aerospace certification depth. Watch for CHIPS Act facility completion rates as the inflection indicator for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Infrastructure Acquisition | NIST-traceable partnerships lock in multi-year enterprise agreements at Texas and Arizona fabs. |
| Software-Defined Test Platform Launch | Remote calibration management penetrates Michigan automotive facilities seeking OpEx flexibility. |
| Mexico Nearshoring Corridor Expansion | Querétaro and Baja California validation labs support just-in-time automotive supply chains. |
| Wide-Bandgap Semiconductor Protocol Development | GaN and SiC test routine libraries capture replacement demand from obsolete silicon-focused instrumentation. |
| Anechoic Chamber Capacity Buildout | NHTSA FMVSS validation mandates drive Ontario and California lidar module certification investment. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each combining interviews with semiconductor fab metrology directors, automotive tier-1 supplier procurement leads, aerospace defense contractor test engineers, and authorized distributor channel managers. Secondary validation draws from FCC equipment authorization databases, NHTSA FMVSS validation protocols, CHIPS Act funding disclosure filings, and SEC 10-K instrument procurement disclosures. Bottom-up instrument shipment analysis and top-down capital expenditure triangulation anchor market sizing.
Rate-of-change decomposition separates volume effects from mix shifts across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user industry, and application lifecycle stage. CAGRs derive from instrument replacement cycle analysis and capital deployment tracking. CHIPS Act facility buildout schedules and DOE efficiency standard implementation timelines feed forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CHIPS Act funding disbursement delays or NHTSA protocol acceleration. Deviation in wide-bandgap semiconductor adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Rohs Tester Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
X-Ray Inspection System for Secondary Battery Market
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
AI Inference Hardware Performance Benchmarking Test Systems Market
Test and Measurement
Ultrasonic Flaw Detector Market
Test and Measurement
Electromagnetic NDT Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Global Non-Destructive Testing and Inspection Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Analog Multimeters Market
Test and Measurement
Dew Point Apparatus Market
Test and Measurement
Solar Clamp Meter Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Microhardness Testing System Market