
 In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market | 2026-2036
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market Insights
Equipment leasing and pay-per-build financing is fragmenting competitive access across the additive manufacturing quality assurance landscape. Bruker leverages its installed base of precision metrology systems to extend service contracts into layer-by-layer monitoring subscriptions. EOS anchors European demand through captive integration of optical sensors into its metal powder bed fusion platforms. Phase3D competes by specializing in fringe-projection photogrammetry for research institutes with limited capital budgets.
In-situ layer-by-layer AM defect monitoring test equipment comprises sensor-integrated systems that capture dimensional, thermal, and acoustic data between successive build layers during additive manufacturing, typically resolving anomalies at 10–50 micron scales to enable real-time process correction or build termination. Its primary commercial purpose is eliminating post-build destructive testing for certified components in regulated industries. Optical sensors dominate current equipment type revenue due to mature CMOS and laser triangulation supply chains, while thermal cameras represent the fastest-growing category as infrared thermography penetrates aerospace qualification protocols. Digital image correlation technology leads structural segment margins because algorithm licensing creates recurring revenue streams distinct from hardware sales cycles.
The FAA and EASA mandate process traceability documentation for flight-critical additively manufactured parts, directly shaping sensor architecture requirements and validation protocols for equipment vendors seeking airframe manufacturer qualification. FDA guidance on 3D-printed medical implants similarly drives thermal camera and ultrasonic testing adoption within quality control labs serving orthopedic device firms. Stakeholders must monitor evolving ISO/ASTM standards for in-situ data archiving formats, as interoperability certifications will determine which technology platforms capture multi-industry procurement contracts across manufacturing facilities and additive foundries.
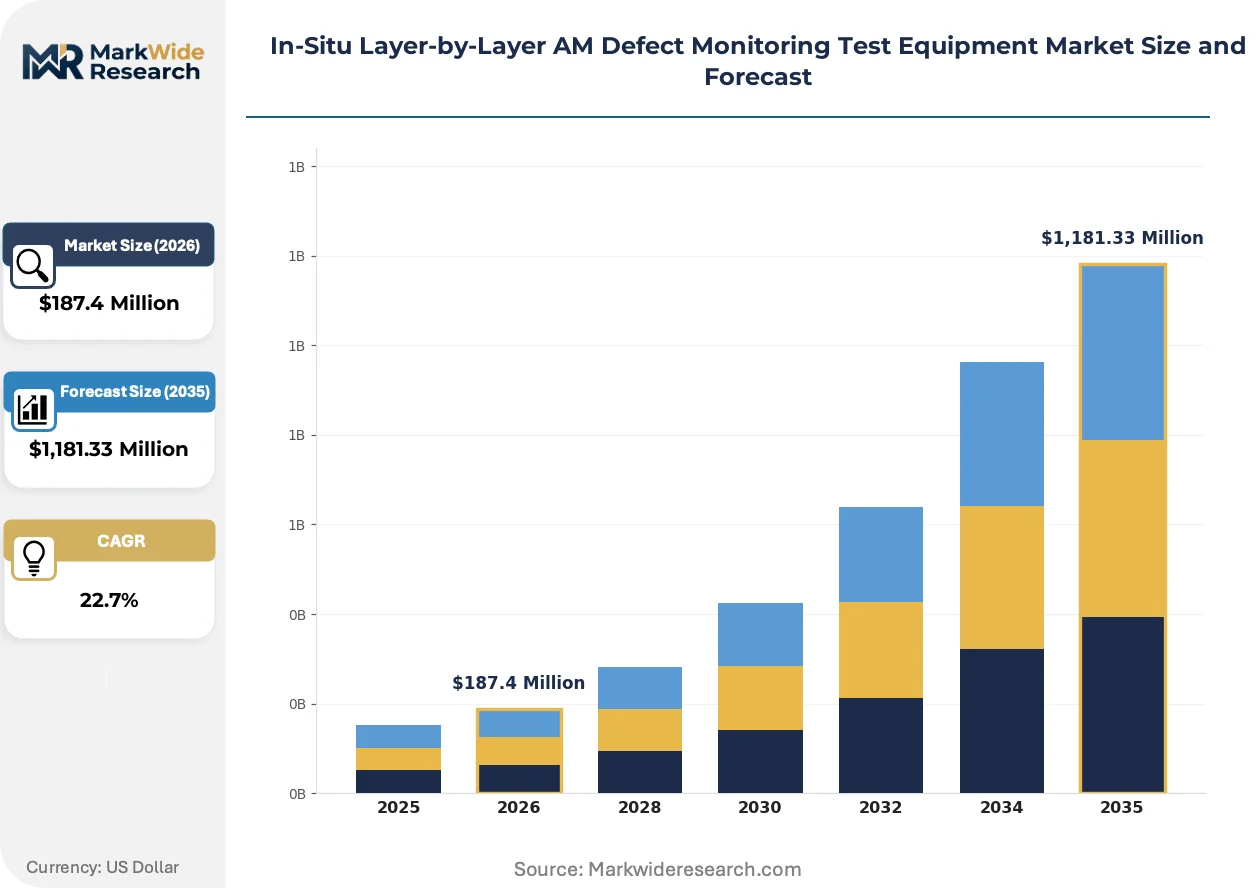
Market Dynamics
The FAA and EASA process traceability mandates for flight-critical additively manufactured parts are compressing sensor architecture development cycles and forcing equipment vendors to revalidate qualification protocols before airframe manufacturer procurement decisions.
Growth Catalysts
- Flight-critical certification mandates:FAA airworthiness directives now require layer-by-layer documentation for titanium and nickel superalloy components in turbine applications, eliminating post-build destructive testing workflows.
- Germany:EOS and SLM Solutions anchor production ecosystems in Munich and Lübeck, pushing optical sensor integration deeper into metal powder bed fusion platforms and creating concentrated demand for thermal camera retrofits.
- Infrared thermography:Aerospace qualification protocols now specify real-time thermal gradient mapping for defect detection in Inconel 718 builds, accelerating hardware refresh cycles among tier-one suppliers.
Market Restraints
- High-purity optical component costs:Germanium lenses and cooled MWIR detectors for thermal cameras face supply concentration among three Japanese specialty glass manufacturers, creating input price volatility.
- Algorithm validation timelines:Machine learning-based anomaly detection requires 18-24 month FDA premarket notification pathways for orthopedic implant applications, extending commercialization cycles.
- Limited qualified technician pools:Photogrammetry calibration and acoustic emission interpretation demand hybrid skill sets spanning materials science and signal processing, constraining deployment velocity at contract manufacturers.
Strategic Opportunities
- Research institute channel expansion:Fringe-projection photogrammetry vendors can bypass capital budget constraints through equipment leasing models targeting university additive manufacturing centers with limited grant funding.
- Medical device thermal camera adoption:FDA guidance on 3D-printed implants creates procurement pull for ultrasonic testing and infrared monitoring within orthopedic device quality control labs.
- ISO/ASTM interoperability certification:Vendors securing early validation for in-situ data archiving formats will capture multi-industry contracts across manufacturing facilities and additive foundries as standardization consolidates.
Industry Challenges
- Multi-sensor fusion complexity:Integrating optical, thermal, and acoustic data streams into unified defect classification algorithms requires specialized firmware development teams that compete with autonomous vehicle and semiconductor sectors for talent.
- Legacy MES integration friction:Layer-by-layer monitoring systems must interface with existing manufacturing execution software from Siemens, Dassault, and SAP, creating custom API development costs that erode hardware margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,181.33 Million |
| CAGR (2026 – 2036) | 22.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Optical Sensors, Acoustic Emission Sensors, Thermal Cameras, Laser Scanners Technology: Infrared Thermography, Ultrasonic Testing, Laser Triangulation, Digital Image Correlation Application: Aerospace Components, Medical Implants, Industrial Tooling, Automotive Parts End User: Manufacturing Facilities, Research Institutes, Quality Control Labs, Additive Foundries |
| Companies Covered | EOS, Renishaw, SLM Solutions, Nikon SLM Solutions, GE Additive, 3D Systems, Bruker, Phase3D, Wayland Additive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market Trends and Innovations
Real-time process correction capabilities are reshaping competitive positioning among equipment vendors, with algorithm licensing models displacing pure hardware sales and service contract structures fragmenting across end-use verticals.
Digital image correlation technology is digitizing dimensional validation workflows by capturing full-field surface deformation data between build layers at 10-50 micron resolution. Aerospace component manufacturers in Germany and the United States are adopting this technology fastest for titanium alloy qualification. The shift is digitizing revenue models away from one-time equipment sales toward recurring software license fees tied to build volume.
EASA's evolving framework for AM part certification is forcing thermal camera architecture redesigns to include redundant temperature reference points and encrypted data logging. European airframe manufacturers now specify these requirements in supplier quality agreements. Medical device firms serving the European market are pre-emptively adopting identical specifications to streamline future MDR compliance.
Pay-per-build financing is displacing traditional capital expenditure procurement among contract manufacturers with irregular production schedules. Equipment lessors are capturing mid-market customers previously excluded by six-figure hardware price points. This model is most visible in the United States, where aerospace job shops face unpredictable order flows from defense primes and commercial satellite constellation programs.
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market Segmentation
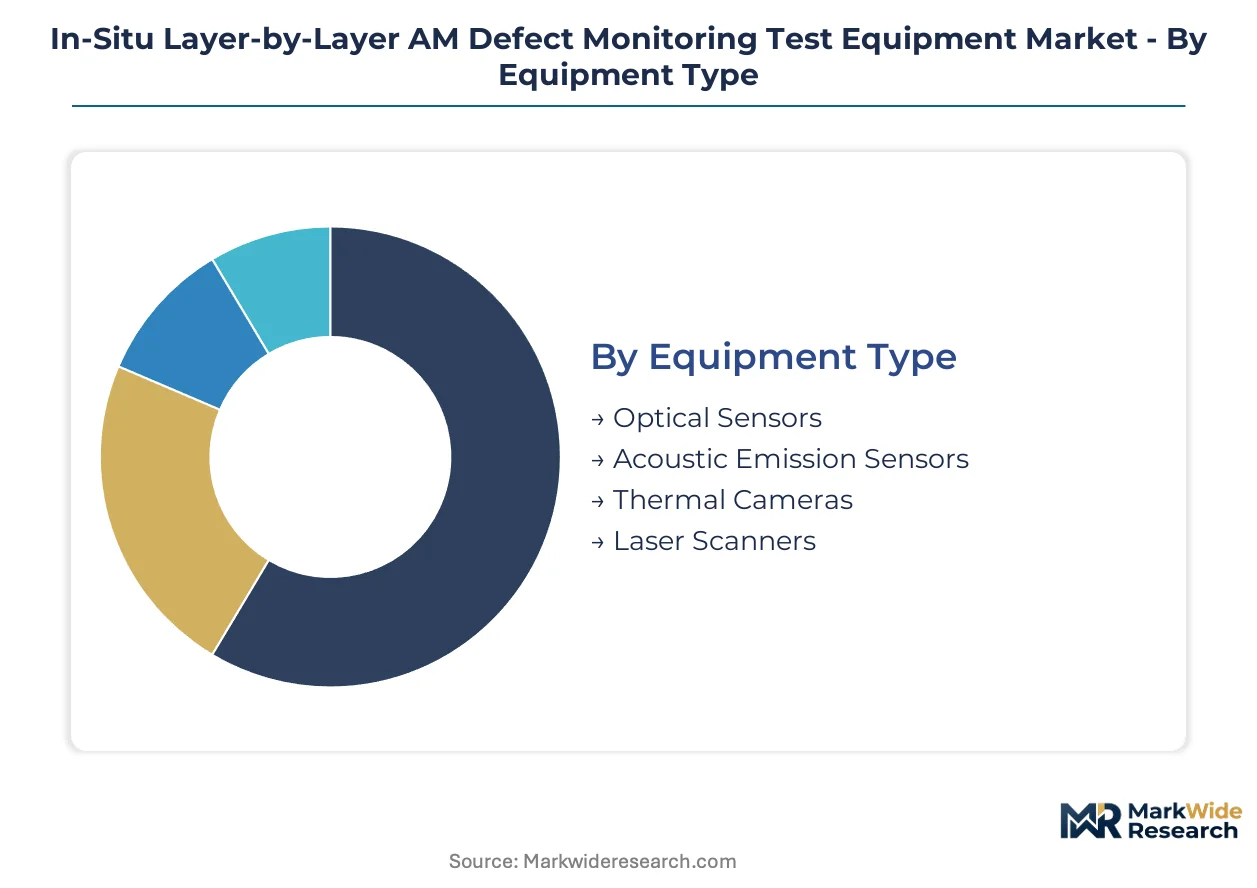
Equipment architecture and procurement patterns fragment sharply across end-use verticals. Sensor modality selection follows regulatory certification requirements rather than pure technical performance, creating divergent technology stacks across aerospace, medical, and industrial segments.
Equipment Type:
Cost tier determines procurement velocity, with premium thermal systems facing capital budget friction against mature optical platforms.
- Optical Sensors:CMOS and laser triangulation systems capture dimensional anomalies at 10-50 micron resolution through mature supply chains. Aerospace manufacturers in Germany specify these for titanium alloy qualification workflows, though thermal retrofits are displacing legacy installations.
- Thermal Cameras:Cooled MWIR detectors with germanium lenses enable real-time thermal gradient mapping for defect detection in Inconel 718 builds. EASA qualification protocols now mandate redundant temperature reference points, accelerating hardware refresh cycles among tier-one European suppliers.
- Acoustic Emission Sensors:Piezoelectric arrays detect crack propagation signatures during metal powder bed fusion. Research institutes deploy these for fundamental process physics studies.
- Laser Scanners:Fringe-projection systems deliver full-field surface capture for dimensional validation. Quality control labs favor these for post-build verification rather than in-situ integration.
Optical sensors hold installed capacity. Thermal cameras are rotating up the share rankings.
Technology:
Application specificity drives technology selection, with aerospace thermal protocols diverging from medical ultrasonic requirements.
- Infrared Thermography:Real-time thermal gradient mapping penetrates aerospace qualification protocols for nickel superalloy components. FAA airworthiness directives specify this modality for flight-critical part documentation, creating procurement pull from turbine manufacturers.
- Digital Image Correlation:Full-field surface deformation algorithms generate recurring software license revenue distinct from hardware sales. EOS and SLM Solutions integrate this technology into captive metal powder bed fusion platforms for dimensional validation.
- Ultrasonic Testing:Phased-array probes detect subsurface porosity in titanium medical implants. FDA premarket notification pathways extend commercialization cycles for machine learning-enhanced variants.
- Laser Triangulation:Point-cloud generation supports layer height verification at production speeds. Contract manufacturers deploy these for cost-sensitive industrial tooling applications.
Digital image correlation commands margin premiums. Infrared thermography is climbing the fastest.
Application:
Volume concentration varies by certification burden, with flight-critical components demanding exhaustive documentation against lighter industrial requirements.
- Aerospace Components:Titanium and nickel superalloy turbine parts require layer-by-layer traceability documentation under FAA and EASA mandates. Tier-one suppliers in Germany and the United States absorb six-figure equipment costs to eliminate destructive testing workflows.
- Medical Implants:3D-printed orthopedic devices drive thermal camera and ultrasonic testing adoption within quality control labs. FDA guidance on process validation creates procurement pull distinct from European MDR compliance timelines.
- Industrial Tooling:Mold inserts and cutting tools prioritize throughput over exhaustive monitoring. Pay-per-build financing penetrates this segment fastest among contract manufacturers with irregular production schedules.
- Automotive Parts:Series production qualification for aluminum structural components lags aerospace adoption. NHTSA has not issued additive manufacturing-specific directives comparable to FAA airworthiness requirements.
Aerospace components anchor revenue concentration. Medical implants are rotating up the share rankings.
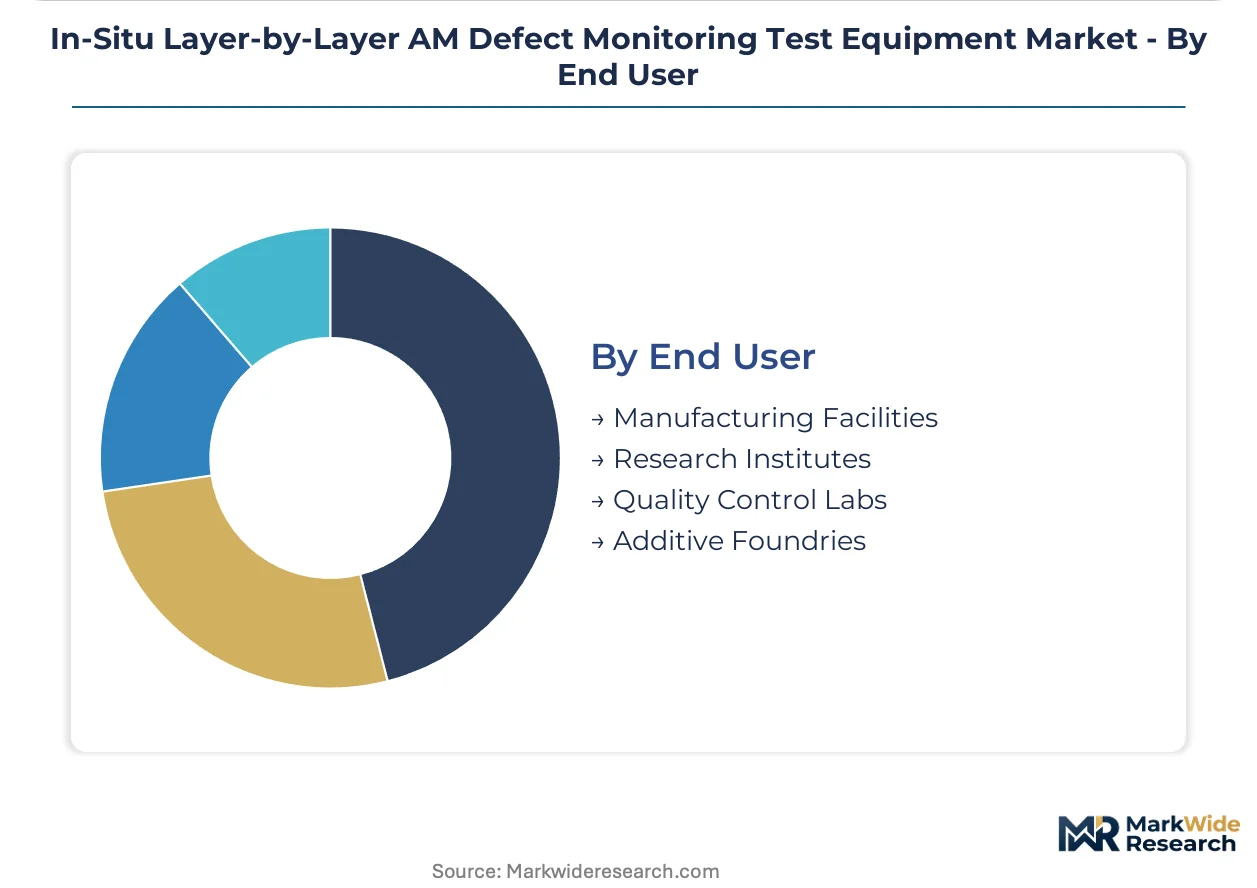
End User:
Customer type shapes pricing architecture, with capital constraints fragmenting access across institutional categories.
- Manufacturing Facilities:Airframe and orthopedic device producers integrate monitoring systems directly into production lines. Siemens, Dassault, and SAP manufacturing execution software integration creates custom API development costs.
- Quality Control Labs:Independent testing houses serve multi-client validation requirements. Equipment leasing models penetrate this channel to bypass capital expenditure thresholds.
- Research Institutes:University additive manufacturing centers with limited grant funding favor fringe-projection photogrammetry. Phase3D competes here through specialized equipment configurations.
- Additive Foundries:Contract manufacturers serving defense primes and satellite constellation programs face unpredictable order flows. Pay-per-build financing captures mid-market customers previously excluded by upfront hardware costs.
Manufacturing facilities hold installed capacity. Additive foundries are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The export-import balance tilts toward equipment deficit in aerospace-dependent economies, while manufacturing clusters in Germany and the United States absorb premium-tier systems faster than domestic supply can satisfy. Capital flows concentrate where regulatory pressure from aviation authorities intersects with established metal additive manufacturing infrastructure.
United States
FAA airworthiness directives for titanium turbine components drive procurement of thermal camera systems among tier-one aerospace suppliers. The agency mandates layer-by-layer traceability documentation for flight-critical parts, compressing validation timelines for equipment vendors. Greater Boston and Pacific Northwest manufacturing clusters absorb six-figure hardware investments to eliminate destructive testing workflows for defense and satellite programs.
Germany
EASA qualification protocols for nickel superalloy builds specify redundant temperature reference points in thermal camera architectures, accelerating hardware refresh cycles. EOS and SLM Solutions anchor production ecosystems in Munich and Lübeck, pushing optical sensor integration deeper into metal powder bed fusion platforms. Bavarian aerospace suppliers pre-emptively adopt encrypted data logging specifications to streamline future certification compliance.
United Kingdom
UK Research and Innovation funding streams support university additive manufacturing centers with limited capital budgets, creating demand for fringe-projection photogrammetry systems. The country's national aerospace regulator aligns with EASA frameworks for process traceability documentation. Midlands-based contract manufacturers serving defense primes face unpredictable order flows, accelerating pay-per-build financing adoption.
Japan
METI industrial technology grants subsidize sensor integration into metal powder bed fusion platforms for domestic machine tool builders. The country's national pharmaceutical regulator emphasizes process validation documentation for orthopedic implant applications, extending commercialization cycles for machine learning-enhanced detection systems. Nagoya-area automotive suppliers lag aerospace adoption due to absent NHTSA-equivalent additive manufacturing directives.
China
MIIT smart manufacturing initiatives channel state funding toward domestic equipment vendors seeking to reduce import dependence for high-purity optical components. The national aviation regulator develops indigenous airworthiness standards for additively manufactured flight-critical parts, creating parallel certification pathways. Yangtze River Delta industrial clusters prioritize throughput over exhaustive monitoring for mold insert and cutting tool applications.
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market Competitive Landscape
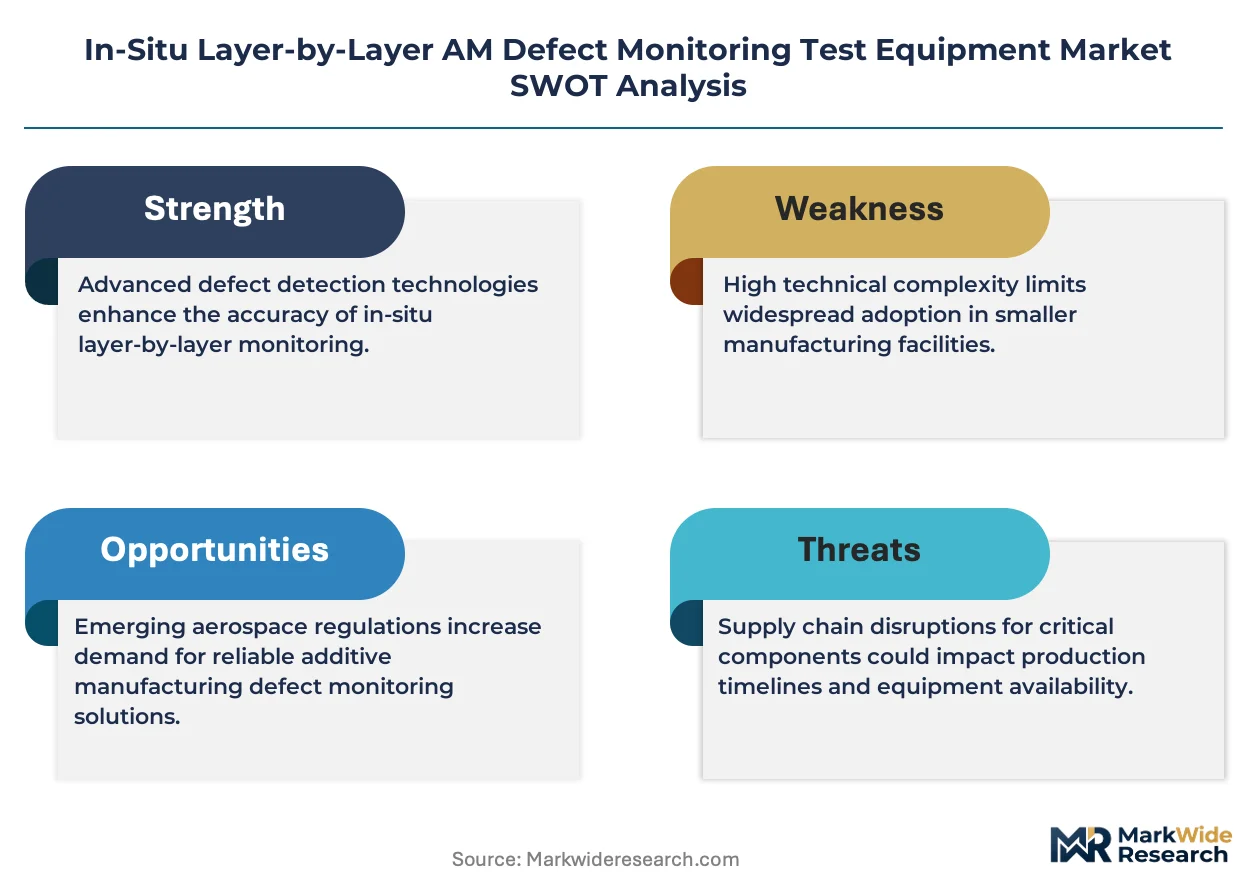
On the supply side, the industry is consolidating around equipment vendors with captive additive manufacturing platform integration and specialized sensor developers serving capital-constrained research channels. Three strategic archetypes dominate: integrated system builders embedding monitoring into metal powder bed fusion hardware; precision metrology incumbents extending service contracts into layer-by-layer subscriptions; and fringe-projection specialists targeting university grant funding cycles. Dominant competitive moves include strategic partnerships between sensor developers and manufacturing execution software providers, plus technology licensing arrangements that monetize algorithm IP separately from hardware sales.
Among integrated system builders, EOS and SLM Solutions exemplify the captive platform strategy, embedding optical and thermal sensors directly into production equipment to control the full workflow stack. Bruker occupies a position within the precision metrology tier, leveraging installed base relationships to extend recurring service revenue into monitoring subscriptions. Phase3D represents the research-channel specialization archetype, configuring fringe-projection systems for additive manufacturing centers with limited capital budgets.
| Leading Market Players |
|---|
| EOS |
| Renishaw |
| SLM Solutions |
| Nikon SLM Solutions |
| GE Additive |
| 3D Systems |
| Bruker |
| Phase3D |
| Wayland Additive |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on Japanese specialty glass manufacturers for germanium lenses and cooled MWIR detectors compresses margin structures across thermal camera tiers while forcing buyers into long-term offtake commitments that lock in pricing spreads between premium aerospace-qualified systems and research-grade alternatives.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation hinges on EASA certification grade and after-sales service bundling, with encrypted data logging and redundant temperature reference points commanding substantial premiums. Cost compression in the economy tier is intensifying because research institutes with limited grant funding negotiate aggressive leasing terms. Contract manufacturers serving defense primes exhibit the highest price sensitivity, while tier-one aerospace suppliers absorb premium pricing to eliminate destructive testing workflows.
Supply Chain Analysis
Export-control restrictions on high-purity optical components limit technology flows from Japan to European and North American equipment vendors. Manufacturing concentrates in Japan, Germany, and the United States, with germanium lens fabrication and cooled MWIR detector assembly drawing from concentrated specialty glass supply. Single-source vulnerability in Japanese substrate production creates exposure to input price volatility. Distribution runs through direct OEM partnerships for integrated systems and specialized distributors for research-channel photogrammetry equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment creates substantial switching costs for certified equipment vendors serving flight-critical aerospace applications.
For Market Incumbents: Entrench platform dominance by embedding optical and thermal sensors into captive metal powder bed fusion hardware before emerging fringe-projection specialists capture research-to-production upgrade pathways. Deepen backward integration into sensor calibration services to offset margin pressure from algorithm licensing commoditization. Prioritize encrypted data logging certification investments that align with evolving EASA specifications. For New Entrants and Emerging Players: China's Yangtze River Delta industrial clusters offer underpenetrated entry points where domestic equipment vendors prioritize throughput over exhaustive monitoring for mold insert applications. Target pay-per-build financing models for additive foundries with irregular production schedules. Pursue university additive manufacturing centers through specialized fringe-projection configurations that bypass capital expenditure thresholds. For Investors and Strategic Acquirers: EASA's evolving framework for AM part certification reshapes the acquisition landscape toward vendors with validated in-situ data archiving formats. Long-term viability centers on algorithm IP monetization separate from hardware sales cycles. Target precision metrology incumbents with installed base relationships extensible into layer-by-layer monitoring subscriptions. Watch for ISO/ASTM interoperability certification announcements as inflection indicators for multi-industry contract capture.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Platform Integration | EOS and SLM Solutions embed optical sensors into metal powder bed fusion workflows to control full production stacks. |
| Algorithm Licensing Model | Digital image correlation vendors monetize software IP separately from hardware through recurring build-volume fees. |
| Equipment Leasing Expansion | Pay-per-build financing captures mid-market contract manufacturers excluded by six-figure capital expenditure requirements. |
| Regulatory Certification Investment | Encrypted data logging and redundant temperature architectures preempt EASA qualification protocol mandates. |
| Research Channel Specialization | Fringe-projection photogrammetry vendors configure systems for university centers with limited grant funding cycles. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, equipment vendor technical documentation, and aerospace manufacturer qualification protocols. Primary interviews engaged additive manufacturing platform engineers, quality control lab directors, and procurement leads at tier-one aerospace suppliers. Secondary sources encompassed FAA airworthiness directives, EASA certification frameworks, FDA premarket notification databases, and ISO/ASTM standard development records. Bottom-up equipment shipment analysis triangulates against top-down market sizing derived from metal powder bed fusion installed base expansion.
Forecast inputs include equipment type segmentation across optical sensors, thermal cameras, acoustic emission arrays, and laser scanners; technology segmentation spanning infrared thermography, digital image correlation, ultrasonic testing, and laser triangulation; and end-use verticals encompassing aerospace components, medical implants, industrial tooling, and automotive parts. CAGRs were derived from regression analysis against regulatory mandate implementation timelines and metal additive manufacturing capacity expansion. Industry-specific inputs incorporate EASA qualification protocol adoption curves and FDA premarket notification pathway durations for machine learning-enhanced detection systems.
Macroeconomic conditions sit as an overlay; deviation in defense procurement cycles, aerospace production backlogs, or medical device R&D spending would shift the trajectory. Forecasts reflect assumptions regarding regulatory mandate enforcement consistency and sensor component supply chain stability. Material shifts in export-control regimes or indigenous airworthiness standard development in China would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Silicon Photonics and Optical I/O Test and Measurement Systems Market
Test and Measurement
Power Semiconductor Wafer-Level Reliability Test Equipment Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Impedance Tester Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Megohmmeters Market
Test and Measurement
Metrology Systems Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Production Testing Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Battery Test Equipment Market
Test and Measurement
Metrology Software Market
Test and Measurement
Resistivity Meters Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Mud Test Equipment Market