
 Global NVH Testing Market | 2026-2036
Global NVH Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global NVH Testing Market Outlook
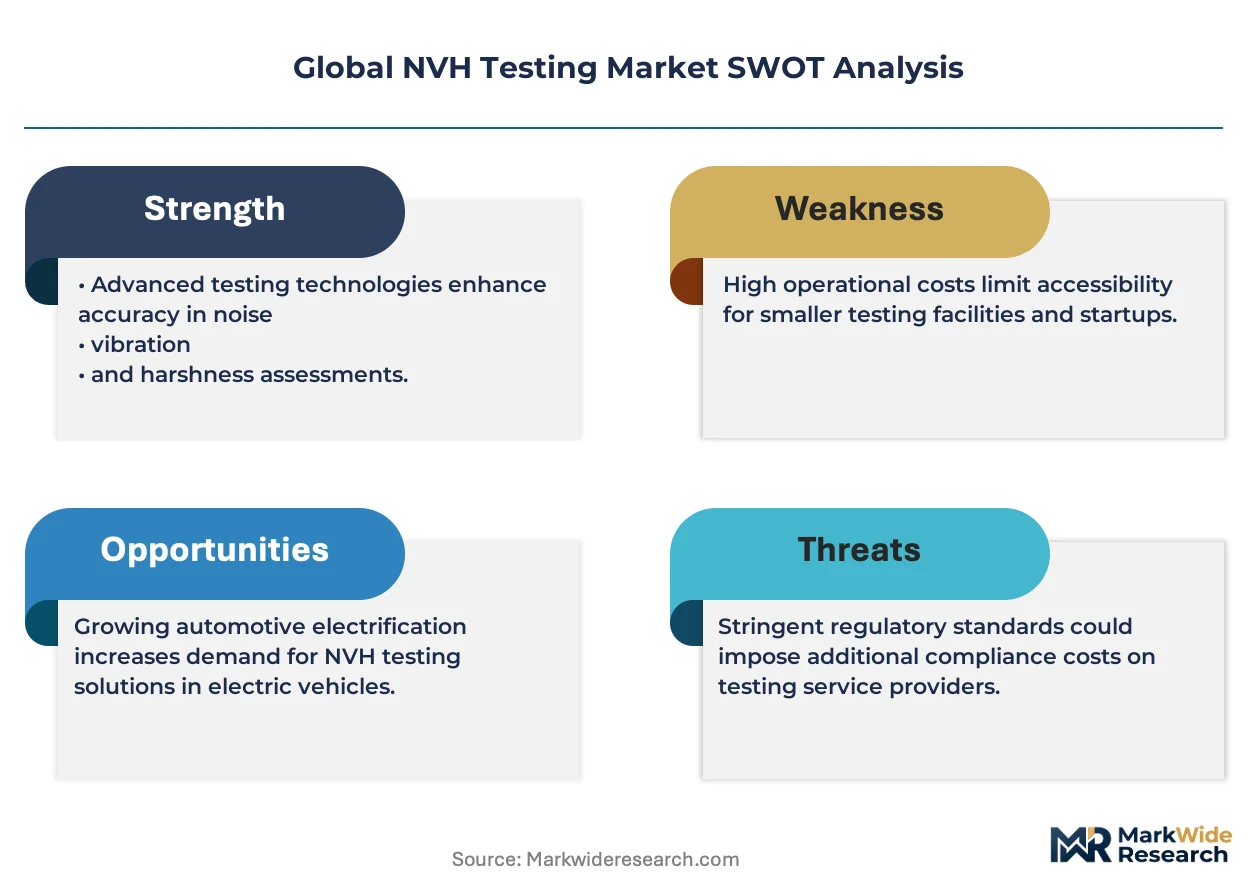
Acoustic engineering talent scarcity is bifurcating the competitive landscape into firms that own specialized expertise and those dependent on outsourced service partnerships. Brüel & Kjær anchors its position through decades of microphone calibration heritage and sensor manufacturing scale. Siemens Digital Industries Software leverages integrated simulation-to-test workflows that compress development timelines for automotive clients. AVL competes through deep combustion and electrification domain knowledge that informs its NVH consulting practice.
NVH testing encompasses the measurement, analysis, and mitigation of noise, vibration, and harshness across mechanical and electro-mechanical systems, employing accelerometers, microphones, and multi-channel data acquisition hardware sampling at rates exceeding 50 kHz to characterize frequency responses from infrasound to ultrasonic regimes. Automotive application demand leads in absolute revenue terms as powertrain electrification introduces new noise sources from inverter switching, gear whine, and tire-road interaction at previously masked frequencies. Testing Laboratories represent a structurally expanding service type as Tier-1 suppliers outsource validation to accredited third parties to avoid capital intensity and maintain schedule flexibility.
The US EPA enforces noise emission standards for commercial vehicles and outdoor equipment, compelling manufacturers to document compliance through standardized test protocols. The EU F-Gas Regulation and CE marking requirements under the Machinery Directive together mandate acoustic performance thresholds for stationary and mobile equipment sold across member states. Japan's METI promotes JIS-compliant measurement methodologies that shape export-oriented testing practices. Stakeholders must monitor how regulatory convergence or divergence between these frameworks affects the portability of test data and the economics of multi-market certification.
Market Dynamics
Powertrain electrification is fundamentally altering acoustic validation requirements across automotive and industrial equipment sectors, as electric motors and inverters generate noise signatures at frequencies and amplitudes distinct from combustion architectures.
Growth Catalysts
- EU F-Gas Regulation:Mandates for quieter HVAC and refrigeration compressors are expanding validation demand for building and transport climate systems across member states.
- China's captive laboratory investment:Domestic EV manufacturers in Shanghai and Shenzhen operate in-house NVH facilities to compress vehicle development cycles.
- Inverter switching frequencies:Higher-frequency electromagnetic noise from silicon carbide power electronics requires new measurement protocols and sensor bandwidth capabilities.
Market Restraints
- Accelerometer supply concentration:Precision piezoelectric sensor manufacturing clusters in Germany and Japan create single-source vulnerability for high-channel-count test systems.
- ISO 17025 accreditation costs:Third-party laboratories face substantial capital outlays for multi-site certification maintenance across divergent national standards.
- Simulation substitution:Multi-physics software platforms reduce physical prototype testing volume for early-stage design validation.
Strategic Opportunities
- India's automotive testing gap:Domestic OEMs and Tier-1 suppliers lack accredited NVH infrastructure for export certification to EU and US markets.
- Wind turbine gearbox monitoring:Condition-based maintenance contracts require continuous vibration sensing for offshore and onshore installations.
- Japan's METI hydrogen roadmap:Fuel cell powertrain noise characterization protocols remain undefined, creating first-mover standard-setting potential.
Industry Challenges
- Acoustic engineering talent scarcity:Universities produce insufficient graduates combining signal processing expertise with domain knowledge in rotating machinery or structural dynamics.
- Legacy data incompatibility:Decades of combustion-engine test archives use sampling rates and frequency weightings mismatched to electrified powertrain analysis requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global NVH Testing Market |
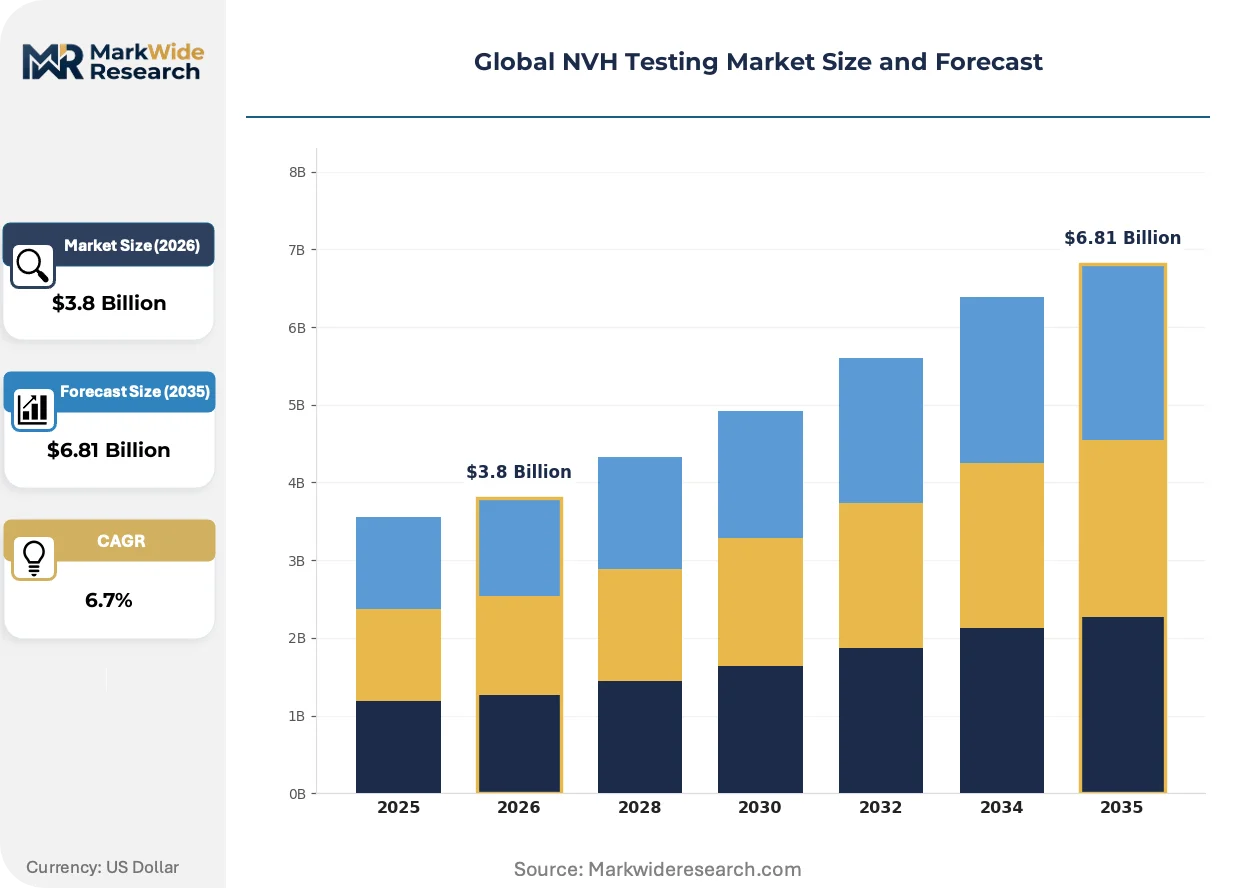
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Finite Element Analysis, Modal Analysis, Random Vibration Testing, Sound Quality Assessment Application: Automotive, Aerospace, Industrial Equipment, Electronics End User: OEMs, Tier-1 Suppliers, Testing Laboratories, Research Institutions Service Type: Consulting, Testing Services, Software Solutions, Training |
| Companies Covered | National Instruments Corporation, Siemens Digital Industries Software, Brüel & Kjær, HEAD acoustics GmbH, Dewesoft, Hottinger Brüel & Kjaer GmbH, Emerson Electric, Prosig Ltd, AVL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global NVH Testing Market Strategic Shifts
Distributed fiber-optic sensing and edge-computing architectures are transforming how vibration data is captured, processed, and transmitted across test environments. These shifts compress measurement latency while expanding spatial coverage.
MEMS-based accelerometers is supplanting traditional piezoelectric sensors in lower-channel-count applications. Automotive Tier-1 suppliers adopt MEMS arrays for tire-road noise mapping and suspension characterization. This transition is supplanting centralized data acquisition hardware with modular, wireless node configurations that reduce cabling mass and installation time.
The EU F-Gas Regulation imposes phasedown schedules for fluorinated greenhouse gases used in refrigeration and air conditioning. Equipment manufacturers must document acoustic performance compliance for alternative refrigerant systems under CE marking requirements. Stationary compressor OEMs in Germany and Italy are restructuring validation workflows to capture sound power levels for R-32 and R-454B charge systems.
Service unbundling is fragmenting traditional test-laboratory relationships. Automotive OEMs retain strategic NVH capability in-house while outsourcing commodity validation to accredited third parties. Chinese EV manufacturers pioneered this bifurcation, operating captive facilities for competitive-intellectual-property work while purchasing standardized environmental and durability testing from independent providers. This pattern now extends to European and North American electrification programs.
Global NVH Testing Market Segmentation
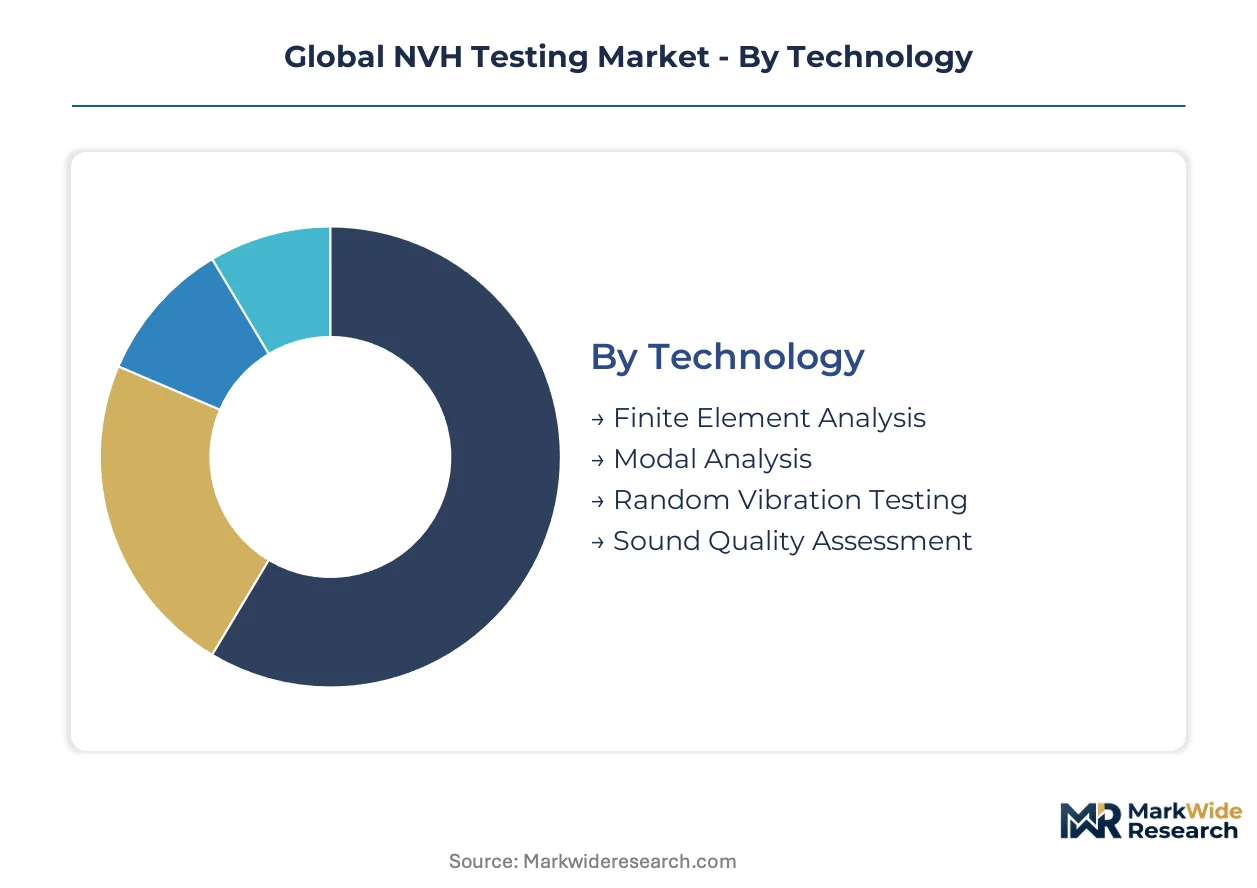
NVH testing segmentation reflects divergent technical requirements across electrification programs and regulatory jurisdictions. Technology and application boundaries blur as powertrain architectures converge on common noise signatures.
Technology:
Margin pools concentrate in high-channel-count data acquisition and real-time analysis software where sensor calibration heritage creates pricing power.
- Finite Element Analysis:Pre-physical simulation of structural vibration modes reduces prototype iterations for automotive body-in-white programs. German and Japanese OEMs deploy FEA for electric vehicle platform development where inverter mounting bracket resonance must resolve before tooling commitment.
- Modal Analysis:Experimental determination of natural frequencies, damping ratios, and mode shapes validates simulation correlation. Aerospace manufacturers in France and the United States apply modal testing to composite wing structures where laminate stacking sequence affects acoustic transmission.
- Random Vibration Testing:Environmental stress screening for electronics and military equipment qualification.
- Sound Quality Assessment:Psychoacoustic metrics including loudness, sharpness, and roughness for brand differentiation.
Modal Analysis holds installed capacity. Sound Quality Assessment is rotating up the share rankings.
Application:
Application mix tracks capital deployment in electrification and defense procurement cycles across Germany, China, and the United States.
- Automotive:Powertrain electrification generates validation demand for gear whine, tire-road noise, and inverter switching signatures. Chinese EV manufacturers in Shanghai and Shenzhen operate captive laboratories to compress development timelines while European OEMs outsource environmental durability testing.
- Aerospace:Composite airframe acoustic transmission and engine nacelle lining optimization. Boeing and Airbus suppliers face FAA and EASA noise certification requirements for next-generation narrowbody programs.
- Industrial Equipment:HVAC compressor validation under EU F-Gas Regulation phasedown schedules.
- Electronics:Fan noise and structural resonance testing for data center and consumer hardware.
Automotive dominates absolute revenue. Aerospace is gaining share fastest.
End User:
Customer type distribution reflects make-versus-buy decisions around intellectual property sensitivity and capital intensity.
- OEMs:Strategic NVH capability retained for competitive-intellectual-property work including electric motor acoustic signature development. Volkswagen, Toyota, and BYD maintain in-house facilities for core powertrain programs.
- Tier-1 Suppliers:Outsourced validation for commodity testing where schedule flexibility outweighs capital commitment. Bosch and Continental purchase environmental and durability testing from accredited third parties.
- Testing Laboratories:ISO 17025-accredited facilities capture outsourced volume from capital-constrained suppliers.
- Research Institutions:University and government laboratory programs advancing measurement methodology standardization.
OEMs anchor capability investment. Testing Laboratories are climbing the fastest.
Service Type:
Service unbundling fragments traditional relationships as customers segment work by IP sensitivity and standardization.
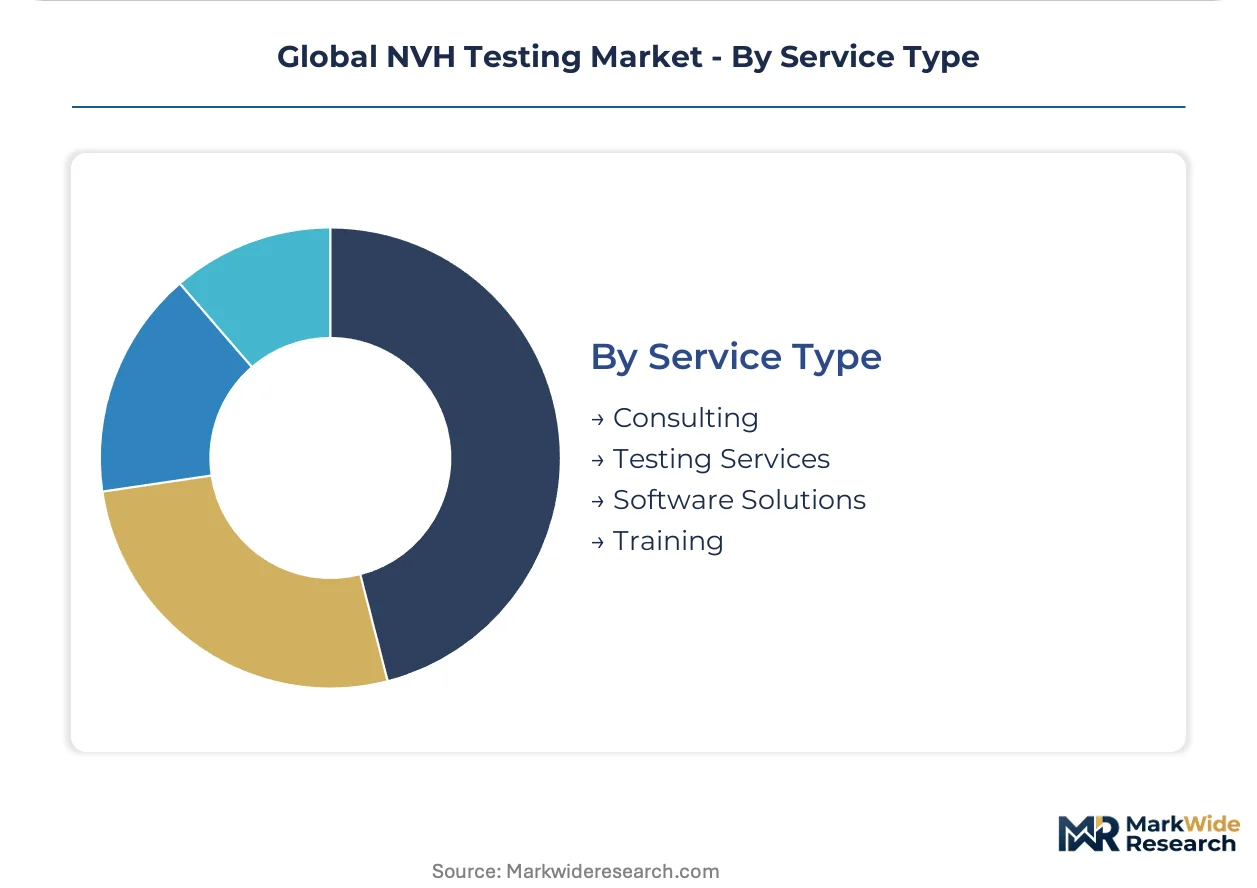
- Consulting:Domain expertise in rotating machinery and structural dynamics commands premium pricing. AVL and Siemens Digital Industries Software compete through integrated simulation-to-test workflows that compress automotive development timelines.
- Testing Services:Physical validation including environmental, durability, and acoustic performance certification. Chinese EV manufacturers pioneered captive-plus-outsourced bifurcation now extending to European electrification programs.
- Software Solutions:Multi-physics platforms reducing physical prototype volume for early-stage design validation.
- Training:Acoustic engineering talent scarcity creates demand for signal processing and domain-specific skill development.
Testing Services holds installed capacity. Software Solutions is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys NVH testing for electric powertrain validation at volumes unmatched elsewhere, while Germany concentrates on precision sensor manufacturing and Japan advances hydrogen fuel cell acoustic protocols. This consumption-mix differential shapes investment patterns across the major demand centers.
China
Domestic EV manufacturers in Shanghai and Shenzhen operate captive NVH laboratories to compress vehicle development cycles from concept to production. The Ministry of Ecology and Environment enforces GB standards for noise emission limits that align with export market requirements. BYD and NIO maintain in-house acoustic signature development teams in the Pearl River Delta while outsourcing environmental durability testing to accredited third parties.
Germany
Automotive OEMs in Stuttgart and Munich expand validation budgets for electric powertrains where noise signatures differ fundamentally from combustion platforms. The KBA enforces type approval requirements under UN/ECE regulations that mandate documented acoustic compliance for vehicles sold across EU member states. Precision piezoelectric sensor manufacturing clusters in Bavaria and Baden-Württemberg create supply concentration for high-channel-count test systems.
United States
Commercial vehicle manufacturers face EPA noise emission standards that compel standardized test protocols for outdoor equipment and heavy-duty trucks. The FAA collaborates with Boeing suppliers on composite airframe acoustic transmission testing for next-generation narrowbody programs. Test laboratories in Michigan and California capture outsourced validation volume from capital-constrained Tier-1 suppliers.
Japan
METI promotes JIS-compliant measurement methodologies that shape export-oriented testing practices for automotive and industrial equipment. The hydrogen roadmap creates first-mover standard-setting potential as fuel cell powertrain noise characterization protocols remain undefined. Toyota and Honda retain strategic NVH capability in Nagoya and Tokyo for competitive-intellectual-property work while purchasing commodity testing from independent providers.
India
Domestic OEMs and Tier-1 suppliers lack accredited NVH infrastructure for export certification to EU and US markets, creating structural demand for third-party laboratory investment. The BIS develops harmonized standards that bridge national requirements with international accreditation frameworks. Automotive clusters in Maharashtra and Tamil Nadu drive outsourcing demand as manufacturers seek ISO 17025 certification for component validation.
Global NVH Testing Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding pricing power through sensor calibration heritage and simulation-to-test workflow integration. The middle tier competes on domain expertise in rotating machinery and structural dynamics. Two strategic archetypes dominate: heritage sensor manufacturers with decades of microphone calibration expertise, and software-integrated platforms that compress development timelines through multi-physics simulation. Competitive moves center on strategic partnerships for technology licensing and portfolio diversification into adjacent measurement modalities.
Within the heritage sensor tier, Brüel & Kjær and Hottinger Brüel & Kjaer GmbH exemplify the calibration-anchored positioning that creates defensible market presence. Siemens Digital Industries Software occupies a position bridging simulation and physical test integration. AVL represents the consulting-intensive archetype where deep combustion and electrification domain knowledge informs advisory practice. These three anchors illustrate how competitive differentiation flows from either manufacturing scale, software integration, or specialized engineering expertise rather than undifferentiated test service provision.
| Leading Market Players |
|---|
| National Instruments Corporation |
| Siemens Digital Industries Software |
| Brüel & Kjær |
| HEAD acoustics GmbH |
| Dewesoft |
| Hottinger Brüel & Kjaer GmbH |
| Emerson Electric |
| Prosig Ltd |
| AVL |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at precision piezoelectric sensor foundries in Bavaria and Baden-Württemberg shapes both supply concentration and price floors for high-channel-count NVH test systems. German manufacturing scale creates defensible margin pools for heritage calibration houses while compressing pricing flexibility for downstream integrators dependent on single-source accelerometer supply.
Pricing Analysis
Long-term offtake agreements dominate sensor procurement for automotive OEMs and Tier-1 suppliers, with spot purchases limited to project-based laboratory expansions and emergency replacement cycles. Price differentiation stems from ISO 17025 certification tier and volume scale, with accredited laboratories commanding premiums over uncertified competitors. Pricing pressure intensifies in the MEMS accelerometer tier as automotive Tier-1 suppliers adopt wireless node configurations that displace traditional piezoelectric arrays. Testing laboratories exhibit highest price sensitivity due to capital constraints, while OEM captive facilities prioritize measurement bandwidth and calibration heritage over unit cost.
Supply Chain Analysis
Germany and Japan anchor precision piezoelectric sensor manufacturing, with Bavarian foundries supplying high-channel-count accelerometers and Japanese producers dominating microphone calibration standards. Raw material dependencies include synthetic quartz crystals, specialized ceramics, and rare-earth elements for sensor magnetics. Single-source vulnerability concentrates in German piezoelectric substrate processing, where legacy equipment replacement cycles exceed five years. Distribution runs through authorized distributor networks for hardware components and direct enterprise sales for integrated software platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software subscription and calibration service renewals expand faster than hardware sales in the NVH testing market, creating durable revenue attach opportunities beyond initial system deployment. Recurring revenue layers including sensor recalibration contracts, analysis software seats, and training certifications now represent the primary value accumulation mechanism for established suppliers.
For Market Incumbents: Fortify sensor calibration heritage through backward integration into piezoelectric substrate processing, eliminating single-source exposure to German foundry concentration. Expand ISO 17025 accreditation footprints across Shanghai and Shenzhen to capture Chinese EV manufacturer outsourcing demand. Multi-physics simulation substitution threatens physical test volumes; accelerate software-to-hardware workflow integration to retain platform control. For New Entrants and Emerging Players: Lead with MEMS-based wireless node architectures targeting automotive Tier-1 tire-road noise mapping applications, where installation time reduction creates immediate procurement preference. India's accredited NVH infrastructure gap offers the most penetrable geography for greenfield laboratory investment. Position through JIS-compliant methodology partnerships with Japanese METI to access export-oriented testing demand. For Investors and Strategic Acquirers: Specialized consulting firms combining rotating machinery domain expertise with electrification program experience represent the most defensible acquisition archetype. Long-term viability hinges on standard-setting participation as hydrogen fuel cell and silicon carbide inverter protocols crystallize. Watch for METI hydrogen roadmap standardization announcements as inflection indicators for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Expansion | Sensor recalibration contracts generate recurring revenue streams that exceed hardware margin profiles. |
| MEMS Platform Development | Wireless node architectures reduce automotive Tier-1 installation time and cabling mass. |
| ISO 17025 Multi-Site Certification | Accreditation in China and India captures outsourced validation from capital-constrained suppliers. |
| Simulation-to-Test Integration | Multi-physics workflow bundling defends against pure software substitution threats. |
| Hydrogen Protocol Standardization | Fuel cell NVH characterization first-mover positioning with Japanese METI creates regulatory capture. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, including NVH laboratory directors at automotive OEMs, procurement leads at Tier-1 suppliers, accelerometer manufacturing engineers, and accredited testing facility managers. Secondary validation drew from KBA type approval databases, EPA noise emission filings, METI JIS standard publications, and UN/ECE regulatory harmonization records. Bottom-up channel checks across sensor distribution networks triangulated against top-down OEM R&D spending disclosures.
Across the analysis window, the analytical framework modeled technology adoption by electrification program stage, application segmentation by regulatory jurisdiction stringency, and end-user type by make-versus-buy IP sensitivity. CAGRs were derived from installed base expansion rates and replacement cycle compression in the Chinese EV sector. Forecast inputs included silicon carbide inverter penetration curves and EU F-Gas Regulation compliance timelines for HVAC compressor OEMs.
Forecasts assume regulatory continuity in EU F-Gas phasedown schedules, US EPA noise emission enforcement, and Japanese METI hydrogen roadmap standardization; material policy shifts would require re-modeling. Specific risks include accelerometer supply disruption from German manufacturing concentration and simulation substitution accelerating beyond modeled rates. Recalibration cycles align with material shifts in powertrain electrification investment and regulatory harmonization announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Miniature Atomic Clock Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Metrology Systems Market
Test and Measurement
One-Box Testers Market
Test and Measurement
In-Line Overlay and Critical Dimension Metrology for Sub-3nm Nodes Market
Test and Measurement
Semiconductor Curve Tracer Market
Test and Measurement
Height Measurement Devices Market
Test and Measurement
Electrical and Electronic Test Equipment Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Cell Balancing Algorithm Hardware-in-the-Loop Test Platforms Market
Test and Measurement
Industrial Metrology Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market