
 Ultrasonic NDT Equipment Market | 2026-2036
Ultrasonic NDT Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic NDT Equipment Market Outlook
Aerospace MRO is expanding its share of ultrasonic NDT procurement as airlines extend fleet lifecycles and deepen inspection protocols. Baker Hughes Company dominates upstream oil and gas inspection contracts through its captive supply of ruggedized automated scanning systems. Eddyfi specializes in advanced phased array instrumentation for corrosion mapping in energy infrastructure. EVIDENT leverages its heritage in precision optics to sustain technology leadership in portable flaw detection hardware.
Ultrasonic NDT equipment employs high-frequency mechanical waves, typically operating between 0.5 and 25 MHz, to detect subsurface discontinuities without damaging the test material; transducers convert electrical pulses into acoustic energy that propagates through metals, composites, or ceramics to reveal cracks, voids, or delaminations critical to structural integrity assessment. Handheld and portable units command the largest installed base due to their flexibility across field deployments, while automated systems capture the fastest expansion as robotics integration reduces human exposure in hazardous inspection environments. Phased array technology leads the technology dimension with its ability to steer and focus beams electronically, though pulsed systems retain entrenched positions in cost-sensitive weld inspection workflows across construction and pipeline applications.
ASME Section V and Section VIII standards in the United States mandate periodic ultrasonic examination of pressure vessels and piping, directly shaping equipment specifications and calibration requirements for domestic suppliers. The EU's Pressure Equipment Directive and CE marking obligations enforce comparable conformity benchmarks across European member states, while China's GB standards and SAMR oversight govern import certification for foreign NDT manufacturers accessing industrial sectors there. Stakeholders must monitor how evolving safety codes in energy and transportation sectors recalibrate the trade-off between inspection speed and defect resolution sensitivity.
Market Dynamics
Phased array ultrasonic technology is compressing inspection timelines across aerospace MRO and energy infrastructure, forcing equipment vendors to recalibrate hardware-software integration depth and field service architectures.
Growth Catalysts
- Fleet lifecycle extension mandates:Airlines operating aging wide-body aircraft deepen inspection protocols, expanding procurement of portable phased array systems for wing spar and engine pylon examinations.
- ASME Section VIII updates:Tighter ultrasonic examination requirements for pressure vessels in North American refineries and chemical plants drive replacement of legacy pulsed systems with automated scanning rigs.
- Germany's industrial corridor concentration:Automotive OEMs and pipeline operators in Baden-Württemberg and North Rhine-Westphalia upgrade flaw detection capabilities, creating dense demand clusters for high-frequency transducers.
Market Restraints
- Specialized alloy input volatility:Piezoelectric ceramic substrates and tungsten backing materials face price instability, compressing margins for transducer manufacturers serving cost-sensitive weld inspection segments.
- Calibration equipment supply concentration:Reference block fabrication and certification services cluster in Japanese and German metrology labs, creating bottleneck risks for rapid deployment timelines.
- Radiographic testing substitution:Digital radiography advances in pipeline girth weld inspection threaten ultrasonic market share in applications where defect type discrimination matters less than speed.
Strategic Opportunities
- Wind turbine blade manufacturing:Carbon fiber composite inspection gaps in nacelle and blade root bonding create white space for shear wave and guided wave ultrasonic systems.
- EU Green Deal industrial transformation:Hydrogen pipeline retrofit mandates and carbon capture infrastructure inspections open new specification requirements for high-temperature hydrogen-compatible transducers.
- Cloud-connected field analytics:Equipment-as-a-service models embedding real-time defect classification algorithms displace outright hardware sales in mid-market inspection service providers.
Industry Challenges
- Phased array operator certification timelines:ASNT Level II and III qualification pathways for beam steering and focal law optimization extend 18-24 months, throttling deployment velocity for advanced systems.
- Legacy system integration friction:Automated scanning rigs face protocol mismatches with decades-old data management platforms in upstream oil and gas inspection contractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic NDT Equipment Market |
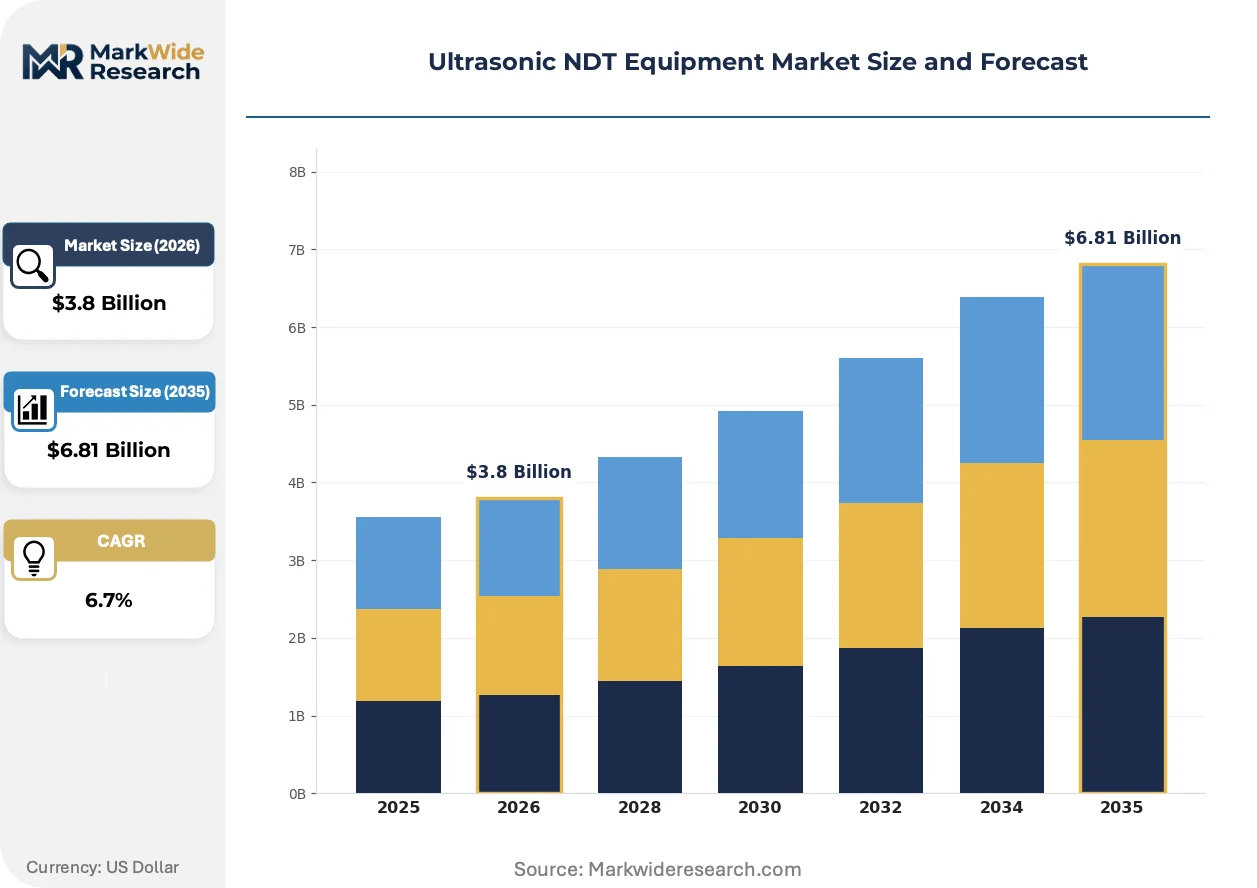
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Portable, Automated, Fixed Technology: Digital, Analog, Pulsed, Phased Array End User: Manufacturing, Aerospace, Automotive, Construction Application: Infrastructure, Pressure Vessels, Pipeline, Weld Inspection |
| Companies Covered | Baker Hughes Company, EVIDENT, Eddyfi, Sonatest, NDT Systems Inc, Olympus Corporation, MISTRAS Group, Intertek Group plc, SGS Société Générale de Surveillance SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic NDT Equipment Market Strategic Shifts
Artificial intelligence inference at the edge is compressing the gap between raw acoustic signal capture and actionable defect classification, reshaping how inspection contractors staff field operations and price service contracts.
Full-matrix capture with total focusing method is rewriting the resolution-speed tradeoff in corrosion mapping applications. Offshore platform operators and subsea pipeline inspectors adopt these systems to reduce diving hours and vessel standby costs. The technology is compressing the addressable market for conventional raster scanning by enabling single-pass coverage of complex geometries.
REACH restrictions on lead zirconate titanate formulations are forcing transducer manufacturers to reformulate piezoelectric compositions. European suppliers face accelerated R&D cycles to maintain sensitivity specifications under revised substance authorization timelines. The regulatory pressure is concentrating supply relationships with ceramics specialists holding early alternative material patents.
Inspection service bundling is consolidating procurement decisions at the enterprise level. Major energy and aerospace contractors now specify ultrasonic equipment through multi-year framework agreements covering hardware, software licenses, and analyst training. This behavior is most visible in the US Gulf Coast and North Sea regions, where integrated service providers displace fragmented equipment resale channels.
Ultrasonic NDT Equipment Market Segmentation
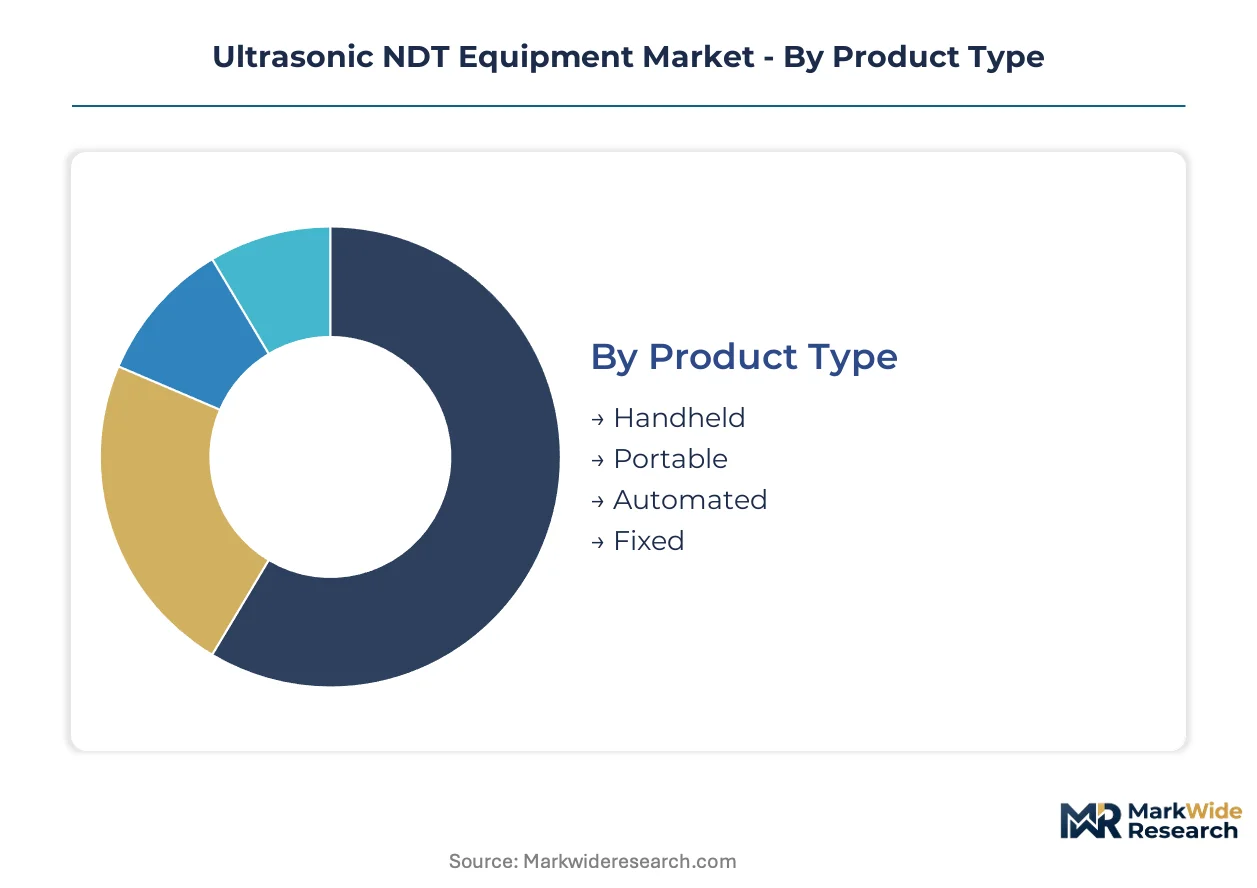
Ultrasonic NDT equipment procurement patterns diverge sharply between field-deployable units and capital-intensive automated systems. Understanding these splits reveals how inspection contractors balance mobility against throughput, and how regulatory complexity reshapes technology preferences across end-use verticals.
Product Type:
Portable and handheld units dominate unit shipments, yet automated systems capture disproportionate value through robotics integration and software depth.
- Handheld:Single-element transducer housings built for spot-check accessibility in confined structural geometries. Demand clusters in construction site weld verification and in-service bridge inspection contracts across Germany's industrial corridor, where mobility traces to tight access points in legacy infrastructure.
- Portable:Battery-powered phased array platforms with modular probe connections for multi-technique field deployment. Airlines extending wide-body fleet lifecycles deepen procurement for wing spar and engine pylon examinations, compressing inspection timelines without hangar immobilization.
- Automated:Gantry and robotic scanning rigs with encoded motion control for repeatable volumetric coverage.
- Fixed:Permanent installation systems for continuous monitoring of critical rotating machinery and pressure boundary components.
Today's leader: Portable. Tomorrow's challenger: Automated.
Technology:
Digital signal processing architectures now displace analog backends across all price tiers, while beam-steering capabilities redefine resolution benchmarks.
- Digital:FPGA-based acquisition systems with real-time filtering and A-scan storage for traceable documentation. North American refineries upgrading to ASME Section VIII-compliant examination protocols favor these platforms for pressure vessel corrosion mapping, where data retention mandates exceed analog capabilities.
- Phased Array:Multi-element probe assemblies with programmable focal laws enabling electronic beam steering without mechanical scanning. Offshore platform operators adopt these for subsea pipeline girth weld inspection, reducing diving hours through single-pass complex geometry coverage.
- Analog:Discrete component receiver chains with CRT or basic LCD display outputs.
- Pulsed:Conventional spike-excitation systems for high-voltage, short-duration ultrasonic generation in cost-sensitive applications.
Phased Array commands premium positioning. Digital infrastructure expands most quickly across mid-market service providers.
End User:
Manufacturing and aerospace inspection budgets concentrate capital deployment, while automotive and construction segments fragment procurement across smaller contractor bases.
- Aerospace:MRO operations and airframe manufacturers with stringent damage tolerance requirements for fatigue-critical structures. Fleet lifecycle extension mandates at US and European carriers deepen protocols for hidden corrosion detection in aging aluminum and composite assemblies.
- Manufacturing:Foundries, forges, and mill operations with in-process quality gates for billet and casting verification. German automotive OEMs in Baden-Württemberg upgrade flaw detection capabilities for powertrain component integrity assurance.
- Automotive:Tier-1 suppliers with spot-check protocols for chassis and powertrain weld quality.
- Construction:Fabrication yards and field contractors with structural steel and pipeline weld acceptance testing.
Aerospace anchors technology investment. Manufacturing scales volume procurement.
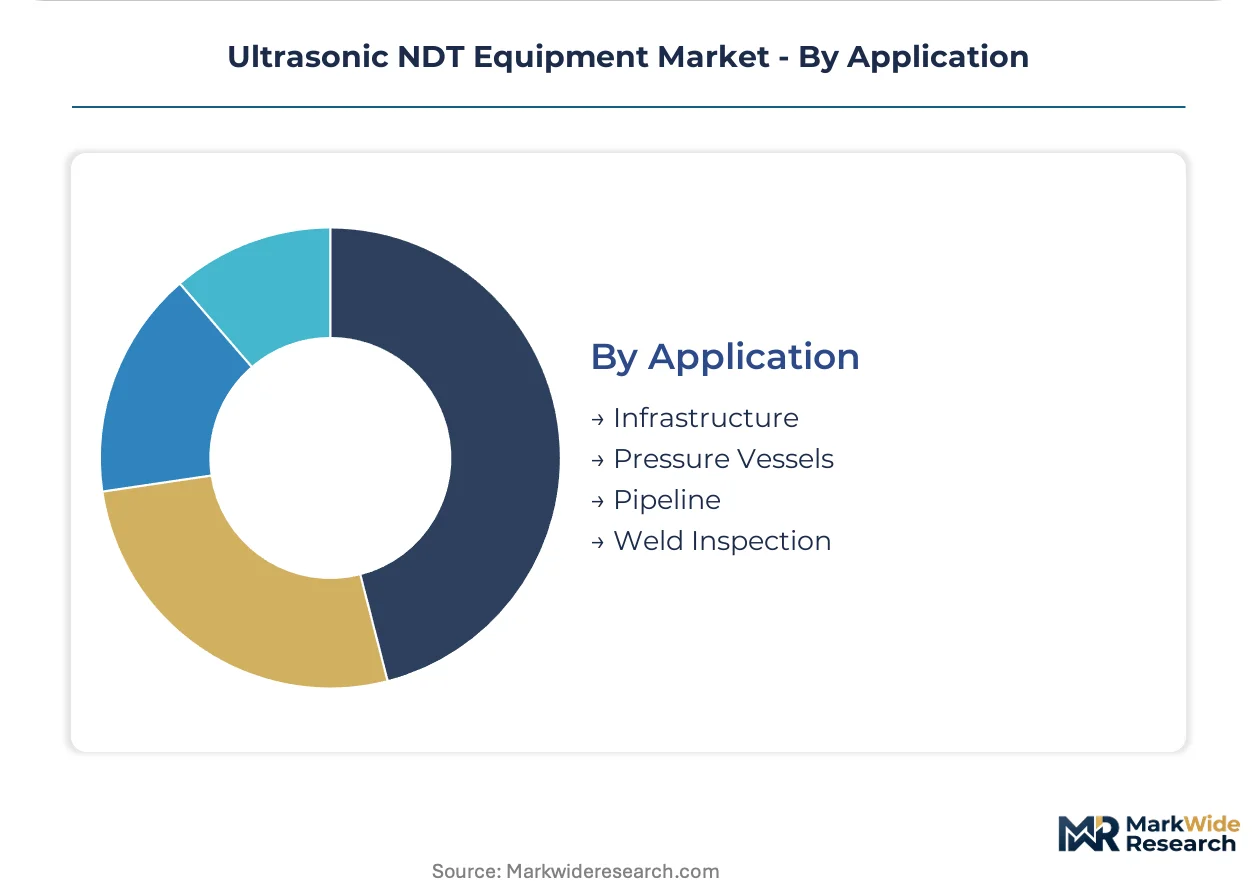
Application:
Weld inspection retains the broadest installed base, yet pressure vessel and pipeline applications drive specification complexity and recurring revenue attachment.
- Pressure Vessels:Thickness monitoring and crack detection in boilers, reactors, and storage spheres subject to cyclic pressure loading. ASME Section VIII updates in US refineries and chemical plants mandate automated scanning rigs with encoded coverage patterns, replacing legacy manual ultrasonic techniques.
- Pipeline:Girth weld qualification and in-service corrosion/ crack assessment for transmission and distribution networks. EU Green Deal hydrogen pipeline retrofit mandates open specification requirements for high-temperature hydrogen-compatible transducers in North Sea and continental European infrastructure.
- Weld Inspection:Fusion zone and heat-affected zone defect detection across construction and fabrication codes.
- Infrastructure:Bridge, tunnel, and building structural health monitoring with access-limited deployment constraints.
Pressure Vessels concentrate regulatory-driven replacement. Pipeline applications gain share fastest through energy transition infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment manufacturers migrate production toward jurisdictions with streamlined metrology certification pathways, exploiting cost-of-compliance gaps between established testing regimes and emerging industrial standards. This arbitrage reshapes regional competitiveness as inspection service providers consolidate procurement across fewer vendor relationships.
United States
ASME Section VIII updates mandate automated scanning rigs for pressure vessel examinations across Gulf Coast refineries and chemical plants. The FAA deepens damage tolerance protocols for aging commercial aircraft fleets, expanding MRO procurement of portable phased array systems. Houston anchors upstream oil and gas inspection demand, where integrated service providers specify ruggedized automated systems through multi-year framework agreements.
Germany
Automotive OEMs in Baden-Württemberg and pipeline operators in North Rhine-Westphalia upgrade flaw detection capabilities for powertrain integrity and energy infrastructure assurance. REACH restrictions on lead zirconate titanate formulations force transducer manufacturers to reformulate piezoelectric compositions under revised substance authorization timelines. Stuttgart and Düsseldorf concentrate demand clusters for high-frequency transducers serving both automotive and pipeline inspection workflows.
China
GB standards and SAMR oversight govern import certification for foreign NDT manufacturers accessing industrial sectors, creating compliance barriers for equipment without domestic testing documentation. Dual carbon goals accelerate hydrogen pipeline infrastructure planning, opening specification requirements for high-temperature hydrogen-compatible transducers. Yangtze River Delta manufacturing hubs deepen in-process quality gates for billet and casting verification in foundry operations.
Japan
METI industrial standards enforcement and JIS certification requirements maintain rigorous entry barriers for ultrasonic equipment imports. Reference block fabrication and calibration services concentrate in domestic metrology labs, creating bottleneck risks for rapid deployment timelines. Nagoya and Osaka industrial corridors sustain entrenched positions in precision transducer manufacturing for export markets.
United Kingdom
North Sea offshore platform operators adopt full-matrix capture systems to reduce diving hours and vessel standby costs in subsea pipeline inspection. The Civil Aviation Authority aligns with EASA damage tolerance frameworks for aging fleet examinations at MRO facilities. Aberdeen concentrates energy sector procurement decisions through integrated service providers specifying bundled hardware-software-training contracts.
Ultrasonic NDT Equipment Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with technology-integrated portfolios commanding premium positioning in automated inspection rigs while component suppliers serve cost-sensitive portable equipment markets. The vendor base organizes around three archetypes: diversified industrial conglomerates with captive NDT divisions, pure-play instrumentation specialists with deep software-hardware integration, and inspection service providers backward-integrating into equipment specification and distribution. Dominant competitive moves include strategic partnerships between transducer manufacturers and robotics integrators, plus geographic expansion through localized calibration and certification service establishment.
Among diversified industrial technology providers, Baker Hughes Company and Eddyfi exemplify contrasting archetypes—one representing upstream oil and gas captive supply chains, the other specializing in advanced phased array instrumentation for energy infrastructure corrosion mapping. EVIDENT occupies a position within precision optics heritage players that sustain technology leadership in portable flaw detection hardware through optical-mechanical integration capabilities. These three anchors illustrate how vendor positioning stratifies between automation-heavy energy contracts and mobility-critical aerospace MRO deployments.
| Leading Market Players |
|---|
| Baker Hughes Company |
| EVIDENT |
| Eddyfi |
| Sonatest |
| NDT Systems Inc |
| Olympus Corporation |
| MISTRAS Group |
| Intertek Group plc |
| SGS Société Générale de Surveillance SA |
| Others |
Value Chain & Pricing Dynamics
Phased array hardware-software integration is compressing unit economics while concentrating procurement leverage among integrated service providers, reshaping how transducer manufacturers and robotics integrators negotiate volume terms across aerospace MRO and energy infrastructure contracts.
Pricing Analysis
Distributor margins in the portable equipment tier typically run 15-25 points above direct-to-OEM automated rig contracts, with three-tier pricing structure across premium, standard, and economy levels anchored by certification grade and after-sales service bundling. Price differentiation hinges on ASNT training inclusion and software license duration, with margins tightening most acutely in cost-sensitive weld inspection segments where piezoelectric ceramic input volatility feeds through. Tier-1 aerospace contractors show lowest price sensitivity due to fleet safety mandates, while construction site operators drive hardest bargain on spot-check portable units.
Supply Chain Analysis
Certification gating through Japanese and German metrology labs concentrates reference block fabrication and transducer calibration services, creating bottleneck exposure for rapid deployment timelines. Manufacturing draws from Japanese precision ceramics specialists, German industrial automation component suppliers, and Chinese PCB assembly operations, with piezoelectric substrates, tungsten backing materials, and FPGA acquisition boards as critical inputs. Single-source vulnerability runs through lead zirconate titanate formulations facing REACH substance authorization pressure. Distribution runs through inspection service providers bundling hardware-software-training contracts, displacing fragmented equipment resale channels in the US Gulf Coast and North Sea regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers geographic-arbitrage value through metrology certification cost differentials between Japanese JIS pathways and streamlined European notified-body procedures, enabling equipment manufacturers to recalibrate production footprints against compliance burden.
For Market Incumbents: To counter digital radiography substitution in pipeline girth weld inspection, Baker Hughes and Eddyfi should deepen backward integration into transducer ceramics and expand Stuttgart-area calibration service capacity. Phased array operator certification bottlenecks threaten deployment velocity; incumbents must embed training modules within hardware-software bundles to compress ASNT Level II qualification timelines for inspection contractors. For New Entrants and Emerging Players: EU Green Deal hydrogen pipeline retrofit mandates in Germany and the Netherlands open a window for high-temperature hydrogen-compatible transducer specialization, with Baden-Württemberg automotive OEMs as the most penetrable anchor client base. Wind turbine blade root bonding inspection gaps represent adjacent white space; entrants should pursue shear wave system partnerships with nacelle manufacturers rather than competing head-to-head in saturated aerospace MRO channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-market phased array software specialists lacking robotics integration capabilities, as automated scanning rig demand accelerates faster than pure-play instrumentation can capture. Long-term viability over a 5-10 year window rests on cloud-connected field analytics attachment rates displacing outright hardware sales. Watch inspection service bundling consolidation at the enterprise level as the inflection signal for equipment vendor margin compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Transducer Ceramics | REACH reformulation deadlines force captive supply of lead-free piezoelectric compositions to maintain sensitivity specifications. |
| Phased Array Training Bundling | ASNT qualification bottlenecks throttle deployment; embedded certification modules accelerate contractor adoption velocity. |
| Hydrogen-Compatible Transducer Development | EU Green Deal pipeline retrofit mandates in Germany and the Netherlands create specification requirements for high-temperature hydrogen service. |
| Cloud-Connected Field Analytics Platform | Equipment-as-a-service models embedding real-time defect classification displace outright hardware sales in mid-market inspection providers. |
| Stuttgart Calibration Service Expansion | Reference block certification concentration in German metrology labs creates geographic arbitrage for streamlined deployment timelines. |
Study Parameters
Direct dialogue with NDT equipment procurement managers at aerospace MRO facilities, inspection service provider operations directors, transducer manufacturing engineers, and energy sector asset integrity managers grounded qualitative findings. Secondary validation drew from ASME code update filings, FAA damage tolerance directives, EU Pressure Equipment Directive implementation guidance, and customs data on ultrasonic equipment trade flows. Bottom-up unit economics and top-down sectoral spending estimates were cross-referenced to establish market sizing boundaries.
Segment-level outputs across the projection horizon reflect modeled splits by product type, technology architecture, end-use vertical, and application workflow, with CAGRs derived from regression against industrial capital expenditure cycles and regulatory compliance mandate timelines. Forecast inputs incorporated fleet age demographics at US and European carriers, refinery turnaround schedules on the US Gulf Coast, and German automotive OEM powertrain investment commitments.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated digital radiography substitution or protracted REACH alternative-material approval timelines. A model refresh is warranted upon material change in ASME Section VIII examination protocol enforcement or EU hydrogen infrastructure deployment acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ultrasonic Pulse Velocity Tester Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Fiber Optic Test Equipment (FOTE) Market
Test and Measurement
Gloss Meters Market
Test and Measurement
Europe Nondestructive Testing Equipment Market
Test and Measurement
Indoor Air Quality Multi-Pollutant Sensor Calibration Test Equipment Market
Test and Measurement
Moisture Analyzer Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
RF Test Equipment Market
Test and Measurement
Calibration Management Software Market
Test and Measurement
Battery Drop Tester Market
Test and Measurement
Structure Tester Market
Test and Measurement
Semiconductor Curve Tracer Market