
 Mud Test Equipment Market | 2026-2036
Mud Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Mud Test Equipment Market Insights
Composite sensor housings are broadening the performance envelope for downhole instruments under extreme pressure-temperature conditions. Fann Instrument Company leverages its legacy calibration protocols to sustain precision dominance in North American shale plays. OFI Testing Equipment anchors its position through backward integration into custom sensor manufacturing. Baker Hughes competes by extending digital telemetry across its mud monitoring portfolio.
Mud test equipment comprises instruments that measure the physical and chemical properties of drilling fluids, including plastic viscosity, yield point, gel strength, and filtrate loss, with operating ranges typically spanning ambient to 500°F and atmospheric to 20,000 psi equivalent. These devices ensure borehole stability, cuttings transport efficiency, and formation damage prevention across rotary drilling operations. The electromagnetic technology segment leads in offshore deployments where real-time data transmission commands premium positioning, while mechanical instruments retain cost-driven share in onshore contract drilling. Filter presses and viscometers together occupy the deepest margin pools due to replacement-part dependency and API certification requirements.
The EPA enforces Subpart W methane monitoring rules that indirectly elevate drilling fluid testing rigor, while API RP 13B-1 and RP 13B-2 standards govern equipment calibration protocols accepted across US basins. OSHA's silica exposure limits for oilfield workers further shape instrument specifications for dust-generating sample preparation steps. Stakeholders must weigh the capital trade-off between automated digital platforms and manual mechanical units as labor costs and regulatory documentation burdens diverge across operating environments.
Market Dynamics
Drilling contractors face mounting pressure to automate fluid testing workflows as EPA methane disclosure rules tighten documentation requirements and labor costs diverge sharply across Texas and North Dakota oilfields.
Growth Catalysts
- EPA Subpart W compliance:Methane monitoring mandates elevate drilling fluid testing rigor, forcing operators to upgrade from manual to automated instrumentation for audit-ready data trails.
- Shale basin intensity:Permian and Bakken operators deploy real-time telemetry to optimize drilling economics, accelerating replacement cycles for legacy mechanical viscometers.
- Composite sensor housings:Advanced polymer-ceramic blends extend operating envelopes beyond 20,000 psi and 500°F, opening ultra-deepwater and high-temperature geothermal applications.
Market Restraints
- API certification bottlenecks:Third-party calibration protocols for RP 13B-1 and RP 13B-2 standards create 12-16 week lead times for new instrument validation.
- Sensor supply concentration:Precision pressure transducers and electromagnetic flow elements concentrate among German and Japanese component suppliers, exposing buyers to currency and logistics volatility.
- Mechanical instrument durability:Legacy spring-and-dial viscometers persist in cost-driven onshore contract drilling, compressing pricing power for digital platform vendors.
Strategic Opportunities
- OSHA silica rule alignment:Dust-exposure limits for oilfield sample preparation create demand for enclosed, automated filtration systems with integrated ventilation.
- Geothermal expansion:High-temperature drilling in Iceland and Kenya requires mud test equipment rated beyond conventional oilfield specifications, opening premium positioning.
- Digital telemetry convergence:Integration of edge computing with downhole sensors enables predictive maintenance contracts, shifting revenue from hardware sales to recurring service streams.
Industry Challenges
- Calibration technician scarcity:Specialized expertise in API RP 13B protocol execution concentrates among aging field engineers, constraining service expansion.
- Legacy system integration:Drilling contractors operating mixed fleets of mechanical and digital instruments face data format incompatibilities that fragment workflow automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mud Test Equipment Market |
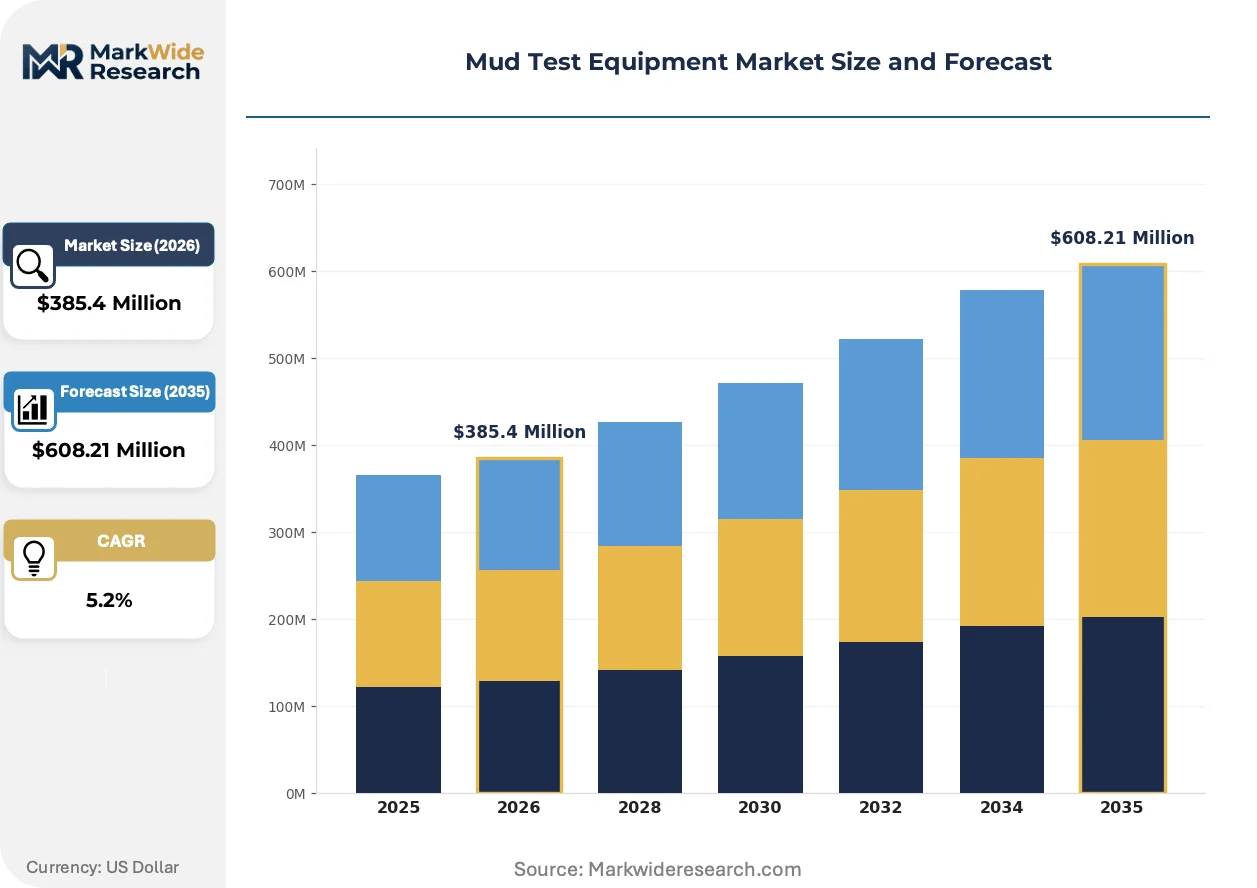
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $608.21 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Viscometers, Rheometers, Density Meters, Filter Presses, Sand Content Testers, Corrosion Test Kits Technology: Electromagnetic, Ultrasonic, Digital Pressure, Optical, Thermal Conductivity, Mechanical Application: Oil Well Drilling, Geotechnical Investigation, Mining Exploration, Environmental Monitoring, Construction Soil Testing, Research Laboratories End User: Drilling Contractors, Research Institutions, Mining Companies, Consulting Engineers, Environmental Agencies, Equipment Manufacturers |
| Companies Covered | OFI Testing Equipment, Fann Instrument Company, LEUTERT, SINOMUD GROUP, Schlumberger, Halliburton, Baker Hughes, Weatherford International, NOV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mud Test Equipment Market Trends and Innovations
Real-time data architectures are displacing batch-testing workflows across North American shale operations, compressing decision cycles from hours to minutes and reshaping vendor competitive requirements.
Portable electromagnetic viscometers are modularizing field deployment architectures, enabling drilling contractors to distribute testing nodes across multiple well pads rather than centralizing at rig sites. Permian Basin operators pilot these units for simultaneous multi-well monitoring. This topology is modularizing service contracts toward per-well rather than per-rig pricing structures.
EPA enforcement of Subpart W methane disclosure rules tightens chain-of-custody requirements for drilling fluid samples, mandating timestamped digital records that mechanical instruments cannot generate. Operators in Texas and North Dakota retrofit fleets with automated data-logging capabilities. Filter press and viscometer suppliers now bundle cloud connectivity as standard to maintain contract eligibility.
Integrated procurement platforms consolidate mud test equipment purchasing with consumables and replacement sensors, displacing the traditional separation between capital and operating expenditure decisions. Large independents in the Delaware Basin negotiate enterprise agreements spanning multiple service lines. This consolidation concentrates vendor selection authority at regional headquarters rather than individual rig superintendents.
Mud Test Equipment Market Segmentation
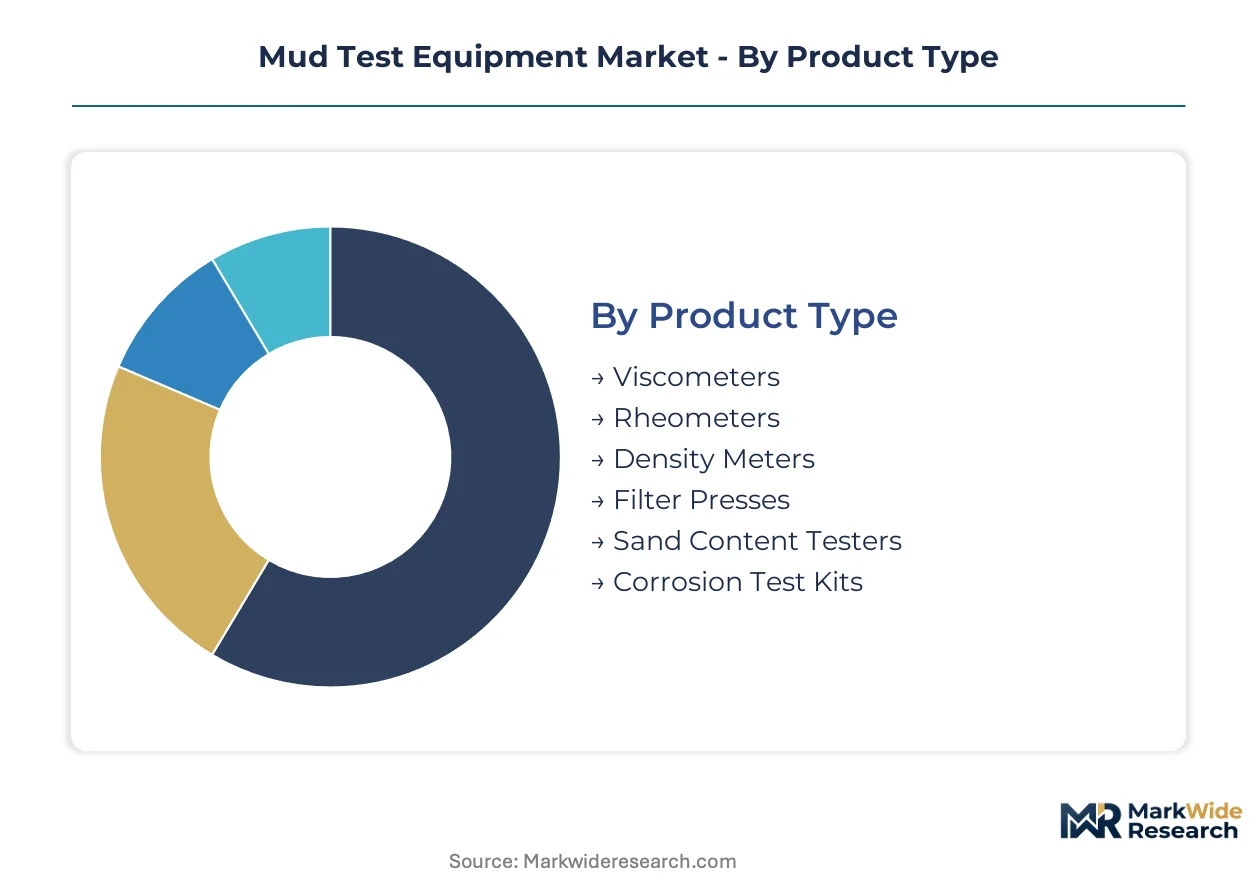
Segmentation in mud test equipment reveals how drilling economics, regulatory pressure, and operational intensity reshape procurement priorities across distinct buyer profiles. Equipment specifications diverge sharply between high-frequency shale basin operations and intermittent geotechnical contracts, creating tiered vendor strategies.
Product Type:
Buyers differentiate primarily by testing frequency and regulatory documentation burden, with high-volume operators prioritizing automation and audit-ready data trails.
- Viscometers:These instruments measure plastic viscosity, yield point, and gel strength through rotational shear testing, with API RP 13B-1 calibration protocols mandatory for US basin acceptance. Demand concentrates among Permian and Bakken drilling contractors facing EPA Subpart W methane disclosure documentation requirements that timestamped digital outputs satisfy.
- Filter Presses:Static filtration devices quantify fluid loss under differential pressure, comprising cell assemblies, filtration media, and pressure sources. Replacement-part dependency and API certification requirements sustain margin pools, with environmental agencies in Texas and North Dakota driving upgrade cycles for automated data-logging models.
- Rheometers:Advanced rotational instruments capture viscoelastic properties under oscillatory and steady-shear conditions for complex fluid characterization.
- Density Meters:Pressure-balanced mud balance devices and nuclear densitometers measure drilling fluid weight for wellbore stability management.
- Sand Content Testers:Sieving and sedimentation-based instruments quantify abrasive solids concentration to predict equipment wear rates.
- Corrosion Test Kits:Static and dynamic corrosion cells evaluate drilling fluid compatibility with downhole metallurgy under simulated bottom-hole conditions.
Viscometers lead volumes today; filter presses are gaining share fastest through replacement-cycle acceleration and regulatory retrofit demand.
Technology:
Technology selection tracks the cost-versus-precision trade-off, with premium electromagnetic systems commanding offshore positioning and mechanical units retaining onshore contract drilling share.
- Electromagnetic:Coil-based sensing elements measure fluid properties without moving parts, enabling real-time telemetry integration. Offshore deployments in the Gulf of Mexico and North Sea command premium positioning where data transmission latency directly impacts drilling economics.
- Mechanical:Spring-loaded dial indicators and manual torque mechanisms deliver calibration-stable measurements at capital cost points accessible to independent drilling contractors. Legacy instrument durability sustains cost-driven onshore contract drilling penetration in Texas and North Dakota oilfields.
- Digital Pressure:MEMS-based transducer arrays capture rheological parameters through differential pressure measurement across calibrated flow restrictions.
- Ultrasonic:Acoustic propagation velocity and attenuation sensing enables non-invasive density and solids concentration determination.
- Optical:Laser scattering and imaging systems characterize particle size distribution and phase separation in opaque drilling fluids.
- Thermal Conductivity:Heated probe methods determine thermal properties critical for high-temperature geothermal and deepwater applications.
Mechanical technology anchors installed base volumes; electromagnetic systems are expanding most quickly through offshore digitization mandates.
Application:
Application segmentation reflects drilling intensity differentials, with continuous oil well operations demanding ruggedized field instrumentation versus intermittent laboratory calibration requirements.
- Oil Well Drilling:Rotary drilling operations require continuous monitoring of plastic viscosity, yield point, and filtrate loss to ensure borehole stability and cuttings transport efficiency. Shale basin intensity in the Permian and Bakken accelerates replacement cycles for legacy mechanical viscometers as operators deploy real-time telemetry.
- Research Laboratories:Controlled-environment facilities demand precision calibration traceability and multi-parameter characterization capabilities for fluid formulation development. Academic and corporate R&D centers in Houston and Midland anchor demand for advanced rheometer configurations.
- Geotechnical Investigation:Site characterization drilling for foundation engineering employs portable viscosity and density measurement for soil-bentonite slurry quality control.
- Mining Exploration:Core drilling programs utilize mud testing to optimize diamond bit life and core recovery rates in varying lithologies.
- Environmental Monitoring:Contaminated site assessment and remediation drilling requires fluid testing to prevent cross-contamination and verify disposal compliance.
- Construction Soil Testing:Slurry wall and diaphragm wall installation quality control depends on viscosity and density verification for trench stability.
Oil well drilling dominates revenue concentration; research laboratories are climbing the fastest through composite sensor housing adoption for extreme condition simulation.
End User:
End user structure concentrates procurement authority, with large drilling contractors negotiating enterprise agreements while fragmented independents sustain spot-market equipment sales.
- Drilling Contractors:Operating companies and service providers running rotary rigs constitute the primary equipment purchaser category, with fleet standardization driving volume consolidation. Large independents in the Delaware Basin negotiate integrated procurement platforms spanning multiple service lines, concentrating vendor selection authority at regional headquarters.
- Environmental Agencies:Federal and state regulators deploy standardized testing equipment for compliance verification and enforcement sampling. EPA enforcement of Subpart W methane disclosure rules tightens chain-of-custody requirements, mandating timestamped digital records that drive automated instrumentation retrofit cycles.
- Research Institutions:Universities and national laboratories acquire precision instrumentation for drilling fluid science and geothermal energy research.
- Mining Companies:Mineral exploration divisions maintain portable testing capability for remote core drilling operations.
- Consulting Engineers:Geotechnical and environmental consulting firms supply project-specific testing services with rental and lease equipment models.
- Equipment Manufacturers:Original equipment suppliers maintain in-house testing capability for product development and quality assurance.
Drilling contractors command the largest procurement volumes; environmental agencies are expanding most quickly through regulatory enforcement budget growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Permian Basin anchors international demand for mud test equipment, with shale operators driving replacement cycles for legacy mechanical viscometers across North American, Middle Eastern, and Asia-Pacific drilling corridors.
United States
EPA Subpart W methane disclosure rules mandate timestamped digital records for drilling fluid samples, forcing Permian and Bakken operators to retrofit fleets with automated data-logging viscometers. OSHA silica exposure limits shape specifications for enclosed filtration systems. Houston and Midland host the densest clusters of drilling contractors negotiating integrated procurement platforms.
Saudi Arabia
Saudi Aramco's upstream expansion programs sustain demand for high-pressure filter presses rated beyond 20,000 psi equivalent. The country's national oil company imposes API RP 13B calibration protocols across all vendor qualifications. Dhahran and the Eastern Province concentrate service company headquarters managing Red Sea and onshore rig fleets.
China
Shale gas development in Sichuan-Chongqing and Tarim basins accelerates adoption of electromagnetic viscometers for real-time telemetry integration. GB standards for drilling fluid testing equipment align with API specifications for domestic and export markets. Beijing-Tianjin-Hebei hosts state-owned oilfield service companies consolidating regional procurement authority.
Norway
North Sea electrification mandates and ultra-deepwater drilling economics command premium positioning for electromagnetic mud monitoring systems with subsea data transmission capabilities. The country's petroleum regulator enforces stringent equipment certification for Barents Sea operations. Stavanger anchors the European headquarters of international oilfield service majors.
United Arab Emirates
ADNOC's sour gas expansion and artificial island drilling programs require mud test equipment rated for hydrogen sulfide service and extreme temperature cycling. The emirates' national petroleum regulator mandates third-party calibration traceability for all downhole instrumentation. Abu Dhabi concentrates regional procurement decisions for offshore Arabian Gulf operations.
Mud Test Equipment Market Competitive Landscape
Global majors compete with regional champions across technology tiers and geographic coverage dimensions. The vendor base stratifies between integrated oilfield service conglomerates, specialized testing equipment manufacturers, and component-focused sensor suppliers. Three archetypes dominate: full-service drilling fluid technology providers, precision instrumentation specialists, and digital telemetry platform developers. Competitive moves center on backward integration into custom sensor manufacturing and enterprise procurement platform consolidation.
Among Houston-based integrated service providers, Halliburton, Baker Hughes, and Schlumberger exemplify the full-service archetype spanning drilling fluids, testing instrumentation, and real-time data services. Fann Instrument Company and OFI Testing Equipment occupy positions within the precision instrumentation tier, with the former representing legacy calibration protocol dominance and the latter exemplifying backward integration into captive sensor production. Weatherford International and NOV anchor the digital platform vector through modular telemetry architectures.
| Leading Market Players |
|---|
| OFI Testing Equipment |
| Fann Instrument Company |
| LEUTERT |
| SINOMUD GROUP |
| Schlumberger |
| Halliburton |
| Baker Hughes |
| Weatherford International |
| NOV |
| Others |
Pricing and Supply Chain Analysis
Composite sensor housing adoption simultaneously compresses manufacturing costs and concentrates precision component sourcing among German and Japanese suppliers. This dual effect reshapes vendor margin structures across electromagnetic and mechanical instrument tiers.
Pricing Analysis
Input-cost pass-through from precision pressure transducers and electromagnetic flow elements sustains premium positioning for digital platforms. Three-tier pricing structure across API-certified, industrial-grade, and entry-level mechanical units reflects calibration protocol investment and telemetry integration depth. Cost compression in mechanical viscometer segments is intensifying because legacy spring-and-dial durability extends replacement cycles. Independent drilling contractors in Texas exhibit highest price sensitivity, while offshore operators in the Gulf of Mexico accept premium electromagnetic systems.
Supply Chain Analysis
Transoceanic freight volatility from German and Japanese component hubs elevates landed costs for electromagnetic sensor assemblies. Manufacturing concentrates in the United States, China, and Germany, with final assembly drawing from polymer-ceramic composite feedstocks, MEMS transducer arrays, and API-certified calibration standards. Single-source vulnerability in precision pressure sensing elements exposes buyers to currency fluctuation. Distribution runs through oilfield service company regional warehouses and direct procurement platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on automated data-logging retrofit cycles and composite sensor premium-tier adoption displacing legacy mechanical units.
For Market Incumbents: Anticipate EPA Subpart W enforcement tightening by securing backward integration into captive sensor manufacturing. Consolidate calibration technician expertise through targeted hiring in Midland and Houston clusters before scarcity intensifies. Defend against portable electromagnetic viscometer modularization by bundling cloud connectivity as standard.
For New Entrants and Emerging Players: Capture geothermal drilling expansion in Iceland and Kenya with mud test equipment rated beyond conventional oilfield specifications. Penetrate OSHA silica rule alignment opportunities through enclosed, automated filtration systems with integrated ventilation. Pursue per-well rather than per-rig service contracting to bypass incumbent rig-site relationships.
For Investors and Strategic Acquirers: Valuations sit cheapest among precision instrumentation specialists lacking digital telemetry integration. Five-to-ten year viability favors vendors with API RP 13B protocol execution capabilities and regional procurement platform relationships. Watch EPA enforcement budget allocations as the inflection signal for automated instrumentation retrofit velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | OFI Testing Equipment's captive production secures supply continuity against German-Japanese component concentration. |
| Digital Telemetry Platform Convergence | Baker Hughes extends real-time data transmission across Gulf of Mexico offshore deployments. |
| API Certification Investment | Fann Instrument Company sustains precision dominance through legacy calibration protocol maintenance. |
| Geographic Expansion into Geothermal | High-temperature drilling in Kenya and Iceland opens premium positioning beyond oilfield specifications. |
| Enterprise Procurement Platform Consolidation | Delaware Basin independents concentrate vendor selection authority at regional headquarters. |
Research Methodology
Multiple input streams — drilling contractor procurement directors, oilfield service company R&D leads, environmental agency compliance officers, and aftermarket service managers — were reconciled against SEC 10-K filings, customs and trade data, EPA enforcement databases, and API certification records. Primary interviews across Texas, North Dakota, and Houston-Midland clusters were validated through secondary documentation. Bottom-up equipment shipment analysis and top-down drilling activity modeling were cross-referenced for triangulation.
Historical replacement cycle patterns were cross-referenced against panel input from rig superintendents and regional procurement heads. Segmentation dimensions modeled include product type, technology tier, application intensity, and end-user procurement authority structure. CAGRs were derived from equipment deployment velocity across shale basin drilling corridors. Forecast inputs incorporated EPA regulatory enforcement trajectories and composite sensor housing adoption curves.
Regulatory enforcement intensity, component supply disruption, and drilling contractor capital allocation shifts are the dominant revision risks to modeled projections. Forecasts reflect assumptions about API protocol maintenance and electromagnetic telemetry integration timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Asia-Pacific Nondestructive Testing Equipment Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Fluorometers Market
Test and Measurement
High Rate Discharge Test Machine Market
Test and Measurement
North America Electronic Test and Measurement Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Distortion Meter Market
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Wi-Fi Test Equipment Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
EMC Shielding and Test Equipment Market
Test and Measurement
Density Meter Market
Test and Measurement
Simulation and Test Data Management Market
Test and Measurement
Power Electronics GaN and SiC Device Reliability Test Systems Market
Test and Measurement
Noise Vibration Harshness (NVH) Testing Market