
 AI-Enabled Testing Market | 2026-2036
AI-Enabled Testing Market Size, Share, and Industry Trends Forecast 2026-2036
AI-Enabled Testing Market Analytics
Multi-source procurement of AI testing platforms is restructuring how enterprises evaluate vendor resilience and capability depth. Tricentis sustains broad technology leadership across continuous testing pipelines. Functionize Inc. leverages natural language processing to differentiate autonomous test generation. Sauce Labs Inc. anchors cloud-native browser and mobile testing infrastructure at scale.
AI-enabled testing encompasses software validation systems that apply machine learning models to autonomously generate, execute, and maintain test cases across functional, performance, and security parameters, typically processing execution logs, DOM structures, and user behavior telemetry to predict failure modes before production deployment. Its primary industrial purpose is collapsing the feedback loop between code commit and defect detection in DevOps pipelines. Cloud-based and SaaS deployment models are capturing the fastest expansion as organizations prioritize elastic infrastructure over capital-intensive on-premises installations. Functional testing retains the largest volume footprint, while security testing commands premium pricing due to compliance-driven procurement mandates in finance and healthcare sectors.
The EU AI Act, ISO/IEC 23053, and FDA software validation guidance collectively establish conformance baselines that determine market access for testing platforms serving regulated industries. EMA and FDA requirements for computerized system validation in pharmaceutical manufacturing directly expand demand for audit-ready AI testing documentation. Stakeholders must monitor how emerging algorithmic accountability frameworks in the European Union and United States redefine liability allocation between testing platform vendors and their enterprise clients.
Market Dynamics
Algorithmic accountability mandates from Brussels to Washington are compressing validation timelines and forcing test automation vendors to embed compliance documentation directly into execution pipelines.
Growth Catalysts
- EU AI Act Conformity Requirements:High-risk AI system classification triggers mandatory pre-deployment validation protocols across financial services and healthcare, expanding procurement of audit-ready testing platforms.
- Automotive Software Complexity:Germany's KBA mandates for autonomous driving systems drive specialized validation tool procurement for sensor fusion and decision-logic verification.
- Self-Healing Test Scripts:Machine learning models that automatically repair broken selectors upon DOM changes reduce maintenance overhead and accelerate release cadence in CI/CD environments.
Market Restraints
- Specialized Talent Scarcity:Shortage of engineers capable of training domain-specific models for test generation limits platform customization velocity.
- Training Data Access Constraints:Enterprise security policies restrict export of production execution logs to cloud-based testing vendors, degrading model accuracy.
- On-Premises Infrastructure Lock-In:Defense and classified government programs require air-gapped validation environments, excluding SaaS-native platform architectures.
Strategic Opportunities
- Pharmaceutical Manufacturing Validation:FDA computerized system validation requirements for AI-driven quality control create demand for GxP-compliant testing documentation in North American life sciences.
- Edge Computing Test Orchestration:Distributed validation of IoT firmware across heterogeneous device fleets requires new synchronization protocols between cloud coordinators and local test agents.
- Green Software Certification:EU Green Deal energy efficiency metrics for data center operations create procurement preference for testing platforms with carbon-aware test scheduling.
Industry Challenges
- Explainability Documentation Burden:Regulators in France and Germany demand interpretable test coverage rationale for high-stakes algorithmic decisions, forcing vendors to reverse-engineer model logic.
- Multi-Cloud Execution Fragmentation:Enterprises distributing workloads across AWS, Azure, and GCP require testing platforms to normalize environment provisioning APIs and credential management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | AI-Enabled Testing Market |
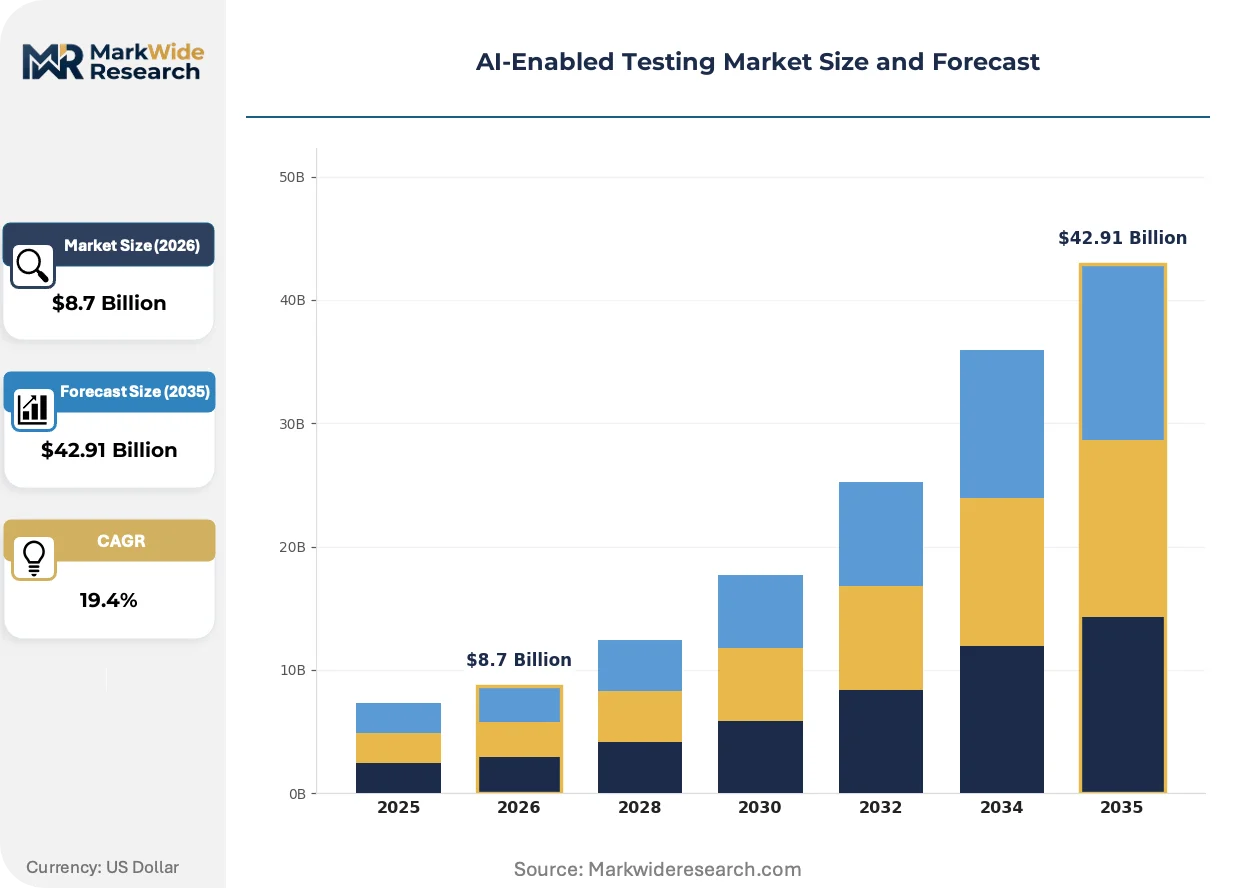
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $42.91 Billion |
| CAGR (2026 – 2036) | 19.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Type: Functional Testing, Performance Testing, Security Testing, Regression Testing Deployment Model: On-Premises, Cloud-Based, Hybrid, SaaS End User: Enterprises, Startups, Educational Institutions, Government Agencies Industry Sector: IT Services, Healthcare, Finance, Telecommunications |
| Companies Covered | Sauce Labs Inc., Tricentis, Functionize Inc., Applitools Ltd., Diffblue Ltd., TestRigor Inc., Mabl Inc., ReTest GmbH, Capgemini SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
AI-Enabled Testing Market Evolving Landscape
Test automation architectures are fragmenting into composable microservices that decouple generation, execution, and reporting functions. This decomposition enables selective capability procurement and accelerates vendor substitution.
Natural language test specification interfaces are modularizing how business analysts interact with automation pipelines. Domain experts at insurance and retail enterprises now author executable test cases without scripting expertise. This capability compression is collapsing the traditional handoff queue between product owners and QA engineers.
ISO/IEC 23053 conformity assessment frameworks are mandating standardized documentation of AI system testing procedures. Medical device manufacturers in the European Union must submit structured evidence of validation coverage for algorithmic components. This regulatory pressure is forcing platform vendors to embed audit-trail generation as a native function rather than post-hoc report compilation.
Consumption-based licensing for test execution minutes is displacing perpetual seat-based contracts in enterprise procurement. Platform vendors now compete on granular pricing transparency and committed-use discounts. This shift is most pronounced among mid-market SaaS companies seeking to align validation costs with release frequency rather than headcount expansion.
AI-Enabled Testing Market Segmentation
AI-enabled testing platforms serve divergent operational requirements across deployment topologies, regulatory environments, and organizational maturity levels. Segment-specific procurement patterns reveal how compliance mandates, infrastructure legacy, and talent density reshape vendor selection criteria.
Testing Type:
Enterprises prioritize validation depth based on production failure cost profiles and regulatory exposure severity.
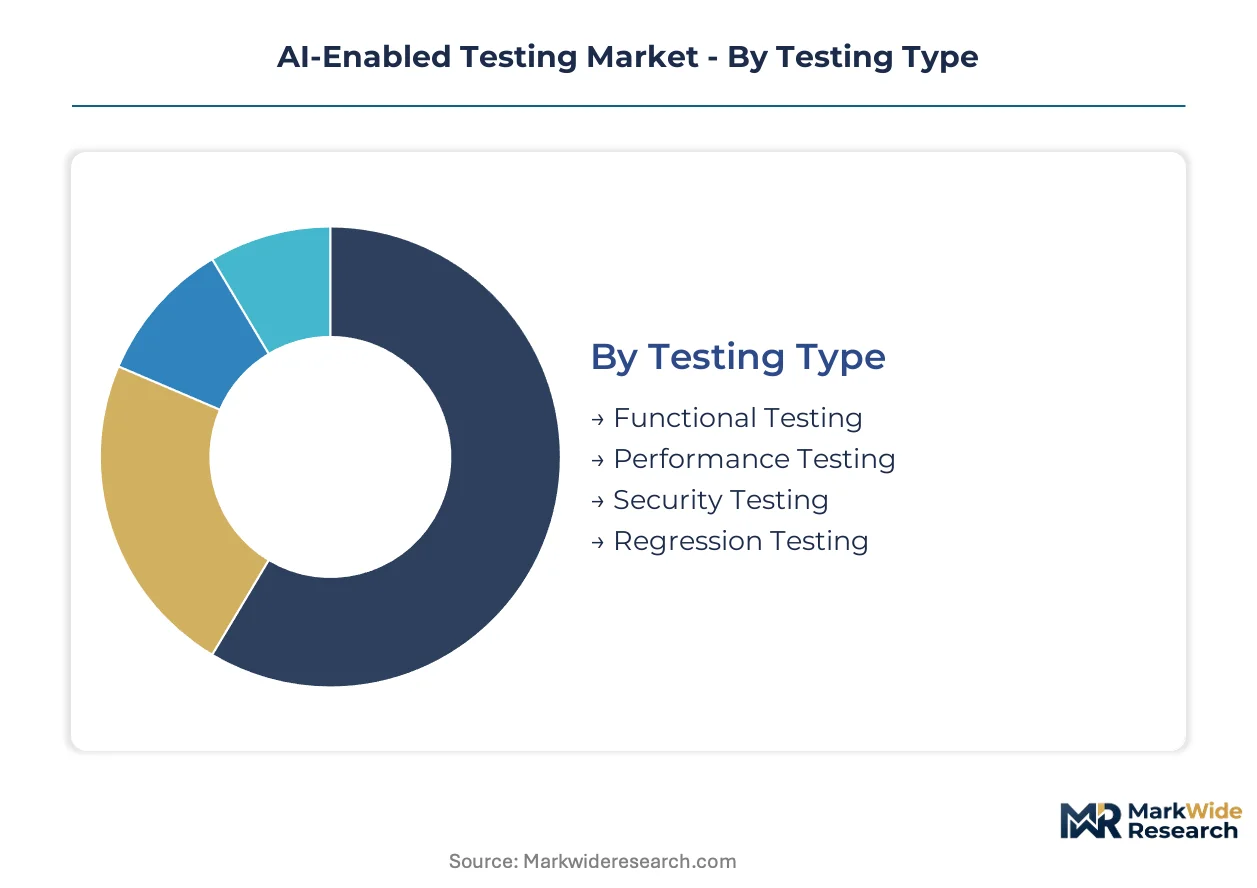
- Functional Testing:Validates application behavior against specified requirements through automated script execution. Healthcare systems in Germany and finance platforms in the United States concentrate procurement here due to ISO/IEC 23053 documentation mandates for high-risk algorithmic decisions.
- Security Testing:Probes vulnerability surfaces using machine learning to predict attack vectors before deployment. EU AI Act conformity requirements for financial services in France and healthcare in Germany drive premium pricing and specialized vendor certification.
- Performance Testing:Stresses infrastructure under simulated load conditions to identify scalability bottlenecks.
- Regression Testing:Re-executes test suites upon code modification to detect unintended side effects.
Functional testing anchors current procurement volumes; security testing is gaining share fastest.
Deployment Model:
Infrastructure sovereignty requirements and data residency regulations fragment platform architecture preferences across customer profiles.
- Cloud-Based:Delivers elastic compute resources for test execution without capital expenditure. Mid-market SaaS vendors in the United States and digital-native enterprises in India prioritize this model for CI/CD velocity.
- SaaS:Abstracts infrastructure management entirely through subscription-based consumption models. European startups and educational institutions in Germany favor granular pricing alignment with release frequency.
- On-Premises:Retains execution environments within customer-controlled data centers for classified workloads.
- Hybrid:Orchestrates sensitive validation on-premises while bursting peak loads to cloud infrastructure.
Cloud-based deployments dominate new procurement; SaaS models are climbing the fastest among organizations without legacy infrastructure debt.
End User:
Organizational scale and compliance maturity determine platform sophistication requirements and integration complexity tolerance.
- Enterprises:Demand enterprise-grade governance, audit trails, and multi-region orchestration. Automotive manufacturers in Germany and pharmaceutical conglomerates in Switzerland procure specialized platforms for KBA and FDA validation documentation.
- Government Agencies:Require air-gapped environments and FedRAMP or equivalent security certifications. Defense programs in the United States and classified research institutions mandate on-premises architectures excluded from SaaS-native offerings.
- Startups:Prioritize velocity over governance, favoring consumption-based pricing.
- Educational Institutions:Seek teaching platforms with accessible natural language interfaces for curriculum integration.
Enterprises command the largest contract values; government agencies are expanding procurement most aggressively due to algorithmic accountability mandates.
Industry Sector:
Sector-specific regulatory density and software criticality create divergent testing automation requirements.
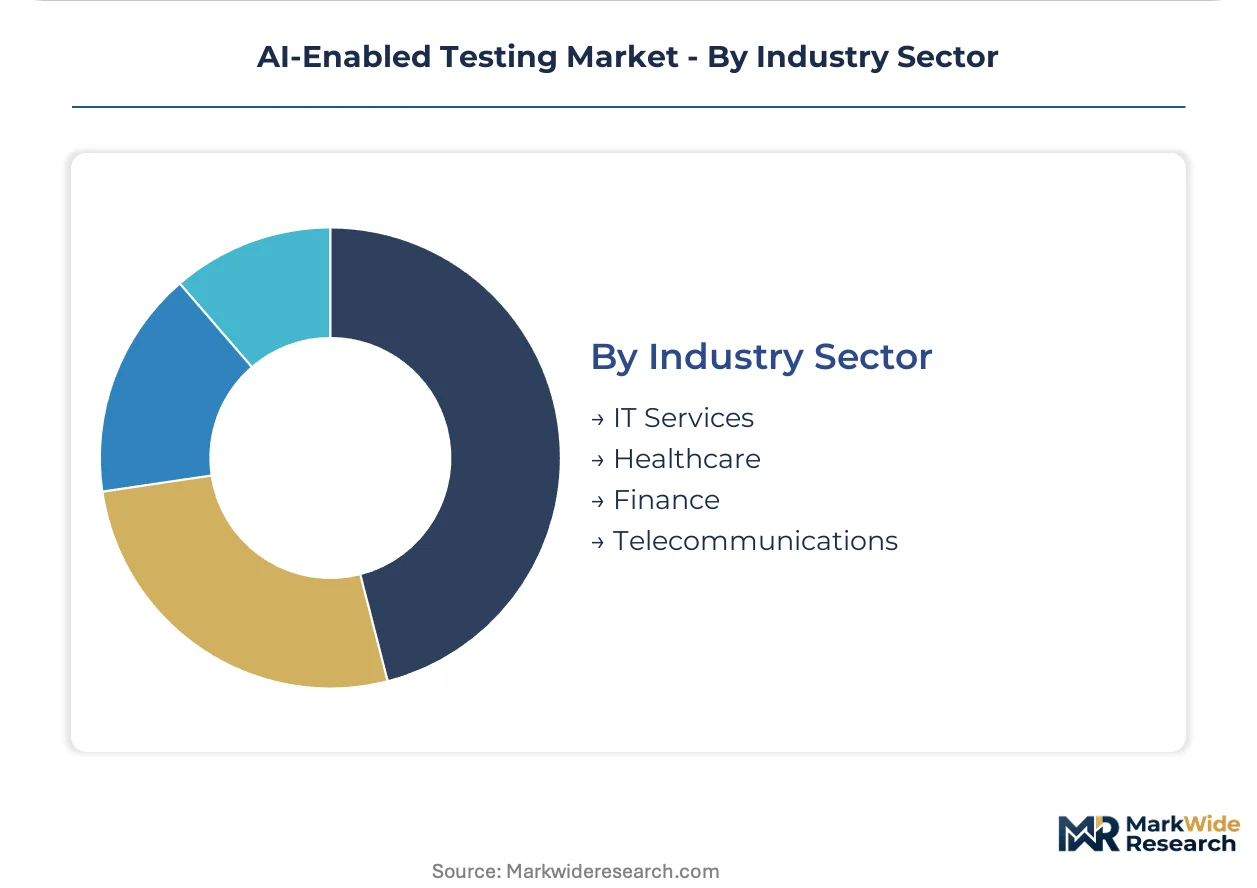
- Finance:Faces EU AI Act high-risk system classification triggering mandatory pre-deployment validation. Banks in France and insurance groups in Germany procure audit-ready platforms with embedded compliance documentation.
- Healthcare:Navigates FDA software validation guidance and EMA computerized system requirements. Medical device manufacturers in the United States and pharmaceutical producers in Germany demand GxP-compliant test evidence generation.
- IT Services:Serves as the adoption frontier for self-healing test scripts and natural language test specification.
- Telecommunications:Validates 5G network function virtualization and edge computing orchestration protocols.
Finance leads current sector spending; healthcare is expanding most quickly as FDA and EMA guidance hardens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vendor location strategies as compliance-cost differentials widen between jurisdictions with mature algorithmic accountability frameworks and those still formalizing standards. Enterprises now route validation workloads toward regions offering streamlined certification pathways without sacrificing audit rigor.
United States
Financial services firms in New York and San Francisco are expanding procurement of intelligent test automation for SEC and FDA compliance validation. FDA software validation guidance for medical devices drives specialized platform demand among Boston-area biotech clusters. The FDA's computerized system validation requirements directly shape vendor product roadmaps serving pharmaceutical manufacturers.
Germany
Automotive software validation requirements from KBA and industrial IoT testing protocols concentrate procurement in Munich and Stuttgart engineering corridors. The EU AI Act's high-risk system classification triggers mandatory pre-deployment validation across Frankfurt banking centers. ISO/IEC 23053 standard implementation is reshaping certification requirements for algorithmic quality assurance systems nationwide.
United Kingdom
London's fintech sector is driving demand for audit-ready testing platforms aligned with emerging Financial Conduct Authority algorithmic accountability expectations. The UK Medicines and Healthcare products Regulatory Agency's software validation requirements expand procurement among Cambridge life sciences clusters. Post-Brexit regulatory divergence is creating parallel certification tracks for vendors serving EU and UK markets simultaneously.
France
Paris-based insurance groups and banking conglomerates are procuring platforms with embedded CNIL-compliant documentation for high-stakes algorithmic decisions. ANSM requirements for medical device software validation expand demand among Lyon and Strasbourg manufacturing hubs. The EU AI Act's French implementation is pioneering interpretable test coverage rationale mandates that vendors must reverse-engineer into model logic.
India
Bengaluru and Hyderabad IT services hubs are adopting self-healing test scripts and natural language test specification interfaces for export-oriented software validation. The country's national IT regulator is formalizing data localization requirements that restrict production execution log export to cloud-based testing vendors. Mid-market SaaS companies in Mumbai are prioritizing consumption-based licensing to align validation costs with release frequency.
AI-Enabled Testing Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue autonomous test generation and natural language interfaces as differentiation vectors. The vendor base clusters around three capability poles: continuous testing pipeline breadth, AI-native test authoring, and cloud-native execution infrastructure. Strategic archetypes include end-to-end platform consolidators, point-solution AI specialists, and services-anchored systems integrators. Dominant competitive moves encompass geographic expansion into regulated European markets and technology licensing partnerships for self-healing script capabilities.
Within the AI-native specialization tier, Functionize Inc. and Diffblue Ltd. exemplify machine learning-first architectures, while ReTest GmbH anchors German-engineered precision in automotive validation contexts. Tricentis represents the platform consolidation archetype through continuous testing pipeline breadth. Sauce Labs Inc. occupies the cloud-native execution position with browser and mobile infrastructure at scale. These three named entities collectively illustrate how vendor positioning stratifies across automation depth, compliance documentation sophistication, and infrastructure elasticity rather than converging on undifferentiated functional parity.
| Leading Market Players |
|---|
| Sauce Labs Inc. |
| Tricentis |
| Functionize Inc. |
| Applitools Ltd. |
| Diffblue Ltd. |
| TestRigor Inc. |
| Mabl Inc. |
| ReTest GmbH |
| Capgemini SE |
| Others |
Value Network & Pricing Analysis
Consumption-based licensing preferences from mid-market SaaS buyers in the United States and Germany are forcing platform vendors to restructure cost recovery around execution-minute metering rather than perpetual seat contracts, compressing upfront revenue recognition and shifting margin pressure toward infrastructure optimization.
Pricing Analysis
GPU compute and cloud storage costs pass through directly to SaaS-tiered subscription rates, with premium tiers absorbing specialized compliance documentation modules for FDA and EU AI Act mandates. Price differentiation centers on audit-trail sophistication and self-healing script density. Pricing pressure stems from open-source test frameworks commoditizing baseline functional coverage. Startups exhibit highest price sensitivity; pharmaceutical manufacturers in Germany and Switzerland show lowest sensitivity due to GxP validation requirements.
Supply Chain Analysis
Specialized AI training infrastructure rests on NVIDIA GPU supply from Taiwan and United States foundries, with cloud orchestration software anchored in Seattle and Bengaluru development clusters. Open-source test frameworks and proprietary ML model weights constitute critical IP dependencies. Single-source vulnerability concentrates in advanced semiconductor fabrication. Distribution runs through direct enterprise sales teams and hyperscaler marketplace integrations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in AI-enabled testing hinges on automation density reducing human-in-the-loop validation hours, while premium-tier compliance documentation commands pricing premiums from regulated buyers in finance and healthcare.
For Market Incumbents: Lock in enterprise relationships through embedded compliance documentation pipelines that satisfy FDA and EU AI Act audit requirements. Deepen vertical integration into self-healing script training data pipelines to reduce cloud compute dependency. Defend against point-solution AI specialists by consolidating natural language test generation with execution infrastructure. For New Entrants and Emerging Players: Autonomous test generation for edge computing IoT firmware represents the most penetrable white-space target, with pharmaceutical manufacturing validation in North America offering secondary expansion. Pursue consumption-based pricing alignment with mid-market SaaS release cadences. Go-to-market leverage centers on integration partnerships with hyperscaler CI/CD marketplaces. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native test authoring specialists possessing proprietary NLP model weights and automotive validation certification from KBA-aligned engagements. Long-term viability favors platforms with multi-cloud orchestration capabilities and embedded regulatory documentation engines. Watch FDA guidance evolution on AI-driven quality control systems as inflection indicator for pharmaceutical sector procurement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates test generation, execution, and compliance documentation into unified CI/CD pipelines for DevOps teams. |
| Acquisition of Specialist Firm | Captures proprietary self-healing script algorithms and automotive validation expertise from KBA-certified engineering teams. |
| Strategic Partnership | Embeds testing modules within hyperscaler marketplaces to capture mid-market SaaS procurement workflows. |
| Geographic Expansion | Establishes EU AI Act compliance documentation capabilities for Frankfurt banking and Paris insurance verticals. |
| Product Launch | Introduces natural language test interfaces that collapse handoff queues between product owners and QA engineers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs, IT procurement officers, platform engineers, and integration specialists at financial services, healthcare, and automotive enterprises with secondary validation against SEC filings, hyperscaler capex disclosures, and EU regulatory guidance documents. Bottom-up deployment model sizing and top-down sector spending estimates were triangulated for convergence.
Segment-weighting applied deployment model, organization size, vertical industry, and regional adoption pattern dimensions across the projection horizon. CAGRs derived from regression analysis of historical platform procurement velocity against regulatory mandate implementation timelines. Forecast inputs incorporated EU AI Act high-risk system classification rollout schedules and FDA computerized system validation guidance evolution.
The model holds under steady regulatory implementation timelines; deviation in EU AI Act enforcement intensity or FDA guidance acceleration would shift sector procurement velocity. Forecasts reflect documented assumptions regarding cloud infrastructure cost trajectories and enterprise DevOps maturity progression. A small set of named triggers—algorithmic accountability framework expansion, semiconductor supply disruption, and open-source framework commoditization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Calibration Management Software Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Optical Fiber Network Latency and Time Synchronization Test Equipment Market
Test and Measurement
Whiteness Meter Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Flow Meter Calibration Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Melt Flow Tester Market
Test and Measurement
Air Measuring Equipment Market
Test and Measurement
Reverberation Chambers Market
Test and Measurement
LTE Testing Equipment Market
Test and Measurement
Glow Wire Test Apparatus Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Manufacturing Test Systems Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market