
 Starch-Based Texturizing Agents Market | 2026-2036
Starch-Based Texturizing Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Starch-Based Texturizing Agents Market Analytics
Modular ingredient bundling is hardening as the dominant procurement pattern, with buyers preferring pre-blended texturizing systems over single-component sourcing. Cargill Inc. leverages its integrated grain supply chain to control native starch quality from field to formulation. Kerry Group plc sustains competitive advantage through specialized dairy application labs in Europe and North America. Tate & Lyle PLC differentiates via clean-label modified starch portfolios tailored to bakery sector specifications.
Starch-based texturizing agents comprise carbohydrate polymers derived from corn, wheat, potato, or tapioca that undergo physical, chemical, or enzymatic modification to achieve specific viscosity, gelation, or mouthfeel properties in finished products. Modified starch dominates current value generation due to its engineered stability under thermal and shear stress, while instant starch segments expand fastest in convenience-focused beverage and sauce applications where hydration speed determines manufacturing throughput.
The FDA governs starch safety and labeling under GRAS determinations in the United States, while EFSA and REACH compliance govern modified starch approvals and chemical processing standards across Europe. These frameworks elevate formulation costs for non-compliant suppliers and redirect R&D investment toward enzymatic and physical modification pathways. Stakeholders must monitor evolving clean-label definitions and regional allergen thresholds as these parameters increasingly determine market access and premium positioning.
Market Dynamics
Modular ingredient bundling now dominates procurement as bakery and dairy manufacturers abandon single-component sourcing in favor of pre-blended texturizing systems that compress formulation cycles and reduce supplier management overhead.
Growth Catalysts
- EU Green Deal compliance mandates:The EU Green Deal and F-Gas Regulation are forcing processors toward enzymatic and physical modification pathways, accelerating clean-label starch adoption across European bakery chains.
- Clean-label bakery demand:German industrial baking clusters are driving volume as recognizable ingredient declarations become non-negotiable for retail private-label contracts.
- Instant starch hydration speed:Beverage and sauce manufacturers prioritize rapid-dispersing modified starches to maximize line throughput in high-speed filling operations.
Market Restraints
- Native corn starch price volatility:Weather-driven harvest fluctuations in major grain-producing regions create input cost instability that squeezes margin structures for unhedged processors.
- Supply concentration in German ingredient hubs:Geographic clustering of modification capacity around industrial baking centers creates single-point vulnerability for European supply security.
- REACH chemical processing friction:ECHA compliance requirements for chemically modified starches elevate R&D costs and extend approval timelines versus physical or enzymatic alternatives.
Strategic Opportunities
- Underpenetrated convenience beverage segments:Ready-to-drink protein beverages and plant-based milk alternatives present white-space demand for clean-label instant starches with neutral flavor profiles.
- Enzymatic-physical modification convergence:Hybrid processing technologies that combine enzyme precision with physical shear stability enable premium positioning in thermal-stress applications.
- Direct-to-manufacturer digital channels:B2B platform procurement of pre-blended texturizing systems is compressing distributor margins while expanding formulation service bundling.
Industry Challenges
- Specialized food polymer formulation talent scarcity:The intersection of carbohydrate chemistry and industrial process engineering lacks sufficient trained professionals to support R&D pipeline expansion.
- Clean-label certification timeline compression:Evolving definitions of "natural" and "recognizable" across retail banners force repeated reformulation cycles and label re-registration costs.
- Legacy dairy processing equipment incompatibility:Existing UHT and aseptic filling lines require retrofit investment to handle high-viscosity modified starch systems without shear degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Starch-Based Texturizing Agents Market |
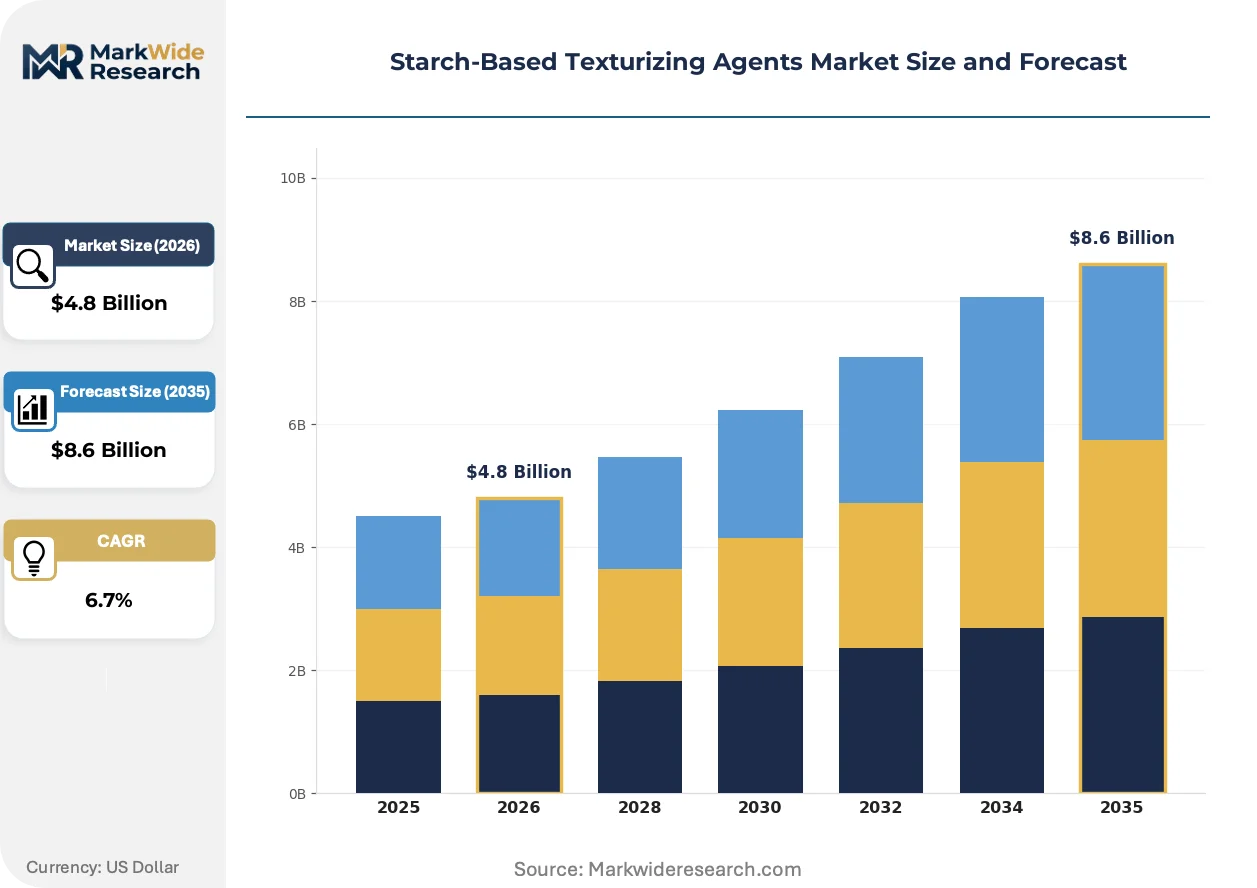
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Instant Starch, Gelatinized Starch, Native Starch Application: Dairy Products, Sauces, Bakery, Confectionery End User: Food Industry, Beverage Industry, Pharmaceutical Sector, Nutraceuticals Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Tate & Lyle PLC, Kerry Group plc, Cargill Inc., Roquette Frères, Beneo GmbH, Ingredion Incorporated, Avebe Group, Ajinomoto Co., Inc., Archer Daniels Midland Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Starch-Based Texturizing Agents Market Evolving Landscape
Clean-label enzymatic modification is overtaking chemical processing as the dominant starch engineering pathway, reshaping competitive positioning around transparency credentials rather than functional performance alone.
Physical modification via high-pressure shear and thermal treatment is overtaking chemical cross-linking in premium bakery applications where E-number avoidance commands shelf price premiums. Artisan and industrial bakers in Germany and France are adopting these starches for laminated dough stability. The shift is compressing demand for traditional acetylated and phosphorylated alternatives in Western European retail channels.
REACH and the EU F-Gas Regulation are tightening chemical processing standards for modified starches used in food contact materials and processing equipment. Industrial consequence includes mandatory substitution of certain cross-linking agents and elevated documentation burdens for chemical modification pathways. German and Dutch starch processors are responding by accelerating capital deployment into enzymatic and physical modification infrastructure.
Ingredient bundling contracts now displace single-component purchasing as the dominant procurement model among mid-scale bakery and dairy manufacturers. Pre-blended texturizing systems that combine starches with hydrocolloids and emulsifiers are capturing share from independent hydrocolloid distributors. This pattern is most visible in German industrial baking clusters where formulation service integration determines supplier selection.
Starch-Based Texturizing Agents Market Segmentation
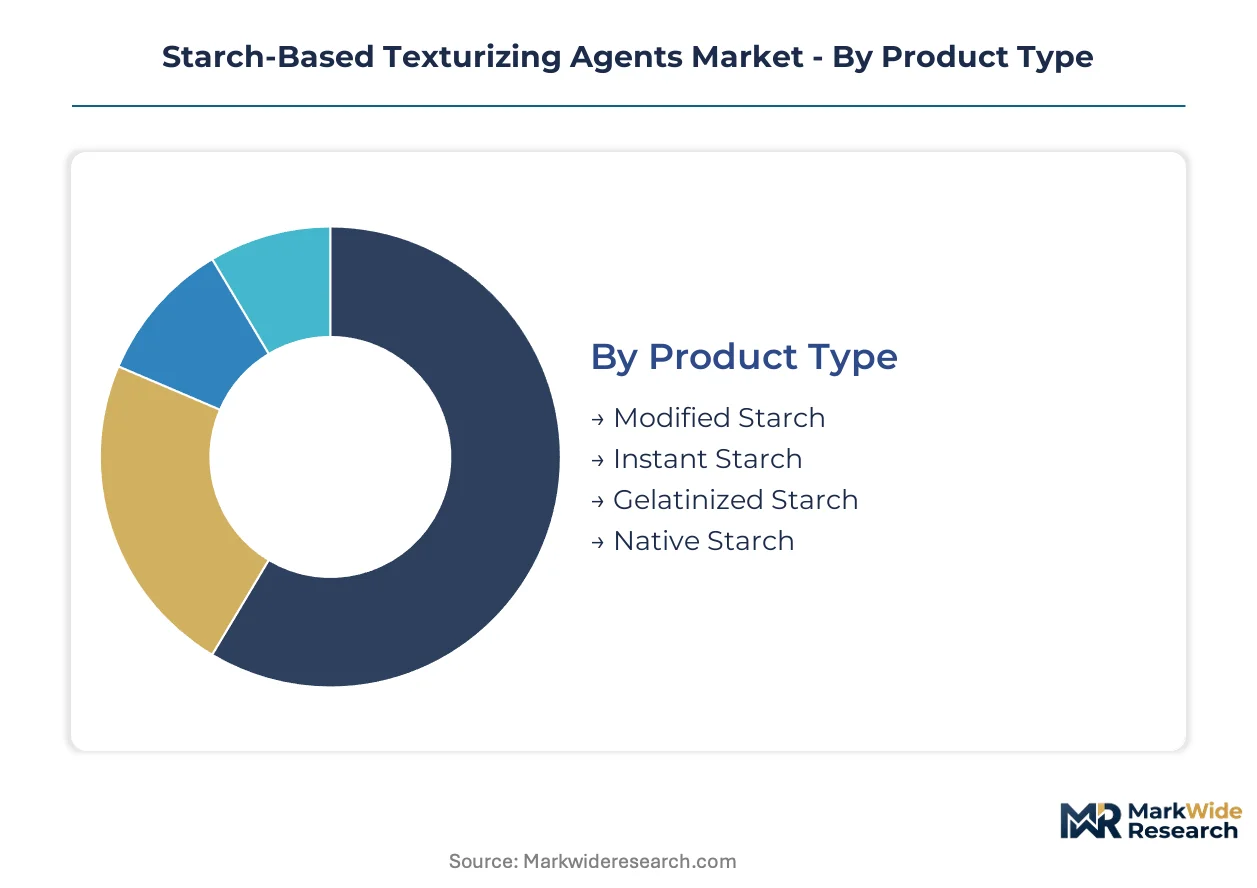
Segmentation in the starch-based texturizing agents market reveals how functional requirements, processing constraints, and procurement patterns fragment demand across distinct technical and commercial boundaries. Each dimension carries specific implications for formulation strategy and supplier selection.
Product Type:
Modified starch dominates standalone ingredient procurement where thermal stability and shear resistance determine specification sheets, while instant and pre-gelatinized variants embed more deeply into pre-blended systems.
- Modified Starch:Chemically or physically altered carbohydrate polymers engineered for viscosity retention under UHT processing and freeze-thaw cycles. German industrial bakeries and dairy processors specify these for laminated dough stability and cream mouthfeel in retail private-label contracts.
- Instant Starch:Pre-gelatinized and agglomerated particles designed for cold-water hydration without heating. Beverage manufacturers in high-speed filling operations prioritize these for line throughput maximization in ready-to-drink protein and plant-based milk applications.
- Gelatinized Starch:Thermally processed native starch with pre-swollen granule structure enabling rapid viscosity development. Commonly specified for no-cook sauce applications and convenience food systems.
- Native Starch:Unmodified carbohydrate polymers retaining original granule integrity and amylose-amylopectin ratios. Serves cost-sensitive applications and clean-label formulations where processing conditions permit lower stability thresholds.
Volume placements concentrate in Modified Starch; the faster expansion belongs to Instant Starch.
Application:
Application segmentation tracks how thermal stress profiles and shelf stability requirements differentiate formulation specifications across food manufacturing verticals.
- Dairy Products:Cultured products, processed cheese, and cream fillings demand starches with acid stability and syneresis control. French and German dairy processors specify these for extended shelf-life desserts.
- Sauces:Pourable and spoonable emulsion systems require starches with freeze-thaw tolerance and clean flavor release. Instant starches with neutral profiles gain preference in high-speed manufacturing.
- Bakery:Laminated doughs, fillings, and glazes utilize modified starches for moisture management and structural integrity. Clean-label enzymatic modifications are displacing traditional chemical cross-linking in Western European retail channels.
- Confectionery:Gelling agents and texture modifiers for jellies, gums, and deposited candies. Specific gel strength and clarity requirements drive specialized starch selection.
Current procurement volumes favor Bakery applications; Nutraceutical and functional food intersections are climbing the fastest.
End User:
End-user segmentation distinguishes between formulation complexity, regulatory scrutiny, and technical service intensity across downstream industries.
- Food Industry:Industrial bakeries, dairy processors, and prepared meal manufacturers constitute the core demand base. German baking clusters drive specification standards through integrated formulation service contracts.
- Beverage Industry:Ready-to-drink and concentrate manufacturers prioritize hydration speed and flavor neutrality. Plant-based milk alternatives represent emerging specification territory.
- Pharmaceutical Sector:Tablet binders, disintegrants, and controlled-release matrices require pharmacopeial-grade starches with documented purity and traceability. Regulatory documentation burdens exceed food-grade requirements.
- Nutraceuticals:Functional food and dietary supplement applications where clean-label credentials and specific digestive properties command premium positioning.
Food Industry placements hold the largest share; Nutraceuticals demonstrate the steepest expansion trajectory.
Distribution Channel:
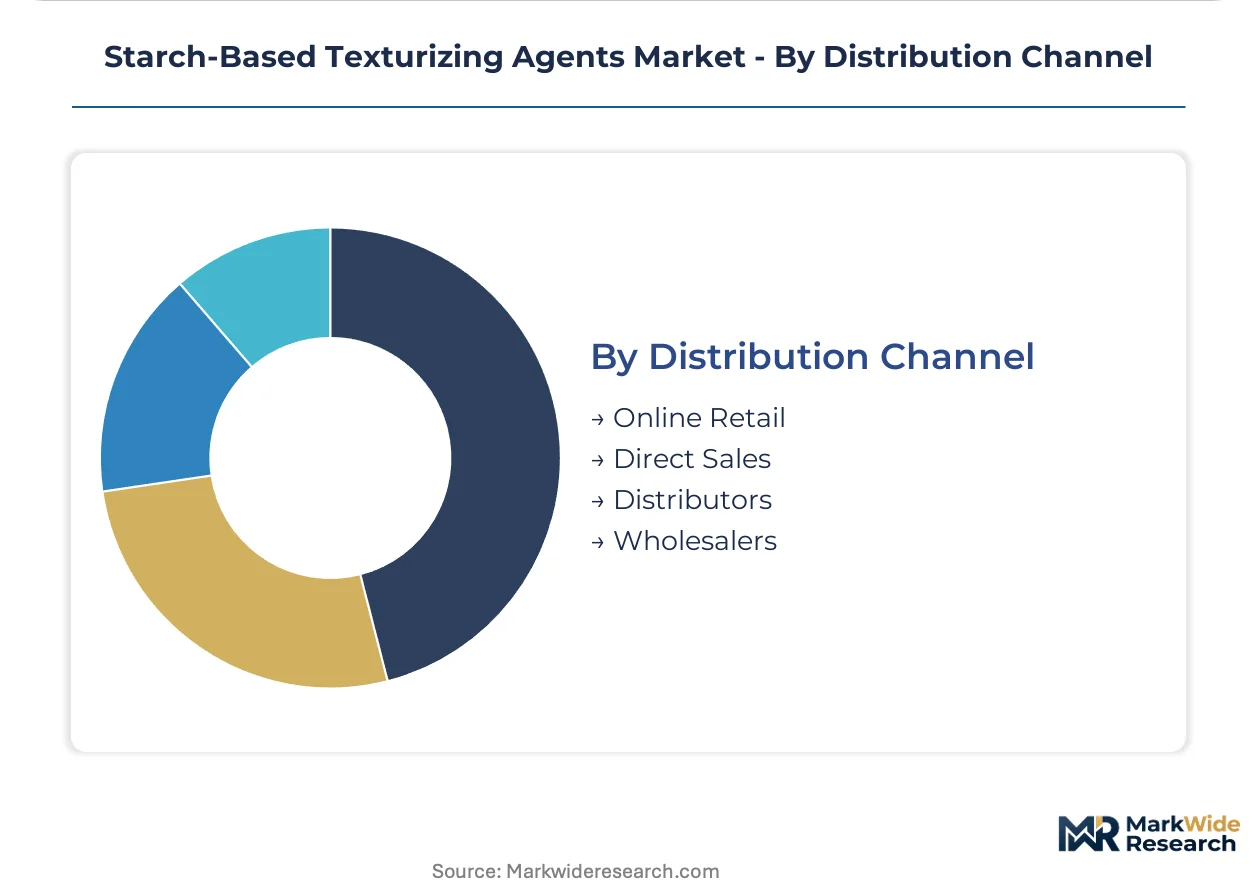
Channel segmentation reflects procurement centralization trends and the displacement of traditional distributor intermediaries by direct manufacturer relationships.
- Direct Sales:Large-scale manufacturers negotiate formulation-integrated contracts with starch producers. Cargill and Kerry Group leverage technical service teams to secure direct relationships with German industrial baking clusters.
- Distributors:Regional ingredient distributors serve mid-scale manufacturers lacking procurement scale for direct sourcing. Margin compression from pre-blended system competition threatens traditional distributor relevance.
- Online Retail:B2B platform procurement emerging for standardized grades and smaller volume orders. Digital channels expand access for specialty and sample quantities.
- Wholesalers:Bulk commodity starch distribution for cost-sensitive applications and geographic markets with fragmented manufacturing bases.
Direct Sales channels capture the dominant volume flow; Online Retail platforms are gaining share fastest among emerging and mid-scale manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in northwestern Europe while consumption spreads across industrial baking and dairy processing centers worldwide. Germany concentrates modification infrastructure around Cologne and Hamburg ports. Demand fragmentation pulls supply chains toward regional formulation service hubs.
Germany
Industrial baking clusters in Lower Saxony and North Rhine-Westphalia drive specification standards for clean-label modified starches. EFSA and REACH compliance mandates accelerate enzymatic processing adoption versus chemical cross-linking pathways. Ingredient manufacturers concentrate around Hamburg port logistics and Cologne chemical processing corridors to serve pan-European dairy and bakery contracts.
United States
Corn belt proximity secures native starch feedstock advantages for Midwest modification facilities serving beverage and sauce manufacturers. FDA GRAS determinations govern labeling transparency requirements that elevate formulation documentation burdens. Chicago and Minneapolis-St. Paul anchor technical service teams supporting direct sales contracts with national bakery and dairy processors.
France
Wheat starch processing heritage in Hauts-de-France and Grand Est regions supplies premium bakery applications with specific amylose-amylopectin ratios. ECHA chemical processing standards redirect capital toward physical modification infrastructure. Lyon and Paris basin dairy processors specify acid-stable starches for extended shelf-life dessert applications.
China
Domestic corn and potato starch production scales serve cost-sensitive sauce and convenience food manufacturers across eastern provinces. SAMR food additive regulations and evolving GB standards tighten import requirements for modified starch classifications. Yangtze River Delta beverage clusters drive instant starch demand for high-speed filling operations in Shanghai and Jiangsu manufacturing zones.
Netherlands
Rotterdam port logistics and Randstad distribution networks position Dutch processors as European supply chain coordinators for specialty starch blends. EU Green Deal carbon accounting requirements favor enzymatic modification investments over legacy chemical pathways. Eindhoven and Groningen host R&D facilities developing hybrid physical-enzymatic processing for thermal-stress bakery applications.
Starch-Based Texturizing Agents Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The vendor base stratifies between integrated grain processors controlling upstream supply and application-focused formulators bundling technical service. Three archetypes dominate: agricultural conglomerates with captive starch supply, ingredient specialists with dairy and bakery formulation labs, and regional modification houses serving cost-sensitive commoditized grades. Competitive moves concentrate on backward integration into grain origination and pre-blended system formulation services that displace single-component distributors.
Among the integrated agricultural conglomerates, Cargill Inc. exemplifies upstream control over corn supply chains from field to modification facility. Kerry Group plc and Tate & Lyle PLC occupy positions within the formulation-specialist tier, anchoring competitive dynamics around technical service intensity and clean-label portfolio breadth. These three represent divergent strategic postures: captive supply security versus application expertise versus regulatory-optimized product architectures.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Kerry Group plc |
| Cargill Inc. |
| Roquette Frères |
| Beneo GmbH |
| Ingredion Incorporated |
| Avebe Group |
| Ajinomoto Co., Inc. |
| Archer Daniels Midland Co. |
| Others |
Value Network & Pricing Analysis
EU Green Deal carbon accounting mandates gate qualified supply access and premium-tier pricing for enzymatic and physically modified starches, redirecting procurement toward compliant German and Dutch processors while compressing margins for legacy chemical modification pathways.
Pricing Analysis
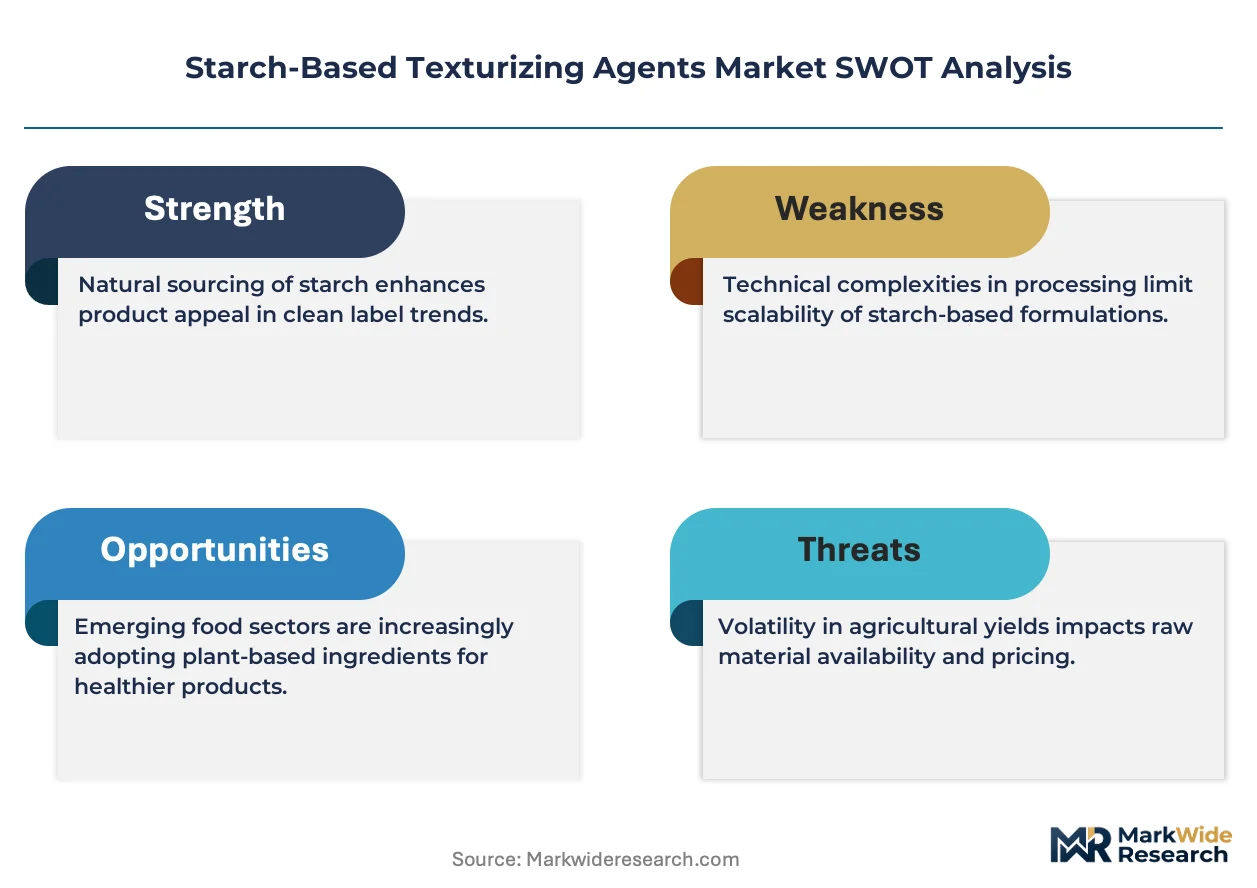
Margin tightening in standard-grade modified starches reflects native corn starch price volatility and REACH compliance cost burdens. Three-tier pricing structure across premium clean-label, standard modified, and economy native grades differentiates by certification level and enzymatic processing investment. Cost-down pressure on chemical cross-linking tiers accelerates as bakery chains eliminate E-number ingredients from retail contracts. Mid-scale dairy processors demonstrate highest price sensitivity; multinational baking conglomerates absorb premiums for formulation-integrated service bundles.
Supply Chain Analysis
Dual-sourcing requirements from German industrial baking clusters mandate qualified backup suppliers for modified starch systems, compressing single-source relationships despite geographic concentration advantages. Supply concentrates in Germany, the Netherlands, and the United States, drawing from corn belt harvests, wheat starch processing heritage, and Rotterdam port logistics. Raw material dependencies rest on corn, wheat, and potato feedstocks. Single-point vulnerability around Cologne-Hamburg modification corridors elevates supply security risk. Distribution runs through direct manufacturer contracts with formulation service integration displacing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into grain origination and captive modification capacity defines the vertical-integration race, with upstream feedstock control and downstream formulation service bundling as the decisive levers separating consolidators from commoditized suppliers.
For Market Incumbents: Lock in exclusive supply contracts with Lower Saxony and North Rhine-Westphalia baking clusters before enzymatic modification capacity shortages harden. Acquire specialized dairy application labs in France to defend against Kerry Group's technical service intensity. Prioritize hybrid physical-enzymatic processing R&D to meet EU F-Gas Regulation substitution timelines.
For New Entrants and Emerging Players: Begin with ready-to-drink protein beverage and plant-based milk alternative segments where clean-label instant starch specifications remain underdeveloped. Target Chinese Yangtze River Delta beverage manufacturers through B2B platform procurement channels. Lead with neutral flavor profile positioning and rapid hydration speed guarantees.
For Investors and Strategic Acquirers: Accelerating capital deployment into enzymatic modification infrastructure by established Dutch and German processors is the leading indicator that premium-tier margin pools are consolidating ahead of chemical pathway obsolescence. Five-to-ten-year viability favors application-focused formulators with dairy and bakery lab networks over commodity modification houses. Watch for REACH documentation burden spikes signaling distressed asset availability.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Modification Capacity Expansion | EU Green Deal compliance secures access to German retail private-label contracts. |
| Backward Integration into Grain Origination | Cargill's field-to-formulation model captures native starch quality premiums. |
| Pre-blended Texturizing System Development | Formulation service bundling displaces independent hydrocolloid distributors. |
| Hybrid Physical-Enzymatic Processing Investment | Combines enzyme precision with thermal stability for laminated dough applications. |
| Direct-to-Manufacturer Digital Channel Buildout | B2B platform procurement compresses distributor margins while expanding formulation services. |
Research Methodology
Independent corroboration across formulation directors at German industrial baking clusters, procurement leads at French dairy processors, and technical R&D heads at Dutch starch modification facilities underwrites the qualitative findings. Secondary validation draws from EFSA guidance documents, REACH registration databases, EU F-Gas Regulation implementation notices, and customs trade data for starch derivative flows. Bottom-up volume modeling across product type, application, and end-user segments triangulates against top-down industry aggregation.
Comparable-period anchoring to historical modified starch demand patterns across bakery, dairy, and beverage verticals structures the projection horizon. Segmentation dimensions modeled include modification pathway, thermal stability grade, clean-label certification tier, and regional regulatory cluster. CAGRs derive from trend extrapolation adjusted for enzymatic adoption curves and substitution elasticity between chemical and physical modification. Forecast inputs incorporate EU Green Deal implementation pace and instant starch hydration speed requirements in high-speed filling operations.
Underlying measurement precision varies by segment; modified starch volume estimates carry tighter precision than emerging nutraceutical applications. Forecasts reflect assumptions around regulatory substitution timelines and clean-label definition convergence. Deviation in EU F-Gas Regulation enforcement intensity or native corn harvest volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Dairy Enzymes Market
Food Additives and Ingredients
North America Food Starch Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Cocoglycerides Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Starch-Based Edible Coatings Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
North America Food Enzymes Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Japan Food Acidulants Market