
 Australia Food Preservatives Market | 2026-2036
Australia Food Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Preservatives Market Outlook
Asset-light toll manufacturing and third-party blending arrangements is narrowing the capital barrier for mid-tier ingredient suppliers seeking national distribution. Cargill Inc leverages its integrated grain processing network to secure cost-advantaged sorbic acid feedstock for Australian operations. Kerry Group plc anchors its position through specialized antimicrobial blends tailored to local meat export protocols. BASF SE competes via technical service partnerships with major bakery chains requiring customized propionate solutions.
Australia food preservatives comprise chemical and natural substances added to food matrices at concentrations typically ranging from 0.05% to 0.3% by weight to inhibit microbial proliferation, oxidative rancidity, and enzymatic browning, thereby extending shelf stability under ambient and refrigerated storage conditions. Sorbates dominate volume consumption across the country's processed food sector due to broad pH efficacy and favorable regulatory status under FSANZ Standard 1.3.1. Benzoates maintain entrenched positions in acidic beverage applications where cost-performance ratios remain superior to alternative preservation systems. Antimicrobial function categories command the largest share of formulation value, reflecting meat and dairy processors' stringent pathogen control requirements for both domestic retail and export market access.
FSANZ Standard 1.3.1 governs maximum permitted levels and labeling declarations for all preservative additives in Australian food products, while the Australia New Zealand Food Standards Code mandates quantitative ingredient declarations that directly influence clean-label product development priorities. TGA oversight of novel preservative substances entering therapeutic or functional food categories creates additional approval pathways affecting innovation timelines. Stakeholders must monitor pending FSANZ proposals on reduced maximum levels for select benzoate applications and assess reformulation investments against emerging natural preservation technologies before regulatory thresholds shift.
Market Dynamics
FSANZ label transparency mandates are compressing formulation timelines as meat processors and bakery chains race to replace synthetic preservatives with clean-label alternatives before regulatory thresholds shift. This regulatory pressure intersects with export protocol requirements, forcing simultaneous compliance with multiple preservation standards.
Growth Catalysts
- Export meat protocol compliance:Australian beef and lamb processors require antimicrobial preservation systems that satisfy both domestic retail and destination market access requirements, expanding procurement of specialized sorbate blends.
- FSANZ Standard 1.3.1 reformulation window:Pending proposals on reduced benzoate maximum levels are accelerating R&D investment in natural acidification and fermentation-derived preservation alternatives.
- Sydney-Melbourne processing cluster expansion:Concentrated food manufacturing in Victoria and New South Wales creates procurement density that supports dedicated preservative distribution infrastructure.
Market Restraints
- Petrochemical feedstock volatility:Sorbic acid and benzoic acid production costs fluctuate with benzene and acetic acid pricing, compressing margin predictability for local formulators.
- Natural extract supply concentration:Rosemary extract and green tea polyphenol sourcing depends on concentrated Mediterranean and East Asian agricultural zones, exposing buyers to harvest variability.
- pH efficacy limitation:Natural antimicrobial peptides demonstrate narrow activity windows compared to synthetic alternatives, restricting application in neutral-pH prepared meals.
Strategic Opportunities
- Queensland and Western Australia penetration:Food processing capacity in these states remains underdeveloped relative to preservative distribution coverage, creating first-mover positioning for regional blending facilities.
- Plant-based protein preservation:Meat alternative manufacturers require customized mold inhibition and oxidative stability systems distinct from traditional meat applications.
- TGA functional food pathway:Novel preservatives with probiotic or gut-health positioning can access accelerated approval through therapeutic goods classification, opening premium positioning channels.
Industry Challenges
- Clean-label formulation expertise scarcity:Food technologists skilled in natural preservation system design command premium compensation, constraining mid-tier manufacturer hiring pipelines.
- Dual certification timeline compression:Products requiring both FSANZ compliance and destination country export approval face extended validation cycles that delay commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Preservatives Market |
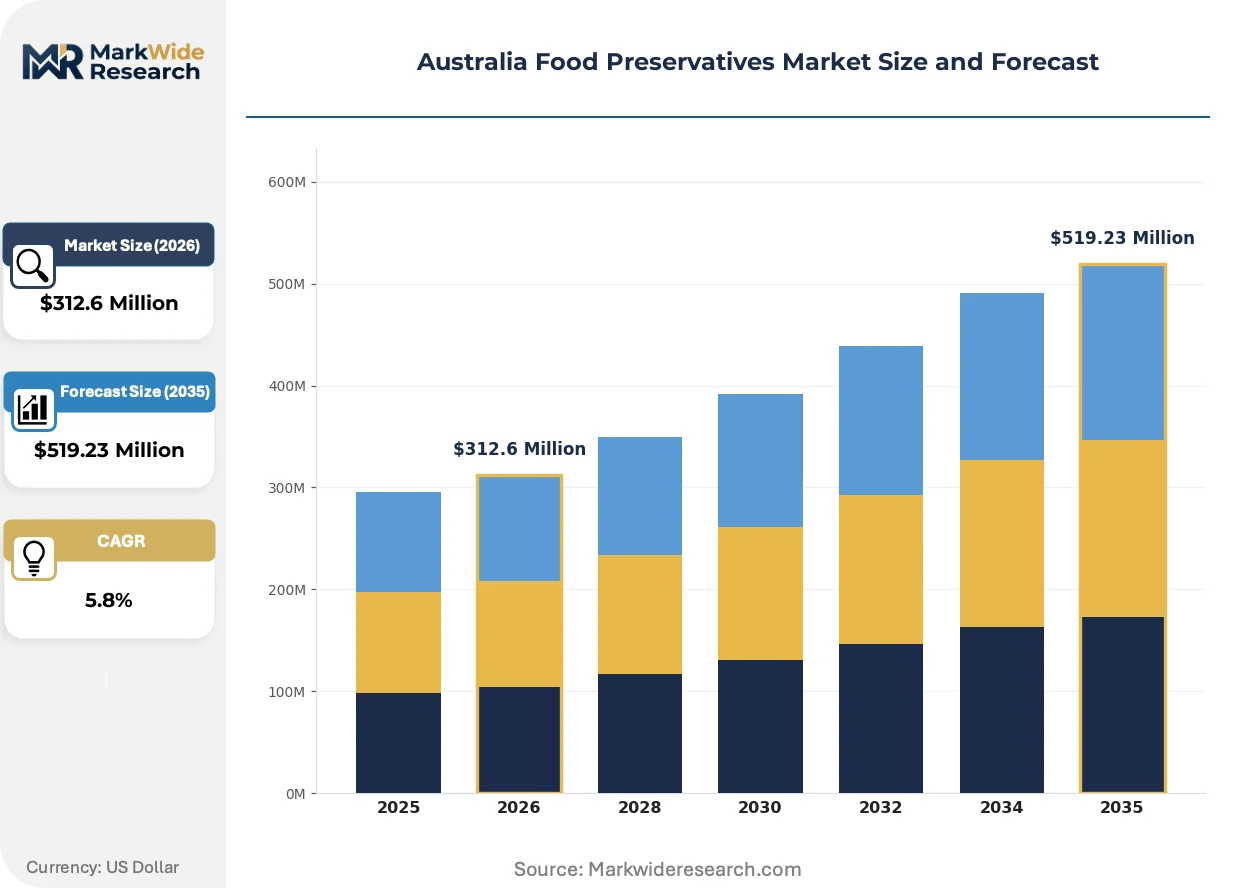
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $519.23 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sorbates, Benzoates, Nitrates, Propionates End User: Food Processing, Beverages, Bakery, Dairy Function: Antimicrobial, Antioxidant, Flavoring Agent, Color Retention Form: Liquid, Powder, Granule, Gel |
| Companies Covered | Cargill Inc, Koninklijke DSM N.V., Archer Daniels Midland Company, Jungbunzlauer Suisse AG, Brenntag Inc., DuPont de Nemours Inc., BASF SE, Kerry Group plc, Tate & Lyle PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Preservatives Market Strategic Shifts
Preservation technology in Australian food manufacturing is pivoting toward bio-derived solutions that satisfy both regulatory disclosure requirements and extended shelf-life specifications for export-bound products. This shift is compressing traditional synthetic preservatory cycles while opening new formulation service revenue streams.
High-pressure processing and cold plasma surface treatment are migrating from premium beverage applications into ready-to-eat meal and fresh-cut produce preservation. Major supermarket chains in Sydney and Melbourne are piloting these non-thermal systems to eliminate chemical preservatives from private-label prepared foods. The technology is migrating from niche premium positioning toward mainstream cost parity as equipment manufacturers scale standardized unit designs.
FSANZ proposals on quantitative ingredient declaration thresholds are forcing reformulation investments ahead of formal rule adoption. Processed meat manufacturers face the steepest compliance burden, as current benzoate and nitrite labeling triggers consumer rejection in clean-label-sensitive retail channels. These processors are accelerating partnerships with natural preservation specialists to maintain shelf stability while achieving label simplification.
Direct procurement relationships between food manufacturers and specialty ingredient distributors are displacing traditional broad-line chemical supply arrangements. Mid-tier meat processors in regional Victoria are contracting directly with antimicrobial blend formulators, bypassing generalist distributors to secure technical service and custom formulation support. This pattern concentrates most visibly in export-oriented facilities where preservation system failure carries destination market access penalties.
Australia Food Preservatives Market Segmentation
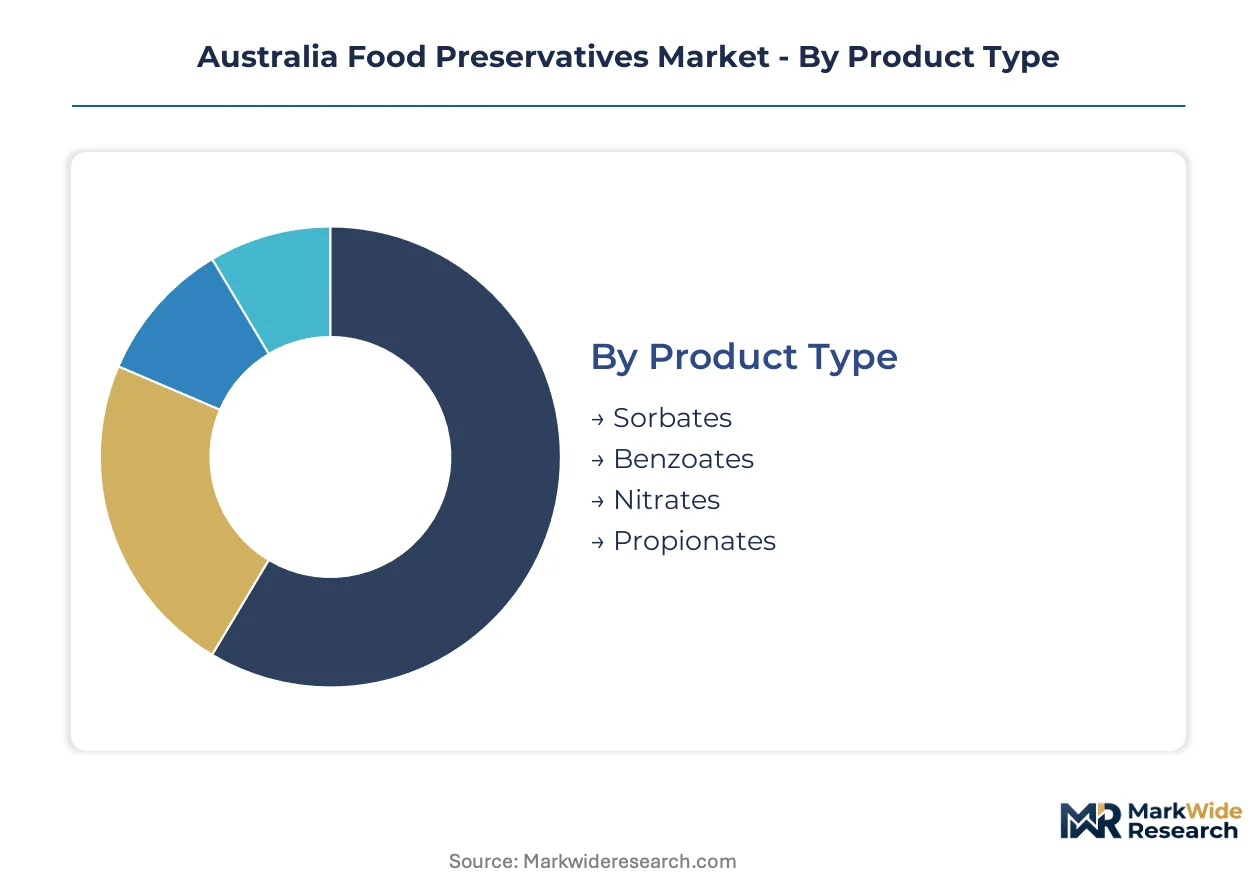
Australia's food preservative segmentation reflects the tension between mature synthetic chemistries and emerging natural alternatives. FSANZ disclosure mandates are compressing demand toward function-specific solutions that satisfy both shelf-life targets and clean-label retail positioning.
Product Type:
Mature synthetic categories dominate procurement volumes, though emerging fermentation-derived alternatives are capturing reformulation budgets ahead of regulatory threshold shifts.
- Sorbates:Potassium sorbate and sorbic acid formulations inhibit mold and yeast across pH ranges from 2.5 to 6.5, making them indispensable in processed meat applications. Victorian meat processors account for the heaviest procurement concentration, driven by export protocol compliance requirements for extended ambient stability during ocean freight.
- Benzoates:Sodium benzoate and benzoic acid derivatives deliver cost-efficient antimicrobial protection in acidic beverage matrices below pH 4.5. Sydney and Melbourne beverage manufacturers maintain entrenched positions here, though pending FSANZ maximum level reductions are forcing accelerated R&D into acidification alternatives.
- Nitrates:Sodium nitrite and potassium nitrate preserve cured meat color while inhibiting Clostridium botulinum spore germination.
- Propionates:Calcium and sodium propionate variants prevent rope spoilage in yeast-leavened bakery products through specific anti-mold action.
Sorbates handle the majority of throughput; benzoates are expanding most quickly on reformulation investment intensity.
End User:
Cost tier differentiation separates commodity-scale processors from premium-positioned manufacturers seeking specialized technical service partnerships.
- Food Processing:Ready-to-eat meal and processed meat manufacturers require multi-hurdle preservation systems combining antimicrobials with modified atmosphere packaging. New South Wales and Victoria processing clusters generate procurement density that supports dedicated distribution infrastructure and on-site technical support.
- Beverages:Acidic soft drink and juice processors favor benzoate-sorbate blends for yeast and mold control, though natural acidification with cultured dextrose is displacing synthetic options in premium positioning channels.
- Bakery:Industrial bread and cracker manufacturers rely on propionate-based mold inhibition for extended shelf-life without refrigeration.
- Dairy:Yogurt and cheese processors employ sorbate surface treatments and natamycin coatings for fungal control in high-moisture products.
Food processing commands the largest formulation value; beverages are climbing the fastest on clean-label substitution momentum.
Function:
Application requirements dictate whether antimicrobial efficacy, oxidative stability, or sensory preservation takes priority in formulation design.
- Antimicrobial:Pathogen inhibition and spoilage organism control systems command premium pricing due to export market access dependencies. Australian beef and lamb processors invest heavily here, as preservation system failure carries destination country rejection penalties that dwarf ingredient costs.
- Antioxidant:Ascorbyl palmitate, tocopherols, and rosemary extract prevent lipid oxidation in high-fat meat and snack applications.
- Flavoring Agent:Certain organic acids and their salts contribute both preservation and sensory modulation functions.
- Color Retention:Nitrite-based curing systems maintain characteristic pink hues in processed meats while delivering antimicrobial co-benefits.
Antimicrobial functions absorb the greatest R&D expenditure; antioxidant applications are gaining share fastest on natural extract sourcing improvements.
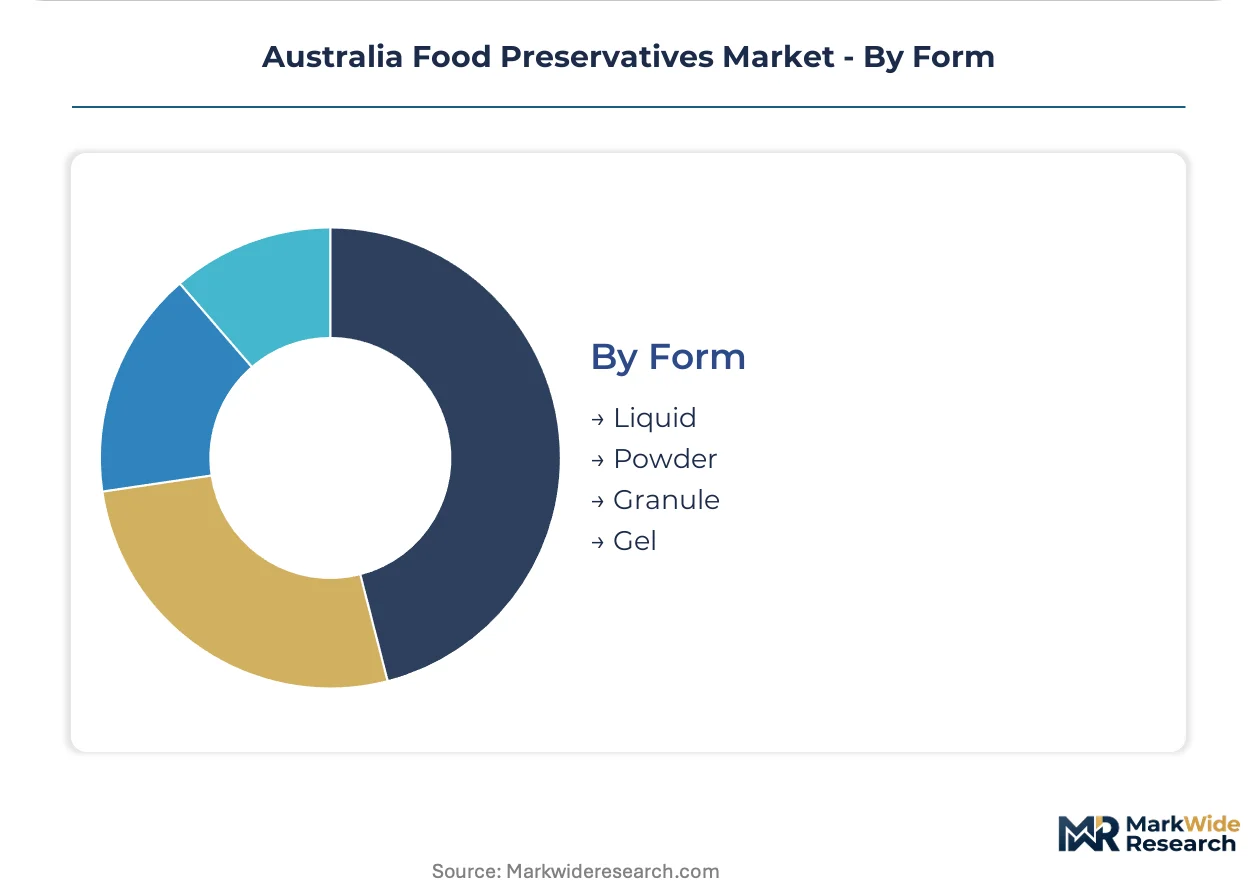
Form:
Supply concentration in liquid and powder formats reflects manufacturing infrastructure legacy, with emerging gel and granule variants targeting specific application efficiencies.
- Liquid:Pumpable sorbate and benzoate solutions enable automated dosing in high-throughput beverage and sauce manufacturing. Melbourne and Sydney blending facilities maintain regional distribution advantages for bulk liquid formats.
- Powder:Free-flowing propionate and sorbate powders facilitate dry blending in flour-based applications.
- Granule:Low-dust granulated formats improve handling safety and dissolution kinetics in meat processing environments.
- Gel:Thixotropic antimicrobial gels enable surface application uniformity in irregular meat cuts.
Liquid forms move the highest absolute volumes; gel formulations are expanding most steeply on specialized meat processing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FSANZ disclosure mandates and export protocol requirements are redistributing preservative procurement across Australian states, with processing clusters in Victoria and New South Wales absorbing the heaviest reformulation investment while Queensland and Western Australia present underdeveloped distribution coverage.
New South Wales
Sydney's ready-to-eat meal manufacturers are expanding sorbate procurement to satisfy extended shelf-life specifications for supermarket private-label contracts. FSANZ Standard 1.3.1 compliance costs are accelerating partnerships with specialized antimicrobial blend suppliers. The Parramatta-Ryde processing corridor hosts concentrated beverage manufacturing that drives benzoate consumption despite pending maximum level reductions.
Victoria
Melbourne anchors national meat processing output, with beef and lamb exporters requiring multi-hurdle preservation systems for destination market access. TGA oversight of novel functional food preservatives creates additional approval pathways for local manufacturers. The Geelong-Ballarat corridor supports dedicated distribution infrastructure serving regional meat processors with on-site technical service capabilities.
Queensland
Brisbane's emerging food manufacturing base is attracting first-mover preservative distributors seeking to establish regional blending facilities ahead of capacity expansion. State government food industry development programs are incentivizing processing investment outside traditional southeastern clusters. The Logan-Ipswich corridor shows early concentration in dairy processing driving natamycin and sorbate surface treatment demand.
Western Australia
Perth's isolated processing sector relies on extended supply chains that create cost premiums for liquid preservative formats. The state's mining-dependent economy limits food manufacturing scale relative to national output. Fremantle-port logistics constraints are prompting direct procurement relationships with specialty ingredient distributors bypassing traditional broad-line chemical arrangements.
South Australia
Adelaide's wine and beverage sector maintains entrenched benzoate positions in acidic applications despite clean-label substitution pressure. The state's smaller processing scale limits dedicated preservative distribution infrastructure compared to eastern states. Barossa Valley food tourism is stimulating artisanal product development with natural preservation system requirements distinct from industrial formulations.
Australia Food Preservatives Market Competitive Environment
On the supply side, the industry is consolidating around integrated grain processors and specialized antimicrobial formulators capable of delivering technical service alongside commodity chemistries. Strategic archetypes include global agricultural conglomerates with captive feedstock positions, European fermentation-derived specialists, and regional toll-blending operators serving mid-tier meat processors. Dominant competitive moves encompass backward integration into sorbic acid feedstock and portfolio diversification toward clean-label fermentation extracts.
Among global agricultural conglomerates, Cargill Inc exemplifies the integrated feedstock archetype through grain processing network leverage. Kerry Group plc occupies the specialized formulation tier with antimicrobial blends tailored to export protocol requirements. BASF SE anchors the technical service model through customized propionate solutions for bakery chain partnerships. Koninklijke DSM N.V. represents the fermentation-derived specialist position with natural preservation technologies. Archer Daniels Midland Company sits within the diversified ingredient supplier tier with broad chemical and natural product coverage.
| Leading Market Players |
|---|
| Cargill Inc |
| Koninklijke DSM N.V. |
| Archer Daniels Midland Company |
| Jungbunzlauer Suisse AG |
| Brenntag Inc. |
| DuPont de Nemours Inc. |
| BASF SE |
| Kerry Group plc |
| Tate & Lyle PLC |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Queensland and Western Australia blending facilities is compressing procurement costs for eastern processors while elevating freight premiums for Perth manufacturers, creating divergent supplier behavior and pricing postures across state boundaries. This utilization gap rewards first-movers establishing regional toll-manufacturing presence while penalizing isolated buyers dependent on Melbourne-Sydney supply lines.
Pricing Analysis
Certification level (FSANZ-grade versus export-protocol-grade) creates the primary spread between commodity sorbate blends and specialized antimicrobial formulations for meat processors. Three-tier pricing structure across premium, standard, and economy levels reflects technical service bundling, with Victorian export facilities absorbing premium tiers for destination-market compliance support. Cost compression in standard-grade benzoates is intensifying because pending FSANZ maximum level reductions are accelerating substitution R&D. Mid-tier meat processors in regional Victoria demonstrate highest price sensitivity, while export-oriented lamb processors in New South Wales prioritize technical service over unit cost.
Supply Chain Analysis
Toll-blending concentration in Melbourne and Sydney corridors dominates national capacity, with Brenntag and regional operators holding established infrastructure. Feedstock sourcing draws from Chinese sorbic acid production, Malaysian palm-derived raw materials, and domestic grain-based fermentation inputs. Single-source vulnerability concentrates in Chinese petrochemical feedstock for synthetic acid production, exposing formulators to benzene price volatility and tariff exposure. Distribution runs through dedicated chemical logistics networks serving Victoria and New South Wales processing clusters, with direct procurement relationships increasingly displacing broad-line distributor arrangements for technical service-dependent buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
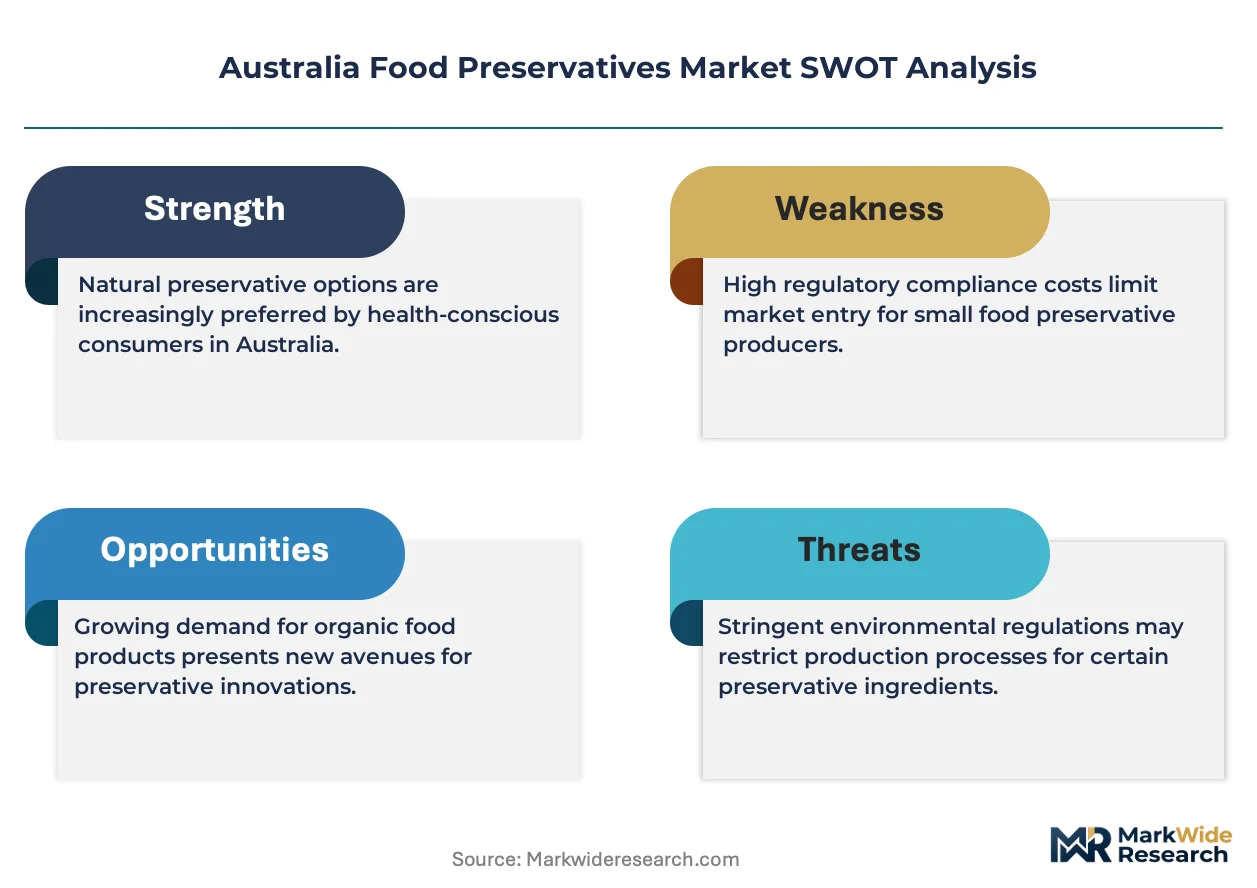
This market functions as a defensive-moat story anchored in regulatory entrenchment. FSANZ approval pathways and export protocol certification create switching costs that protect incumbent positions against commodity substitution.
For Market Incumbents: Pre-empt emerging natural preservation specialists by acquiring fermentation-derived technology capabilities before TGA functional food pathways mature. Secure backward integration into sorbic acid feedstock through grain processing partnerships, defending margin position against petrochemical volatility. Expand technical service teams in Queensland to capture first-mover regional blending advantages.
For New Entrants and Emerging Players: Build out regional blending capacity in Brisbane and Perth corridors where distribution infrastructure remains underdeveloped relative to processing expansion. Target plant-based protein manufacturers with customized mold inhibition systems distinct from traditional meat applications. Establish direct procurement relationships with mid-tier processors seeking FSANZ compliance support without premium-tier pricing.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because regulatory complexity and technical service requirements favor scaled formulators over commodity distributors. Acquisition candidates include regional toll-blenders with established FSANZ relationships and natural preservation specialists with TGA functional food pathway experience. Monitor FSANZ proposal adoption timelines as inflection signal for reformulation investment cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sorbic Acid Feedstock | Cargill's grain processing network secures cost-advantaged captive supply for Australian operations. |
| Regional Blending Facility Expansion | Queensland infrastructure addresses undercapacity and reduces freight premiums for Brisbane processors. |
| Natural Preservation Technology Acquisition | Fermentation-derived specialists capture reformulation budgets ahead of FSANZ threshold shifts. |
| Export Protocol Technical Service Partnerships | Kerry Group's antimicrobial blends satisfy destination market access requirements for lamb exporters. |
| TGA Functional Food Pathway Navigation | Novel preservatives with probiotic positioning access accelerated approval and premium channel positioning. |
Study Parameters
Desk research of FSANZ regulatory filings, customs import records, and food industry association datasets preceded structured interviews with antimicrobial blend formulators, meat processing procurement directors, and bakery chain technical managers. Primary fieldwork with Victorian export facilities and Sydney ready-to-eat meal manufacturers validated secondary demand estimates. Bottom-up procurement volume modeling triangulated against top-down market sizing from industry production statistics.
Assumptions held FSANZ Standard 1.3.1 maximum levels constant across the projection horizon while varying natural substitution penetration rates and regional processing capacity expansion scenarios. Segmentation dimensions modeled include product type (sorbates, benzoates, propionates, nitrates), end-use industry (meat processing, beverages, bakery, dairy), function category (antimicrobial, antioxidant, color retention), and geographic cluster (Victoria, New South Wales, Queensland, Western Australia). CAGRs derived from weighted average of historical volume trends and forward-looking capacity utilization signals.
Sensitivities concentrate around FSANZ regulatory proposal adoption timing, Chinese petrochemical feedstock price volatility, and natural extract harvest variability from Mediterranean rosemary and East Asian green tea sources. Forecasts reflect these documented assumptions and risk factors. Quarterly review of FSANZ amendment notices and destination country export protocol changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Butyric Acid Market
Food Additives and Ingredients
Neohesperidine DC Market
Food Additives and Ingredients
North America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
Africa Food Additives Market
Food Additives and Ingredients
Germany Food Additives Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Argentina Food Acidulants Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Sucroglycerides Market