
 Bulk Tote Dumpers Market | 2026-2036
Bulk Tote Dumpers Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Tote Dumpers Market Outlook
North American material handling equipment builders is broadening production capacity for sanitary bulk handling systems. National Bulk Equipment sustains a product portfolio centered on USDA- and FDA-compliant designs for dairy and protein processing lines. Flexicon leverages integrated bulk handling ecosystems that span conveying, discharging, and containment functions. PPM Technologies anchors its position through specialized food-grade dumper configurations engineered for fragile and coated products.
Bulk tote dumpers are mechanized material handling machines designed to lift and invert intermediate bulk containers, typically to heights of eight to twelve feet, for controlled discharge of powders, granules, or semi-solid materials into downstream processing equipment. Stainless steel construction dominates food and pharmaceutical installations where surface finish, weld quality, and cleanability under CIP protocols determine equipment qualification. Stationary dumpers occupy the mature core of the installed base, while mobile dumpers are gaining share in facilities reconfiguring production lines for shorter batch runs and multi-product flexibility. Electric drive technology leads new equipment specification due to precision speed control and reduced hydraulic fluid contamination risk in clean environments.
OSHA ergonomic standards and FDA sanitary equipment design guidelines shape buyer specification sheets and vendor qualification checklists across the United States. The USDA Dairy Grading Branch and 3-A Sanitary Standards organization further constrain equipment geometry and surface specifications in dairy and beverage applications. Buyers must weigh total cost of ownership against compliance documentation burden when evaluating domestic fabrication against imported alternatives.
Market Dynamics
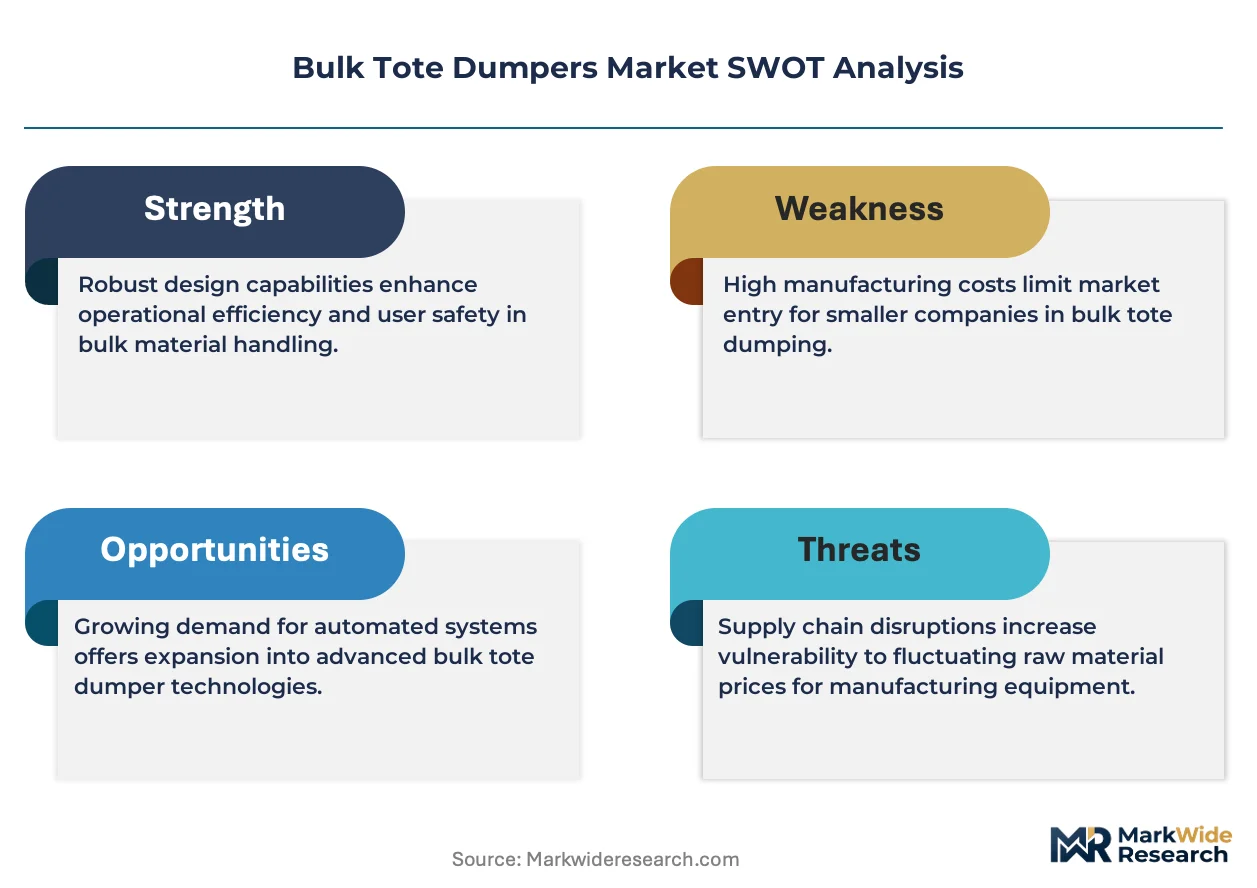
Automated material handling systems are displacing manual tote dumping operations across food and pharmaceutical processing facilities, driven by OSHA ergonomic mandates and FDA sanitary design requirements that now disqualify legacy equipment from new facility approvals.
Growth Catalysts
- OSHA Ergonomic Mandates:Federal workplace safety standards now require mechanical assistance for repetitive lifting above fifty pounds, forcing protein processing plants to retrofit manual dumping stations with powered equipment.
- Batch Size Compression:Contract manufacturers serving multiple food brands are adopting mobile dumpers to enable rapid line changeovers between allergen-controlled and standard production runs.
- Stainless Steel Supply Localization:Domestic fabrication of sanitary-grade 304 and 316L enclosures is shortening lead times for North American equipment builders qualifying for USDA dairy processing contracts.
Market Restraints
- Specialized Fabrication Concentration:Precision TIG welding for FDA-compliant surface finishes concentrates among certified shops in Wisconsin and Ohio, creating supply bottlenecks during capacity expansion cycles.
- Electric Drive Component Lead Times:Servo motors and variable frequency drives for precise speed control face extended procurement timelines from industrial automation suppliers.
- Used Equipment Arbitrage:Refurbished hydraulic dumpers from decommissioned beverage plants compete against new electric models on upfront capital expenditure comparisons.
Strategic Opportunities
- Cellular Agriculture Integration:Precision fermentation facilities producing cultivated proteins require sanitary bulk handling systems engineered for sterile media transfer and containment.
- Clean-in-Place Automation Convergence:Dumpers integrating spray ball arrays and drainable bases with PLC-controlled sequencing are capturing pharmaceutical bioprocessing installations.
- Midwest Manufacturing Corridor Density:Chicago-Milwaukee-Minneapolis ingredient processing clusters create service and parts logistics advantages for regional equipment builders.
Industry Challenges
- Sanitary Welding Certification Bottlenecks:ASME BPE and 3-A SSI qualification timelines for weld procedures and welder performance extend equipment delivery schedules by eight to fourteen weeks.
- Legacy Control System Integration:Brownfield dairy plants operating vintage SCADA architectures face commissioning delays when connecting modern Ethernet/IP-enabled dumpers to proprietary networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Tote Dumpers Market |
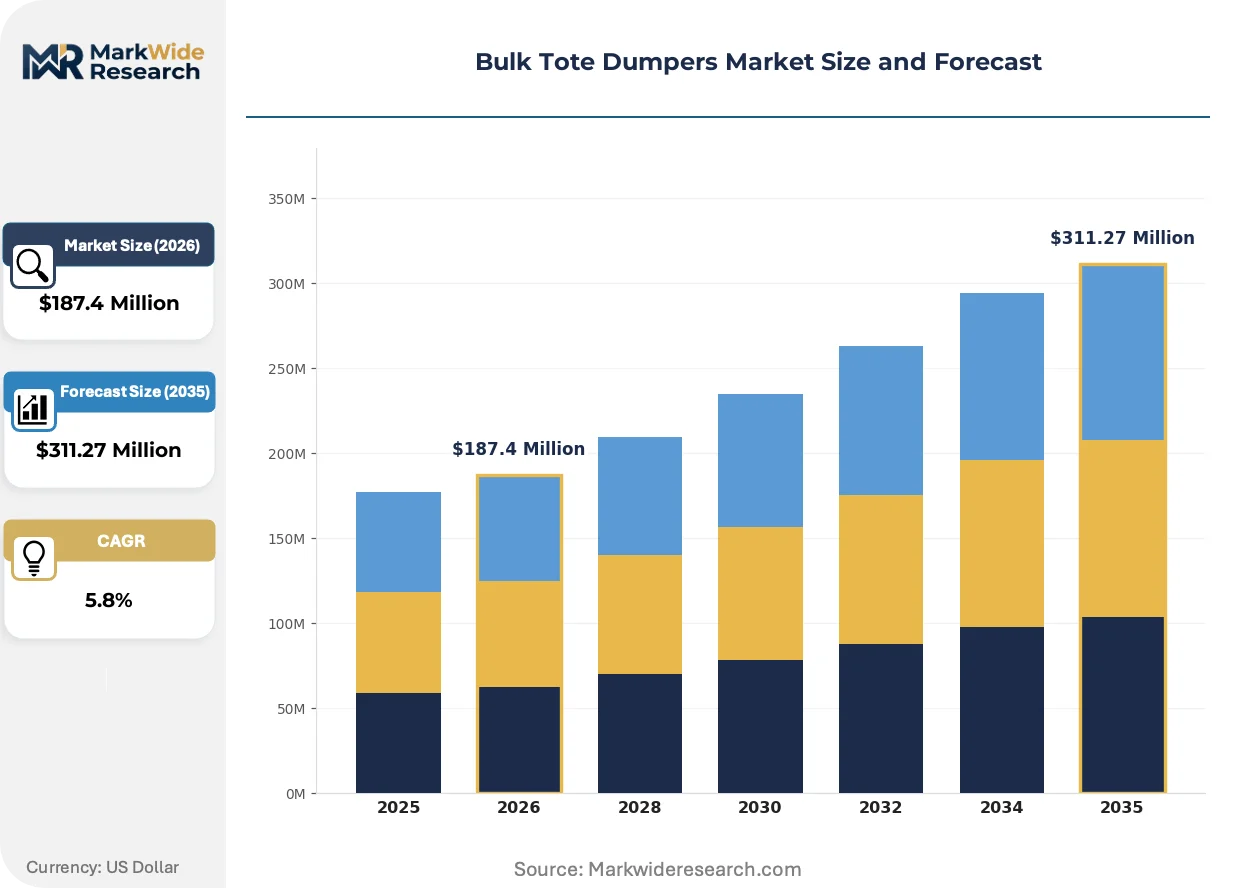
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mobile Dumpers, Stationary Dumpers, Custom Dumpers, Pneumatic Dumpers End User: Food Processing, Pharmaceuticals, Chemicals, Agriculture Technology: Hydraulic, Electric, Manual, Pneumatic Material: Stainless Steel, Aluminum, Carbon Steel, Plastic |
| Companies Covered | Automated Conveyor Company, CDS-LIPE, National Bulk Equipment, TOTE Systems, Weening Brothers Mfg, California Food Machinery, PPM Technologies, CM Process Solutions, Flexicon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Tote Dumpers Market Strategic Shifts
Equipment specification sheets are prioritizing cleanability validation and data connectivity over mechanical throughput metrics, reflecting buyer risk management priorities in regulated processing environments.
Electromechanical lift-and-rotate mechanisms are integrating sealed brushless motors and absolute encoders to eliminate hydraulic fluid contamination risks in aseptic suites. Pharmaceutical fill-finish operations and high-care food zones are specifying these drives for precise container positioning. The technology is integrating predictive maintenance algorithms that flag bearing wear and belt tension drift before unplanned downtime.
FDA's Food Safety Modernization Act traceability rules are forcing equipment builders to embed RFID readers and vision systems at dumping stations. Lot code verification and container weight capture now flow automatically to manufacturing execution systems. Dairy and ready-to-eat cereal processors in the upper Midwest are retrofitting existing dumpers with these data acquisition modules to avoid regulatory penalties.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-sized co-manufacturers. Monthly payments covering hardware, preventive maintenance, and compliance documentation reduce balance sheet pressure for facilities running multi-year production agreements. This arrangement concentrates in the United States contract packaging sector where customer switching costs and brand liability exposure favor operational expenditure structures.
Bulk Tote Dumpers Market Segmentation
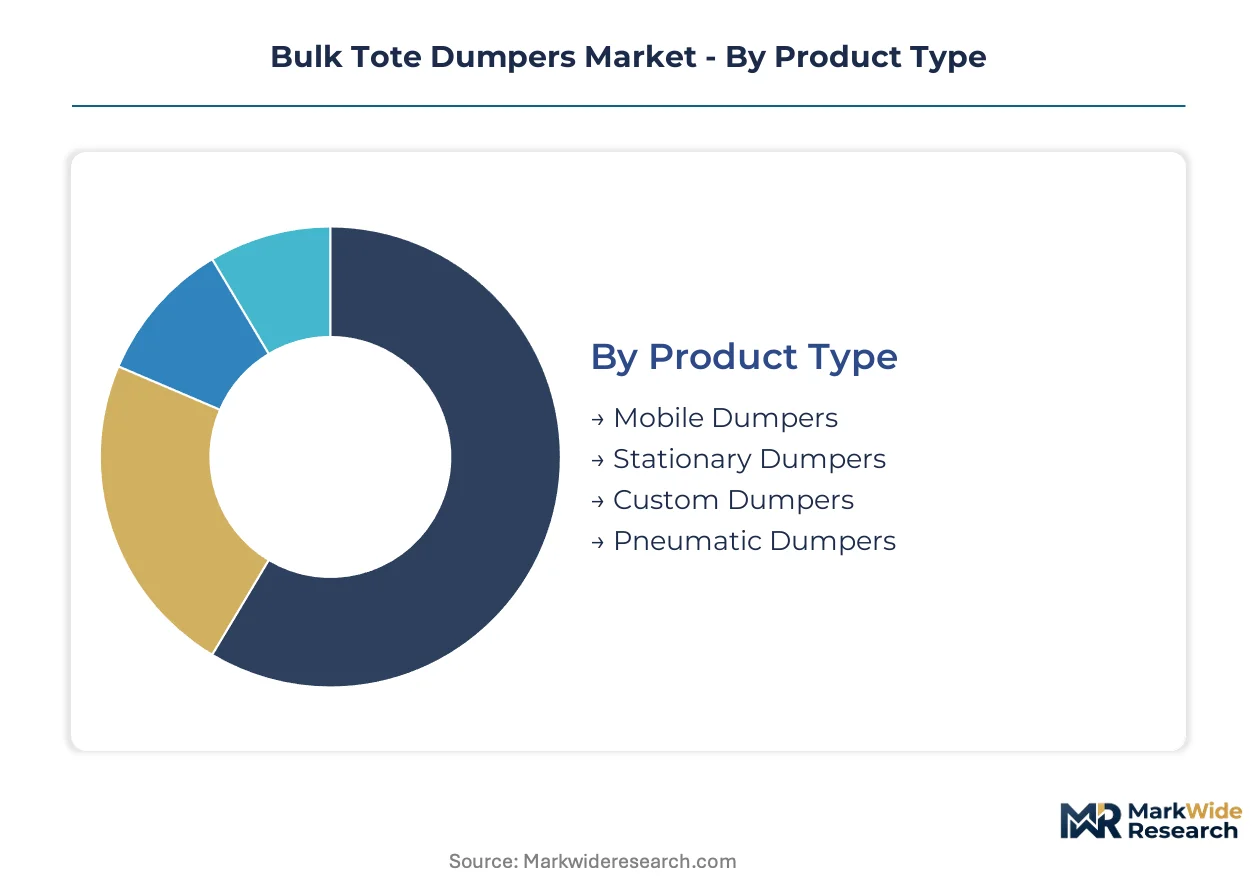
Segmentation in bulk tote dumpers reveals how equipment specification diverges between integrated production lines and standalone material handling stations. Buyers select across product mobility, power transmission, and construction material based on contamination risk, batch frequency, and regulatory exposure.
Product Type:
Integration depth varies sharply: mobile dumpers serve reconfigurable lines while stationary units anchor permanent installations.
- Stationary Dumpers:Fixed-base machines with welded frames and permanent utility connections dominate high-volume dairy and protein processing plants. FDA-compliant stainless steel enclosures and integrated CIP manifolds position these units in the upper Midwest manufacturing corridor where USDA dairy contracts concentrate.
- Mobile Dumpers:Castor-mounted units with quick-disconnect power and pneumatic docking systems enable rapid repositioning between allergen-controlled and standard production zones. Contract manufacturers running shorter batch cycles for multiple food brands drive specification of these flexible configurations.
- Custom Dumpers:Application-engineered units accommodate non-standard tote dimensions or specialized discharge heights.
- Pneumatic Dumpers:Compressed-air lift mechanisms serve facilities with existing plant air infrastructure and lower duty cycle requirements.
Stationary dumpers lead volumes today; mobile dumpers are gaining share fastest.
End User:
Regulatory intensity and contamination tolerance separate end-use applications into distinct specification tiers.
- Food Processing:Dairy, meat, and ready-to-eat cereal operations specify USDA- and FDA-compliant surface finishes with 3-A Sanitary Standards certification. OSHA ergonomic mandates for repetitive lifting above fifty pounds accelerate replacement of manual stations with powered equipment across protein processing plants.
- Pharmaceuticals:Aseptic fill-finish and bioprocessing operations require electromechanical drives, sealed brushless motors, and integration with isolator or restricted access barrier systems. ASME BPE weld qualification and cleanability validation under CIP protocols determine vendor selection.
- Chemicals:Corrosion-resistant coatings and explosion-proof electrical enclosures address solvent handling and powder processing applications.
- Agriculture:Grain handling and feed processing operations prioritize throughput capacity and weather-resistant construction over sanitary surface specifications.
Food processing leads volumes today; pharmaceuticals is climbing the fastest.
Technology:
Power transmission selection reflects cleanroom classification, precision requirements, and maintenance access constraints.
- Electric:Servo-driven lift-and-rotate mechanisms with variable frequency drives deliver precise speed control and position feedback. Pharmaceutical bioprocessing and high-care food zones specify these systems to eliminate hydraulic fluid contamination risks.
- Hydraulic:Fluid power systems with cylinder-actuated lifting remain prevalent in legacy installations and heavy-duty agricultural applications. Extended lead times for servo motors are shifting some specification toward refurbished hydraulic units in cost-sensitive brownfield retrofits.
- Pneumatic:Compressed-air actuation serves light-duty applications with existing plant air infrastructure.
- Manual:Hand-crank or lever-operated dumpers persist in small-batch specialty food operations below OSHA ergonomic thresholds.
Hydraulic systems lead installed base today; electric drives are expanding most quickly.
Material:
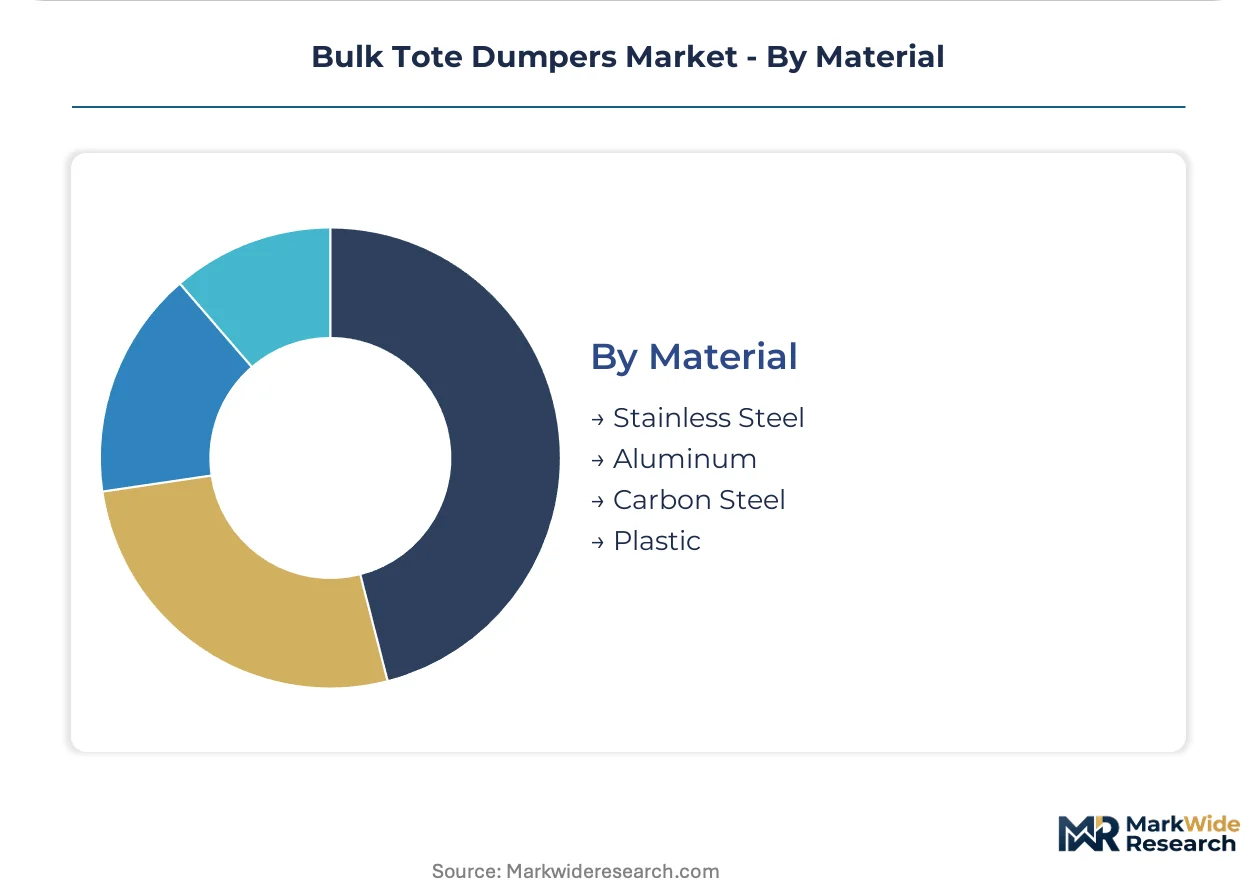
Surface finish requirements and chemical exposure dictate construction material selection across end-use applications.
- Stainless Steel:Grade 304 and 316L enclosures with precision TIG welds and Ra 0.8 micrometer surface finishes dominate dairy, pharmaceutical, and high-care food installations. Domestic fabrication in Wisconsin and Ohio shortens lead times for USDA-qualifying equipment.
- Aluminum:Lightweight extruded frames serve mobile dumper applications where maneuverability and corrosion resistance outweigh sanitary weld requirements.
- Carbon Steel:Painted or powder-coated mild steel constructions address agricultural and industrial chemical handling with lower regulatory exposure.
- Plastic:Polyethylene or fiberglass reinforced polymer housings serve corrosive chemical environments and temporary installations.
Stainless steel leads volumes today; aluminum is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment procurement patterns diverge sharply where regulatory compliance costs widen the gap between domestic fabrication and imported alternatives. Buyers in jurisdictions with stringent sanitary mandates favor local supply chains to reduce qualification documentation burden and accelerate USDA dairy contract approvals.
United States
Protein processing plants across the Midwest manufacturing corridor are retrofitting manual dumping stations with powered equipment to satisfy OSHA ergonomic mandates for repetitive lifting above fifty pounds. FDA's Food Safety Modernization Act traceability rules are forcing equipment builders to embed RFID readers and vision systems at dumping stations. The Chicago-Milwaukee-Minneapolis-St. Paul cluster concentrates demand for USDA- and FDA-compliant stainless steel systems with 3-A Sanitary Standards certification.
Germany
Precision fermentation facilities producing cultivated proteins are specifying sanitary bulk handling systems engineered for sterile media transfer. The country's national pharmaceutical regulator enforces strict cleanability validation under EU GMP Annex 1 for aseptic processing equipment. Bavaria's biotech corridor around Munich anchors demand for electromechanical dumpers with sealed brushless motors and isolator integration.
China
Domestic food brands are accelerating automated material handling adoption to reduce labor costs and contamination risks in powder processing operations. The national food safety regulator under SAMR is tightening surface finish and weld quality standards for equipment used in infant formula and dairy applications. The Yangtze River Delta manufacturing belt around Shanghai concentrates fabrication capacity for sanitary-grade 304 and 316L enclosures serving Asia-Pacific contract manufacturers.
India
Contract manufacturers serving multinational food brands are adopting mobile dumpers to enable rapid line changeovers between allergen-controlled and standard production runs. FSSAI sanitary equipment guidelines and state-level factory inspectorates are elevating compliance requirements for material handling equipment in processed food zones. Maharashtra's Pune-Nashik industrial corridor and Gujarat's Sanand-Vithalapur belt are emerging as demand centers for flexible batch processing configurations.
Japan
Pharmaceutical fill-finish operations are specifying electromechanical lift-and-rotate mechanisms with predictive maintenance algorithms to eliminate unplanned downtime in aseptic suites. The national pharmaceutical regulator PMDA enforces ASME BPE weld qualification and cleanability validation for bioprocessing equipment. The Kansai region around Osaka anchors demand for high-precision dumpers integrating with restricted access barrier systems in sterile manufacturing suites.
Bulk Tote Dumpers Market Competitive Environment
United States producers anchor the premium sanitary tier; European specialists hold position in precision fermentation and pharmaceutical applications. The vendor base splits between integrated bulk handling ecosystem providers and standalone dumper fabricators. Three archetypes dominate: full-line material handling integrators, sanitary welding specialists with USDA qualification, and regional service-focused builders. Capacity expansion and compliance documentation partnerships represent the dominant competitive moves as buyers prioritize total cost of ownership over upfront capital expenditure.
Among United States-based fabricators, National Bulk Equipment, Flexicon, and PPM Technologies exemplify distinct strategic positions. National Bulk Equipment occupies a position within the USDA- and FDA-compliant sanitary welding tier, leveraging domestic fabrication for dairy and protein processing lines. Flexicon anchors the integrated bulk handling ecosystem archetype, spanning conveying, discharging, and containment functions. PPM Technologies sits within the specialized food-grade configuration segment, engineered for fragile and coated products. These three companies represent how geographic proximity to the Midwest manufacturing corridor creates service and parts logistics advantages in a market where qualification timelines and compliance documentation burden determine vendor selection.
| Leading Market Players |
|---|
| Automated Conveyor Company |
| CDS-LIPE |
| National Bulk Equipment |
| TOTE Systems |
| Weening Brothers Mfg |
| California Food Machinery |
| PPM Technologies |
| CM Process Solutions |
| Flexicon |
| Others |
Value Chain & Pricing Dynamics
Electromechanical drive adoption in pharmaceutical and high-care food zones is compressing hydraulic system margins while concentrating premium-tier supply among certified fabricators in Wisconsin and Ohio. This technology transition simultaneously elevates qualification costs for new entrants and tightens procurement timelines for buyers seeking USDA dairy contract approvals.
Pricing Analysis
Distributor margins of fifteen to twenty-five percent separate factory-direct OEM pricing from end-user acquisition costs for sanitary-grade equipment. Three-tier pricing structure across premium certified, standard industrial, and economy refurbished levels stratifies by surface finish certification and CIP integration depth. Cost compression in the standard tier is intensifying because extended servo motor lead times push buyers toward refurbished hydraulic alternatives. Contract manufacturers running multi-product lines exhibit highest price sensitivity; pharmaceutical bioprocessors demonstrate lowest sensitivity due to contamination risk premiums.
Supply Chain Analysis
Single-source vulnerability sits with precision TIG welding capacity concentrated in Wisconsin, Ohio, and select Bavarian fabrication shops serving EU pharmaceutical demand. Stainless steel raw material supply draws from domestic mills in Pennsylvania and Indiana plus German specialty producers for pharmaceutical-grade 316L. Component procurement for sealed brushless motors and variable frequency drives rests on industrial automation suppliers in Germany and Japan. Tariff exposure on Chinese-sourced electrical enclosures elevates landed cost volatility. Distribution runs through regional equipment integrators who bundle installation, commissioning, and compliance documentation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential in bulk tote dumpers rests on electric drive standardization reducing field service intensity and premium-tier buyers accepting equipment-as-a-service contracting to transfer compliance burden.
For Market Incumbents: Extend certified welding capacity partnerships into the Minneapolis-St. Paul corridor to capture cellular agriculture facility construction. Defend against refurbished hydraulic arbitrage by embedding predictive maintenance algorithms that demonstrate total cost of ownership superiority. Prioritize backward integration into servo motor inventory buffers to neutralize procurement timeline disadvantages against legacy hydraulic competitors. For New Entrants and Emerging Players: The premium-to-economy price gap in mobile dumpers for contract manufacturing offers immediate white-space penetration. Target India's Maharashtra and Gujarat industrial corridors where FSSAI compliance elevation creates first-mover advantage for sanitary-certified entrants. Pursue pharmaceutical bioprocessing applications in Japan's Kansai region where ASME BPE qualification scarcity limits incumbent responsiveness. Lead with rapid commissioning capabilities and modular CIP integration to differentiate against established Midwest fabricators. For Investors and Strategic Acquirers: Valuations sit cheapest among regional service-focused builders lacking USDA qualification but possessing established maintenance relationships in food processing clusters. Five-to-ten year viability favors acquisition of sanitary welding specialists with 3-A SSI certification pathways and geographic proximity to Chicago-Milwaukee ingredient processing density. Monitor cellular agriculture capital deployment announcements as inflection signal for precision fermentation equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sanitary Welding Certification Investment | ASME BPE and 3-A SSI qualification compresses delivery timelines for dairy and pharmaceutical contracts. |
| Equipment-as-a-Service Contracting | Monthly payment structures reduce balance sheet pressure for mid-sized co-manufacturers running multi-year agreements. |
| Electric Drive Platform Standardization | Servo motor integration eliminates hydraulic contamination risks in FDA-regulated aseptic processing environments. |
| Cellular Agriculture Partnership Development | Precision fermentation facilities require sterile media transfer systems engineered for containment validation. |
| Regional Service Network Expansion | Proximity to Midwest manufacturing corridor creates parts logistics advantages for urgent maintenance response. |
Study Parameters
Multiple input streams — equipment procurement databases, regulatory filing analysis, and fabrication capacity surveys — were reconciled across primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and sanitary welding certification auditors. Secondary validation incorporated FDA 483 inspection observations, USDA dairy equipment approval records, OSHA ergonomic enforcement data, and SEC filings from publicly traded material handling equipment manufacturers. Bottom-up demand modeling triangulated against top-down industry association shipment statistics.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions by product mobility, power transmission technology, construction material, and end-use regulatory intensity. Modeled dimensions spanned stationary versus mobile configurations, electric versus hydraulic versus pneumatic drives, stainless steel versus aluminum versus carbon steel construction, and food processing versus pharmaceutical versus chemical versus agricultural applications. CAGRs were derived from historical shipment trajectories adjusted for regulatory mandate implementation timelines and capital expenditure cycle phasing in protein processing and dairy operations.
Caveats apply where FDA Food Safety Modernization Act enforcement intensity, OSHA ergonomic mandate expansion scope, or cellular agriculture capital deployment velocity could materially shift the outlook. Forecasts reflect assumptions about stainless steel supply localization progress and electric drive component availability normalization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Conductive Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Isothermal Bags and Containers Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Circular Industrial Bags Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Household and Cleaning Container Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Drum Liners Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
Bag-In-Box Container Market
Bags and Containers
Global Household Food Storage Containers Market