
 Circular Industrial Bags Market | 2026-2036
Circular Industrial Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Circular Industrial Bags Market Outlook
Asset-light leasing models for bulk packaging fleets is tilting competitive dynamics toward operators with balance-sheet capacity to finance circular bag pools. Greif leverages its North American container network to sustain high fleet utilization rates across industrial corridors. LC Packaging anchors European demand through specialized woven polypropylene designs for agricultural and chemical clients. Conitex Sonoco competes on vertical integration from resin extrusion to finished bag fabrication.
Circular industrial bags are engineered from woven polypropylene, polyethylene, or multiwall paper constructions rated for loads between 500 kg and 2,000 kg, designed for repeated filling, transport, and discharge cycles in closed-loop supply chains. Woven polypropylene dominates current volume due to tear resistance and washability, while paper-based alternatives occupy premium niches where biodegradability commands procurement preference. The storage application segment leads in revenue per unit as conditioned warehousing requirements drive specification upgrades. Manufacturing end users generate the deepest demand pool, though agriculture is expanding fastest as grain cooperatives adopt shared-bag pooling systems.
The EPA regulates industrial packaging under Resource Conservation and Recovery Act provisions that govern hazardous material containment and reuse documentation. REACH compliance in Europe mandates disclosure of chemical substances in bag coatings, directly affecting import access for non-EU producers. China's GB standards for plastic packaging set mandatory recycled content thresholds that reshape supplier qualification criteria. Stakeholders must monitor how extended producer responsibility frameworks in multiple jurisdictions alter total cost of ownership calculations for circular bag programs.
Market Dynamics
Closed-loop pooling systems are compressing ownership economics across cement and chemical supply chains, forcing packaging suppliers to finance fleet assets rather than sell disposable units. This capital reallocation is restructuring competitive barriers around balance-sheet depth and logistics network density.
Growth Catalysts
- REACH substance disclosure mandates:European chemical handlers must document coating compositions, accelerating replacement cycles for non-compliant bag inventories and creating upgrade demand.
- Woven polypropylene washability:Mechanical cleaning protocols now achieve 15+ reuse cycles in grain handling, cutting per-tonne packaging costs below single-use alternatives.
- China's circular economy zones:State-backed industrial parks in Jiangsu and Guangdong subsidize shared-bag infrastructure, concentrating pilot deployments among state-owned cement producers.
Market Restraints
- Propylene resin price volatility:Feedstock fluctuations from naphtha crackers in South Korea and Singapore squeeze converter margins during contract renegotiations.
- Single-use FIBC residual demand:Construction-grade cement distributors in price-sensitive markets resist deposit-return schemes, maintaining parallel procurement of disposable bulk bags.
- Multiwall paper moisture vulnerability:Humidity exposure during monsoon logistics limits paper-based alternatives to climate-controlled corridors, capping addressable volume.
Strategic Opportunities
- India's PLI scheme for technical textiles:Domestic woven fabric capacity expansion supports localized bag fabrication for agricultural cooperatives in Punjab and Haryana.
- RFID-integrated fleet tracking:Convergence of woven substrate durability with IoT sensor embedding enables real-time location and condition monitoring across multi-user pools.
- Battery mineral logistics:Lithium carbonate and nickel sulfate handlers are specifying antistatic woven constructions for hazardous powder containment in closed-loop extraction-to-refinery circuits.
Industry Challenges
- ISO 21898 certification timelines:Third-party testing for 5:1 and 6:1 safety factor ratings extends product qualification by 8-12 weeks, delaying fleet deployment.
- Legacy ERP integration:Pooling operators struggle to synchronize deposit-tracking modules with customer inventory management systems, creating reconciliation friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Circular Industrial Bags Market |
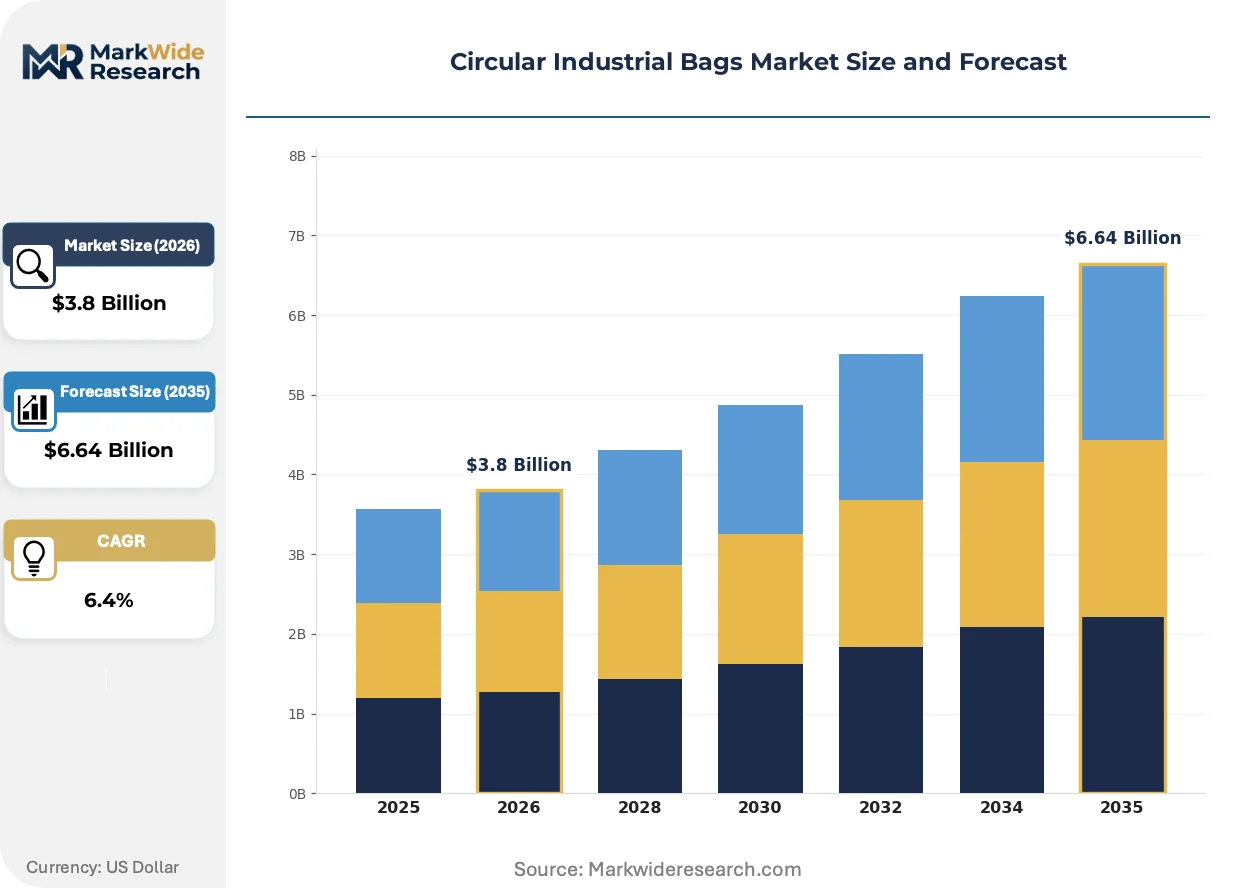
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Woven Bags, Non-Woven Bags, Plastic Bags, Paper Bags Application: Packaging, Storage, Transportation, Waste Management End User: Manufacturing, Construction, Agriculture, Retail Distribution Channel: Online Retail, Direct Sales, Wholesalers, Distributors |
| Companies Covered | Global-Pak, BAG Corp, Greif, Conitex Sonoco, Berry Plastics, AmeriGlobe, LC Packaging, RDA Bulk Packaging, Sackmaker, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Circular Industrial Bags Market Strategic Shifts
Material science advances and regulatory disclosure requirements are converging to redefine performance specifications and supply chain accountability across reusable bulk packaging systems.
Antistatic woven polypropylene constructions are migrating from niche chemical applications to mainstream battery mineral handling, where electrostatic discharge risks during lithium powder transport have triggered specification upgrades. Mining logistics coordinators in Western Australia and Chile's Atacama region are mandating surface resistivity ratings below 10^8 ohms. This migration is compressing the addressable market for standard non-conductive weaves in hazardous powder segments.
REACH Article 33 disclosure obligations now require downstream communication of Substances of Very High Concern in bag coatings and thread treatments, compelling Asian converters to reformulate UV stabilizers and antistatic additives. Chemical manufacturers with EU export exposure are auditing supplier compliance documentation quarterly. The agricultural segment faces the steepest reformulation costs due to broad biocide usage in grain-storage applications.
Shared-bag pooling contracts are displacing direct purchase arrangements among North American grain cooperatives, with usage-based pricing replacing capital expenditure on owned fleets. Elevator operators in Iowa and Illinois are consolidating procurement through third-party fleet managers. This behavioral shift concentrates buying power among logistics intermediaries and compresses manufacturer direct sales channels in the corn belt.
Circular Industrial Bags Market Segmentation
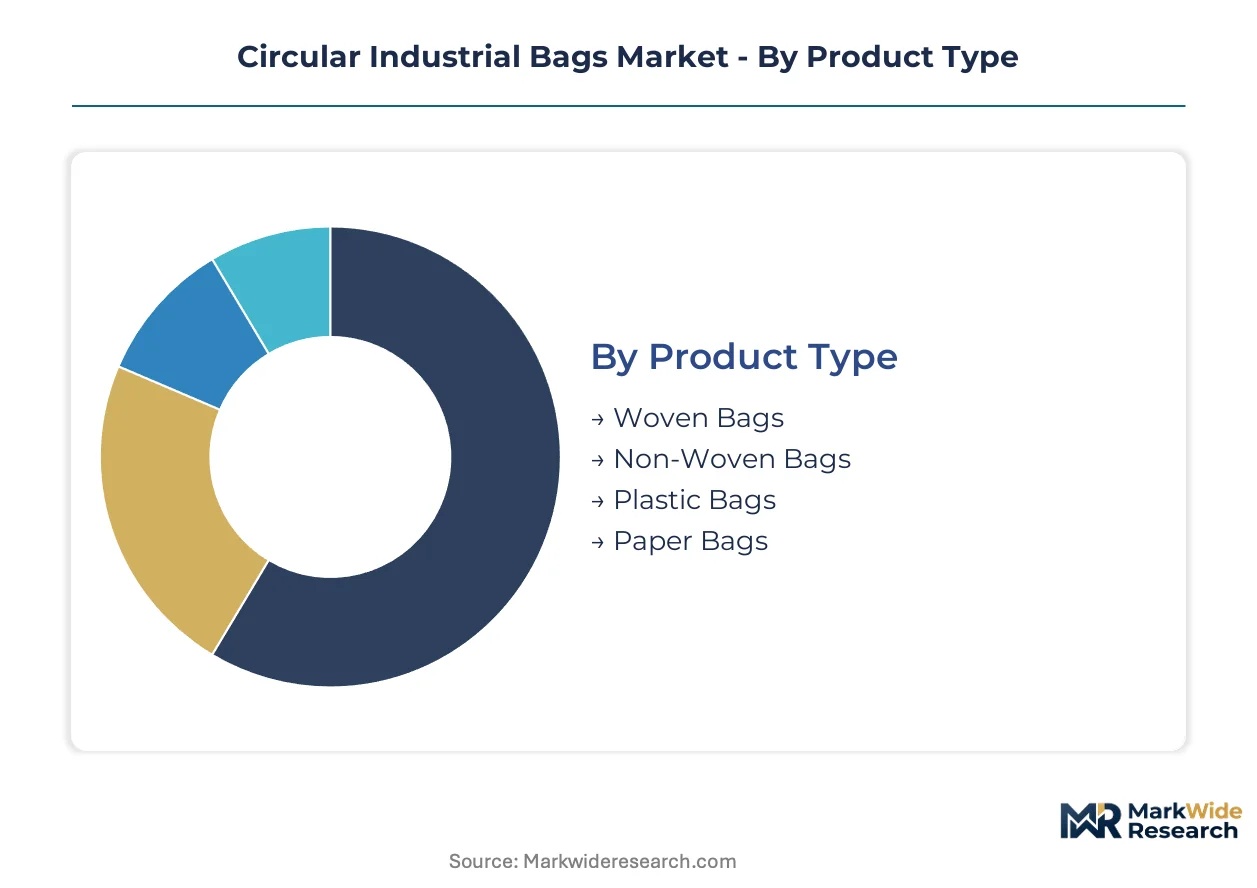
Circular industrial bags serve divergent operational requirements across material handling workflows. Segmentation reveals how substrate selection and channel configuration determine reuse economics and fleet financing structures.
Product Type:
Mature woven constructions dominate installed base volumes, while emerging alternatives target sustainability premiums and specialized containment needs.
- Woven Bags:Polypropylene tape yarns create tear-resistant shells rated for 500-2,000 kg loads with 15+ mechanical wash cycles. Cement manufacturers in China and grain handlers across the US Midwest specify these for closed-loop pooling systems where durability amortizes capital deployment.
- Non-Woven Bags:Spunbond polypropylene offers lighter-weight alternatives for single-cycle or limited-reuse applications. European chemical distributors are piloting these for REACH-compliant coatings that simplify substance disclosure documentation.
- Plastic Bags:Extruded polyethylene films serve moisture-critical bulk transport in lithium carbonate and nickel sulfate logistics.
- Paper Bags:Multiwall kraft constructions satisfy biodegradability mandates in premium agricultural and food-grade corridors.
Woven bags handle the majority of throughput; non-woven alternatives are climbing the fastest on share as coating reformulation costs reshape procurement.
Application:
Cost tier stratification separates capital-intensive storage infrastructure from transactional packaging services.
- Packaging:Primary containment functions at filling points require ISO 21898 certification for 5:1 and 6:1 safety factors. Chemical handlers in Germany and France prioritize antistatic specifications for hazardous powder containment.
- Storage:Conditioned warehousing demands drive specification upgrades including UV stabilization and humidity barriers. Revenue per unit peaks here due to extended asset deployment cycles and monitoring infrastructure.
- Transportation:Multi-modal logistics compatibility determines weave density and lifting loop configurations for rail and containerized freight.
- Waste Management:Industrial byproduct containment emphasizes chemical resistance and discharge valve designs for hazardous material protocols.
Storage commands premium pricing tiers; packaging applications are expanding most quickly as pooling contracts displace direct ownership.
End User:
Customer type concentration varies by capital intensity and procurement centralization patterns across industrial sectors.
- Manufacturing:Integrated production facilities with captive logistics networks achieve lowest per-unit costs through dedicated fleet deployment. Chemical and cement producers generate the deepest demand pool for high-cycle reusable systems.
- Agriculture:Grain cooperatives in Iowa, Illinois, and Punjab are consolidating procurement through third-party fleet managers with usage-based pricing models.
- Construction:Project-based cement distributors in price-sensitive markets maintain parallel disposable bag procurement, resisting deposit-return schemes.
- Retail:Bulk commodity handlers require standardized bag specifications for cross-dock efficiency in distribution center networks.
Manufacturing anchors volume commitments; agriculture is gaining share fastest as cooperative pooling systems mature.
Distribution Channel:
Supply concentration determines margin capture between manufacturers and logistics intermediaries.
- Direct Sales:Large fleet operators with balance-sheet capacity negotiate multi-year pooling contracts directly with bag fabricators. Greif and LC Packaging anchor this channel through captive logistics network density.
- Distributors:Regional wholesalers aggregate fragmented demand from mid-sized agricultural and construction users, capturing value through inventory pooling and technical specification guidance.
- Wholesalers:Volume resellers serve spot-market procurement for construction-grade cement distributors with irregular demand patterns.
- Online Retail:Digital platforms facilitate specification comparison for standardized bag configurations, though complex pooling contracts remain relationship-driven.
Direct sales capture the majority of contract value; distributor networks are expanding most quickly as cooperative procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances in woven polypropylene feedstocks are reshaping regional manufacturing footprints. Countries with captive resin capacity leverage cost advantages for bag fabrication, while import-dependent markets concentrate on pooling logistics and coating specialization.
China
Cement manufacturers in Jiangsu and Guangdong provinces deploy state-subsidized shared-bag infrastructure under circular economy zone mandates. GB standards for plastic packaging enforce recycled content thresholds that disqualify non-compliant imports. State-owned producers in the Yangtze River Delta pilot 20+ reuse cycle systems for domestic construction supply chains.
Germany
Chemical handlers along the Rhine corridor demand REACH-compliant coating documentation for antistatic woven constructions. ECHA substance disclosure mandates accelerate replacement of legacy bag inventories containing SVHC-treated components. Industrial packaging fabricators in North Rhine-Westphalia reformulate UV stabilizers to maintain EU market access.
United States
Grain cooperatives across Iowa and Illinois consolidate procurement through third-party fleet managers with usage-based pricing. EPA Resource Conservation and Recovery Act provisions govern hazardous material containment documentation for chemical sector reuse programs. Elevator operators in the Midwest corn belt displace direct ownership with pooled bag systems.
India
Agricultural cooperatives in Punjab and Haryana expand woven fabric capacity under the PLI scheme for technical textiles. BIS certification requirements for load-rated bulk packaging delay import qualification for non-domestic producers. Fabrication clusters in Gujarat supply localized bag production for regional grain handling networks.
Brazil
Mining logistics coordinators in Minas Gerais specify antistatic woven constructions for lithium carbonate transport to export terminals. ANVISA pharmaceutical packaging standards create parallel demand for certified clean-room bag specifications. Soybean cooperatives in Rio Grande do Sul pilot shared-pool models for port-bound bulk commodity flows.
Circular Industrial Bags Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in resin extrusion and coating formulation. The vendor base stratifies between balance-sheet-heavy fleet operators and regional fabricators serving spot-market demand. Three archetypes dominate: captive logistics network operators, specialized coating formulators, and vertically integrated resin-to-bag converters. Competitive dynamics center on multi-year pooling contract capture and ISO 21898 certification speed.
Among North American container network operators, Greif exemplifies the fleet-integrator archetype through captive logistics density. LC Packaging anchors European demand specialization through woven polypropylene design leadership for agricultural and chemical segments. Conitex Sonoco occupies a position representing vertical integration from resin extrusion through finished bag fabrication.
| Leading Market Players |
|---|
| Global-Pak |
| BAG Corp |
| Greif |
| Conitex Sonoco |
| Berry Plastics |
| AmeriGlobe |
| LC Packaging |
| RDA Bulk Packaging |
| Sackmaker |
| Others |
Value Chain & Pricing Dynamics
Jiangsu province's woven fabric clusters concentrate polypropylene tape yarn capacity, translating upstream resin cost volatility directly into converter margin compression across Asian supply contracts. This geographic concentration of extrusion and weaving assets grants local producers pricing leverage over import-dependent buyers in India and Southeast Asia, while European and North American purchasers absorb freight premiums for REACH-compliant and EPA-certified alternatives.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across cement and chemical supply chains. Three-tier pricing structure across premium antistatic specifications, standard ISO 21898-certified constructions, and economy-grade disposable alternatives separates procurement tiers by certification level and volume scale. Pricing pressure stems from propylene resin feedstock fluctuations at South Korean and Singapore naphtha crackers, squeezing converter margins during quarterly contract renegotiations. Construction-grade cement distributors exhibit highest price sensitivity, resisting deposit-return schemes, while battery mineral handlers accept premium tiers for hazardous powder containment.
Supply Chain Analysis
Extended payment terms from state-owned cement producers in China strain working capital for regional fabricators in Gujarat and Punjab. Raw material flows draw from Saudi Arabian and Qatari polypropylene resin sources, Chinese tape yarn extrusion, and Indian weaving and coating finishing. Single-source vulnerability concentrates at South Korean petrochemical complexes supplying Asia-Pacific converters. Distribution runs through direct multi-year pooling contracts for large fleet operators and regional distributor networks for fragmented agricultural demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as shared-bag pooling contracts displace direct ownership among grain cooperatives, creating niches for fleet managers and coating specialists between resin producers and end users.
For Market Incumbents: Build balance-sheet moats through captive logistics network density across industrial corridors. Greif and LC Packaging exemplify this archetype by financing circular bag pools that compress competitor access to multi-year contracts. Incumbents should accelerate ISO 21898 certification speed to outpace qualification delays threatening fleet deployment timelines. Capacity addition in Jiangsu and Guangdong circular economy zones captures state-subsidized demand from state-owned cement producers. For New Entrants and Emerging Players: Pursue white-space targeting of battery mineral logistics specifications for lithium carbonate and nickel sulfate handlers in Western Australia and Chile's Atacama region. Antistatic woven constructions with surface resistivity below 10^8 ohms represent the most penetrable segment, as mining logistics coordinators mandate upgrades from standard non-conductive weaves. Go-to-market angle: hazardous powder containment specialization with closed-loop extraction-to-refinery circuit integration. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-integrator archetypes with captive pooling contracts and usage-based pricing models. Long-term viability over the five-to-ten year window favors operators with logistics network density over pure-play fabricators exposed to resin cost volatility. Acquisition target archetype: regional coating formulators with REACH-compliant reformulation capabilities. Signal to watch: RFID-embedded fleet tracking adoption rates as IoT integration becomes table stakes for multi-user pool operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Extrusion | Captive polypropylene supply from naphtha crackers insulates Conitex Sonoco from Korean feedstock volatility. |
| RFID Fleet Tracking Integration | Real-time location monitoring across multi-user pools differentiates Greif's logistics network density. |
| REACH-Compliant Coating Reformulation | SVHC-free UV stabilizers preserve LC Packaging's EU market access under ECHA disclosure mandates. |
| Shared-Bag Pooling Infrastructure | Usage-based pricing models consolidate grain cooperative procurement through third-party fleet managers. |
| Antistatic Specification Migration | Surface resistivity-rated constructions capture battery mineral logistics demand from lithium extractors. |
Study Parameters
A standing panel of plant managers at cement and chemical facilities, procurement leads at agricultural cooperatives, distribution channel partners in woven polypropylene, technical R&D directors for coating formulations, and fleet logistics coordinators provided ongoing calibration across the research cycle. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, GB standards documentation, SEC 10-K filings of listed packaging companies, and ECHA substance registration databases. Bottom-up unit economics from bag fabrication costs and top-down demand aggregation from end-use sector procurement patterns were triangulated for convergence.
Scenario-bracketing framed low, base, and high cases across the projection horizon without fixed year anchors. Segmentation dimensions modeled include substrate type, application function, end-use industry, distribution channel configuration, and regional regulatory cluster. CAGRs were derived from fitted growth curves applied to disclosed capacity expansion timelines and state subsidy program budgets. Industry-specific forecast inputs incorporated propylene resin price elasticity coefficients and ISO 21898 certification queue lengths.
The forecast holds incumbent behavior within observed patterns; aggressive moves by state-backed Chinese cement producers to internalize bag fabrication would shift outcomes. Forecasts reflect documented assumptions about circular economy zone subsidy continuity and REACH enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Compression Bags Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Padding Bags Market
Bags and Containers
Bag-In-Tube Market
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
MSW Bag Opener Market
Bags and Containers
FIBC Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Self-Sealing Bags Market
Bags and Containers
Jumbo Bags Market