
 Mesh Tarpaulin Sheets Market | 2026-2036
Mesh Tarpaulin Sheets Market Size, Share, and Industry Trends Forecast 2026-2036
Mesh Tarpaulin Sheets Market Foresight
Aftermarket service revenue for installation support and custom fabrication is narrowing as a margin pool, shifting value toward material suppliers with technical specification control. Zhejiang Tianyuan Fabric Co., Ltd. leverages integrated warp-knitting and PVC coating lines to capture this migration. Shur-Co LLC anchors North American transportation demand through proprietary tensioning systems. Cunningham Covers specializes in bespoke dimensions for UK agricultural and marine clients, sustaining premium positioning.
Mesh tarpaulin sheets are woven textile substrates manufactured from HDPE, PVC, or canvas fibers with calibrated open-area ratios, typically ranging from thirty to seventy percent porosity to balance wind load reduction with UV and moisture protection; their primary purpose spans temporary weather shielding, debris containment, and controlled-environment agriculture across commercial and industrial settings. The heavy-duty thickness tier commands disproportionate margin contribution due to multi-layer lamination requirements and extended warranty terms, while lightweight HDPE variants in agricultural shading represent the fastest-growing volume segment driven by protected-culture expansion. PVC-coated mesh in transportation logistics retains structural dominance in value terms, anchored by flame-retardant certifications and European regulatory compliance.
The EPA enforces VOC emission thresholds during PVC coating operations, compelling manufacturers to invest in solvent recovery or water-based alternatives; China's MEE implements parallel GB standard updates for construction-site textiles that restrict additive formulations and mandate recyclability disclosures. ISO 9001 quality certification and REACH substance restrictions collectively shape supplier qualification criteria across European distribution channels. Stakeholders must monitor evolving polymer feedstock volatility and regional enforcement divergence to calibrate capacity allocation and formulation R&D priorities.
Market Dynamics
REACH compliance in Europe and China's GB standard revisions are tightening material specifications across the value chain, forcing reformulation investments and consolidating procurement toward suppliers with certified coating capabilities.
Growth Catalysts
- Protected-culture agriculture:India's National Horticulture Mission subsidizes shade-net adoption for vegetable cultivation, driving volume procurement of lightweight HDPE mesh variants.
- REACH substance restrictions:European distributors now require full chemical disclosure, accelerating supplier consolidation toward integrated manufacturers with in-house testing laboratories.
- Windbreak deployment:Brazil's grain belt operators are installing perimeter mesh systems to reduce post-harvest losses, creating sustained replacement demand for heavy-duty PVC-coated grades.
Market Restraints
- Crude-derived feedstock volatility:PVC resin and plasticizer costs fluctuate with naphtha cracking margins, compressing formulation economics for mid-tier producers without captive ethylene supply.
- Shandong cluster concentration:Over sixty percent of China's weaving and coating capacity sits within two hundred kilometers of Qingdao, exposing supply continuity to regional power rationing or environmental enforcement surges.
- Woven monofilm substitution:Laminated non-woven alternatives achieve comparable tear strength at lower unit weights, threatening specification-grade mesh in temporary shelter applications.
Strategic Opportunities
- Indonesian archipelago logistics:Island-to-island cargo protection creates demand for salt-spray-resistant coated mesh with integrated RFID tracking pockets.
- EU Green Deal procurement mandates:Public infrastructure tenders now specify minimum recycled content thresholds, rewarding suppliers with post-industrial PVC recovery streams.
- Digital print integration:UV-curable inkjet systems enable on-demand branding and safety marking, converting commodity tarpaulins into advertising surfaces for fleet operators.
Industry Challenges
- Coating technician scarcity:Solvent-based PVC line operators require hazardous materials certification that training institutes in Shandong and Zhejiang cannot supply at replacement rates.
- Multi-standard certification timelines:Simultaneous pursuit of REACH, GB, and BIS registrations stretches technical documentation teams across eighteen-month approval windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesh Tarpaulin Sheets Market |
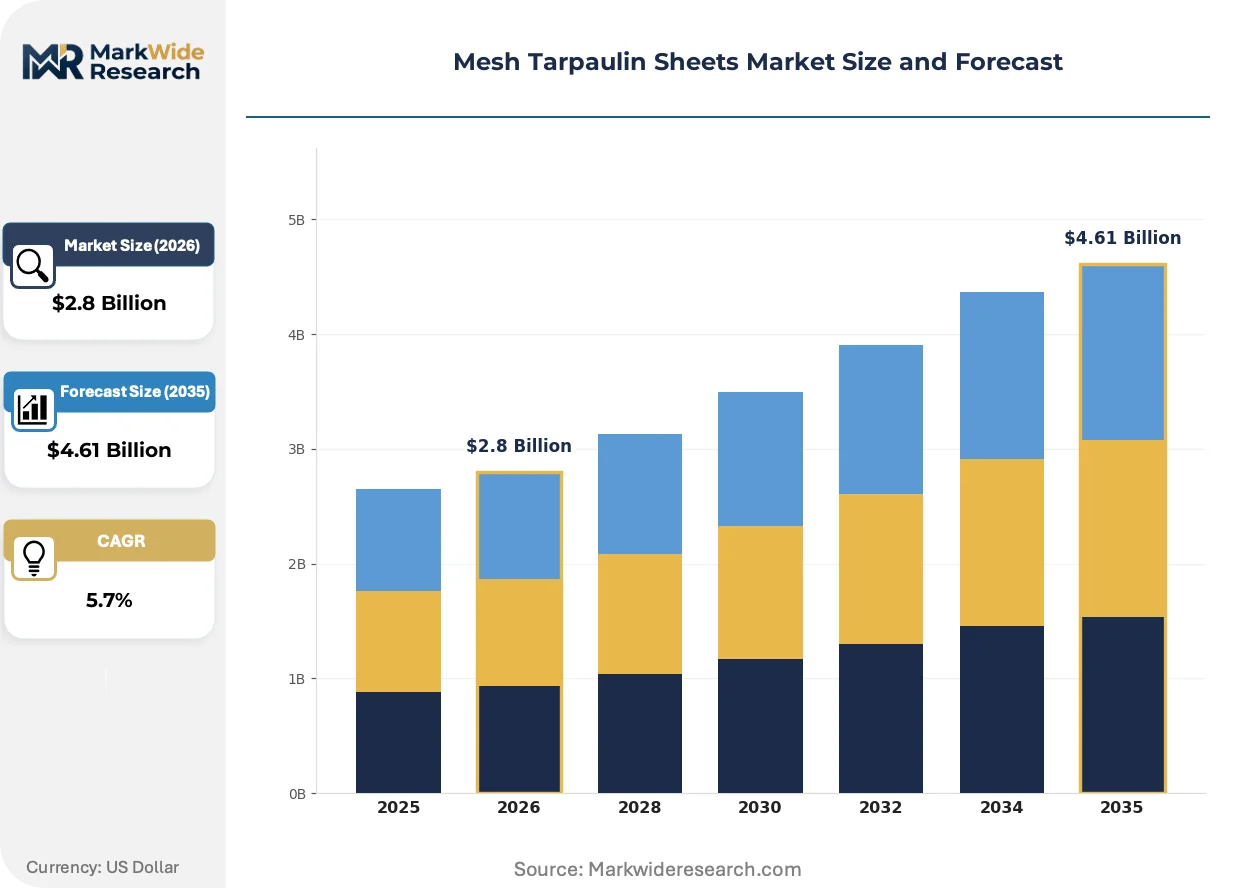
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, PVC, Canvas, Others Application: Agriculture, Construction, Transportation, Sports End User: Manufacturers, Retailers, Distributors, Individual Consumers Thickness: Lightweight, Medium, Heavy-duty, Ultra Heavy-duty |
| Companies Covered | Shurco UK Ltd., J Clemishaw 1870 Ltd., Mysore Nandi Tarpaulins Mfg Co, Zhejiang Tianyuan Fabric Co., Ltd., Shree Tarpaulin, Canadian Tarpaulin Manufacturers LTD., Cunningham Covers, HeytexBrandenburger GmbH, Shur-Co LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesh Tarpaulin Sheets Market Shifts & Advancements
Water-based coating chemistry and digital fabrication workflows are compressing lead times and enabling mass customization without inventory proliferation.
Photocatalytic titanium dioxide surface treatments are rendering obsolete conventional UV-stabilizer packages that degrade within thirty-six months of tropical exposure. Agricultural shade-house operators in Southeast Asia are specifying these self-cleaning grades for five-year warranty coverage. The technology is compressing replacement cycles and shifting margin toward coating specialists with nanomaterial dispersion expertise.
China's MEE has mandated recyclability disclosures for construction-site textiles under revised GB standards effective 2024. Manufacturers must now document additive formulations and end-of-life processing pathways. European importers are responding by dual-sourcing from Shandong producers with verified mechanical recycling partnerships.
Buyers in the UK agricultural sector are unbundling installation services from material supply, contracting directly with regional rigging crews. Cunningham Covers and similar bespoke fabricators now ship flat-packed dimensioned panels rather than installed systems. The shift is most visible in marine and equestrian applications where site-specific tensioning requirements vary by structure age and wind exposure.
Mesh Tarpaulin Sheets Market Segmentation
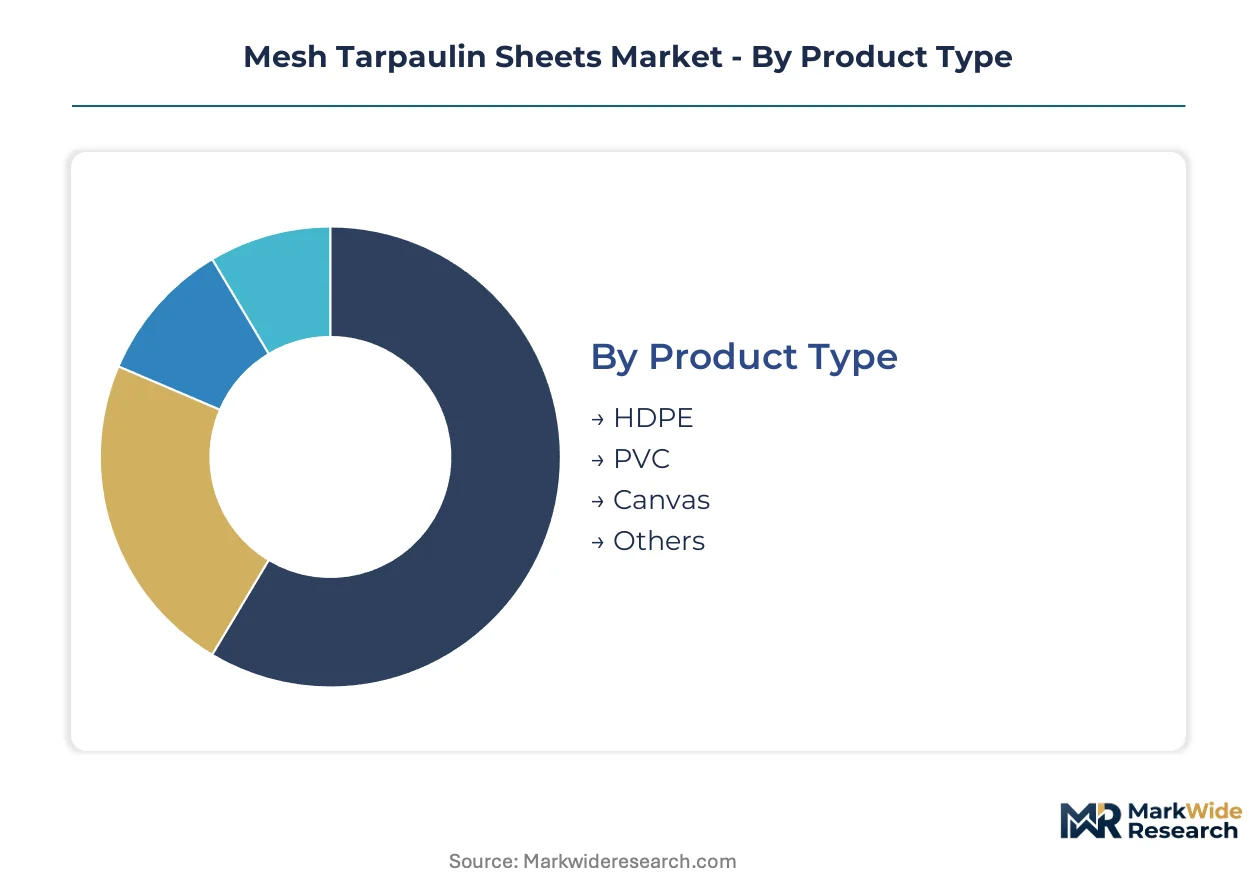
Segmentation in mesh tarpaulin sheets reveals divergent replacement cycles and margin structures across material grades and use cases. Procurement patterns vary sharply between agricultural shade operators seeking three-season durability and logistics fleets demanding decade-long service intervals.
Product Type:
Replacement velocity separates these material categories, with agricultural HDPE mesh turning over every two to three growing seasons while PVC-coated grades in transportation stretch toward eight-year lifecycles.
- HDPE:High-density polyethylene monofilament woven mesh dominates agricultural shading with thirty to fifty percent open-area porosity calibrated for light diffusion. India's National Horticulture Mission procurement concentrates demand in Gujarat and Maharashtra states, where subsidized shade-net adoption for vegetable cultivation drives volume procurement of lightweight variants with UV-stabilizer packages rated for thirty-six months of tropical exposure.
- PVC:Polyvinyl chloride coated polyester mesh retains structural dominance in value terms through multi-layer lamination and flame-retardant certifications meeting European REACH compliance requirements. Transportation logistics operators in Germany and France specify these grades for curtain-sided trailer systems, where tensioning hardware compatibility and tear-strength specifications anchor supplier qualification criteria.
- Canvas:Cotton or synthetic canvas substrates serve heritage marine and military applications requiring breathability without synthetic coating off-gassing.
- Others:Emerging bio-based and recycled polymer blends target EU Green Deal procurement mandates specifying minimum post-industrial content thresholds.
HDPE anchors the volume base while PVC gains share at the steepest rate through specification-grade transportation and construction applications.
Application:
Cost tier stratification separates these use cases, with construction and transportation commanding premium pricing for certified grades while agricultural procurement operates on thin margins driven by subsidy programs.
- Agriculture:Shade-house and windbreak deployment represents the fastest-growing volume segment as protected-culture expansion accelerates across India, Brazil, and Southeast Asia. Brazil's grain belt operators install perimeter mesh systems to reduce post-harvest losses, creating sustained replacement demand for heavy-duty PVC-coated grades with five-year warranty coverage.
- Construction:Debris containment and scaffolding enclosure applications require GB-standard compliance in China and OSHA-equivalent certifications in the United States. Shandong province integrated weaving and coating clusters supply both domestic builders and export channels with construction-grade textiles meeting revised recyclability disclosure mandates.
- Transportation:Curtain-sided trailer and flatbed cargo protection retains the highest margin contribution per square meter through proprietary tensioning system integration and fleet branding requirements.
- Sports:Tennis court windscreen and golf driving range applications demand colorfastness specifications and custom dimension fabrication capabilities.
Construction anchors the value base while agriculture expands most quickly through subsidy-driven volume procurement.
End User:
Customer type determines specification control and margin capture, with integrated manufacturers and national distributors wielding formulation influence that individual consumers cannot access.
- Manufacturers:Tarpaulin fabricators and finished goods producers purchase master rolls for cutting and seaming into dimensioned panels, requiring consistent coating adhesion and weldability across production batches.
- Retailers:Agricultural supply and hardware store chains stock standardized sizes for immediate availability, compressing lead times but limiting customization scope.
- Distributors:Regional logistics and construction material wholesalers aggregate demand across multiple end-use segments, qualifying suppliers through ISO 9001 certification and multi-standard registration capabilities.
- Individual Consumers:Marine, equestrian, and residential buyers purchase small quantities through direct-to-channel platforms, driving demand for flat-packed dimensioned panels with installation guidance documentation.
Distributors anchor the procurement volume base while manufacturers gain specification influence at the steepest rate through backward integration into coating operations.
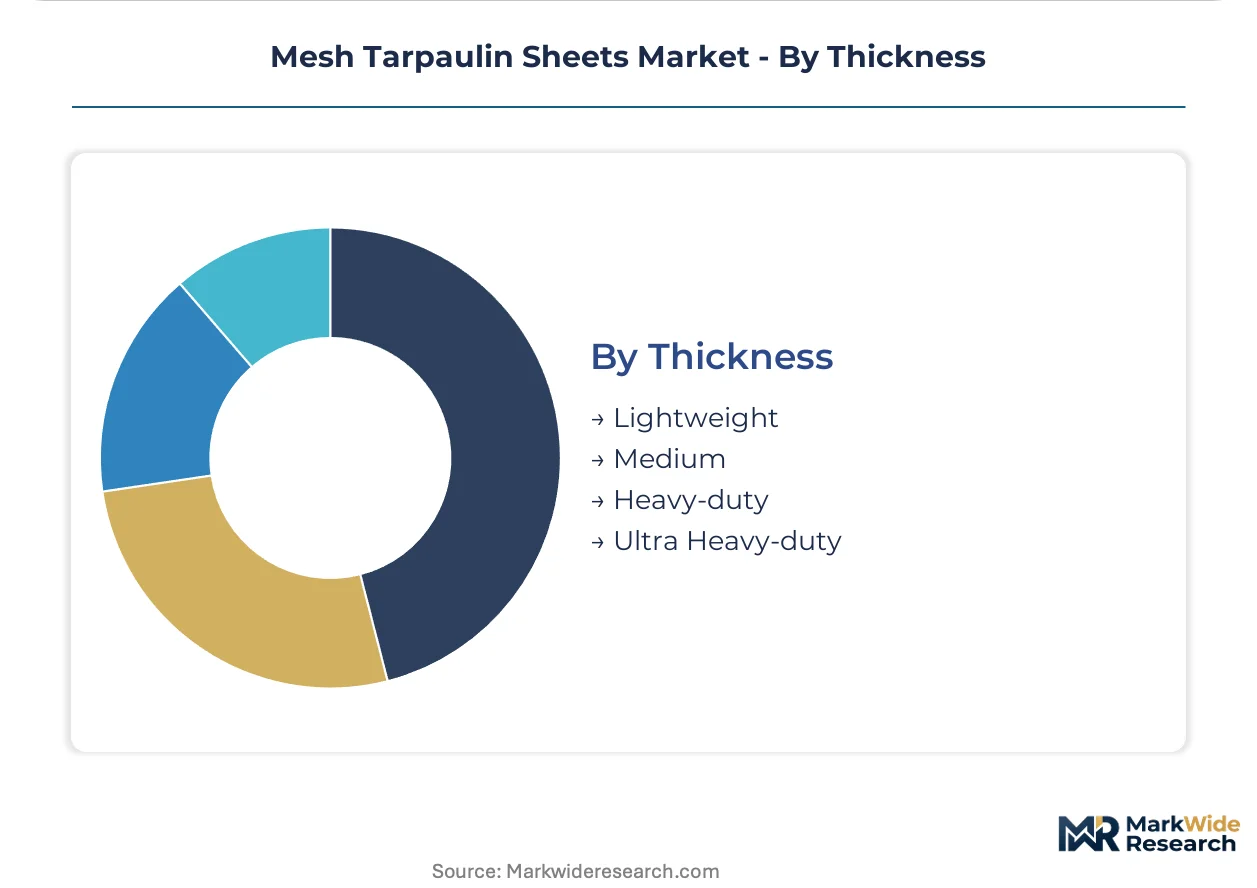
Thickness:
Margin concentration intensifies with gauge, as multi-layer lamination requirements and extended warranty terms in heavy-duty tiers separate qualified suppliers from commodity competitors.
- Lightweight:Sub-200 gsm HDPE variants serve temporary shelter and seasonal agricultural shading with two-to-three-season replacement cycles.
- Medium:200-400 gsm grades balance portability with durability for recreational and light commercial applications.
- Heavy-duty:400-600 gsm PVC-coated mesh commands disproportionate margin contribution through flame-retardant certifications, European regulatory compliance, and integrated RFID tracking pocket compatibility for Indonesian archipelago logistics operators.
- Ultra Heavy-duty:Exceeding 600 gsm, these grades incorporate reinforced selvedges and titanium dioxide photocatalytic surface treatments for five-year warranty coverage in Southeast Asian tropical exposure conditions.
Heavy-duty thickness anchors the margin base while ultra heavy-duty climbs the fastest through specification-grade infrastructure and marine applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: European logistics operators prioritize REACH-certified flame-retardant grades for fleet longevity, while Indian and Brazilian agricultural buyers chase subsidy-optimized lightweight HDPE for seasonal turnover.
China
Construction-grade textile demand concentrates in Shandong province, where integrated weaving and coating clusters supply domestic builders and export channels. The MEE's GB standard revisions mandate recyclability disclosures and restrict additive formulations, forcing reformulation investments among Qingdao-area manufacturers. Zhejiang province hosts parallel warp-knitting operations serving transportation logistics with PVC-coated specifications.
India
The National Horticulture Mission subsidizes shade-net adoption across Gujarat and Maharashtra states, driving volume procurement of lightweight HDPE mesh variants. BIS certification requirements tighten material specifications for construction-site deployment. Domestic fabricators in Tamil Nadu and Karnataka are expanding coating capacity to capture backward integration value from master-roll imports.
Germany
Curtain-sided trailer fleets specify REACH-compliant PVC-coated mesh with flame-retardant certifications, anchoring European value demand. The EU Green Deal procurement mandates minimum recycled content thresholds for public infrastructure tenders. Ruhr Valley logistics operators are qualifying suppliers with post-industrial PVC recovery streams and ISO 9001 documentation.
Brazil
Grain belt operators install perimeter windbreak mesh systems to reduce post-harvest losses, creating sustained replacement demand for heavy-duty PVC-coated grades. ANVISA-aligned import regulations govern construction-site textile specifications. São Paulo state distributors aggregate agricultural demand across Mato Grosso and Rio Grande do Sul production zones.
United States
Transportation logistics operators anchor North American demand through proprietary tensioning system integration and fleet branding requirements. EPA VOC emission thresholds during PVC coating operations compel solvent recovery investments. Midwest agricultural cooperatives in Iowa and Illinois are expanding protected-culture vegetable operations with seasonal HDPE shade-house deployment.
Mesh Tarpaulin Sheets Market Competitive Landscape
Capability concentration sits with integrated coating specialists; scale advantage sits with regional distribution networks. The vendor base separates into three tiers: master-roll producers with captive resin supply, regional fabricators with custom dimension capabilities, and logistics-focused assemblers with tensioning hardware integration. Consolidation pressure is accelerating through REACH compliance costs and multi-standard certification timelines. Dominant competitive moves include backward integration into coating operations and geographic expansion through distribution partnerships.
Among UK-based specialists, Cunningham Covers and J Clemishaw 1870 Ltd. occupy positions within the bespoke fabrication tier, serving marine and agricultural clients with flat-packed dimensioned panels. Zhejiang Tianyuan Fabric Co., Ltd. exemplifies the integrated manufacturer archetype with warp-knitting and coating capabilities concentrated in China's eastern manufacturing corridor. These three entities represent distinct competitive vectors: custom engineering responsiveness, heritage market presence, and vertical production control.
| Leading Market Players |
|---|
| Shurco UK Ltd. |
| J Clemishaw 1870 Ltd. |
| Mysore Nandi Tarpaulins Mfg Co |
| Zhejiang Tianyuan Fabric Co., Ltd. |
| Shree Tarpaulin |
| Canadian Tarpaulin Manufacturers LTD. |
| Cunningham Covers |
| HeytexBrandenburger GmbH |
| Shur-Co LLC |
| Others |
Supply & Pricing Matrix
Shandong cluster concentration risk determines both tiered pricing spreads and supply chain configuration across the mesh tarpaulin value chain. Regional power rationing or environmental enforcement surges at Qingdao-area weaving and coating facilities compress margins for mid-tier producers while amplifying premium capture by integrated manufacturers with captive resin supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between Shandong master-roll producers and European logistics fleets, while spot purchasing governs Indian agricultural subsidy programs. Price differentiation rests on REACH certification tier and flame-retardant additive packages, with certified grades commanding substantial premiums over commodity HDPE variants. Cost compression in lightweight agricultural tiers is intensifying because naphtha-derived feedstock volatility squeezes formulation economics for non-integrated producers. Smallholder cooperatives in Gujarat and Maharashtra exhibit highest price sensitivity, whereas German curtain-sided trailer operators prioritize specification compliance over unit cost.
Supply Chain Analysis
Extended payment terms from European distributors strain working capital for Qingdao-area coating specialists without supply-chain finance facilities. Manufacturing gravity centers on China, India, and Germany, with raw material dependencies spanning PVC resin from naphtha cracking, HDPE monofilament from ethylene feedstock, and titanium dioxide nanoparticles for photocatalytic surface treatments. Single-source vulnerability concentrates in Shandong province, where over sixty percent of weaving capacity sits within two hundred kilometers of Qingdao. Distribution runs through regional logistics wholesalers in São Paulo, Düsseldorf, and Mumbai who aggregate demand across construction, transportation, and agricultural end uses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation chemistry expertise and multi-standard certification capabilities constitute scarce assets that consolidate procurement toward qualified suppliers. The market rewards backward integration into coating operations while penalizing fabricators dependent on imported master rolls.
For Market Incumbents: Insulate margin position by deepening captive ethylene supply arrangements and accelerating water-based coating chemistry R&D ahead of EPA VOC threshold tightening. Zhejiang and Shandong producers should expand in-house testing laboratories to compress REACH, GB, and BIS registration timelines. Laminated non-woven substitution threats in temporary shelter applications demand specification-grade differentiation through proprietary tensioning system compatibility. For New Entrants and Emerging Players: Indonesian archipelago logistics presents underpenetrated white space for salt-spray-resistant coated mesh with integrated RFID tracking pockets. Brazilian grain belt windbreak deployment offers second entry vector through ANVISA-aligned heavy-duty PVC grades with five-year warranty coverage. New entrants should pursue direct contracting with island-to-island cargo operators rather than competing through São Paulo distributor channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated coating specialists with verified mechanical recycling partnerships. Long-term viability across the next decade hinges on post-industrial PVC recovery stream access and nanomaterial dispersion expertise. Acquisition targets should demonstrate GB standard compliance progress and established European distributor relationships. The signal to watch is MEE enforcement surge frequency in Shandong province, which would accelerate supplier shakeout and concentrate share among compliant integrated manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Operations | Captures formulation margin and compresses REACH certification timelines for Shandong producers. |
| Water-Based Coating Chemistry Transition | Aligns with EPA VOC thresholds and MEE GB standard revisions for construction-grade textiles. |
| Post-Industrial PVC Recovery Partnership | Qualifies suppliers for EU Green Deal procurement mandates specifying minimum recycled content. |
| Digital Print Integration Investment | Enables UV-curable inkjet branding that converts commodity tarpaulins into fleet advertising surfaces. |
| Geographic Expansion Through Distribution Partnerships | Secures channel access in Indonesian archipelago logistics and Brazilian grain belt windbreak markets. |
Research Methodology
Initial hypotheses were tested against primary input from coating line operators, procurement leads at European logistics fleets, agricultural cooperative managers in Gujarat, and technical R&D directors at Shandong weaving clusters, then refined through secondary validation against customs trade data, SEC filings of listed textile manufacturers, MEE GB standard revision documents, and EU ECHA REACH substance restriction updates. Bottom-up demand modeling across end-use segments triangulated with top-down supply capacity assessments at Qingdao and Zhejiang production hubs.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning material grade tier, application use case, end-user channel type, and regional regulatory cluster. CAGRs were derived from replacement cycle analysis and protected-culture agriculture expansion trajectories. Industry-specific forecast inputs included National Horticulture Mission subsidy disbursement patterns and curtain-sided trailer fleet refresh schedules in Germany and France.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by state-sponsored Chinese producers or sudden REACH substance restriction additions would shift outcomes. Macroeconomic deviation in naphtha cracking margins, regulatory enforcement divergence between MEE and EPA jurisdictions, or breakthroughs in laminated non-woven tear strength would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Textile Machinery and Equipment
Disposable Garment Bags Market
Textile Machinery and Equipment
Spools Market
Textile Machinery and Equipment
Electric Fabric Shaver Market
Textile Machinery and Equipment
3D Knitting Machines Market
Textile Machinery and Equipment
Cloth Measuring Machine Market
Textile Machinery and Equipment
Global Digital Printing and Dyeing Machine Market
Textile Machinery and Equipment
Tarpaulin Sheets Market
Textile Machinery and Equipment
US Textile Processing Machinery Market
Textile Machinery and Equipment
Sewing Machine Market
Textile Machinery and Equipment
Automatic Roll Filters Market
Textile Machinery and Equipment
Textile Mill Electric Drives Market
Textile Machinery and Equipment
Global Rotary Clothes Dryer Market
Textile Machinery and Equipment
Middle East and Africa Textile Films Market
Textile Machinery and Equipment
Europe Fabric Shavers Market
Textile Machinery and Equipment
Sewing Machine Component Market
Textile Machinery and Equipment
Drop Cloth Market