
 Glucosylglycerol Market | 2026-2036
Glucosylglycerol Market Size, Share, and Industry Trends Forecast 2026-2036
Glucosylglycerol Market Insights
Cosmetic formulators is reorganizing ingredient sourcing priorities toward biotech-derived humectants with verified moisturization efficacy. Evonik Industries leverages its specialty actives portfolio to anchor supply relationships with European personal care brands. BASF SE competes through integrated biotechnology fermentation capacity that sustains cost advantages at scale. Croda International Plc differentiates via lipid-compatible glucosylglycerol grades tailored for anhydrous formulations.
Glucosylglycerol is a compatible solute formed enzymatically from glucose and glycerol, typically produced through bacterial fermentation using halophilic microorganisms such as Halomonas elongata or recombinant Escherichia coli strains engineered for trehalose synthase pathways, yielding a clear hygroscopic liquid with water-retention capacity superior to glycerol at equivalent concentrations. The ingredient serves primarily as a humectant, osmoprotectant, and skin-conditioning agent in topical formulations and cell-culture media. Liquid glucosylglycerol occupies the dominant volume position due to ease of formulation integration, while powder formats are gaining fastest in solid-dose pharmaceutical applications where excipient stability matters. Cosmetics represents the deepest margin pool among application segments, though food-grade certification requirements constrain supplier participation.
EMA guidelines on biotechnological active substances and REACH registration obligations for enzymatic process intermediates shape purity documentation burdens for European suppliers. FDA cosmetic ingredient safety assessments and EPA fermentation facility discharge permits add compliance layers for US market access. Stakeholders must monitor evolving ISO 16128 natural origin criteria and pending EU microplastic restrictions that could reclassify certain polymer-containing humectant alternatives.
Market Dynamics
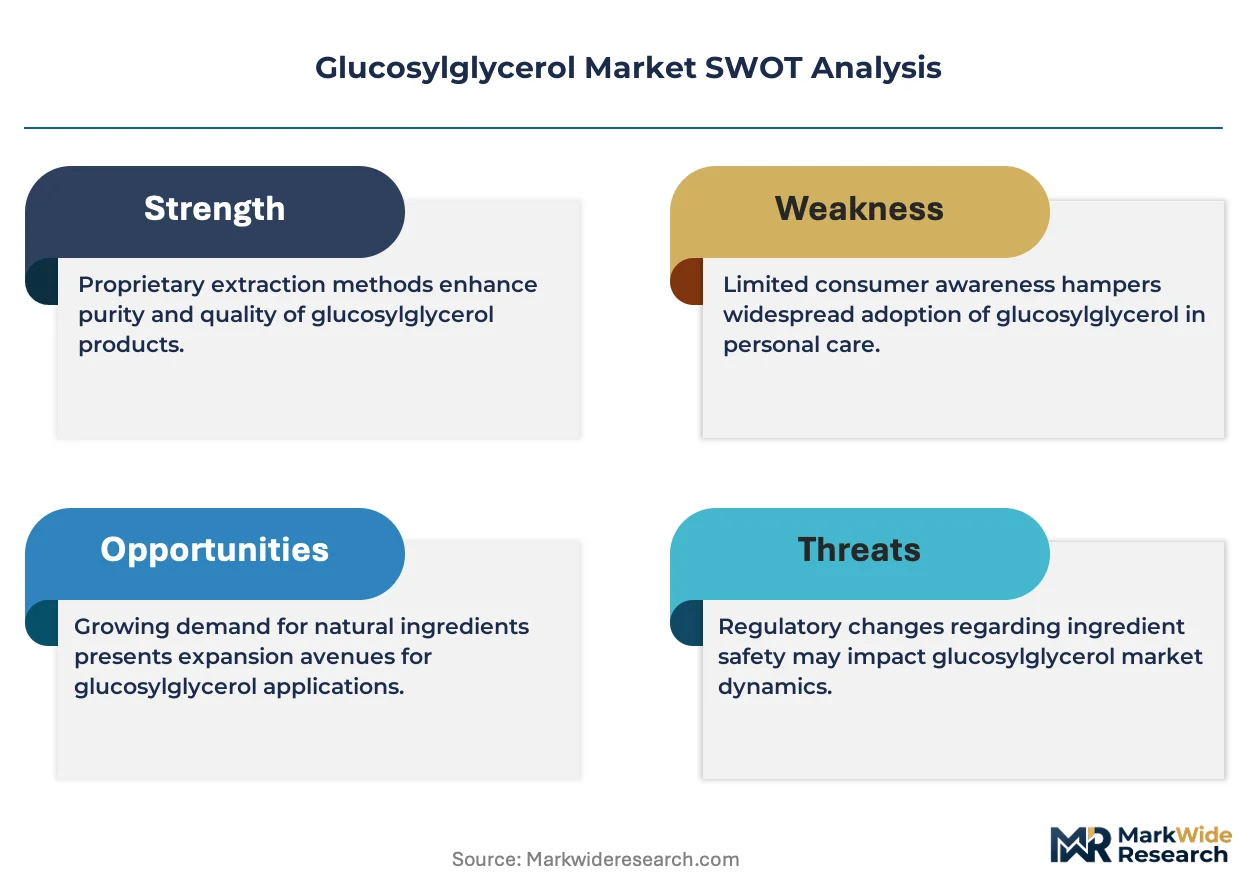
Cosmetic formulators are abandoning conventional petrochemical humectants as REACH registration deadlines and ISO 16128 natural-origin benchmarks force ingredient documentation upgrades across European supply chains.
Growth Catalysts
- REACH Phase-In Substances:The European Chemicals Agency's 2023-2028 registration timeline for enzymatic process intermediates is disqualifying non-compliant glycerol derivatives, redirecting procurement toward biotech-verified alternatives.
- Halophilic Fermentation:Advances in extremophile cultivation using Halomonas elongata strains are collapsing production costs for high-purity glucosylglycerol while improving water-activity coefficients.
- Clean-Label Skincare:North American premium brands are reformulating around EWG-verified ingredient lists, creating specification pull for fermentation-derived humectants with traceable supply chains.
Market Restraints
- Feedstock Volatility:Glucose syrup prices track corn futures, exposing contract manufacturers to margin compression when agricultural commodity markets spike.
- German Supply Concentration:Over half of cosmetic-grade fermentation capacity clusters near Frankfurt and Düsseldorf, creating geographic vulnerability to regional energy disruptions or logistics constraints.
- Technical Purity Ceilings:Current downstream filtration protocols struggle to consistently achieve sub-100 ppm protein residue levels required by pharmaceutical-grade specifications.
Strategic Opportunities
- India Personal Care:BIS certification pathways for biotech ingredients remain underdeveloped, offering first-mover advantage to suppliers establishing local analytical documentation capabilities.
- Cell-Culture Media:Osmoprotectant applications in biopharmaceutical manufacturing represent an adjacent segment with pricing premiums 3-4x above cosmetic grades.
- EU Green Deal Biomanufacturing:Horizon Europe funding streams for sustainable process chemistry are subsidizing capital expenditure for fermentation facility retrofits.
Industry Challenges
- Fermentation Scale-Up Expertise:Industrial microbiologists capable of optimizing trehalose synthase pathway yields in 50,000+ liter bioreactors command compensation premiums that strain mid-tier producer economics.
- EMA Master File Navigation:Biotechnological active substance dossier preparation requires 18-24 month timelines, delaying market entry for new manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucosylglycerol Market |
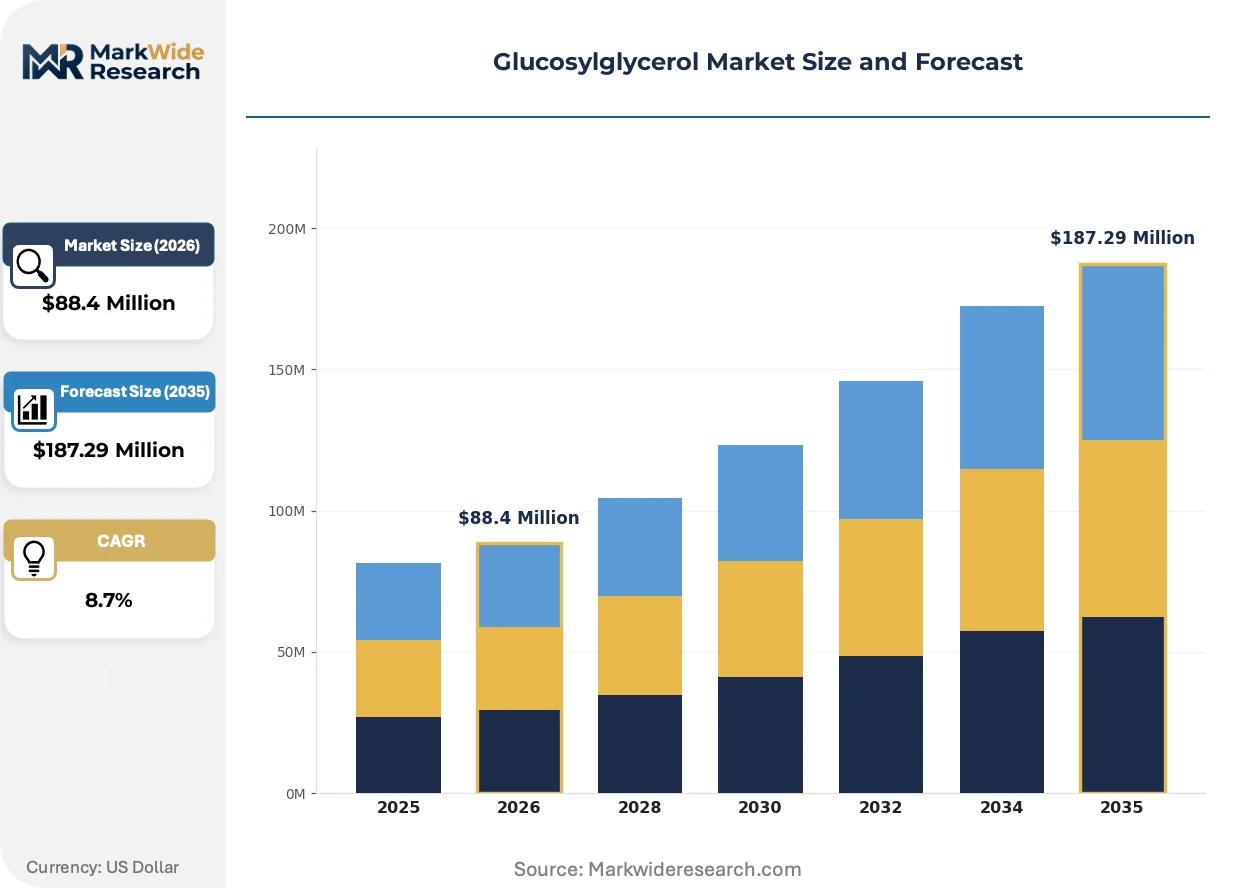
| Market Size in 2026 | $88.4 Million |
| Market Size in 2035 | $187.29 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Powder, Gel, Granule Application: Cosmetics, Pharmaceuticals, Food & Beverage, Agriculture End User: Manufacturers, Research Institutions, Retailers, Distributors Distribution Channel: Online, Offline, Direct Sales, Wholesalers |
| Companies Covered | Evonik Industries, BASF SE, Merck KGaA, Kao Corporation, Bitop AG, Clariant AG, Croda International Plc, Solvay S.A., Jungbunzlauer Suisse AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucosylglycerol Market Trends and Innovations
Continuous processing technologies and single-use bioreactor systems are collapsing batch-to-batch variability while compressing capital requirements for new market entrants.
Enzymatic glycosylation using immobilized trehalose synthase is decomposing the traditional multi-step chemical synthesis route for compatible solutes. Specialty chemical producers in Germany and Switzerland are retrofitting existing fermentation infrastructure to capture this transition. The technology is decomposing cost structures that previously favored high-volume glycerol derivatives, enabling mid-scale biotech specialists to achieve viable unit economics at 500-2000 ton annual outputs.
EMA's 2023 guideline on quality requirements for biotechnological active substances is mandating enhanced host-cell protein clearance validation for cosmetic-grade ingredients previously exempt from pharmaceutical-tier documentation. Contract manufacturers serving European personal care brands are absorbing analytical capital costs to maintain supply relationships. Anhydrous formulation specialists face the steepest compliance burden, as lipid-compatible glucosylglycerol grades require additional solvent residue testing protocols.
Ingredient buyers are consolidating supplier panels around vertically integrated fermentation houses capable of delivering REACH-compliant documentation packages without third-party analytical outsourcing. Premium skincare brands in France and Germany are disqualifying trading-house intermediaries, preferring direct manufacturing relationships with audited bioprocess facilities. This concentration is most visible in the DACH region, where specialty chemical clusters enable same-week sample turnaround for formulation trials.
Glucosylglycerol Market Segmentation
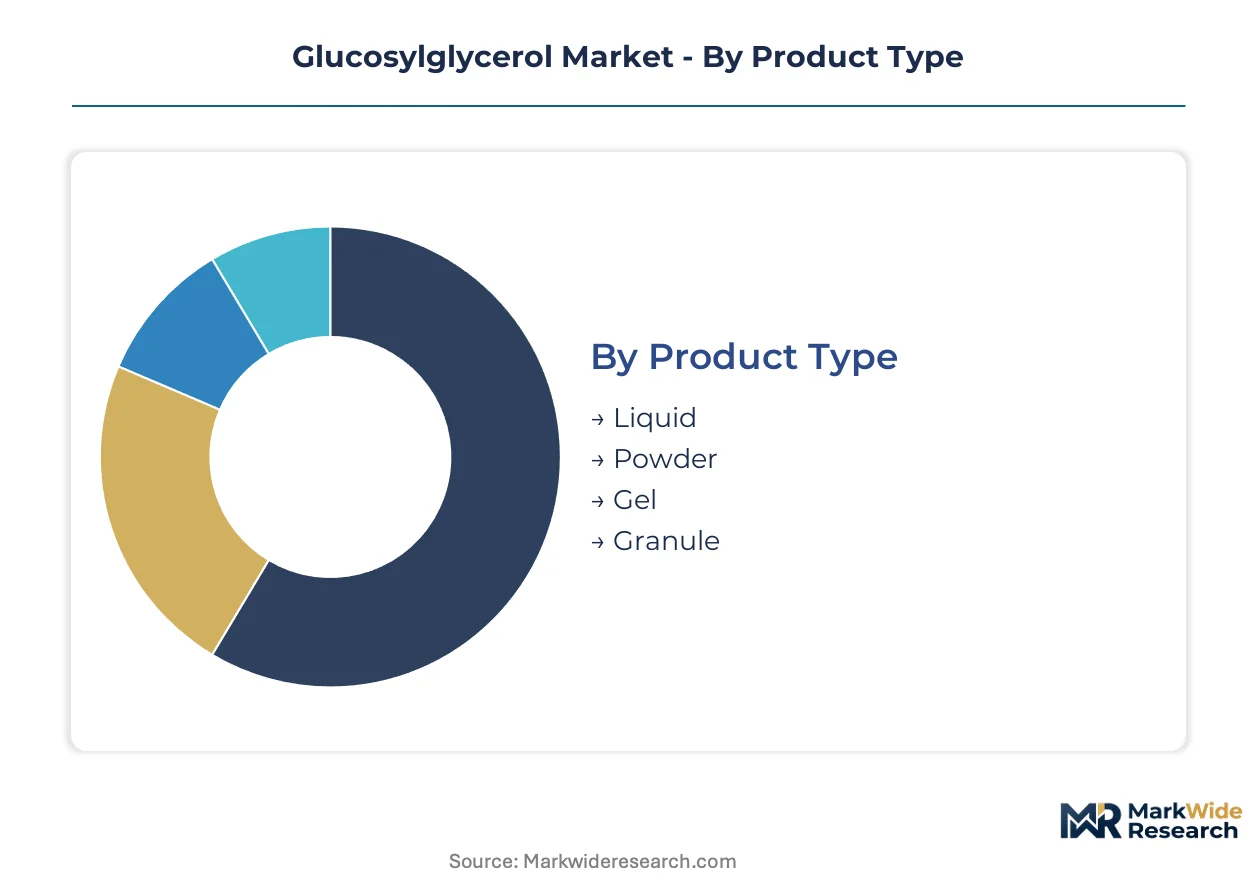
Glucosylglycerol procurement patterns diverge sharply across product formats and end-use specifications. Formulators prioritize different purity grades, solubility profiles, and documentation packages depending on whether the target application is cosmetic, pharmaceutical, or agricultural.
Product Type:
Margin pools concentrate in high-purity liquid grades where cosmetic formulators pay premiums for verified humectant efficacy and rapid formulation integration.
- Liquid:Clear hygroscopic solution with water-retention capacity exceeding glycerol at equivalent concentrations. Demand clusters with European personal care brands near Frankfurt and Düsseldorf specialty chemical hubs seeking REACH-compliant documentation for direct manufacturing relationships.
- Powder:Spray-dried crystalline format with extended shelf stability for solid-dose pharmaceutical applications. Procurement is accelerating from CDSCO-regulated Indian pharmaceutical manufacturers building local analytical capabilities for biotech ingredient certification.
- Gel:Thickened aqueous preparation with enhanced skin-adhesion properties for topical delivery systems.
- Granule:Free-flowing solid format with controlled dissolution kinetics for agricultural osmoprotectant applications.
The dominant share belongs to Liquid, while Powder is closing the gap fastest.
Application:
Volume leadership sits with cosmetics, though pricing premiums of 3-4x attach to pharmaceutical-grade specifications demanding sub-100 ppm protein residue validation.
- Cosmetics:Primary function as humectant and skin-conditioning agent in premium skincare formulations. EWG-verified clean-label specifications from North American brands are tightening supply chain traceability requirements beyond REACH baseline compliance.
- Pharmaceuticals:Osmoprotectant applications in cell-culture media and biopharmaceutical manufacturing. EMA master file navigation demands 18-24 month dossier preparation timelines, constraining supplier participation to vertically integrated fermentation houses.
- Food & Beverage:Compatible solute for moisture retention and texture stabilization in processed formulations.
- Agriculture:Stress-protectant applications for crop enhancement under saline or drought conditions.
Cosmetics commands the deepest margin pool, though Pharmaceuticals shows the steepest expansion trajectory as biomanufacturing capacity scales.
End User:
Procurement authority is consolidating among manufacturers with in-house fermentation expertise capable of delivering integrated documentation packages.
- Manufacturers:Vertically integrated personal care and pharmaceutical producers operating captive bioprocess facilities or direct contract manufacturing agreements.
- Research Institutions:Academic and government laboratories investigating extremophile cultivation and trehalose synthase pathway optimization.
- Retailers:Specialty ingredient distributors serving mid-tier formulators without direct fermentation house relationships.
- Distributors:Trading intermediaries facing disqualification from premium brand supplier panels as procurement consolidates around audited bioprocess facilities.
Manufacturers hold the dominant procurement volume, while Research Institutions are gaining influence fastest through Horizon Europe funding for sustainable process chemistry.
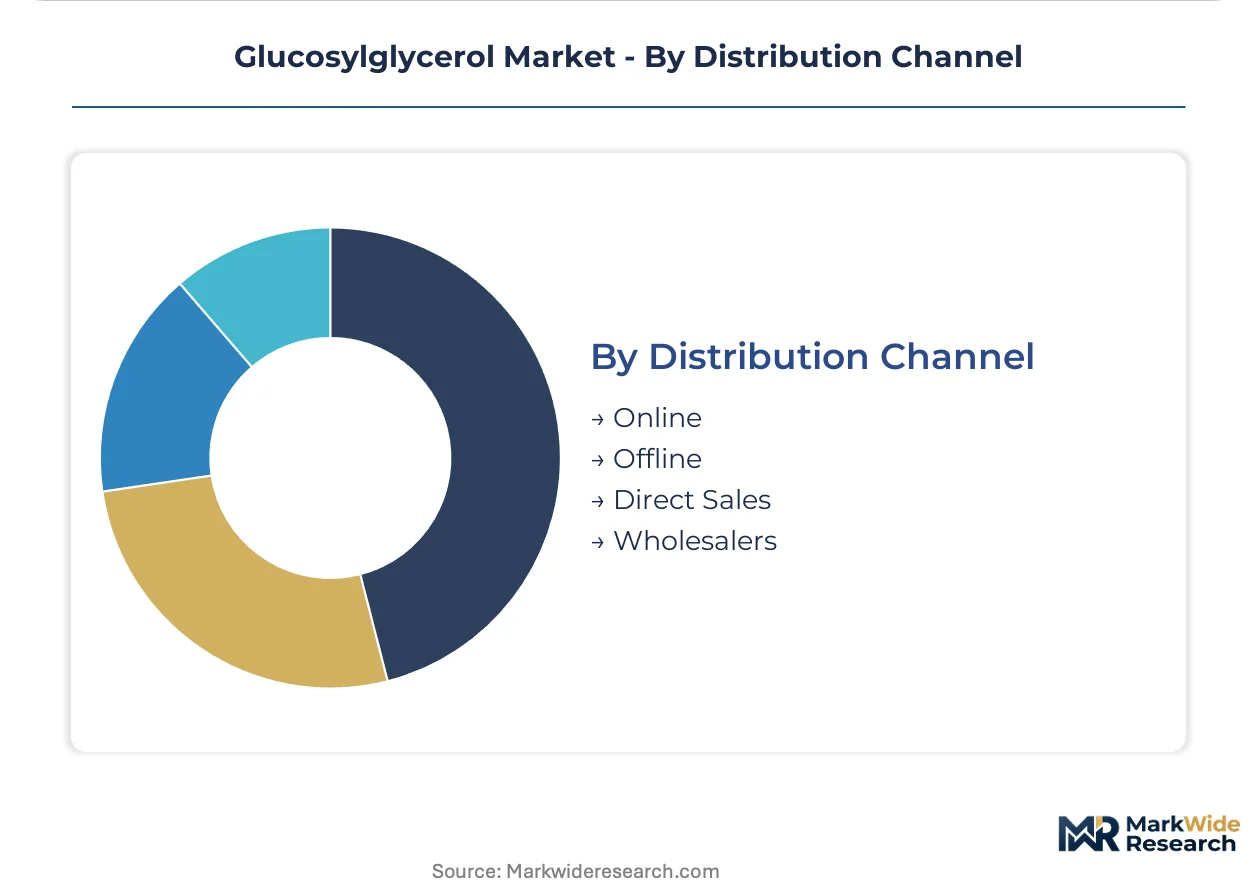
Distribution Channel:
Channel economics favor direct relationships as EMA and FDA compliance burdens render third-party intermediaries uneconomical for pharmaceutical-grade transactions.
- Online:Digital procurement platforms for standard-grade cosmetic ingredients with established specification sheets.
- Offline:Traditional chemical distributor networks serving regional formulators in underdeveloped certification markets.
- Direct Sales:Manufacturing relationships with audited bioprocess facilities enabling same-week sample turnaround for formulation trials in the DACH region.
- Wholesalers:Bulk volume aggregators facing margin compression as supplier panels consolidate around vertically integrated fermentation houses.
Direct Sales captures the dominant transaction value, while Online channels are expanding most quickly for standard-grade cosmetic specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German fermentation houses export cosmetic-grade glucosylglycerol to North American premium skincare brands seeking EWG-verified supply chains. This trade corridor anchors transatlantic pricing benchmarks while Asian pharmaceutical manufacturers build parallel sourcing relationships with Swiss and Japanese suppliers.
Germany
Specialty chemical clusters near Frankfurt and Düsseldorf concentrate contract manufacturing for European personal care brands. ECHA's REACH Phase-In substance deadlines through 2028 disqualify non-compliant glycerol derivatives, redirecting procurement toward biotech-verified alternatives. Evonik Industries anchors supply relationships from its Darmstadt-area facilities.
United States
Clean-label skincare brands reformulate around EWG-verified ingredient lists, creating specification pull for fermentation-derived humectants. FDA cosmetic ingredient safety assessments and EPA fermentation facility discharge permits add compliance layers for market access. Premium formulators in New Jersey and California consolidate supplier panels around audited bioprocess facilities.
Switzerland
Jungbunzlauer Suisse AG exemplifies the vertically integrated fermentation archetype serving pharmaceutical-grade specifications. Swissmedic guidelines on biotechnological active substances shape purity documentation for cell-culture media applications. Basel-area biotechnology infrastructure supports osmoprotectant production for biopharmaceutical manufacturing.
India
CDSCO-regulated pharmaceutical manufacturers accelerate procurement of spray-dried powder formats for solid-dose applications. BIS certification pathways for biotech ingredients remain underdeveloped, offering first-mover advantage to suppliers establishing local analytical documentation capabilities. Mumbai and Hyderabad clusters drive demand for excipient-grade compatible solutes.
Japan
Kao Corporation represents integrated personal care producers with captive fermentation expertise. METI funding for sustainable biomanufacturing subsidizes extremophile cultivation research. Osaka-area chemical parks host trehalose synthase pathway optimization programs for high-purity glucosylglycerol output.
Glucosylglycerol Market Competitive Landscape
Player mix skews toward diversified specialty chemical conglomerates with integrated biotechnology fermentation capacity. Three to five multinational suppliers control REACH-compliant documentation pathways for European cosmetic brands. Strategic archetypes separate into fermentation-integrated conglomerates, lipid-compatible formulation specialists, and pharmaceutical-grade purity validators. Competitive moves center on backward integration into glucose feedstock sourcing and EMA master file navigation capabilities.
Within the fermentation-integrated tier, BASF SE and Evonik Industries exemplify conglomerates leveraging scale advantages in enzymatic glycosylation. Croda International Plc occupies a position among lipid-compatible formulation specialists tailoring anhydrous grades. Merck KGaA and Bitop AG sit within the pharmaceutical-grade purity validator archetype, anchoring osmoprotectant supply for cell-culture media applications.
| Leading Market Players |
|---|
| Evonik Industries |
| BASF SE |
| Merck KGaA |
| Kao Corporation |
| Bitop AG |
| Clariant AG |
| Croda International Plc |
| Solvay S.A. |
| Jungbunzlauer Suisse AG |
| Others |
Pricing and Supply Chain Analysis
Six-to-eight-week sample turnaround times for REACH-compliant documentation packages concentrate pricing power with German fermentation houses near Frankfurt and Düsseldorf, compressing margins for distributors lacking direct bioprocess auditing relationships. This lead-time band tightens procurement options for North American premium skincare brands seeking EWG-verified supply chains, forcing acceptance of premium-tier contract structures or exclusion from qualified supplier panels.
Pricing Analysis
Enzymatic glycosylation technology-generation pricing gaps separate incumbent halophilic fermentation processes from emerging immobilized trehalose synthase platforms and next-generation continuous processing systems. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and industrial-grade specifications anchors the dominant model, with differentiation driven by protein residue certification levels and EMA master file navigation capabilities. Cost compression in cosmetic-grade tiers intensifies as mid-scale biotech specialists achieve viable unit economics at 500-2000 ton annual outputs. Contract manufacturers demonstrate highest price sensitivity due to glucose syrup feedstock volatility, while pharmaceutical osmoprotectant buyers accept 3-4x premiums for sub-100 ppm protein validation.
Supply Chain Analysis
Inbound logistics costs from Rotterdam-Antwerp port congestion and container availability constraints on Asia-Europe trade lanes amplify working capital requirements for glucose syrup imports. Supply concentrates in Germany, Switzerland, and Japan, with raw material dependencies on corn-derived glucose, glycerol feedstocks, and specialized extremophile cultivation media. Single-source vulnerability around Halomonas elongata strain banks at Darmstadt-area facilities creates concentration risk. Distribution runs through direct manufacturing relationships with audited bioprocess facilities, bypassing traditional chemical distributors for REACH-compliant transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Halophilic fermentation advances are disrupting compatible solute economics, with ECHA's 2023-2028 REACH Phase-In substance timeline accelerating substitution away from petrochemical glycerol derivatives toward biotech-verified alternatives.
For Market Incumbents: Compound defensive positioning through captive trehalose synthase pathway optimization and EMA master file navigation capabilities that delay competitor facility qualification by 18-24 months. Threats from immobilized enzyme platform specialists demand backward integration into glucose feedstock sourcing to insulate margins from agricultural commodity spikes. Priority lever rests with same-week sample turnaround infrastructure in the DACH region that locks in premium skincare brand relationships. For New Entrants and Emerging Players: Differentiate on CDSCO-aligned analytical documentation capabilities for Indian pharmaceutical manufacturers accelerating powder-format procurement for solid-dose applications. White-space targets include BIS certification pathway development for biotech ingredients and osmoprotectant supply for biopharmaceutical manufacturing with 3-4x pricing premiums. Go-to-market angle centers on Horizon Europe funding access for sustainable process chemistry retrofits. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified specialty chemical conglomerates with underutilized fermentation capacity and stranded cosmetic-grade documentation assets. Long-term viability frames around 5-10 year windows for enzymatic glycosylation platform consolidation before continuous processing commoditizes unit economics. Acquisition target archetype: mid-tier German contract manufacturers with REACH-compliant infrastructure and direct brand relationships. Signal to watch: EMA guideline enforcement tightening host-cell protein clearance validation for cosmetic-grade ingredients previously exempt from pharmaceutical-tier documentation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Feedstock | Corn futures exposure compression secures margin stability for fermentation houses near Frankfurt. |
| EMA Master File Navigation Capability | 18-24 month dossier preparation timelines create qualification barriers for new manufacturing sites. |
| Continuous Processing Technology Adoption | Single-use bioreactor systems collapse batch-to-batch variability for mid-scale biotech specialists. |
| CDSCO-Aligned Analytical Documentation | Indian pharmaceutical manufacturers accelerate powder-format procurement for solid-dose applications. |
| Horizon Europe Funding Access | EU Green Deal biomanufacturing subsidies offset capital expenditure for fermentation facility retrofits. |
Research Methodology
Operator-level perspectives from fermentation plant managers, cosmetic formulators, pharmaceutical procurement leads, and regulatory affairs directors anchored the qualitative base for this analysis. Primary interviews combined with secondary validation from ECHA registration databases, EMA biotechnological active substance guidelines, SEC filings of specialty chemical conglomerates, and customs/trade data for glucose syrup and compatible solute flows. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across product formats and end-use specifications.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios, REACH compliance timeline variations, and halophilic fermentation yield improvement trajectories. Segmentation dimensions modeled include product format, application grade tier, end-use industry, and regional production hub concentration. CAGRs derived from installed fermentation capacity expansion schedules, brand reformulation pipeline visibility, and documentation upgrade timelines across the analysis window. Industry-specific inputs incorporated extremophile cultivation yield curves and trehalose synthase pathway optimization rates.
The analysis sits within stated boundaries; outcomes outside sustained EMA guideline enforcement, glucose feedstock price stability, or REACH Phase-In substance deadline adherence would require recalibration. Forecasts reflect assumptions around halophilic fermentation cost reduction trajectories and clean-label skincare brand procurement consolidation patterns. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Feed Yeast Market
Ingredients
Bay Leaf Oil Market
Ingredients
Asia-Pacific Dairy Ingredients Market
Ingredients
Bean Ingredients Market
Ingredients
GCC Bakery Ingredients Market
Ingredients
Instant Starches Market
Ingredients
Punica Granatum (Pomegranate) Seed Oil Market
Ingredients
Colombia Food Ingredients Market
Ingredients
Industrial and Bar-B-Que Charcoal Market
Ingredients
Feed Premix Market
Ingredients
Fish Peptones Market
Ingredients
Sesame Seed Extract Market
Ingredients
Safflower Oil Market
Ingredients
Omega-3 Encapsulation Market
Ingredients
Date Syrup Market
Ingredients
High Protein Flour Market