
 Pomegranate Market | 2026-2036
Pomegranate Market Size, Share, and Industry Trends Forecast 2026-2036
Pomegranate Market Intelligence
The capital-intensity divergence between integrated processors and commodity traders is reorganizing competitive tiers across the pomegranate value chain. POMWonderful leverages captive orchards in California's Central Valley to sustain year-round supply consistency. Tropicana competes through beverage-scale procurement networks that anchor global concentrate flows. RW Knudsen Family differentiates via organic certification and cold-press positioning in premium channels.
Pomegranate comprises the edible fruit of Punica granatum, a deciduous shrub bearing leathery-skinned berries with arils containing anthocyanins, punicalagins, and ellagic acid typically processed at brix levels of 12-16 for juice applications. The fruit serves pharmaceutical, nutraceutical, and food-grade markets requiring standardized polyphenol content. Fresh pomegranates retain dominant volume share in Middle Eastern and South Asian retail channels where whole-fruit consumption persists. Pomegranate extract concentrates margin pools in cosmetic and dietary supplement applications where punicalagin standardization commands premium pricing. Dried pomegranate segments occupy niche positions in snack and bakery ingredient channels with slower velocity but higher shelf stability.
USDA grading standards and FDA juice labeling requirements shape product specifications for American market access, while EFSA novel food assessments govern extract approvals in European trade. India's FSSAI fortification guidelines and BIS processing standards regulate domestic concentrate quality and import thresholds. Stakeholders must monitor evolving polyphenol measurement protocols and origin-certification demands as buyer traceability requirements harden across export markets.
Market Dynamics
Functional beverage formulations are restructuring procurement priorities across the pomegranate value chain, as polyphenol standardization requirements harden in pharmaceutical and nutraceutical channels.
Growth Catalysts
- EFSA novel food pathways:European clearance mechanisms for pomegranate extract concentrates are accelerating pharmaceutical-grade applications, expanding margin pools in cosmetic and dietary supplement segments.
- California orchard consolidation:Captive cultivation investments in the Central Valley and San Joaquin Valley are compressing supply volatility for year-round juice concentrate availability.
- Punicalagin extraction refinement:Advanced solvent-free processing technologies are enabling higher polyphenol retention rates in cosmetic-grade extracts, opening premium positioning in skin-care formulations.
Market Restraints
- Input cost volatility:Water scarcity in Maharashtra and California is amplifying irrigation expenditure for orchard operators, squeezing margins at the cultivation tier.
- REACH compliance friction:ECHA registration requirements for extract exports are extending certification timelines and elevating testing costs for European market access.
- Concentrate substitution:Tart cherry and blueberry concentrates are displacing pomegranate in mid-tier functional beverage formulations where polyphenol specificity is less critical.
Strategic Opportunities
- India domestic fortification:FSSAI guidelines for food fortification are creating institutional procurement channels for pomegranate concentrate in school nutrition and public health programs.
- Cold-press channel expansion:Premium retail and direct-to-consumer platforms are absorbing higher-unit-value organic juice products with extended shelf-life packaging.
- Dual carbon alignment:China's SAMR sustainability disclosure frameworks are incentivizing low-carbon processing investments for export-oriented concentrate facilities.
Industry Challenges
- Polyphenol measurement standardization:Divergent analytical protocols between USDA, BIS, and EFSA are complicating cross-border certification and lot-release procedures.
- Orchard-to-processor traceability infrastructure:Blockchain and IoT integration for origin verification is requiring capital deployment that mid-tier traders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pomegranate Market |
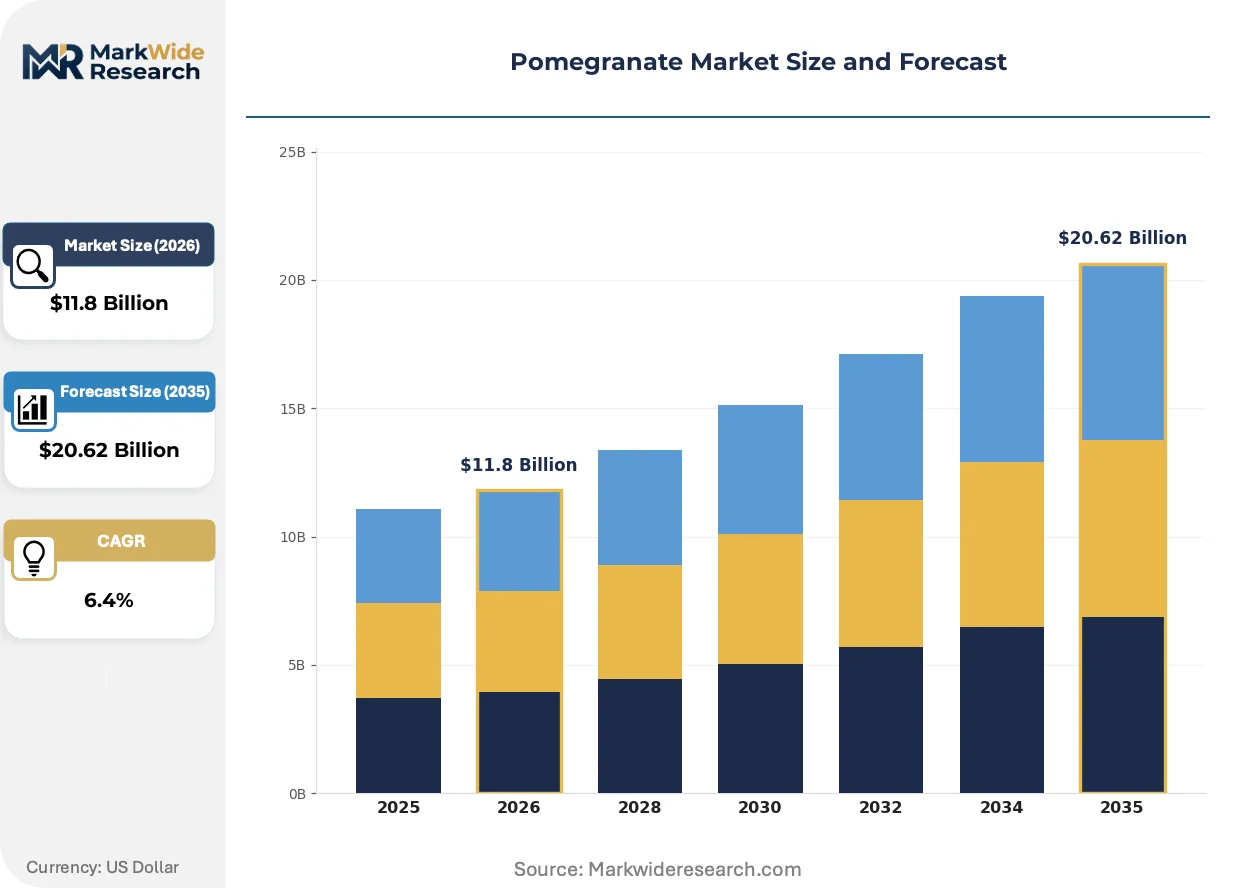
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Pomegranates, Pomegranate Juice, Pomegranate Extract, Dried Pomegranates End User: Retail Consumers, Food Manufacturers, Beverage Industry, Cosmetic Manufacturers Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Farmers Markets Form: Whole Fruits, Juiced, Concentrates, Powder |
| Companies Covered | Tropicana, Jale and Zolotoy Sad, POMWonderful, Arvee, Narni, Lakewood, RW Knudsen Family, TTM Food, Minute Maid, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pomegranate Market Strategic Shifts & Innovations
Processing technology and regulatory disclosure requirements are converging to reshape competitive positioning across concentrate and extract segments.
Supercritical CO2 extraction is decomposing traditional solvent-based methods for punicalagin recovery, enabling pharmaceutical-grade purity without residual chemical markers. Nutraceutical contract manufacturers in Germany and Switzerland are adopting these systems at accelerating replacement cycles. This technology is decomposing the historical price premium commanded by organic-certified extracts, as conventional-grade outputs achieve equivalent polyphenol standardization.
REACH authorization amendments for botanical extracts are tightening substance volume tracking requirements across European supply chains. Manufacturers must now document full lifecycle environmental footprints for concentrate exports, elevating compliance costs for non-integrated traders. Cosmetic formulators in France and Italy are responding by consolidating supplier bases toward vertically integrated processors with captive analytical laboratories.
Ingredient buyers are compressing supplier qualification cycles, demanding simultaneous provision of organic certification, polyphenol assay data, and carbon footprint documentation in initial procurement rounds. This pattern is displacing traditional multi-stage vendor approval processes in North American beverage manufacturing. The shift is most pronounced in California and Pacific Northwest formulation facilities serving functional drink brands.
Pomegranate Market Segmentation
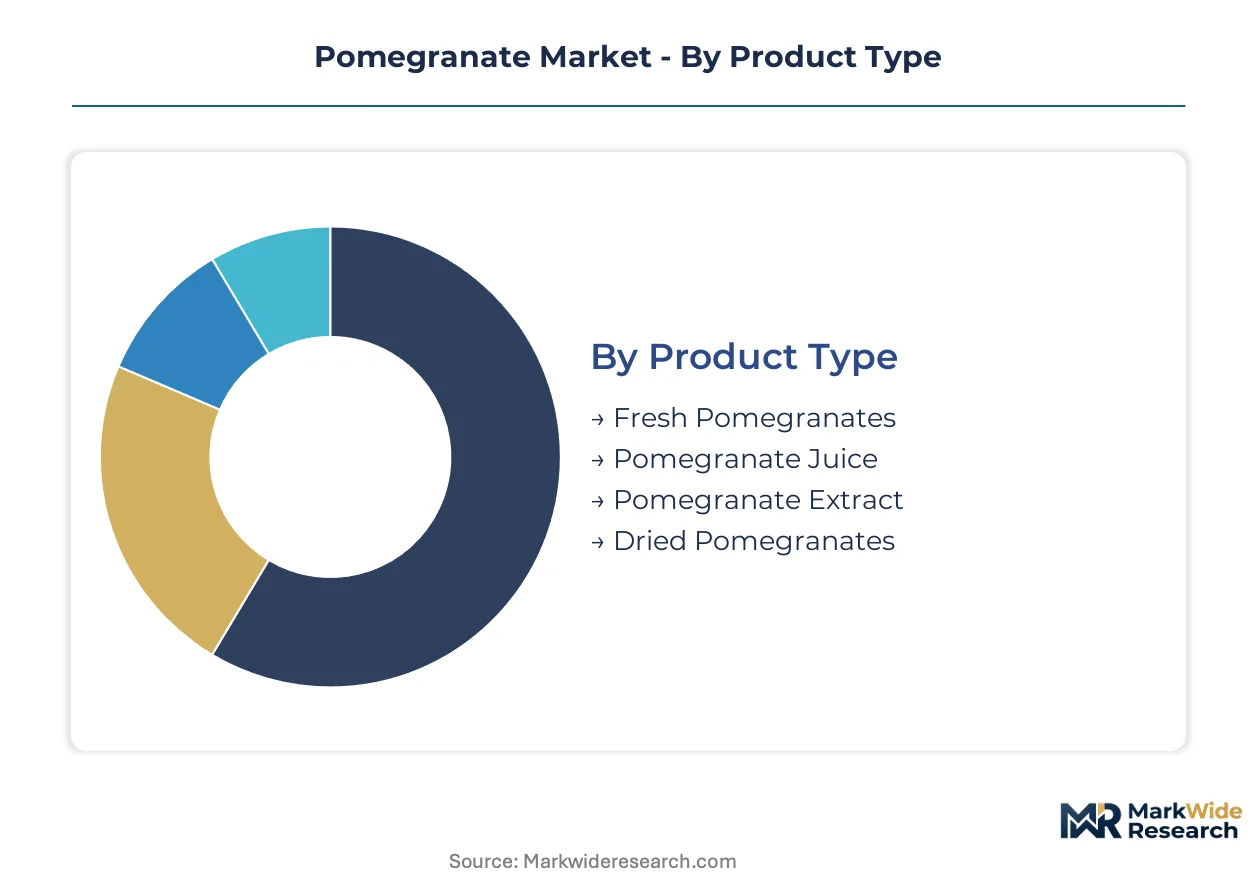
Pomegranate value chain participants navigate divergent margin structures and certification requirements across product categories. Segmentation clarity enables procurement teams to align specifications with end-use applications while managing regulatory exposure across jurisdictions.
Product Type:
EFSA novel food assessments, FDA juice labeling standards, and BIS processing requirements create distinct compliance burdens across product categories, filtering market access for non-specialized suppliers.
- Fresh Pomegranates:Whole fruits with leathery rind and aril clusters containing anthocyanins and punicalagins, typically graded by USDA standards for size and external blemishes. Retail channels in India and Iran absorb dominant volume where whole-fruit consumption traditions persist; water scarcity in California and Maharashtra is compressing orchard margins and elevating import dependence in European markets.
- Pomegranate Juice:Single-strength or reconstituted beverages processed at 12-16 brix with standardized polyphenol content, subject to FDA identity standards and FSSAI fortification guidelines. Beverage manufacturers in Germany and the United States concentrate procurement for functional drink formulations; tart cherry and blueberry substitution is intensifying in mid-tier formulations where polyphenol specificity carries less weight.
- Pomegranate Extract:Concentrated polyphenol preparations standardized for punicalagin content, governed by REACH registration and EFSA novel food pathways for pharmaceutical and cosmetic applications.
- Dried Pomegranates:Dehydrated arils or segments with extended shelf stability, positioned in snack and bakery ingredient channels with slower inventory velocity.
Fresh Pomegranates handles the majority of throughput; Pomegranate Extract is expanding most quickly on share.
End User:
Procurement sophistication varies sharply across customer tiers, with institutional buyers demanding integrated certification packages that commodity traders struggle to assemble.
- Retail Consumers:Individual purchasers selecting whole fruits or premium juices through supermarkets and direct-to-consumer platforms, with organic and cold-press preferences concentrating in California and Pacific Northwest markets.
- Food Manufacturers:Industrial buyers incorporating dried segments or concentrated extracts into bakery, confectionery, and functional food formulations, requiring FSSAI-compliant documentation for Indian operations and EFSA traceability for European exports.
- Beverage Industry:Scale processors of juice concentrates and functional drink formulations, compressing supplier qualification cycles to demand simultaneous organic certification, polyphenol assays, and carbon footprint documentation.
- Cosmetic Manufacturers:Formulators in France and Italy sourcing pharmaceutical-grade punicalagin extracts for skin-care applications, consolidating supplier bases toward vertically integrated processors with captive analytical laboratories.
Beverage Industry commands the dominant procurement volume; Cosmetic Manufacturers is climbing the fastest as premium extract demand accelerates.
Distribution Channel:
Channel selection determines margin capture and traceability infrastructure requirements, with digital platforms disrupting traditional wholesale hierarchies.
- Online Retail:Direct-to-consumer platforms absorbing premium organic and cold-press juice products, requiring extended shelf-life packaging investments and blockchain-enabled origin verification.
- Supermarkets:Conventional retail chains dominating fresh fruit volume in Middle Eastern and South Asian markets where whole-pomegranate display traditions persist.
- Wholesale Distributors:Bulk concentrate and extract handlers serving food and beverage manufacturers, facing margin compression from REACH compliance costs and polyphenol measurement standardization requirements.
- Farmers Markets:Localized fresh fruit channels with limited scale but highest per-unit margins for heritage cultivars and organic-certified produce.
Supermarkets retains the volume leadership; Online Retail is gaining share fastest through premium product absorption.
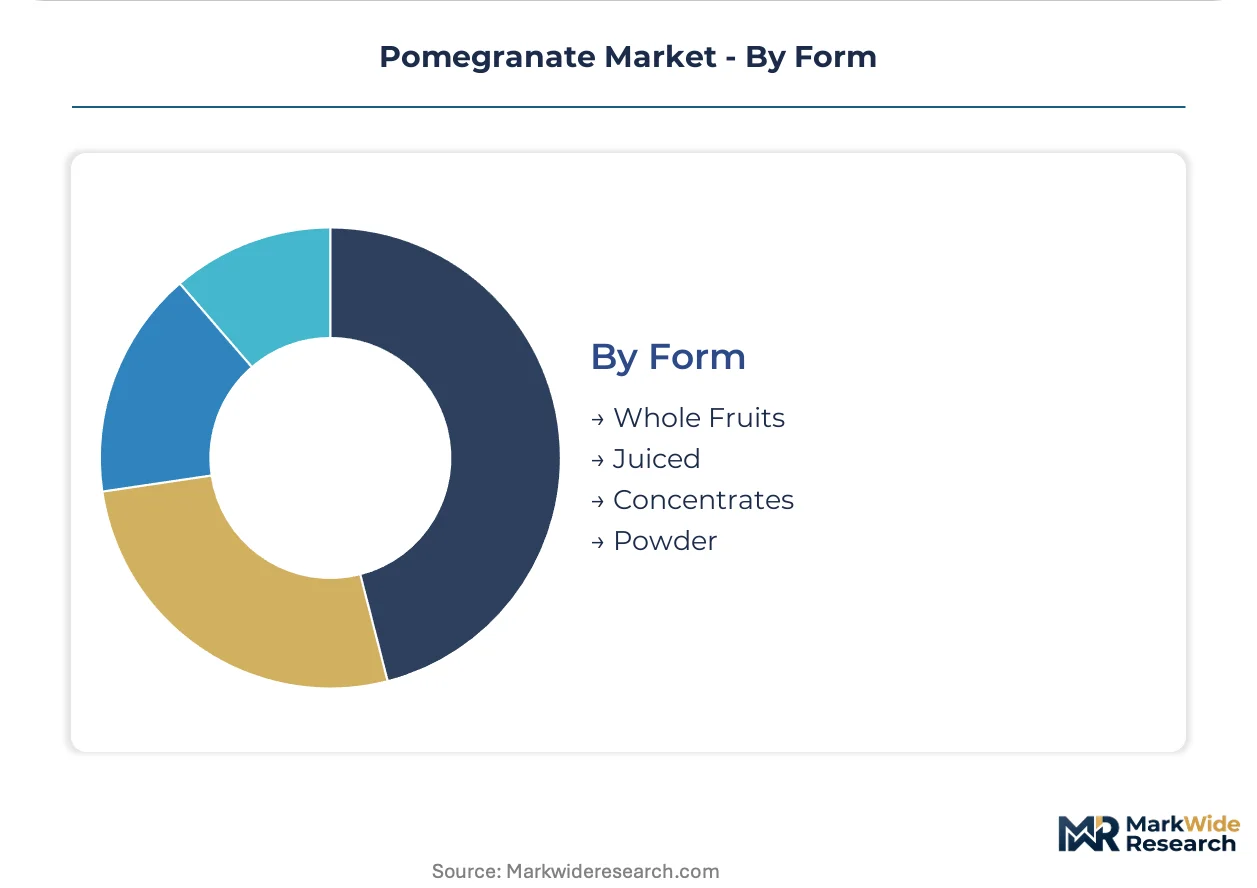
Form:
Processing intensity and polyphenol retention rates segment form selection, with extraction technology investments determining competitive positioning.
- Whole Fruits:Unprocessed pomegranates for fresh consumption or manual aril extraction, dominant in Middle Eastern retail where pericarp utilization traditions persist.
- Juiced:Single-strength liquid products for immediate consumption or further processing, governed by FDA juice labeling and requiring HACCP-compliant handling infrastructure.
- Concentrates:Reduced-moisture preparations at elevated brix for beverage reconstitution and industrial formulation, with supercritical CO2 extraction displacing solvent-based methods in premium tiers.
- Powder:Spray-dried or freeze-dried preparations for nutraceutical capsules and cosmetic formulations, commanding premium positioning where punicalagin standardization exceeds pharmaceutical thresholds.
Concentrates manages the bulk of industrial throughput; Powder is expanding most steeply as nutraceutical and cosmetic applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian retail channels demonstrate the highest price elasticity for fresh whole fruits, while German cosmetic formulators absorb premium extract pricing with minimal volume sensitivity. California orchard operators face irrigation cost pressures that compress margins at the cultivation tier. Iranian export flows concentrate in Middle Eastern fresh fruit corridors where pericarp utilization traditions persist.
United States
Beverage manufacturers in California and the Pacific Northwest compress supplier qualification cycles for organic-certified concentrates. FDA juice labeling standards and USDA grading protocols shape product specifications for domestic market access. San Joaquin Valley orchard consolidation accelerates as POMWonderful and integrated processors expand captive cultivation to secure year-round supply consistency.
India
Maharashtra state cultivation investment intensifies despite water scarcity amplifying irrigation expenditure for orchard operators. FSSAI fortification guidelines for school nutrition and public health programs create institutional procurement channels for pomegranate concentrate. Mumbai-Pune industrial corridor food processors expand cold-press capacity to serve premium domestic retail and export markets.
Germany
Nutraceutical contract manufacturers in Bavaria and Baden-Württemberg adopt supercritical CO2 extraction systems at accelerating replacement cycles. EFSA novel food assessments and REACH registration requirements govern pharmaceutical-grade extract approvals and substance volume tracking. Cosmetic formulators in the Rhine-Ruhr region consolidate supplier bases toward vertically integrated processors with captive analytical laboratories.
China
SAMR sustainability disclosure frameworks incentivize low-carbon processing investments for export-oriented concentrate facilities in Shandong and Xinjiang. Dual carbon alignment requirements reshape procurement criteria for European-bound extract shipments. Yangtze River Delta beverage compounders expand functional drink formulation capacity using imported concentrate flows.
Iran
Whole-fruit export volumes dominate regional trade into UAE, Saudi Arabia, and other Gulf markets where pericarp utilization traditions persist. Domestic processing infrastructure remains limited relative to cultivation scale. Mashhad and Yazd cultivation zones concentrate heritage cultivar production for premium fresh fruit channels.
Pomegranate Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the pomegranate value chain. Integrated processors with captive orchards command supply consistency premiums, while commodity traders compete on procurement network scale. Three archetypes dominate: orchard-integrated beverage brands, organic-certified cold-press specialists, and nutraceutical extract refiners. Competitive moves concentrate on backward integration into cultivation assets and supercritical extraction technology licensing.
Among orchard-integrated beverage processors, POMWonderful exemplifies captive supply control through Central Valley holdings. Tropicana occupies a position representing scale-driven concentrate procurement networks anchoring global flows. RW Knudsen Family sits within the organic-certified premium tier, differentiating through cold-press positioning in direct-to-consumer channels. These three anchors illustrate the structural divergence between volume-scale beverage supply and premium extract specialization.
| Leading Market Players |
|---|
| Tropicana |
| Jale and Zolotoy Sad |
| POMWonderful |
| Arvee |
| Narni |
| Lakewood |
| RW Knudsen Family |
| TTM Food |
| Minute Maid |
| Others |
Cost & Logistics Intelligence
Captive orchard scale in California's Central Valley compresses unit economics for integrated processors while elevating price floors for commodity traders dependent on spot procurement. Water scarcity in Maharashtra and irrigation cost inflation across both cultivation belts are amplifying margin divergence between backward-integrated beverage brands and non-specialized concentrate handlers.
Pricing Analysis
After-sales contract revenue from long-term concentrate supply agreements drives lifetime value for integrated processors serving beverage compounders. Three-tier pricing structure across organic-certified premium, conventional food-grade, and commodity feedstock tiers separates POMWonderful's captive supply premiums from mid-tier concentrate spot markets. Pricing pressure stems from tart cherry and blueberry substitution in functional beverage formulations where polyphenol specificity carries less weight. Beverage manufacturers in Germany and the United States demonstrate lowest price sensitivity for pharmaceutical-grade punicalagin extracts, while Indian institutional buyers under FSSAI fortification programs anchor the most elastic demand tier.
Supply Chain Analysis
Inventory lead times for supercritical CO2 extraction equipment extend qualification cycles for European cosmetic formulators consolidating supplier bases toward German and Swiss contract manufacturers. Supply concentrates in California's San Joaquin Valley, India's Maharashtra state, and Iran's Mashhad cultivation zones, with Iranian fresh fruit flows dominating Middle Eastern retail channels where pericarp utilization traditions persist. Raw material dependencies center on irrigation water access, heritage cultivar propagation stock, and pharmaceutical-grade solvent systems for punicalagin recovery. Tariff exposure on EU-bound extract shipments under REACH registration requirements elevates compliance costs for non-integrated traders. Distribution runs through wholesale concentrate handlers serving beverage scale processors, with direct-to-consumer platforms absorbing premium organic cold-press volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pomegranate market tracks a cyclical recovery pattern as functional beverage procurement rebounds from concentrate substitution troughs, with polyphenol standardization requirements in pharmaceutical channels providing demand floor support.
For Market Incumbents: Shield margin pools in pharmaceutical-grade extract tiers by deepening supercritical CO2 extraction capacity in Bavaria and Baden-Württemberg manufacturing corridors. Consolidate supplier qualification advantages through captive analytical laboratories that compress lot-release timelines for EFSA novel food pathways. Water scarcity in California and Maharashtra threatens cultivation-tier stability; secure irrigation infrastructure or captive orchard holdings in both belts to buffer supply volatility. For New Entrants and Emerging Players: Differentiate on cold-press organic certification for direct-to-consumer platforms in California and Pacific Northwest markets where premium absorption outpaces conventional retail velocity. Target India's institutional procurement channels under FSSAI fortification guidelines for school nutrition programs, the most penetrable white-space segment with volume scale potential. Deploy blockchain-enabled origin verification as the go-to-market angle to satisfy compressed supplier qualification cycles among North American beverage manufacturers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors nutraceutical extract refiners with supercritical CO2 extraction licensing capabilities over commodity concentrate traders facing REACH compliance cost inflation. Long-term viability over the next decade rests on polyphenol measurement standardization convergence across USDA, BIS, and EFSA protocols. Watch for EFSA novel food assessment acceleration as the inflection signal indicating pharmaceutical-grade extract margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Orchard Expansion | Secures year-round supply consistency for POMWonderful against California water scarcity. |
| Supercritical CO2 Licensing | Enables German contract manufacturers to achieve pharmaceutical-grade punicalagin purity without residual solvents. |
| Blockchain Traceability Deployment | Satisfies compressed qualification cycles among Pacific Northwest beverage formulators demanding origin verification. |
| Cold-Press Channel Buildout | Captures premium retail absorption in direct-to-consumer platforms with extended shelf-life packaging. |
| EFSA Novel Food Pre-Submission | Accelerates pharmaceutical-grade extract approvals for cosmetic formulators in France and Italy. |
Research Approach
Desk research of customs trade databases, EFSA novel food assessment registers, and FSSAI fortification guideline publications preceded structured interviews with beverage procurement directors, cosmetic formulator R&D leads, orchard operations managers, and nutraceutical contract manufacturing executives. Secondary validation drew from USDA grading standard documentation, REACH registration filings with ECHA, and California agricultural water district reports. Bottom-up cultivation area estimates and top-down concentrate flow analysis were triangulated against polyphenol assay data from supercritical extraction facilities.
Variance decomposition across product type, end-use application, form factor, and geographic regulatory cluster shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level volume trajectories and value-per-unit movements throughout the forecast period. Forecast inputs incorporated irrigation cost inflation curves for Maharashtra and San Joaquin Valley operators, plus EFSA novel food assessment pipeline velocity for pharmaceutical-grade extract segments.
Forecasts assume regulatory continuity in EFSA novel food pathways, REACH substance volume tracking, and FSSAI fortification guidelines; material policy shifts in any regime would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Dill Pickles Market
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Guanabana Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Venezuela Fruits and Vegetable Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Gold Kiwifruit Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Turkish Figs Market