
 Cholic Acid Market | 2026-2036
Cholic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Cholic Acid Market Analysis
API contract manufacturing revenue is tilting toward high-purity cholic acid for orphan-drug applications. Sigma-Aldrich leverages its catalog breadth to dominate research-grade supply across North American and European laboratories. Zhongshan Belling Biotechnology anchors its position through captive fermentation capacity and backward integration into bile-raw-material sourcing. Pfizer CentreOne competes by extending its CDMO platform into controlled-substance and bile-acid derivative synthesis.
Cholic acid is a primary bile acid with a steroid nucleus and a three-alpha-hydroxyl configuration, synthesized in the liver from cholesterol via the classical and alternative pathways; it functions physiologically as a biological detergent for lipid emulsification and is manufactured industrially through solvent extraction from bovine or ovine bile, followed by chromatographic purification to meet pharmacopeial monograph specifications. Modified cholic acid and synthetic cholic acid represent the fastest-expanding product categories, as pharmaceutical clients seek alternatives to animal-derived supply chains amid BSE-related import restrictions. Drug formulations and clinical trials applications concentrate the highest margin pools, whereas powder and capsule forms dominate volume throughput due to simpler stability requirements and lower cold-chain dependency.
The FDA enforces stringent identity and purity standards for cholic acid APIs through ICH Q3D elemental impurity guidelines and USP monograph compliance, while China's NMPA mandates batch-level nucleic-acid testing and geographic sourcing documentation for all animal-derived imports. The European Medicines Agency applies REACH and EU MDR traceability rules that extend liability across the bile-acid derivative supply chain. Stakeholders must monitor regulatory divergence between pharmacopeial standards and emerging biosynthetic qualification pathways to secure long-term formulation contracts.
Market Dynamics
China's NMPA impurity-profile tightening for imported bile acids is forcing API buyers to requalify suppliers, concentrating procurement toward domestic fermentation-based manufacturers in Jiangsu and Zhejiang provinces who control captive feedstock access.
Growth Catalysts
- Orphan-drug demand:Pharmaceutical-grade cholic acid for rare liver disease therapies draws heightened procurement from specialty API buyers seeking GMP-certified supply chains.
- REACH traceability mandates:EMA enforcement of EU MDR liability rules across bile-acid derivative supply chains compels documented geographic sourcing and batch-level nucleic-acid testing.
- Fermentation technology maturation:Microbial synthesis platforms in Chinese manufacturing clusters achieve pharmacopeial purity without animal-derived raw material dependency.
Market Restraints
- Bovine spongiform encephalopathy trade barriers:BSE-related import restrictions in multiple jurisdictions block solvent-extracted cholic acid from traditional bovine bile supply chains.
- Input cost volatility:Bile raw material prices fluctuate with livestock herd cycles and slaughter rates, compressing margins for extraction-dependent producers.
- ICH Q3D compliance burden:FDA elemental impurity guidelines require expensive analytical equipment and validated testing protocols that exclude smaller API manufacturers.
Strategic Opportunities
- Synthetic biology pathways:Cell-free enzymatic synthesis and engineered yeast strains converge to create fully synthetic cholic acid independent of animal agriculture.
- Indian CDMO expansion:Underpenetrated contract manufacturing capacity in India offers alternative production geography as Chinese supply faces NMPA scrutiny.
- Research-grade channel innovation:Direct-to-laboratory e-commerce platforms bypass traditional distributor markups for catalog chemical buyers in academic and biotech segments.
Industry Challenges
- Analytical chemistry skill scarcity:Steroid nucleus characterization and three-alpha-hydroxyl configuration verification require specialized chromatography expertise that outpaces training pipeline output.
- Dual certification timelines:Simultaneous USP monograph compliance and NMPA registration create 18-24 month approval windows that delay revenue recognition.
- Cold-chain infrastructure capex:Stability requirements for high-purity formulations demand validated refrigerated storage and distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cholic Acid Market |
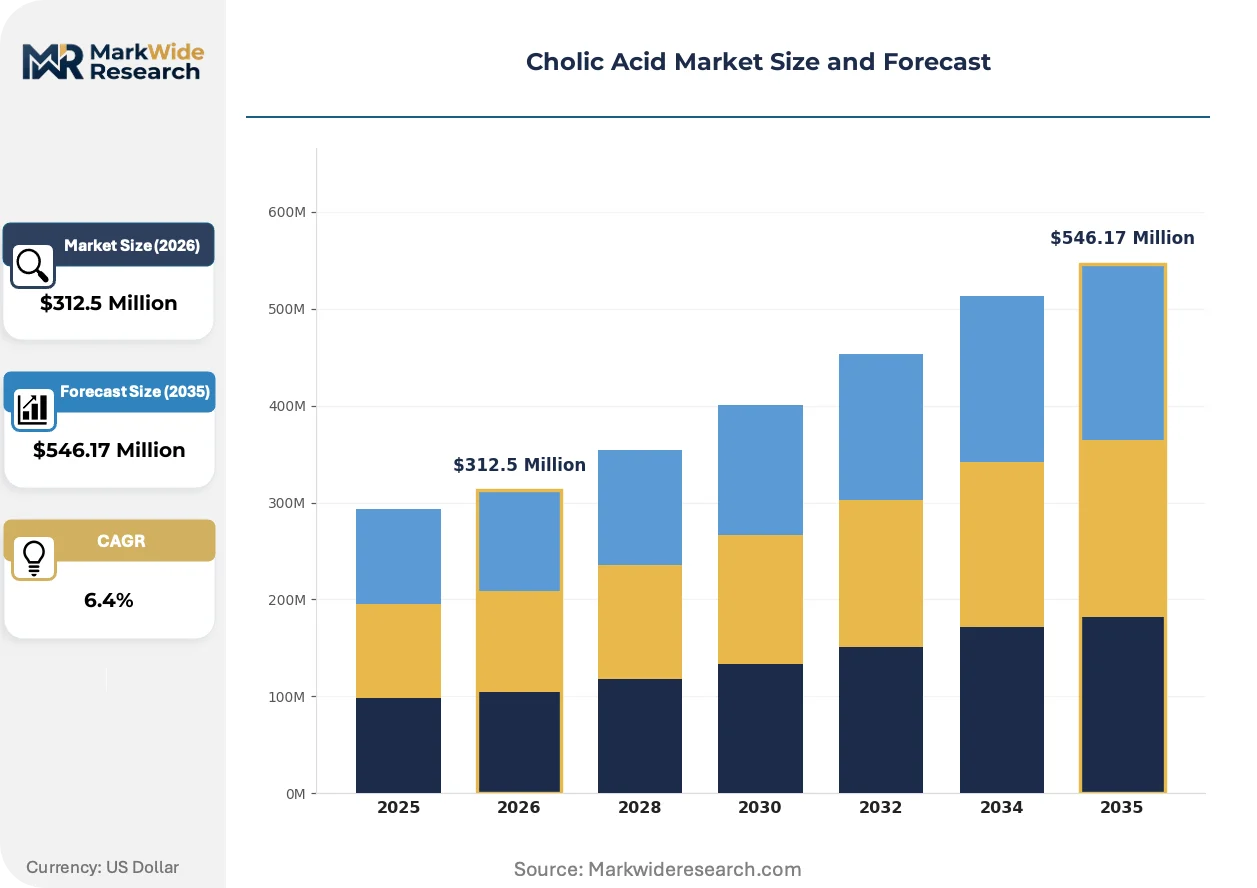
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Raw Cholic Acid, Modified Cholic Acid, Synthetic Cholic Acid, Cholic Acid Derivatives End User: Pharmaceutical Companies, Dietary Supplement Manufacturers, Research Institutions, Chemical Industries Application: Drug Formulations, Nutraceuticals, Scientific Research, Clinical Trials Form: Oral Tablets, Capsules, Powder, Liquid Solutions |
| Companies Covered | Avanti Polar Lipids, Cayman Chemical, Toronto Research Chemicals, Sigma-Aldrich, Pfizer CentreOne, Dr Falk Pharma, Bruschettini, Zhongshan Belling Biotechnology, ICE Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cholic Acid Market Emerging Trajectories
Bioprocess engineering advances and regulatory divergence between pharmacopeial and biosynthetic qualification pathways are compressing traditional extraction economics while opening alternative manufacturing routes.
Enzymatic cascade synthesis using recombinant 7α-hydroxylase and 12α-hydroxylase enzymes converts cholesterol directly to cholic acid without bile extraction. Specialty API buyers in orphan-drug development are qualifying these biocatalytic routes for clinical-grade supply. Animal-derived extraction methods are rendering obsolete for applications requiring BSE-free documentation.
China's NMPA now mandates batch-level nucleic-acid testing and geographic sourcing documentation for all animal-derived bile acid imports. This regulatory friction accelerates domestic substitution toward fermentation-based manufacturers with backward-integrated feedstock control. Imported solvent-extracted product faces extended customs clearance and enhanced inspection protocols.
Specialty pharmaceutical buyers now consolidate procurement through qualified CDMO platforms rather than catalog distributors. Sigma-Aldrich's research-grade dominance faces pressure from direct manufacturer relationships as API buyers seek volume commitments and regulatory file support. This channel consolidation concentrates in North American and European markets where orphan-drug developers require GMP-compliant supply with documented DMF availability.
Cholic Acid Market Segmentation
Cholic acid procurement patterns diverge sharply across purity grades and end-use specifications. Pharmaceutical buyers impose cycle-time pressures that reshape inventory velocity for each segment category.
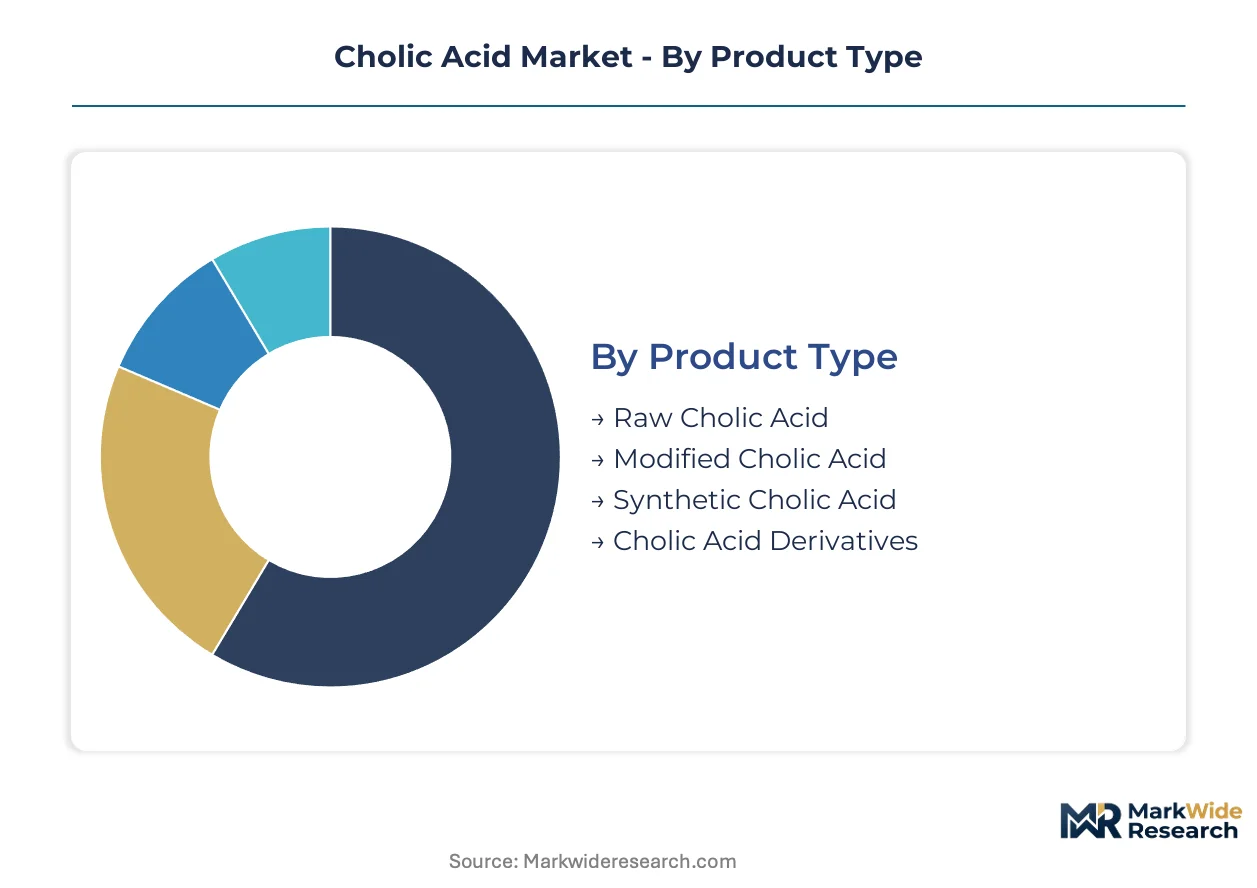
Product Type:
Raw material conversion cycles vary from weeks for extraction-based grades to months for synthetic qualification, creating distinct working capital profiles across the four product categories.
- Raw Cholic Acid:Solvent-extracted from bovine or ovine bile with pharmacopeial-grade purification. Jiangsu province manufacturers dominate supply to legacy formulation houses in India and Brazil facing BSE documentation hurdles.
- Modified Cholic Acid:Chemically altered at the C-24 carboxyl position or steroid nucleus to enhance bioavailability or targeting. Specialty API buyers in orphan-drug development concentrate procurement here for gallstone dissolution and metabolic disorder therapies.
- Synthetic Cholic Acid:Engineered through microbial fermentation or enzymatic cascades eliminating animal-derived inputs. Zhejiang fermentation clusters scale this segment fastest as NMPA impurity-profile tightening accelerates domestic substitution.
- Cholic Acid Derivatives:Conjugated forms including glycocholic and taurocholic acids for specific therapeutic applications. CDMO platforms in North America and Europe qualify these for controlled-substance synthesis partnerships.
Raw Cholic Acid dominates installed base. Synthetic Cholic Acid is where expansion concentrates.
End User:
Customer sophistication tiers separate specification-heavy pharmaceutical procurement from catalog-driven research purchasing, with margin structures inverting across these boundaries.
- Pharmaceutical Companies:GMP-certified manufacturers of rare liver disease therapies and gallstone treatments. These buyers demand DMF-supported supply chains with validated analytical methods for three-alpha-hydroxyl configuration verification.
- Dietary Supplement Manufacturers:Formulators of liver support and digestive health products with less stringent purity requirements. Cost pressure from private-label competition compresses margins for standard-grade cholic acid.
- Research Institutions:Academic laboratories and biotech discovery groups consuming catalog-grade material. Sigma-Aldrich's e-commerce platform captures volume here through rapid fulfillment and certificate-of-analysis documentation.
- Chemical Industries:Specialty surfactant and emulsifier producers leveraging cholic acid's detergent properties. Applications in chromatography media and nanoparticle synthesis drive specification customization.
Pharmaceutical Companies anchor premium pricing. Research Institutions are gaining transaction volume fastest.
Application:
Regulatory pathway intensity separates clinical-grade applications from commercial nutraceutical deployment, with qualification timelines stretching from months to years.
- Drug Formulations:Finished dosage forms for cholestatic liver diseases and bile acid synthesis disorders. FDA orphan-drug designations concentrate demand for high-purity APIs with ICH Q3D elemental impurity compliance.
- Nutraceuticals:Over-the-counter supplements marketed for digestive health and metabolic support. Stability requirements favor powder and capsule forms with simpler cold-chain profiles.
- Scientific Research:Cell culture reagents and biochemical assay components. Catalog distributors compete on lot-to-lot consistency and rapid international shipping.
- Clinical Trials:Investigational new drug applications requiring GMP material with extensive characterization data. CDMO partnerships secure long-term supply agreements through regulatory file support.
Drug Formulations command highest unit economics. Clinical Trials are expanding most quickly.
Form:
Stability engineering and packaging requirements create cost tier separation, with liquid formulations demanding disproportionate distribution infrastructure investment.
- Oral Tablets:Compressed dosage forms with defined dissolution profiles for immediate or modified release. European and North American markets favor this form for patient compliance in chronic therapy regimens.
- Capsules:Gelatin or HPMC shells protecting hygroscopic powder from moisture degradation. Dietary supplement manufacturers prefer capsules for formulation flexibility and consumer acceptance.
- Powder:Bulk active pharmaceutical ingredient for downstream processing or compounding. Fermentation-based Chinese producers ship powder to global formulation sites for final dosage manufacturing.
- Liquid Solutions:Aqueous or solvent-based preparations for parenteral or topical applications. Cold-chain validation requirements limit this form to specialized pharmaceutical applications with premium pricing.
Powder dominates volume throughput. Liquid Solutions concentrate where formulation complexity justifies infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Brazil exhibit acute price sensitivity for standard-grade material, while orphan-drug developers in Switzerland and the United States absorb premium pricing for GMP-certified supply with full regulatory file support.
United States
FDA orphan-drug designations for cholestatic liver disease therapies concentrate procurement among specialty API buyers. The agency enforces ICH Q3D elemental impurity guidelines through USP monograph compliance. Greater Boston hosts formulation houses qualifying synthetic cholic acid for clinical-grade supply.
China
NMPA impurity-profile tightening for imported bile acids accelerates domestic substitution toward fermentation-based output. The regulator mandates batch-level nucleic-acid testing and geographic sourcing documentation. Jiangsu and Zhejiang province clusters scale microbial synthesis platforms with captive feedstock integration.
Germany
EMA REACH traceability mandates and EU MDR liability rules compel documented supply chain verification for bile-acid derivatives. The country's national pharmaceutical regulator enforces extended liability across derivative supply chains. Bavaria-based CDMO platforms qualify synthetic routes for controlled-substance partnerships.
India
CDSCO registration requirements for imported APIs create procurement friction for extraction-dependent supply. The national regulator applies phased manufacturing compliance programs for domestic API producers. Maharashtra formulation houses requalify suppliers amid BSE documentation hurdles for bovine-derived material.
Switzerland
Swissmedic enforces stringent pharmacopeial standards for high-purity APIs used in metabolic disorder therapies. The regulator applies advanced therapy medicinal product frameworks for innovative bile-acid formulations. Basel-region headquarters anchor procurement decisions for global orphan-drug portfolios.
Cholic Acid Market Vendor Landscape
Catalog distributors and fermentation-based manufacturers split the market along purity-grade lines. The vendor base concentrates around three strategic archetypes: research-grade chemical suppliers with e-commerce platforms, captive-fermentation specialists with backward-integrated feedstock control, and CDMO platforms extending into controlled-substance synthesis. Competitive moves center on regulatory file support capabilities and synthetic biology pathway qualification.
Within the research-grade tier, Sigma-Aldrich occupies a position exemplifying catalog breadth dominance across North American and European laboratory markets. Zhongshan Belling Biotechnology represents the captive-fermentation archetype with Zhejiang province manufacturing concentration. Pfizer CentreOne sits within the CDMO platform category, anchoring controlled-substance and bile-acid derivative synthesis partnerships.
| Leading Market Players |
|---|
| Avanti Polar Lipids |
| Cayman Chemical |
| Toronto Research Chemicals |
| Sigma-Aldrich |
| Pfizer CentreOne |
| Dr Falk Pharma |
| Bruschettini |
| Zhongshan Belling Biotechnology |
| ICE Pharma |
| Others |
Supply Flow & Price Mechanics
BSE-related import restrictions determine both pricing tier spreads and supply chain shape by forcing buyers toward fermentation-based alternatives with validated impurity profiles. Pharmaceutical-grade material commands substantial premiums over research-grade supply as NMPA documentation requirements and ICH Q3D compliance costs concentrate procurement among qualified manufacturers.
Pricing Analysis
After-sales regulatory file support and DMF availability drive lifetime value for CDMO partnerships. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified pharmaceutical supply from catalog research grades and raw extraction material. Cost compression in standard-grade segments intensifies because Indian and Brazilian formulation houses exert acute price pressure on bovine-derived imports. Dietary supplement manufacturers exhibit highest price sensitivity, while orphan-drug developers in Switzerland absorb premium positioning for documented supply chains.
Supply Chain Analysis
Bile raw material availability and cholesterol feedstock quality anchor upstream dependencies for extraction-based producers. Supply concentrates in China, India, and Germany, with Jiangsu and Zhejiang fermentation clusters displacing traditional bovine bile sourcing. Solvent extraction equipment, chromatographic purification resins, and validated cold-chain infrastructure constitute critical input categories. Single-source vulnerability runs through China's NMPA-certified fermentation capacity as geographic sourcing documentation requirements tighten. Distribution runs through qualified CDMO platforms for pharmaceutical buyers and direct e-commerce channels for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as regulatory divergence between pharmacopeial and biosynthetic qualification pathways creates distinct supply niches for fermentation specialists, CDMO platforms, and research-grade distributors.
For Market Incumbents: Build regulatory file support moats by securing simultaneous USP monograph and NMPA registration capabilities. Defend against synthetic biology entrants by extending captive fermentation capacity in Zhejiang with backward-integrated cholesterol feedstock control. Channel consolidation among orphan-drug developers threatens catalog distributors; counter through exclusive volume commitments with documented DMF availability.
For New Entrants and Emerging Players: Pursue underpenetrated Indian CDMO capacity as Chinese supply faces enhanced NMPA scrutiny. Target research-grade direct-to-laboratory e-commerce with rapid international fulfillment and lot-to-lot consistency guarantees. Synthetic biology pathway qualification offers the most penetrable entry angle for pharmaceutical-grade supply independent of animal agriculture.
For Investors and Strategic Acquirers: NMPA impurity-profile tightening reshapes the acquisition landscape toward fermentation-based manufacturers with pharmacopeial purity capabilities. Long-term viability centers on platforms capable of serving both orphan-drug developers and controlled-substance synthesis partnerships. Signal to monitor: batch-level nucleic-acid testing mandates spreading beyond China to other import jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory File Support Expansion | DMF-backed supply chains secure orphan-drug procurement from FDA-designated developers. |
| Fermentation Capacity Scale-Up | Zhejiang province clusters achieve pharmacopeial purity without BSE documentation burdens. |
| Synthetic Biology Pathway Qualification | Engineered yeast strains eliminate animal-derived input dependency for clinical-grade material. |
| Direct-to-Laboratory E-Commerce | Bypass traditional distributor markups for catalog chemical buyers in academic segments. |
| Indian CDMO Geographic Expansion | Alternative production geography mitigates NMPA scrutiny concentration on Chinese supply. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of FDA filings, NMPA registration databases, USP monograph updates, and trade customs records. Primary interviews engaged fermentation process engineers, API procurement managers at specialty pharmaceutical houses, regulatory affairs directors navigating dual certification timelines, and CDMO business development leads. Bottom-up capacity assessments of Jiangsu and Zhejiang manufacturing clusters triangulate against top-down demand modeling from orphan-drug pipelines and clinical trial registrations.
Forecast inputs include treatment line segmentation across cholestatic liver diseases and metabolic disorders, dosage form differentiation between powder and liquid formulations, and regional regulatory cluster divergence between FDA, EMA, and NMPA jurisdictions. CAGRs derive from volume-weighted averaging across these dimensions. Industry-specific inputs incorporate BSE-related trade barrier propagation timelines and fermentation technology maturation curves for synthetic cholic acid cost parity.
Sensitivities concentrate around NMPA documentation requirement expansion, ICH Q3D guideline enforcement intensity, and synthetic biology pathway regulatory acceptance timelines. Forecasts reflect assumptions about continued orphan-drug designation momentum and stable cholesterol feedstock pricing. Quarterly review of import clearance durations, batch rejection rates at Chinese customs, and CDMO qualification announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Egypt Food Colorants Market
Flavorings and Food Additives
Sour Flavor Ingredient Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
Carvone Market
Flavorings and Food Additives
Beverage Flavoring Market
Flavorings and Food Additives
Natural Food Colors Market
Flavorings and Food Additives
Quillaia Extracts Market
Flavorings and Food Additives
Flavanones Market
Flavorings and Food Additives
Flavor Modulators Market
Flavorings and Food Additives
Valencene Market
Flavorings and Food Additives
Seaweed Flavor Market
Flavorings and Food Additives
South America Food Flavor Market
Flavorings and Food Additives
Global Artichoke Extract Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Rose Water Market