
 Carotenoids Pigment Market | 2026-2036
Carotenoids Pigment Market Size, Share, and Industry Trends Forecast 2026-2036
Carotenoids Pigment Market Outlook
Capital-intensity divergence between fermentation-based astaxanthin producers and synthetic beta-carotene manufacturers is unwinding competitive stability in the carotenoids pigment sector. BASF SE leverages its petrochemical feedstock integration to sustain cost leadership in synthetic carotenoid output. DSM anchors its position through microbial fermentation platforms that supply algal-derived astaxanthin to dietary supplement end users. Kemin Industries specializes in lutein extraction from marigold oleoresin, occupying a differentiated niche in eye-health formulations.
Carotenoids pigments comprise lipid-soluble polyene compounds—beta-carotene, lutein, zeaxanthin, and astaxanthin—synthesized via either chemical routes or biological extraction from plants, algae, and microorganisms, with conjugated double-bond systems conferring antioxidant activity and coloration from yellow to deep red. These pigments serve primarily as colorants, nutritional fortifiers, and oxidative-stability agents across food matrices, animal nutrition, and topical applications. Astaxanthin commands premium positioning within the product type architecture due to its superior singlet-oxygen quenching capacity and restricted supply from Haematococcus pluvialis cultivation. The food and beverage application segment dominates volume throughput, while pharmaceutical-grade carotenoids concentrate margin pools where USP and EP monograph compliance filters supplier eligibility.
FDA color additive regulations under 21 CFR 73 and EFSA food additive re-evaluations are reshaping permissible sources and purity thresholds for carotenoid colorants in ingestible products. REACH registration requirements and EU Green Deal sustainable sourcing mandates are compelling natural extraction pathway investments over petrochemical synthesis. Stakeholders must monitor regulatory divergence between FDA notification pathways and EU novel food determinations, as asynchronous approvals will fragment product launch timelines and inventory allocation across Atlantic markets.
Market Dynamics
Clean-label mandates from FDA and EFSA are compressing synthetic carotenoid margins while fermentation-derived alternatives capture formulation slots in dietary supplements and functional foods.
Growth Catalysts
- EFSA Novel Food determinations:Streamlined approvals for algal astaxanthin are accelerating European dietary supplement launches and displacing synthetic alternatives in premium positioning.
- Direct-to-consumer nutraceutical channels:E-commerce platforms are collapsing traditional distribution layers and enabling smaller extraction specialists to reach eye-health formulators without broker intermediation.
- Haematococcus pluvialis cultivation:Closed photobioreactor systems are improving astaxanthin yield consistency and reducing batch-to-batch variation that previously constrained pharmaceutical-grade supply.
Market Restraints
- Petrochemical feedstock volatility:Synthetic beta-carotene producers face margin compression when naphtha and benzene prices spike, eroding cost advantage over biological routes.
- Marigold oleoresin supply concentration:Lutein extraction depends on Indian and Mexican flower cultivation, exposing processors to monsoon variability and agricultural commodity cycles.
- 21 CFR 73 color additive petitions:FDA notification timelines for new carotenoid sources extend 18-24 months, freezing product development pipelines for innovative extraction methods.
Strategic Opportunities
- Personalized nutrition platforms:Genotyping services are creating demand for lutein-zeaxanthin combinations tailored to individual macular pigment density profiles.
- EU Green Deal sustainable sourcing mandates:Carbon footprint disclosure requirements favor fermentation-based production over petrochemical synthesis in public procurement.
- Cosmeceutical topical delivery:Liposomal encapsulation technologies are opening dermal antioxidant applications where astaxanthin commands premium positioning over conventional vitamin derivatives.
Industry Challenges
- USP monograph compliance timelines:Pharmaceutical-grade certification requires 12-18 months of analytical validation, delaying revenue recognition for new extraction facilities.
- Photobioreactor scale-up engineering:Translating laboratory Haematococcus productivity to industrial 50,000-liter systems demands specialized bioprocess talent scarce outside academic marine biology programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carotenoids Pigment Market |
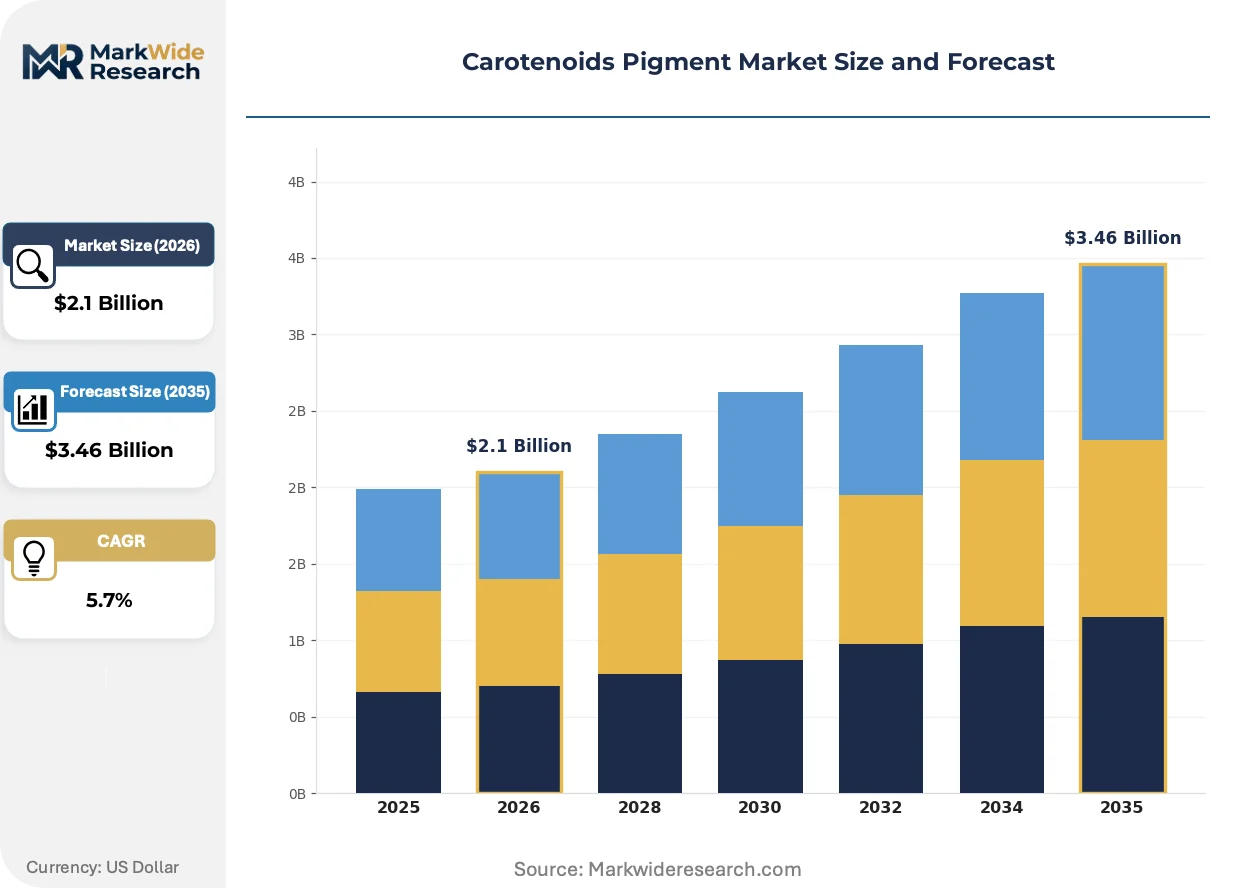
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.46 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lutein, Beta-Carotene, Astaxanthin, Zeaxanthin Application: Food & Beverage, Animal Feed, Cosmetics, Pharmaceuticals Source: Natural, Synthetic, Plant-based, Algal End User: Food Manufacturers, Dietary Supplements, Cosmetic Companies, Pharmaceutical Firms |
| Companies Covered | BASF SE, DSM, Kemin Industries, Chr. Hansen Holdings A/S, Allied Biotech Corporation, Döhler GmbH, Cyanotech Corporation, Givaudan, Lycored, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carotenoids Pigment Market Strategic Shifts
Fermentation technology advances and regulatory disclosure requirements are compressing synthetic carotenoid dominance while enabling biological production platforms to capture premium market tiers.
Precision fermentation platforms using engineered Yarrowia lipolytica strains are miniaturizing production footprints for beta-carotene and lycopene, enabling distributed manufacturing closer to formulation sites. Dietary supplement contract manufacturers in the United States are adopting these systems to reduce working capital tied to imported synthetic inventory. The technology is miniaturizing minimum efficient scale thresholds and fragmenting supply concentration away from petrochemical-integrated majors.
REACH registration requirements for imported carotenoid colorants are tightening purity documentation and supply chain traceability obligations on European formulators. ECHA substance evaluation workflows now demand full life-cycle carbon data for natural extraction versus synthetic routes. Food and beverage manufacturers in Germany and France are responding by qualifying dual-source suppliers and accelerating internal carbon accounting capabilities.
Subscription-based supplement models are compressing traditional retail replenishment cycles and shifting volume forecasting risk onto carotenoid suppliers. Direct-to-consumer brands in California and New York are demanding quarterly price locks and volume flexibility clauses that legacy distributors cannot accommodate. This channel rotation is most visible in astaxanthin and lutein SKUs targeting eye-health cohorts aged 45-65.
Carotenoids Pigment Market Segmentation
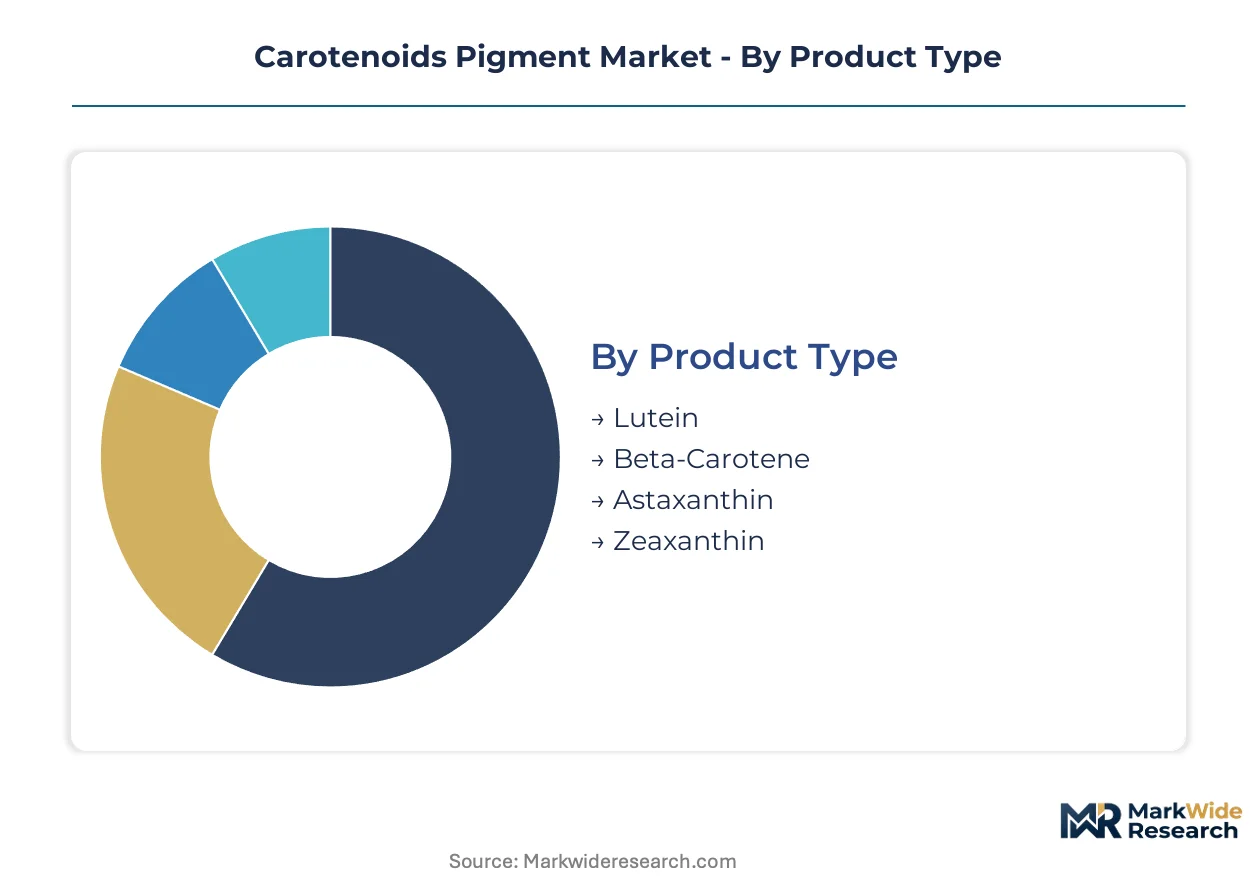
Carotenoid procurement decisions hinge on regulatory status, production method, and end-use purity requirements. Formulators segment sourcing strategies across colorant, nutritional, and pharmaceutical specifications where compliance thresholds diverge sharply.
Product Type:
FDA 21 CFR 73 color additive listings and EFSA food additive re-evaluations create divergent approval statuses that determine which carotenoids enter specific formulation channels.
- Astaxanthin:Haematococcus pluvialis-derived astaxanthin carries EFSA novel food authorization and FDA GRAS status for dietary supplements. Pharmaceutical-grade demand concentrates in Japan and the United States where USP monograph compliance filters supplier eligibility. Premium positioning reflects restricted supply from closed photobioreactor cultivation and superior singlet-oxygen quenching capacity.
- Lutein:Marigold oleoresin extraction yields lutein esters standardized for eye-health formulations. Indian and Mexican flower cultivation exposes processors to agricultural commodity cycles and monsoon variability. Dietary supplement contract manufacturers in California and New York specify lutein-zeaxanthin ratios for macular health SKUs targeting consumers aged 45-65.
- Beta-Carotene:Synthetic petrochemical routes dominate food colorant applications; fermentation alternatives gain traction in clean-label positioning.
- Zeaxanthin:Co-extracted with lutein from marigold or produced via microbial fermentation for precise isomeric purity in ocular supplements.
Established volume favors beta-carotene; emerging adoption favors astaxanthin.
Application:
Margin concentration follows purity tier escalation from colorant to pharmaceutical grades, with certification requirements acting as supplier filters.
- Food & Beverage:Volume throughput concentrates here. Beta-carotene and annatto serve beverage fortification and dairy coloration where FDA 21 CFR 73.95 and 21 CFR 73.300 govern permissible use levels. Clean-label momentum in Germany and France accelerates natural extraction sourcing over synthetic alternatives.
- Pharmaceuticals:USP and EP monograph compliance creates the steepest margin tier. Astaxanthin and lutein command premium positioning for oxidative-stability applications and ocular health formulations. Certification requires 12-18 months of analytical validation, delaying revenue recognition for new extraction facilities.
- Animal Feed:Poultry and aquaculture sectors drive astaxanthin demand for flesh pigmentation and egg yolk coloration.
- Cosmetics:Liposomal encapsulation technologies open dermal antioxidant applications where astaxanthin displaces conventional vitamin derivatives.
Food and beverage anchors volume; pharmaceuticals capture margin.
Source:
Carbon footprint disclosure requirements under EU Green Deal mandates favor biological production pathways in European public procurement.
- Algal:Haematococcus pluvialis cultivation in closed photobioreactor systems supplies pharmaceutical-grade astaxanthin. Closed systems improve yield consistency and reduce batch-to-batch variation. DSM and specialized fermentation houses dominate this supply tier.
- Synthetic:Petrochemical feedstock integration sustains cost leadership in beta-carotene. BASF SE leverages naphtha and benzene derivatives for food-grade colorant production. Margin compression occurs during feedstock price spikes.
- Natural:Marigold oleoresin and palm oil derivatives serve markets where clean-label positioning outweighs cost sensitivity.
- Plant-based:Tomato and carrot extraction supplies lycopene and beta-carotene for organic-certified formulations.
Algal sourcing expands most quickly; synthetic retains cost advantage.
End User:
Channel structure determines procurement flexibility, with direct-to-consumer brands demanding terms legacy distributors cannot accommodate.
- Dietary Supplements:E-commerce platforms collapse traditional distribution layers. Subscription-based models compress replenishment cycles and shift volume forecasting risk onto suppliers. Quarterly price locks and volume flexibility clauses characterize California and New York brand procurement.
- Pharmaceutical Firms:USP monograph compliance and FDA New Dietary Ingredient notification pathways govern procurement. Validation timelines extend 18-24 months for novel extraction methods.
- Food Manufacturers:REACH registration requirements and EFSA re-evaluations tighten purity documentation and supply chain traceability obligations.
- Cosmetic Companies:Formulators seek liposomal and nano-encapsulation technologies for dermal delivery systems.
Dietary supplements drive channel innovation; pharmaceutical firms enforce compliance rigor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in India and Mexico exhibit acute price sensitivity to agricultural commodity swings, while pharmaceutical-grade purchasers in the United States and Japan absorb premium pricing for USP-monograph compliance. This demand-elasticity divergence shapes regional procurement strategies and supplier qualification timelines.
United States
Dietary supplement contract manufacturers in California and New York drive astaxanthin and lutein procurement for eye-health SKUs targeting consumers aged 45-65. FDA 21 CFR 73 color additive petitions govern new source approvals, extending notification timelines 18-24 months. Direct-to-consumer nutraceutical channels in Los Angeles and Brooklyn collapse traditional distribution layers, enabling smaller extraction specialists to reach formulators without broker intermediation.
Germany
Food and beverage manufacturers accelerate natural extraction sourcing over synthetic alternatives under clean-label momentum. REACH registration requirements and EFSA food additive re-evaluations tighten purity documentation and supply chain traceability obligations. Industrial clusters in Bavaria and North Rhine-Westphalia host formulation facilities qualifying dual-source suppliers to meet EU Green Deal carbon footprint disclosure mandates.
India
Marigold oleoresin cultivation concentrates in Karnataka and Andhra Pradesh, exposing lutein processors to monsoon variability and agricultural commodity cycles. FSSAI food safety standards govern colorant permissible limits in ingestible products. Extraction facilities in Hyderabad and Bengaluru face working capital pressure from flower price volatility that synthetic beta-carotene competitors avoid.
Japan
Pharmaceutical-grade astaxanthin demand concentrates here, where USP monograph compliance filters supplier eligibility for oxidative-stability applications. METI industrial standards and PMDA pharmaceutical regulations enforce stringent purity thresholds. Bioprocess engineering talent from academic marine biology programs in Tokyo and Osaka supports closed photobioreactor scale-up for Haematococcus pluvialis cultivation.
Brazil
Poultry and aquaculture sectors drive astaxanthin demand for flesh pigmentation and egg yolk coloration. ANVISA food additive regulations govern permissible carotenoid sources in animal nutrition. Processing facilities in São Paulo and Paraná import algal-derived astaxanthin amid limited domestic fermentation capacity, exposing feed compounders to currency fluctuation risks.
Carotenoids Pigment Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with petrochemical-integrated majors and microbial fermentation platforms occupying distinct vertical positions. The upper tier sustains cost leadership through feedstock integration or proprietary cultivation technology. Three archetypes define competitive positioning: synthetic chemistry majors leveraging naphtha derivatives, algal biotechnology specialists controlling closed photobioreactor supply, and botanical extraction houses anchored to agricultural supply contracts. Dominant competitive moves include backward integration into fermentation capacity and geographic expansion through distributor partnerships.
Within the petrochemical-integrated tier, BASF SE exemplifies cost leadership through synthetic beta-carotene production. DSM occupies a position in microbial fermentation platforms supplying algal-derived astaxanthin. Kemin Industries represents the botanical extraction archetype through marigold oleoresin specialization for eye-health formulations. These three anchors illustrate how production method selection determines addressable market tiers and margin profiles.
| Leading Market Players |
|---|
| BASF SE |
| DSM |
| Kemin Industries |
| Chr. Hansen Holdings A/S |
| Allied Biotech Corporation |
| Döhler GmbH |
| Cyanotech Corporation |
| Givaudan |
| Lycored |
| Others |
Value Chain & Pricing Dynamics
Fermentation-derived astaxanthin substitution for synthetic beta-carotene in premium dietary supplements simultaneously shifts supply geography toward algal biotechnology clusters and compresses pricing power among petrochemical-integrated majors. This displacement dynamic reconfigures procurement economics as formulators absorb higher unit costs for clean-label positioning while synthetic producers face margin erosion from feedstock volatility.
Pricing Analysis
After-sales service contracts for USP monograph compliance and analytical validation support drive lifetime value for pharmaceutical-grade suppliers. Three-tier pricing structure across pharmaceutical, nutritional, and colorant grades reflects certification burden and purity thresholds. Pricing pressure stems from REACH registration requirements tightening documentation costs for European formulators. Dietary supplement contract manufacturers exhibit acute price sensitivity, while pharmaceutical firms absorb premiums for oxidative-stability applications.
Supply Chain Analysis
Inventory lead times for marigold oleoresin stretch across agricultural growing seasons, forcing lutein processors to carry working capital exposure through monsoon cycles. Supply concentrates in India, Mexico, and China for botanical extraction, while algal biotechnology clusters in Japan and the Netherlands serve pharmaceutical tiers. Raw material dependencies include Haematococcus pluvialis biomass, marigold flower feedstock, and petrochemical naphtha derivatives. Single-source vulnerability in closed photobioreactor systems threatens batch consistency. Distribution runs through direct-to-consumer nutraceutical channels and specialized ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EFSA novel food streamlining for algal astaxanthin disrupts incumbent synthetic positioning, creating acquisition and capacity investment windows for biological production platforms.
For Market Incumbents: Fortify cost leadership in synthetic beta-carotene through backward integration into naphtha derivatives while accelerating microbial fermentation partnerships to hedge clean-label displacement. BASF SE's petrochemical feedstock integration exemplifies defensive positioning against algal biotechnology encroachment. Certification investment in USP monograph compliance preserves pharmaceutical-tier access. For New Entrants and Emerging Players: Lead with precision fermentation platforms using engineered Yarrowia lipolytica strains to capture distributed manufacturing demand from California and New York dietary supplement contract manufacturers. White-space concentration in personalized nutrition platforms for lutein-zeaxanthin combinations offers penetrable positioning. Go-to-market leverage through subscription-based supplement brands collapses traditional distributor layers. For Investors and Strategic Acquirers: EU Green Deal carbon footprint disclosure mandates reshape the acquisition landscape toward fermentation-based production assets with documented life-cycle data. Five-to-ten year viability favors algal biotechnology specialists controlling closed photobioreactor supply over synthetic chemistry exposure. Acquisition target archetype: mid-cap fermentation houses with USP monograph pathway progress. Signal to monitor: FDA 21 CFR 73 petition approval velocity for novel extraction methods.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Captive Haematococcus pluvialis supply secures pharmaceutical-grade astaxanthin batch consistency for Japanese oxidative-stability formulators. |
| USP Monograph Certification Investment | Analytical validation pathways filter supplier eligibility for premium pharmaceutical-tier margin pools in United States ocular health applications. |
| Direct-to-Consumer Channel Partnership | Subscription-based supplement models in California and New York compress replenishment cycles and shift volume forecasting risk onto suppliers. |
| Precision Fermentation Platform Deployment | Engineered Yarrowia lipolytica strains miniaturize minimum efficient scale thresholds and fragment supply concentration away from petrochemical majors. |
| Dual-Source Supplier Qualification | EU Green Deal carbon disclosure mandates in Germany and France accelerate internal accounting capabilities and reduce single-source exposure. |
Study Parameters
Cross-validation between primary interviews with dietary supplement formulators, pharmaceutical procurement managers, and algal biotechnology engineers and secondary validation through FDA 21 CFR 73 filings, EFSA novel food determinations, and REACH registration databases anchors the qualitative findings. Bottom-up triangulation across extraction facility capacity assessments and top-down demand modeling from end-use consumption patterns ensures coverage integrity.
Sensitivity analysis across grade tier, production method, and regional regulatory cluster informs the analytical framework over the projection horizon. CAGRs derive from segmented volume-to-value conversion using purity-adjusted pricing tiers and channel-specific margin structures. Forecast inputs include Haematococcus pluvialis cultivation yield assumptions and marigold oleoresin price volatility indices.
The analysis sits within stated boundaries; outcomes outside EFSA streamlining velocity or FDA petition approval timelines would require recalibration. Forecasts reflect documented assumptions on regulatory convergence and feedstock price trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Hops Essential Oil Market
Flavorings and Food Additives
Vanilla Oleoresin Market
Flavorings and Food Additives
Tangerine Peel Extract Market
Flavorings and Food Additives
Global Syrup Market
Flavorings and Food Additives
Orange Essential Oil Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Salts and Flavored Salts Market
Flavorings and Food Additives
D-Limonene Market
Flavorings and Food Additives
Global Bitterness Suppressors and Flavor Carriers Market
Flavorings and Food Additives
Apple Essence Market
Flavorings and Food Additives
Smoke Flavorings Market
Flavorings and Food Additives
Global Floral Flavors Market
Flavorings and Food Additives
Naringin Market
Flavorings and Food Additives
Jujube Extracts Market