
 Grapefruit Oil Market | 2026-2036
Grapefruit Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Grapefruit Oil Market Analysis
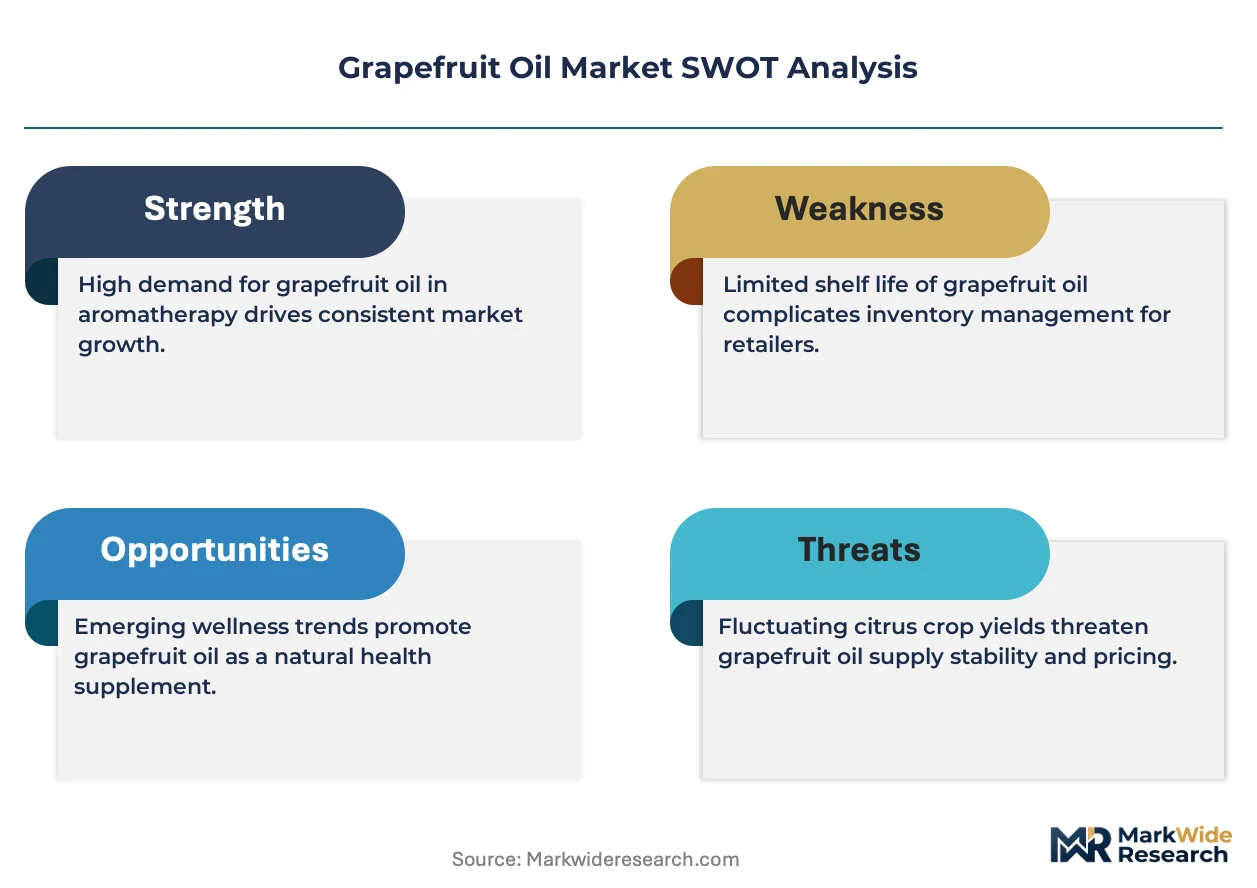
Premium organic certification tiers is collapsing the gap between commodity grapefruit oil and pharmaceutical-grade extracts. Givaudan SA leverages captive citrus sourcing in Florida to sustain supply security for flavor houses. Robertet Group SA anchors its position through proprietary cold-pressing technology that preserves limonene integrity. Citromax competes on scale from its Argentine grapefruit belt operations, while Young Living Essential Oils LC differentiates through direct-to-consumer channel control in the wellness segment.
Grapefruit oil is an essential oil extracted from Citrus paradisi peel, typically containing 90-95% limonene alongside nootkatone and citral, which impart its characteristic bitter-citrus aroma and antimicrobial properties. Cold-pressed grapefruit oil dominates flavor and fragrance applications where terpene profiles must remain intact, while steam-distilled variants serve cleaning product formulations requiring higher volatility. The organic product type segment commands premium positioning in personal care end-user channels, whereas conventional grades still occupy volume leadership through food service and wholesale distribution into beverage manufacturing.
The FDA governs grapefruit oil safety in food and cosmetic applications through GRAS determinations and cosmetic ingredient reviews, while the EPA regulates antimicrobial claims in cleaning products containing citrus terpenes. ECHA's REACH requirements impose full substance dossiers on European importers, creating compliance barriers for smaller exporters from Argentina and Mexico. Stakeholders must monitor how tightening residue limits under evolving EU Green Deal chemical sustainability frameworks reshape sourcing economics across Mediterranean and Latin American supply basins.
Market Dynamics
Cold-pressing technology maturation is compressing extraction yields while EU REACH dossier requirements are forcing importer consolidation. These dual pressures are restructuring competitive economics between Argentine scale operators and Florida-based captive citrus processors.
Growth Catalysts
- Clean-label personal care:California and New York-based cosmetics brands are mandating natural fragrance ingredients. Cold-pressed grapefruit oil satisfies formulation transparency requirements.
- REACH compliance consolidation:ECHA's substance dossier rules favor larger importers with regulatory affairs capacity. Smaller traders are exiting, concentrating volume among compliant handlers.
- Limonene antimicrobial applications:EPA-registered cleaning product manufacturers are expanding terpene-based formulations. Grapefruit oil's 90-95% limonene content matches performance specifications.
Market Restraints
- Argentine supply concentration:Weather volatility in Entre Ríos and Tucumán provinces threatens harvest reliability. Frost events in 2022 demonstrated systemic exposure.
- Synthetic limonene substitution:Petrochemical-derived alternatives from pine feedstocks undercut natural oil pricing in industrial cleaning applications.
- Citrus greening disease:Huanglongbacterium spread in Florida groves reduces peel oil recovery rates. Infected fruit produces lower terpene concentrations.
Strategic Opportunities
- EU Green Deal chemical sustainability frameworks:Evolving residue limit standards favor organic-certified supply chains. Early compliance investments secure preferential market access.
- Direct-to-consumer wellness channels:Subscription aromatherapy platforms bypass traditional wholesale distribution. Young Living's model demonstrates margin capture potential.
- Pharmaceutical-grade extraction:Supercritical CO2 technology enables nootkatone isolation for drug precursor applications. This displaces commodity flavor-grade positioning.
Industry Challenges
- Organic certification timeline compression:USDA NOP and EU 834/2007 conversion periods delay supply expansion. New grove entrants face three-year transition barriers.
- Terpenoid stability expertise scarcity:Formulation chemists with limonene oxidation prevention knowledge command premium compensation. Technical talent gaps constrain R&D velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grapefruit Oil Market |
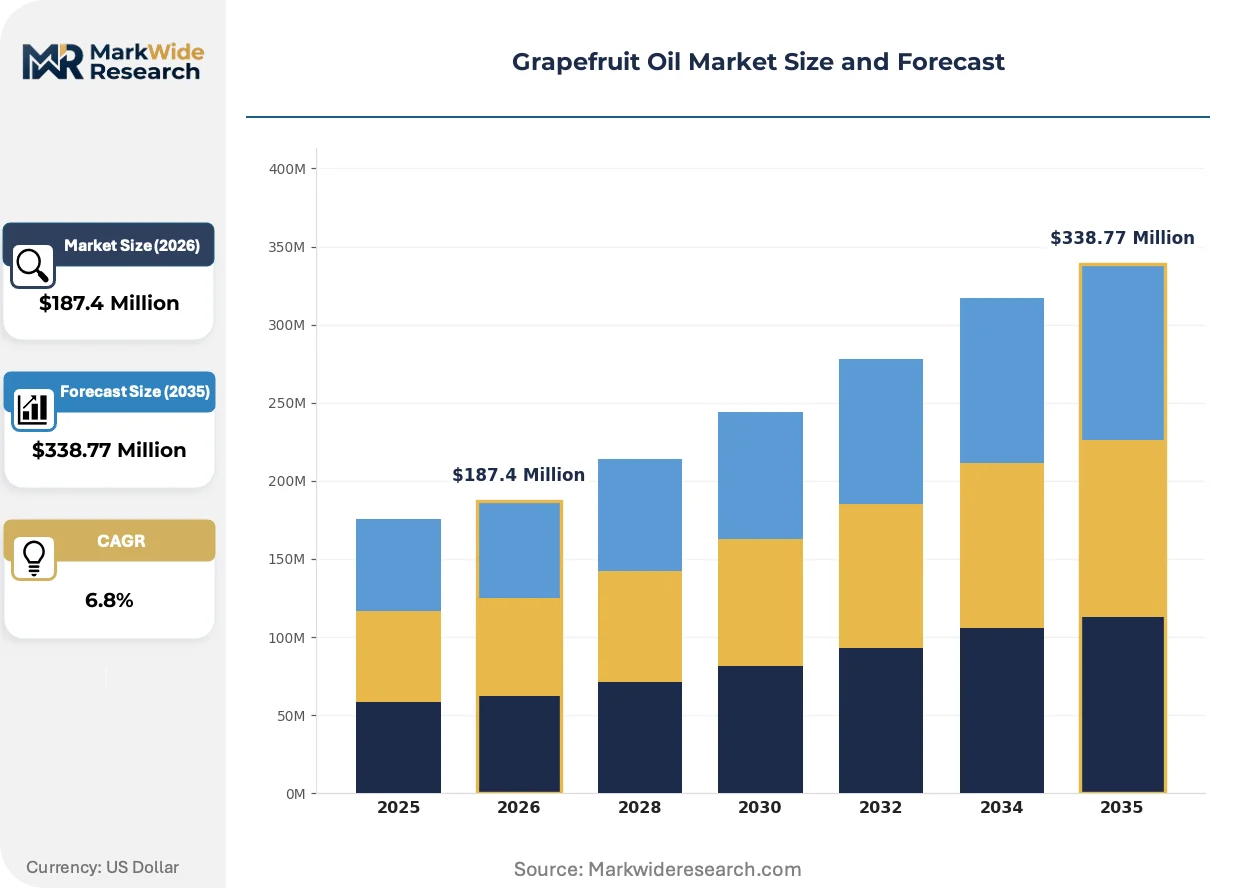
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Pressed, Steam Distilled, Organic, Conventional Application: Aromatherapy, Cosmetics, Cleaning Products, Food & Beverage End User: Retail, Wholesale, Food Service, Personal Care Distribution Channel: Online Stores, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | Givaudan SA, Symrise AG, International Flavors & Fragrances Inc., dsm-Firmenich NV, Robertet Group SA, ADM (Florida Chemical), Citromax, Treatt, Young Living Essential Oils LC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grapefruit Oil Market Emerging Trajectories
Supercritical fluid extraction is disrupting traditional mechanical pressing while regulatory data requirements reshape importer economics. These forces are fragmenting the supplier base between technology-enabled specialists and commodity volume players.
Molecular distillation systems are decomposing the traditional cold-press value chain. Pharmaceutical manufacturers seeking purified nootkatone fractions are adopting this technology rapidly. High-purity extraction is decomposing the historical premium attached to artisanal pressing methods.
ECHA's REACH authorization requirements are tightening substance dossier standards for citrus terpene imports. European flavor houses are consolidating supplier relationships to manage compliance costs. Cold-pressed grapefruit oil shipments into Rotterdam and Hamburg are concentrating among three large importers with dedicated regulatory affairs teams.
Wellness brand procurement teams are shortening supplier qualification cycles from eighteen to six months. Direct sourcing from Argentine cooperatives is displacing traditional US distributor intermediaries. This pattern is most visible among California-based clean-label personal care companies establishing captive supply relationships.
Grapefruit Oil Market Segmentation
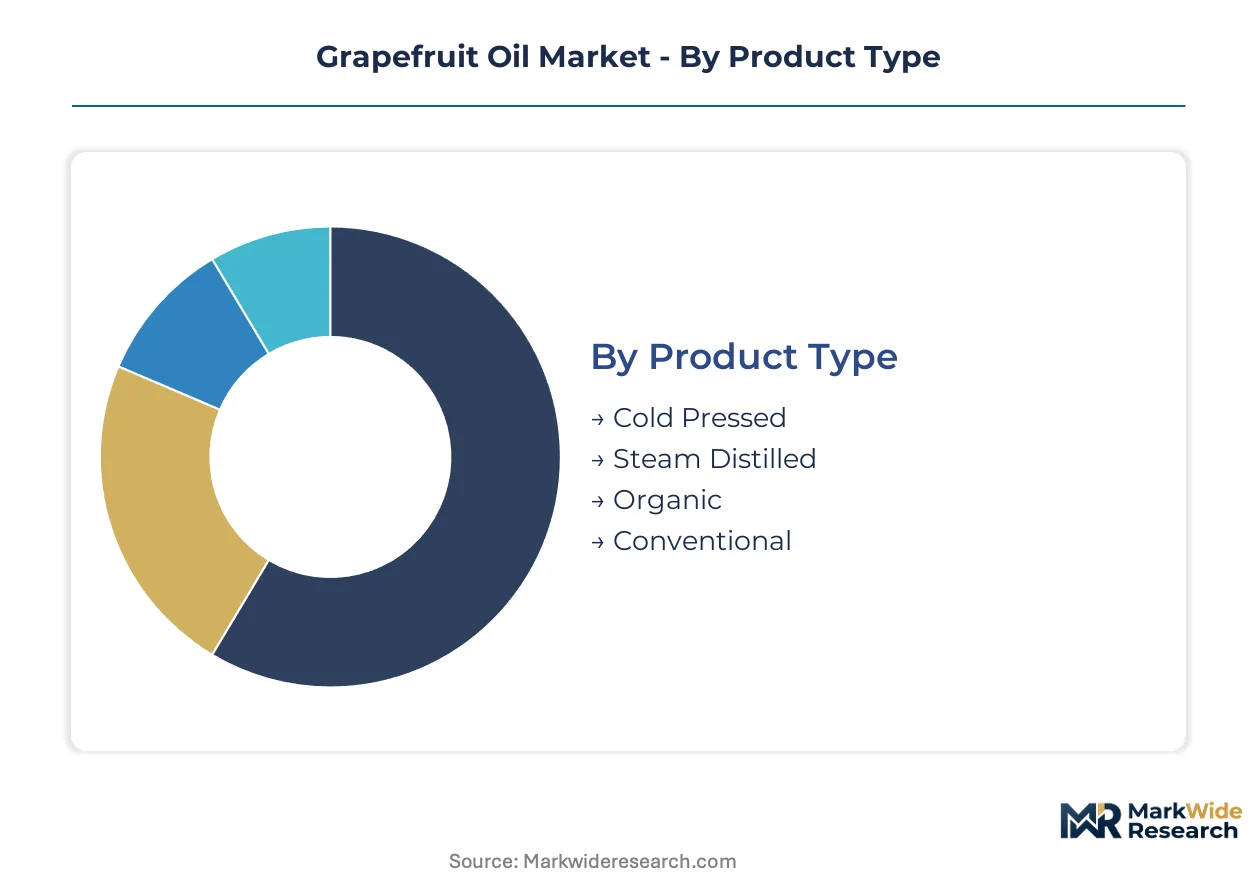
Grapefruit oil segmentation reflects divergent supply chain requirements across extraction methods and purity grades. Personal care manufacturers prioritize cold-pressed terpene integrity while industrial buyers accept steam-distilled volatility. Channel fragmentation between direct-to-consumer wellness platforms and traditional wholesale distribution creates parallel commercial ecosystems.
Product Type:
Domestic consumption patterns favor cold-pressed and organic grades in California and New York personal care clusters, while export-led demand from European flavor houses concentrates on conventional and steam-distilled specifications for regulatory compliance flexibility.
- Cold Pressed:Mechanical extraction at ambient temperatures preserves limonene concentrations of 90-95% alongside nootkatone and citral fractions. California clean-label cosmetics brands mandate this grade for fragrance transparency requirements. Florida captive citrus processors dominate supply security for this segment through Givaudan's integrated groves.
- Steam Distilled:Thermal vapor extraction yields higher volatility suited to EPA-registered cleaning product formulations where rapid evaporation matters. Argentine scale operators from Citromax compete aggressively here on volume economics. European REACH dossier requirements favor larger importers with dedicated regulatory affairs capacity.
- Organic:USDA NOP and EU 834/2007 certification commands premium positioning in direct-to-consumer wellness channels. Three-year grove conversion timelines constrain supply expansion.
- Conventional:Volume leadership persists through food service and wholesale beverage manufacturing where cost sensitivity dominates procurement decisions.
Conventional grades hold the largest share; momentum sits with organic certification tiers.
Application:
Cost tier differentiation separates pharmaceutical-grade extraction investments from commodity flavor and fragrance positioning.
- Aromatherapy:Direct-to-consumer subscription platforms bypass traditional wholesale distribution. Young Living's channel control model demonstrates margin capture potential in this segment.
- Cosmetics:Clean-label personal care brands in New York and California mandate natural fragrance ingredients with full formulation transparency. Cold-pressed grapefruit oil satisfies these procurement specifications.
- Cleaning Products:EPA-registered manufacturers expand terpene-based antimicrobial formulations. Synthetic limonene from pine feedstocks threatens substitution in price-sensitive industrial accounts.
- Food & Beverage:GRAS determinations govern FDA safety oversight. Flavor houses consolidate supplier relationships to manage ECHA REACH compliance costs for European imports.
Cosmetics commands premium pricing; cleaning products expand most quickly on EPA registration tailwinds.
End User:
Customer type fragmentation concentrates procurement expertise among wholesale handlers while retail and direct channels demand supplier qualification acceleration.
- Retail:Wellness brand procurement teams compress supplier qualification cycles from eighteen to six months. Direct sourcing from Argentine cooperatives displaces traditional US distributor intermediaries.
- Wholesale:Rotterdam and Hamburg shipments concentrate among three large importers with dedicated regulatory affairs teams managing ECHA substance dossiers.
- Food Service:Volume leadership through conventional grades where cost sensitivity dominates procurement decisions.
- Personal Care:Clean-label mandates from California and New York-based brands drive cold-pressed grade specification.
Wholesale holds the largest share; personal care gains share fastest on clean-label procurement mandates.
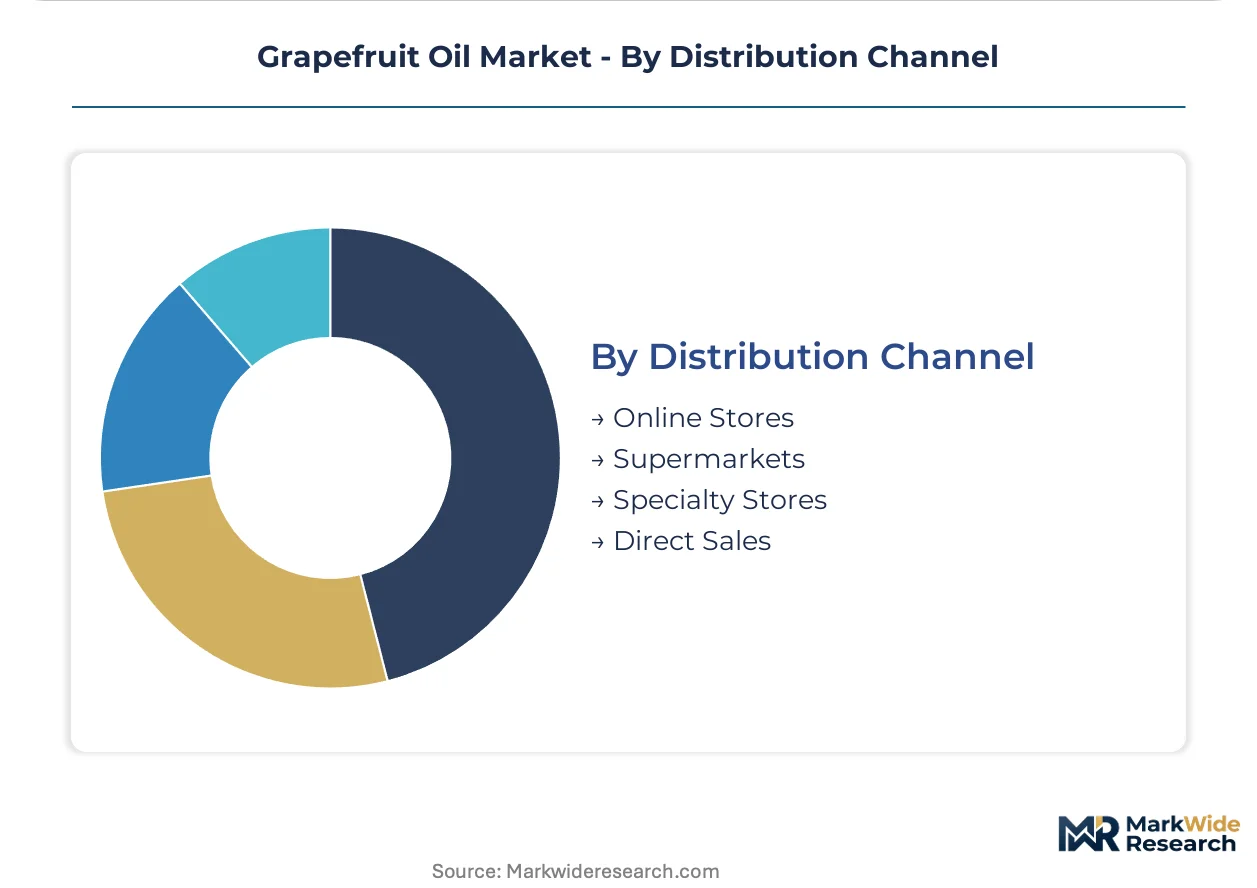
Distribution Channel:
Supply concentration favors direct sales relationships for compliant handlers while online platforms fragment traditional wholesale economics.
- Online Stores:Subscription aromatherapy platforms bypass traditional wholesale distribution. Young Living's direct-to-consumer model demonstrates margin capture potential.
- Supermarkets:Mass-market personal care placement requires conventional grade volume economics.
- Specialty Stores:Premium organic certification tiers command shelf space differentiation in curated retail environments.
- Direct Sales:Captive supply relationships between California clean-label brands and Argentine cooperatives shorten intermediation.
Direct sales holds the largest share; online stores climb the fastest on subscription platform expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor Argentine scale operators supplying North American and European flavor houses, while domestic consumption clusters concentrate in coastal personal care manufacturing hubs. Trade flows respond to divergent regulatory stringency between FDA GRAS determinations and ECHA REACH dossier requirements.
United States
California clean-label cosmetics brands and New York personal care manufacturers drive cold-pressed grade procurement. FDA GRAS determinations govern food and cosmetic applications, while EPA registration requirements shape antimicrobial cleaning product formulations. Florida's integrated citrus processors anchor captive supply security for domestic flavor houses.
Argentina
Entre Ríos and Tucumán provinces generate volume leadership through scale-oriented conventional grade production. The national agricultural export framework supports citrus derivative shipments to Rotterdam and Hamburg. Frost volatility in 2022 demonstrated systemic weather exposure for international buyers.
Germany
Flavor houses in Hamburg concentrate European import handling for REACH-compliant substance dossiers. ECHA authorization requirements favor larger importers with dedicated regulatory affairs capacity. The EU Green Deal chemical sustainability frameworks reshape residue limit standards for incoming citrus terpenes.
France
Grasse-based fragrance compounders source cold-pressed grades for fine fragrance applications. ANSM cosmetic ingredient oversight aligns with EU 834/2007 organic certification recognition. Proprietary extraction technology specialists preserve limonene integrity for high-end personal care formulations.
United Kingdom
London-headquartered wellness brands accelerate direct-to-consumer subscription platform expansion. Post-Brexit regulatory divergence from EU REACH creates parallel compliance pathways for citrus oil importers. Specialty retail channels in the Southeast command premium organic certification tier placement.
Grapefruit Oil Market Vendor Landscape
Listed leaders compete with private specialists across technology and channel dimensions. The supplier base fragments between integrated flavor houses with captive citrus sourcing and independent extractors competing on scale or certification tiers. Three archetypes dominate: Florida-based captive processors, Argentine scale operators, and direct-to-consumer wellness platforms. Consolidation pressures emanate from REACH compliance costs and cold-pressing technology maturation.
Among Switzerland-listed flavor houses, Givaudan SA and Firmenich anchor integrated supply positions through captive Florida groves. Robertet Group SA exemplifies technology-driven differentiation through proprietary extraction methods. Young Living Essential Oils LC occupies the direct-to-consumer archetype with subscription platform control. These three represent distinct competitive vectors: upstream integration, process specialization, and channel disintermediation.
| Leading Market Players |
|---|
| Givaudan SA |
| Symrise AG |
| International Flavors & Fragrances Inc. |
| dsm-Firmenich NV |
| Robertet Group SA |
| ADM (Florida Chemical) |
| Citromax |
| Treatt |
| Young Living Essential Oils LC |
| Others |
Supply Flow & Price Mechanics
EU REACH substance dossier requirements gate both supplier qualification and price differentiation simultaneously, compressing margins for non-compliant traders while enabling compliant handlers to command extraction premiums across Rotterdam and Hamburg import channels.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium organic, standard cold-pressed, and economy steam-distilled levels. Price differentiation rests on certification grade and volume scale, with USDA NOP and EU 834/2007 tiers commanding substantial extraction premiums. Pricing pressure stems from synthetic limonene substitution in industrial cleaning applications, where petrochemical alternatives undercut natural oil economics. Food service procurement teams exhibit highest price sensitivity, while pharmaceutical-grade extract buyers demonstrate lowest elasticity.
Supply Chain Analysis
Port congestion on the Buenos Aires-Rotterdam trade lane elevates inbound logistics costs for Argentine citrus derivatives. Geographic supply concentrates in Argentina, Florida, and California, with Entre Ríos province generating volume leadership. Raw material dependencies center on fresh grapefruit peel, extraction solvents, and organic certification inputs. Single-source vulnerability runs through Argentine weather exposure, demonstrated by frost events in 2022. Distribution runs through three large Rotterdam and Hamburg importers with dedicated regulatory affairs capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Synthetic limonene from pine feedstocks threatens substitution across industrial cleaning applications, forcing incumbents to defend natural oil positioning through certification differentiation and channel control.
For Market Incumbents: Shield organic certification tiers through accelerated USDA NOP and EU 834/2007 grove conversion investments. Deepen upstream control over Florida captive citrus assets to secure supply security against Argentine weather volatility. Prioritize terpenoid stability R&D to preserve limonene integrity against oxidation degradation. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription platforms targeting California and New York clean-label personal care clusters. The personal care end-user channel offers lowest penetration barriers given compressed supplier qualification cycles. Pursue captive supply relationships with Argentine cooperatives to bypass established US distributor intermediaries. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across supercritical CO2 extraction infrastructure for pharmaceutical-grade nootkatone isolation. Long-term viability favors technology-enabled specialists over commodity volume players across the projection horizon. Target acquisition archetypes include proprietary cold-pressing technology holders and REACH-compliant European import handlers. Monitor EU Green Deal residue limit evolution as inflection signal for organic supply chain preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Florida Citrus Groves | Givaudan's captive sourcing secures supply security against Argentine frost volatility. |
| Supercritical CO2 Extraction Capacity Buildout | Robertet's pharmaceutical-grade nootkatone isolation displaces commodity flavor positioning. |
| REACH Compliance Certification Investment | European flavor houses consolidate volume among three Rotterdam and Hamburg importers. |
| Direct-to-Consumer Channel Launch | Young Living's subscription platform demonstrates margin capture in wellness segments. |
| Organic Grove Conversion Program | USDA NOP three-year timelines constrain supply expansion for premium tier capture. |
Methodological Framework
Operator-level perspectives from extraction plant managers, procurement leads at flavor houses, regulatory affairs directors, and wellness brand supply chain heads anchored the qualitative base. Secondary validation drew from ECHA substance dossier filings, FDA GRAS determinations, USDA NOP certification records, and Argentine agricultural export statistics. Bottom-up volume modeling and top-down market sizing triangulated across extraction method, certification tier, and end-use application dimensions.
Sensitivity analysis tested forecast robustness across Argentine weather volatility scenarios and synthetic limonene substitution rates throughout the projection horizon. The analytical framework modeled segmentation across extraction technology, organic versus conventional grade, personal care versus industrial application, and regional regulatory cluster. CAGRs derived from trend extrapolation of clean-label procurement mandates and EPA antimicrobial registration expansion. Industry-specific inputs included citrus greening disease progression in Florida groves and EU Green Deal residue limit evolution.
The analysis sits within stated boundaries; outcomes outside sustained clean-label procurement growth or REACH compliance cost trajectories would require recalibration. Forecasts reflect assumptions around organic certification adoption rates and synthetic substitution elasticity in industrial cleaning. Citrus disease spread, trade policy shifts, and extraction technology disruption constitute primary revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Global Eucalyptus Essential Oil Market
Flavorings and Food Additives
Flavoring Agents Market
Flavorings and Food Additives
Savory Extract Market
Flavorings and Food Additives
Citrus Concentrate Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
Orange Peel Extract Market
Flavorings and Food Additives
Oryzanol Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Global Flavors Market
Flavorings and Food Additives
North America Food Flavor Market
Flavorings and Food Additives
Betanin Food Color Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Natural Acerola Cherry Extract Market
Flavorings and Food Additives
Argentina Food Flavor and Enhancer Market
Flavorings and Food Additives
Annatto Extract Market
Flavorings and Food Additives
Mandarin Oil Market