
 Food Grade Menthol Crystal Market | 2026-2036
Food Grade Menthol Crystal Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Menthol Crystal Market Insights
Flavor-house technical service agreements is rebalancing how food grade menthol crystals move from commodity sales to specification-locked supply partnerships. BASF leverages its integrated aroma chemical platform to secure long-term contracts with multinational confectionery brands. Symrise AG anchors European demand through its precision-controlled crystallization and custom blending capabilities. Takasago International Corporation differentiates via biotechnology-derived menthol routes that reduce batch-to-batch terpene profile variation.
Food grade menthol crystal denotes purified l-menthol meeting FCC, JECFA, and EP monograph specifications for optical rotation, melting point, and residual solvent limits, produced via steam distillation of Mentha arvensis oil followed by fractional freezing or via asymmetric catalytic hydrogenation of thymol for synthetic grades. Its primary commercial purpose centers on delivering cooling sensation and mint flavor in oral care, confectionery, and medicated food products without pharmaceutical regulatory burden. Natural menthol commands persistent premiums in organic-certified and geographic-indication flavor applications where synthetic alternatives face formulation restrictions. Pharmaceutical application represents the fastest-expanding consumption vector as menthol crystals gain inclusion in drug-delivery lozenges and oromucosal preparations requiring food-grade rather than USP certification pathways.
FDA food additive regulations, JECFA safety evaluations, and EU Flavouring Regulation 1334/2008 collectively define permissible purity thresholds, labeling requirements, and maximum use levels for menthol in food matrices. These frameworks compel manufacturers to maintain dual-certification compliance documentation for cross-border ingredient shipments. Stakeholders must monitor evolving clean-label disclosure mandates and biotechnological origin verification protocols that will determine competitive access to premium formulation contracts.
Market Dynamics
Flavor-house specification-locked supply partnerships are displacing commodity spot purchasing as confectionery brands seek batch-to-batch optical rotation consistency for clean-label mint formulations.
Growth Catalysts
- Clean-label confectionery expansion:Sugar-free and functional mint product launches in North America are pulling crystallization capacity toward FCC-grade optical rotation specifications.
- EU Flavouring Regulation 1334/2008 compliance:Maximum use level documentation requirements are forcing flavor houses to lock in certified supply chains rather than source opportunistically.
- Biotechnology-derived routes:Asymmetric catalytic hydrogenation of thymol is reducing terpene profile variation, enabling synthetic grades to penetrate organic-restricted formulations.
Market Restraints
- Mentha arvensis oil price volatility:Monsoon-dependent Indian crop yields create input cost instability for natural menthol crystallizers.
- Supply concentration in Uttar Pradesh processing clusters:Domestic essential oil infrastructure bottlenecks create single-geography exposure for export-oriented pharmaceutical flavoring operations.
- Dual-certification documentation burden:Cross-border shipments require simultaneous FCC, JECFA, and EP monograph compliance, extending fulfillment timelines.
Strategic Opportunities
- Oromucosal drug-delivery formulations:Pharmaceutical lozenge manufacturers are adopting food-grade rather than USP certification pathways, opening new volume channels.
- Geographic indication flavor applications:European organic-certified mint products command persistent premiums where synthetic alternatives face formulation restrictions.
- Precision-controlled crystallization services:Custom blending capabilities allow technical service agreements to capture value beyond commodity crystal sales.
Industry Challenges
- Residual solvent testing capacity:Analytical laboratories face backlogs verifying fractional freezing process compliance with EP monograph limits.
- Crystallization equipment lead times:Stainless steel vessel procurement delays are constraining capacity expansion at Indian processing clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Menthol Crystal Market |
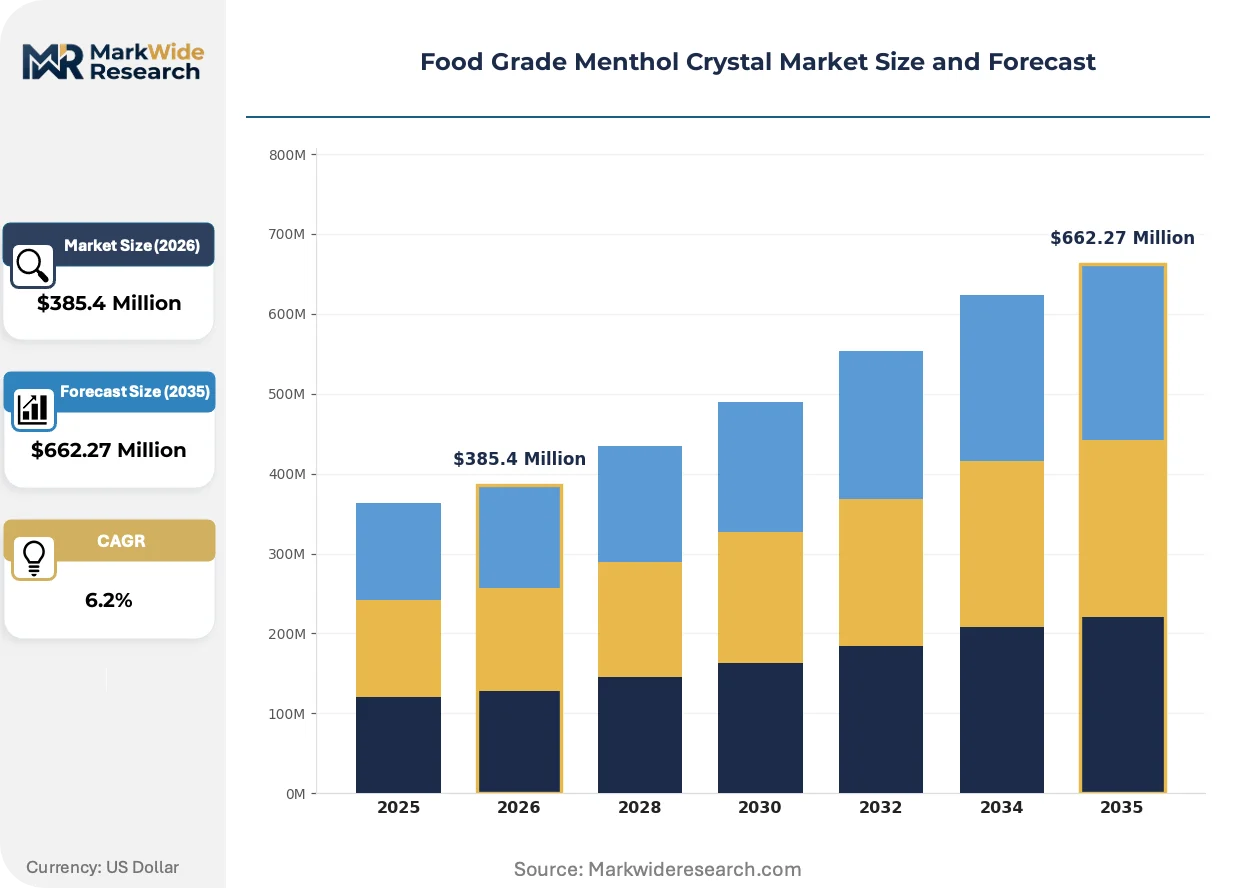
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $662.27 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Menthol, Synthetic Menthol, Dentifrice Menthol, Food Flavoring Menthol Application: Candy, Beverages, Chewing Gum, Pharmaceutical End User: Food Manufacturers, Beverage Producers, Pharmaceutical Companies, Confectionery Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | BASF, Symrise AG, Takasago International Corporation, Arora Aromatics, Silverline Chemicals, KM Chemicals, Nantong Menthol Factory, Fengle Perfume, Nectar Lifesciences, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Menthol Crystal Market Trends and Innovations
Biotechnology and precision analytics are compressing batch-to-batch variation windows while regulatory documentation requirements are hardening supply chain lock-in mechanisms across flavor-house procurement.
Continuous crystallization monitoring via in-line polarimetry is integrating real-time optical rotation feedback into production workflows. Mid-sized confectionery manufacturers in Germany and the Netherlands are adopting these systems to reduce QC hold times. The technology is integrating specification compliance into process control rather than post-batch verification, compressing the gap between natural and synthetic grade consistency claims.
REACH substance evaluation dossiers for menthol isomers are tightening residual impurity disclosure thresholds for EU market access. Flavor houses must now submit extended safety data sets covering stereochemical purity profiles. Pharmaceutical flavoring operations serving oromucosal preparations are most affected, accelerating migration toward JECFA-preferred synthetic routes with cleaner analytical signatures.
Long-term offtake agreements with crystallization specialists are replacing spot market purchases among North American sugar-free gum manufacturers. These contracts embed minimum optical rotation guarantees and dedicated batch reservation clauses. The shift is most visible in contract manufacturing organizations serving private-label mint brands, where certification continuity has become a procurement priority over unit cost minimization.
Food Grade Menthol Crystal Market Segmentation
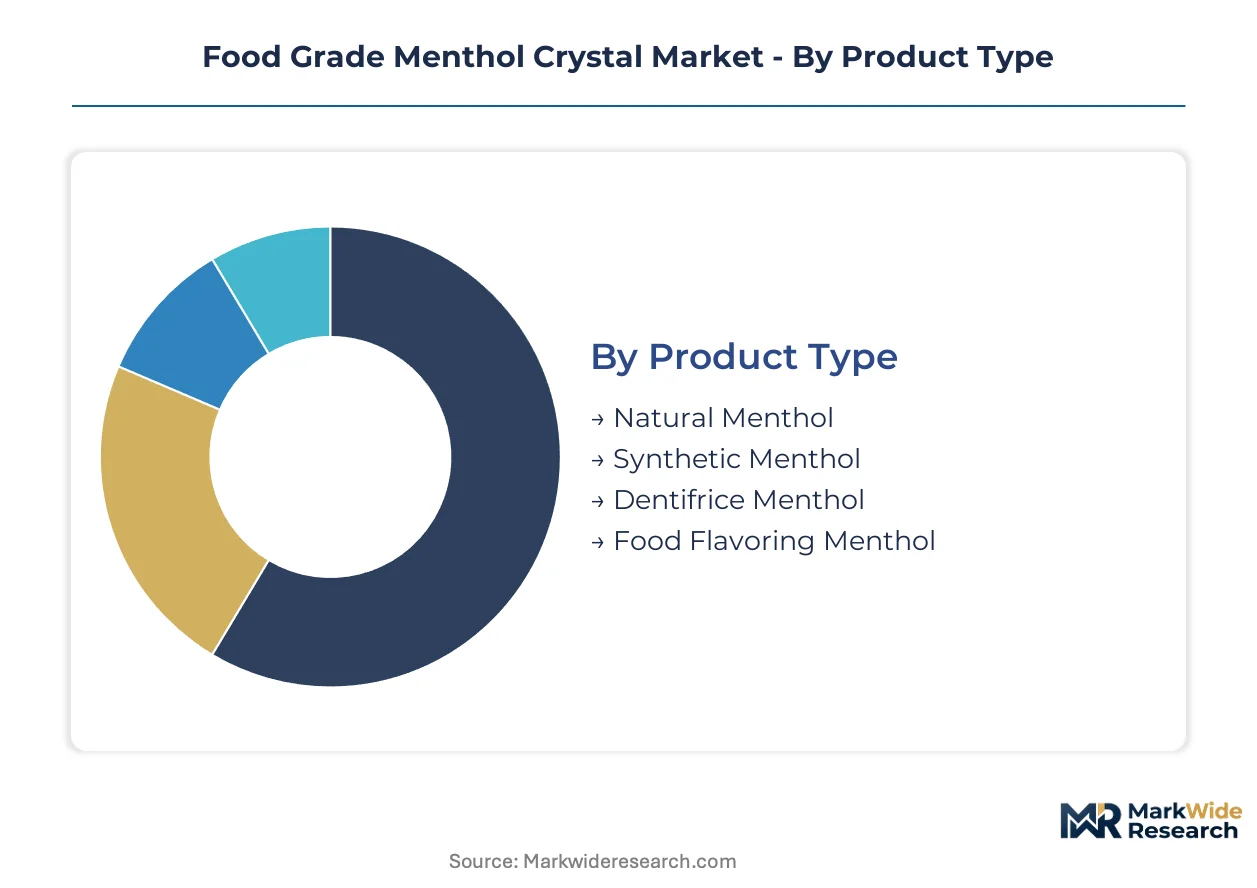
Segmentation in food grade menthol crystals reveals how capital deployment, regulatory pathways, and procurement rigidity fragment supply relationships. Crystallization equipment intensity and certification documentation burdens create divergent competitive moats across product grades and customer types.
Product Type:
Capital intensity concentrates in natural menthol crystallization, where fractional freezing infrastructure and solvent recovery systems demand the heaviest upfront investment.
- Natural Menthol:Purified l-menthol extracted from Mentha arvensis oil via steam distillation and fractional freezing, meeting FCC and JECFA optical rotation specifications. Indian processing clusters in Uttar Pradesh absorb the bulk of installed capacity as export-oriented pharmaceutical flavoring operations scale crystallization infrastructure.
- Synthetic Menthol:Manufactured via asymmetric catalytic hydrogenation of thymol, delivering tighter batch-to-batch terpene consistency with lower agricultural input exposure. German and Dutch confectionery manufacturers are expanding procurement of synthetic grades to circumvent Mentha arvensis price volatility and monsoon-dependent yield risks.
- Dentifrice Menthol:Specialized grade optimized for oral care applications with enhanced cooling persistence and controlled release properties.
- Food Flavoring Menthol:Standard FCC-grade crystals for general confectionery and beverage applications with flexible optical rotation tolerances.
Natural menthol absorbs the bulk of installed capacity; synthetic menthol is expanding most quickly as REACH dossier requirements harden impurity disclosure thresholds.
Application:
Volume concentration follows sugar-free formulation launches, with procurement patterns diverging between clean-label confectionery and oromucosal pharmaceutical channels.
- Candy:Hard-boiled and compressed mint tablets requiring precise cooling sensation delivery and flavor stability across shelf life. North American sugar-free product launches are pulling crystallization capacity toward dedicated batch reservation contracts with optical rotation guarantees.
- Chewing Gum:Functional mint and medicated gum formulations demanding sustained release of cooling actives. Private-label contract manufacturers in the United States are locking in long-term offtake agreements to secure certification continuity for retail brand supply.
- Beverages:Ready-to-drink mint-infused and functional cooling drinks with solubility-optimized crystal specifications.
- Pharmaceutical:Oromucosal drug-delivery lozenges and throat preparations requiring food-grade rather than USP certification pathways, opening new volume channels for FCC-grade suppliers.
Chewing gum captures the steepest procurement volume; pharmaceutical applications are climbing the fastest as lozenge manufacturers migrate from pharmaceutical to food-grade certification routes.
End User:
Customer scale determines specification-locked contract prevalence, with multinational brands demanding dedicated technical service agreements unavailable to smaller buyers.
- Food Manufacturers:Processed food and dairy applications incorporating mint flavoring with clean-label disclosure requirements.
- Beverage Producers:Functional drink and flavored water formulators requiring solubility-tailored crystal grades.
- Pharmaceutical Companies:Oromucosal and drug-delivery specialists adopting food-grade certification to streamline regulatory pathways. These buyers are concentrating procurement among crystallizers with dual FCC-JECFA documentation capabilities.
- Confectionery:Sugar-free and functional mint product specialists driving the tightest optical rotation specifications. Multinational brands are displacing commodity spot purchasing with embedded minimum purity guarantees and batch reservation clauses.
Confectionery commands the deepest technical service integration; pharmaceutical companies are gaining share fastest in contract value terms.
Distribution Channel:
Channel selection reflects buyer scale and certification urgency, with large manufacturers bypassing intermediaries to secure documentation continuity.
- Direct Sales:Long-term offtake agreements between crystallization specialists and multinational confectionery or pharmaceutical buyers. These relationships embed specification compliance into procurement rather than post-delivery verification.
- Distributors:Regional chemical and flavor ingredient distributors serving mid-sized manufacturers without volume thresholds for direct crystallizer contracts.
- Online Retail:E-procurement platforms for small-batch and specialty grade purchases with extended fulfillment timelines.
- Wholesalers:Commodity spot market access for price-sensitive buyers accepting batch-to-batch variation.
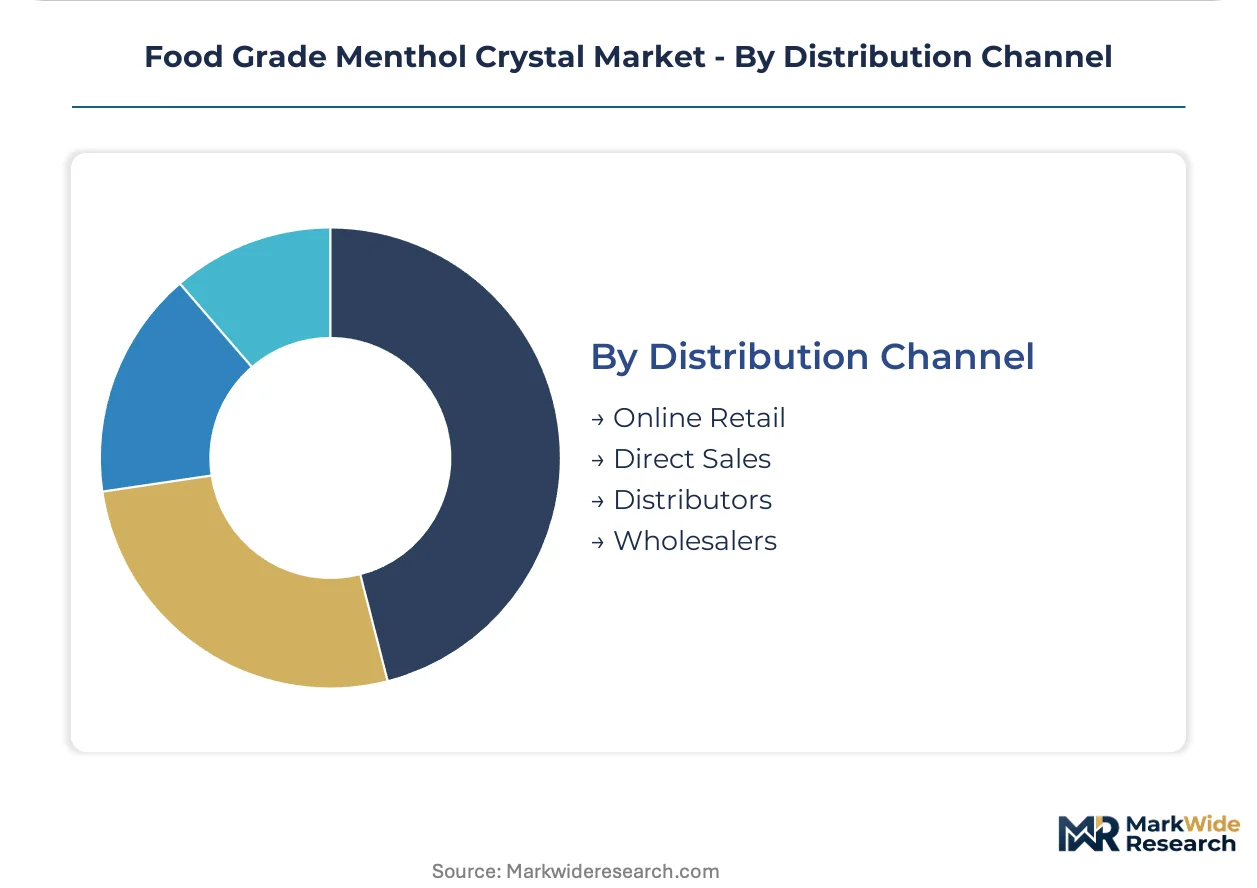
Direct sales capture the highest contract value; distributor relationships are expanding most quickly among mid-sized European clean-label manufacturers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates crystallization capacity while Germany and the United States absorb premium-grade volumes. This production-consumption divide shapes procurement patterns across regulatory jurisdictions.
India
Uttar Pradesh processing clusters handle fractional freezing infrastructure for export-oriented pharmaceutical flavoring operations. FSSAI purity mandates and DGFT export documentation requirements compel dual-certification maintenance at crystallization facilities. Domestic essential oil infrastructure bottlenecks in Bareilly and Barabanki create single-geography exposure for global supply chains.
Germany
Mid-sized confectionery manufacturers in Bavaria and North Rhine-Westphalia adopt in-line polarimetry systems for real-time optical rotation feedback. REACH substance evaluation dossiers for menthol isomers tighten residual impurity disclosure thresholds for EU market access. ECHA compliance documentation now covers extended safety data sets for stereochemical purity profiles.
United States
Sugar-free gum contract manufacturers lock in long-term offtake agreements with dedicated batch reservation clauses. FDA updated food additive safety reviews tighten purity requirements for flavor-grade menthol crystals. Private-label mint brands in Chicago and New Jersey procurement networks prioritize certification continuity over unit cost minimization.
China
Nantong and Shanghai synthetic menthol producers scale asymmetric catalytic hydrogenation capacity to reduce terpene profile variation. SAMR food additive regulations align with JECFA safety evaluations for cross-border ingredient shipments. Yangtze River Delta chemical parks integrate stainless steel crystallization vessel production to shorten equipment lead times.
Netherlands
Rotterdam and Eindhoven flavor houses anchor European demand through precision-controlled crystallization services. EU Flavouring Regulation 1334/2008 maximum use level documentation forces certified supply chain lock-in rather than opportunistic sourcing. Randstad region technical service agreements capture value beyond commodity crystal sales through custom blending capabilities.
Food Grade Menthol Crystal Market Competitive Landscape
Top-tier vendors anchor integrated aroma chemical platforms, while regional crystallizers compete on batch-specific optical rotation guarantees. The vendor base splits between multinational flavor houses with captive supply chains and independent processors serving spot market demand. Three archetypes dominate: specification-locked contract specialists, biotechnology-derived synthetic producers, and natural menthol fractional freezing operators. Capacity expansion and backward integration into Mentha arvensis oil processing represent the dominant competitive vectors.
Among German integrated chemical conglomerates, BASF occupies a position exemplifying platform-scale supply chain control. Swiss and Japanese specialists in precision flavor chemistry, Symrise AG and Takasago International Corporation, represent the technical service agreement archetype with embedded crystallization capabilities. These three anchors illustrate how geographic origin and corporate structure map onto divergent procurement relationship models in food-grade menthol crystal supply.
| Leading Market Players |
|---|
| BASF |
| Symrise AG |
| Takasago International Corporation |
| Arora Aromatics |
| Silverline Chemicals |
| KM Chemicals |
| Nantong Menthol Factory |
| Fengle Perfume |
| Nectar Lifesciences |
| Others |
Pricing and Supply Chain Analysis
Asymmetric catalytic hydrogenation of thymol is compressing synthetic menthol production costs while concentrating supply leverage among German and Dutch chemical parks with captive hydrogenation infrastructure. This process shift simultaneously erodes natural menthol's cost premium and tightens procurement options for buyers seeking batch-to-batch terpene consistency.
Pricing Analysis
Margin tightening in natural menthol reflects monsoon-dependent Mentha arvensis oil volatility and Uttar Pradesh crop yield instability. Pricing stratifies across FCC-JECFA dual-certified premium grades, single-certified standard tiers, and spot-market economy lots with relaxed optical rotation tolerances. Cost-down pressure on natural grades accelerates because confectionery manufacturers are migrating toward synthetic alternatives with tighter analytical signatures. Small-batch beverage formulators exhibit highest price sensitivity; multinational pharmaceutical lozenge producers prioritize certification continuity over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's FSSAI export documentation are reshaping sourcing patterns for cross-border pharmaceutical flavoring shipments. Supply concentrates in Uttar Pradesh processing clusters, German hydrogenation facilities, and Chinese Yangtze River Delta synthetic plants. Raw material flows draw from Mentha arvensis oil distilleries, thymol feedstock streams, and stainless steel crystallization vessel fabricators. Single-geography exposure in Bareilly-Barabanki infrastructure creates vulnerability to monsoon disruption and DGFT documentation backlogs. Distribution runs through direct long-term offtake agreements for multinational buyers and regional chemical distributors for mid-tier confectionery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Stainless steel crystallization vessel procurement delays are constraining capacity expansion at Indian processing clusters, propping pricing power for incumbent fractional freezing operators with installed infrastructure.
For Market Incumbents: Cement specification-locked supply partnerships by embedding minimum optical rotation guarantees and dedicated batch reservation clauses into technical service agreements. Invest in backward integration into Mentha arvensis oil processing to circumvent Uttar Pradesh crop yield volatility. Prioritize dual FCC-JECFA certification maintenance to defend against synthetic-grade competitors with cleaner REACH dossier profiles. For New Entrants and Emerging Players: Capture oromucosal drug-delivery formulation channels where pharmaceutical lozenge manufacturers are migrating from USP to food-grade certification pathways. Target mid-sized European clean-label confectionery manufacturers in Bavaria and North Rhine-Westphalia adopting in-line polarimetry systems. Lead with biotechnology-derived synthetic routes that reduce batch-to-batch terpene profile variation and compress QC hold times. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of independent crystallization specialists with dual-certification documentation capabilities and stranded capacity in Uttar Pradesh clusters. Long-term viability hinges on securing supply relationships with multinational flavor houses displacing commodity spot purchasing. Watch FDA updated food additive safety review timelines as inflection indicator for premium-grade pricing spreads.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mentha arvensis Oil Processing | Captive supply secures input cost stability against monsoon-dependent Indian crop yields. |
| Dual FCC-JECFA Certification Investment | Documentation continuity unlocks cross-border pharmaceutical flavoring procurement contracts. |
| Precision-Controlled Crystallization Capacity Expansion | Custom blending capabilities capture value beyond commodity crystal sales in Rotterdam-Eindhoven corridor. |
| Biotechnology-Derived Synthetic Route Scale-Up | Asymmetric catalytic hydrogenation reduces terpene profile variation for REACH-compliant EU access. |
| Long-Term Offtake Agreement with Confectionery Multinationals | Embedded optical rotation guarantees displace spot market volatility in North American sugar-free gum channels. |
Research Methodology
Document review covered FSSAI export documentation, REACH substance evaluation dossiers, FDA food additive safety reviews, and JECFA monograph specifications, complemented by interviews with crystallization plant managers, flavor house procurement leads, confectionery technical service directors, and pharmaceutical regulatory affairs specialists. Secondary validation drew from DGFT trade statistics, ECHA compliance filings, SEC 10-K aroma chemical disclosures, and EU Flavouring Regulation 1334/2008 implementation guidance. Bottom-up crystallization capacity assessments and top-down end-use demand modeling were triangulated against cross-border shipment documentation.
Market size outputs integrate grade-tier segmentation by natural versus synthetic origin, application splits across confectionery and pharmaceutical channels, and end-user procurement rigidity levels across the projection horizon. CAGRs were derived from installed capacity expansion timelines, regulatory pathway adoption curves, and substitution elasticity between natural and synthetic grades. Key inputs include Mentha arvensis oil price volatility indices, stainless steel vessel procurement lead times, and REACH dossier filing trajectories for menthol isomers.
The model holds under stable FSSAI-DGFT documentation processing and REACH implementation timelines; deviation in FDA safety review stringency or Uttar Pradesh monsoon patterns would shift grade-premium structures and capacity utilization assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
China Food Flavor and Enhancer Market
Flavorings and Food Additives
Neotame Market
Flavorings and Food Additives
Tangerine Essential Oil Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Ginkgo Biloba Extract Market
Flavorings and Food Additives
Dairy Flavors Market
Flavorings and Food Additives
Anthocyanin Food Colors Market
Flavorings and Food Additives
Brazil Food Colorants Market
Flavorings and Food Additives
United States Food Flavor Market
Flavorings and Food Additives
Pumpkin Spice Products Market
Flavorings and Food Additives
Global Paprika Oleoresin Market
Flavorings and Food Additives
Global Ginger Extract Market
Flavorings and Food Additives
Beverage Flavoring Agent Market
Flavorings and Food Additives
Cheese Flavor Market
Flavorings and Food Additives
Water-Soluble Flavors Market
Flavorings and Food Additives
Food Flavors & Flavor Enhancers Market