
 Brazil Food Colorants Market | 2026-2036
Brazil Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Food Colorants Market Outlook
Leasing arrangements for extraction and fermentation equipment is rewriting competitive entry barriers for mid-sized natural colorant producers in Brazil. Chr. Hansen Holding leverages its microbial fermentation expertise to sustain premium positioning in carmine alternatives. Givaudan anchors its Brazilian operations through localized supply partnerships with tropical fruit pigment sources. Sensient Technologies competes via integrated powder and liquid formulation capabilities serving multinational food manufacturers.
Food colorants comprise pigments and dyes added to edible products to restore color lost during processing, enhance visual appeal, or differentiate flavor profiles, with natural variants derived from anthocyanin-rich fruits, carotenoid-bearing plants, and curcumin sources requiring pH-stable formulations between 2.5 and 8.0 for beverage compatibility. Their primary commercial purpose centers on influencing consumer purchase decisions through visual consistency and brand recognition across packaged goods. Natural color types command expanding shelf space as clean-label mandates from Brazilian supermarket chains intensify, while synthetic variants retain cost advantages in mass-market confectionery where heat stability during extrusion remains critical. Powder forms dominate industrial-scale bakery applications for dosing precision, whereas liquid concentrates lead beverage manufacturing for homogeneous dispersion.
ANVISA governs colorant safety assessments and maximum permissible concentrations under Brazilian food additive legislation, while the Ministry of Agriculture enforces Good Manufacturing Practices at production facilities. These frameworks elevate compliance costs for imported synthetic dyes while creating preferential pathways for domestically sourced natural pigments with established toxicological dossiers. Stakeholders must monitor pending ANVISA consultations on revised titanium dioxide restrictions and calibrate formulation portfolios accordingly.
Market Dynamics
ANVISA's tightening purity standards for synthetic dyes are compressing formulation portfolios while beverage manufacturers accelerate natural colorant integration, forcing suppliers to rebuild technical dossiers around domestically sourced anthocyanin and carotenoid alternatives.
Growth Catalysts
- Clean-label mandates:Brazilian supermarket chains now require natural color declarations on packaged goods, pulling reformulation demand through São Paulo's processed food corridor.
- Fermentation technology:Microbial production platforms for carmine alternatives reduce batch-to-batch variability while securing supply independent of cochineal harvest cycles.
- Functional beverage expansion:Sports and wellness drink manufacturers seek pH-stable natural pigments compatible with acidic formulations between 2.5 and 8.0.
Market Restraints
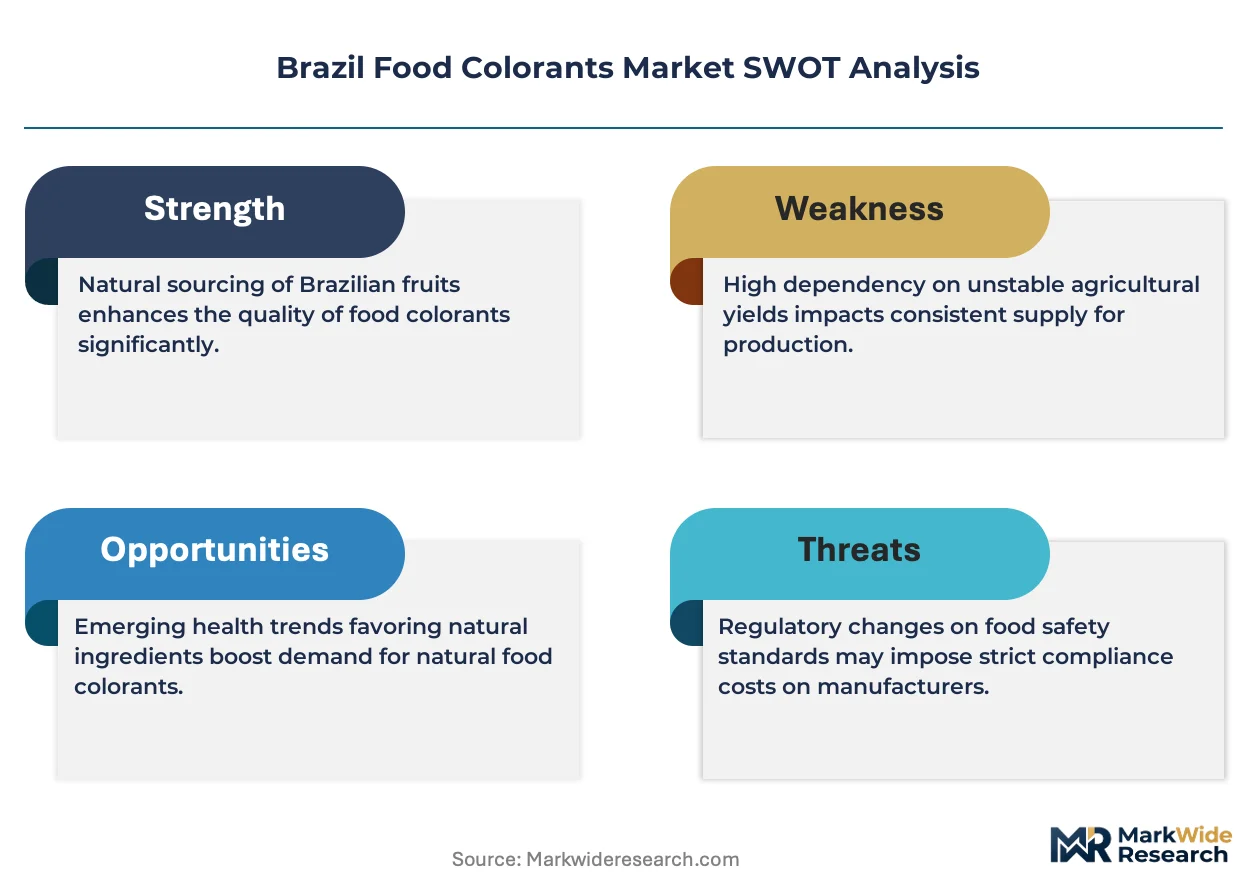
- Input cost volatility:Tropical fruit pigment sources face climate-driven harvest fluctuations, compressing margin predictability for natural colorant producers.
- Heat stability limitations:Anthocyanin-based formulations degrade above 85°C, restricting deployment in extruded confectionery where synthetic azo dyes retain performance advantages.
- Regulatory friction:ANVISA's pending titanium dioxide restrictions force manufacturers to reformulate white opacity applications without approved natural alternatives at equivalent cost.
Strategic Opportunities
- Northeast fruit belt expansion:Bahia and Pernambuco harbor underexploited acerola and pitanga sources for high-anthocyanin extraction with established organic certification pathways.
- Leasing model innovation:Equipment financing for extraction and fermentation assets lowers capital barriers for mid-tier producers entering natural colorant manufacturing.
- Ministry of Agriculture alignment:Good Manufacturing Practice certification at production facilities creates preferential market access for domestic pigment suppliers over import-dependent competitors.
Industry Challenges
- Toxicological dossier compilation:Natural colorant producers must assemble comprehensive safety data packages for ANVISA approval, extending time-to-market by 18-24 months versus synthetic dye registrations.
- pH formulation expertise scarcity:Beverage applications demand specialized knowledge in buffer systems and encapsulation technologies to stabilize natural pigments across acidic matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Food Colorants Market |
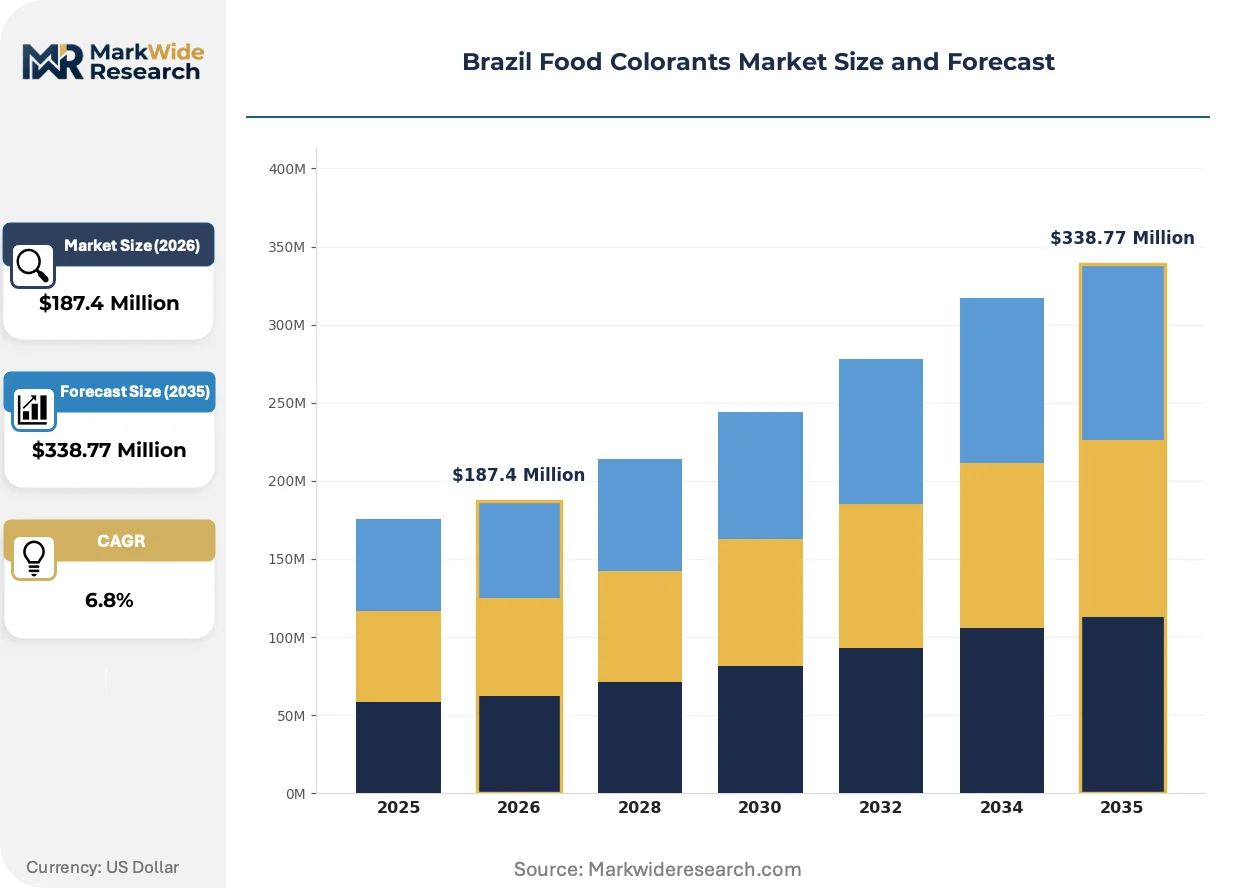
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Color Type: Natural, Synthetic, Organic, Inorganic Application: Beverages, Confectionery, Dairy Products, Bakery Form: Liquid, Powder, Gel, Paste End User: Food Manufacturers, Beverage Companies, Bakery Retailers, Restaurants |
| Companies Covered | Givaudan, Chr. Hansen Holding, Koninklijke DSM, Sensient Technologies, DDW The Color House, Archer Daniels Midland Company, Kalsec, Döhler Group, Aromata Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Food Colorants Market Strategic Shifts
Fermentation-based pigment production and advanced encapsulation technologies are collapsing traditional supply chain structures while regulatory pressure accelerates substitution timelines across beverage and confectionery formulations.
Encapsulation technology using modified starch and gum arabic matrices is collapsing the stability gap between natural and synthetic colorants in heat-processed applications. Bakery manufacturers in São Paulo's industrial corridor now specify spray-dried anthocyanin concentrates for muffin and cake mixes previously dependent on azo dyes. This compression enables clean-label claims without sacrificing shelf-life performance or thermal processing tolerance.
ANVISA's updated food additive regulations are elevating purity thresholds for synthetic dyes while streamlining approval pathways for domestically sourced natural pigments with established toxicological histories. The Ministry of Agriculture enforces Good Manufacturing Practice audits at production facilities, creating compliance differentiation between certified domestic suppliers and import-dependent competitors. Beverage manufacturers are responding by dual-sourcing strategies that weight regulatory risk alongside unit economics.
Supermarket private-label procurement teams now mandate natural colorant specifications as a condition of shelf placement, displacing conventional cost-first supplier selection. This specification-driven purchasing concentrates volume among certified natural colorant producers with integrated formulation capabilities. The shift is most visible in Rio de Janeiro and São Paulo retail networks where clean-label penetration in processed foods exceeds national averages.
Brazil Food Colorants Market Segmentation
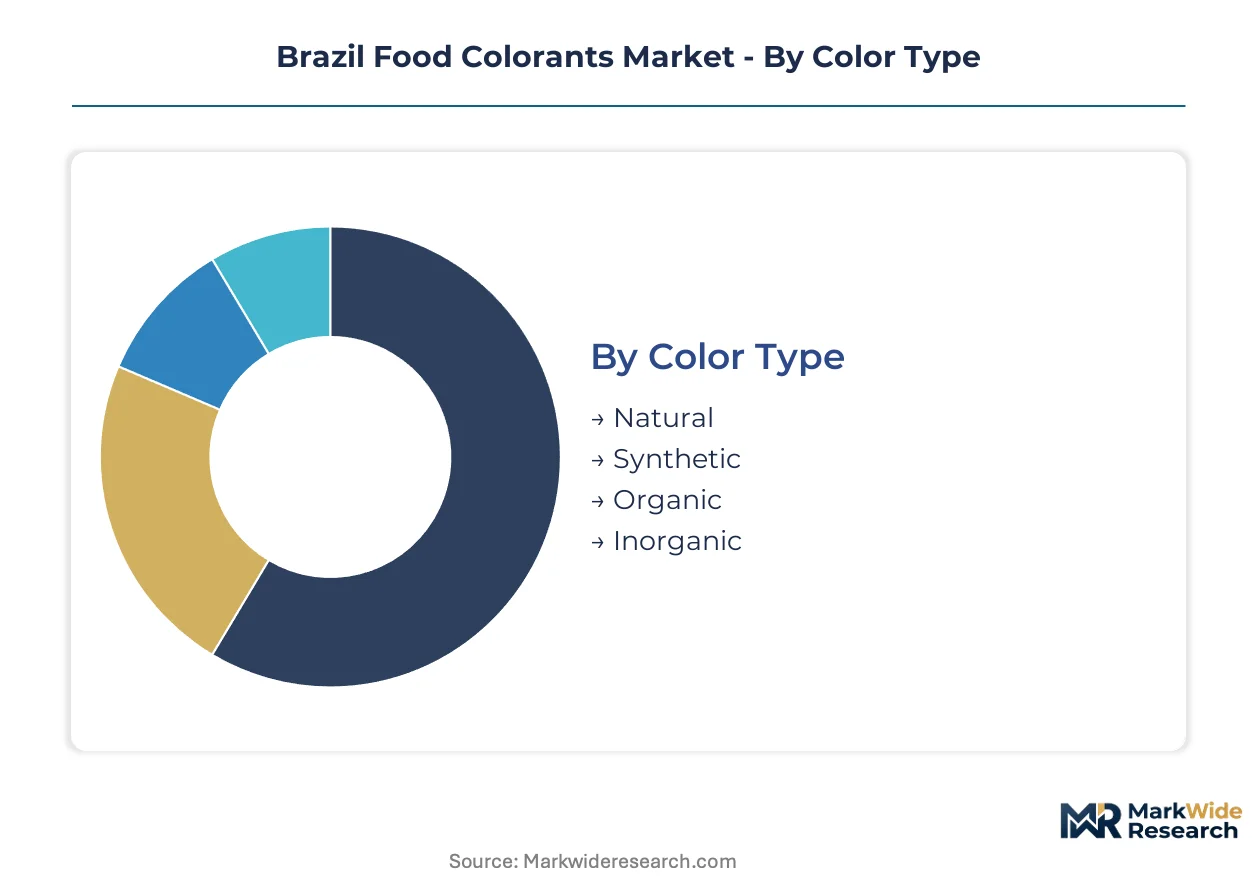
Segmentation in Brazil's food colorants market reveals how regulatory pressure and clean-label procurement reshape supplier priorities across formulation types, end-use applications, and delivery formats. Understanding these divides exposes where ANVISA compliance investments concentrate and where leasing-enabled entrants can capture share.
Color Type:
Formulators navigate a use-case spectrum stretching from heat-stable synthetic azo dyes in mass-market confectionery to pH-sensitive anthocyanin extracts in functional beverages.
- Natural:Anthocyanin-rich acerola and carotenoid-bearing tropical fruit extracts dominate beverage and dairy applications. São Paulo's processed food corridor pulls volume as supermarket chains mandate clean-label declarations. Climate-driven harvest volatility in Bahia and Pernambuco compresses margin predictability for producers lacking fermentation alternatives.
- Synthetic:Azo dyes and titanium dioxide retain cost advantages in extruded confectionery where thermal stability above 85°C remains non-negotiable. ANVISA's tightening purity standards and pending titanium dioxide restrictions force manufacturers to rebuild technical dossiers or exit white opacity applications entirely.
- Organic:Certified organic pigments from established toxicological dossiers access preferential ANVISA approval pathways. Northeast fruit belt expansion targets acerola and pitanga sources with existing organic certification infrastructure.
- Inorganic:Mineral-based colorants including iron oxides serve niche applications in decorative confectionery and pet food where synthetic dye restrictions do not apply.
The dominant share belongs to Natural colorants, while Synthetic formulations are closing the gap fastest through encapsulation technologies that narrow performance differentials.
Application:
Cost tier stratification separates premium functional beverage formulations from commodity confectionery runs where unit economics still favor legacy synthetic systems.
- Beverages:Sports and wellness drink manufacturers specify pH-stable natural pigments compatible with acidic matrices between 2.5 and 8.0. Buffer system expertise and encapsulation capabilities differentiate qualified suppliers in this specification-intensive segment.
- Confectionery:Heat stability requirements during extrusion and baking preserve synthetic dye dominance in mass-market chocolate and candy production. Spray-dried anthocyanin concentrates are displacing azo dyes in premium clean-label sub-segments where thermal processing tolerance has improved.
- Dairy Products:Carotenoid formulations for cheese and yogurt applications demand light-stable systems resistant to photo-oxidation during retail display. Fermentation-derived alternatives reduce batch-to-batch variability independent of seasonal harvest cycles.
- Bakery:Powder colorants dominate industrial-scale dosing precision for muffin and cake mixes. São Paulo bakery manufacturers increasingly specify encapsulated natural concentrates previously dependent on synthetic systems.
Beverages command premium pricing power through technical specification barriers, though Bakery applications are expanding most quickly via encapsulation technology diffusion.
Form:
Volume concentration in industrial processing favors formats that integrate cleanly with automated dosing and homogeneous dispersion systems.
- Liquid:Concentrates lead beverage manufacturing for uniform dispersion in high-speed bottling lines. pH-stable liquid anthocyanin formulations require specialized buffer expertise that concentrates supply among integrated producers.
- Powder:Spray-dried forms dominate bakery and dry mix applications where dosing precision and shelf stability outweigh reconstitution convenience. Encapsulation using modified starch matrices enables heat-processed deployment previously restricted to synthetic dyes.
- Gel:High-viscosity formats serve artisan bakery and restaurant applications requiring manual color matching and controlled dosing in small-batch production.
- Paste:Concentrated paste forms target confectionery decoration and compound coating applications where intense color saturation must survive shear mixing without phase separation.
Powder formats retain the largest installed base in industrial processing, while Liquid concentrates are gaining share fastest through beverage sector expansion.
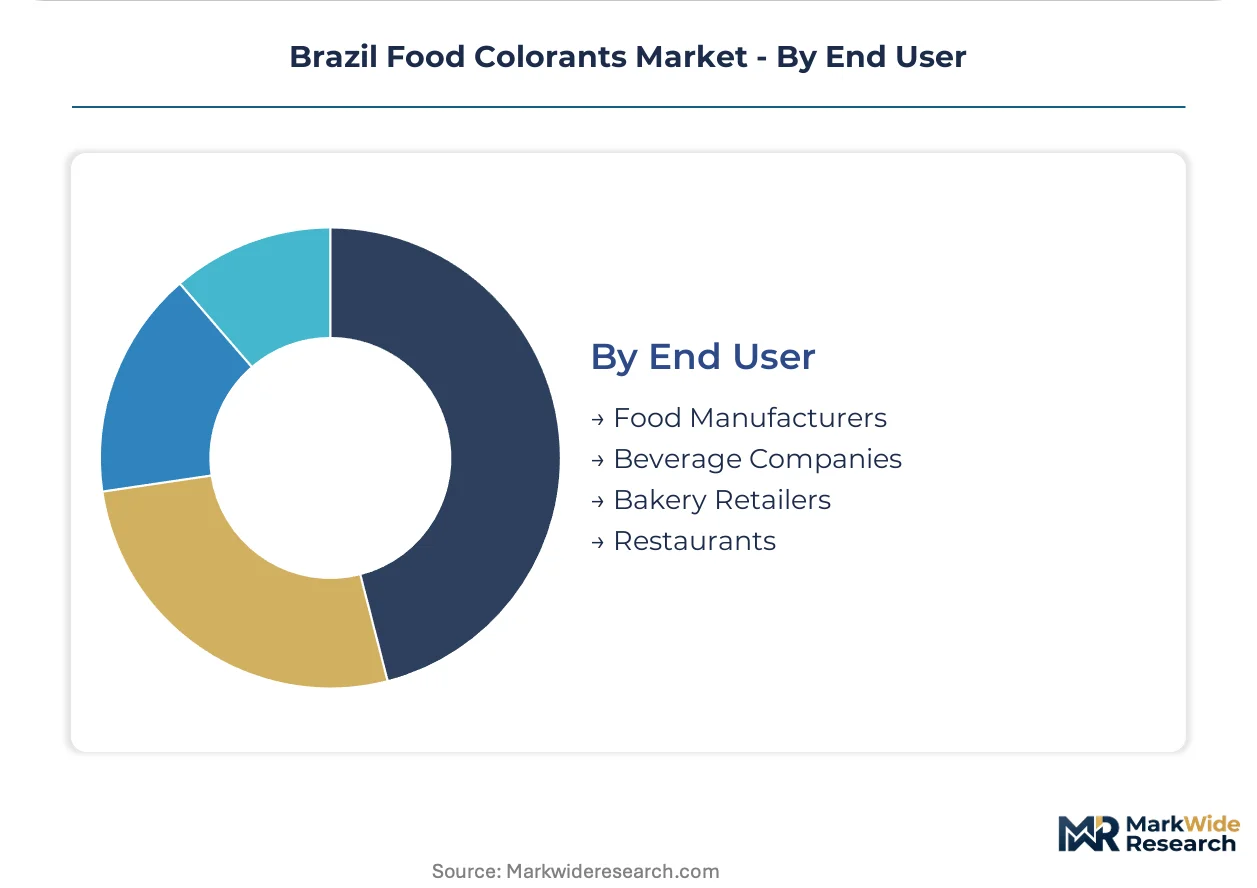
End User:
Customer type determines whether procurement prioritizes regulatory risk mitigation, formulation technical support, or pure unit cost minimization.
- Food Manufacturers:Multinational processed food producers in São Paulo's industrial corridor demand integrated formulation capabilities spanning powder and liquid systems. Dual-sourcing strategies weight ANVISA compliance certification alongside unit economics.
- Beverage Companies:Functional drink specialists require pH-stable natural pigments with documented toxicological dossiers for accelerated regulatory approval. Technical partnership depth with suppliers separates qualified vendors from commodity merchants.
- Bakery Retailers:Supermarket private-label procurement teams mandate natural colorant specifications as a condition of shelf placement in Rio de Janeiro and São Paulo networks. Clean-label penetration exceeds national averages in these retail corridors.
- Restaurants:Foodservice operators favor gel and paste formats for manual color matching in dessert and beverage preparation, with minimal regulatory documentation requirements compared to packaged goods manufacturers.
Food Manufacturers represent the deepest volume concentration, though Beverage Companies are climbing the fastest through clean-label reformulation mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA's updated purity standards for synthetic dyes and streamlined approval pathways for domestic natural pigments are redistributing manufacturing investment across Brazil's federal states.
São Paulo
Beverage manufacturers and processed food producers in São Paulo's industrial corridor drive the bulk of natural colorant procurement. The Ministry of Agriculture enforces Good Manufacturing Practice audits at production facilities throughout the metropolitan region. Multinational food manufacturers cluster in Guarulhos and Barueri, demanding integrated powder and liquid formulation capabilities from certified suppliers.
Bahia
Acerola and pitanga cultivation for high-anthocyanin extraction expands across the Recôncavo Baiano with established organic certification infrastructure. ANVISA preferential approval pathways accelerate market access for domestically sourced pigments with complete toxicological dossiers. Processing facilities in Feira de Santana aggregate fruit belt harvests for concentrate production serving national beverage manufacturers.
Pernambuco
Tropical fruit pigment sources in the Zona da Mata face climate-driven harvest fluctuations that compress margin predictability for extraction-dependent producers. The Ministry of Agriculture certification programs create compliance differentiation for domestic suppliers over import-dependent competitors. Caruaru and Vitória de Santo Antão host emerging extraction cooperatives targeting clean-label supply contracts.
Minas Gerais
Dairy product manufacturers in the Triângulo Mineiro specify carotenoid formulations with light-stable systems resistant to photo-oxidation. ANVISA's pending titanium dioxide restrictions force regional cheese and yogurt producers to reformulate white opacity applications. Uberlândia and Uberaba anchor carotenoid demand from fermentation-derived alternatives that reduce batch-to-batch variability.
Rio Grande do Sul
Confectionery manufacturers in Porto Alegre's industrial zone preserve synthetic dye dominance for heat-stable extrusion applications above 85°C. Encapsulation technology diffusion enables spray-dried anthocyanin concentrates to penetrate premium clean-label sub-segments. ANVISA compliance investments concentrate among suppliers serving dual-sourcing strategies that weight regulatory risk alongside unit economics.
Brazil Food Colorants Market Competitive Environment
On the supply side, the industry is consolidating around fermentation-enabled natural pigment producers and integrated formulation specialists capable of serving multinational procurement mandates. Three strategic archetypes dominate: microbial fermentation platforms for carmine alternatives, tropical fruit extraction operations with organic certification, and multinational ingredient houses with localized supply partnerships. Competitive moves center on equipment leasing arrangements that lower capital barriers for mid-tier entrants and encapsulation technology licensing that collapses stability differentials between natural and synthetic systems.
Within the fermentation-specialist tier, Chr. Hansen Holding exemplifies premium positioning through microbial production expertise that secures supply independent of agricultural harvest cycles. Givaudan anchors the multinational ingredient house archetype through Brazilian operations integrated with tropical fruit pigment sourcing networks. Sensient Technologies occupies the formulation-integrated position, serving São Paulo-based food manufacturers with combined powder and liquid capabilities. These three entities represent distinct competitive vectors that procurement teams weight against ANVISA compliance certification and technical partnership depth.
| Leading Market Players |
|---|
| Givaudan |
| Chr. Hansen Holding |
| Koninklijke DSM |
| Sensient Technologies |
| DDW The Color House |
| Archer Daniels Midland Company |
| Kalsec |
| Döhler Group |
| Aromata Group |
| Others |
Value Chain & Pricing Dynamics
Feira de Santana's processing capacity expansion in Bahia's acerola belt is compressing extraction margins for imported synthetic dyes while elevating domestic natural pigment premiums. ANVISA compliance certification now functions as a price discriminator separating certified suppliers from commodity merchants in São Paulo's procurement corridors.
Pricing Analysis
Certification level (ANVISA-grade vs. uncertified imports) creates the primary spread between premium natural pigments and commodity synthetic alternatives. Three-tier pricing structure across ANVISA-certified premium, standard-grade domestic, and economy-tier synthetic tiers reflects compliance investment recovery timelines. Pricing pressure stems from climate-driven harvest volatility in Pernambuco's Zona da Mata compressing margin predictability for extraction-dependent producers. Mass-market confectionery manufacturers exhibit highest price sensitivity, while functional beverage companies prioritize pH-stable formulation expertise over unit cost minimization.
Supply Chain Analysis
Contract manufacturing concentration rests with Feira de Santana's extraction cooperatives and São Paulo's integrated formulation houses serving multinational food manufacturers. Geographic supply concentration draws from Brazil's Northeast fruit belt (Bahia, Pernambuco), São Paulo's industrial corridor, and residual synthetic dye imports from Asian chemical producers. Raw material dependencies hinge on tropical fruit harvest cycles, fermentation feedstocks, and modified starch encapsulation matrices. Single-source vulnerability runs through cochineal-dependent carmine alternatives vulnerable to harvest disruption. Distribution runs through Ministry of Agriculture-certified facilities directly into multinational procurement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as ANVISA's regulatory tightening forces synthetic-to-natural reformulation cycles that refresh demand for certified domestic pigments.
For Market Incumbents: Harden formulation integration capabilities spanning powder and liquid systems to defend against leasing-enabled mid-tier entrants. Deepen backward integration into Bahia's acerola belt through cooperative offtake agreements that secure harvest priority. Anchor technical partnership depth with beverage manufacturers seeking pH-stable buffer expertise as the priority defensive lever against Givaudan's localized supply networks. For New Entrants and Emerging Players: Pernambuco's Zona da Mata offers the most penetrable geography for organic-certified extraction cooperatives targeting clean-label supply contracts. Equipment leasing arrangements for fermentation assets lower capital barriers while ANVISA approval pathways accelerate for domestically sourced pigments with complete toxicological dossiers. Target bakery manufacturers in São Paulo's industrial corridor with spray-dried anthocyanin concentrates as the primary go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-escalation play because ANVISA's pending titanium dioxide restrictions and tightening synthetic dye purity standards structurally expand addressable market for natural alternatives. Acquisition targets should screen for fermentation-enabled platforms that decouple supply from agricultural volatility. Monitor ANVISA consultation timelines on revised additive restrictions as the critical inflection signal for portfolio reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fruit Belt | Captures Bahia's acerola harvest priority through cooperative offtake structures. |
| Fermentation Platform Scale-Up | Reduces batch-to-batch variability independent of Pernambuco climate cycles. |
| ANVISA Certification Investment | Unlocks preferential approval pathways for domestically sourced natural pigments. |
| Encapsulation Technology Licensing | Collapsing stability gap between natural anthocyanins and synthetic azo dyes. |
| Equipment Leasing Model Launch | Lowers capital barriers for mid-tier producers entering natural colorant manufacturing. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with extraction facility managers, beverage formulation technologists, ANVISA regulatory affairs specialists, and supermarket private-label procurement directors; and secondary validation through ANVISA additive consultation records, Ministry of Agriculture audit disclosures, customs trade data on synthetic dye imports, and São Paulo industrial corridor production statistics. Bottom-up volume estimates from individual processing facilities triangulated against top-down demand projections from end-use application segments.
Forecast inputs considered color type segmentation across natural, synthetic, organic, and inorganic formulations; application splits between beverages, confectionery, dairy, and bakery; form factors spanning liquid concentrates, spray-dried powders, gels, and pastes; and end-user procurement patterns distinguishing multinational manufacturers from regional specialists. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory inflection points and clean-label mandate diffusion rates across Brazilian retail networks.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by fermentation-specialist entrants or accelerated ANVISA restriction timelines would shift outcomes beyond modeled ranges. Quarterly review of ANVISA consultation dockets, Northeast fruit belt harvest reports, and supermarket chain procurement specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Flavorings and Food Additives
Browning Solutions Market
Flavorings and Food Additives
Mouth Freshener Market
Flavorings and Food Additives
US Flavors Market
Flavorings and Food Additives
France Food Flavor and Enhancer Market
Flavorings and Food Additives
Middle East Food Premix Market
Flavorings and Food Additives
Chicken Flavor Market
Flavorings and Food Additives
Asia-Pacific Vanilla Beans and Extract Market
Flavorings and Food Additives
Russia Food Colorants Market
Flavorings and Food Additives
Fractionated Lecithin Market
Flavorings and Food Additives
Rose Water Market
Flavorings and Food Additives
Lecithin Oleoresin Market
Flavorings and Food Additives
Soy Sauce Powder Market
Flavorings and Food Additives
Culinary Essence Market
Flavorings and Food Additives
North America Licorice Extract Market
Flavorings and Food Additives
Chocolate Flavoring Compounds Market
Flavorings and Food Additives
Vanilla Bean Market