
 Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market | 2026-2036
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market Size, Share, and Industry Trends Forecast 2026-2036
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market Insights
Aerospace-grade qualification standards is bifurcating the competitive landscape into certified and uncertified supply tiers. Solvay S.A. leverages its vertically integrated polymer-to-composite chain to dominate high-performance aerospace contracts. Lanxess AG anchors European automotive demand through its Tepex-branded organosheet platform. Teijin Limited specializes in carbon fiber-reinforced thermoplastic laminates for Japanese OEM programs.
Organosheet and semi-finished thermoplastic UD-tape laminate refers to fiber-reinforced thermoplastic sheets and unidirectional tape preforms manufactured through automated fiber placement or tape laying, typically consolidated under heat and pressure to achieve fiber volume fractions exceeding 50 percent and weldable, recyclable properties. These materials serve primary structural and semi-structural roles where metallic alternatives face weight or corrosion constraints. Automotive applications lead volume consumption due to cycle-time advantages in compression molding, while aerospace-grade carbon fiber organosheets command the deepest margin pools despite smaller batch sizes. UD tape formats are expanding fastest in automated production lines for localized reinforcement of injection-molded components.
The U.S. FAA maintains stringent flame-smoke-toxicity certification requirements that shape material selection for cabin-interior and structural airframe applications. Europe's ECHA REACH framework restricts hazardous substance content in composite manufacturing, while Germany's KBA enforces crash-performance standards that validate organosheet substitution for metal in crash-critical automotive parts. Japan's METI promotes lightweight material adoption through its dual carbon goals and domestic supply chain resilience initiatives. Stakeholders must monitor evolving OEM qualification timelines and regulatory harmonization between FAA and EASA standards to secure long-term platform positions.
Market Dynamics
Thermoplastic composite manufacturing is bifurcating around aerospace-grade qualification standards, creating parallel supply tiers where certified producers capture structural airframe contracts while uncertified suppliers compete for automotive and industrial volume applications.
Growth Catalysts
- REACH VOC Restrictions:Europe's ECHA framework on volatile organic compound emissions in thermoset processing is redirecting capital toward thermoplastic organosheet alternatives that eliminate solvent-based curing.
- Electric Vehicle Battery Enclosures:Automotive OEMs in Germany and Japan are expanding procurement of compression-molded composite structures to replace aluminum in EV underbody protection systems.
- Nagoya Manufacturing Belt Concentration:Japan's METI lightweight material initiatives are concentrating demand for carbon fiber-reinforced laminates within the Aichi Prefecture supplier corridor.
Market Restraints
- Carbon Fiber Supply Concentration:Precursor and fiber production remains dominated by Japanese and U.S. suppliers, exposing downstream organosheet producers to input cost volatility and allocation constraints.
- FAA Flame-Smoke-Toxicity Certification:Stringent U.S. airworthiness standards for cabin-interior applications create multi-year qualification timelines that lock out uncertified supply tiers from aerospace margin pools.
- Metallic Substitution Persistence:High-strength aluminum alloys and advanced high-strength steels retain cost advantages in crash-critical automotive components below certain production volumes.
Strategic Opportunities
- Automated Fiber Placement Convergence:Integration of in-situ consolidation with robotic tape laying is reducing scrap rates and enabling localized reinforcement of injection-molded hybrid structures.
- Bavaria Supplier Corridor Expansion:Germany's KBA crash-performance validation for organosheet substitution in front-end carriers is opening procurement channels beyond traditional metal stamping suppliers.
- Recyclability-Mandate Tailwinds:EU end-of-life vehicle directives and Japan's dual carbon goals are creating regulatory preference for weldable, reprocessable thermoplastic composites over thermoset alternatives.
Industry Challenges
- Multi-Physics Simulation Talent Scarcity:Predictive modeling of anisotropic thermoplastic behavior during compression molding requires specialized expertise in coupled thermal-mechanical flow analysis that outpaces current workforce development.
- OEM Qualification Timeline Compression:Platform development cycles in automotive are compressing below the 18-24 months typically required for material substitution validation and crash-test correlation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market |
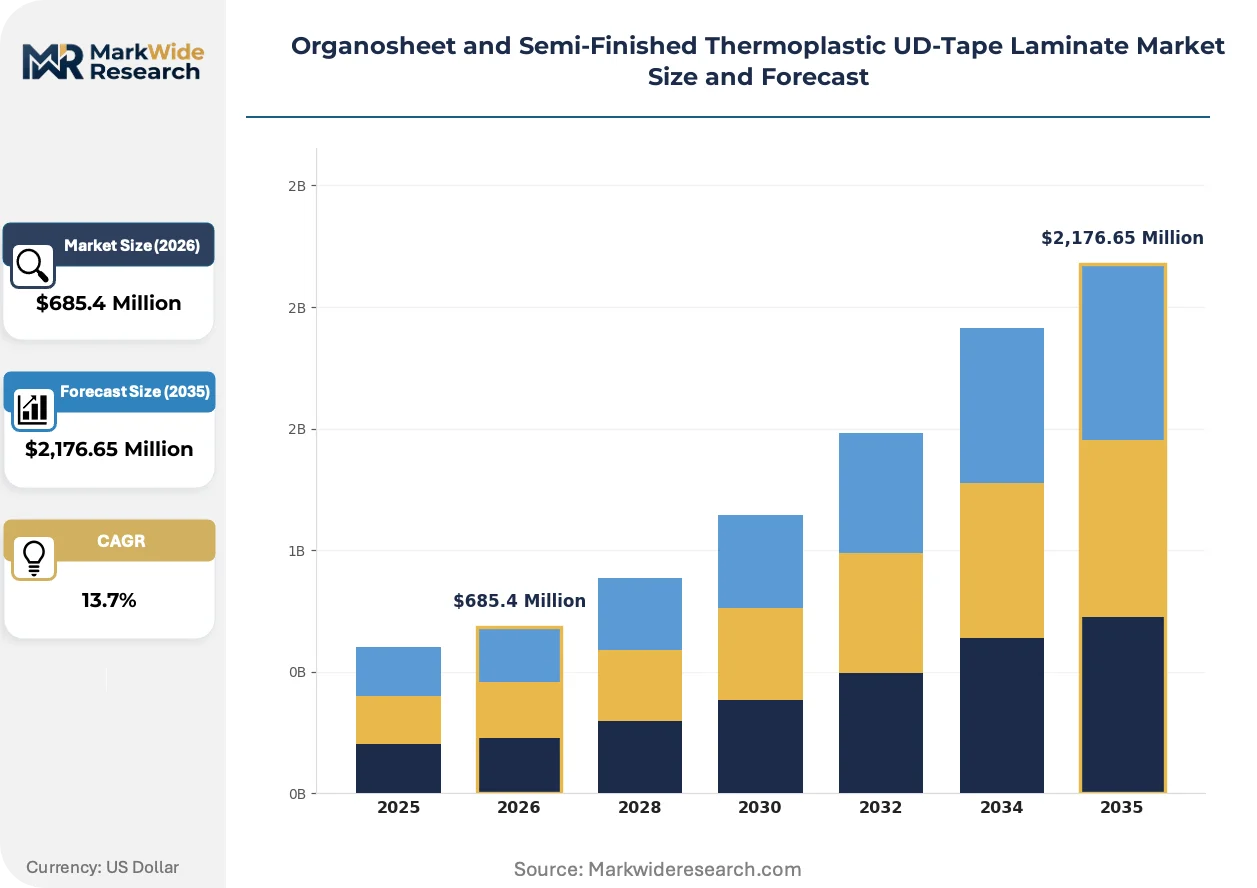
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $2,176.65 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organosheet, UD Tape, Thermoplastic Laminate, Composite Sheet Application: Aerospace, Automotive, Construction, Marine End User: OEMs, Tier-1 Suppliers, Manufacturers, Distributors Material: Fiberglass, Carbon Fiber, Polypropylene, Others |
| Companies Covered | Solvay S.A., Lanxess AG, Teijin Limited, Mitsubishi Chemical Corporation, Toray Industries, Inc., SABIC, BASF SE, Owens Corning, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market Trends and Innovations
Continuous fiber-reinforced thermoplastic processing is fragmenting into distinct technology branches, each optimized for specific fiber lengths, production volumes, and end-use performance requirements rather than converging on a single dominant platform.
Hybrid organosheet-overmolding is fragmenting the traditional separation between structural composites and injection-molded components. Automotive Tier-1 suppliers in Germany are adopting two-step processes where UD-tape laminates form load-bearing shells subsequently overmolded with short-fiber reinforced ribs. This convergence is compressing part counts and assembly operations while creating new weld-line integrity challenges at the organosheet-polymer interface.
Europe's ECHA REACH restrictions on styrene emissions from unsaturated polyester resins are accelerating thermoplastic substitution in construction and marine applications previously dominated by open-mold thermosetting. German industrial safety regulators are extending workplace exposure limits that favor closed, automated thermoplastic consolidation processes. Suppliers with existing thermoplastic tape capacity are capturing volume from thermoset converters facing retrofit costs for emission control equipment.
Buyer concentration among German and Japanese automotive OEMs is compressing supplier negotiation leverage and accelerating specification standardization. Tier-2 laminate producers in Bavaria and Aichi Prefecture report direct sourcing relationships with platform engineering teams that previously channeled through Tier-1 system integrators. This disintermediation is visible most acutely in battery enclosure programs where OEMs specify material grades and consolidation parameters directly to secure supply security for high-volume electric vehicle architectures.
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market Segmentation
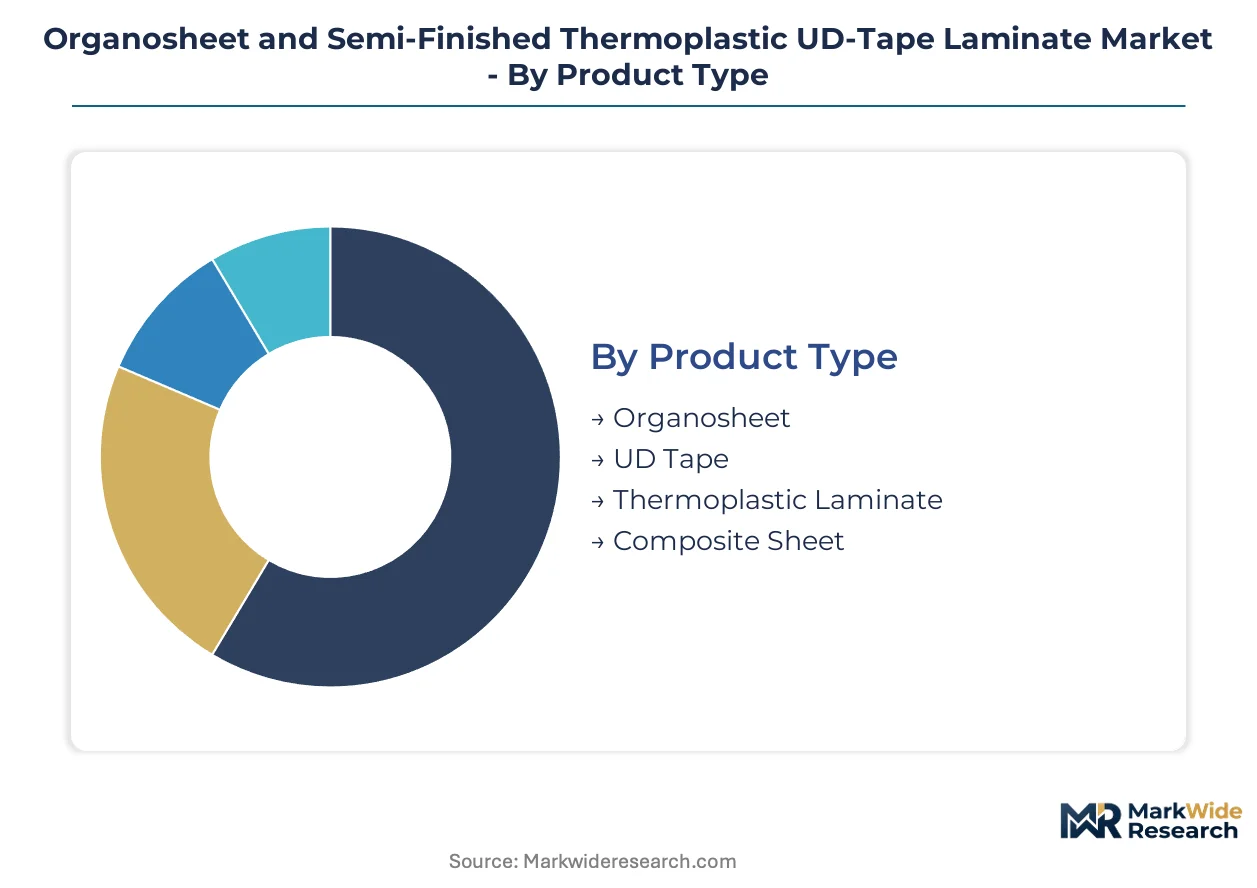
Segmentation in thermoplastic composite markets reveals how qualification barriers, fiber grade premiums, and OEM procurement concentration create divergent margin structures across product formats and supply chain tiers.
Product Type:
Margin pools concentrate in formats that balance fiber volume fraction with processing flexibility, creating tiered pricing based on consolidation complexity and end-use certification requirements.
- Organosheet:Continuous fiber-reinforced thermoplastic sheets consolidated under heat and pressure achieve fiber volume fractions exceeding 50 percent with weldable, recyclable properties. Demand concentrates in Bavaria's automotive supplier corridor where German OEMs specify compression-molded shells for EV battery enclosures to satisfy KBA crash-performance validation.
- UD Tape:Unidirectional fiber-reinforced tape preforms manufactured through automated fiber placement enable localized reinforcement with precise anisotropic control. Procurement is accelerating fastest in Japan's Nagoya manufacturing belt as Tier-1 suppliers integrate robotic tape laying with in-situ consolidation for hybrid injection-molded structures.
- Thermoplastic Laminate:Multi-layer consolidated sheets with tailored fiber orientations serve semi-structural applications requiring moderate strength-to-weight ratios.
- Composite Sheet:General-purpose fiber-reinforced thermoplastic panels target industrial and construction applications with lower qualification barriers.
The dominant share belongs to Organosheet, while UD Tape is closing the gap fastest.
Application:
Application segments diverge sharply by batch size, certification intensity, and substitution economics against incumbent materials.
- Aerospace:Cabin-interior and structural airframe applications command the deepest margin pools despite smaller batch sizes, driven by FAA flame-smoke-toxicity certification requirements that lock out uncertified supply tiers. Solvay S.A. and Teijin Limited anchor this segment through vertically integrated polymer-to-composite chains and carbon fiber-reinforced laminate specialization.
- Automotive:Compression-molded composite structures for underbody protection and front-end carriers lead volume consumption due to cycle-time advantages over thermoset alternatives. Europe's ECHA REACH restrictions on volatile organic compounds redirect investment from solvent-based curing toward thermoplastic organosheet formats.
- Construction:ECHA REACH restrictions on styrene emissions from unsaturated polyester resins accelerate thermoplastic substitution in applications previously dominated by open-mold thermosetting.
- Marine:German industrial safety regulators extend workplace exposure limits that favor closed, automated thermoplastic consolidation processes over traditional open-mold fabrication.
Aerospace captures the highest unit margins, though Automotive generates the largest absolute revenue contribution.
End User:
Buyer concentration patterns determine supplier negotiation leverage and specification control across the value chain.
- OEMs:German and Japanese automotive OEMs increasingly specify material grades and consolidation parameters directly to Tier-2 laminate producers, bypassing traditional Tier-1 system integrators in battery enclosure programs.
- Tier-1 Suppliers:Automotive Tier-1 suppliers in Germany adopt hybrid organosheet-overmolding processes where UD-tape laminates form load-bearing shells subsequently overmolded with short-fiber reinforced ribs.
- Manufacturers:Industrial composite fabricators serve construction and marine applications with lower certification barriers and higher volume flexibility.
- Distributors:Channel partners aggregate demand from fragmented industrial end-users, though direct OEM sourcing compresses their role in high-volume automotive segments.
OEMs hold the dominant procurement position, while Tier-1 Suppliers are expanding their technical influence fastest through process integration investments.
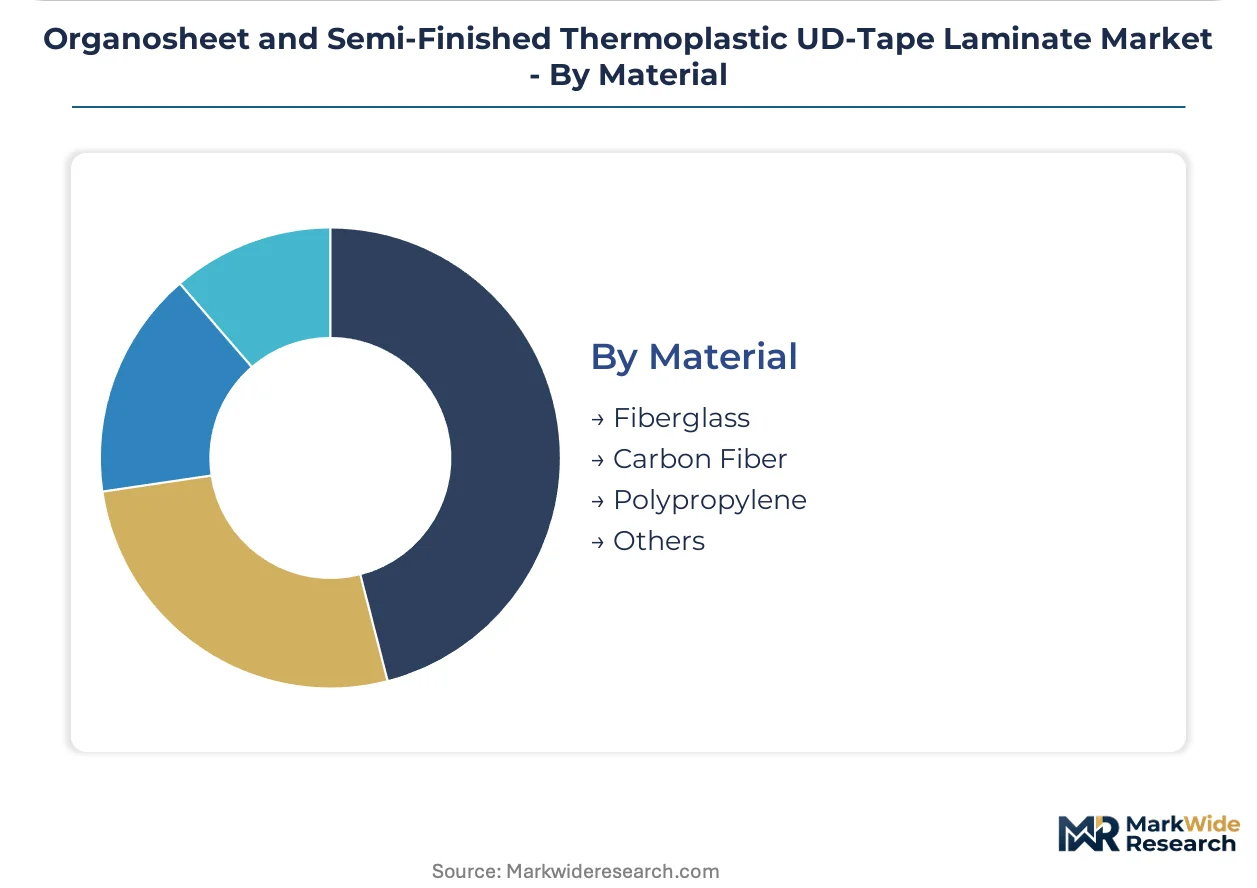
Material:
Fiber and matrix selection dictates performance tier, cost structure, and recyclability credentials in end-of-life vehicle directive compliance.
- Carbon Fiber:Aerospace-grade carbon fiber organosheets command premium positioning through Japanese precursor supply chains concentrated in Teijin Limited and Toray Industries networks, though input cost volatility exposes downstream producers to allocation constraints.
- Fiberglass:E-glass and S-glass reinforced thermoplastics serve cost-sensitive automotive and industrial applications where strength-to-weight ratios must balance against metallic substitution economics.
- Polypropylene:Commodity matrix systems enable lowest-cost organosheet formats for non-structural automotive interior and industrial packaging applications.
- Others:PA6, PA66, and PEEK matrix systems target elevated temperature performance in powertrain-adjacent automotive and specialized industrial applications.
Carbon Fiber maintains the dominant value share, while Fiberglass is expanding volume presence fastest in mass-market automotive programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in thermoplastic organosheets track carbon fiber precursor availability and automotive OEM procurement concentration. Germany and Japan run structural trade surpluses in high-performance laminates, while the United States remains import-dependent for aerospace-qualified material grades.
Germany
Automotive OEMs in Bavaria's supplier corridor are expanding direct procurement of compression-molded battery enclosures. Germany's KBA enforces crash-performance standards that validate organosheet substitution for aluminum in front-end carriers. Lanxess AG anchors European demand through its Tepex-branded platform manufactured in the Brabant chemical cluster.
Japan
Carbon fiber-reinforced laminate demand concentrates in Aichi Prefecture's Nagoya manufacturing belt for hybrid vehicle structures. METI promotes lightweight material adoption through dual carbon goals and domestic supply chain resilience initiatives. Toray Industries and Teijin Limited control precursor and fiber production, exposing downstream converters to allocation constraints.
United States
Aerospace tier-1 suppliers in Washington and California states source qualified organosheets for cabin-interior and structural airframe applications. The FAA maintains stringent flame-smoke-toxicity certification requirements that shape material selection and lock out uncertified supply tiers. Boeing's supplier qualification timelines extend 24-36 months for thermoplastic composite structures.
China
Industrial safety regulators in Jiangsu and Zhejiang provinces are extending workplace exposure limits that favor closed, automated thermoplastic consolidation. MIIT's dual carbon goals accelerate substitution of open-mold thermosetting in construction and marine applications. Domestic precursor capacity expansion is reducing import dependency for mid-grade carbon fiber organosheets.
South Korea
Automotive suppliers in the Busan-Ulsan corridor are integrating UD-tape laminates into electric vehicle underbody protection systems. MFDS workplace chemical exposure standards redirect investment toward solvent-free thermoplastic processing. Hyundai Motor Group's platform engineering teams specify material grades directly to Tier-2 laminate producers for battery enclosure programs.
Organosheet and Semi-Finished Thermoplastic UD-Tape Laminate Market Competitive Landscape
Concentration sits with integrated chemical conglomerates and specialized fiber producers that control polymer-to-composite value chains. The market structures around three tiers: aerospace-qualified specialists with multi-year certification timelines, automotive-scale suppliers with compression-molding expertise, and industrial-grade converters serving construction and marine applications. Dominant competitive moves include backward integration into carbon fiber precursor production and strategic partnerships with robotic tape-laying equipment manufacturers.
Among European chemical conglomerates, Solvay S.A. and Lanxess AG occupy positions anchoring aerospace and automotive demand respectively. Solvay represents the vertically integrated archetype spanning polymer synthesis through qualified composite structures. Lanxess exemplifies the automotive-scale specialist with platform-level OEM relationships. Japanese fiber specialists Toray Industries, Inc. and Teijin Limited sit within the premium-tier vector, controlling precursor supply chains that constrain downstream competition. These four names illustrate how qualification barriers and input material access define competitive positioning across end-use segments.
| Leading Market Players |
|---|
| Solvay S.A. |
| Lanxess AG |
| Teijin Limited |
| Mitsubishi Chemical Corporation |
| Toray Industries, Inc. |
| SABIC |
| BASF SE |
| Owens Corning |
| Covestro AG |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Japanese carbon fiber precursor facilities shapes margin floors across downstream organosheet tiers, compressing pricing power for non-integrated converters while rewarding aerospace-qualified producers with allocation priority during supply crunches.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure where aerospace-grade carbon fiber organosheets command premium positioning over automotive compression-molding grades. Price differentiation separates FAA-certified laminates from uncertified industrial formats, with certification tier and fiber volume fraction as primary drivers. Pricing pressure stems from carbon fiber allocation constraints that favor vertically integrated polymer-to-composite suppliers. Tier-2 laminate producers exhibit highest price sensitivity due to raw material pass-through exposure, while aerospace tier-1 suppliers demonstrate lowest sensitivity given qualification lock-in.
Supply Chain Analysis
Japan and the United States anchor carbon fiber precursor production, with Germany consolidating downstream organosheet conversion for European automotive demand. The supply chain draws from acrylonitrile feedstock, polypropylene and polyamide matrix resins, and robotic tape-laying equipment. Single-source vulnerability concentrates in Japanese precursor supply chains controlled by Toray Industries and Teijin Limited networks. Distribution runs through direct OEM procurement channels that disintermediate traditional Tier-1 system integrators in high-volume battery enclosure programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through multi-year FAA and EASA qualification timelines creates switching costs that protect incumbent positioning.
For Market Incumbents: Fortify aerospace certification portfolios against emerging thermoset substitution threats by accelerating EASA-FAA harmonization compliance. Deepen backward integration into carbon fiber precursor production to neutralize Japanese supply allocation risks. Prioritize capacity addition in Bavaria's automotive corridor to capture KBA-validated battery enclosure procurement. For New Entrants and Emerging Players: Certification fast-track partnerships with South Korean MFDS-aligned testing laboratories offer the most penetrable entry vector for industrial-grade thermoplastic laminates. Target China's Jiangsu and Zhejiang provinces where MIIT workplace safety standards redirect construction and marine demand from open-mold thermosetting. Pursue joint development agreements with robotic tape-laying equipment manufacturers to bypass capital-intensive in-situ consolidation R&D. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aerospace-qualified specialists with locked Boeing and Airbus platform positions. Long-term viability centers on supply chain resilience rather than volume scale, favoring acquisition targets with captive precursor relationships or established Tier-2 direct sourcing contracts. Monitor ECHA REACH enforcement intensity as the inflection signal for thermoset-to-thermoplastic substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Production | Captive acrylonitrile supply secures allocation priority during Japanese fiber export constraints. |
| Aerospace Certification Fast-Track Investment | FAA-EASA dual qualification opens structural airframe contracts with Boeing and Airbus platforms. |
| Robotic Tape-Laying Equipment Partnership | In-situ consolidation integration reduces scrap rates for hybrid organosheet-overmolding processes. |
| Bavaria Corridor Capacity Expansion | Proximity to German OEM platform engineering teams accelerates KBA crash-test validation cycles. |
| Recyclability Certification Program | EU end-of-life vehicle directive compliance creates procurement preference over thermoset alternatives. |
Research Methodology
The analysis maps organosheet formats, UD-tape specifications, and hybrid laminate architectures, each validated through primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, carbon fiber precursor technical directors, and ECHA regulatory affairs specialists. Secondary sources include FAA airworthiness directives, ECHA REACH substance restriction databases, KBA crash-performance test protocols, and customs trade flow data for thermoplastic composite classifications. Bottom-up volume modeling triangulates against top-down OEM procurement budget allocations.
Consistency checks validated outputs against external benchmarks including IHS Markit vehicle production databases, ACC thermoplastic composite demand surveys, and METI lightweight material adoption tracking. Segmentation dimensions span product format, fiber grade, matrix polymer, application sector, and regional production cluster. CAGRs derive from regression analysis of historical procurement volumes correlated with electric vehicle platform ramp schedules and regulatory substitution mandates. Forecast inputs incorporate carbon fiber precursor capacity expansion announcements and robotic tape-laying equipment installation rates.
Decision-makers should treat outputs as directional under assumptions of sustained ECHA REACH enforcement and stable carbon fiber allocation protocols; material deviation in Japanese export policy or FAA certification timeline compression would warrant model refresh. Recalibration cycles align with material shifts in OEM platform standardization decisions and precursor capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Composite Materials
Fiber Reinforced Plastic (FRP) Panels and Sheets Market
Composite Materials
LAMEA Composite Process Material Kits Market
Composite Materials
Copper Clad Laminates Market
Composite Materials
Aramid Fiber Reinforced Polymer Market
Composite Materials
Plastic Composites Market
Composite Materials
Asia-Pacific Molded FRP Grating Market
Composite Materials
Composite Coatings Market
Composite Materials
Polyurethane Composites Market
Composite Materials
Global Carbon Felt and Graphite Felt Market
Composite Materials
Global Composite Resin Market
Composite Materials
Light Curable Flowable Composite Market
Composite Materials
Europe Aluminium Composite Panel Market
Composite Materials
Carbon Fiber Composites Market
Composite Materials
Carbon Fiber Prepreg Market
Composite Materials
Graphite Felt Market
Composite Materials
Glass Fiber Reinforced Plastics (GFRP) Composites Market