
 Clay Coated Paper Market | 2026-2036
Clay Coated Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Clay Coated Paper Market Outlook
Aftermarket service revenue for coating formulation and print-finishing calibration is reconfiguring margin distribution across the value chain. International Paper leverages its North American pulp integration to sustain cost advantages in coated bleached substrates. Mondi Group anchors European supply through controlled forestry assets and specialty packaging grades. WestRock competes via integrated boxboard and converting networks that secure downstream offtake for clay coated output.
Clay coated paper consists of a base paper substrate layered with refined kaolin or calcium carbonate pigments bound by latex or starch adhesives, typically achieving gloss levels of 60-85 GU at 75 degrees for high-fidelity reproduction. The coating fills surface voids to create uniform ink receptivity, serving commercial printing and consumer packaging where visual presentation directly influences purchase behavior. Coated bleached paper occupies the premium tier in publishing and magazine applications where brightness and color fidelity command pricing power. Packaging-grade glossy paper is expanding fastest as brand owners replace plastic sleeves with paper-based alternatives for cosmetics and food cartons. Economy grade segments face compression from uncoated mechanical alternatives in transactional print volumes.
EPA effluent guidelines constrain coating plant discharge in the United States, while REACH registration requirements in Europe govern pigment chemistry and latex additive composition. China's MEE enforces dual carbon compliance on energy-intensive coating lines, reshaping regional cost structures. India's BIS standards for paper and packaging materials create certification barriers that favor organized producers with testing infrastructure. Stakeholders must monitor coating chemistry substitution timelines and carbon border adjustment mechanisms to preserve market access across jurisdictions.
Market Dynamics
Coating chemistry substitution timelines and carbon border adjustment mechanisms are reconfiguring procurement patterns across the clay coated paper value chain, forcing converters to validate pigment sourcing and energy intensity credentials ahead of regulatory enforcement.
Growth Catalysts
- India's PLI scheme for paper-based packaging:Production-linked incentives accelerate domestic capacity expansion for organized producers with BIS certification infrastructure.
- REACH compliance in Europe:Registration requirements for pigment chemistry and latex additives favor established coating plants with ECHA documentation capabilities.
- Cosmetics brand plastic replacement:Premium folding carton demand from beauty and personal care sectors pulls coated bleached substrates into sleeve and box applications.
Market Restraints
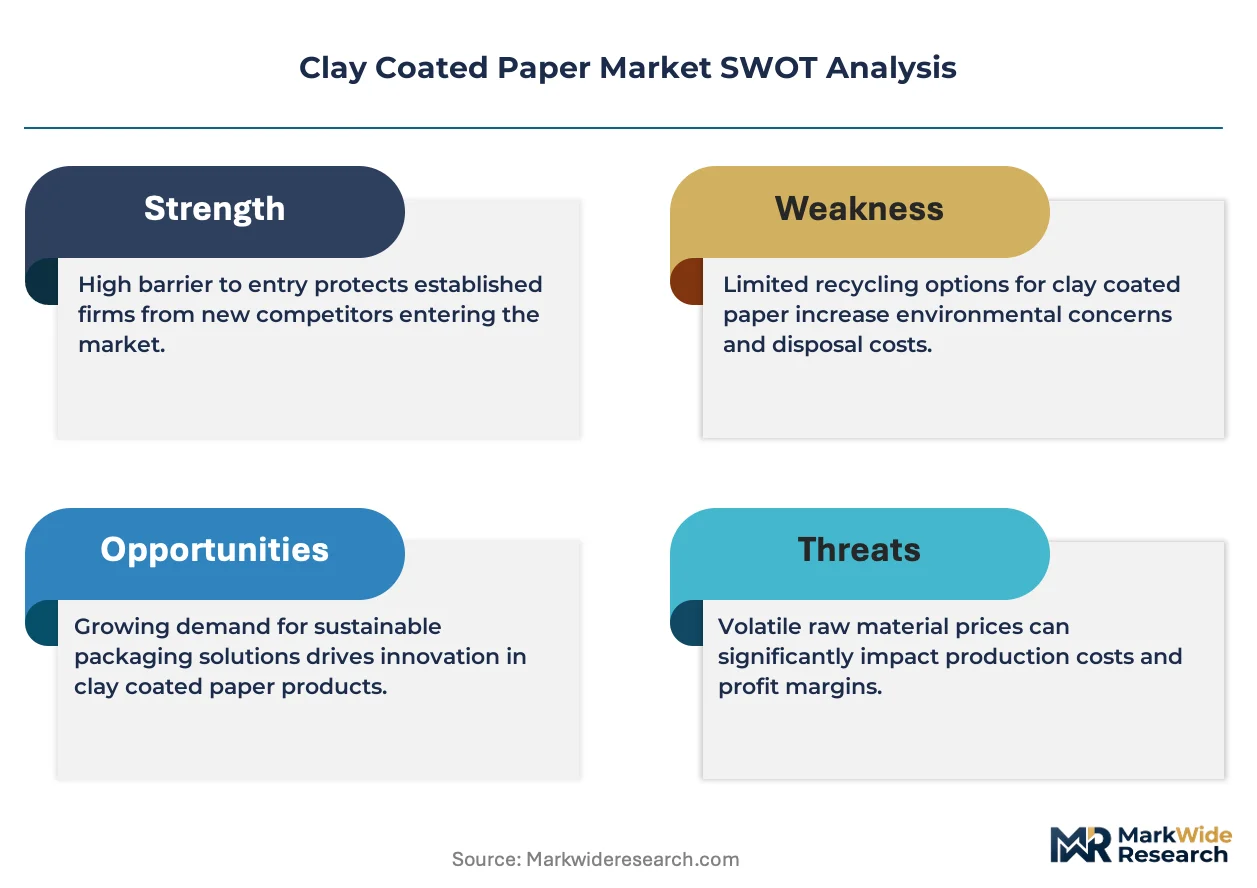
- Kaolin supply concentration:Refined pigment sourcing clusters in specific mining districts, exposing coaters to logistics disruption and input cost volatility.
- Uncoated mechanical substitution:Economy-grade coated paper faces compression from lower-cost alternatives in transactional print and direct mail volumes.
- Dual carbon compliance in China:MEE enforcement on energy-intensive coating lines raises operating costs and limits expansion permits for non-compliant facilities.
Strategic Opportunities
- Food carton barrier coatings:Oxygen and moisture-resistant clay-starch hybrid formulations open penetration into chilled and frozen food packaging previously served by plastic laminates.
- India's BIS certification gap:Testing infrastructure scarcity creates first-mover advantage for organized producers capable of rapid standard compliance.
- Digital print finishing convergence:Inline coating calibration systems enable shorter runs and variable data applications, compressing make-ready times for commercial printers.
Industry Challenges
- Coating formulation talent scarcity:Latex-pigment rheology expertise concentrates among aging technical specialists, constraining plant expansion and product development velocity.
- Effluent treatment capex intensity:EPA discharge guidelines in the United States and MEE standards in China require multimillion-dollar wastewater infrastructure upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clay Coated Paper Market |
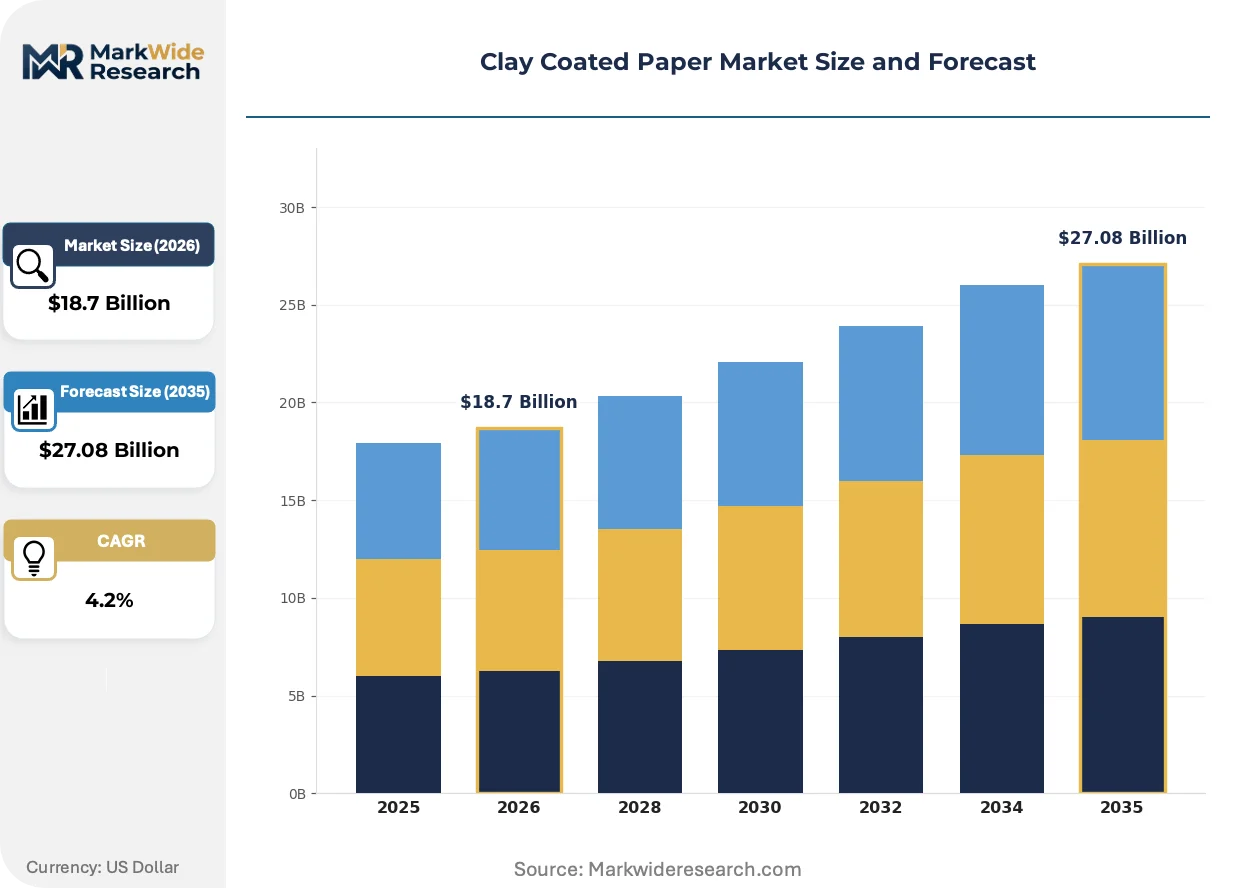
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Unbleached Paper, Coated Bleached Paper, Glossy Paper, Matte Paper End Use Industry: Publishing, Packaging, Printing, Advertising Grade: High-Quality, Standard Quality, Economy Grade, Premium Grade Application: Magazines, Brochures, Labels, Catalogs |
| Companies Covered | International Paper, WestRock, Mondi Group, Stora Enso, Sappi Limited, Nippon Paper Industries, Smurfit Kappa, Oji Holdings Corporation, Graphic Packaging Holding Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clay Coated Paper Market Strategic Shifts
Coating layer functionality and print-finishing integration are advancing faster than base paper substrate evolution, redirecting R&D investment toward surface engineering rather than fiber sourcing.
Barrier-enhanced clay coatings with integrated starch-latex composites are virtualizing the protective function previously delivered by separate plastic laminate films. Food and cosmetics brand owners specify these substrates for premium cartons requiring grease resistance and moisture protection. The technology is virtualizing converter workflows by eliminating secondary lamination steps and reducing material bill complexity.
REACH registration requirements for calcium carbonate and kaolin pigment chemistry are tightening disclosure obligations across European coating operations. ECHA evaluation processes extend lead times for new additive introductions, compressing formulation innovation cycles. Specialty packaging grades with complex multi-layer coatings face the steepest compliance cost escalation, pushing some volume toward simpler single-layer alternatives.
Brand owner sustainability scorecards now mandate recycled fiber content and carbon footprint documentation from coated paper suppliers. Major retailers in Germany and France require chain-of-custody certification for folding cartons, filtering procurement toward integrated producers with controlled forestry assets. This specification tightening is most visible in cosmetics and premium food segments where packaging serves as a visible sustainability signal to consumers.
Clay Coated Paper Market Segmentation
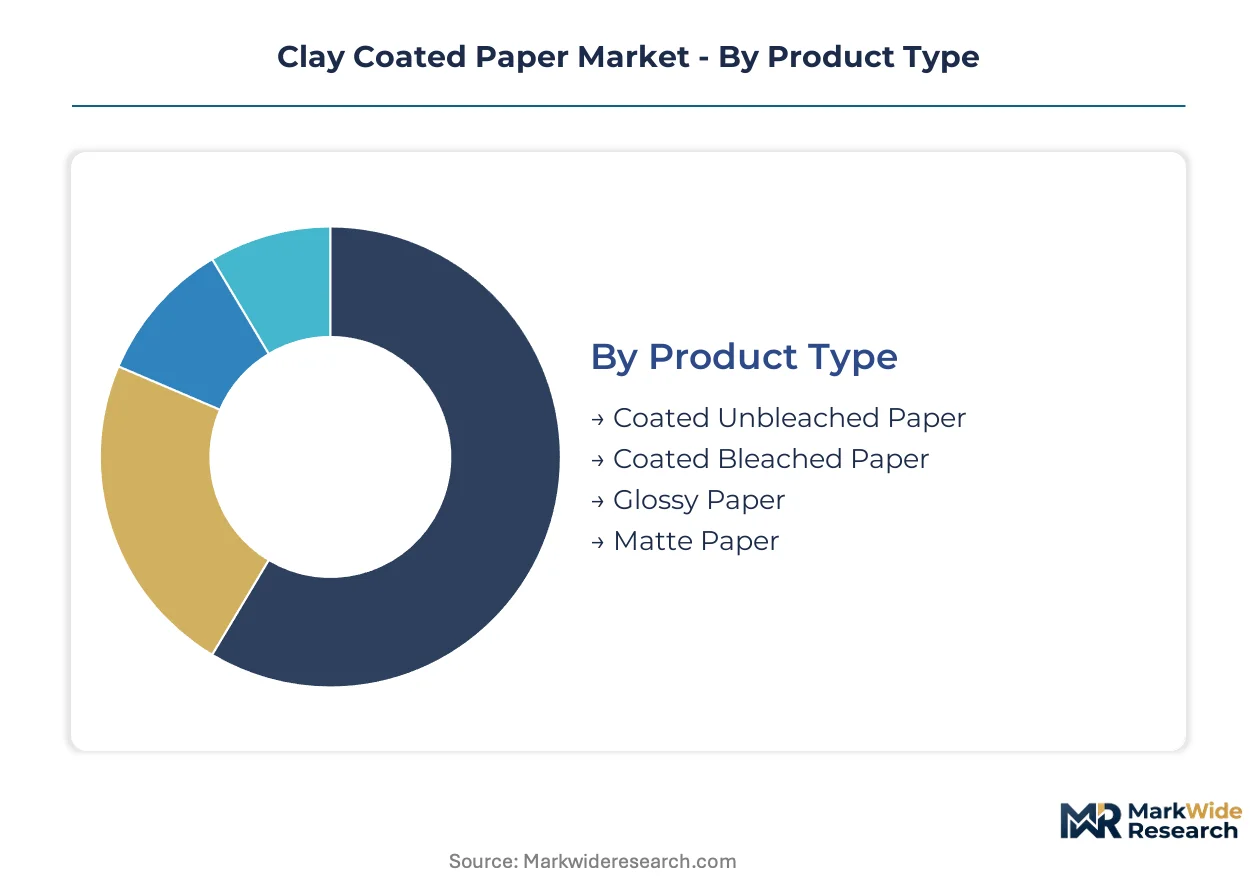
Clay coated paper segmentation reveals how coating chemistry, fiber sourcing, and surface finish specifications align with distinct value tiers and regulatory compliance requirements across publishing and packaging applications. Understanding these divides exposes where margin concentration and capacity expansion capital flow.
Product Type:
Mature segments dominate volume while emerging formulations capture sustainability-driven substitution opportunities.
- Coated Bleached Paper:Brightness levels exceeding 90 ISO and uniform surface porosity enable high-fidelity color reproduction for annual reports and luxury packaging. European cosmetics brands specify this substrate for folding cartons replacing plastic sleeves, driven by ECHA registration requirements for coating chemistry transparency.
- Glossy Paper:Kaolin-starch composites achieve 75-85 GU gloss measurements at 60 degrees, serving magazine covers and promotional inserts where visual impact commands premium pricing. India's PLI scheme for paper-based packaging accelerates domestic capacity for this grade as BIS certification requirements filter out informal producers.
- Coated Unbleached Paper:Retains natural fiber coloration with clay coating for sustainability-positioned food packaging and kraft-style retail bags.
- Matte Paper:Reduced gloss levels suit text-heavy publications and understated luxury packaging where tactile quality outweighs reflective finish.
Coated bleached paper handles the majority of throughput; glossy paper is the fastest mover on share.
End Use Industry:
Application-driven cost tiers separate high-specification packaging from price-sensitive transactional print segments.
- Packaging:Folding cartons for cosmetics, pharmaceuticals, and chilled foods demand barrier-enhanced clay-starch coatings with grease resistance and moisture protection. China's MEE dual carbon enforcement raises energy costs for coating lines serving this segment, reshaping regional supply patterns.
- Publishing:Magazine and book applications concentrate in coated bleached substrates where brightness and opacity specifications meet ISO 12647 color management standards.
- Printing:Commercial sheetfed and web offset operations specify calibrated coating receptivity for consistent ink transfer across variable run lengths.
- Advertising:Direct mail and promotional inserts face compression from uncoated mechanical alternatives and digital channel substitution.
Packaging commands the highest margin tier; advertising contracts most sharply under digital displacement pressure.
Grade:
Customer type stratification separates certified premium supply from commodity volume competing on unit economics.
- Premium Grade:Controlled forestry chain-of-custody certification, carbon footprint documentation, and REACH-compliant coating chemistry serve German and French retailer sustainability scorecards for cosmetics cartons.
- Economy Grade:Transactional print and direct mail volumes face margin compression from uncoated mechanical paper substitution and declining postal advertising spend.
- High-Quality:Magazine and corporate publishing applications balance optical performance with runnability across high-speed web offset presses.
- Standard Quality:General commercial printing and educational materials where brightness specifications moderate cost sensitivity.
Premium grade captures the steepest expansion trajectory; economy grade sheds volume to substitute substrates.
Application:
Volume concentration and margin structure diverge between durable catalog formats and ephemeral promotional materials.
- Magazines:Gloss-coated bleached substrates for consumer titles and controlled-circulation trade publications, with run lengths shortening toward digital print finishing compatibility.
- Labels:Pressure-sensitive and wet-glue applications requiring coating adhesion and die-cutting performance for beverage and personal care brands.
- Brochures:Corporate and tourism marketing collateral with variable data printing requirements driving inline coating calibration adoption.
- Catalogs:Retail and B2B product listings facing structural decline from e-commerce platform substitution and postal cost inflation.
Labels sustain the most resilient demand profile; catalogs confront the steepest structural headwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and France absorb premium pricing for REACH-compliant coated substrates, while Indian converters prioritize unit economics under BIS certification timelines. China's dual carbon enforcement has compressed margins for energy-intensive coating operations.
United States
Packaging converters in Wisconsin and Georgia procure coated bleached grades for cosmetics folding cartons replacing plastic sleeves. EPA effluent guidelines constrain coating plant discharge permits, elevating capital requirements for wastewater infrastructure. The Midwest pulp-to-paper corridor sustains integrated cost advantages for North American coated substrate supply.
Germany
Retail sustainability scorecards from Munich and Hamburg-based brand owners mandate chain-of-custody certification for premium cartons. ECHA registration requirements for kaolin and calcium carbonate pigments extend lead times for new coating formulations. The Baden-Württemberg converting cluster specializes in barrier-enhanced clay-starch hybrids for chilled food applications.
China
Cosmetics manufacturers in Shanghai and Guangzhou specify coated substrates for domestic premium packaging despite margin pressure. MEE enforcement of dual carbon goals limits expansion permits for non-compliant coating lines. The Yangtze River Delta concentration of coating plants faces energy cost restructuring under provincial carbon intensity targets.
India
PLI scheme beneficiaries in Maharashtra and Gujarat accelerate domestic capacity for glossy paper grades serving personal care cartons. BIS certification requirements filter procurement toward organized producers with testing infrastructure. The Vapi industrial corridor hosts expanding coating capacity targeting export markets and domestic brand owner compliance.
Japan
High-specification magazine and commercial printing applications in Tokyo and Osaka sustain demand for calibrated coating receptivity. METI guidance on carbon footprint disclosure shapes supplier selection for publishing houses. The Kanto region's precision converting sector integrates inline coating calibration for shorter digital print runs.
Clay Coated Paper Market Competitive Environment
Capability concentration sits with integrated forest-products groups possessing captive pulp supply and controlled forestry certification; scale advantage sits with diversified packaging converters securing downstream offtake through boxboard networks. The vendor base stratifies across three tiers: multinational integrated producers, regional specialty coaters, and economy-grade mechanical paper competitors. Strategic moves center on backward integration into pulp assets and barrier-coating formulation partnerships with food and cosmetics brand owners.
Within the integrated multinational tier, International Paper exemplifies North American pulp integration advantages, while Mondi Group anchors European supply through specialty packaging grade positioning. WestRock occupies a position at the converter-integrated end, leveraging boxboard and folding carton networks to secure captive demand for clay coated output. These three entities represent distinct archetypes: pulp-captive cost leadership, controlled forestry sustainability premium, and downstream integration security.
| Leading Market Players |
|---|
| International Paper |
| WestRock |
| Mondi Group |
| Stora Enso |
| Sappi Limited |
| Nippon Paper Industries |
| Smurfit Kappa |
| Oji Holdings Corporation |
| Graphic Packaging Holding Company |
| Others |
Value Chain & Pricing Dynamics
Kaolin supply concentration in specific mining districts exposes coaters to logistics disruption that widens spreads between premium REACH-certified grades and economy alternatives while compressing converter margins. This pigment sourcing chokepoint simultaneously determines tiered pricing structures and shapes regional procurement patterns as buyers seek geographic diversification.
Pricing Analysis
Aftermarket service revenue from coating formulation calibration and print-finishing technical support drives lifetime value beyond substrate transactions. Three-tier pricing structure across premium, standard, and economy levels separates certified chain-of-custody grades for German cosmetics brands from BIS-compliant Indian domestic supply and transactional print volumes. Cost compression in economy grades intensifies because uncoated mechanical alternatives capture direct mail spend. Brand owners in beauty and personal care segments exhibit least price sensitivity; postal advertising buyers face acute budget constraints.
Supply Chain Analysis
Export-control scrutiny on coating chemistry intellectual property limits technology transfer for barrier-enhanced clay-starch formulations between European and Asian operations. Supply concentrates in Brazil for refined kaolin, China for calcium carbonate processing, and Finland for controlled forestry pulp. Coating plants draw from latex adhesive specialists in Germany, starch suppliers in Thailand, and pigment refiners in Georgia. Single-source vulnerability runs through kaolin logistics corridors serving the Yangtze River Delta. Distribution runs through integrated packaging converters securing captive offtake via boxboard networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Barrier-enhanced coating adoption for food carton applications signals early-cycle expansion as plastic replacement mandates accelerate specification shifts across cosmetics and chilled food segments.
For Market Incumbents: Harden formulation expertise retention through structured knowledge transfer programs as latex-pigment rheology specialists age out of the workforce. Expand BIS-certified capacity in Maharashtra ahead of PLI scheme maturation to preempt organized competitor entry. Carbon border adjustment mechanisms in Europe threaten margin position for non-compliant coating imports. For New Entrants and Emerging Players: Mid-tier Indian converters lacking in-house coating calibration represent the most penetrable entry point for outsourced formulation services and technical support contracts. Food carton barrier coating partnerships with domestic chilled food brands bypass capital-intensive substrate manufacturing. Technical service bundling unlocks initial relationships before vertical integration into base paper supply. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors controlled forestry assets with REACH documentation infrastructure and downstream converting integration. Five-to-ten year viability rests on carbon intensity credentials and barrier formulation patent positions. Monitor MEE enforcement intensity in Jiangsu province as inflection indicator for Chinese coating capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier Coating R&D Partnership | Cosmetics brand owners in France specify grease-resistant clay-starch hybrids for premium carton applications. |
| Backward Integration into Pulp Assets | Captive bleached softwood supply secures cost position for North American coated substrate producers. |
| BIS Certification Infrastructure Investment | Testing laboratory accreditation filters Indian procurement toward organized producers under PLI scheme. |
| Digital Print Finishing Integration | Inline coating calibration systems at Tokyo commercial printers compress make-ready times for variable data runs. |
| Long-term Supply Agreement with Kaolin Miners | Fixed-price pigment contracts insulate European coaters from logistics disruption in Brazilian mining districts. |
Study Parameters
A spread of perspectives from coating plant technical directors, folding carton procurement managers at cosmetics brands, pulp supply traders, and EPA compliance officers converged on the working assumptions. Primary interviews combined with secondary validation against SEC filings from integrated forest-products groups, ECHA registration databases, and Indian customs import records. Bottom-up capacity modeling triangulated with top-down demand estimation from publishing and packaging end-use surveys.
Demand-supply balance dynamics across bleached pulp availability, coating line energy intensity, and barrier formulation adoption shaped the analytical framework. Segmentation dimensions included coating chemistry type, fiber sourcing grade, surface finish specification, and regional regulatory cluster. CAGRs emerged from installed capacity expansion schedules and substitution elasticity modeling for plastic-to-paper transitions. Kaolin price volatility and dual carbon compliance cost trajectories fed sensitivity scenarios.
Macroeconomic conditions sit as an overlay; deviation in pulp futures pricing and ocean freight rates would shift the trajectory. Forecasts incorporate assumptions on REACH enforcement continuity and PLI scheme extension timelines. Material shifts in MEE carbon intensity targets or BIS certification scope expansion would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper Products
Inkjet Papers and Films Market
Paper Products
Solid Bleached Sulfate (SBS) Board Market
Paper Products
Medium Density Fiberboard Market
Paper Products
Latex-Saturated Paper Market
Paper Products
Global Paperboard Market
Paper Products
Decorative Plastic and Paper Laminates Market
Paper Products
Drum Pulper Market
Paper Products
Dissolving Pulp Market
Paper Products
Unbleached Softwood Kraft Pulp Market
Paper Products
Paper Coating Materials Market
Paper Products
North America Coated Paper Market
Paper Products
Europe Paper Market
Paper Products
Pharma Grade Paper Market
Paper Products
Solar Paper Market
Paper Products
Household Paper Market
Paper Products
Semi Chemical Wood Pulp Market