
 Digital Reading Micropipettes Market | 2026-2036
Digital Reading Micropipettes Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Reading Micropipettes Market Insights
Calibration subscription services is realigning vendor-customer relationships in the Digital Reading Micropipettes space. Eppendorf leverages its German manufacturing base to sustain premium positioning across academic and industrial accounts. Thermo Scientific competes through extensive distribution networks that anchor North American and Asian market penetration. Sartorius differentiates via integrated bioanalytical workflows that extend beyond standalone pipetting into automated liquid handling platforms.
Digital reading micropipettes are precision volumetric instruments employing piston-driven displacement with optical or capacitive sensors to deliver liquid volumes ranging from sub-microliter to milliliter scales, primarily serving quantitative analytical procedures in life sciences and clinical testing. Multi-channel configurations command structural priority in high-throughput pharmaceutical screening where parallel processing reduces assay cycle times. Stainless steel components concentrate margin pools due to durability requirements under repeated autoclaving cycles in GLP-regulated environments. Research laboratories represent the deepest installed base, though clinical diagnostics applications are expanding fastest as point-of-care molecular testing protocols standardize electronic pipetting steps.
FDA quality system regulations and ISO 8655 standards govern accuracy verification protocols, compelling manufacturers to embed traceable calibration certificates and software audit trails as default deliverables. EPA Good Laboratory Practice guidelines and EMA GMP Annex 1 updates further tighten documentation requirements for pipettes used in environmental and pharmaceutical testing workflows. Stakeholders must monitor evolving harmonization between regional metrology institutes and software validation frameworks as cloud-connected pipettes introduce cybersecurity compliance dimensions alongside traditional volumetric performance criteria.
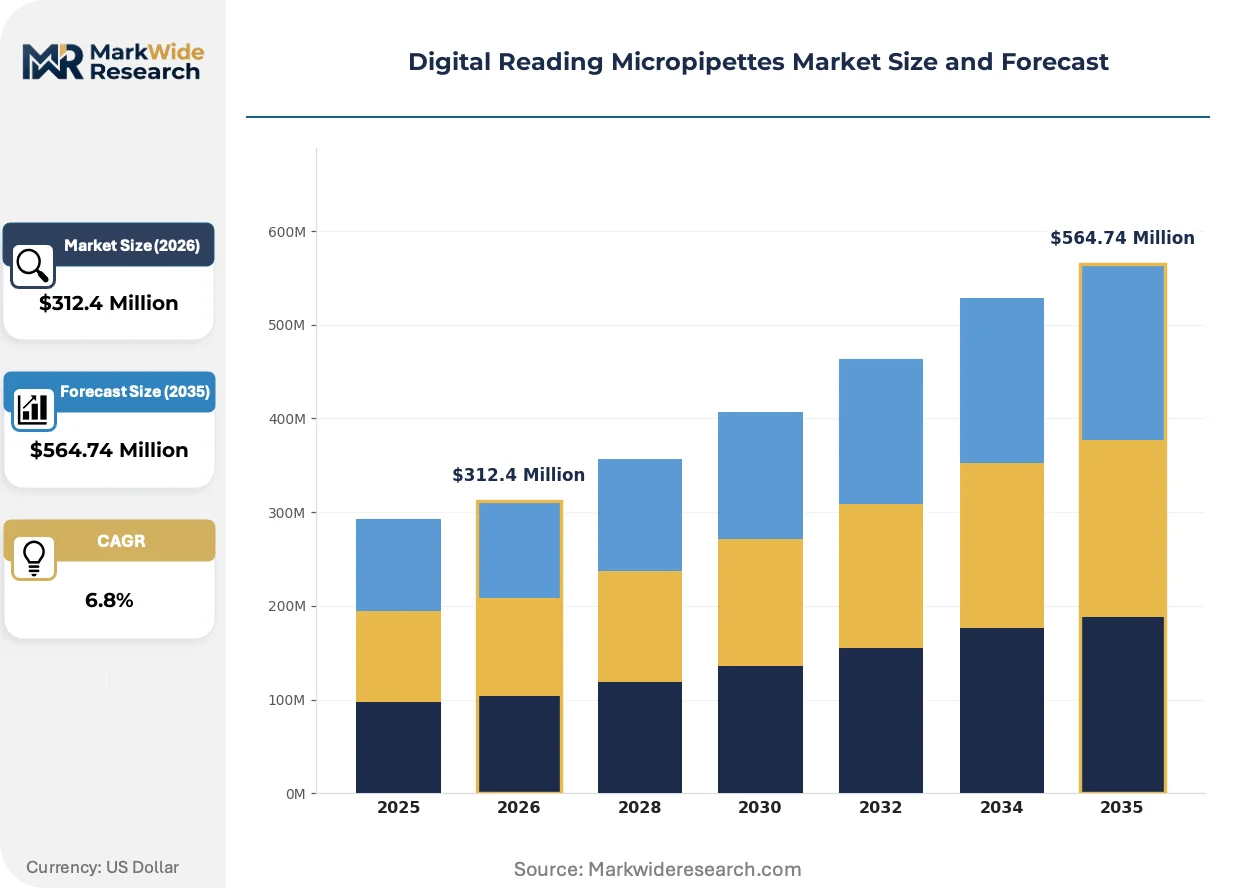
Market Dynamics
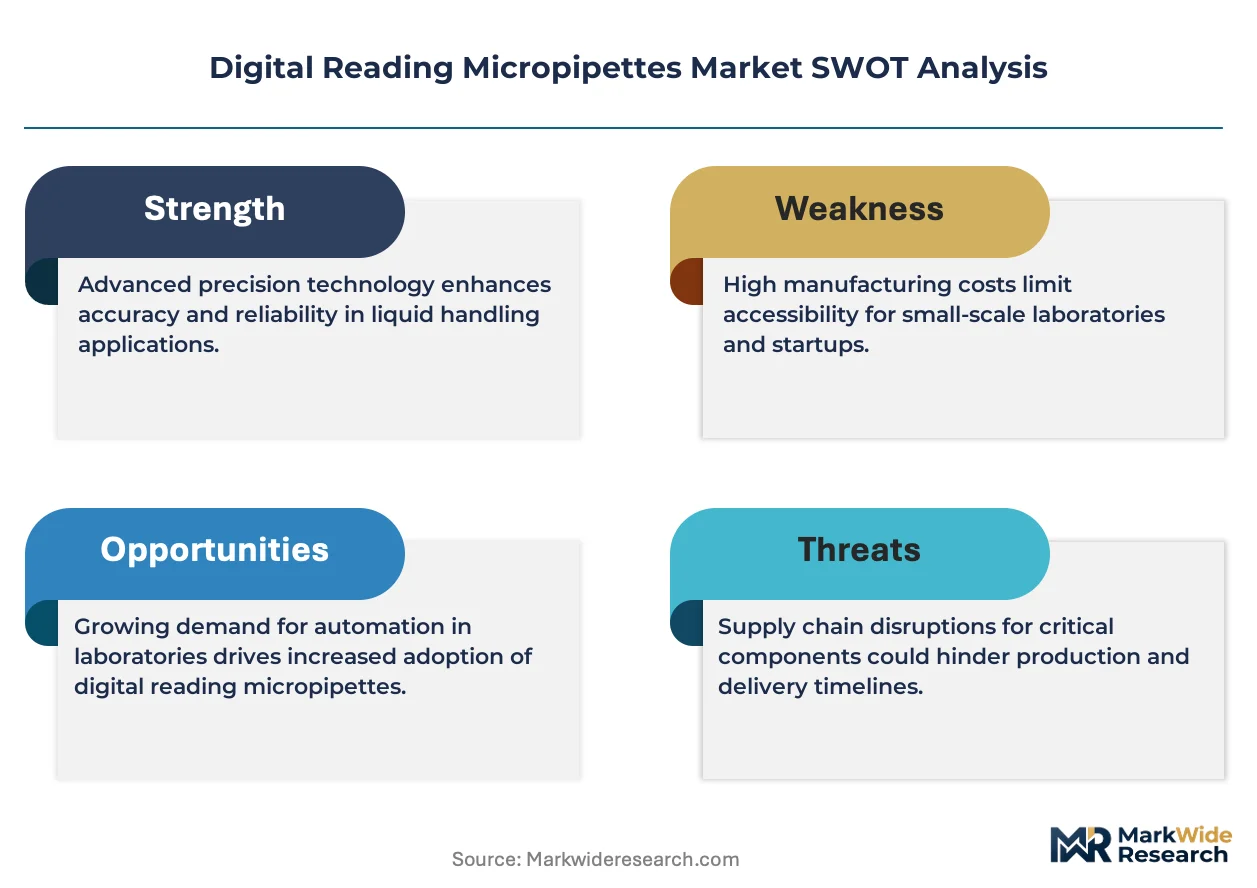
Calibration-as-a-service models are restructuring vendor-customer relationships in precision liquid handling, converting capital equipment sales into recurring revenue streams that lock laboratories into multi-year accuracy verification contracts.
Growth Catalysts
- ISO 8655 calibration mandates:FDA quality system regulations and EPA Good Laboratory Practice guidelines compel pharmaceutical and environmental testing facilities to maintain traceable volumetric accuracy records, driving replacement cycles for non-compliant mechanical pipettes.
- High-throughput screening expansion:Biopharmaceutical contract research organizations in Germany and Massachusetts are standardizing multi-channel electronic pipetting platforms to compress assay cycle times in drug discovery workflows.
- Point-of-care molecular diagnostics:Clinical laboratories in Japan and South Korea are adopting battery-powered digital micropipettes with onboard data logging to standardize nucleic acid extraction protocols outside centralized facilities.
Market Restraints
- Premium stainless steel input costs:Autoclavable piston assemblies and tip cones require surgical-grade alloys whose price volatility compresses margins on mid-tier product lines.
- German manufacturing concentration:Precision machining clusters around Hamburg and Göttingen create geographic supply risk for optical encoder components and capacitive sensor modules.
- Manual pipette substitution persistence:Academic laboratories in India and Brazil continue purchasing mechanical volume-adjustable pipettes where capital constraints override accuracy requirements.
Strategic Opportunities
- Cloud-connected calibration ecosystems:Integration of pipette performance data with laboratory information management systems creates platform stickiness and recurring software subscription revenue.
- Cell and gene therapy manufacturing:GMP-grade aseptic filling operations require certified electronic pipettes with sealed electronics and gamma-sterilizable surfaces.
- Southeast Asia laboratory buildouts:Singapore's Biopolis and Thailand's Eastern Economic Corridor are attracting contract manufacturing organizations that specify ISO 8655-compliant liquid handling infrastructure.
Industry Challenges
- Metrology technician scarcity:Gravimetric calibration procedures require certified personnel capable of operating analytical balances in controlled humidity environments, creating hiring bottlenecks for service organizations.
- Legacy LIMS integration friction:Older laboratory information systems lack API connectivity for real-time pipette performance telemetry, forcing middleware development costs.
- Software validation timelines:FDA 21 CFR Part 11 compliance for electronic records extends product launch schedules by 8-14 months for cloud-enabled devices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Reading Micropipettes Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Channel, Multi-Channel, Adjustable Volume, Fixed Volume End User: Research Laboratories, Pharmaceutical Companies, Clinical Laboratories, Educational Institutions Material: Plastic, Stainless Steel, Aluminum, Glass Application: Liquid Handling, Sample Preparation, Molecular Biology, Diagnostics |
| Companies Covered | Eppendorf, Gilson, Sartorius, Thermo Scientific, Avantor, Accumax, Corning, Hamilton, Socorex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Reading Micropipettes Market Trends and Innovations
Wireless connectivity and embedded sensors are transforming standalone pipettes into networked laboratory endpoints, enabling predictive maintenance algorithms and remote audit capabilities that reshape compliance workflows.
Capacitive liquid level detection is decentralizing volume verification away from external gravimetric stations. Pharmaceutical quality control laboratories in Switzerland and the Netherlands are deploying pipettes with onboard pressure sensors that self-correct for temperature-induced thermal expansion errors. This capability compresses calibration intervals from quarterly to event-triggered, reducing labor costs while tightening process control.
EMA GMP Annex 1 revisions and FDA sterile manufacturing guidance are tightening particulate and bioburden specifications for liquid handling in aseptic processing. Single-use tip ejection systems with HEPA-filtered enclosures are displacing open-bench pipetting in cell therapy manufacturing suites. European contract development organizations are retrofitting cleanroom facilities to accommodate these barrier-isolated electronic pipetting stations.
Service unbundling is fragmenting traditional equipment procurement. Academic core facilities in California and Massachusetts now separate hardware acquisition from calibration contracts, soliciting competitive bids for ISO 17025-accredited service providers independent of manufacturer relationships. This purchasing pattern pressures OEMs to defend attachment rates through proprietary sensor architectures that restrict third-party verification access.
Digital Reading Micropipettes Market Segmentation
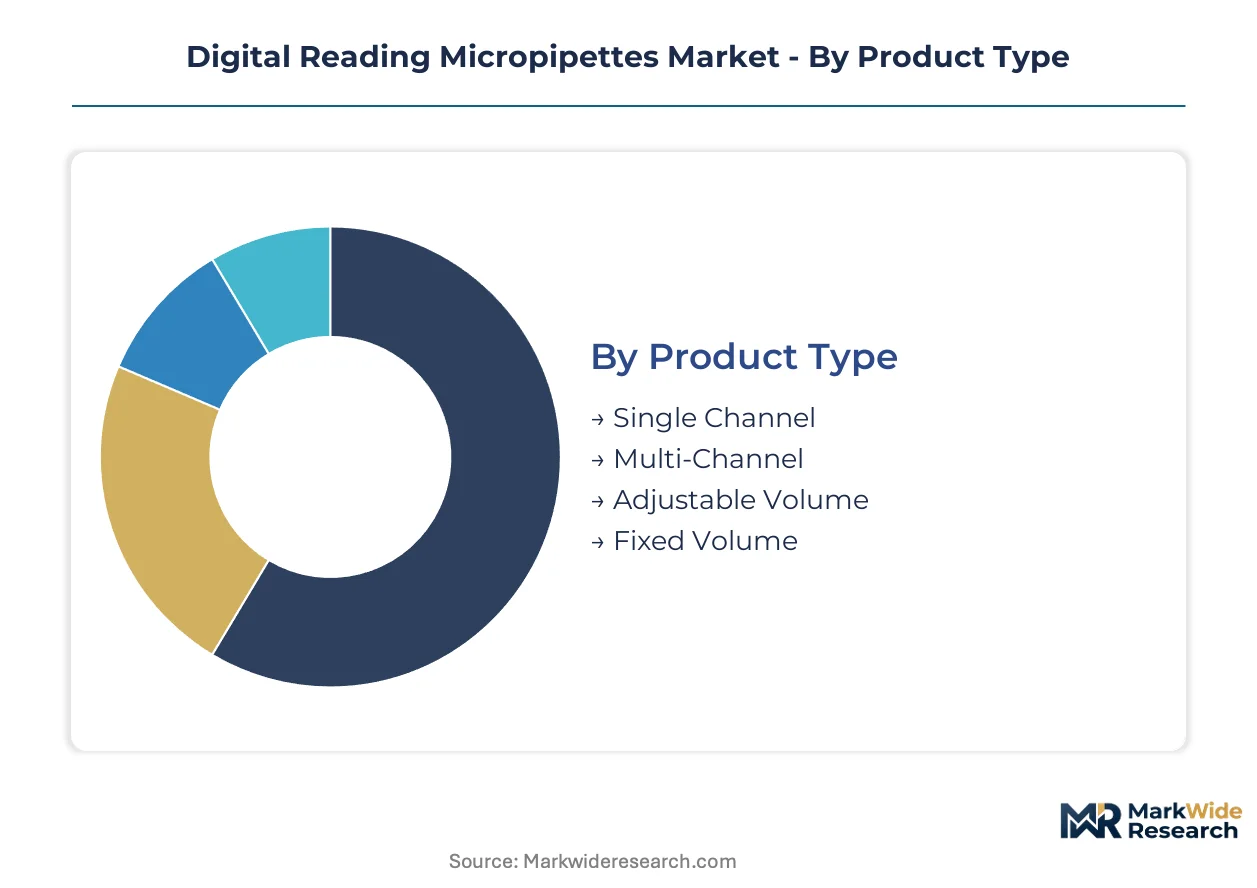
Digital reading micropipettes fragment across four structural dimensions that reshape procurement patterns and margin pools. Product architecture determines whether instruments operate as standalone devices or integrate into automated liquid handling platforms. End-user concentration in regulated pharmaceutical environments versus cost-constrained academic settings creates divergent specification requirements across segments.
Product Type:
Integration depth separates standalone manual operation from embedded automation compatibility, with channel configuration and volume adjustability defining system architecture choices.
- Single Channel:Piston-driven displacement mechanisms with optical encoders deliver 0.1 µL to 10 mL ranges for serial dilution workflows. Pharmaceutical quality control laboratories in Germany specify these for USP-compliant volumetric verification where traceability trumps throughput.
- Multi-Channel:Parallel piston arrays with synchronized capacitive sensors enable 8- to 384-tip configurations for microplate-based assays. Contract research organizations in Massachusetts compress ELISA and qPCR cycle times through standardized 12-channel electronic platforms.
- Adjustable Volume:Motorized spindle mechanisms with digital position feedback span overlapping nominal ranges. Academic core facilities prioritize these for protocol flexibility across diverse research programs.
- Fixed Volume:Locked piston stops eliminate mechanical adjustment points, reducing calibration drift in high-frequency pipetting stations. Clinical diagnostics manufacturers specify these for standardized nucleic acid extraction kits.
Single-channel instruments lead volumes today; multi-channel configurations are gaining share fastest in high-throughput screening deployments.
End User:
Cost tier stratification separates capital-rich regulated industries from budget-constrained educational procurement, with compliance burden intensity determining specification floors.
- Research Laboratories:University core facilities and government institutes constitute the deepest installed base. Funding volatility from NIH and NSF grant cycles creates replacement lag for mechanical-to-digital upgrades.
- Pharmaceutical Companies:GLP and GMP compliance mandates drive ISO 8655-certified electronic pipetting with embedded software audit trails. FDA 21 CFR Part 11 validation requirements extend procurement cycles but lock in premium pricing tiers.
- Clinical Laboratories:Hospital systems and reference laboratories are expanding fastest as point-of-care molecular testing protocols standardize electronic pipetting steps. CAP accreditation requirements tighten accuracy verification documentation.
- Educational Institutions:Undergraduate teaching laboratories represent price-sensitive volume with minimal accuracy requirements. Indian and Brazilian universities continue mechanical pipette procurement where capital constraints override precision specifications.
Research laboratories dominate installed base today; clinical laboratories are climbing the fastest as decentralized diagnostics expand.
Material:
Autoclaving durability requirements and gamma-sterilization compatibility separate premium metal architectures from disposable polymer economics.
- Stainless Steel:Surgical-grade 316L alloys withstand repeated autoclaving cycles and aggressive chemical decontamination. Cell therapy manufacturing suites in Switzerland specify these for GMP-grade aseptic filling operations.
- Plastic:Engineering polymers reduce unit costs for high-throughput operations with single-use tip ejection systems. Lightweight construction suits battery-powered field diagnostics in Southeast Asia.
- Aluminum:Anodized alloys balance thermal conductivity with corrosion resistance for temperature-sensitive reagent handling. Mid-tier product lines target contract manufacturing organizations seeking durability without stainless steel premiums.
- Glass:Borosilicate barrels remain niche for organic solvent compatibility where polymer degradation risks contaminate assays. Specialty pharmaceutical synthesis applications specify these for API handling.
Plastic dominates unit volumes today; stainless steel commands expanding share in regulated sterile manufacturing environments.
Application:
Protocol standardization maturity determines whether digital pipettes displace mechanical alternatives or defend existing electronic installed base.
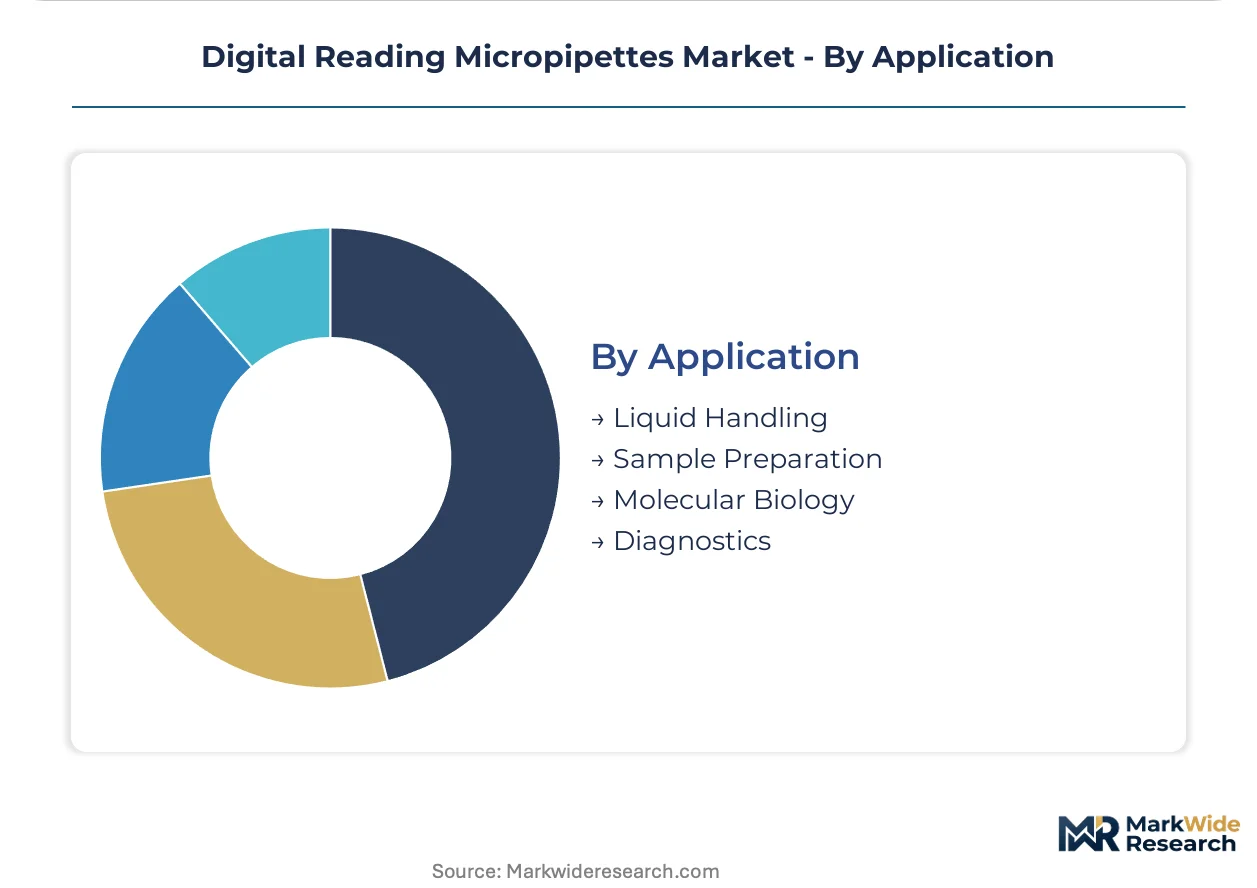
- Liquid Handling:General-purpose transfer operations span reagent dispensing, buffer preparation, and standard solution making. Pharmaceutical formulation laboratories specify multi-channel platforms for buffer exchange workflows.
- Sample Preparation:Nucleic acid extraction and protein purification protocols demand precise volumetric ratios. Clinical laboratories in Japan standardize battery-powered digital micropipettes for decentralized PCR preprocessing.
- Molecular Biology:PCR setup, cloning reactions, and sequencing library preparation require sub-microliter accuracy. Academic genomics cores prioritize single-channel electronic pipettes for master mix assembly.
- Diagnostics:Immunoassay and clinical chemistry workflows integrate pipetting into automated analyzer feed systems. IVD manufacturers in South Korea embed digital pipetting modules into point-of-care platforms.
Liquid handling leads application volumes today; diagnostics is expanding most quickly as decentralized testing protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision manufacturing for digital micropipettes, while the United States drives pharmaceutical adoption through FDA-regulated quality systems. Japan and South Korea are expanding clinical diagnostics deployment. China and India present divergent trajectories in laboratory infrastructure investment.
Germany
Pharmaceutical quality control laboratories in Hamburg and Göttingen anchor demand for ISO 8655-certified electronic pipetting systems. EMA GMP Annex 1 revisions tighten sterile manufacturing specifications for liquid handling instruments. The precision machining cluster around Lower Saxony manufactures optical encoder components for multi-channel platforms.
United States
Biopharmaceutical contract research organizations in Massachusetts standardize high-throughput screening workflows with multi-channel electronic pipettes. FDA 21 CFR Part 11 validation requirements extend procurement cycles for cloud-connected devices. The Greater Boston biotech corridor drives replacement demand from mechanical to digital platforms.
Japan
Hospital systems in Tokyo and Osaka deploy battery-powered digital micropipettes for point-of-care molecular diagnostics. PMDA quality system regulations govern accuracy verification protocols for clinical testing instruments. The Kanto region's reference laboratories standardize electronic pipetting for nucleic acid extraction protocols.
South Korea
IVD manufacturers in Seoul and Busan embed digital pipetting modules into automated analyzer platforms. MFDS medical device regulations mandate traceable calibration certificates for diagnostic liquid handling. The Songdo biocluster attracts contract manufacturing organizations specifying ISO 8655-compliant infrastructure.
China
Academic core facilities in Beijing and Shanghai prioritize adjustable-volume electronic pipettes for protocol flexibility across research programs. NMPA medical device registration requirements tighten documentation for imported precision instruments. The Yangtze River Delta concentrates domestic manufacturing of polymer-based pipette components.
Digital Reading Micropipettes Market Competitive Landscape
Top-tier vendors anchor premium positioning through German manufacturing bases, while mid-tier specialists compete on regional distribution density. The vendor base stratifies across three tiers: precision instrument conglomerates with integrated bioanalytical workflows, laboratory equipment specialists with calibration service networks, and regional fabricators targeting price-sensitive academic procurement. Two dominant competitive moves are reshaping positioning: calibration-as-a-service subscriptions converting capital sales into recurring revenue, and cloud connectivity integration creating platform stickiness through LIMS interoperability.
Within the precision instrument tier, Eppendorf and Sartorius represent archetypes of vertically integrated manufacturers leveraging domestic German machining clusters to defend premium positioning. Thermo Scientific occupies a position exemplifying extensive North American and Asian distribution networks. These three entities anchor the competitive structure, with Eppendorf and Sartorius representing integrated workflow specialists and Thermo Scientific exemplifying scale-driven geographic penetration strategies.
| Leading Market Players |
|---|
| Eppendorf |
| Gilson |
| Sartorius |
| Thermo Scientific |
| Avantor |
| Accumax |
| Corning |
| Hamilton |
| Socorex |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between ISO 8655-compliant systems and uncertified alternatives manifests in both pricing premiums and supply chain sourcing strategies. Pharmaceutical buyers in Germany and Massachusetts absorb tiered pricing spreads for traceable calibration certificates, while academic procurement in India and Brazil filters toward polymer-based instruments sourced through regional distributors.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for polymer-based pipette components. Three-tier pricing structure across premium, standard, and economy levels separates GMP-grade stainless steel systems with embedded software audit trails from battery-powered field units and mechanical teaching-laboratory alternatives. Price differentiation stems from ISO 8655 certification grade and vertical integration depth in optical encoder manufacturing. Cost compression in mid-tier aluminum product lines is intensifying because surgical-grade alloy volatility compresses margins. Educational institutions in emerging markets exhibit highest price sensitivity; GLP-regulated pharmaceutical facilities demonstrate lowest sensitivity due to compliance lock-in.
Supply Chain Analysis
Single-source vulnerability sits with Germany's precision machining clusters around Hamburg and Göttingen for capacitive sensor modules and optical encoder components. Geographic supply concentration centers on Germany, China, and Japan. Raw material dependencies draw from surgical-grade 316L stainless steel, engineering polymers, and specialized glass for borosilicate barrels. Supply chain risk stems from geographic concentration of precision machining capability for regulatory-grade components. Distribution runs through manufacturer-direct service contracts for pharmaceutical accounts and laboratory equipment distributors for academic procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital reading micropipettes constitute a late-cycle quality story as decentralized molecular diagnostics in Japan and South Korea shift procurement specifications toward battery-powered, data-logging platforms with traceable calibration ecosystems.
For Market Incumbents: To counter unbundling of calibration services from hardware sales, Eppendorf and Sartorius should deepen proprietary sensor architectures that restrict third-party verification access. Capacity additions in Southeast Asian service hubs can defend attachment rates for ISO 17025-accredited maintenance contracts against independent service providers. For New Entrants and Emerging Players: Cloud-native calibration platforms with API-first LIMS integration represent the most penetrable wedge for displacing legacy installed base. Target clinical diagnostics manufacturers in South Korea seeking embedded pipetting modules for point-of-care platforms. A software-subscription-first go-to-market angle bypasses capital-intensive German machining requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier specialists lack captive supply of optical encoder components. Long-term viability favors vertically integrated manufacturers with in-house precision machining and recurring service revenue streams. Acquisition target archetype: regional distributors with ISO 17025-accredited calibration laboratories. The signal to watch is unbundling penetration in academic core facilities as a leading indicator of pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration-as-a-Service Platform Launch | Converts Eppendorf's German installed base into recurring revenue with multi-year accuracy verification contracts. |
| Cloud-Connected Pipette Development | Thermo Scientific's LIMS interoperability investments create platform stickiness through predictive maintenance algorithms. |
| Southeast Asian Service Hub Expansion | Singapore's Biopolis proximity enables same-day calibration response for CMOs specifying ISO 8655 infrastructure. |
| Single-Use Tip Ejection System Certification | HEPA-filtered enclosures address EMA GMP Annex 1 particulate specifications for cell therapy manufacturing suites. |
| Battery-Powered Field Diagnostics Partnership | Japanese hospital systems standardize decentralized PCR preprocessing with onboard data logging capabilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged laboratory equipment procurement managers at pharmaceutical quality control facilities, biomedical engineers at clinical diagnostics manufacturers, GPO contracts managers at hospital systems, and calibration service technicians at ISO 17025-accredited laboratories. Secondary validation drew from FDA 510(k) filings for electronic pipetting devices, EMA GMP Annex 1 revision documentation, NMPA medical device registration databases, and customs trade data for precision instrument imports. Bottom-up demand modeling triangulated against top-down manufacturer capacity assessments.
Comparable-period anchoring linked historical replacement cycles for mechanical-to-digital upgrades across the projection horizon. The analytical framework modeled volume and value outputs across product architecture, channel configuration, end-user compliance tier, and regional regulatory cluster dimensions. CAGRs were derived from instrument shipment trajectories weighted by average selling price evolution. Industry-specific forecast inputs incorporated ISO 8655 calibration mandate adoption curves and point-of-care molecular diagnostics protocol standardization rates.
The model holds under stable regulatory enforcement of FDA 21 CFR Part 11 and EPA Good Laboratory Practice guidelines; deviation in harmonization timelines between regional metrology institutes would shift replacement cycle assumptions. Cloud-connected device cybersecurity compliance emergence represents an unmodeled upside risk. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Next-Generation Neurofeedback Device Market
Medical Devices
Global Electrophysiology Devices Market
Medical Devices
Alexandrite Gemstone Lasers Market
Medical Devices
Global Medical Implants Market
Medical Devices
Non-Invasive Intracranial Pressure Monitoring Device Market
Medical Devices
Human Augmentation in Healthcare Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Global Medical Injection Molding Market
Medical Devices
Global Laparoscopy Devices Market
Medical Devices
Intravenous Access Devices Market
Medical Devices
Global Medical Suction Devices Market
Medical Devices
Capsule Endoscope Systems Market
Medical Devices
3D Printed Hip and Knee Implants Market
Medical Devices
Corneal Cross Linking Devices Market
Medical Devices
Wireless ECG Devices Market
Medical Devices
Battery-Operated Lactate Meter Market