

Flaxseed Gum Market Size, Share, and Industry Trends Forecast 2026-2036
Flaxseed Gum Market Insights
Asset-light toll manufacturing and third-party extraction leasing is fragmenting competitive entry barriers in flaxseed gum supply. Cargill leverages backward integration into Canadian seed origination to secure raw material throughput. Kerry Group differentiates through application-specific hydration systems for meat processing binders. ADM competes on multi-plant hydrocolloid infrastructure that extends formulation service capabilities.
Flaxseed gum comprises arabinoxylan-rich polysaccharides extracted from Linum usitatissimum seed coat, typically yielding 6-10% dry-weight gum with cold-water solubility exceeding 80% in refined grades. The extract functions primarily as a viscosifier, emulsion stabilizer, and water-binding agent across food matrices. Soluble fiber grades command premium positioning in digestive health positioning, while mucilage gum variants anchor traditional bakery applications with established formulation familiarity. Dairy alternatives represent the fastest-growing application pool, driven by plant-based beverage emulsion stability requirements.
Health Canada governs novel fiber health claims through its Food Directorate, while the FDA regulates dietary fiber declarations under post-2016 Nutrition Facts modernization. EFSA evaluates viscosity-related digestive health substantiation for EU market access. Stakeholders must monitor evolving fiber quantification methodologies across Health Canada, FDA, and EFSA frameworks, as divergent analytical standards threaten cross-border formulation consistency.
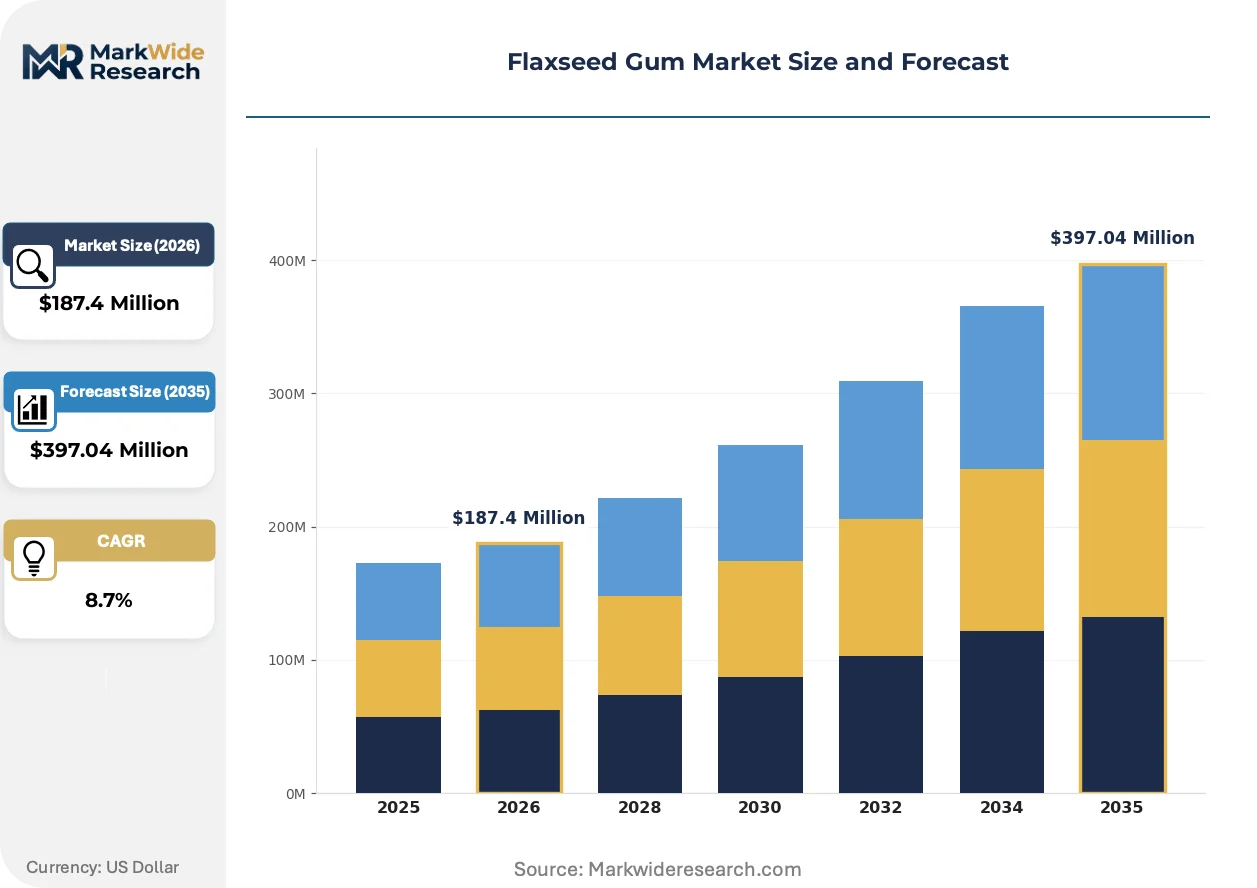
Market Dynamics
The Flaxseed Gum Market pivots on FDA's 2016 Nutrition Facts modernization, which reclassified gum constituents as dietary fiber and triggered reformulation waves across North American clean-label bakery and dairy-alternative portfolios.
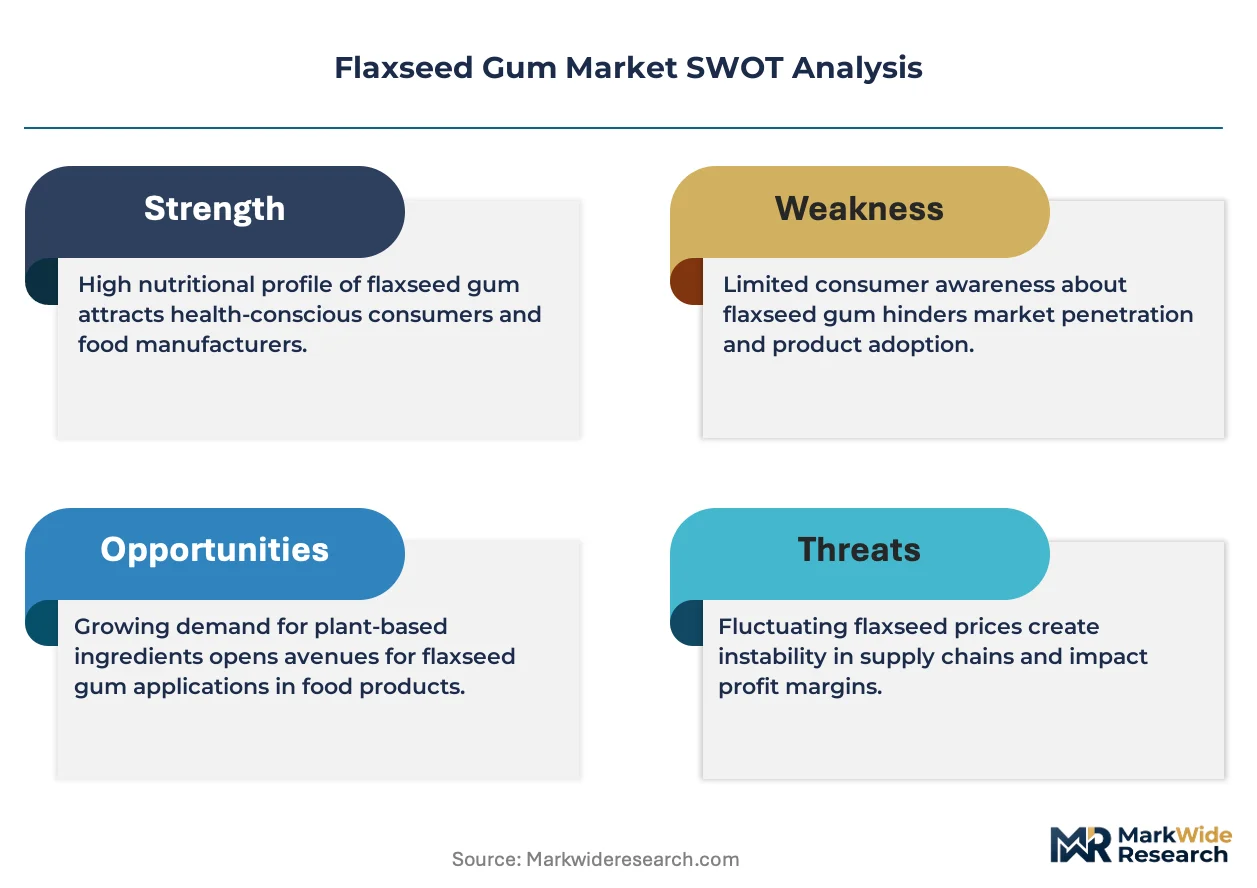
Growth Catalysts
- Clean-label bakery demand:North American manufacturers are stripping synthetic hydrocolloids from ingredient decks. Flaxseed gum's plant-derived viscosity profile satisfies consumer transparency expectations while maintaining dough handling properties.
- EFSA viscosity substantiation pathway:European digestive health claims now accept arabinoxylan-rich polysaccharide evidence. This regulatory clarity accelerates premium positioning for soluble fiber grades in functional foods.
- Prairie cultivation corridors:Canadian flaxseed production clusters in Saskatchewan and Manitoba provide contiguous raw material access. Proximity reduces extraction-to-refinement transport costs for toll manufacturers.
Market Restraints
- Seed coat yield volatility:Gum extraction yields 6-10% dry-weight, creating raw material intensity. Linum usitatissimum harvest fluctuations in Canadian prairies directly compress processor margins.
- Cold-water solubility specification gaps:Unrefined grades fall below 80% solubility thresholds required by plant-based beverage formulators. Technical limitations restrict addressable market penetration in fastest-growing applications.
- Locust bean gum substitution:Established hydrocolloid alternatives with deeper formulation familiarity and price stability threaten displacement in traditional bakery binders.
Strategic Opportunities
- Meat processing hydration systems:Application-specific binders for clean-label processed meats represent underdeveloped territory. Kerry Group's existing systems demonstrate technical feasibility for broader adoption.
- Health Canada novel fiber claims:The Food Directorate's evolving substantiation framework creates first-mover advantage for dossier-ready suppliers seeking digestive health positioning.
- Multi-plant hydrocolloid infrastructure leverage:ADM's distributed extraction assets enable formulation service bundling that smaller toll operators cannot replicate.
Industry Challenges
- Analytical standard divergence:Health Canada, FDA, and EFSA employ non-harmonized fiber quantification methodologies. Cross-border formulation consistency requires redundant testing protocols.
- Application-specific hydration expertise:Meat and dairy-alternative matrices demand tailored viscosity profiles. Technical talent scarcity in hydrocolloid-food matrix interaction slows product development cycles.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flaxseed Gum Market Trends and Innovations
Digital extraction monitoring and enzyme-assisted refinement are compressing batch-to-batch variability while enabling real-time quality adjustment. These capabilities reshape competitive differentiation beyond raw material access.
Enzyme-assisted cold extraction is virtualizing traditional hot-water gum recovery. This technology preserves arabinoxylan molecular weight distributions essential for premium viscosity performance. Plant-based beverage formulators in Canada and the US are adopting refined grades at accelerated pace. The process is virtualizing capital-intensive thermal infrastructure requirements, lowering entry barriers for regional toll processors.
REACH compliance costs for imported hydrocolloid additives are redirecting European formulator procurement toward domestic-origin alternatives. EFSA's evolving fiber definition creates regulatory alignment pressure with FDA frameworks. Bakery and dairy-alternative manufacturers in Germany and France are qualifying Canadian flaxseed gum suppliers to preempt supply chain disruption.
Direct-procurement relationships between food manufacturers and Prairie extraction facilities are displacing traditional ingredient distributor intermediation. Large-scale bakery and meat-processing buyers are consolidating supplier panels to secure volume commitments. This concentration is most visible across US Midwest and Ontario manufacturing corridors where clean-label reformulation timelines compress sourcing decision cycles.
Flaxseed Gum Market Segmentation
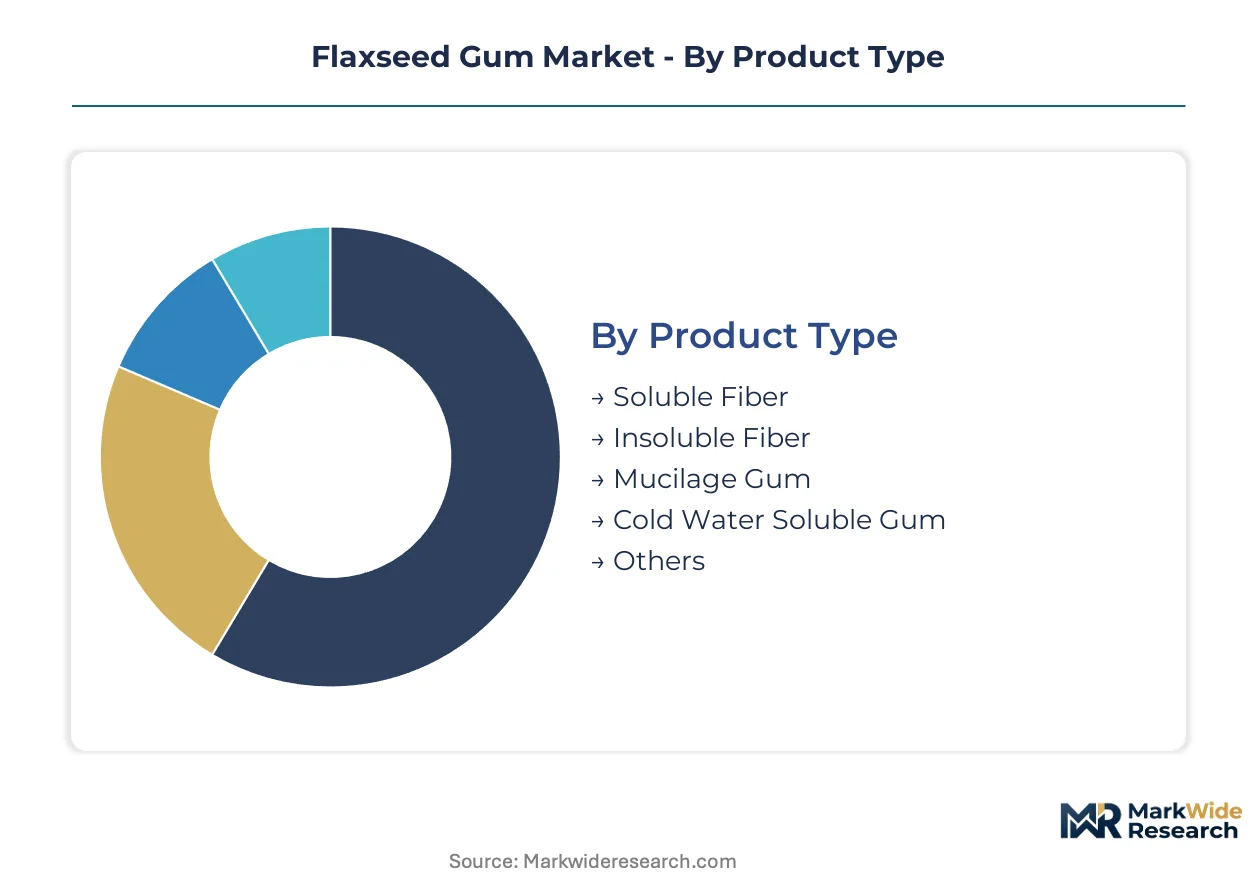
Flaxseed gum's functional versatility across viscosity, emulsion stability, and water-binding creates distinct value propositions for each product grade. Application-specific formulation requirements and regulatory positioning drive divergent commercial strategies across segment boundaries.
Product Type:
The use-case spectrum spans digestive health claims, clean-label texture modification, and premium hydrocolloid performance depending on extraction refinement and arabinoxylan concentration.
- Soluble Fiber:Arabinoxylan-rich polysaccharides exceeding 80% purity enable FDA dietary fiber declarations and Health Canada novel fiber health claims. Dairy alternative manufacturers in Canada and the US concentrate procurement here for plant-based beverage emulsion stability combined with digestive health positioning.
- Mucilage Gum:Traditional cold-water extract with established formulation familiarity in bakery applications. North American clean-label reformulation drives displacement of synthetic hydrocolloids in dough conditioning and crumb structure retention.
- Insoluble Fiber:Seed coat residues with limited functional viscosity serve animal feed and low-cost filler applications.
- Cold Water Soluble Gum:Refined grades meeting 80%+ solubility thresholds for beverage formulators requiring transparent solution clarity.
- Others:Blended grades and co-processed variants for niche industrial applications.
The dominant share belongs to Soluble Fiber, while Cold Water Soluble Gum is closing the gap fastest.
Application:
Cost tier stratification separates premium functional positioning from commodity texture replacement across food and non-food matrices.
- Dairy Alternatives:Plant-based beverage formulators require arabinoxylan molecular weight distributions for emulsion stability without mouthfeel compromise. Prairie corridor extraction facilities supply refined grades to oat and almond milk processors in Canada and the US Midwest.
- Bakery Products:Clean-label reformulation strips synthetic hydrocolloils from ingredient decks. Flaxseed gum's plant-derived viscosity satisfies consumer transparency expectations while maintaining dough handling and shelf-life extension.
- Meat Processing:Application-specific hydration systems for clean-label processed meats demonstrate technical feasibility with Kerry Group's existing platforms.
- Beverages:Functional fiber fortification in ready-to-drink formats leverages Health Canada and FDA regulatory alignment.
- Confectionery:Gelling and stabilizing functions in reduced-sugar formulations.
- Cosmetics:Film-forming and emulsion stabilization in natural personal care positioning.
Dairy Alternatives command premium pricing tiers, though Meat Processing is expanding most quickly as clean-label processed meat demand accelerates.
End User:
Customer type determines specification stringency, volume commitment scale, and technical service intensity required from suppliers.
- Food & Beverage Manufacturers:Direct-procurement relationships with Prairie extraction facilities displace traditional distributor intermediation. Large-scale bakery and meat-processing buyers consolidate supplier panels to secure volume commitments across US Midwest and Ontario manufacturing corridors.
- Personal Care Companies:Natural cosmetic formulators qualify Canadian-origin supply for EFSA and REACH compliance alignment.
- Pharmaceutical Firms:Excipient-grade specifications for controlled-release and tablet binding applications.
- Animal Feed Producers:Low-purity grades for digestive health and pellet binding in livestock nutrition.
Food & Beverage Manufacturers hold the volume concentration, while Personal Care Companies are gaining share fastest on natural positioning trends.
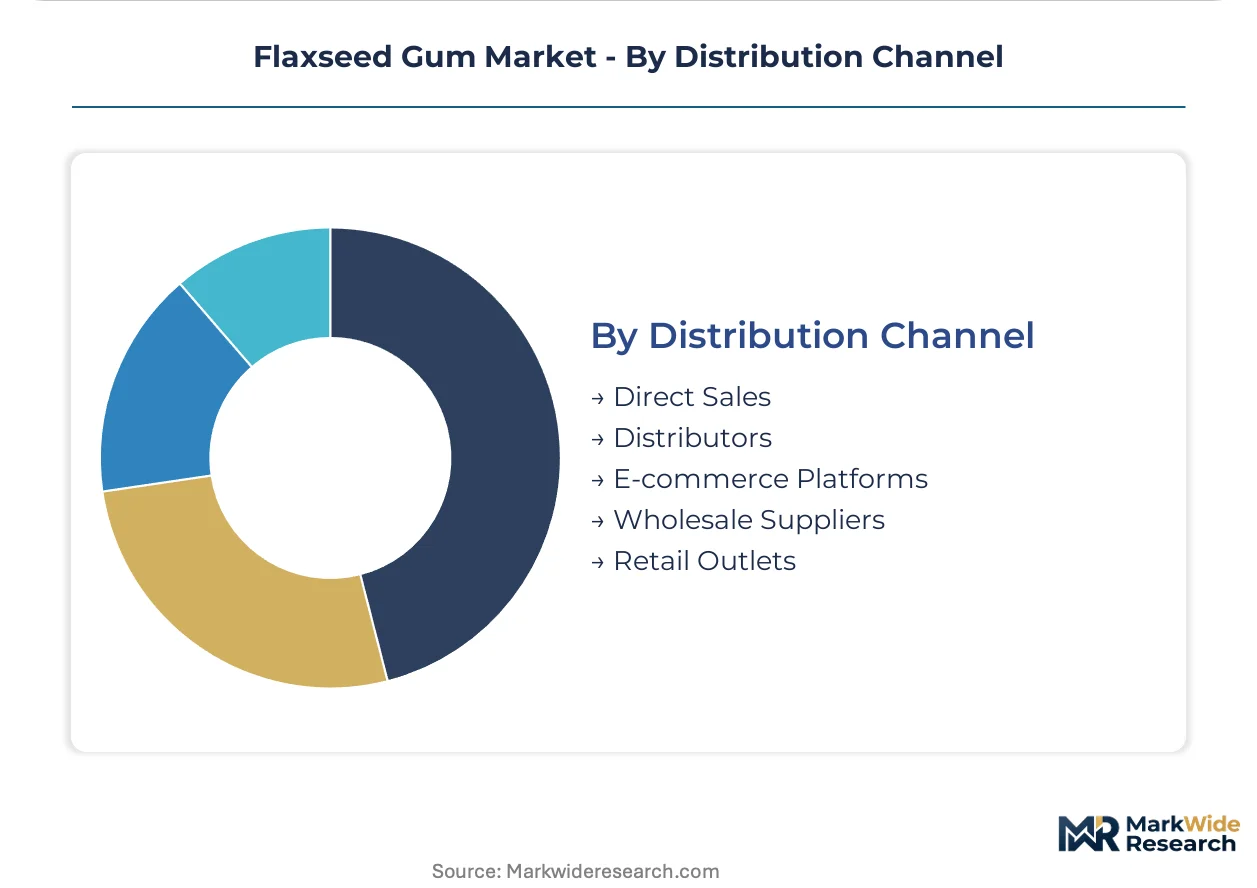
Distribution Channel:
Supply concentration in Saskatchewan and Manitoba extraction corridors shapes channel efficiency and margin capture dynamics.
- Direct Sales:Large-scale buyers consolidate supplier panels to secure volume commitments. Cargill's backward integration into Canadian seed origination enables direct throughput to major food manufacturers.
- Distributors:Traditional ingredient intermediaries face displacement as procurement concentrates around Prairie facilities.
- E-commerce Platforms:Specialty and small-batch formulators access refined grades without minimum order constraints.
- Wholesale Suppliers:Regional toll processors leverage asset-light models for mid-tier volume fulfillment.
- Retail Outlets:Consumer-packaged formats for artisan and home-use applications.
Direct Sales captures the dominant flow, yet E-commerce Platforms are climbing the fastest on small-batch and specialty formulation access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Large-scale bakery and dairy-alternative manufacturers concentrate procurement around Prairie extraction corridors, while European formulators qualify Canadian suppliers to preempt REACH compliance disruption.
United States
Plant-based beverage formulators in the US Midwest drive refined-grade demand for oat and almond milk emulsion stability. FDA's 2016 Nutrition Facts modernization reclassified gum constituents as dietary fiber, triggering clean-label reformulation waves. Minneapolis-St. Paul and Chicago manufacturing corridors anchor direct-procurement relationships with Prairie extraction facilities.
Canada
Saskatchewan and Manitoba cultivation clusters provide contiguous raw material access for toll manufacturers and integrated processors. Health Canada's Food Directorate governs novel fiber health claims through evolving substantiation frameworks. Winnipeg and Regina extraction facilities supply refined grades to domestic dairy-alternative processors and cross-border bakery manufacturers.
Germany
Bakery and dairy-alternative manufacturers in Germany qualify Canadian flaxseed gum suppliers to preempt supply chain disruption from REACH compliance costs. EFSA evaluates viscosity-related digestive health substantiation for EU market access. Cologne and Hamburg formulator clusters drive procurement concentration toward domestic-origin alternatives.
France
Natural cosmetic formulators in France qualify Canadian-origin supply for EFSA and REACH compliance alignment in personal care applications. ANSM oversees cosmetic ingredient safety assessments under EU regulatory frameworks. Paris and Lyon personal care manufacturing corridors anchor premium-grade demand for film-forming and emulsion stabilization functions.
China
Qingdao-based biotechnology specialists participate in hydrocolloid extraction and refinement for regional food applications. SAMR regulates food additive safety and labeling requirements under national standards. Shandong Peninsula processing clusters concentrate mid-tier volume fulfillment for domestic bakery and beverage manufacturers.
Flaxseed Gum Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Integrated agribusiness conglomerates leverage backward integration into Canadian seed origination to secure raw material throughput. Regional toll processors employ asset-light extraction leasing to fragment entry barriers. Application-specific hydration system specialists differentiate through meat processing and dairy-alternative formulation expertise. Dominant competitive moves include direct-procurement relationship consolidation and multi-plant hydrocolloid infrastructure expansion.
Within the integrated agribusiness tier, Cargill and ADM represent channel-controlling archetypes with upstream seed origination capabilities. Kerry Group occupies a position among application-specific specialists, anchoring the hydration systems vector for meat processing binders. Qingdao Tianli Shenghe Biotechnology exemplifies the regional toll processor archetype, sitting within the asset-light extraction segment serving mid-tier volume requirements.
| Leading Market Players |
|---|
| Cargill |
| Ingredion |
| DuPont de Nemours |
| ADM |
| Kerry Group |
| CP Kelco |
| Ashland |
| Glanbia |
| Qingdao Tianli Shenghe Biotechnology |
| Others |
Pricing and Supply Chain Analysis
Saskatchewan's Prairie extraction corridor anchors capacity dynamics that cascade directly into downstream pricing power for refined flaxseed gum grades. Winnipeg and Regina facilities command premium positioning when cold-water solubility specifications tighten for plant-based beverage formulators.
Pricing Analysis
Certification level (FDA-grade dietary fiber declarations versus standard food-grade) creates the primary spread between premium and commodity tiers. Three-tier pricing structure across premium soluble fiber, standard mucilage gum, and economy insoluble grades dominates transactional flows. Cost compression in standard mucilage tiers is intensifying because locust bean gum substitutes erode formulation lock-in. Mid-tier toll processors exhibit highest price sensitivity, while integrated agribusiness buyers with captive seed origination show least.
Supply Chain Analysis
Regional toll processors in Saskatchewan, Manitoba, and North Dakota hold contract-manufacturing concentration for cold-extraction capacity. Raw material flows draw from Linum usitatissimum seed coat harvests, enzyme-assisted refinement inputs, and Prairie logistics infrastructure. Single-source vulnerability concentrates around Saskatchewan cultivation belts exposed to climate-driven yield volatility. Distribution runs through direct-procurement relationships with large-scale bakery and meat-processing buyers consolidating supplier panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flaxseed gum functions as a platform-economics inflection where Health Canada, FDA, and EFSA regulatory interoperability creates ecosystem value for dossier-ready suppliers.
For Market Incumbents: Insulate margin position through backward integration into Canadian seed origination and multi-plant hydrocolloid infrastructure expansion. Cargill's captive Prairie throughput demonstrates defensive value against toll-processor fragmentation. Lock in direct-procurement relationships with US Midwest manufacturing corridors before supplier panel consolidation completes.
For New Entrants and Emerging Players: Meat processing hydration systems for clean-label processed meats represent the most penetrable entry point given Kerry Group's isolated technical demonstration and limited competitive saturation. Enzyme-assisted cold extraction leasing in Manitoba bypasses capital-intensive thermal infrastructure. Lead with application-specific formulation service bundles that ADM's scale cannot replicate nimbly.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors regional toll processors with digital extraction monitoring capabilities and Health Canada novel fiber claim dossier readiness. Long-term viability hinges on regulatory arbitrage across FDA-EFSA-Health Canada fiber definition convergence. Watch EFSA viscosity substantiation pathway acceleration as inflection signal for premium-grade valuation expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzyme-Assisted Cold Extraction Scale-Up | Preserves arabinoxylan molecular weight for premium viscosity performance in plant-based beverages. |
| Health Canada Novel Fiber Dossier Submission | Captures first-mover advantage in digestive health claim positioning ahead of EFSA alignment. |
| Prairie Seed Origination Integration | Secures contiguous raw material access against harvest yield volatility in Saskatchewan belts. |
| Direct-Procurement Relationship Consolidation | Displaces traditional distributor intermediation across US Midwest and Ontario manufacturing corridors. |
| Application-Specific Hydration System Development | Replicates Kerry Group's meat processing binder technical feasibility for broader clean-label adoption. |
Research Methodology
Initial hypotheses were tested against primary input from extraction facility operators, hydrocolloid formulation specialists, regulatory affairs directors at food manufacturers, and Prairie seed origination managers, then refined through secondary validation. Bottom-up triangulation combined customs records, Health Canada Food Directorate guidance documents, FDA Nutrition Facts modernization filings, and EFSA scientific opinions on arabinoxylan substantiation. Top-down cross-checks drew from agribusiness SEC disclosures and hydrocolloid trade association capacity surveys.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, application matrix, end-user specification stringency, and regional regulatory cluster. CAGRs were synthesized from granular volume build-ups by segment and value capture by purity grade. Industry-specific forecast inputs incorporated enzyme-assisted extraction adoption curves and direct-procurement relationship migration rates.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity price indices and trans-Pacific logistics costs would shift the trajectory. Forecasts reflect documented assumptions on regulatory alignment timing and seed coat yield stability. Quarterly review of Health Canada novel fiber claim approval velocity and EFSA scientific opinion publication cadence is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.