
 5G Mmwave Technology Market | 2026-2036
5G Mmwave Technology Market Size, Share, and Industry Trends Forecast 2026-2036
5G Mmwave Technology Market Outlook
Project finance tied to spectrum leasing is narrowing the competitive field for 5G mmWave infrastructure. Nokia leverages captive antenna manufacturing to sustain margin control across European deployments. Qualcomm anchors its position through modem-RF system integration that dominates handset supply chains. Samsung Electronics competes by extending in-house semiconductor fabrication into baseband and front-end module production.
5G mmWave technology operates in frequency bands between 24 GHz and 100 GHz, utilizing massive MIMO antenna arrays with beamforming to deliver multi-gigabit throughput over short distances for dense urban and industrial environments. Base stations command the largest capital allocation among product types as carriers densify networks, while Fixed Wireless Access represents the fastest-expanding application segment as operators bypass fiber trenching in underserved areas. Network Management Systems concentrate margin pools through software-defined orchestration of distributed architectures.
The FCC governs spectrum allocation and auction mechanics in the United States, directly shaping carrier deployment timelines and equipment procurement volumes. ETSI and 3GPP standards frameworks in Europe enforce interoperability mandates that determine vendor qualification and market access thresholds. Stakeholders must monitor O-RAN policy divergence between Washington and Brussels to anticipate supply chain reconfiguration requirements.
Market Dynamics
Beamforming silicon integration is compressing base station economics faster than carriers can densify networks, forcing infrastructure vendors to absorb margin compression or cede share to captive semiconductor suppliers.
Growth Catalysts
- FCC Auction 110:The 47 GHz spectrum release unlocked contiguous blocks for ultra-dense urban grids, accelerating small cell deployment timelines across US metropolitan corridors.
- Fixed Wireless Access:Rural broadband providers bypass fiber trenching costs by deploying mmWave customer premise equipment, converting CAPEX avoidance into subscriber acquisition budgets.
- O-RAN 7.2x split:The fronthaul interface standardization is fragmenting vendor lock-in, enabling multi-vendor baseband-to-radio configurations that reduce single-source dependency.
Market Restraints
- GaN-on-SiC substrate concentration:Power amplifier foundry capacity clusters in Taiwan and Japan, exposing procurement to geopolitical chokepoint risk.
- Line-of-sight propagation:28 GHz signals attenuate through foliage and atmospheric moisture, constraining suburban deployment economics despite urban success.
- REACH substance restrictions:ECHA candidate list scrutiny on gallium compounds is extending supplier qualification timelines for European base station shipments.
Strategic Opportunities
- Industrial private networks:German automotive OEMs and chemical complexes are licensing localized 3.7-24.25 GHz blocks for deterministic factory automation.
- AI-driven beam management:Machine learning prediction of user equipment movement is reducing handover latency, opening stadium and transit hub applications previously uneconomical.
- US BEAD program:The $42 billion broadband equity allocation prioritizes wireless alternatives where fiber costs exceed $10,000 per passing, directing subsidy flow toward mmWave FWA.
Industry Challenges
- RF systems integration talent:The scarcity of engineers proficient in millimeter-wave phased array calibration is throttling OEM production ramps and extending R&D cycles.
- Multi-vendor interoperability testing:O-RAN compliance verification across disaggregated radio units and distributed units consumes 40% of deployment schedules, delaying revenue recognition.
- Thermal dissipation at edge density:Street-level small cell enclosures lack power and cooling infrastructure, forcing derated output or active cooling retrofits that erode deployment margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 5G Mmwave Technology Market |
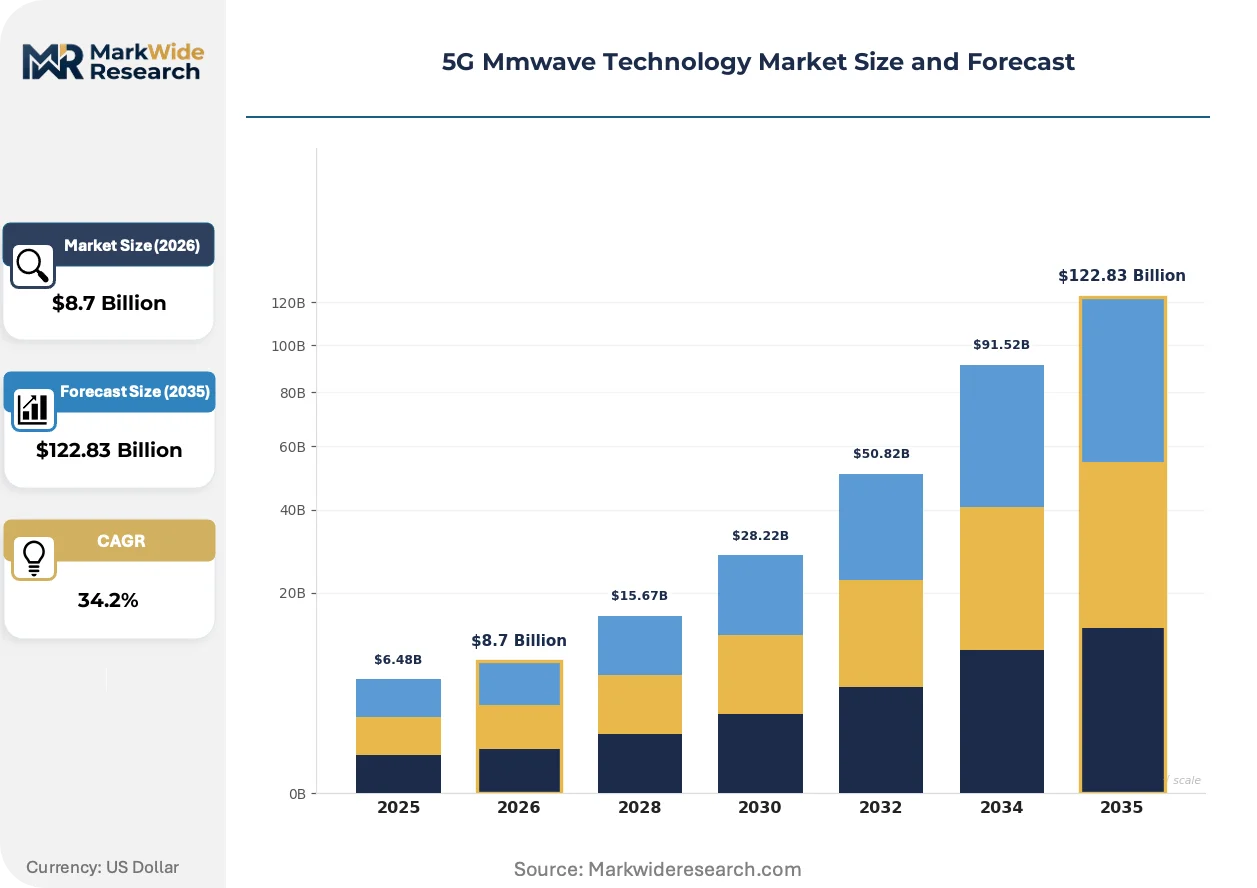
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $122.83 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Fixed Wireless Access, Smart Cities, Autonomous Vehicles, Industrial IoT Product Type: Base Stations, Antennas, Repeaters, Network Management Systems Deployment Model: Private Network, Public Network, Hybrid Model, Distributed Architecture End User: Telecommunications, Healthcare, Manufacturing, Transportation |
| Companies Covered | Nokia, Analog Devices, Qualcomm, ZTE, Keysight Technologies, Huawei, Samsung Electronics, Intel, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
5G Mmwave Technology Market Strategic Shifts
Silicon photonics and intelligent surface materials are redefining signal propagation economics, compressing the cost-per-gigabit delivered while expanding addressable terrain beyond traditional line-of-sight constraints.
Integrated photonic beamformers are replacing discrete RF phase shifters in massive MIMO arrays. Verizon and AT&T trial units from 2024 deployments demonstrate 60% power reduction per antenna element. This consolidation is rendering obsolete the legacy distributed antenna feeder architectures that dominated 4G infrastructure.
ETSI's harmonized 26 GHz band plan is synchronizing European carrier roadmaps previously fragmented by national variances. The framework mandates contiguous 1 GHz blocks, enabling equipment economies of scale that single-country allocations could not support. Base station OEMs are consolidating SKU portfolios around this unified specification, accelerating cost-down curves for cross-border deployments.
Enterprise buyers are unbundling network management from hardware procurement, contracting software-defined orchestration as a separate service layer. Manufacturing campuses in South Korea and logistics hubs in the Netherlands are leading this shift, replacing capital-intensive owned infrastructure with subscription-based network-as-a-service arrangements that transfer obsolescence risk to operators.
5G Mmwave Technology Market Segmentation
5G mmWave market segmentation reveals divergent capital allocation patterns across infrastructure layers. Application contexts determine propagation requirements and beamforming complexity. Product hierarchies reflect margin concentration in software-defined orchestration versus hardware commoditization.
Application:
Maturity varies sharply across use cases, with commercial deployments clustering in established connectivity paradigms while emerging scenarios await ecosystem maturation.
- Fixed Wireless Access:Delivers multi-gigabit residential broadband through customer premise equipment operating in 24-39 GHz bands. Rural electric cooperatives in the US Midwest and satellite-dependent regions across Australia are converting avoided fiber trenching costs into subscriber acquisition budgets.
- Smart Cities:Dense small cell grids support traffic management, public safety video backhaul, and environmental monitoring through integrated sensor networks. Seoul's Gangnam district and Barcelona's 22@ innovation zone demonstrate revenue concentration in municipalities with dedicated digital infrastructure budgets.
- Autonomous Vehicles:Vehicle-to-infrastructure links enable cooperative perception and intersection coordination through 28 GHz roadside units. Pilots in Michigan's Mcity and Germany's A9 digital testbed face propagation reliability constraints in adverse weather.
- Industrial IoT:Deterministic wireless replaces Ethernet for mobile robotics and augmented reality maintenance in controlled factory environments. German automotive OEMs in Baden-Württemberg license localized 3.7-24.25 GHz blocks for deterministic automation.
Fixed Wireless Access retains volume leadership; Industrial IoT holds the steepest expansion curve.
Product Type:
Cost tier stratification separates capital-intensive radio hardware from recurring software revenue streams.
- Base Stations:Macro and small cell units incorporating massive MIMO arrays with 64-256 antenna elements dominate carrier capital expenditure. Densification timelines in South Korea's urban corridors and US stadium districts concentrate procurement volumes.
- Antennas:Phased array modules with integrated beamforming ICs determine link budget performance. Nokia's captive manufacturing in Finland and Qualcomm's modem-RF integration anchor supply concentration in integrated versus discrete architectures.
- Repeaters:Transparent amplification units extend coverage in non-line-of-sight corridors and indoor environments. Deployment concentrates in transit tunnels and airport terminals where signal penetration fails.
- Network Management Systems:Software-defined orchestration platforms provision slice isolation and dynamic spectrum allocation. Enterprise buyers in Dutch logistics hubs unbundle this layer from hardware procurement, converting capital expenditure to subscription arrangements.
Base Stations command capital allocation dominance; Network Management Systems capture margin expansion.
Deployment Model:
Customer type differentiation separates sovereign-controlled infrastructure from commercial carrier economics.
- Private Network:Licensed local spectrum enables deterministic latency for manufacturing and mining operations. German chemical complexes and South Korean shipyards lead procurement as spectrum frameworks mature.
- Public Network:Commercial carrier infrastructure serves mass-market mobile broadband and FWA subscribers. FCC Auction 110 releases in the United States and ETSI's harmonized 26 GHz framework in Europe shape procurement timelines.
- Hybrid Model:Shared infrastructure combines public coverage with private slice isolation for enterprise priority traffic. Trials in France's Grand Est region demonstrate spectrum efficiency gains.
- Distributed Architecture:O-RAN-compliant disaggregation separates baseband and radio unit functions across vendor boundaries. Multi-vendor interoperability testing consumes deployment schedules but fragments vendor lock-in.
Public Network sustains installed base scale; Private Network demonstrates the most rapid deployment acceleration.
End User:
Volume concentration tracks sector-specific digitization maturity and regulatory pressure for connectivity redundancy.
- Telecommunications:Mobile network operators and fixed-line incumbents deploy infrastructure for consumer and enterprise service tiers. Verizon and AT&T trial silicon photonic beamformers demonstrating power reduction in live networks.
- Healthcare:Hospital systems deploy private networks for surgical robotics and patient monitoring with isolation from public network congestion. Cleveland Clinic and Karolinska Institutet pilot networks face electromagnetic compatibility certification timelines.
- Manufacturing:Automotive and electronics producers replace wired connectivity for mobile assembly platforms. BMW's Leipzig plant and Samsung's Pyeongtaek semiconductor complex anchor demand in high-value production environments.
- Transportation:Ports, airports, and rail operators coordinate autonomous equipment through dedicated infrastructure. Rotterdam Maasvlakte and Singapore Changi concentrate procurement in freight and passenger throughput maximization.
Telecommunications maintains revenue concentration; Manufacturing exhibits the sharpest uptake acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in 5G mmWave equipment tilt toward net importers in emerging markets while established manufacturing economies retain component trade surpluses. Spectrum auction timing and subsidy programs now determine procurement velocity more than raw infrastructure demand.
United States
Verizon and AT&T drive base station procurement through FCC Auction 110's 47 GHz release, converting spectrum holdings into dense urban small cell grids. The $42 billion BEAD program redirects subsidy flow toward Fixed Wireless Access where fiber costs exceed thresholds per passing. Deployment concentrates in Midwest rural electric cooperative territories and stadium corridors across Texas and California.
South Korea
SK Telecom and KT Corporation sustain the world's densest small cell concentration in Seoul's Gangnam district and Busan-Ulsan industrial corridors. The Ministry of Science and ICT's 28 GHz licensing framework accelerated private network adoption at Samsung's Pyeongtaek semiconductor complex and Hyundai Heavy Industries shipyards. Manufacturing campuses in Gyeonggi Province convert avoided fiber trenching into subscriber acquisition budgets.
Germany
BMW's Leipzig automotive plant and BASF Ludwigshafen chemical complex anchor industrial private network licensing under BNetzA's 3.7-24.25 GHz local framework. ETSI's harmonized 26 GHz band plan synchronizes equipment procurement timelines previously fragmented by national variances. Baden-Württemberg automotive OEMs and North Rhine-Westphalia chemical producers lead deterministic factory automation deployments.
Japan
NTT Docomo and KDDI trial silicon photonic beamformers demonstrating power reduction in live Tokyo and Osaka networks. METI's spectrum allocation prioritizes manufacturing campus coverage in Aichi Prefecture's automotive cluster and Kyushu's semiconductor fabrication zones. Dense urban corridors in Kanto and Kansai regions concentrate base station densification timelines.
China
MIIT's 24.75-27.5 GHz and 37-42.5 GHz band plans drive carrier procurement volumes through state-mandated deployment targets. Manufacturing concentration in Guangdong Province's Pearl River Delta and Jiangsu Province's Yangtze River Delta feeds component export flows. ZTE and Huawei anchor domestic supply chains while facing equipment export restrictions to Western markets.
5G Mmwave Technology Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in semiconductor and antenna modules. The vendor base stratifies between consolidated infrastructure OEMs with captive manufacturing and disaggregated radio unit suppliers enabled by O-RAN standardization. Three archetypes dominate: integrated platform vendors with in-house semiconductor fabrication, RF component specialists supplying beamforming silicon, and software-defined orchestration providers capturing recurring revenue streams. Competitive moves center on strategic partnerships for multi-vendor interoperability certification and geographic expansion through spectrum auction timing alignment.
Among Nordic-integrated platform vendors, Nokia and Ericsson exemplify infrastructure OEMs with captive antenna manufacturing capabilities. Qualcomm occupies a position representing modem-RF system integration that dominates handset supply chain insertion. Samsung Electronics anchors the Korean chaebol archetype extending semiconductor fabrication into baseband and front-end module production. These three entities represent divergent strategic postures on vertical integration depth versus ecosystem partnership models.
| Leading Market Players |
|---|
| Nokia |
| Analog Devices |
| Qualcomm |
| ZTE |
| Keysight Technologies |
| Huawei |
| Samsung Electronics |
| Intel |
| Ericsson |
| Others |
Value Chain & Pricing Dynamics
The Kaohsiung-Tokyo semiconductor freight corridor compresses shipping costs for GaN-on-SiC substrates while amplifying price differentiation between captive-integrated base station OEMs and modular radio unit suppliers. This logistics dynamic concentrates procurement leverage among carriers with volume commitments to Taiwanese foundry capacity, forcing tier-two infrastructure vendors toward spot-market gallium nitride pricing.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Certification under ETSI's harmonized 26 GHz framework commands tier-one positioning, while volume scale and after-sales service bundling separate mid-tier suppliers from commodity antenna module vendors. Pricing pressure stems from beamforming silicon integration compressing base station margins faster than carrier densification timelines. Public network carriers exhibit acute price sensitivity due to O-RAN disaggregation enabling multi-vendor sourcing, whereas private network licensees in German automotive plants prioritize deterministic latency guarantees over unit cost.
Supply Chain Analysis
Export-control restrictions on 5G baseband semiconductor manufacturing equipment limit technology flows to Chinese foundries, reshaping procurement geography toward South Korean and Japanese fabrication capacity. Gallium nitride substrates, silicon carbide wafers, and beamforming integrated circuits draw from Taiwan, Japan, and the United States. Single-source vulnerability concentrates in GaN-on-SiC power amplifier foundries clustered in Hsinchu and Osaka. Distribution runs through carrier-direct procurement for public networks and systems integrator channels for private industrial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery pattern tied to FCC spectrum auction timing, with Auction 110's 47 GHz release triggering infrastructure procurement waves that lag spectrum licensing by 18-24 months.
For Market Incumbents: Pre-empt margin compression by deepening captive antenna manufacturing capabilities and accelerating O-RAN 7.2x split certification timelines. Beamforming silicon integration from Qualcomm and Analog Devices threatens discrete RF module suppliers with obsolescence; Nokia and Ericsson must consolidate modem-RF system integration or cede share to semiconductor-integrated platforms. Priority levers include in-house GaN-on-SiC substrate sourcing and multi-vendor interoperability testing investments.
For New Entrants and Emerging Players: Establish a beachhead in industrial private networks for German chemical complexes and South Korean shipyards, where localized spectrum licensing creates vendor qualification windows before carrier-scale procurement consolidates. The most penetrable segment combines O-RAN-compliant radio units with AI-driven beam management software for stadium and transit hub applications. Go-to-market positioning should emphasize deterministic latency guarantees and subscription-based network-as-a-service arrangements that transfer obsolescence risk from capital-constrained manufacturing buyers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded 5G mmWave R&D assets and captive semiconductor fabrication capabilities. Long-term viability hinges on backward integration into beamforming silicon and sustained O-RAN standardization alignment. Watch for inflection signals in FCC secondary market spectrum trading volumes, which indicate carrier deployment commitment acceleration or retrenchment.
| Strategic Initiative | Industry Significance |
|---|---|
| Beamforming Silicon Integration | Qualcomm's modem-RF consolidation renders discrete phase shifter architectures obsolete in massive MIMO arrays. |
| O-RAN 7.2x Split Certification | Multi-vendor interoperability testing fragments vendor lock-in and accelerates baseband-to-radio disaggregation. |
| Private Network Licensing | German automotive OEMs and chemical complexes license localized 3.7-24.25 GHz blocks for deterministic factory automation. |
| Silicon Photonic Beamformers | Verizon and AT&T trials demonstrate 60% power reduction per antenna element in live network deployments. |
| Fixed Wireless Access Scale-Up | US BEAD program subsidies redirect procurement toward mmWave customer premise equipment where fiber costs exceed thresholds. |
Study Parameters
The analysis maps base station hardware, antenna modules, repeaters, and network management systems, each validated through network planning engineers at Tier 1 carriers, procurement leads at rural electric cooperatives, RF systems integration specialists, and semiconductor foundry account managers. Primary interview insights triangulate against FCC auction records, ETSI standardization documents, 3GPP release timelines, SEC equipment vendor filings, and customs data on GaN-on-SiC substrate trade flows. Bottom-up deployment forecasts by metropolitan corridor integrate with top-down carrier capex guidance.
Assumptions held fixed include O-RAN standardization continuity, REACH substance restriction enforcement timelines, and FCC spectrum allocation frameworks; variables stress-tested encompass GaN-on-SiC foundry capacity expansion rates and carrier densification budget elasticity across the projection horizon. Segmentation dimensions encompass application context, product hierarchy, deployment model, and end-user sector. CAGRs derive from deployment timeline modeling against subscriber penetration curves, with inputs including small cell inter-site distance economics and fixed wireless access subscriber acquisition cost trajectories.
Stress conditions across geopolitical export controls, spectrum auction delays, and beamforming silicon yield rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on carrier procurement pacing and regulatory harmonization timelines. Material shifts in FCC secondary market spectrum trading activity or ETSI band plan fragmentation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Asia-Pacific Distributed Antenna System Market
Wireless Technologies
Visible Light Communication (VLC) Market
Wireless Technologies
Wireless Mesh Networking Market
Wireless Technologies
Industrial Wireless Broken Signal Solutions Market
Wireless Technologies
Outdoor Wi-Fi Market
Wireless Technologies
Wireless Access Point Market
Wireless Technologies
Wigig Market
Wireless Technologies
Wireless Communication Technologies in Healthcare Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Global Wireless Data Communication Market
Wireless Technologies
Mobile WLAN Access Points Market
Wireless Technologies
Global Wireless Health Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Wireless Communication Equipment Market