
 Peanut Ingredients Market | 2026-2036
Peanut Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Peanut Ingredients Market Analysis
Food manufacturers is reorganizing procurement priorities around protein fortification and allergen management, pulling volume from traditional bakery buyers. Olam International leverages its African and South American sourcing networks to secure raw peanut supply chains. Archer Daniels Midland Company sustains crushing and oil extraction infrastructure across multiple continents. Golden Peanut & Tree Nuts dominates the North American shelling and ingredient processing tier with specialized roasting and milling capabilities.
Peanut ingredients encompass mechanically processed peanut derivatives including defatted flour, expeller-pressed oil, and milled paste with specified particle sizes and protein contents, serving as functional inputs for texture, emulsification, and nutritional enhancement in formulated foods. Peanut butter occupies the largest value share within product type segmentation due to its penetration across retail and foodservice channels, while peanut flour captures expanding demand from gluten-free and high-protein bakery applications. Food manufacturers represent the most concentrated end user segment, with direct sales channels capturing premium margin pools from large-volume contract buyers.
FDA allergen labeling requirements under FALCPA and EFSA novel food consultations shape product development timelines and cross-border formulation standards for peanut-derived ingredients. ISO 22000 and HACCP certification thresholds determine supplier eligibility for multinational food manufacturer procurement programs. Stakeholders must monitor evolving protein content claims regulation and traceability mandates to preserve market access across jurisdictions.
Market Dynamics
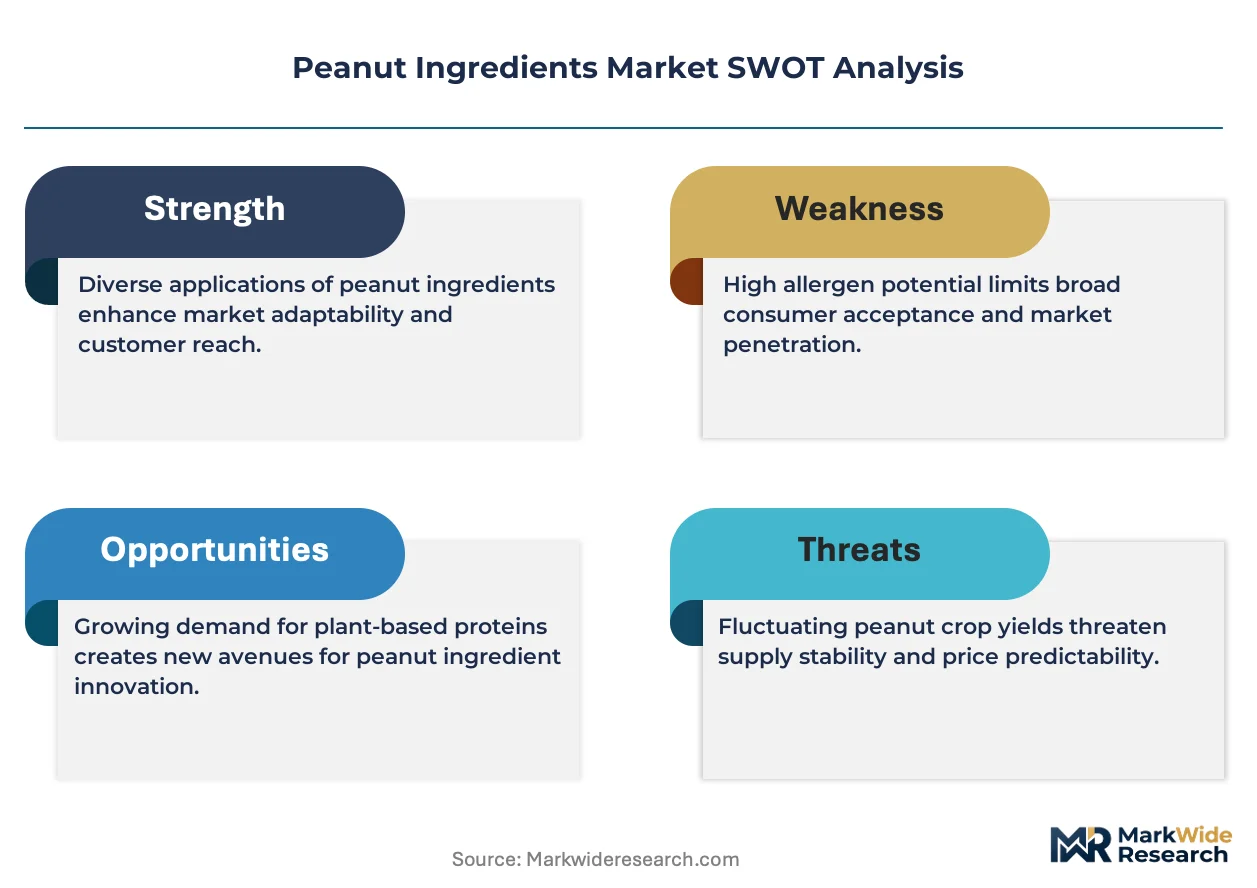
Plant-based protein adoption by food manufacturers is reorganizing procurement priorities around protein fortification and allergen management, pulling volume from traditional bakery buyers toward specialized ingredient processors with certified crushing and milling infrastructure.
Growth Catalysts
- Clean-label reformulation mandates:FDA and EFSA guidance on simplified ingredient declarations is forcing manufacturers to source minimally processed peanut derivatives with traceable supply chains.
- Gluten-free bakery expansion:Defatted peanut flour is capturing formulation share from wheat alternatives in high-protein bread and snack applications.
- China processed food manufacturing:Expansion of domestic snack production bases is accelerating import demand for specified particle-size peanut paste.
Market Restraints
- Aflatoxin testing costs:Pre-shipment laboratory verification requirements in African and South American origin zones inflate working capital for shelling operations.
- Single-origin supply concentration:Crushing infrastructure clusters in the United States and Argentina create geographic vulnerability to weather-induced crop failures.
- Pulse protein substitution:Pea and lentil protein isolates are displacing peanut flour in certain plant-based meat applications due to allergen-free positioning.
Strategic Opportunities
- India snack manufacturing:Domestic processed food producers are underpenetrated in premium peanut butter and paste categories relative to per capita consumption potential.
- EU Green Deal bioeconomy incentives:Peanut hull fiber valorization for packaging and composite materials qualifies for circular economy R&D funding.
- Direct-to-manufacturer digital platforms:Blockchain-enabled procurement portals are compressing distributor margins and enabling price transparency for large-volume contract buyers.
Industry Challenges
- ISO 22000 certification timelines:Small and mid-tier processors face 12-18 month compliance gaps that exclude them from multinational food manufacturer approved supplier lists.
- Legacy ERP integration:Lot-level traceability mandates require capital-intensive upgrades to inventory management systems for batch tracking across shelling, roasting, and milling stages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peanut Ingredients Market |
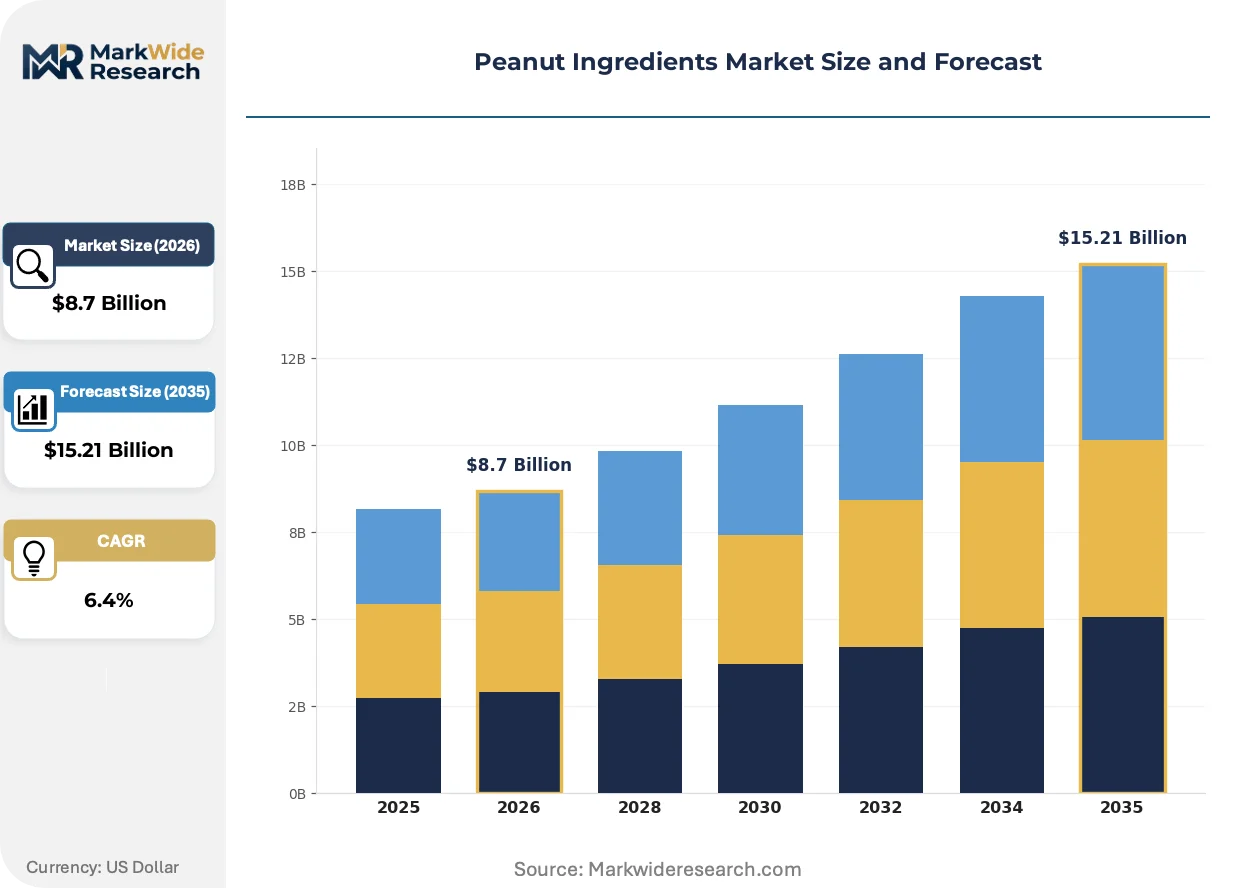
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peanut Butter, Peanut Oil, Peanut Flour, Whole Peanuts Application: Baking, Confectionery, Snacks, Sauces End User: Food Manufacturers, Restaurants, Retailers, Home Cooks Distribution Channel: Online Retail, Supermarkets, Wholesale, Direct Sales |
| Companies Covered | Golden Peanut & Tree Nuts, Wilmar International, Olam International, Birdsong Peanut Company, Hampton Farms, Archer Daniels Midland Company, Shandong Luhua Group, American Peanut Ingredients, Cargill Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peanut Ingredients Market Emerging Trajectories
Mechanical processing technologies and regulatory traceability mandates are compressing supplier qualification timelines while enabling new functional applications for peanut-derived inputs across formulated food categories.
Expeller-pressed oil extraction with controlled temperature profiles is supplanting solvent-based hexane extraction in premium ingredient specifications. Organic and non-GMO certified food manufacturers are adopting cold-press methods at accelerated procurement cycles. This shift is compressing capital recovery timelines for legacy solvent-based crushing infrastructure while enabling clean-label positioning in retail and foodservice channels.
EFSA novel food consultation requirements for enzymatically modified peanut proteins are extending product development timelines by 18-24 months. The industrial consequence is a freeze on launch pipelines for hydrolyzed protein isolates targeting sports nutrition applications. European formulators are responding by pivoting R&D toward mechanically processed fractions that fall outside novel food scope.
Large-volume contract buyers are consolidating supplier relationships around vertically integrated processors with captive roasting and oil extraction capabilities. Distributor networks serving mid-tier bakery and confectionery segments are losing share to direct procurement teams at multinational food manufacturers. This concentration is most visible in the United States, where three shelling cooperatives now capture the majority of food-grade peanut ingredient volume.
Peanut Ingredients Market Segmentation
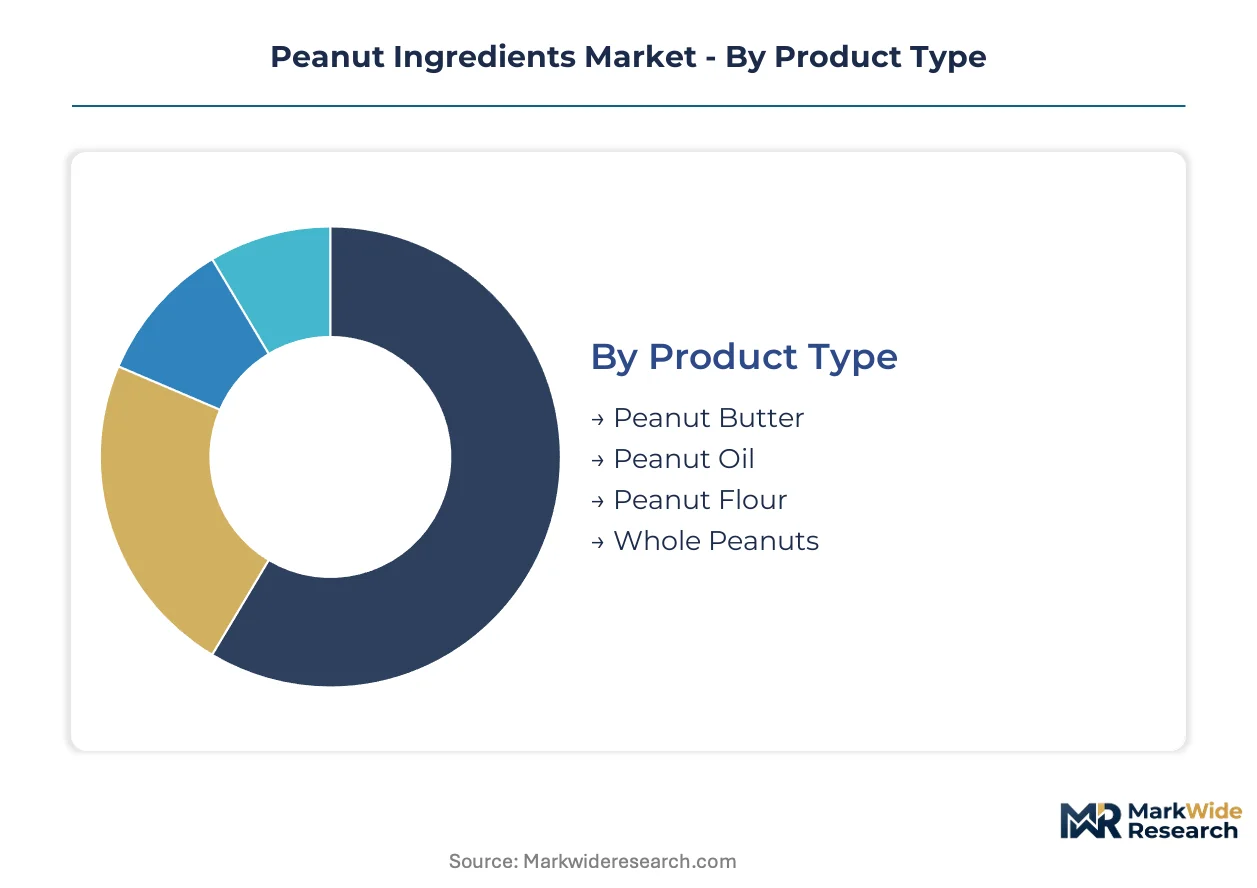
Segmentation in the peanut ingredients market reveals how regulatory frameworks and functional specifications reshape procurement patterns across distinct buyer categories. Understanding these divisions exposes where margin pools concentrate and where certification requirements create supplier exclusion zones.
Product Type:
FDA allergen labeling under FALCPA and EFSA novel food consultations impose divergent compliance burdens across processed formats, with enzymatically modified fractions facing extended approval timelines in Europe while mechanically processed derivatives move through faster regulatory pathways.
- Peanut Butter:Emulsified paste with specified particle size distribution and oil stability parameters, serving as the dominant retail and foodservice format. Demand concentrates in the United States where three shelling cooperatives now capture the majority of food-grade volume, pulled by clean-label reformulation mandates that favor minimally processed derivatives with traceable supply chains.
- Peanut Oil:Expeller-pressed and solvent-extracted grades with differentiated smoke points and fatty acid profiles for frying and dressing applications. Food manufacturers in China are accelerating import demand for specified viscosity grades as domestic snack production bases expand, though aflatoxin testing costs in origin zones inflate working capital requirements.
- Peanut Flour:Defatted powder with controlled protein content for gluten-free bakery fortification.
- Whole Peanuts:Raw and roasted kernels for direct consumption and ingredient processing.
Established volume favors peanut butter; emerging adoption favors peanut flour.
Application:
Cost tier differentiation separates commodity-grade inputs for mass-market snacks from premium-specified fractions targeting clean-label bakery and confectionery segments with certified organic and non-GMO positioning.
- Baking:High-protein flour fractions and stabilized paste formats for bread, pastry, and gluten-free formulations. Defatted peanut flour is capturing formulation share from wheat alternatives in the United States and Europe, where FALCPA and EFSA guidance on simplified ingredient declarations force manufacturers toward traceable supply chains.
- Confectionery:Specified roast color and particle size grades for chocolate enrobing and praline applications. European formulators are pivoting R&D toward mechanically processed fractions that fall outside EFSA novel food scope, avoiding 18-24 month consultation delays for hydrolyzed protein targets.
- Snacks:Whole kernel and split grades for roasting and flavor coating.
- Sauces:Emulsified paste and oil blends for dressing and marinade formulations.
Volume concentrates in snacks; steepest expansion trajectory appears in baking.
End User:
Customer type determines procurement scale and certification stringency, with multinational food manufacturers imposing ISO 22000 and HACCP thresholds that exclude small and mid-tier processors from approved supplier lists.
- Food Manufacturers:Large-volume contract buyers with direct procurement teams consolidating supplier relationships around vertically integrated processors. These buyers are reorganizing priorities around protein fortification and allergen management, pulling volume from traditional bakery buyers toward specialized ingredient processors with certified crushing and milling infrastructure.
- Restaurants:Foodservice operators sourcing bulk paste and oil through distributor networks.
- Retailers:Private-label and branded product merchandisers with specification control over supplier tiers.
- Home Cooks:Consumer-packaged goods purchasers through retail and online channels.
Procurement concentration favors food manufacturers; channel fragmentation persists among home cooks.
Distribution Channel:
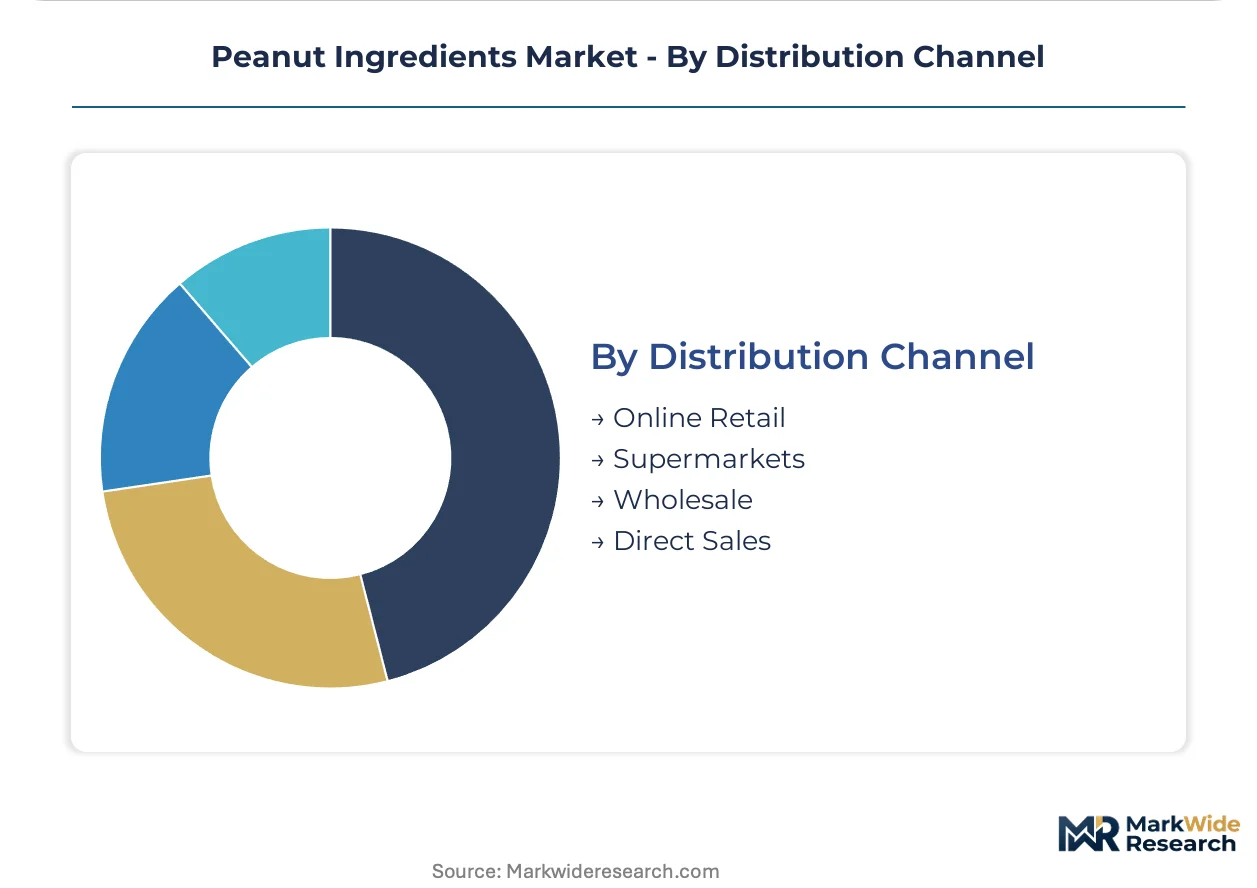
Supply concentration in crushing infrastructure clusters creates geographic vulnerability that shapes channel selection, with direct sales capturing premium margin pools from buyers seeking captive roasting and oil extraction capabilities.
- Online Retail:E-commerce platforms serving consumer and small-business segments with fragmented order sizes.
- Supermarkets:Mass-market retail merchandising of branded and private-label packaged goods.
- Wholesale:Distributor networks serving mid-tier bakery and confectionery segments with aggregated volume.
- Direct Sales:Large-volume contract relationships between multinational food manufacturers and vertically integrated processors. Blockchain-enabled procurement portals are compressing distributor margins and enabling price transparency for these buyers, most visible in the United States where direct channels now dominate food-grade volume.
Margin capture favors direct sales; volume accessibility favors wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Argentina and Brazil export raw peanut kernels to crushing facilities in the United States and China, creating a trans-Atlantic supply corridor that shapes procurement patterns for food-grade ingredients.
United States
Three shelling cooperatives in Georgia and Alabama now capture the majority of domestic food-grade volume, driven by clean-label reformulation mandates from multinational food manufacturers. FDA allergen labeling requirements under FALCPA force traceable supply chain documentation across all processed formats. The Southeast cluster—centered on Albany, Georgia—hosts specialized roasting and milling infrastructure serving direct sales contracts.
China
Domestic snack production bases in Shandong and Jiangsu provinces are accelerating import demand for specified particle-size peanut paste from South American origins. SAMR food safety standards impose lot-level traceability requirements that favor vertically integrated processors with captive crushing capabilities. The Yangtze River Delta concentration around Shanghai houses the largest oil extraction infrastructure for foodservice-grade outputs.
India
Gujarat and Andhra Pradesh shelling operations supply defatted flour to gluten-free bakery formulators in Europe and North America. FSSAI licensing requirements for food ingredient processors create compliance gaps that exclude smaller operators from export eligibility. The Saurashtra peninsula cluster dominates mechanical processing capacity for high-protein fractions targeting contract manufacturing.
Argentina
Cordoba and Buenos Aires provinces anchor South American raw peanut exports to crushing facilities in China and the United States. Aflatoxin testing costs for pre-shipment laboratory verification inflate working capital requirements for shelling cooperatives. The Pampas agricultural belt concentrates grower-processor relationships that feed Atlantic export corridors.
Germany
EFSA novel food consultation requirements extend product development timelines for enzymatically modified peanut proteins, forcing European formulators toward mechanically processed fractions. EU Green Deal bioeconomy incentives support peanut hull fiber valorization for packaging applications in the Baden-Württemberg industrial corridor. Stuttgart-based ingredient distributors serve as consolidation points for premium-specified imports from United States and Argentine origins.
Peanut Ingredients Market Vendor Landscape
Listed leaders compete with private specialists across certification infrastructure, creating a tiered structure where public company scale advantages clash with private operator agility in allergen-managed processing. The vendor base concentrates around three strategic archetypes: African and South American sourcing network operators, North American shelling and roasting specialists, and Asian integrated oilseed processors. Dominant competitive moves include backward integration into captive farming operations and strategic partnerships with blockchain-enabled procurement platform developers.
Within the sourcing-network tier, Olam International and Archer Daniels Midland Company exemplify geographically diversified supply chain operators with crushing infrastructure spanning multiple continents. Golden Peanut & Tree Nuts occupies a position as the dominant North American shelling and ingredient processing specialist. These three anchors represent distinct competitive positions: trans-continental raw material access, multi-continental processing scale, and regional premium-tier concentration respectively.
| Leading Market Players |
|---|
| Golden Peanut & Tree Nuts |
| Wilmar International |
| Olam International |
| Birdsong Peanut Company |
| Hampton Farms |
| Archer Daniels Midland Company |
| Shandong Luhua Group |
| American Peanut Ingredients |
| Cargill Incorporated |
| Others |
Supply Flow & Price Mechanics
Expeller-pressed oil extraction replacing solvent-based hexane methods simultaneously shifts processing geography toward North American and European certified facilities and compresses capital recovery timelines for legacy infrastructure operators. This substitution dynamic concentrates pricing power among processors with cold-press capabilities while elevating working capital requirements for aflatoxin testing in African and South American origin zones.
Pricing Analysis
Mechanical-processing versus solvent-extraction technology generations create a pronounced pricing gap in premium ingredient specifications. Three-tier pricing structure across premium cold-pressed, standard expeller-pressed, and economy solvent-extracted levels stratifies the market, with ISO 22000 and organic certification tiers commanding measurable premiums over commodity grades. Pricing pressure stems from pulse protein substitution in plant-based meat applications, where allergen-free pea and lentil isolates displace peanut flour formulations. Food manufacturers with direct procurement teams exhibit lowest price sensitivity due to volume scale, while mid-tier bakery buyers through distributor networks face margin compression from lot-level traceability mandates.
Supply Chain Analysis
Strategic stockpile preferences dominate peanut ingredient procurement, with multinational food manufacturers maintaining 3-6 month coverage against weather-induced crop failures in concentrated origin zones. Geographic supply concentrates in the United States, Argentina, and China, where crushing infrastructure clusters create single-source vulnerability to Atlantic shipping disruptions. Raw material dependencies rest on pre-shipment aflatoxin verification, specialized roasting equipment, and specified particle-size milling capacity. Tariff exposure on South American kernel exports to Chinese processing facilities threatens margin stability. Distribution runs through vertically integrated processor-direct channels for large-volume contract buyers, while wholesale networks fragment service to mid-tier confectionery and bakery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled procurement platforms are transforming peanut ingredient sourcing into a platform-economy structure, with interoperability between lot-level traceability systems and food manufacturer ERP networks creating winner-take-most dynamics among certified processors.
For Market Incumbents: Consolidate supplier relationships around captive roasting and oil extraction capabilities to defend against direct-to-manufacturer digital platforms compressing distributor margins. Prioritize backward integration into African and South American farming operations to secure raw supply against weather-induced crop failures. ISO 22000 certification investment represents the critical lever for maintaining multinational food manufacturer approved supplier status as compliance timelines exclude mid-tier competitors.
For New Entrants and Emerging Players: FSSAI export eligibility fast-track positions Gujarat and Andhra Pradesh shelling operations to capture underpenetrated premium peanut butter and paste demand from Indian domestic snack manufacturers. Target the Saurashtra peninsula cluster for high-protein fraction mechanical processing, where European gluten-free bakery formulators seek alternative suppliers to United States and Argentine incumbents. Go-to-market angle should emphasize direct digital procurement portal participation to bypass legacy distributor networks and capture price transparency advantages.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed North American shelling cooperatives in Georgia and Alabama facing capital-intensive ERP upgrades for lot-level traceability mandates. Five-to-ten year viability favors processors with demonstrated EFSA novel food consultation navigation capabilities and established EU Green Deal bioeconomy funding access for hull fiber valorization. The signal to watch is SAMR enforcement intensity on Chinese domestic snack production bases, which would accelerate import demand for South American and United States origin specified particle-size paste.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Farming | Secures raw peanut supply chains against Argentine and Brazilian weather volatility for crushing facilities. |
| ISO 22000 Certification Fast-Track | Enables market access to multinational food manufacturer procurement programs excluding uncertified processors. |
| Blockchain Procurement Platform Partnership | Compresses distributor margins while delivering price transparency to large-volume direct contract buyers. |
| EFSA Novel Food Consultation Navigation | Avoids 18-24 month product development freezes for enzymatically modified protein isolates in European markets. |
| EU Green Deal Bioeconomy Positioning | Qualifies peanut hull fiber valorization projects for circular economy R&D funding in Baden-Württemberg corridor. |
Methodological Framework
Operator-level perspectives from shelling cooperative managers, food manufacturer procurement directors, and FSSAI licensing officers anchored the qualitative base for this analysis. Primary interviews with roasting facility engineers and gluten-free bakery formulators combined with secondary validation from FDA FALCPA guidance documents, EFSA novel food consultation records, and SAMR food safety standards. Trade data from customs records and SEC filings of publicly listed oilseed processors supplemented bottom-up and top-down triangulation across the peanut ingredient value chain.
Sensitivity analysis tested forecast robustness against alternative scenarios for aflatoxin testing cost inflation and pulse protein substitution rates. The analytical framework modeled volume and value outputs across product type segmentation, application tier differentiation, end-user procurement scale, and distribution channel concentration throughout the projection horizon. CAGRs derived from historical crushing capacity utilization trends and clean-label reformulation adoption curves, with specific inputs including organic certification penetration rates and direct-to-manufacturer digital platform transaction growth.
Decision-makers should treat outputs as directional under assumptions of sustained FDA and EFSA regulatory trajectory and stable Atlantic shipping corridor access; material deviation would warrant model refresh. Forecasts reflect base-case assumptions for plant-based protein adoption velocity and allergen management protocol standardization. Revision becomes warranted when pulse protein isolate pricing crosses thresholds that accelerate displacement of peanut flour in high-protein bakery applications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Spray-Dried Isolate Market
Ingredients
Europe Potato Protein Market
Ingredients
Passion Fruit Powder Market
Ingredients
Cocoa Derivatives Market
Ingredients
Grape Skin Extract Market
Ingredients
Protein Ingredients Market
Ingredients
Global Pea Protein Ingredients Market
Ingredients
Asia-Pacific Food Coating Ingredients Market
Ingredients
North America Lipid Market
Ingredients
Soy Flour Market
Ingredients
Farnesene Market
Ingredients
Low Fat Oil Market
Ingredients
Europe Malt Extract Market
Ingredients
Quark Powder Market
Ingredients
Soy Protein Hydrolysate Market
Ingredients
North America Gluten Free Flour Market