
 North America Sodium Reduction Ingredients Market | 2026-2036
North America Sodium Reduction Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
North America Sodium Reduction Ingredients Market Analytics
Clean-label food manufacturers is collapsing the historical dominance of conventional salt-reliant processed food producers across North America. Cargill Inc. leverages its integrated potassium mining and food ingredient distribution network to anchor supply security for regional meat processors. Kerry Group Plc competes through specialized taste modulation systems that mask bitterness in reduced-sodium formulations. Tate & Lyle Plc differentiates via advanced flavor enhancement technologies targeting bakery and snack applications.
Sodium reduction ingredients comprise functional compounds—primarily potassium chloride, yeast extracts, mineral salts, and amino acid-based taste modulators—engineered to replicate or enhance salty perception while lowering sodium content below 140mg per serving in finished goods. Their primary commercial purpose centers on enabling food manufacturers to meet reformulation targets without sacrificing consumer sensory acceptance. Salt substitutes dominate current volume flows due to established supply chains and familiar labeling, while taste modulators represent the fastest-expanding margin pool as patent-protected bitter-blocking technologies command premium positioning. Flavor enhancers occupy a mature, cost-competitive tier where yeast extract suppliers battle on fermentation scale and umami intensity consistency.
The FDA voluntary sodium reduction guidelines and USDA school meal sodium limits shape product development roadmaps across the United States, while Health Canada's sodium reduction strategy for processed foods drives parallel compliance investments north of the border. These frameworks elevate demand for documented sodium reduction claims and third-party validated reformulation support. Stakeholders must monitor evolving enforcement thresholds and clean-label certification requirements to anticipate which ingredient platforms will secure preferred supplier status with multinational food manufacturers.
Market Dynamics
Clean-label mandates from FDA voluntary sodium reduction targets are compressing reformulation timelines for processed food manufacturers across the United States and Canada. This regulatory pressure is forcing ingredient suppliers to accelerate bitterness-masking technologies and mineral salt blend development to maintain sensory parity in reduced-sodium products.
Growth Catalysts
- USDA school meal sodium limits:K-12 foodservice operators require documented sodium reduction claims, pulling demand for validated potassium chloride and yeast extract formulations into institutional supply chains.
- Midwest meat processing concentration:Large-scale sausage and cured meat production clusters in Illinois, Iowa, and Nebraska generate concentrated procurement volumes for mineral salt substitutes.
- Yeast extract fermentation scale-up:Advances in continuous fermentation systems reduce unit costs for umami-intense flavor enhancers, expanding addressable applications in snacks and savory bakery.
Market Restraints
- Potassium chloride supply concentration:Saskatchewan potash mining operations and limited North American refining capacity create geographic chokepoints for primary salt substitute feedstock.
- Bitter aftertaste technical ceiling:Current taste modulation systems fail to fully mask potassium chloride metallic notes above 30% sodium replacement levels in delicate applications.
- Health Canada compliance friction:Divergent sodium claim thresholds and labeling requirements between Canadian and US markets force dual-track product development and inventory segmentation.
Strategic Opportunities
- Quebec and Ontario dairy alternatives:Plant-based cheese and meat analog producers in Eastern Canada represent underpenetrated demand for sodium-reduced savory flavor systems.
- Precision fermentation-amino acid convergence:Combining microbial production with targeted bitter-blocking peptides opens clean-label taste modulation without synthetic additives.
- Direct-to-manufacturer technical service:Bypassing traditional distribution, ingredient suppliers embed reformulation scientists inside Midwest co-packer and private-label facilities.
Industry Challenges
- Sensory scientist talent scarcity:Food manufacturers struggle to recruit trained descriptive panel leaders and consumer insight specialists capable of validating reduced-sodium parity claims.
- Clean-label certification timeline compression:Third-party non-GMO and organic validations for new mineral salt sources extend product launch windows by 8-14 months.
- Legacy seasoning equipment incompatibility:Existing salt dispersion and tumbling systems in meat processing plants require capital retrofit to handle hygroscopic potassium chloride blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Sodium Reduction Ingredients Market |
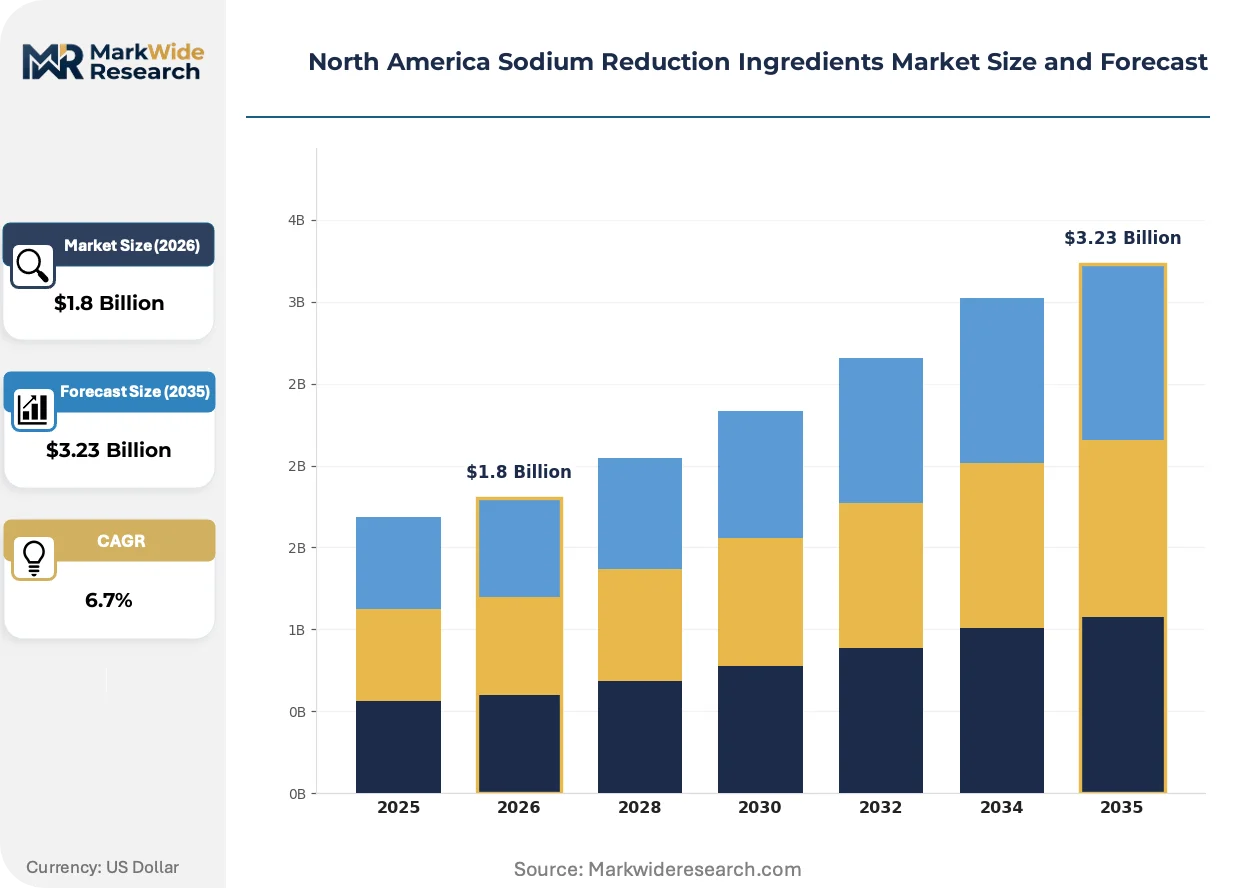
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavor Enhancers, Salt Substitutes, Taste Modulators, Nutraceuticals Application: Processed Foods, Snacks, Sauces, Meat Products End User: Food Manufacturers, Restaurants, Retailers, Caterers Form: Powder, Liquid, Granular, Tablet |
| Companies Covered | Cargill Inc., Kerry Group Plc, Tate & Lyle Plc, Givaudan SA, DSM NV, DuPont, Corbion N.V., Sensient Technologies Corporation, Biospringer, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Sodium Reduction Ingredients Market Evolving Landscape
Reformulation science is shifting from simple salt substitution toward multi-modal sodium perception engineering. This evolution integrates mineral chemistry, fermentation-derived flavor compounds, and neurosensory research to replicate salty taste through non-sodium pathways.
Bitter-blocking peptide technology is decomposing the historical trade-off between sodium reduction and consumer acceptance. These amino acid sequences bind to human TAS2R receptors, suppressing potassium chloride bitterness without adding calories or altering labeling. Large snack manufacturers in the US Mountain West and Texas are piloting these systems in extruded products and nut coatings. The structural consequence is compressing R&D cycles for reduced-sodium launches from 18-24 months toward 9-12 month competitive windows.
FDA voluntary sodium reduction targets for processed foods are triggering documented reformulation investments across the US packaged food sector. The agency's phased category-specific benchmarks for 2025-2030 are embedding sodium reduction into product development roadmaps rather than reactive line extensions. Bakery and prepared meals segments face the steepest percentage reduction requirements, driving accelerated procurement of yeast extracts and mineral salt blends with established supply security.
Mid-scale meat processors are consolidating ingredient supplier relationships around bundled technical service contracts. These arrangements embed supplier R&D staff directly inside customer pilot plants, replacing transactional procurement with co-developed formulation partnerships. The model is most visible in Wisconsin and Minnesota, where regional sausage and deli meat manufacturers lack internal sensory science capabilities and depend on external expertise for clean-label reformulation validation.
North America Sodium Reduction Ingredients Market Segmentation
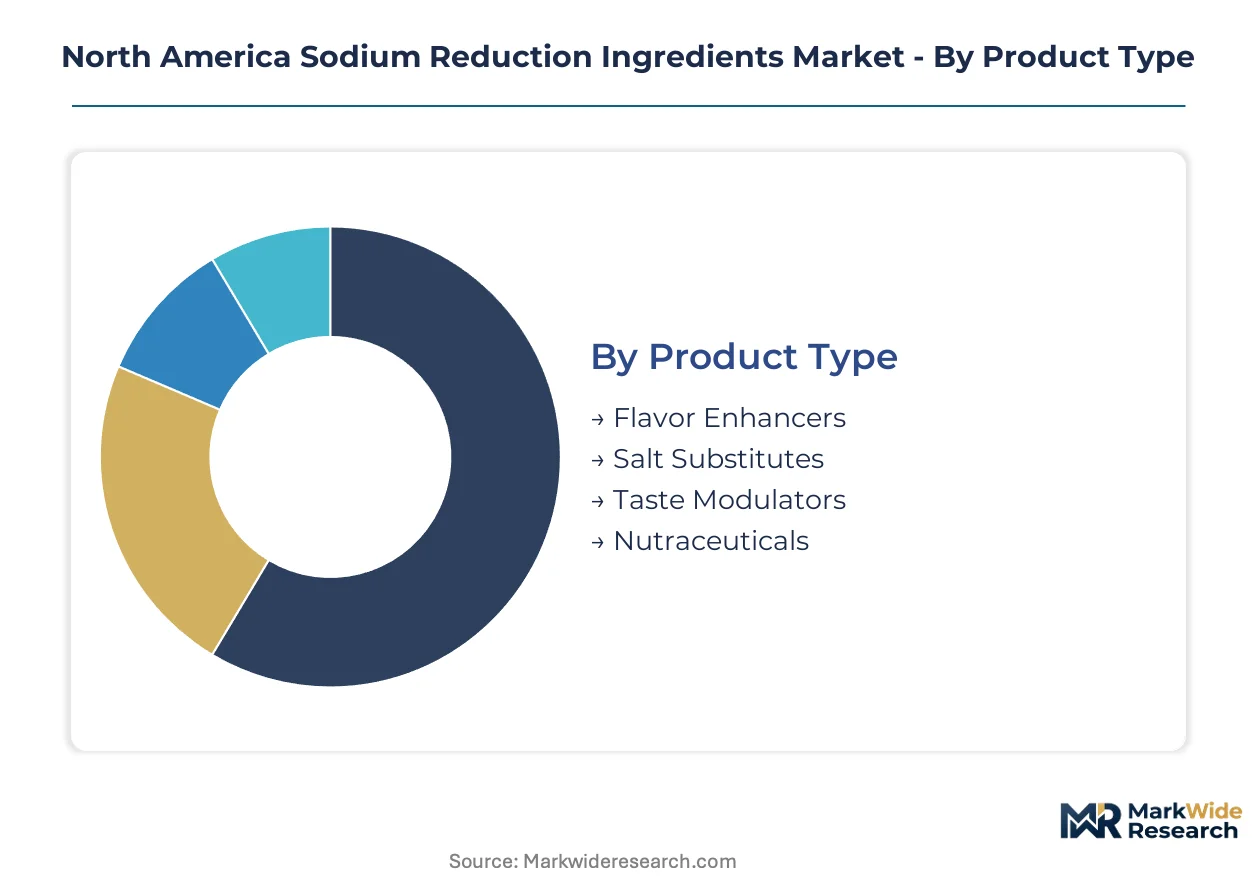
Sodium reduction ingredient purchasing patterns diverge sharply across product categories and end-use applications. Reformulation complexity and sensory performance requirements create distinct procurement behaviors that suppliers must navigate through specialized technical service models.
Product Type:
Salt substitutes face the most intense substitution pressure from emerging taste modulation technologies, forcing incumbent mineral salt suppliers to defend volume through integrated technical service bundling.
- Flavor Enhancers:Yeast extracts and hydrolyzed vegetable proteins deliver concentrated umami intensity through glutamate-rich fermentation-derived compounds. Meat processors in Nebraska and Iowa leverage these systems to maintain savory depth while cutting sodium below USDA school meal thresholds. The segment commands stable procurement volumes but faces margin compression from commoditized yeast extract supply.
- Salt Substitutes:Potassium chloride blends remain the workhorse platform for 20-35% sodium reduction in cured meats and baked goods. Saskatchewan potash mining concentration creates supply security risks that Midwest meat processors mitigate through multi-year offtake agreements with integrated distributors.
- Taste Modulators:Bitter-blocking peptides and nucleotide-based systems enable deeper sodium cuts without metallic aftertaste. These patent-protected platforms are climbing the fastest as snack manufacturers pilot 50%+ sodium reduction in extruded products.
- Nutraceuticals:Mineral-fortified salt alternatives target health-conscious retail segments with documented cardiovascular benefits.
Salt substitutes anchor the volume base while taste modulators gain share at the steepest rate.
Application:
Cost tier stratification separates mass-market reformulation from premium clean-label positioning, with mid-tier applications capturing the most dynamic procurement activity.
- Processed Foods:Canned soups, frozen dinners, and ready-to-eat meals face the steepest FDA sodium reduction percentage requirements. Manufacturers deploy yeast extract and potassium chloride layering to hit 140mg-per-serving targets without consumer rejection.
- Snacks:Extruded chips, crackers, and nut coatings demand precise salt crystal distribution control. Powder-based mineral salt substitutes dominate, though liquid taste modulators are expanding in seasoned coatings for uniform flavor delivery.
- Sauces:High-moisture formulations tolerate potassium chloride better than dry applications, enabling deeper sodium cuts in ketchup, salad dressings, and cooking sauces.
- Meat Products:Cured ham, bacon, and sausage production in Illinois and Wisconsin requires specialized potassium chloride blends with anti-caking agents for tumbling equipment compatibility.
Processed foods generate the largest procurement volumes while snacks demonstrate the most rapid technology turnover.
End User:
Customer type determines technical service intensity, with institutional operators demanding documented compliance validation that retail-facing manufacturers often bypass.
- Food Manufacturers:National packaged food companies maintain internal sensory science teams but outsource complex bitter-masking challenges to specialized ingredient suppliers. Co-packer consolidation in the Midwest is concentrating procurement leverage among fewer large-scale operators.
- Restaurants:Chain operators with centralized menu development specify sodium-reduced seasoning systems for franchise distribution. Quick-service sandwich chains in Texas and California pilot reformulated bread and sauce platforms.
- Retailers:Private-label product development teams at major grocers depend heavily on supplier R&D partnerships for clean-label reformulation.
- Caterers:Institutional foodservice operators serving K-12 and healthcare facilities must document sodium compliance for USDA and CMS reimbursement eligibility.
Food manufacturers dominate absolute demand while restaurants are expanding procurement most aggressively.
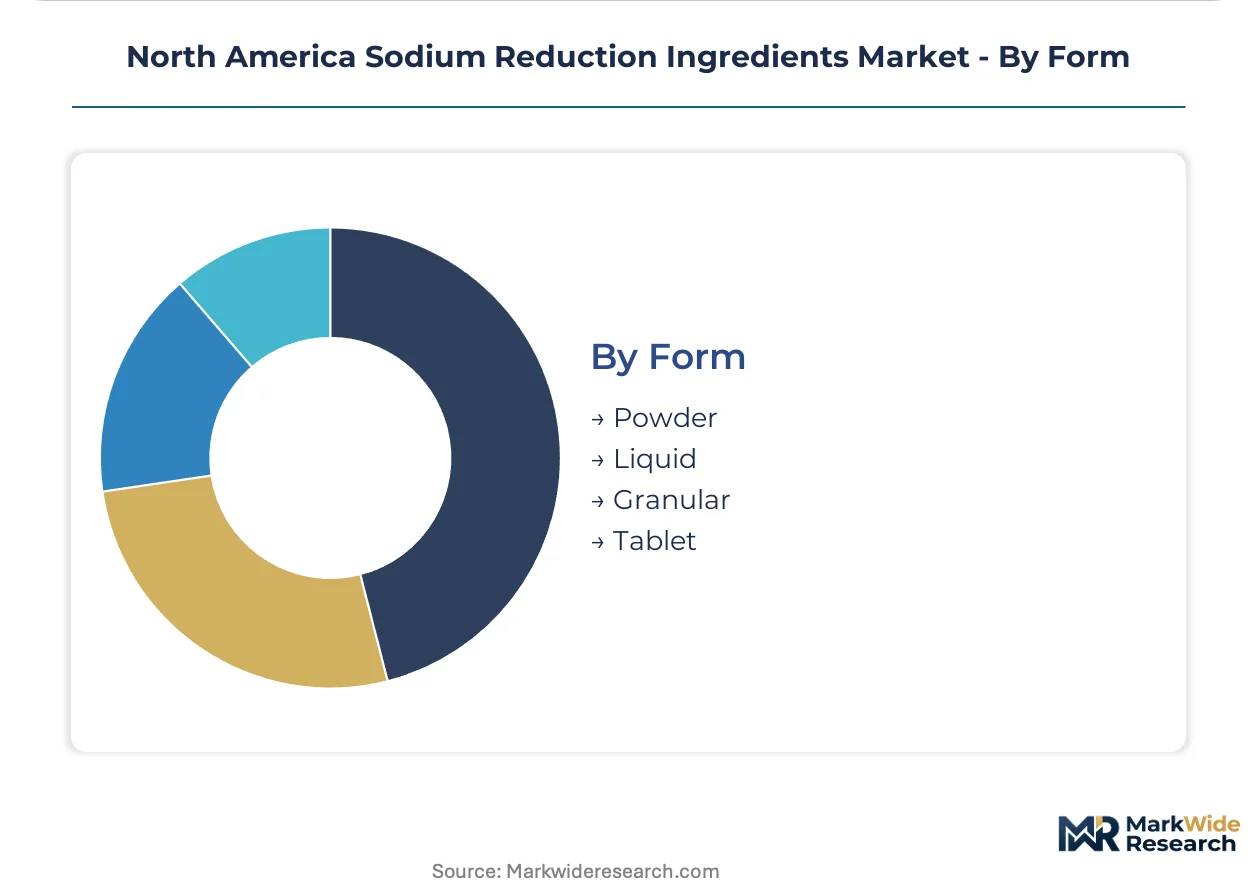
Form:
Supply concentration in powder processing infrastructure shapes competitive dynamics, with liquid and granular alternatives requiring specialized capital investment that limits supplier entry.
- Powder:Spray-dried mineral salt blends and yeast extract powders flow through existing seasoning equipment with minimal retrofit. The dominant form factor captures economies of scale in bulk handling and storage.
- Liquid:Brine-based potassium chloride solutions enable precise injection in processed meats and uniform distribution in sauces. Continuous fermentation systems for liquid yeast extracts are reducing unit costs below powder equivalents in high-volume applications.
- Granular:Crystal size engineering mimics salt dissolution kinetics for tabletop and finishing applications where immediate flavor impact matters.
- Tablet:Compressed mineral salt formats target foodservice portion control and consumer tabletop replacement markets.
Powder forms maintain volume leadership while liquid systems are advancing most quickly on cost-competitiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian potash exports from Saskatchewan supply Midwest US meat processors with potassium chloride feedstock, creating a cross-border trade corridor that anchors North American salt substitute supply security.
United States
Midwest meat processing clusters in Illinois, Iowa, and Wisconsin drive concentrated demand for mineral salt blends and yeast extract systems. FDA voluntary sodium reduction targets for processed foods compress reformulation timelines for national packaged food manufacturers. Chicago and Minneapolis-St. Paul co-packer facilities embed supplier R&D scientists directly inside pilot plants to accelerate clean-label validation.
Canada
Saskatchewan potash mining operations supply the majority of North American potassium chloride feedstock for salt substitute manufacturing. Health Canada's sodium reduction strategy for processed foods mandates parallel compliance investments from US exporters selling into Canadian retail channels. Quebec and Ontario plant-based dairy alternative producers represent emerging demand centers for sodium-reduced savory flavor systems.
Mexico
Central Mexico food processing corridors around Querétaro and Guanajuato expand procurement of yeast extracts for tortilla and snack seasoning applications. Mexican federal front-of-pack labeling regulations pressure sodium disclosure transparency for imported processed foods. Baja California and Nuevo León manufacturing clusters pilot reformulated seasoning systems for US-exported private-label products.
North America Sodium Reduction Ingredients Market Competitive Landscape
Listed leaders compete with private specialists across technical service intensity, with public companies leveraging capital markets for fermentation scale-up while private operators embed reformulation scientists inside customer facilities. The vendor base concentrates around three archetypes: integrated potassium miners with captive food-grade refining, specialized taste modulation technology licensors, and fermentation-derived flavor houses with continuous production systems. Dominant competitive moves include backward integration into Saskatchewan potash offtake agreements and direct-to-manufacturer technical service contracts that bypass traditional distribution.
Within the integrated supply tier, Cargill Inc. anchors North American potassium chloride security through captive mining and distribution infrastructure. Kerry Group Plc and Tate & Lyle Plc exemplify the technology-specialist archetype, with the former occupying a position in taste modulation systems and the latter representing advanced flavor enhancement capabilities for bakery and snack applications.
| Leading Market Players |
|---|
| Cargill Inc. |
| Kerry Group Plc |
| Tate & Lyle Plc |
| Givaudan SA |
| DSM NV |
| DuPont |
| Corbion N.V. |
| Sensient Technologies Corporation |
| Biospringer |
| Others |
Value Network & Pricing Analysis
Fermentation scale economies in yeast extract production compress unit costs below powder equivalents, concentrating supply leverage among continuous-system operators while establishing price floors that commodity mineral salt suppliers struggle to breach. This scale asymmetry rewards integrated potassium miners with captive refining capacity and penalizes standalone blenders dependent on Saskatchewan potash spot markets.
Pricing Analysis
Next-generation bitter-blocking peptide systems command premium positioning over established potassium chloride blends and legacy yeast extracts. Three-tier pricing structure across premium, standard, and economy levels segments buyers by reformulation complexity and sensory performance requirements. Cost compression in standard-grade mineral salts intensifies as Chinese fermentation capacity expands into North American yeast extract markets. Institutional foodservice operators serving K-12 and healthcare facilities demonstrate highest price sensitivity due to reimbursement-constrained procurement budgets, while premium snack manufacturers absorb premium taste modulation costs to accelerate clean-label positioning.
Supply Chain Analysis
Inventory lead times for Saskatchewan-derived potassium chloride stretch 8-14 weeks during peak Midwest meat processing seasons, forcing processors into multi-year offtake agreements. Supply concentrates in Canada for potash feedstock, the United States for fermentation-derived flavor systems, and Mexico for tortilla and snack seasoning applications. Raw material dependencies include Saskatchewan potash ore, Midwest corn-derived fermentation feedstocks, and Great Lakes region processing chemicals. Single-source vulnerability in Saskatchewan mining operations exposes downstream blenders to geographic concentration risk. Distribution runs through integrated ingredient distributors with embedded technical service capabilities rather than traditional commodity brokers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA voluntary sodium reduction targets and USDA school meal compliance creates formidable switching costs for institutional foodservice operators, embedding incumbent ingredient suppliers into validated supply chains that resist displacement.
For Market Incumbents: Fortify supply security through backward integration into Saskatchewan potash offtake agreements and captive refining capacity expansion. Deepen technical service embedding inside Midwest co-packer facilities to replace transactional procurement with co-development partnerships. Patent-protected bitter-blocking technologies from emerging biotech entrants threaten premium positioning in taste modulation segments. For New Entrants and Emerging Players: Differentiate on precision fermentation-derived amino acid systems that bypass synthetic additive labeling concerns while delivering clean-label bitter suppression. Quebec and Ontario plant-based dairy alternative producers represent the most penetrable white-space segment, with underdeveloped savory flavor system supply relative to reformulation demand. Direct-to-manufacturer technical service contracts bypassing traditional distribution offer the strongest go-to-market angle for mid-scale meat processors lacking internal sensory science capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated potassium miners with captive food-grade refining and long-term institutional offtake agreements. Long-term viability over the coming decade hinges on regulatory durability of sodium reduction mandates and clean-label certification requirements. Acquisition targets should display fermentation scale advantages or patent-protected taste modulation portfolios. The signal to watch is Health Canada enforcement threshold tightening relative to FDA benchmarks, which would accelerate dual-track compliance investments and expand addressable market for documented reformulation support services.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potash Supply | Captive Saskatchewan mining capacity secures feedstock against geographic concentration risk. |
| Precision Fermentation Scale-Up | Continuous amino acid production reduces unit costs below traditional extraction methods. |
| Embedded Technical Service Contracts | Supplier R&D scientists inside Midwest pilot plants accelerate clean-label validation timelines. |
| Bitter-Blocking Peptide Patent Portfolio | TAS2R receptor-targeting technologies enable 50%+ sodium reduction without metallic aftertaste. |
| Dual-Track Compliance Certification | Simultaneous FDA and Health Canada validation expands addressable market for US exporters. |
Research Methodology
Operator-level perspectives from food manufacturing R&D directors, sensory scientists at Midwest co-packers, procurement leads at institutional foodservice operators, and Saskatchewan potash mining executives anchored the qualitative base. Primary interview findings combined with secondary validation from FDA sodium reduction guidance documents, USDA school meal compliance databases, Health Canada processed food labeling regulations, and SEC filings from listed ingredient suppliers. Bottom-up volume modeling triangulated against top-down category spending analysis across the projection horizon.
Sensitivity analysis tested forecast robustness against regulatory enforcement intensity variations and raw material price volatility assumptions. Segmentation dimensions modeled include product type hierarchy, application category, end-user procurement behavior, and geographic production cluster concentration. CAGRs derived from category-specific volume trajectories weighted by reformulation timeline compression under FDA phased benchmarks. Industry-specific inputs incorporated fermentation capacity utilization rates and potassium chloride blend penetration curves across meat processing versus bakery applications.
Forecasts assume regulatory continuity in FDA voluntary sodium reduction targets and Health Canada processed food labeling regimes; material policy shifts would require re-modeling. Commodity price volatility in Saskatchewan potash markets and clean-label certification timeline extensions represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Europe Pea Starch Market
Ingredients
Ben Oil Market
Ingredients
Rooster Comb Extract Market
Ingredients
Cocoa Market
Ingredients
Protein Trends and Technologies Market
Ingredients
China Gelatin Market
Ingredients
Global Cocoa Ingredients Market
Ingredients
Mineral Premix Market
Ingredients
Bone and Joint Health Ingredients Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Proteose Peptone Market
Ingredients
Agave Inulin Market
Ingredients
Global Hydrolyzed Wheat Protein Market
Ingredients
France Sodium Reduction Ingredients Market
Ingredients
Mediterranean Marine Ingredients for Pet Health Market
Ingredients
Global Pine Pollen Powder Market