
 Animal Hormone Therapy Market | 2026-2036
Animal Hormone Therapy Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Hormone Therapy Market Outlook
China is rewriting competitive dynamics in animal hormone therapy through expanded biopharmaceutical manufacturing zones. Zoetis leverages its transcontinental distribution network to sustain supply continuity across veterinary channels. Boehringer Ingelheim anchors European production capacity with dedicated hormone synthesis facilities. Merck & Co. dominates North American veterinary hospital formulary placements through specialized reproductive health portfolios.
Animal hormone therapy encompasses the clinical administration of endocrine-active compounds including estrogen, progesterone, testosterone, and corticosteroids to modulate physiological functions in domestic and production animals, typically formulated as injectable suspensions, oral tablets, transdermal gels, or subcutaneous implants with defined release kinetics. These therapies serve primary commercial purposes in reproductive synchronization, growth optimization, behavioral modification, and endocrine disorder management across veterinary practice settings. Corticosteroid formulations occupy the largest revenue pool within product type segmentation due to their broad therapeutic index across inflammatory and autoimmune indications in both companion and livestock species. Implant delivery methods represent the fastest-growing category as producers seek extended-release formats that reduce handling frequency and improve compliance in large herd operations.
The FDA Center for Veterinary Medicine enforces stringent New Animal Drug Application requirements that govern hormone therapy approval timelines and label claims in the United States. The European Medicines Agency coordinates centralized marketing authorization through its Committee for Medicinal Products for Veterinary Use, while national regulators in Germany and France maintain pharmacovigilance oversight for hormone residues in food-producing animals. Veterinary stakeholders must monitor evolving residue tolerance thresholds and antimicrobial stewardship crossover policies that increasingly influence hormone therapy prescribing patterns and product development priorities.
Market Dynamics
Extended-release implant technology is compressing dosing frequency requirements across large-scale livestock operations, fundamentally restructuring veterinary service delivery economics and herd management labor allocation.
Growth Catalysts
- Reproductive Synchronization Protocols:Dairy operations in Wisconsin and Bavaria are standardizing timed artificial insemination programs that depend on prostaglandin and gonadotropin administration, creating consistent demand for hormone therapy products across 300+ day production cycles.
- EMA Centralized Authorization:The European Medicines Agency's Committee for Medicinal Products for Veterinary Use streamlined marketing authorization pathways for generic hormone formulations, reducing time-to-market for new entrants by consolidating previously fragmented national approvals.
- Subcutaneous Implant Manufacturing:Polymer matrix technology advances enable controlled release kinetics spanning 100-200 days, allowing feedlot operators to reduce handling stress and labor costs while maintaining growth promotion efficacy.
Market Restraints
- Active Pharmaceutical Ingredient Concentration:Synthesis of complex steroid hormones depends on a limited base of European and Chinese chemical manufacturers, creating supply vulnerability when environmental inspections disrupt production at single-source facilities.
- Residue Monitoring Protocols:The FDA's Safe Meat and Poultry Inspection Service enforces zero-tolerance enforcement actions for violative hormone residues in beef exports, compelling producers to maintain costly withdrawal documentation and testing regimens.
- Plant-Based Protein Substitution:Alternative protein investments in fermentation-derived dairy and cultivated meat are redirecting capital away from conventional livestock expansion, constraining addressable herd growth in developed markets.
Strategic Opportunities
- Companion Animal Therapeutics:Veterinary clinics in Germany and France are expanding hormone therapy applications beyond reproduction into behavioral management and endocrine disorder treatment for aging pet populations.
- Biopharmaceutical Manufacturing Zones:China's expanded veterinary API production clusters offer contract manufacturing capacity for hormone synthesis, enabling Western formulators to reduce cost structures through technology transfer partnerships.
- Precision Livestock Integration:Sensor-enabled estrus detection systems combined with automated hormone delivery protocols are creating demand for programmable implant devices that synchronize with digital herd management platforms.
Industry Challenges
- Veterinary Pharmaceutical Formulation Expertise:Extended-release product development requires specialized knowledge in polymer science and pharmacokinetic modeling that resides in a narrow talent pool concentrated at legacy animal health companies.
- Multinational Label Harmonization:Divergent residue tolerance thresholds between the FDA, EMA, and national regulators in Brazil and Australia force manufacturers to maintain separate product specifications and documentation systems for each export destination.
- Cold Chain Integrity:Temperature-sensitive biological hormone products require validated storage and distribution infrastructure that remains underdeveloped in emerging livestock production regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Hormone Therapy Market |
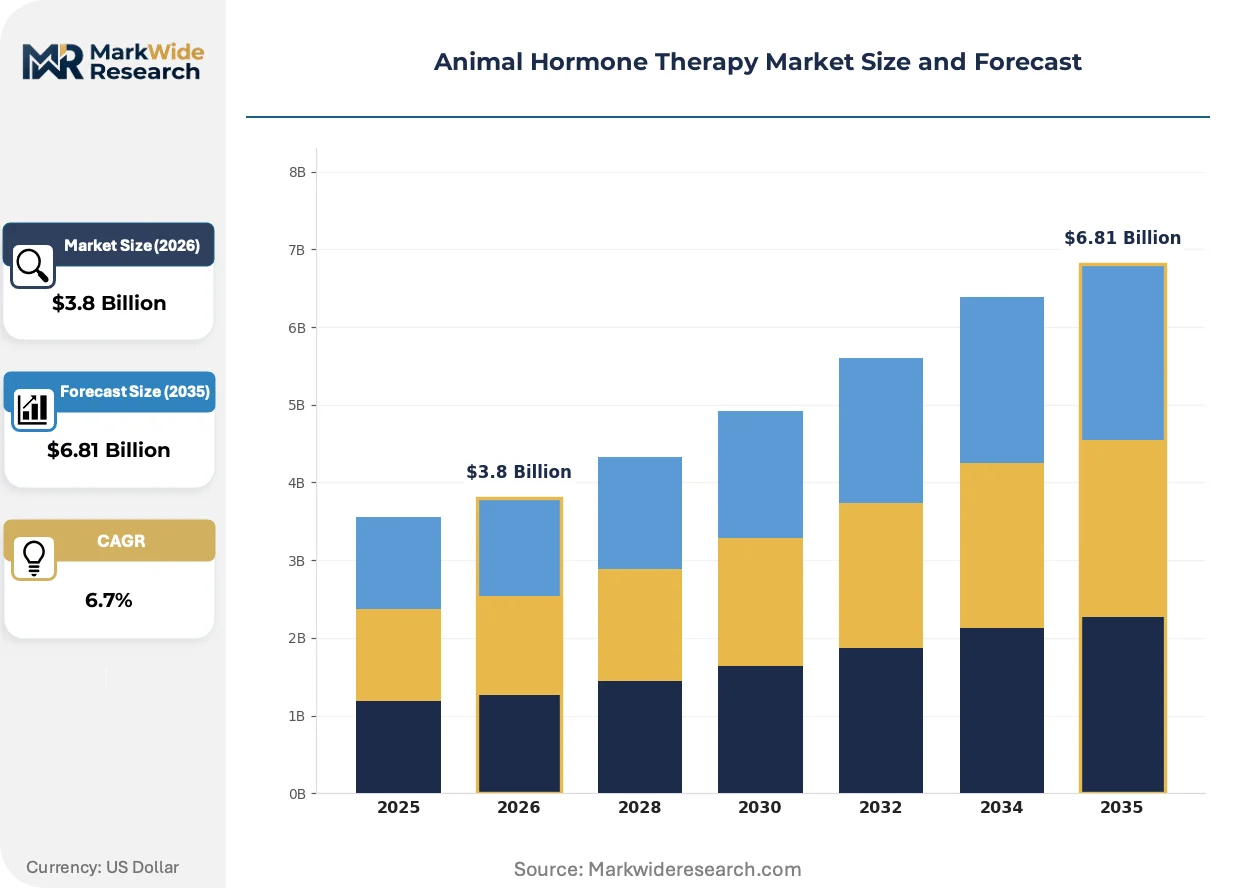
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Estrogen, Progesterone, Testosterone, Corticosteroids Delivery Method: Injectable, Oral, Transdermal, Implant Animal Type: Dogs, Cats, Horses, Livestock Therapeutic Area: Reproductive Health, Growth Promotion, Behavioral Issues, Endocrine Disorders |
| Companies Covered | Merck & Co., Soparfin SCA (Vetoquinol), Boehringer Ingelheim, IDEXX Laboratories, CEVA Sante Animale, Virbac Group, Zoetis, Dechra Pharmaceuticals, Elanco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Hormone Therapy Market Strategic Shifts
Digital herd management platforms are converging with hormone delivery systems to enable precision-timed interventions, while regulatory scrutiny of food safety residues intensifies formulation innovation requirements.
Sustained-release polymer matrices containing trenbolone acetate and estradiol benzoate enable growth promotion in cattle with single-administration protocols spanning 120-150 days. Feedlot operators in the Texas Panhandle and Queensland are adopting these implants at accelerating rates to reduce labor costs and animal handling stress. The technology is migrating from premium seedstock operations into mainstream commercial beef production, compressing margins for conventional injectable growth promotant suppliers.
The FDA Center for Veterinary Medicine's revised Guidance for Industry 263 eliminates over-the-counter availability of medically important antimicrobial hormones, reclassifying these products as prescription-only veterinary feed directives. This policy shift forces producers to establish documented veterinary-client-patient relationships before accessing combination hormone-antimicrobial implants. Large integrated pork production systems in Iowa and North Carolina are responding by consolidating veterinary service contracts and investing in on-staff veterinary capacity.
Consolidated procurement by integrated protein companies is displacing traditional distributor-mediated purchasing for hormone therapy products. Tyson Foods and JBS are negotiating direct supply agreements with manufacturers for implant formulations, bypassing veterinary distribution intermediaries. This channel compression is most visible in the US Midwest, where vertically coordinated cattle feeding operations now account for the majority of volume purchases previously fragmented across independent feedyards.
Animal Hormone Therapy Market Segmentation
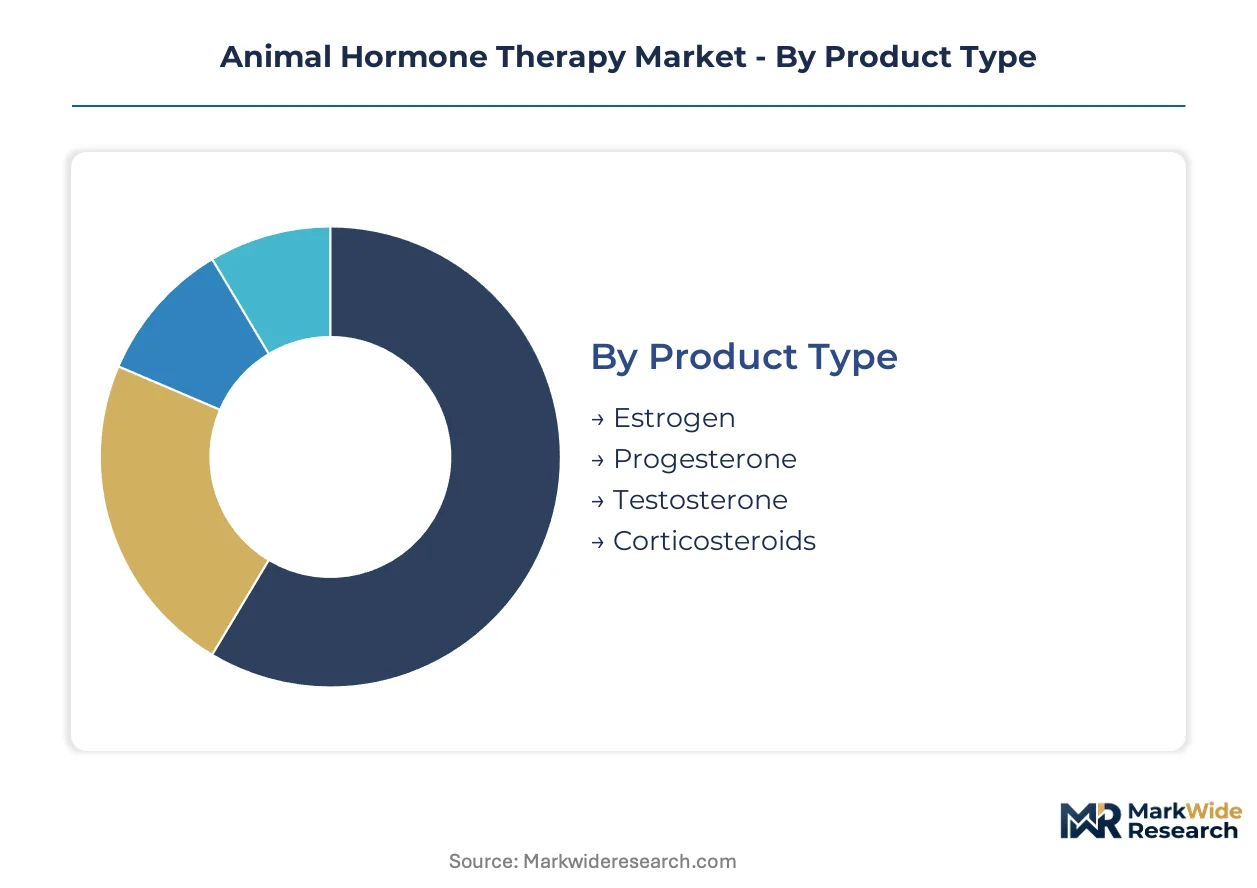
Animal hormone therapy markets fragment across four dimensions that determine pricing power, regulatory exposure, and customer loyalty. Product chemistry and delivery mechanism interact to shape margin structures, while animal type and therapeutic indication define addressable population sizes and treatment frequencies.
Product Type:
Corticosteroids turn inventory fastest due to acute indication patterns, while sex hormones operate on slower reproductive cycle timelines that compress reorder frequency.
- Corticosteroids:Synthetic glucocorticoid and mineralocorticoid formulations address inflammatory, allergic, and autoimmune conditions across species. Demand concentrates in companion animal emergency clinics in Germany and the United States, driven by rising atopic dermatitis diagnoses and post-surgical recovery protocols.
- Progesterone:Natural and synthetic progestin products regulate estrous cycles and support pregnancy maintenance in breeding operations. Dairy cooperatives in Wisconsin and Bavaria standardize timed artificial insemination programs that create predictable 21-day dosing intervals across 300+ day production cycles.
- Estrogen:Estradiol-based therapies manage follicular development and estrus suppression in performance horses and production livestock.
- Testosterone:Androgen replacement and anabolic applications target behavioral modification and muscle development in working animals.
Corticosteroids dominate installed base. Progesterone is where expansion concentrates.
Delivery Method:
Cost tier separation runs sharpest here, with implant manufacturing complexity supporting premium positioning against commoditized injectable volumes.
- Implant:Subcutaneous polymer matrix devices release active compounds over 100-200 days through controlled degradation kinetics. Feedlot operators in the Texas Panhandle and Queensland cattle stations are adopting single-administration protocols that eliminate repeat handling and reduce labor costs.
- Injectable:Aqueous and oil-based suspensions deliver immediate bioavailability for acute therapeutic interventions. Veterinary hospitals in France maintain formulary preference for parenteral corticosteroids in emergency presentations.
- Oral:Tablet and liquid formulations enable owner-administered chronic therapy in companion animals.
- Transdermal:Gel and patch applications provide non-invasive absorption for behavioral and replacement indications.
Injectable formats dominate installed base. Implant is climbing the fastest.
Animal Type:
Volume concentration tilts toward production animals, while margin capture favors companion species with higher willingness-to-pay for chronic therapy.
- Livestock:Cattle, swine, and poultry operations apply hormones for growth optimization and reproductive synchronization at population scale. Integrated protein companies in Iowa and North Carolina negotiate direct supply agreements that bypass traditional veterinary distribution channels.
- Dogs:Aging pet populations in German and French clinics drive demand for thyroid replacement, adrenal support, and behavioral modulation therapies.
- Horses:Performance and breeding operations require precise endocrine management for competition eligibility and fertility outcomes.
- Cats:Feline-specific formulations address diabetes management and stress-related behavioral conditions in indoor populations.
Livestock dominates installed base. Dogs is where expansion concentrates.
Therapeutic Area:
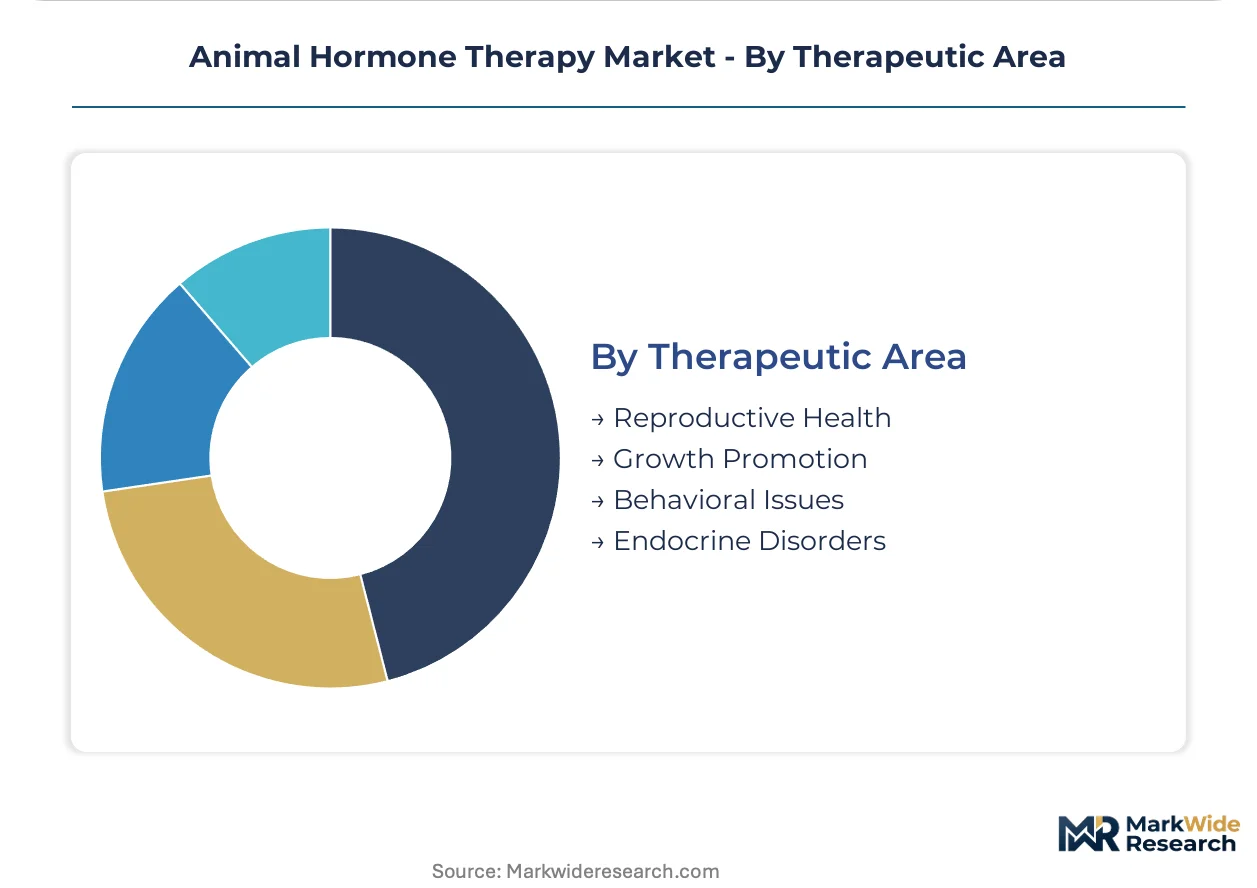
Application maturity varies sharply, with growth promotion facing regulatory headwinds while endocrine disorder treatment gains clinical acceptance.
- Reproductive Health:Estrus synchronization, pregnancy maintenance, and fertility optimization protocols dominate dairy and beef breeding operations. The EMA's centralized authorization pathway streamlines marketing approval for generic gonadotropin formulations across member states.
- Growth Promotion:Anabolic implants improve feed conversion efficiency in cattle finishing systems. FDA residue monitoring protocols enforce zero-tolerance enforcement actions that compel costly withdrawal documentation and testing regimens for export-oriented producers.
- Endocrine Disorders:Hypothyroidism, hyperadrenocorticism, and diabetes mellitus management extends to aging companion animal populations.
- Behavioral Issues:Hormonal intervention addresses aggression, anxiety, and inappropriate elimination in domestic pets.
Reproductive health dominates installed base. Endocrine disorders is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's veterinary pharmaceutical cold chain infrastructure underwrites European distribution capacity for temperature-sensitive hormone therapies, while China's expanded biopharmaceutical manufacturing zones reshape API supply geography.
United States
Dairy cooperatives in Wisconsin standardize timed artificial insemination protocols that create predictable demand cycles for prostaglandin and gonadotropin products. The FDA Center for Veterinary Medicine enforces prescription-only veterinary feed directives that reclassify combination hormone-antimicrobial implants. Feedlot operators in the Texas Panhandle adopt single-administration implant protocols spanning 120-150 days to reduce labor costs.
Germany
Veterinary clinics across Bavaria and North Rhine-Westphalia expand hormone therapy applications into behavioral management and endocrine disorder treatment for aging companion animals. The Federal Office for Consumer Protection and Food Safety maintains pharmacovigilance oversight for hormone residues in food-producing animals. Manufacturing clusters in Baden-Württemberg host dedicated hormone synthesis facilities serving European formulation demand.
China
Expanded veterinary API production clusters in Jiangsu and Zhejiang provinces offer contract manufacturing capacity for steroid hormone synthesis. The National Medical Products Administration coordinates marketing authorization for imported hormone formulations while domestic manufacturers scale output. Yangtze River Delta biopharmaceutical zones enable Western formulators to reduce cost structures through technology transfer partnerships.
Brazil
Integrated beef production systems in São Paulo and Mato Grosso states drive demand for growth promotion implants in cattle finishing operations. ANVISA maintains residue monitoring protocols that align with FDA export requirements for beef shipments to the United States. Commercial feedyards in the Center-West region negotiate direct supply agreements with hormone manufacturers, bypassing traditional distribution channels.
Australia
Cattle stations in Queensland and New South Wales adopt extended-release implant technology to reduce handling frequency across remote pastoral operations. The Therapeutic Goods Administration coordinates with the Australian Pesticides and Veterinary Medicines Authority on hormone residue tolerance thresholds for export-oriented producers. Precision livestock integration projects in Victoria combine sensor-enabled estrus detection with automated hormone delivery protocols.
Animal Hormone Therapy Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in API synthesis and polymer matrix manufacturing. The vendor base concentrates around legacy animal health companies with established veterinary distribution relationships and emerging contract manufacturers in expanded biopharmaceutical zones. Three archetypes dominate: integrated pharmaceutical conglomerates with transcontinental distribution networks, mid-cap specialists focused on reproductive health portfolios, and regional formulators leveraging technology transfer partnerships for cost-competitive supply. Competitive moves center on direct procurement negotiations with integrated protein companies and capacity expansion in controlled-release implant manufacturing.
Among integrated pharmaceutical conglomerates, Merck & Co. and Zoetis occupy positions that exemplify platform-scale distribution architecture, while Boehringer Ingelheim anchors European production capacity through dedicated hormone synthesis infrastructure. These companies represent the tier that sustains supply continuity across veterinary channels through captive manufacturing and established regulatory relationships.
| Leading Market Players |
|---|
| Merck & Co. |
| Soparfin SCA (Vetoquinol) |
| Boehringer Ingelheim |
| IDEXX Laboratories |
| CEVA Sante Animale |
| Virbac Group |
| Zoetis |
| Dechra Pharmaceuticals |
| Elanco |
| Others |
Value Chain & Pricing Dynamics
Single-source API dependency in Chinese and European steroid hormone synthesis creates simultaneous vulnerability in both pricing tier compression and supply chain redundancy. This concentration forces formulators to accept volatile input costs while maintaining rigid residue compliance documentation across FDA and EMA jurisdictions.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations between integrated protein companies and implant manufacturers. Three-tier pricing structure across premium extended-release, standard injectable, and economy generic levels reflects polymer matrix complexity versus commodity suspension formulations. Cost compression in the economy tier intensifies because Brazilian and Australian feedlot operators consolidate direct purchasing agreements. Small independent veterinary clinics in Germany exhibit highest price sensitivity, while Tyson Foods and JBS demonstrate lowest sensitivity due to captive veterinary capacity and long-term supply contracts.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic sourcing decisions for active pharmaceutical ingredients. Steroid hormone synthesis concentrates in Jiangsu and Zhejiang provinces, with secondary capacity in Baden-Württemberg and Basel-region facilities. Polymer matrix substrates, controlled-release coatings, and sterilized packaging components constitute critical input dependencies. Single-source vulnerability persists at fermentation-derived gonadotropin facilities subject to environmental inspection disruptions. Distribution runs through Rotterdam cold chain infrastructure for European veterinary channels, while direct manufacturer-to-feedyard logistics predominate in North American livestock operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision livestock platform economics are consolidating around sensor-enabled estrus detection systems that demand interoperable hormone delivery protocols. This ecosystem shift rewards vendors capable of API synthesis, implant manufacturing, and digital integration across a unified technology stack.
For Market Incumbents: Build regulatory data moats through residue pharmacovigilance databases that generic entrants cannot replicate. Deepen captive hormone synthesis capacity in expanded Chinese biopharmaceutical zones to offset European API cost structures. Consolidate veterinary distribution relationships in Germany and France before channel compression accelerates. Defend against emerging contract manufacturers by securing exclusive polymer matrix technology licenses from materials science specialists. For New Entrants and Emerging Players: Pursue companion animal endocrine disorder management in aging pet populations across French and German veterinary clinics. Target programmable implant device development that synchronizes with digital herd management platforms in Australian cattle stations. Exploit technology transfer partnerships with Jiangsu province API producers to achieve cost-competitive supply positioning. Establish go-to-market presence through direct veterinary clinic relationships rather than distributor-mediated channels. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform operators with captive manufacturing and regulatory filing capabilities. Long-term viability across the projection horizon rests on backward integration into steroid hormone synthesis and forward integration into precision livestock data services. Acquisition target archetype: mid-cap reproductive health specialists with established EMA centralized authorizations and dormant polymer science R&D programs. Signal to watch: feedlot operator adoption rates of single-administration implant protocols exceeding conventional injectable reorder frequencies.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Release Implant Manufacturing Scale-Up | Polymer matrix capacity expansion in Texas Panhandle feedlot corridors reduces per-unit labor costs for cattle finishing operations. |
| EMA Centralized Authorization Pathway Investment | Streamlined generic gonadotropin approvals across member states accelerate time-to-market for reproductive synchronization protocols. |
| Precision Livestock Platform Integration | Sensor-enabled estrus detection systems in Queensland cattle stations create demand for programmable hormone delivery devices. |
| API Production Technology Transfer Partnership | Jiangsu province biopharmaceutical zones enable Western formulators to reduce steroid hormone synthesis cost structures. |
| Veterinary Distribution Channel Consolidation | Direct supply agreements with Iowa and North Carolina pork production systems displace traditional distributor intermediaries. |
Study Parameters
Desk research of FDA New Animal Drug Application filings, EMA Committee for Medicinal Products for Veterinary Use decisions, and veterinary formulary databases preceded structured interviews with reproductive health product managers, feedlot operations directors, polymer science R&D leads, and companion animal clinic veterinarians. Secondary validation drew from customs trade records, SEC 10-K veterinary segment disclosures, and residue monitoring protocol publications. Bottom-up triangulation across implant shipment volumes and top-down reconciliation against protein company procurement disclosures anchored market sizing.
Assumptions held fixed across the modeling period include regulatory residue tolerance thresholds, polymer degradation kinetics in extended-release formulations, and veterinary feed directive classification status. Variables tested encompassed Chinese environmental inspection frequency impacts on API availability, precision livestock platform adoption curves, and integrated protein company vertical coordination intensity. Segmentation modeling addressed product chemistry, delivery mechanism, animal type, and therapeutic indication dimensions. CAGR derivation rested on install-base expansion rates in companion animal clinics and replacement demand cycles in livestock operations.
Sensitivities concentrate around FDA withdrawal period enforcement actions, EMA pharmacovigilance signal detection, and Chinese API facility inspection outcomes. Forecasts reflect assumptions regarding regulatory pathway stability and polymer matrix manufacturing yield consistency. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Leukocytoclastic Vasculitis Market
Specialty Medicine
Personalized Medicine Market
Specialty Medicine
Global Wolff Parkinson White Syndrome Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Cutaneous Fibrosis Treatment Market
Specialty Medicine
Global Primary Immunodeficiency Therapeutics Market
Specialty Medicine
Castrate Resistant Prostate Cancer Therapeutics Market
Specialty Medicine
Global Sarcopenia Treatment Market
Specialty Medicine
Global Lichen Nitidus Treatment Market
Specialty Medicine
Microcephaly Market
Specialty Medicine
Global Alopecia Market
Specialty Medicine
Uterine Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Endometrial Cancer Market
Specialty Medicine
Global Non-Oncology Precision Medicine Market