
 Axillary Hyperhidrosis Treatment Market | 2026-2036
Axillary Hyperhidrosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Axillary Hyperhidrosis Treatment Market Outlook
Capital-intensity divergence between energy-based device manufacturers and topical pharmaceutical developers is bifurcating competitive dynamics in axillary hyperhidrosis care. AbbVie leverages its established neuromodulator infrastructure to sustain dominance in botulinum toxin segments. miraDry anchors the microwave therapy niche with proprietary sweat gland ablation systems that command premium placement in dermatology clinics.
Axillary hyperhidrosis treatment encompasses medical and procedural interventions that reduce eccrine sweat gland activity through pharmacological inhibition, neuromuscular blockade, or selective thermolysis of glandular tissue. Microwave therapy devices operate at frequencies that generate localized heat to destroy sweat glands while preserving surrounding dermal structures. Botulinum toxin injections represent the largest revenue pool within product type segments due to repeat treatment cycles and broad clinician familiarity. Laser therapy competes for share in the technology dimension by offering precision targeting with shorter recovery profiles than surgical excision. Dermatology clinics capture disproportionate margin across end user segments by bundling diagnostic assessment with procedural delivery.
FDA oversees botulinum toxin labeling and device premarket clearance through its Center for Devices and Radiological Health and Center for Drug Evaluation and Research. The EU MDR imposes clinical evidence requirements on energy-based devices that extend certification timelines for microwave and radiofrequency systems. Stakeholders must monitor evolving reimbursement decisions by Medicare and private payers that determine patient access to procedural versus pharmaceutical interventions.
Market Dynamics
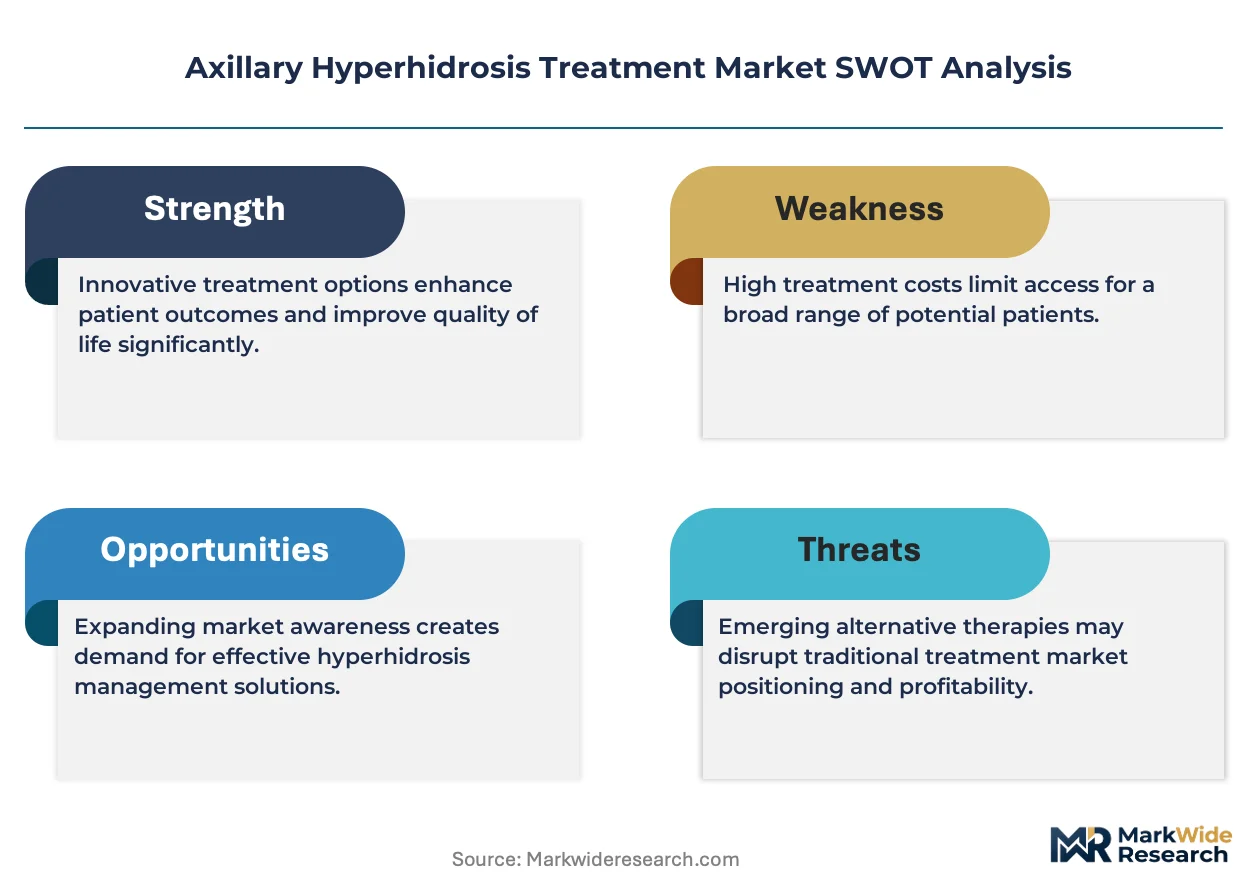
Energy-based device manufacturers face divergent capital requirements compared to topical pharmaceutical developers, splitting competitive dynamics between high-capex hardware platforms and lower-barrier drug formulations.
Growth Catalysts
- Botulinum toxin repeat cycles:Patient retention through quarterly injection schedules sustains recurring revenue streams for neuromodulator providers.
- EU MDR compliance pathways:Energy-based device manufacturers leveraging existing clinical evidence packages accelerate certification timelines for microwave ablation systems.
- Dermatology clinic consolidation:Multi-site aesthetic chains in the United States bundle diagnostic assessment with procedural delivery, expanding addressable patient pools.
Market Restraints
- Device capex concentration:Microwave therapy systems require substantial upfront investment, limiting deployment to well-capitalized clinic networks.
- Reimbursement heterogeneity:Medicare and private payer coverage decisions for hyperhidrosis procedures vary across United States state lines, creating access inequities.
- Topical antiperspirant substitution:Over-the-counter aluminum chloride formulations retain first-line treatment status among cost-sensitive patients.
Strategic Opportunities
- Japan's aging aesthetic patient base:Metropolitan dermatology practices in Tokyo and Osaka show readiness to adopt premium energy-based interventions for quality-of-life conditions.
- Telemedicine pre-screening:Virtual consultation platforms reduce patient acquisition costs for procedural candidates prior to in-clinic assessment.
- FDA expanded indication pathways:Botulinum toxin developers pursuing label extensions beyond axillary to palmar and plantar sites unlock incremental addressable populations.
Industry Challenges
- Interventional dermatology training pipelines:Microwave and laser device operation requires specialized hands-on certification that outpaces current fellowship output.
- Cross-border MDR evidence harmonization:Manufacturers seeking simultaneous United States and European clearance face divergent clinical endpoint requirements that prolong development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Axillary Hyperhidrosis Treatment Market |
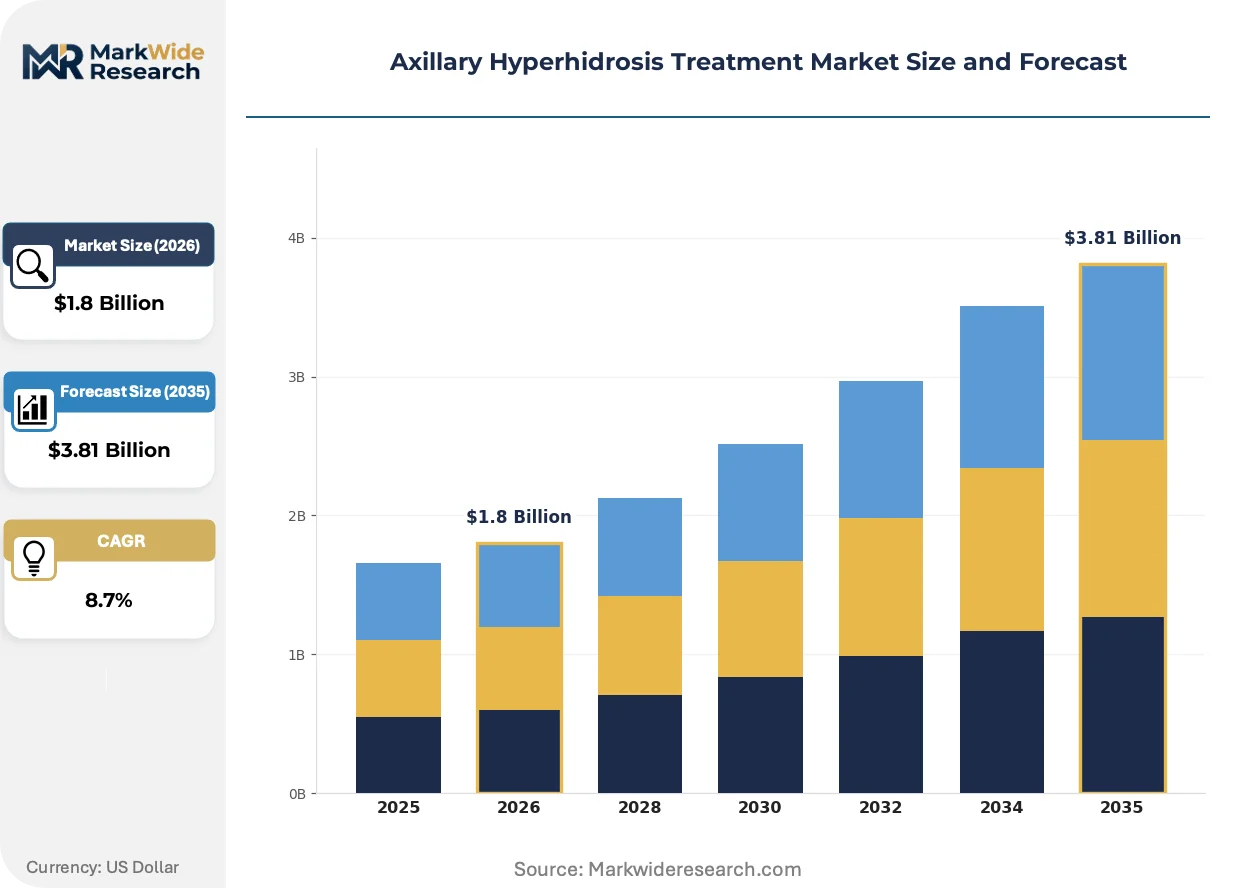
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antiperspirants, Iontophoresis Devices, Botulinum Toxin, Surgical Procedures Technology: Laser Therapy, Microwave Therapy, Radiofrequency, Chemical Treatment End User: Hospitals, Dermatology Clinics, Home Care, Ambulatory Surgical Centers Distribution Channel: Online Pharmacies, Retail Pharmacies, Direct Sales, Hospital Pharmacies |
| Companies Covered | Allergan plc (AbbVie), Journey Medical Corporation, Riemann A/S, SweatBlock, miraDry, GlaxoSmithKline Plc, Revance Therapeutics, Merz Pharma, Botanix Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Axillary Hyperhidrosis Treatment Market Strategic Shifts
Microwave therapy hardware is undergoing substantial form-factor reduction while regulatory frameworks on both sides of the Atlantic impose stricter clinical evidence demands on energy-based interventions.
Radiofrequency sweat gland ablation technology is miniaturizing from cart-based systems to handheld platforms suitable for outpatient deployment. Smaller dermatology practices in Germany and the United States are piloting these compact units to expand service menus without dedicated procedure rooms. This hardware compression is miniaturizing capital barriers and enabling point-of-care placement previously restricted to hospital-affiliated centers.
The EU MDR now mandates extended follow-up data for class IIa and IIb energy-based devices, forcing manufacturers to sponsor post-market clinical studies. European notified bodies have extended review timelines by twelve to eighteen months for microwave and laser systems lacking predicate device equivalence. Device developers are responding by prioritizing United States FDA 510(k) clearance first, then leveraging that dossier for European submissions.
Patients are self-referring through direct-to-clinic digital channels rather than primary care gatekeepers, compressing the diagnostic-to-treatment interval. Aesthetic-focused platforms in the United States and United Kingdom now offer hyperhidrosis-specific booking workflows that bypass traditional insurance pre-authorization steps. This channel shift is most pronounced among working-age professionals aged 25-45 seeking same-week procedural appointments.
Axillary Hyperhidrosis Treatment Market Segmentation
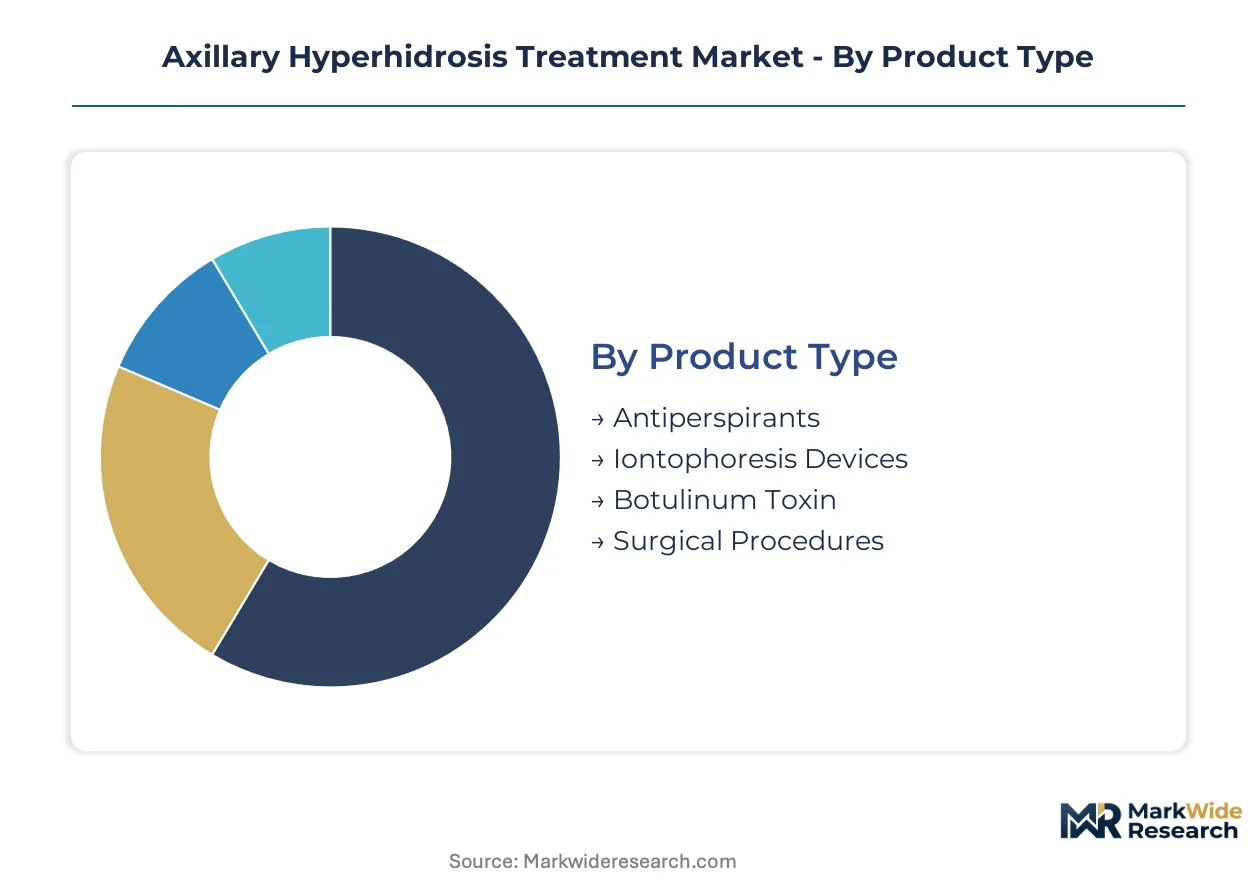
Axillary hyperhidrosis treatment segments fragment across therapeutic modality, energy delivery mechanism, care setting, and procurement pathway. Each dimension carries distinct margin profiles, regulatory burdens, and patient access constraints that shape competitive positioning.
Product Type:
Antiperspirants and iontophoresis devices concentrate demand in domestic self-care markets across the United States and Germany, while botulinum toxin and surgical procedures flow through export-led specialist channels into Japan and metropolitan European clinics.
- Antiperspirants:Aluminum chloride formulations dominate first-line intervention with over-the-counter accessibility and minimal clinical oversight. United States retail channels capture volume through pharmacy chains and mass merchandisers, though substitution pressure from prescription alternatives constrains premium pricing.
- Iontophoresis Devices:Home-use electrical systems deliver tap water iontophoresis through battery-powered units with programmable current modulation. German and Japanese patients favor these devices for palmar-plantar extension cases where clinic access is limited by reimbursement thresholds.
- Botulinum Toxin:Intradermal neuromodulator injections require physician administration and sustain recurring revenue through quarterly retreatment cycles. United States dermatology clinics and hospital outpatient departments anchor demand, with AbbVie's established infrastructure commanding preferred formulary placement.
- Surgical Procedures:Endoscopic thoracic sympathectomy and localized sweat gland excision address refractory cases through irreversible intervention. Japanese tertiary centers and select German university hospitals maintain surgical volume despite compensatory hyperhidrosis risks limiting patient candidacy.
Botulinum toxin commands the established base. The steepest expansion runs through iontophoresis devices.
Technology:
Cost stratification separates premium energy-based platforms from commodity chemical approaches, with laser and microwave systems targeting affluent patient segments while radiofrequency miniaturization compresses capital barriers for mid-tier clinics.
- Laser Therapy:Nd:YAG and diode platforms deliver selective photothermolysis to eccrine glands with precision targeting and abbreviated recovery profiles. United States aesthetic chains and German dermatology practices deploy these systems for working-age professionals seeking same-week return to activity.
- Microwave Therapy:miraDry systems generate localized thermocoagulation at 5.8 GHz to destroy sweat glands while sparing adjacent dermal structures. United States clinic networks with dedicated procedure rooms capture premium placement, though device capex limits penetration to well-capitalized operators.
- Radiofrequency:Fractional and bulk heating modalities are miniaturizing from cart-based to handheld configurations suitable for outpatient deployment. Compact units enable German and United States smaller practices to expand service menus without infrastructure investment.
- Chemical Treatment:Topical anticholinergics and botulinum toxin formulations occupy the lowest cost tier with broad accessibility but limited duration of effect. First-line status among cost-sensitive patients preserves volume despite efficacy gaps versus energy-based alternatives.
Laser therapy commands the established base. The steepest expansion runs through radiofrequency miniaturization.
End User:
Patient acuity and reimbursement maturity determine site-of-care selection, with complex comorbid cases funneling toward hospitals while uncomplicated primary axillary presentations concentrate in dermatology clinics.
- Hospitals:Tertiary centers manage refractory cases requiring multidisciplinary coordination with cardiology or neurology for compensatory hyperhidrosis complications. Japanese university hospitals and German Klinikum networks anchor inpatient surgical volume.
- Dermatology Clinics:Specialized aesthetic and medical dermatology practices capture disproportionate margin through bundled diagnostic assessment and procedural delivery. United States multi-site chains and German Hautarztpraxen dominate botulinum toxin and energy-based intervention volume.
- Home Care:Self-administered antiperspirants and iontophoresis devices serve mild-to-moderate cases with minimal clinical oversight. United States direct-to-consumer channels and German Apotheke e-commerce platforms sustain replenishment demand.
- Ambulatory Surgical Centers:Freestanding facilities perform localized sweat gland excision and select microwave ablations on scheduled basis. United States ASC networks leverage streamlined reimbursement pathways for procedural efficiency.
Dermatology clinics command the established base. The steepest expansion runs through ambulatory surgical centers.
Distribution Channel:
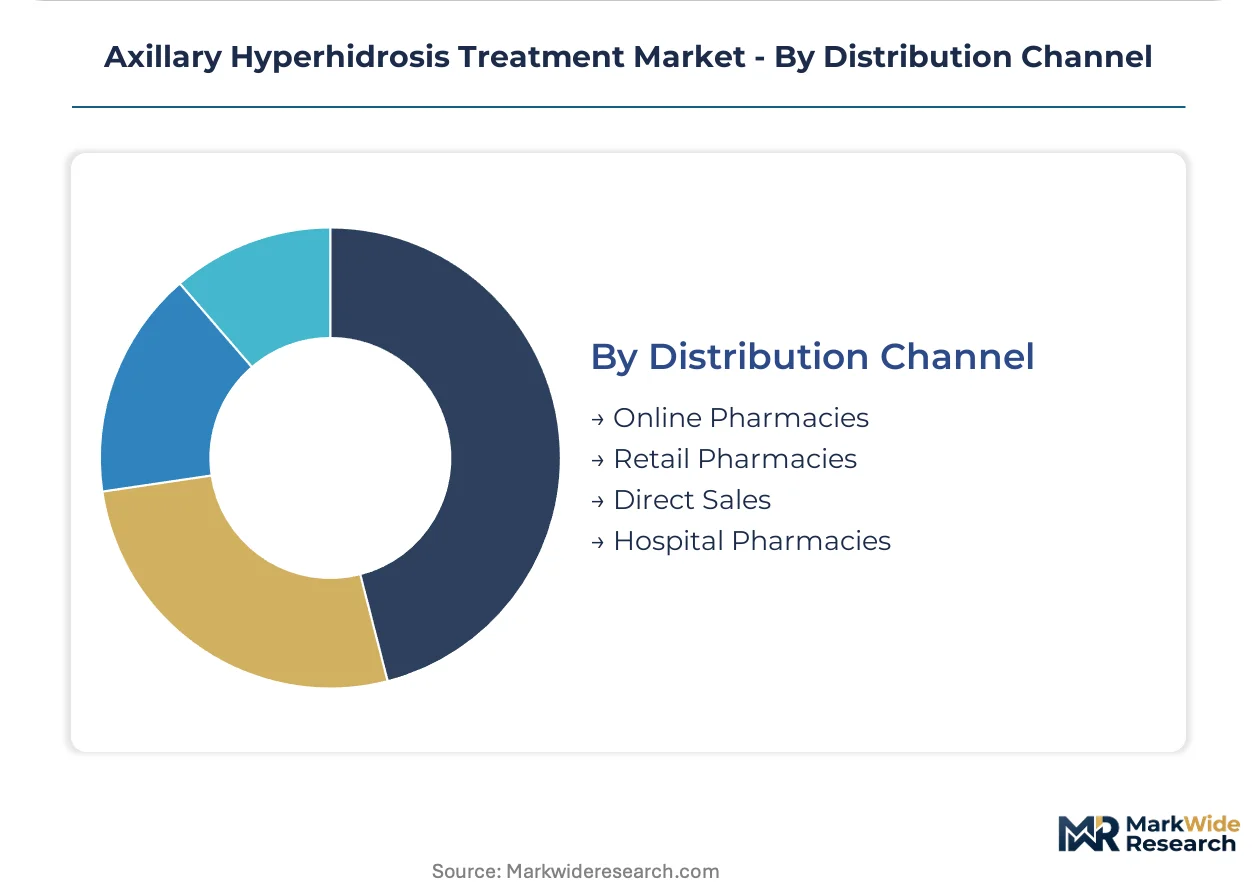
Channel selection reflects product regulatory classification, with prescription biologics and devices flowing through controlled pharmacy and direct sales pathways while consumer-grade products fragment across digital and retail touchpoints.
- Online Pharmacies:Digital platforms aggregate antiperspirant and iontophoresis device demand with subscription replenishment models. United States Amazon Pharmacy and German DocMorris capture recurring revenue through automated refill programs.
- Retail Pharmacies:Brick-and-mortar chains provide immediate access to over-the-counter formulations with pharmacist consultation. United States CVS and Walgreens, plus German dm-drogerie markt, sustain volume through convenience positioning.
- Direct Sales:Manufacturer-controlled channels deliver high-value energy-based devices and botulinum toxin through field specialist engagement. United States device manufacturers and AbbVie's neuromodulator sales force maintain clinical relationships to secure formulary commitment.
- Hospital Pharmacies:Closed-formulary procurement manages botulinum toxin inventory for inpatient and outpatient administration. Japanese university hospital pharmacists and German Klinikapotheken coordinate with dermatology and surgery departments for case-specific allocation.
Retail pharmacies command the established base. The steepest expansion runs through online pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while German clinics compete on procedural efficiency rather than premium capture. Japanese reimbursement maturity sustains device adoption despite demographic headwinds. Regulatory divergence between FDA clearance pathways and EU MDR compliance timelines fragments go-to-market strategies across Atlantic markets.
United States
Dermatology clinic chains in Florida and Texas drive botulinum toxin volume through bundled aesthetic packages. FDA's Center for Devices and Radiological Health maintains distinct 510(k) review tracks for microwave ablation systems versus laser platforms. Metropolitan practices in Los Angeles and New York capture premium placement for energy-based interventions through direct-to-consumer marketing channels.
Germany
Hautarztpraxen in Bavaria and North Rhine-Westphalia anchor iontophoresis device adoption for palmar-plantar extension cases. EU MDR notified bodies in Berlin and Munich impose extended clinical evidence requirements on class IIb energy devices. Compact radiofrequency systems are piloting in Frankfurt and Hamburg outpatient settings without dedicated procedure room infrastructure.
Japan
Tokyo and Osaka dermatology practices show readiness for premium microwave interventions among aging aesthetic patients. PMDA's pharmaceutical and medical device agency coordinates review timelines with METI industrial policy frameworks. University hospitals in Nagoya maintain surgical volume for endoscopic thoracic sympathectomy despite compensatory hyperhidrosis risk counseling requirements.
United Kingdom
London aesthetic chains and Manchester dermatology groups are adopting telemedicine pre-screening to compress diagnostic-to-treatment intervals. MHRA's post-Brexit regulatory framework maintains alignment with EU MDR device classification standards. Private pay clinics in Birmingham and Edinburgh bypass NHS referral pathways through direct-access booking platforms.
Canada
Ontario and British Columbia dermatology networks are expanding microwave therapy service menus following Health Canada device licensing. Provincial reimbursement variance creates access inequities between Quebec's public formulary and Alberta's private insurance dominance. Toronto and Vancouver multi-site practices capture disproportionate procedural margin through bundled diagnostic assessment protocols.
Axillary Hyperhidrosis Treatment Market Competitive Environment
Concentration sits with neuromodulator incumbents and energy-based device specialists, splitting competitive dynamics between pharmaceutical repeat-revenue models and capital-intensive hardware platforms. The vendor base organizes around three archetypes: established biologics manufacturers with dermatology sales infrastructure, single-technology device developers with proprietary ablation systems, and topical formulation specialists serving cost-sensitive first-line segments. Dominant competitive moves include strategic partnerships between device manufacturers and dermatology clinic chains, plus portfolio diversification into adjacent body areas beyond axillary indications.
Within the neuromodulator tier, AbbVie and Merz Pharma exemplify incumbents with established clinician relationships and formulary placement. Among energy-based device developers, miraDry anchors the microwave therapy niche with proprietary sweat gland ablation positioning. Revance Therapeutics represents the emerging biologics archetype pursuing differentiated formulation approaches. These three occupy positions across the pricing spectrum from premium procedural interventions to recurring pharmaceutical maintenance.
| Leading Market Players |
|---|
| Allergan plc (AbbVie) |
| Journey Medical Corporation |
| Riemann A/S |
| SweatBlock |
| miraDry |
| GlaxoSmithKline Plc |
| Revance Therapeutics |
| Merz Pharma |
| Botanix Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
Quarterly botulinum toxin procurement contracts lock in supply access and price visibility for United States dermatology clinic chains negotiating volume commitments with AbbVie's neuromodulator sales force. These arrangements tether clinic networks to predictable per-unit costs while insulating manufacturers from spot-market volatility in biological production inputs.
Pricing Analysis
The customization-premium spread separates configured-to-order microwave therapy installations from standard botulinum toxin vial pricing across dermatology clinic procurement. Three-tier pricing structure across premium, standard, and economy levels stratifies by device energy delivery specification and after-sales service bundling. Cost compression in home-use iontophoresis devices intensifies as Chinese manufacturers enter German and United States direct-to-consumer channels. Price-sensitive patients in home care segments drive substitution toward aluminum chloride formulations, while premium energy-based interventions retain inelastic demand among working-age professionals in metropolitan United States markets.
Supply Chain Analysis
Just-in-time inventory strategies dominate botulinum toxin distribution through cold-chain logistics networks serving United States hospital outpatient departments, while strategic stockpiling of microwave therapy hardware components concentrates at miraDry's California assembly facility. Component sourcing draws from German precision electronics for radiofrequency generators, Japanese optical subsystems for laser platforms, and Chinese battery cells for handheld iontophoresis units. Single-source vulnerability in 5.8 GHz magnetron supply creates exposure for microwave device manufacturers. Distribution runs through manufacturer-direct field specialist channels for high-value energy systems, contrasting with pharmacy wholesale networks for topical formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where telemedicine pre-screening platforms are consolidating patient acquisition channels and compressing diagnostic-to-treatment intervals across United States and United Kingdom dermatology networks.
For Market Incumbents: Secure formulary placement through expanded indication pathways for palmar and plantar hyperhidrosis, defending against emerging biologics developers pursuing differentiated neuromodulator formulations. Deepen backward integration into biological production through captive supply of botulinum toxin bulk drug substance, insulating margin from raw material cost volatility. Channel control through exclusive clinic network partnerships limits competitive access to high-volume metropolitan markets. For New Entrants and Emerging Players: FDA breakthrough device designation fast-track offers accelerated review timelines for novel radiofrequency miniaturization platforms targeting mid-tier dermatology practices without dedicated procedure room infrastructure. White-space concentration sits with compact handheld energy devices for German and United States outpatient deployment, where capital barriers exclude cart-based system competitors. Telemedicine-integrated direct-to-clinic booking platforms provide the most penetrable go-to-market angle for patient acquisition cost reduction. For Investors and Strategic Acquirers: Capital is best deployed toward single-technology device developers with proprietary ablation systems and established European notified body relationships, positioning for EU MDR compliance acceleration. Long-term viability hinges on reimbursement pathway maturation for procedural interventions across Medicare and private payer networks. The signal to watch is state-level Medicaid coverage expansion for hyperhidrosis procedures, indicating inflection in patient access and volume acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Expanded Indication Pathway | Palmar and plantar label extensions unlock incremental addressable populations beyond axillary presentations. |
| EU MDR Certification Acceleration | Leveraging existing FDA 510(k) dossiers compresses European notified body review timelines for microwave systems. |
| Telemedicine Platform Integration | Virtual pre-screening workflows reduce patient acquisition costs prior to in-clinic procedural assessment. |
| Hospital System Partnership | Tertiary center alliances secure surgical volume for endoscopic thoracic sympathectomy refractory cases. |
| Reimbursement Strategy Development | Medicare coverage determination advocacy determines patient access to premium energy-based interventions. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 510(k) device clearances, EMA marketing authorization applications, ClinicalTrials.gov intervention records, and CMS Medicare reimbursement determinations across the axillary hyperhidrosis treatment landscape. Dermatologists, clinic operations directors, biomedical engineers, GPO contracts managers, and payer access specialists provided structured input on procedure volume trends and procurement decision criteria. Bottom-up patient flow modeling triangulates against top-down pharmaceutical and device revenue aggregation.
Segmentation dimensions modeled span therapeutic modality, energy delivery mechanism, care setting, and procurement pathway across the projection horizon. Treatment line positioning, device regulatory classification tier, and regional reimbursement maturity inform volume and value allocation. CAGRs derive from procedure frequency assumptions for repeat-intervention modalities and device replacement cycles for capital equipment. Forecast inputs incorporate botulinum toxin retreatment interval elasticity and microwave therapy patient candidacy screening rates.
Decision-makers should treat outputs as directional under assumptions of stable FDA review timelines and EU MDR notified body capacity; material deviation would warrant model refresh. Revision becomes warranted when Medicare local coverage determination variance crosses state-level access inequity thresholds or when Japanese PMDA device reimbursement reclassification alters metropolitan clinic adoption patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Malignant Glioma Therapeutics Market
Specialty Medicine
Global Acute Agitation and Aggression Treatment Market
Specialty Medicine
Psychedelic Medicine Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
Klinefelter Syndrome Treatment Market
Specialty Medicine
Post-Traumatic Stress Disorder Treatment Market
Specialty Medicine
Splenomegaly Therapeutics Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Aflatoxicosis Treatment Market
Specialty Medicine
Sex Cord-Gonadal Stromal Tumor Market
Specialty Medicine
Global Pemphigus Vulgaris Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Nasal Polyposis Treatment Market
Specialty Medicine
Acute Intermittent Porphyria Market
Specialty Medicine
Hashimoto's Thyroiditis Therapeutics Market