
 Global Topical Antibiotics Market | 2026-2036
Global Topical Antibiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Global Topical Antibiotics Market Foresight
Polymyxin B is pivoting toward broader ointment formulations as resistance patterns erode neomycin's cost advantage in wound care. Pfizer Inc. leverages its hospital formulary relationships to sustain access across outpatient surgical settings. GlaxoSmithKline plc anchors consumer familiarity through legacy bacitracin brands in retail pharmacy channels. Novartis AG differentiates via retapamulin specialization in resistant staphylococcal skin infections.
Topical antibiotics are antimicrobial agents formulated for direct application to skin or mucosal surfaces, typically achieving localized bactericidal or bacteriostatic action at concentrations between 0.1% and 2% without significant systemic absorption. Their primary purpose centers on preventing or treating superficial bacterial infections while minimizing resistance selection pressure and systemic adverse effects compared to oral alternatives. Mupirocin commands the largest revenue share among product types due to its established efficacy against methicillin-resistant Staphylococcus aureus in nasal and skin decolonization protocols. Ointment formulations retain dominant volume position because of superior skin occlusion and moisture retention in wound care, though gel formats are gaining share in acne treatment where cosmetic elegance drives patient compliance. Dermatology clinics represent the most concentrated end-user margin pool, as prescriber control over formulary selection reduces price sensitivity compared to retail pharmacy substitution.
The US FDA maintains stringent chemistry, manufacturing, and controls requirements for topical antibiotic approvals, while the EMA's MDR framework intensifies post-market surveillance obligations across Europe. India's CDSCO enforces progressive bioequivalence standards for generic topical formulations under its PLI scheme for active pharmaceutical ingredients. China's NMPA implements GB standards for dermatological preparations that increasingly reference antimicrobial stewardship criteria. Stakeholders must monitor how evolving resistance surveillance data from the WHO influences national formularies and reimbursement tiers for first-line versus reserve topical agents.
Market Dynamics
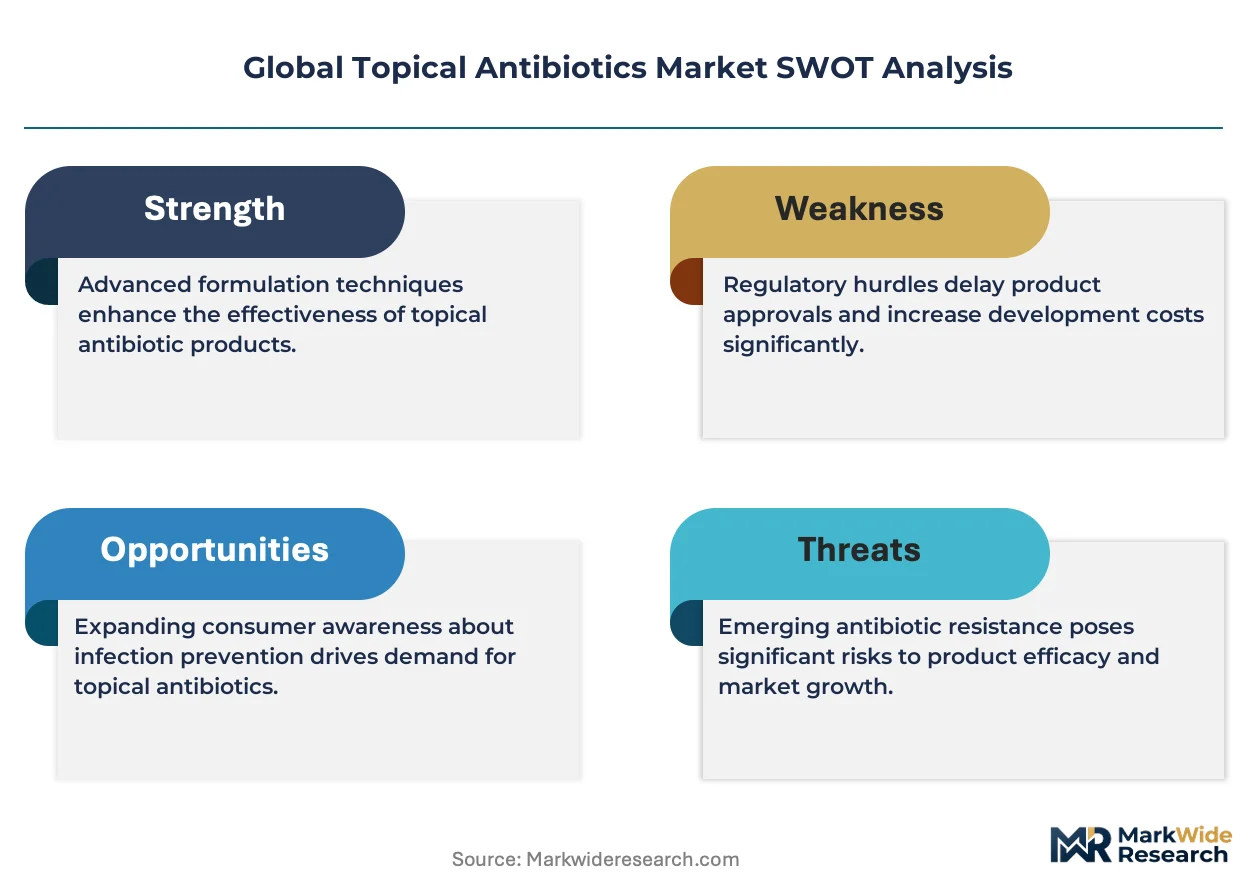
Antimicrobial resistance surveillance is compressing the effective lifecycle of established topical agents, forcing formulators to accelerate novel mechanism exploration while regulators tighten stewardship criteria across hospital and retail channels.
Growth Catalysts
- US FDA Labeling Revisions:The agency's antimicrobial resistance disclosure mandates are accelerating hospital formulary upgrades toward agents with documented sensitivity profiles.
- Dermatology Clinic Chains:China's tier-one cities are standardizing formulary choices through centralized procurement agreements that favor proven efficacy over cost.
- Surgical Prophylaxis Protocols:Hospital outpatient clinics in India are expanding topical antibiotic use in pre-operative skin preparation to reduce surgical site infections.
Market Restraints
- API Supply Concentration:Polymyxin B and bacitracin active pharmaceutical ingredients concentrate among Chinese and Indian bulk manufacturers, exposing formulators to single-source disruption risk.
- Neomycin Resistance Erosion:Widespread bacterial resistance has degraded this agent's clinical utility in wound care, forcing portfolio write-downs among legacy ointment brands.
- EMA MDR Surveillance Burden:Europe's intensified post-market clinical follow-up requirements extend compliance timelines and inflate regulatory maintenance costs for topical antimicrobial sponsors.
Strategic Opportunities
- Retapamulin Specialization:Resistant staphylococcal skin infections represent an underserved indication where novel pleuromutilin mechanisms command premium positioning.
- PLI Scheme Incentives:India's production-linked incentive framework for active pharmaceutical ingredients reduces capital barriers for domestic topical antibiotic manufacturing.
- Gel Format Cosmetic Elegance:Acne treatment channels are displacing ointment viscosity with gel aesthetics that improve adolescent compliance and expand addressable patient pools.
Industry Challenges
- Bioequivalence Standard Escalation:CDSCO's progressive requirements for generic topical formulations demand costly clinical endpoint studies that smaller sponsors struggle to fund.
- Formulation Stability Expertise:Moisture retention and occlusion engineering for chronic wound applications requires specialized talent scarce outside established dermatological houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Topical Antibiotics Market |
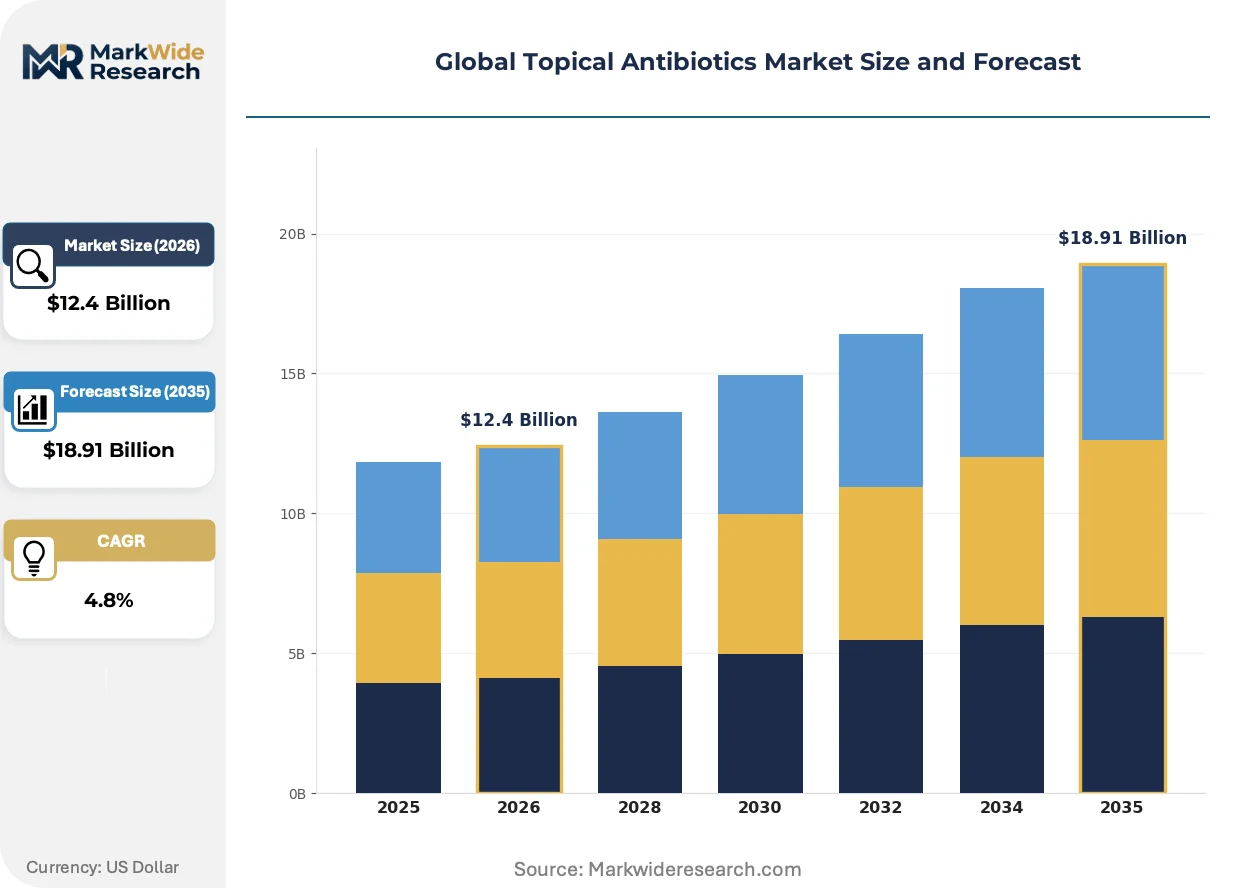
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $18.91 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mupirocin, Neomycin, Bacitracin, Polymyxin B, Retapamulin Formulation: Ointment, Cream, Gel, Spray, Powder Application: Wound Care, Acne Treatment, Dermatitis, Burn Management, Surgical Prophylaxis End User: Pharmacies, Dermatology Clinics, Outpatient Clinics, Home Healthcare Providers, Specialized Care Centers |
| Companies Covered | Bausch Health Companies Inc., Almirall S.A., Medimetriks Pharmaceuticals Inc., Pfizer Inc., GlaxoSmithKline plc, Novartis AG, Bayer AG, Lupin, Sun Pharmaceutical Industries Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Topical Antibiotics Market Shifts & Advancements
Formulation science and regulatory chemistry are converging to redefine product differentiation, with occlusion mechanics and resistance stewardship emerging as the primary axes of competitive positioning.
Lipid-based nanocarrier systems are expanding into topical antibiotic delivery by enhancing dermal penetration of macromolecular agents previously limited to surface activity. Compounding pharmacies and specialty dermatology manufacturers are adopting these carriers for methicillin-resistant Staphylococcus aureus decolonization protocols. This penetration enhancement is expanding into previously refractory skin structures, compressing the efficacy gap between topical and systemic administration routes.
China's NMPA is implementing GB standards for dermatological preparations that explicitly reference antimicrobial stewardship criteria in product registration dossiers. This regulatory architecture forces sponsors to submit resistance surveillance data as a condition of approval renewal. Domestic manufacturers and multinationals operating in Shanghai and Beijing clinical trial centers are restructuring development programs to incorporate longitudinal resistance monitoring from Phase II forward.
Prescriber-controlled procurement through dermatology clinic chains is displacing retail pharmacy substitution in China's tier-one cities and India's metropolitan hospital networks. This channel consolidation reduces price sensitivity by removing patient-driven generic switching at the point of dispensing. The concentration of formulary authority is most visible in Mumbai and Delhi NCR, where hospital outpatient departments now direct over half of topical antibiotic volume through centralized purchasing agreements.
Global Topical Antibiotics Market Segmentation
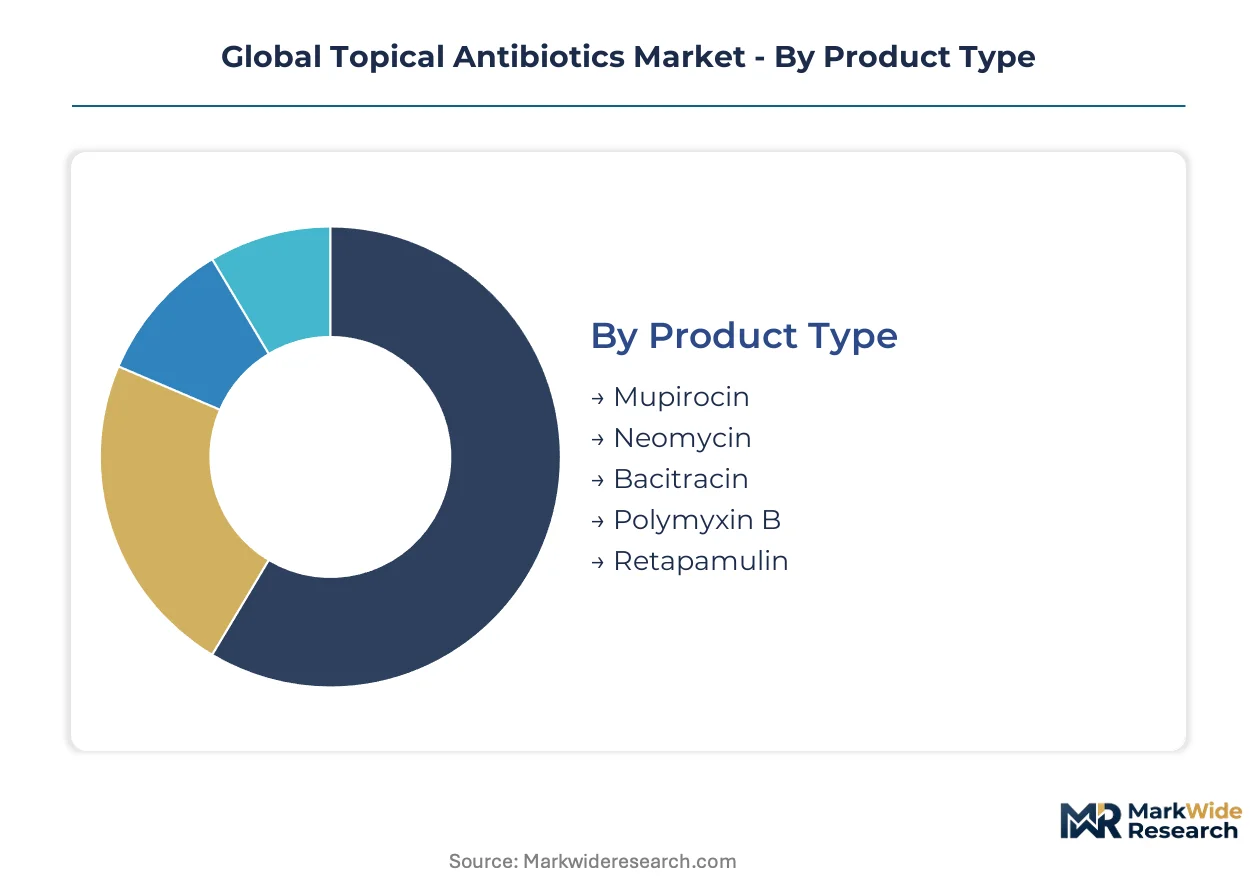
Product differentiation in topical antibiotics hinges on resistance profiles, occlusion mechanics, and prescriber control over dispensing channels. Formulators compete across molecular mechanisms, physical delivery systems, and site-of-care access points.
Product Type:
The customization-vs-standardization spectrum stretches from legacy broad-spectrum agents to precision anti-staphylococcal compounds with documented resistance patterns.
- Mupirocin:A pseudomonic acid derivative formulated at 2% concentration for nasal and skin decolonization. Demand concentrates in hospital outpatient settings across India and the United States where methicillin-resistant Staphylococcus aureus protocols mandate documented efficacy.
- Neomycin:An aminoglycoside antibiotic typically combined with polymyxin B and bacitracin in triple-therapy ointments. Widespread bacterial resistance has degraded clinical utility in wound care, forcing portfolio rationalization among legacy manufacturers.
- Bacitracin:A polypeptide antibiotic blocking cell wall synthesis, standard in over-the-counter first-aid ointments. Retail pharmacy channels in North America sustain volume through consumer familiarity.
- Polymyxin B:A cyclic lipopeptide targeting gram-negative pathogens, increasingly formulated as standalone ointments as resistance erodes neomycin's cost advantage. Chinese bulk manufacturers supply most active pharmaceutical ingredient.
- Retapamulin:A pleuromutilin antibiotic with novel mechanism against resistant staphylococcal skin infections. Specialized dermatology clinics command premium positioning for this reserve agent.
Most installed capacity flows through Mupirocin. Expansion is steepest in Retapamulin.
Formulation:
Cost tier stratification separates occlusion-intensive chronic wound applications from cosmetic-sensitive acne channels.
- Ointment:Petrolatum-based vehicles achieving superior moisture retention and skin occlusion. Wound care protocols in India's hospital outpatient clinics standardize on this format for surgical prophylaxis.
- Cream:Oil-in-water emulsions offering easier spreadability and washability than ointments. Dermatitis applications favor this balance of occlusion and cosmetic acceptability.
- Gel:Aqueous polymer matrices delivering cosmetic elegance without residue. China's tier-one city dermatology clinics are displacing ointment viscosity with gel aesthetics for adolescent acne compliance.
- Spray:Aerosol or pump-dispensed solutions for large surface area coverage. Burn management units favor this format for patient comfort during dressing changes.
- Powder:Micronized antibiotic formulations for moist intertriginous areas. Home healthcare providers in humid climates specify this format for fungal-bacterial co-infection prevention.
Volume concentrates in Ointment. Value expansion is climbing the fastest in Gel.
Application:
Customer type determines margin structure, with prescriber-controlled channels capturing premium pricing over retail substitution.
- Wound Care:Chronic ulcer and traumatic injury management requiring sustained antimicrobial presence. Hospital outpatient departments in Mumbai and Delhi NCR direct procurement through centralized purchasing agreements.
- Acne Treatment:Propionibacterium acnes suppression combined with anti-inflammatory action. Gel formulations are gaining share where cosmetic elegance drives adolescent compliance.
- Dermatitis:Atopic and contact dermatitis with secondary bacterial colonization. Dermatology clinic chains standardize formulary choices across China's tier-one cities.
- Burn Management:Infection prevention in partial-thickness and full-thickness thermal injuries. Specialized care centers specify silver-sulfadiazine combinations with topical antibiotics.
- Surgical Prophylaxis:Pre-operative skin preparation to reduce surgical site infections. India's expanding hospital outpatient clinic networks are scaling adoption for minor procedures.
Procurement authority concentrates in Wound Care. Prescription volume is expanding most quickly in Surgical Prophylaxis.
End User:
Geography and channel structure determine whether price sensitivity or clinical authority governs purchasing decisions.
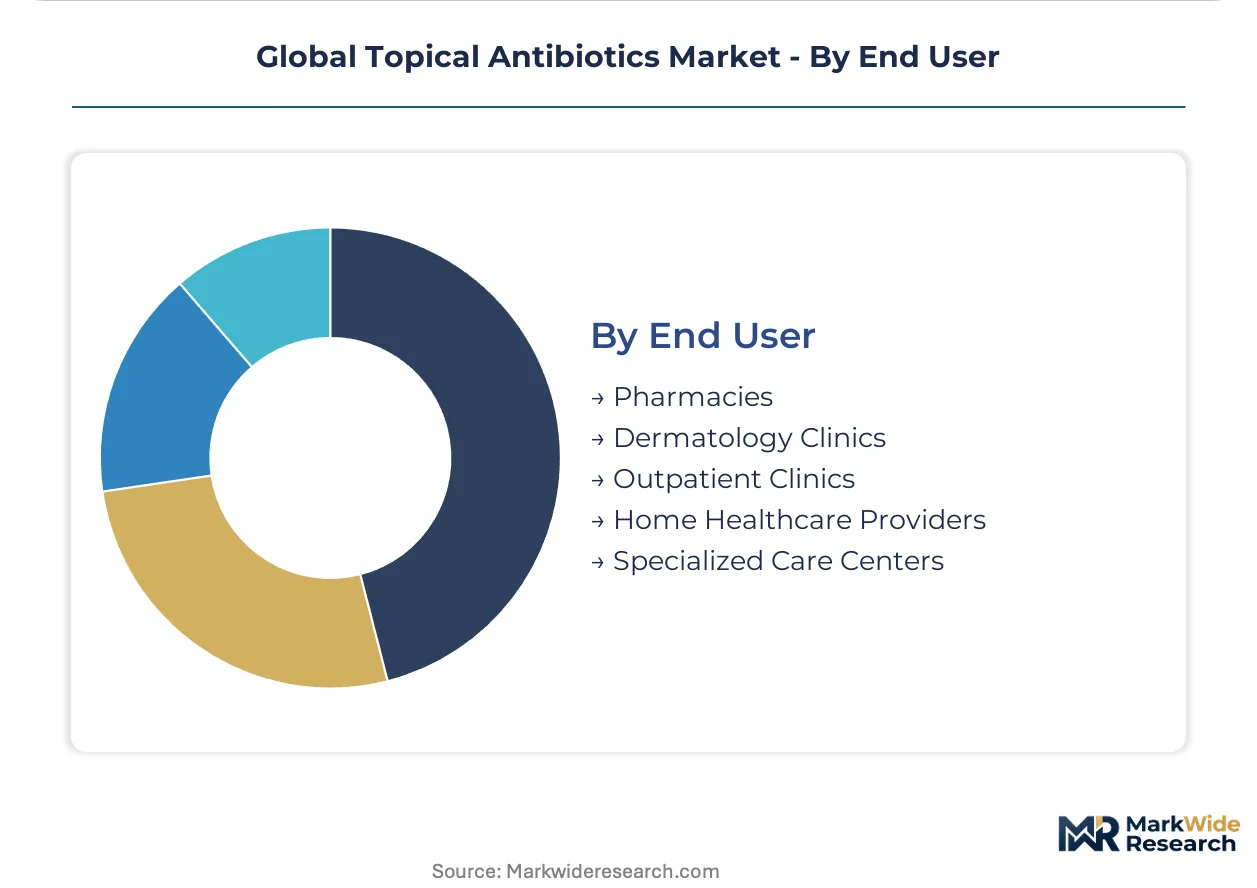
- Pharmacies:Retail dispensing with high substitution pressure from generic alternatives. Patient-driven switching at point of sale compresses margins for branded ointments.
- Dermatology Clinics:Prescriber-controlled formulary selection with reduced price sensitivity. China's metropolitan chains concentrate margin pool through centralized procurement.
- Outpatient Clinics:Hospital-affiliated settings expanding topical antibiotic use for pre-operative preparation. India's surgical prophylaxis protocols are scaling through this channel.
- Home Healthcare Providers:Long-term wound management for mobility-limited patients. Powder formulations address intertrigo prevention in humid climates.
- Specialized Care Centers:Burn units and reconstructive surgery facilities with protocol-driven purchasing. Spray formats dominate for large surface area applications.
Margin capture concentrates in Dermatology Clinics. Patient volume is gaining share fastest in Outpatient Clinics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai anchors the industry's regulatory evolution, with China's NMPA GB standards reshaping antimicrobial stewardship requirements across dermatological preparations. Hospital outpatient networks in Mumbai and Delhi NCR concentrate procurement authority through centralized purchasing agreements. The FDA's labeling revisions in the United States are accelerating formulary upgrades toward agents with documented sensitivity profiles.
United States
FDA antimicrobial resistance disclosure mandates are accelerating hospital formulary upgrades toward agents with documented sensitivity profiles. The agency's chemistry, manufacturing, and controls requirements maintain stringent approval pathways for topical antibiotic sponsors. Boston and San Francisco clinical research clusters concentrate Phase II-III development programs for novel pleuromutilin mechanisms.
China
NMPA GB standards for dermatological preparations explicitly reference antimicrobial stewardship criteria in product registration dossiers. Tier-one city dermatology clinic chains in Shanghai and Beijing standardize formulary choices through centralized procurement agreements. Yangtze River Delta manufacturing bases supply bulk active pharmaceutical ingredients for polymyxin B and bacitracin formulations.
India
CDSCO progressive bioequivalence standards for generic topical formulations demand costly clinical endpoint studies under the PLI scheme for active pharmaceutical ingredients. Hospital outpatient clinics in Mumbai and Delhi NCR direct over half of topical antibiotic volume through centralized purchasing agreements. Gujarat and Maharashtra bulk manufacturing clusters concentrate polymyxin B and bacitracin active pharmaceutical ingredient production.
Germany
EMA MDR framework intensifies post-market surveillance obligations and extends compliance timelines for topical antimicrobial sponsors. REACH and RoHS regulations govern excipient chemistry in dermatological preparations. Bavaria and Baden-Württemberg pharmaceutical manufacturing clusters specialize in lipid-based nanocarrier formulation science for enhanced dermal penetration.
United Kingdom
MHRA post-Brexit regulatory autonomy maintains alignment with EMA MDR surveillance standards while streamlining national approval pathways. London and Southeast England dermatology clinic chains concentrate prescriber-controlled procurement with reduced retail pharmacy substitution. Oxford and Cambridge research corridors advance resistance surveillance data integration into product development programs.
Global Topical Antibiotics Market Competitive Landscape
Global majors compete with regional champions across hospital formulary access and retail pharmacy channel penetration. The market structure fragments across three tiers: multinational pharmaceutical conglomerates with legacy brand portfolios, mid-cap specialists in resistant staphylococcal indications, and regional generic manufacturers serving cost-sensitive procurement. Three strategic archetypes dominate: hospital-centric formulators leveraging surgical prophylaxis protocols, consumer-facing brands anchoring retail pharmacy familiarity, and innovation-driven developers pursuing novel mechanisms against documented resistance patterns. M&A activity concentrates on acquiring lipid-based nanocarrier formulation capabilities, while strategic partnerships proliferate between bulk API manufacturers in India and China and finished dose formulators in regulated markets.
Within the multinational tier, Pfizer Inc. and GlaxoSmithKline plc exemplify divergent channel strategies. Pfizer occupies a position anchored in hospital formulary relationships across outpatient surgical settings, while GlaxoSmithKline represents consumer-facing brand equity through legacy bacitracin positioning in retail pharmacy channels. Novartis AG sits within the specialization archetype, with retapamulin development signaling premium positioning in resistant staphylococcal skin infections. Among regional manufacturers, Sun Pharmaceutical Industries Ltd. and Lupin exemplify Indian production scale advantages under CDSCO PLI scheme incentives, while Almirall S.A. represents European mid-cap specialization in dermatological delivery systems.
| Leading Market Players |
|---|
| Bausch Health Companies Inc. |
| Almirall S.A. |
| Medimetriks Pharmaceuticals Inc. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Novartis AG |
| Bayer AG |
| Lupin |
| Sun Pharmaceutical Industries Ltd. |
| Others |
Supply & Pricing Matrix
Polymyxin B active pharmaceutical ingredient costs cascade from Yangtze River Delta manufacturing bases through three pricing tiers: premium reserve agents for resistant staphylococcal infections, standard hospital formulary products, and economy generic ointments for retail pharmacy substitution. Input cost pass-through varies by channel control, with dermatology clinic chains absorbing less price volatility than patient-driven retail dispensing.
Pricing Analysis
Input cost pass-through from Chinese and Indian bulk API manufacturers stratifies pricing across premium, standard, and economy tiers. Price differentiation hinges on documented resistance sensitivity profiles and prescriber control over formulary selection. Pricing pressure stems from CDSCO bioequivalence standard escalation forcing costly clinical endpoint studies. Hospital outpatient clinics exhibit lowest price sensitivity due to centralized procurement authority, while retail pharmacies face highest substitution pressure from patient-driven generic switching.
Supply Chain Analysis
Single-source vulnerability sits with Chinese and Indian bulk manufacturers for polymyxin B and bacitracin active pharmaceutical ingredients. Raw material dependencies include fermentation-derived polypeptides, cyclic lipopeptide precursors, and petrolatum-based ointment vehicles. Supply chain risk centers on regulatory restriction exposure from EMA MDR intensified post-market surveillance obligations. Distribution runs through hospital formulary committees in Mumbai and Delhi NCR, dermatology clinic chains in Shanghai and Beijing, and retail pharmacy networks across North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Topical Antibiotics Market functions as a stable compounder anchored by antimicrobial resistance surveillance mandates that perpetually refresh formulary upgrade cycles across hospital and clinic channels.
For Market Incumbents: Deepen hospital formulary relationships through surgical prophylaxis protocol integration in India's expanding outpatient clinic networks. Secure backward integration into polymyxin B active pharmaceutical ingredient production under India's PLI scheme to defend against Chinese supply disruption. Invest in lipid-based nanocarrier formulation capabilities to differentiate from generic substitution pressure in retail channels.
For New Entrants and Emerging Players: Enter via retapamulin specialization for resistant staphylococcal skin infections, the most penetrable premium segment where novel pleuromutilin mechanisms command formulary placement. Target gel format development for China's tier-one city dermatology clinics where cosmetic elegance displaces ointment viscosity in adolescent acne protocols. Pursue strategic partnerships with Yangtze River Delta API suppliers to bypass capital-intensive fermentation infrastructure.
For Investors and Strategic Acquirers: Consolidation pressure builds where formulation stability expertise for chronic wound applications concentrates among established dermatological houses with scarce specialized talent. Long-term viability favors sponsors with integrated resistance surveillance capabilities from Phase II development forward. Acquisition target archetype: mid-cap specialists with retapamulin pipelines or lipid-based nanocarrier platforms. Watch FDA antimicrobial resistance labeling revision timing as inflection indicator for formulary upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Lipid-Based Nanocarrier Development | Enhances dermal penetration of macromolecular agents for MRSA decolonization protocols in hospital settings. |
| PLI Scheme API Manufacturing | Reduces capital barriers for domestic polymyxin B production under CDSCO progressive bioequivalence standards. |
| Gel Format Cosmetic Elegance | Captures adolescent acne compliance in China's tier-one city dermatology clinic chains displacing ointments. |
| Resistance Surveillance Integration | Satisfies NMPA GB standards requiring longitudinal monitoring from Phase II forward for approval renewal. |
| Hospital Formulary Partnership | Secures centralized procurement access in Mumbai and Delhi NCR outpatient surgical prophylaxis expansion. |
Research Methodology
Direct dialogue with drug development executives, regulatory affairs leads, formulary directors at hospital systems, and dermatology clinic procurement managers grounded qualitative insights. Secondary validation drew from FDA antimicrobial resistance labeling filings, EMA MDR submission databases, CDSCO PLI scheme documentation, and NMPA GB standard registration dossiers. Bottom-up patient volume modeling and top-down pharmaceutical market sizing were triangulated to cross-verify segment outputs.
Segment-level projections across product type, formulation, application, and end-user channels were generated over the projection horizon. Compound annual growth rates were derived from elasticity-adjusted demand curves incorporating antimicrobial resistance surveillance data and formulary upgrade cycle frequencies. Industry-specific forecast inputs included hospital outpatient clinic expansion rates in India, dermatology clinic chain consolidation in China's tier-one cities, and FDA labeling revision implementation timelines.
Inputs from FDA, EMA, CDSCO, and NMPA regulatory databases were available through the study window; gaps in real-time resistance surveillance data from WHO national formularies introduce uncertainty bands around formulary adoption assumptions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
Liposomal Doxorubicin Market
Biopharmaceuticals
Conjugated Estrogen Market
Biopharmaceuticals
Influenza Vaccine Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market
Biopharmaceuticals
Recombinant Erythropoietin Market
Biopharmaceuticals
Benzbromarone API Market
Biopharmaceuticals
APAC Insulin Market
Biopharmaceuticals
Global Drug Discovery Market
Biopharmaceuticals
Europe Insulin Delivery Devices Market
Biopharmaceuticals
Triptorelin Market
Biopharmaceuticals
Global Rheumatoid Arthritis Drugs Market
Biopharmaceuticals
Somatostatin Analogs Market
Biopharmaceuticals
US Influenza Vaccine Market
Biopharmaceuticals
Global Resistant Pseudomonas Aeruginosa Infections Drugs Market
Biopharmaceuticals
Europe Insulin Pens Market