
 Biopharmaceutical Fermentation Market | 2026-2036
Biopharmaceutical Fermentation Market Size, Share, and Industry Trends Forecast 2026-2036
Biopharmaceutical Fermentation Market Analysis
Platform licensing revenue is reconfiguring margin pools away from standalone equipment sales toward integrated bioprocess ecosystems. Thermo Fisher Scientific leverages its chromatography and cell culture media portfolio to anchor long-term service contracts. Danaher Corporation sustains competitive positioning through its Beckman Coulter life sciences instrumentation and Pall filtration technologies. Sartorius Stedim Biotech dominates single-use bioreactor systems, a segment where disposable technologies reduce cross-contamination risks in multi-product facilities.
Biopharmaceutical fermentation denotes the controlled cultivation of microbial or mammalian cells in bioreactors to produce therapeutic proteins, monoclonal antibodies, or vaccines, typically operating at scales from 1,000 to 20,000 liters with precise control of dissolved oxygen, pH, and temperature parameters. The process serves as the manufacturing backbone for biologics that cannot be synthesized through chemical routes. Fed-batch fermentation occupies the largest installed base due to its operational flexibility and proven regulatory track record for monoclonal antibody production, while continuous fermentation represents the fastest-growing technology segment as manufacturers pursue higher volumetric productivity and reduced facility footprints. Contract Manufacturing Organizations constitute the most rapidly expanding end user category, driven by Big Pharma's strategic outsourcing of capacity-intensive biologics production.
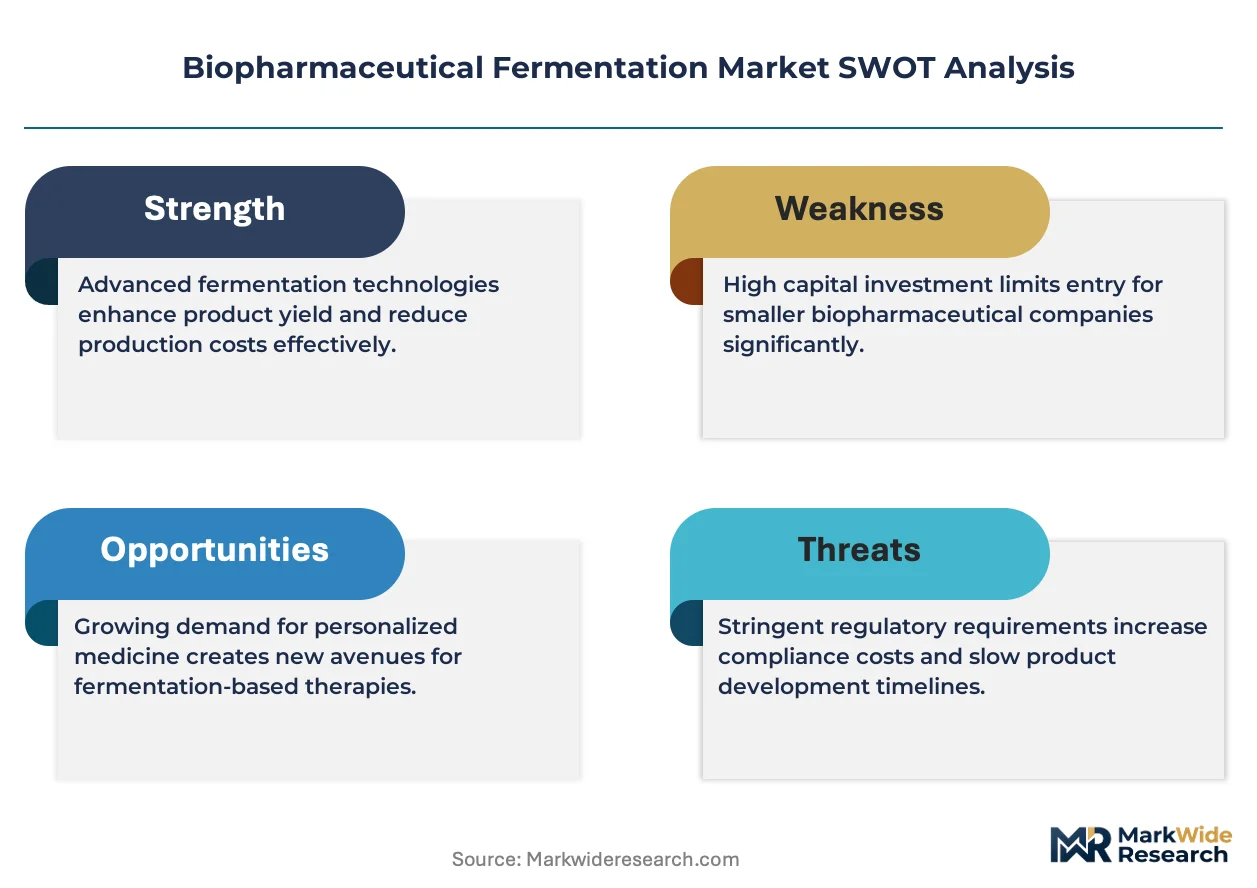
FDA current Good Manufacturing Practice regulations and EMA's Guideline on Process Validation for Biotechnological Processes govern facility design, batch release criteria, and post-approval change management protocols across major manufacturing jurisdictions. ISO 14644 cleanroom classifications and PDA Technical Report No. 66 further define environmental monitoring standards that shape capital expenditure decisions for new greenfield sites. Stakeholders must monitor how emerging gene therapy modalities and personalized medicine batches reshape scale requirements and regulatory submission pathways for fermentation-derived products.
Market Dynamics
Contract Manufacturing Organizations are consolidating bioreactor capacity around single-use technologies, compressing facility build timelines from five years to eighteen months and rewiring competitive advantage toward flexible multi-product platforms rather than stainless steel scale.
Growth Catalysts
- Single-use bioreactor adoption:Disposable vessel technologies eliminate CIP/SIP validation cycles, accelerating batch turnaround for multi-product Contract Manufacturing Organizations serving Big Pharma outsourcing contracts.
- FDA process validation guidelines:The agency's 2011 Process Validation guidance and subsequent ICH Q12 lifecycle management frameworks reward facilities with robust process analytical technology infrastructure, favoring vendors with integrated data platforms.
- Cell culture capacity expansion in China:WuXi Biologics and domestic peers are commissioning 20,000-liter stainless steel trains and 2,000-liter single-use lines to capture biosimilar export demand.
Market Restraints
- Plastics supply concentration:Medical-grade silicone tubing and gamma-irradiated film resins concentrate among three polymer compounders, exposing bioreactor assemblers to resin allocation shocks.
- EMA quality risk management compliance:ICH Q9 implementation demands extensive failure mode analysis documentation, extending facility qualification timelines by eight to fourteen months.
- Continuous fermentation technical barriers:Cell retention devices and perfusion control algorithms remain unproven at commercial monoclonal antibody titers above five grams per liter, limiting process intensification claims.
Strategic Opportunities
- India biosimilar manufacturing:CDSCO's relaxed comparability protocols for approved reference biologics create first-mover openings for fermentation-based trastuzumab and rituximab production.
- Continuous processing regulatory tailwind:FDA's Emerging Technology Program offers pre-submission meetings for real-time release testing implementations, de-risking novel control strategy filings.
- Gene therapy vector convergence:Adeno-associated virus production is migrating from transient transfection to stable producer cell lines, requiring suspension adaptation expertise held by mammalian fermentation specialists.
Industry Challenges
- Process analytical technology integration:Raman spectroscopy and capacitance probe data streams require harmonization with legacy distributed control systems, stretching validation resources.
- Advanced therapy medicinal product skill gaps:Cell and gene therapy batches demand operators trained in closed-system aseptic technique, a competency scarce in traditional microbial fermentation workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biopharmaceutical Fermentation Market |
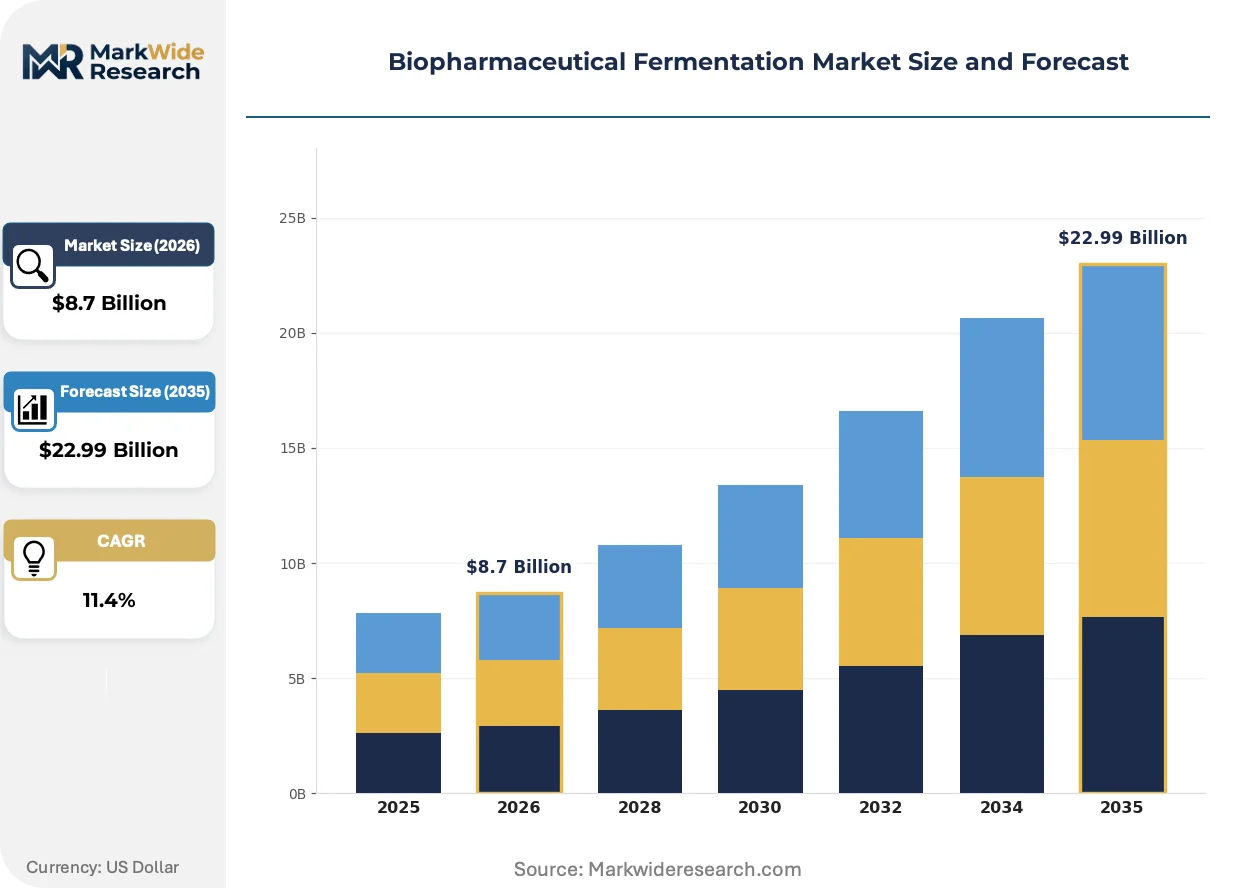
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Vaccines, Recombinant Proteins, Enzymes Application: Oncology, Infectious Diseases, Autoimmune Disorders, Hormonal Therapies Technology: Batch Fermentation, Continuous Fermentation, Fed-Batch Fermentation, Perfusion Fermentation End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations |
| Companies Covered | Thermo Fisher Scientific Inc, Danaher Corporation, Sartorius Stedim Biotech, Merck KGaA, Eppendorf AG, GE Healthcare, Lonza Group AG, Agilent Technologies, Becton, Dickinson and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biopharmaceutical Fermentation Market Emerging Trajectories
Digital twin architectures and real-time multivariate modeling are compressing process development cycles while regulatory bodies race to codify control strategies for novel modalities. These forces are redrawing where value accumulates across the bioprocess equipment stack.
Digital twin simulation platforms replicate bioreactor hydrodynamics and metabolic flux in silico before physical runs. Bioprocess development groups at major Contract Manufacturing Organizations deploy these tools to reduce design of experiment burdens by sixty percent. The technology is digitizing scale-up risk assessment, enabling virtual tech transfer between development and commercial sites.
EMA's revised Annex 1 on sterile manufacturing mandates continuous viable particle monitoring in Grade A filling zones, effective August 2023. This pressures fermentation facilities to extend environmental monitoring programs upstream into bioreactor harvest operations. European fill-finish contractors are responding by installing isolator-based containment systems that segregate open processing from operator-borne contamination vectors.
Buyers are unbundling equipment purchases from long-term consumables contracts, reversing the razor-and-blade model that dominated single-use bioreactor penetration. Procurement functions at mid-sized biotech developers now negotiate media and bag supply separately from hardware, pressuring Sartorius and Thermo Fisher to defend attachment rates. This behavior is most pronounced in the United States, where venture-backed companies prioritize capital preservation over operational integration.
Biopharmaceutical Fermentation Market Segmentation
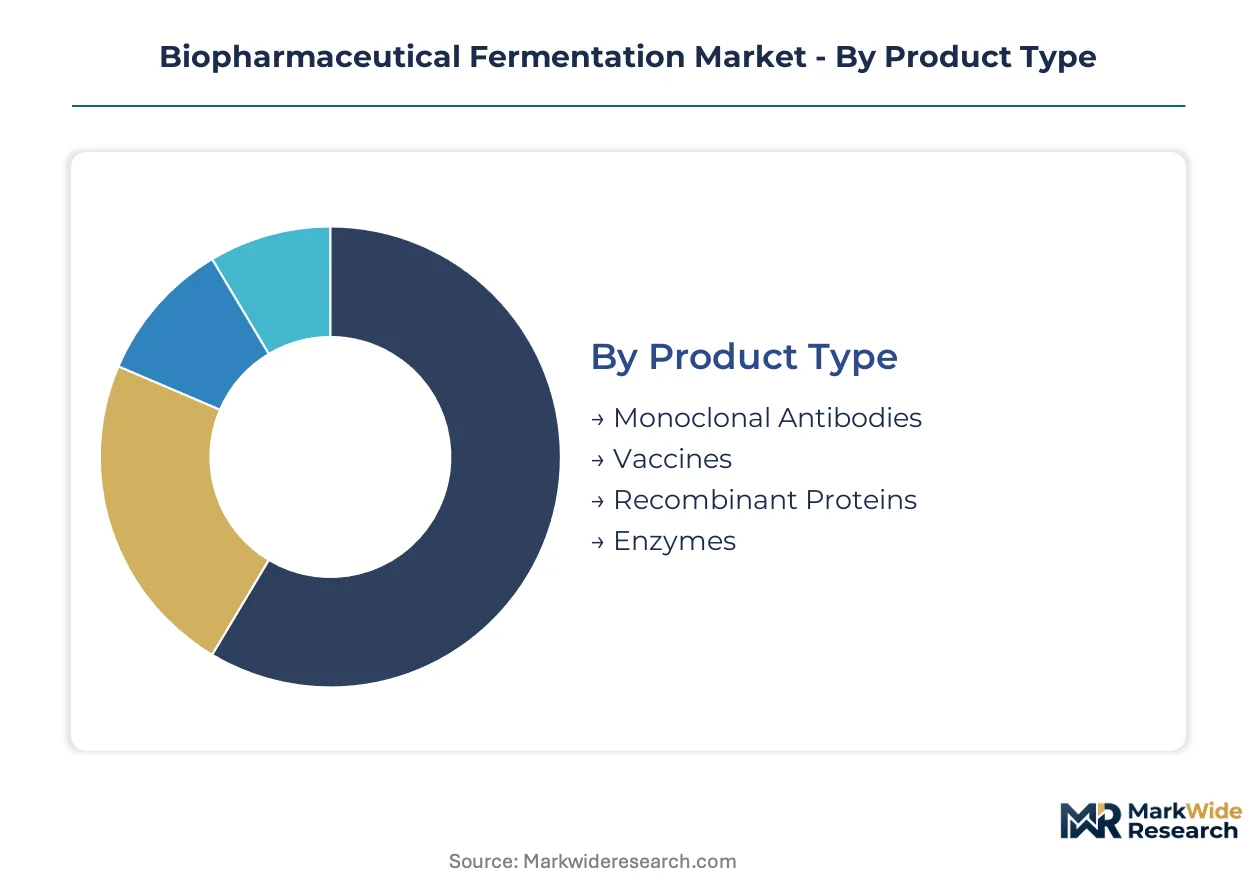
Biopharmaceutical fermentation segments diverge sharply in bioreactor scale, regulatory pathway complexity, and margin structure. Product type determines upstream processing architecture, while end-user category dictates facility investment intensity and technology adoption timelines.
Product Type:
Manufacturing scale spans 1,000-liter gene therapy batches to 20,000-liter monoclonal antibody trains across therapeutic modalities.
- Monoclonal Antibodies:Mammalian cell culture in fed-batch or perfusion modes dominates this segment, with titers exceeding five grams per liter now standard at commercial scale. Demand concentrates among Contract Manufacturing Organizations in the United States and China serving Big Pharma outsourcing contracts, driven by biosimilar volume and novel antibody-drug conjugate pipelines.
- Vaccines:Microbial fermentation platforms using E. coli or yeast host cells supply recombinant protein subunit and virus-like particle formulations. Egg-based production for influenza strains retains significant installed base, though mammalian suspension systems are displacing legacy platforms for pandemic preparedness contracts.
- Recombinant Proteins:Insulin, growth factors, and blood clotting factors require high-purity harvest and downstream polishing.
- Enzymes:Industrial-scale microbial fermentation supplies replacement therapies for rare metabolic disorders.
Established volume favors Monoclonal Antibodies; emerging adoption favors Vaccines on novel platform technologies.
Application:
Therapeutic area concentration shapes facility specialization and regulatory submission strategy.
- Oncology:Checkpoint inhibitors and antibody-drug conjugates command the largest fermentation capacity allocation, with batch sizes scaling to meet combination therapy demand. CAR-T cell therapy expansion in the United States and China is pulling CDMO investment toward co-located vector and cell processing capabilities.
- Infectious Diseases:Pandemic vaccine surge capacity and antimicrobial resistance programs drive government-funded manufacturing networks. mRNA platform diversification post-COVID is redirecting fermentation demand toward lipid nanoparticle encapsulation rather than traditional protein expression.
- Autoimmune Disorders:TNF-alpha inhibitors and IL-targeting biologics require stable high-titer production.
- Hormonal Therapies:Recombinant insulin and growth hormone represent mature, cost-optimized segments.
Oncology commands capacity premiums; Infectious Diseases captures policy-driven investment cycles.
Technology:
Process modality selection determines capital efficiency, batch consistency, and regulatory qualification burden.
- Fed-Batch Fermentation:Intermittent nutrient feeding maintains exponential growth phase while managing byproduct accumulation, offering operational flexibility that has dominated monoclonal antibody manufacturing for two decades. The installed base across the United States, Germany, and China remains the reference standard for regulatory submissions.
- Continuous Fermentation:Perfusion with cell retention devices achieves higher volumetric productivity and smaller facility footprints, though commercial-scale titers above five grams per liter remain technically demanding. FDA's Emerging Technology Program is accelerating validation pathways for real-time release testing implementations.
- Batch Fermentation:Simple, closed-system operations suit early-phase clinical material and microbial platforms.
- Perfusion Fermentation:Steady-state operation with continuous harvest maximizes product quality consistency for unstable proteins.
Fed-Batch retains regulatory familiarity; Continuous Fermentation is climbing the fastest on productivity metrics.
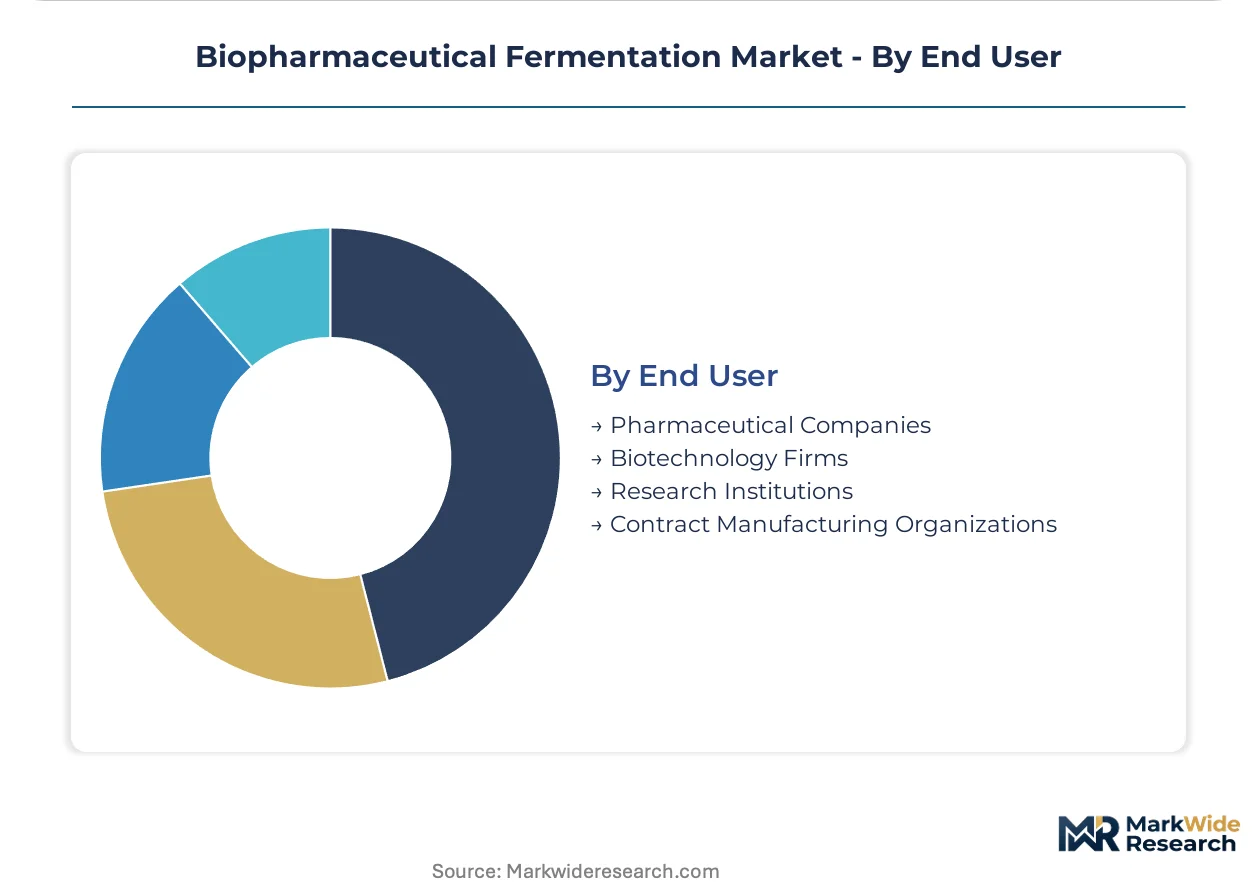
End User:
Customer category determines procurement sophistication, technology risk tolerance, and service bundling preferences.
- Contract Manufacturing Organizations:Multi-product flexibility requirements are compressing facility build timelines from five years to eighteen months through single-use technology standardization. WuXi Biologics, Samsung Biologics, and European peers are commissioning 20,000-liter stainless steel trains alongside 2,000-liter disposable lines to capture biosimilar export demand.
- Pharmaceutical Companies:In-house capacity strategies diverge between large-cap biologics owners maintaining captive production and mid-tier firms outsourcing entirely. Merck and Roche retain fermentation leadership through vertical integration into cell line development and media formulation.
- Biotechnology Firms:Virtual development models rely on CDMO partnerships for clinical and commercial supply.
- Research Institutions:Academic and government laboratories operate smaller-scale systems for early discovery and process development.
Contract Manufacturing Organizations are expanding most quickly; Pharmaceutical Companies defend proprietary process knowledge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Switzerland demonstrate lowest price elasticity for premium single-use systems, while Chinese and Indian procurement teams drive hardest on per-liter cost negotiations for stainless steel capacity.
United States
FDA's Emerging Technology Program accelerates real-time release testing approvals for continuous fermentation implementations. The 2011 Process Validation guidance rewards facilities with integrated process analytical technology infrastructure. Greater Boston and San Francisco Bay Area clusters host the densest concentration of CDMO commissioning activity for gene therapy vector production.
Germany
EMA's revised Annex 1 sterile manufacturing mandates drive upstream environmental monitoring investments into bioreactor harvest operations. ICH Q9 quality risk management compliance extends facility qualification timelines, favoring established players with documentation expertise. Bavaria and Baden-Württemberg anchor the European single-use technology supply base through specialized polymer compounders.
China
WuXi Biologics and domestic peers commission 20,000-liter stainless steel trains alongside 2,000-liter disposable lines to capture biosimilar export demand. NMPA alignment with ICH guidelines accelerates multi-regional submission pathways for fermentation-derived products. Shanghai and Suzhou industrial parks concentrate the fastest cell culture capacity expansion in the Asia-Pacific region.
India
CDSCO relaxed comparability protocols for approved reference biologics create first-mover openings for trastuzumab and rituximab fermentation production. Government PLI scheme incentives support domestic biologics manufacturing infrastructure buildout. Hyderabad and Bangalore clusters attract contract manufacturing investment targeting Middle East and African export markets.
Switzerland
Swissmedic's alignment with EMA centralized procedures streamlines multi-country biologics licensing for fermentation-based therapeutics. Precision engineering heritage supports specialized bioreactor component fabrication for global equipment assemblers. Basel and Zurich regions concentrate Big Pharma captive production facilities with integrated cell line development capabilities.
Biopharmaceutical Fermentation Market Vendor Landscape
Capability concentration sits with specialized filtration and analytics vendors; scale advantage sits with diversified life sciences conglomerates. The market structures around three tiers: integrated platform licensors, single-use technology specialists, and precision instrumentation fabricators. Dominant competitive moves include portfolio diversification through chromatography-media bundling and geographic expansion through Asian manufacturing joint ventures.
Within the integrated platform tier, Thermo Fisher Scientific and Danaher Corporation exemplify conglomerate positioning through life sciences instrumentation and filtration technology portfolios. Sartorius Stedim Biotech occupies a specialist position in disposable bioprocessing systems. These three entities collectively represent the competitive archetypes reshaping procurement patterns: bundled service contracts, precision component supply, and flexible manufacturing infrastructure.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc |
| Danaher Corporation |
| Sartorius Stedim Biotech |
| Merck KGaA |
| Eppendorf AG |
| GE Healthcare |
| Lonza Group AG |
| Agilent Technologies |
| Becton, Dickinson and Company |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese stainless steel bioreactor manufacturing is compressing per-liter pricing for mammalian cell culture capacity while simultaneously pressuring Western single-use suppliers to accelerate service bundling. Contract Manufacturing Organizations exploit this utilization gap to negotiate shorter-term contracts with flexible termination clauses, shifting supplier risk toward equipment financiers and consumables compounders.
Pricing Analysis
After-sales revenue from gamma-irradiated film resins and chromatography media consumables now exceeds original equipment margins for single-use bioreactor vendors. Three-tier pricing structure across premium, standard, and economy levels separates validated GMP-grade systems from research-use-only configurations, with FDA-process-validated installations commanding substantial premiums. Cost compression in standard-tier stainless steel capacity is intensifying because WuXi Biologics and domestic peers are commissioning parallel 20,000-liter trains. Biotechnology firms with venture-backed funding profiles demonstrate highest price sensitivity, while Swiss and German Big Pharma captive facilities show lowest elasticity for integrated platform licensing.
Supply Chain Analysis
Tariff exposure between United States and China dominates strategic planning for medical-grade silicone tubing and polymer film resin sourcing. Supply concentrates in Germany, Switzerland, and China for precision bioreactor component fabrication, with gamma-irradiated film resins drawing from three dominant polymer compounders. Single-source vulnerability persists for cell retention devices and perfusion control algorithms used in continuous fermentation implementations. Distribution runs through direct OEM relationships with major Contract Manufacturing Organizations, bypassing traditional distribution intermediaries for large-capacity installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biopharmaceutical fermentation market operates as a defensive-moat story anchored in regulatory entrenchment. FDA and EMA validation documentation requirements create switching costs that extend facility qualification timelines by eight to fourteen months, locking incumbent positions.
For Market Incumbents: Pre-empt emerging continuous fermentation specialists by acquiring cell retention device developers before FDA Emerging Technology Program approvals validate their control strategies. Deepen backward integration into gamma-irradiated film resin compounding to offset plastics supply concentration risks from the three dominant polymer suppliers. Expand qualification documentation libraries to extend ICH Q9 compliance lead times for challengers. For New Entrants and Emerging Players: Build out gene therapy vector production capabilities in Greater Boston and San Francisco Bay Area clusters where CDMO commissioning activity concentrates for adeno-associated virus suspension adaptation. Target Indian biosimilar manufacturing under CDSCO relaxed comparability protocols as the most penetrable regulatory entry point. Lead with closed-system aseptic technique training programs to differentiate from traditional microbial fermentation workforces lacking advanced therapy medicinal product competencies. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across single-use technology segments as disposable standardization compresses facility build timelines from five years to eighteen months. Over the next decade, acquisition targets should emphasize process analytical technology infrastructure vendors with integrated data platforms capable of supporting real-time release testing implementations. Monitor FDA pre-submission meeting volumes for continuous processing as the signal indicating when validated platform licensing will displace standalone equipment sales.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Processing Regulatory Submission | FDA Emerging Technology Program pre-submission meetings de-risk novel control strategy filings for perfusion implementations. |
| Single-Use Technology Standardization | Disposable bioreactor platforms compress facility build timelines and reduce cross-contamination risks in multi-product CDMO facilities. |
| Process Analytical Technology Integration | Raman spectroscopy and capacitance probe data harmonization with legacy distributed control systems stretches validation resources. |
| Gene Therapy Vector Production Expansion | Adeno-associated virus stable producer cell line migration requires suspension adaptation expertise held by mammalian fermentation specialists. |
| Environmental Monitoring Program Extension | EMA Annex 1 mandates drive upstream investments into bioreactor harvest operations for continuous viable particle monitoring compliance. |
Methodological Framework
Desk research of FDA 483 inspection observations, EMA marketing authorization databases, and CDSCO manufacturing license records preceded structured interviews with bioprocess development directors, regulatory affairs leads, CDMO procurement managers, and single-use technology vendor account executives. Secondary validation drew from ICH guideline documentation, PDA technical reports, and ISO 14644 cleanroom classification standards. Bottom-up capacity utilization models and top-down biologics pipeline forecasts were triangulated to anchor segmentation outputs.
Assumptions held constant include ICH Q12 lifecycle management framework continuity, existing FDA Process Validation guidance interpretation, and current EMA Annex 1 environmental monitoring requirements across the projection horizon. Segmentation dimensions modeled encompass product type, process modality, end-user category, and regional regulatory cluster. CAGRs were derived from installed base expansion rates, capacity utilization trajectories, and outsourcing penetration trends. Forecast inputs incorporated bioreactor scale distributions, single-use versus stainless steel technology mix shifts, and Contract Manufacturing Organization commissioning timelines.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Chinese state-supported biologics infrastructure builders would shift outcomes through accelerated price erosion in stainless steel segments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Generic Oncology Drugs Market
Biopharmaceuticals
Global Immuno Oncology Assays Market
Biopharmaceuticals
Bromodomain and Extraterminal Domain (BET) Inhibitors Market
Biopharmaceuticals
North America Biotechnology Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Macrolide Antibiotics Market
Biopharmaceuticals
Biotherapeutics Cell Line Development Market
Biopharmaceuticals
Mexico Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Botanical and Plant Derived Drugs Market
Biopharmaceuticals
Disease-Modifying Antirheumatic Drug (DMARD) Market
Biopharmaceuticals
Laband Syndrome Therapeutics Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Recombinant Protein Therapeutics CDMO Market
Biopharmaceuticals
Octreotide Market
Biopharmaceuticals
Germany Insulin Drugs and Delivery Devices Market