
 Global Protein Expression Market | 2026-2036
Global Protein Expression Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein Expression Market Foresight
CHO cell culture media is decoupling from serum-dependent formulations, cutting batch-to-batch variability and per-unit production costs. Thermo Fisher Scientific leverages its Gibson assembly and ExpiCHO platforms to dominate high-titer transient expression workflows. Agilent Technologies anchors its position through analytical instrumentation that monitors protein quality attributes in real time. Lonza sustains competitive differentiation via modular biomanufacturing facilities that slash client capital deployment.
Protein expression denotes the laboratory or industrial process of synthesizing proteins through heterologous gene transcription and translation within host systems, typically achieving titers from milligrams to grams per liter depending on vector design and bioreactor conditions. Its primary commercial purpose is generating functional biomolecules for therapeutic, diagnostic, and research applications where natural sourcing proves inadequate or nonviable. Mammalian expression systems command premium pricing due to their human-compatible glycosylation patterns required for monoclonal antibody production. Bacterial expression retains cost leadership for non-glycosylated enzymes and fusion proteins where post-translational modification demands remain minimal.
FDA's Quality by Design mandates and EMA's biosimilar comparability guidelines force manufacturers to document critical quality attributes across expression batches, raising compliance costs but filtering subscale competitors. China's NMPA streamlined biologics review pathways are accelerating local CMO capacity expansion while tightening data integrity requirements for imported expression platforms. ISO 13485 and GMP Annex 1 revisions are reshaping cleanroom and contamination control standards for therapeutic protein manufacturing. Stakeholders must monitor how CRISPR-edited host cell lines and continuous bioprocessing reshape facility economics and regulatory inspection priorities.
Market Dynamics
Continuous bioprocessing is compressing facility footprints and batch cycle times, forcing incumbents to retire fed-batch infrastructure or write down stranded assets. This technology transition redistributes competitive advantage toward engineering-intensive contract manufacturers with modular platform expertise.
Growth Catalysts
- FDA Accelerated Approval:Compressed timelines for monoclonal antibody therapies pull forward investment in high-titer mammalian expression platforms. Biopharmaceutical sponsors prioritize CMOs with documented prior-approval inspection histories.
- China NMPA Streamlined Pathways:Domestic biologics review acceleration expands local manufacturing capacity for export-grade therapeutic proteins. Multinational sponsors now dual-source expression campaigns across US and Chinese CMO networks.
- CRISPR Host Cell Engineering:Edited CHO and HEK293 lines achieve glycosylation profiles previously requiring human cell systems. Platform developers license these cell banks under milestone-bearing agreements.
Market Restraints
- Plasmid DNA Supply Concentration:GMP-grade plasmid production clusters in a limited supplier base, creating bottleneck risk for transient expression workflows. Long-term supply agreements now carry force majeure premiums.
- EMA Biosimilar Comparability Burden:Extensive analytical characterization requirements for glycosylation pattern matching extend development timelines. Smaller developers lack capital to build in-house mass spectrometry capabilities.
- Serum Price Volatility:Fetal bovine serum spot markets fluctuate with livestock health cycles, complicating cost forecasting for legacy adherent culture processes. Serum-free media conversion requires 18-24 month validation cycles.
Strategic Opportunities
- India CDMO Capacity:Underdeveloped large-scale mammalian expression infrastructure creates first-mover advantage for platform investors. CDSCO manufacturing license reforms reduce facility approval timelines versus historical baselines.
- Cell-Free Synthesis:In vitro transcription-translation systems bypass living cell constraints for toxic or unstable protein targets. Synthetic biology tool providers are commercializing extract-based platforms for rapid screening applications.
- Japan PMDA Sakigake Designation:Priority review incentives for innovative biologics accelerate Japan-origin development programs. Expression sponsors partner with domestic CMOs to secure manufacturing slots under expedited timelines.
Industry Challenges
- Process Analytical Technology Integration:Real-time quality attribute monitoring requires cross-functional teams combining bioprocessing engineers, data scientists, and regulatory specialists. Talent scarcity in PAT implementation delays GMP filing readiness.
- Multi-Product Facility Segregation:Campaign changeover validation for antibody-drug conjugates versus naked monoclonal antibodies demands extensive cleaning verification. CMOs face capacity allocation conflicts between high-value and high-volume programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein Expression Market |
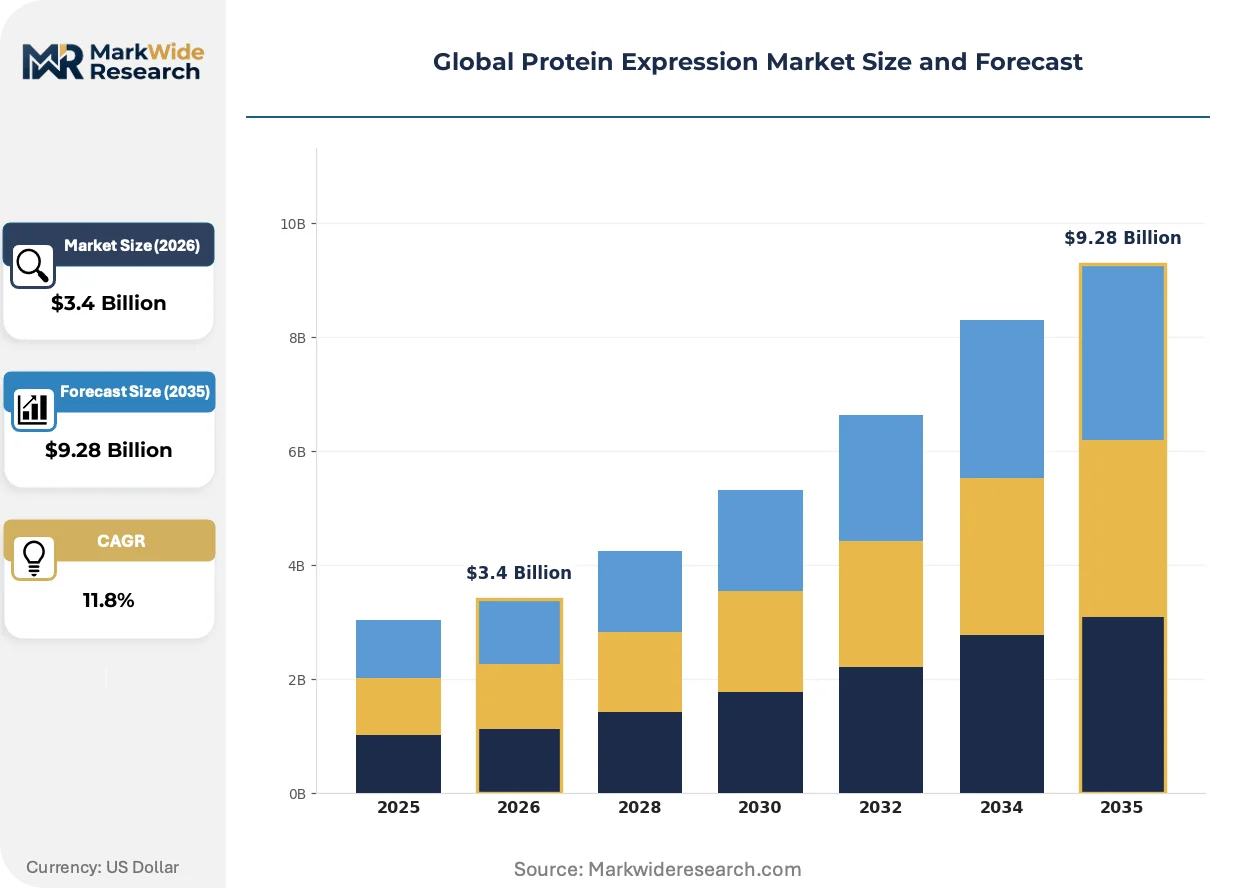
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Cell-Free Systems, Mammalian Expression, Bacterial Expression, Yeast Expression Product Type: Recombinant Proteins, Antibodies, Enzymes, Fusion Proteins Application: Diagnostics, Drug Discovery, Therapeutic Proteins, Industrial Applications End User: Biopharmaceutical Companies, Academic Research Institutions, Contract Research Organizations, Biotechnology Firms |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Merck KGaA, Lonza, Sartorius, QIAGEN, Bio-Rad Laboratories, Promega, Takara Bio, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein Expression Market Shifts & Advancements
Platform standardization is colliding with personalized medicine requirements, creating tension between economies of scale and lot-size flexibility. Expression technology providers are responding with configurable hardware and disposable fluid management systems.
Single-use bioreactor technology is modularizing facility design, enabling 2,000-liter production trains to deploy in warehouse-converted cleanrooms rather than purpose-built steel plants. Mid-cap biopharmaceutical companies are adopting these systems for Phase III material supply, avoiding $200-million-plus capital commitments. This shift is modularizing the competitive landscape, allowing niche CMOs to challenge integrated majors on speed-to-GMP rather than scale alone.
EMA's Annex 1 revision on sterile manufacturing is mandating closed-system processing for aseptic operations, disqualifying open manipulations previously standard in seed train expansion. Facility retrofit costs concentrate among European CMOs with legacy stainless steel infrastructure. Mammalian expression sponsors are prioritizing partners with pre-validated isolator technology to avoid regulatory query delays.
Biopharmaceutical procurement teams are consolidating expression campaigns with single CMO partners capable of spanning cell line development through commercial supply. This vendor consolidation displaces the historical model of fragmented outsourcing across specialized boutiques. US-based monoclonal antibody developers are most aggressive in this shift, seeking to reduce technology transfer risks and audit burden multiplication.
Global Protein Expression Market Segmentation
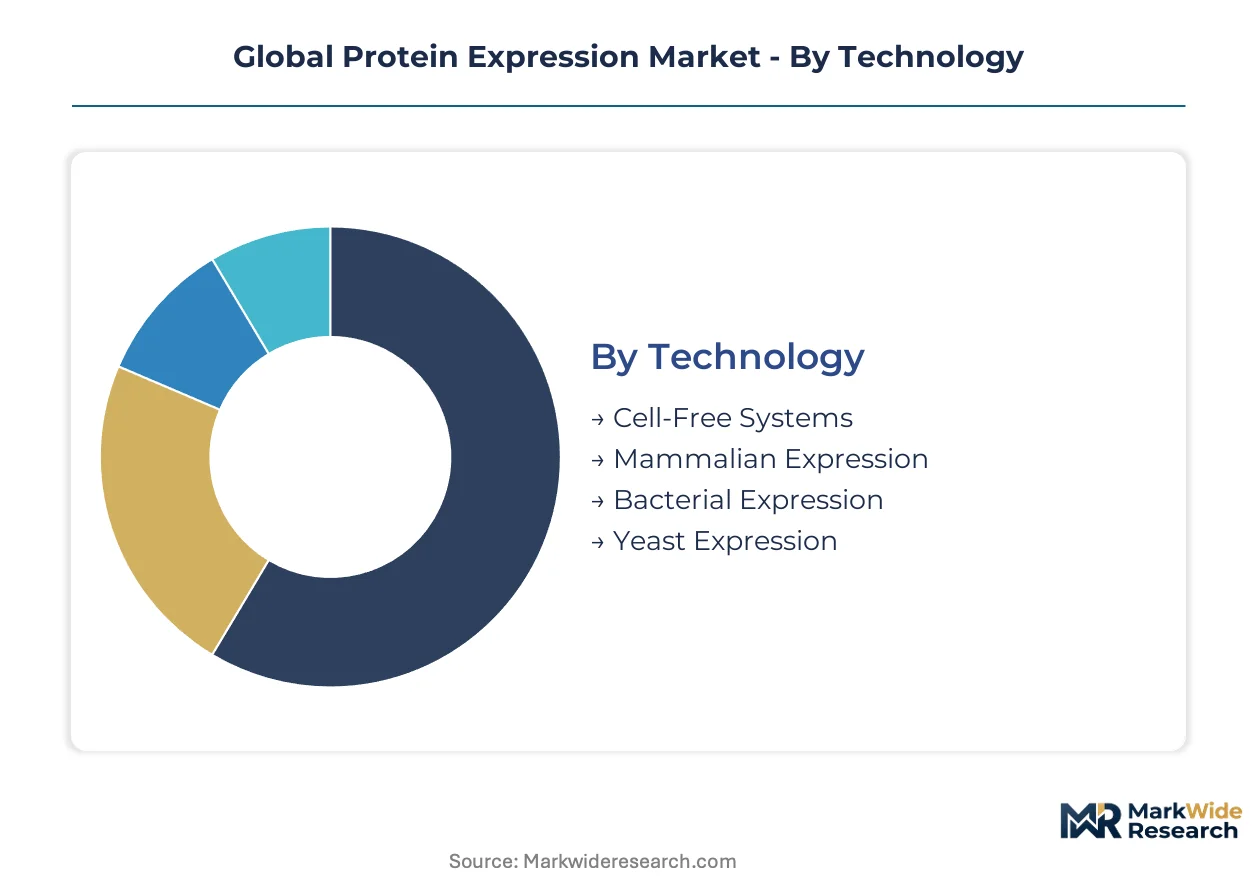
Protein expression segmentation reveals how technology choices cascade through product specifications, application requirements, and procurement patterns. Understanding these linkages exposes where margin concentrates and where commoditization threatens.
Technology:
Technology selection determines glycosylation fidelity, scalability ceiling, and regulatory pathway complexity.
- Mammalian Expression:CHO and HEK293 systems generate human-compatible glycosylation patterns essential for monoclonal antibody therapeutics. Demand clusters in Massachusetts and California biotech corridors where FDA prior-approval inspection histories command premium CMO pricing.
- Bacterial Expression:E. coli platforms dominate non-glycosylated enzyme production with faster doubling times and simpler media formulations. Cost-sensitive industrial enzyme procurement in Germany and China favors these systems for bulk manufacturing.
- Yeast Expression:Pichia pastoris and Saccharomyces cerevisiae offer intermediate glycosylation capabilities for vaccines and subunit proteins. FDA's CBER guidance on yeast-derived products shapes validation requirements.
- Cell-Free Systems:In vitro transcription-translation bypasses cell viability constraints for toxic or unstable protein targets. Synthetic biology tool providers commercialize extract-based platforms for rapid screening workflows.
Mature deployment sits with Mammalian Expression. Newer deployment is concentrated in Cell-Free Systems.
Product Type:
Product categories stratify by molecular complexity, regulatory burden, and pricing power.
- Antibodies:Monoclonal and bispecific constructs require mammalian hosts and command the highest per-gram valuations. China's NMPA streamlined biologics pathways accelerate domestic manufacturing capacity for export-grade therapeutic antibodies.
- Recombinant Proteins:Cytokines, growth factors, and hormones span multiple expression hosts based on post-translational modification needs. Germany's EMA-regulated CMOs specialize in complex multi-domain constructs.
- Fusion Proteins:Chimeric molecules combining functional domains demand precise linker engineering and cleavage site validation. Fc-fusion half-life extension drives oncology and immunology applications.
- Enzymes:Industrial biocatalysts and diagnostic reagents prioritize yield over glycosylation fidelity. Bacterial expression retains cost leadership for high-volume protease and polymerase production.
Volume leadership belongs to Enzymes. Value concentration rests with Antibodies.
Application:
Application context dictates quality grade, documentation depth, and timeline pressure.
- Therapeutic Proteins:GMP-grade manufacturing for clinical and commercial supply demands validated cell banks and extensive analytical characterization. FDA Quality by Design mandates force documentation of critical quality attributes across expression batches.
- Drug Discovery:Research-grade material supports target validation and lead optimization with accelerated turnaround requirements. CROs in the United States compete on transient expression speed for screening campaigns.
- Diagnostics:Immunoassay components and calibrators require consistent lot-to-lot performance but lower purity thresholds than therapeutics. ISO 13485 quality systems govern manufacturing for IVD manufacturers.
- Industrial Applications:Food processing enzymes and biofuel catalysts prioritize cost-per-unit activity over regulatory dossier completeness. GRAS self-determination pathways in the United States reduce approval friction.
Regulatory intensity peaks in Therapeutic Proteins. Speed premiums concentrate in Drug Discovery.
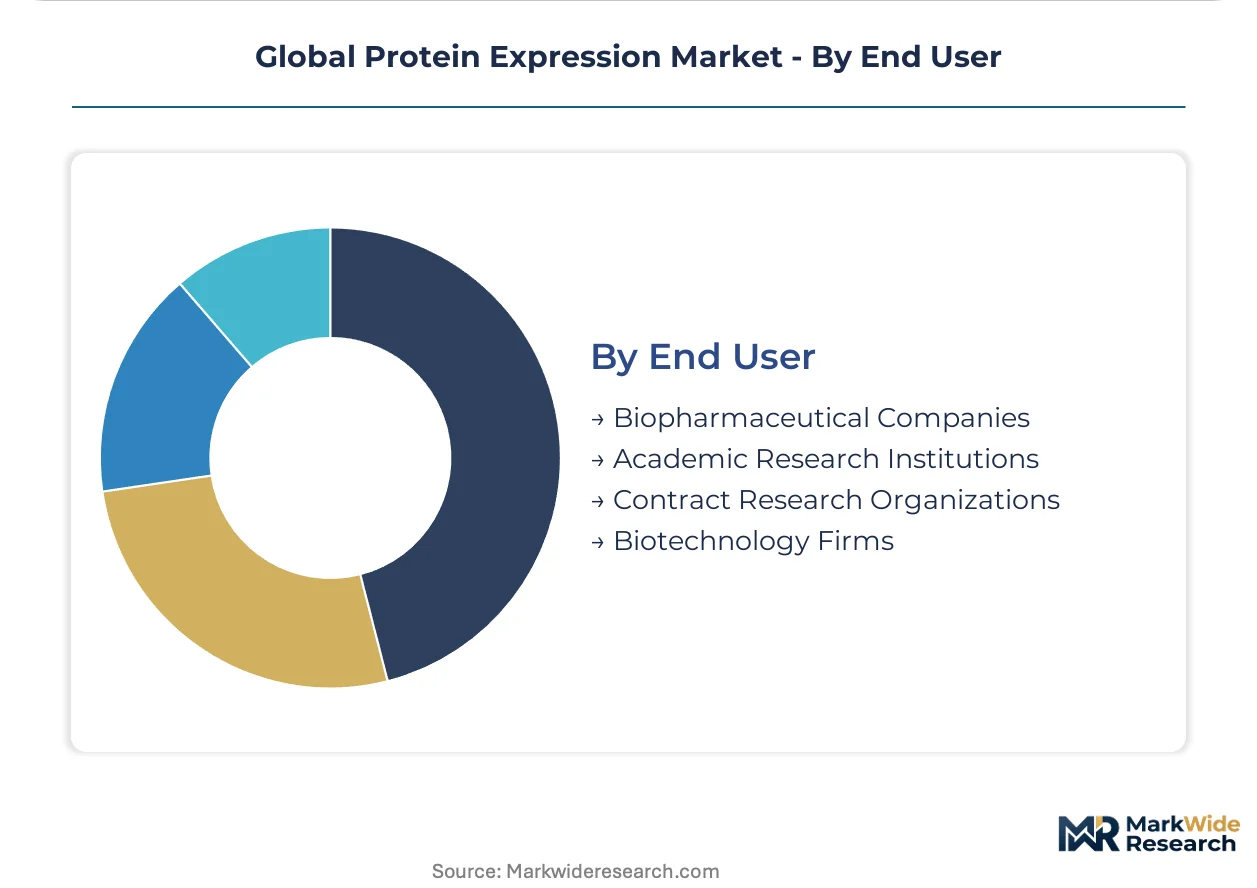
End User:
End user type shapes procurement sophistication, contract structure, and technical service expectations.
- Biopharmaceutical Companies:Large-cap sponsors consolidate expression campaigns with single CMO partners spanning cell line development through commercial supply. Technology transfer risk reduction drives vendor consolidation.
- Contract Research Organizations:Mid-scale CROs specialize in rapid transient expression for discovery-stage material with flexible milestone-based pricing. CDSCO manufacturing license reforms in India expand capacity for Western sponsor outsourcing.
- Academic Research Institutions:University core facilities and principal investigator labs prioritize reagent accessibility over GMP compliance. Grant-funded procurement favors catalog proteins and shared resource centers.
- Biotechnology Firms:Venture-backed developers balance platform flexibility against capital efficiency in facility decisions. Single-use bioreactor adoption enables Phase III material supply without steel plant commitments.
Procurement sophistication is highest among Biopharmaceutical Companies. Price sensitivity concentrates in Academic Research Institutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharmaceutical manufacturing demand clusters in three jurisdictions with clustered biotech hubs and accelerated regulatory pathways. Contract manufacturing investment concentrates where prior-approval inspection histories command pricing premiums.
United States
FDA accelerated approval pathways for monoclonal antibody therapies compress development timelines and pull forward investment in high-titer mammalian expression platforms. Massachusetts and California biotech corridors anchor concentrated CMO capacity where documented inspection histories justify premium pricing. Biopharmaceutical sponsors prioritize partners with established regulatory track records.
China
NMPA streamlined biologics review pathways accelerate domestic manufacturing capacity for export-grade therapeutic proteins. Multinational sponsors now dual-source expression campaigns across US and Chinese CMO networks. Yangtze River Delta biotech parks anchor contract manufacturing expansion with tightened data integrity requirements for imported expression platforms.
Germany
EMA adaptive licensing frameworks and biosimilar comparability guidelines force extensive analytical characterization for glycosylation pattern matching. EMA-regulated CMOs specialize in complex multi-domain recombinant protein constructs. Bavaria and Baden-Württemberg anchor European therapeutic protein manufacturing with legacy stainless steel infrastructure facing Annex 1 retrofit costs.
India
CDSCO manufacturing license reforms reduce facility approval timelines versus historical baselines, creating first-mover advantage for large-scale mammalian expression platform investors. Underdeveloped infrastructure in high-volume biologics manufacturing attracts capital deployment. Maharashtra and Karnataka biotech corridors expand CRO capacity for Western sponsor outsourcing.
Japan
PMDA Sakigake designation priority review incentives for innovative biologics accelerate Japan-origin development programs. Expression sponsors partner with domestic CMOs to secure manufacturing slots under expedited timelines. Kanto and Kansai regions concentrate biopharmaceutical development with METI-supported biomanufacturing initiatives.
Global Protein Expression Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with platform technology providers commanding premium positions in high-titer workflows while analytical instrumentation vendors anchor quality attribute monitoring. The vendor base organizes around three archetypes: integrated life science conglomerates with end-to-end expression platforms, specialized contract manufacturers with modular facility expertise, and analytical tool providers enabling real-time process monitoring. Dominant competitive moves include strategic technology licensing for CRISPR-edited host cell lines and capacity expansion through single-use bioreactor infrastructure.
Within the integrated life science tier, Thermo Fisher Scientific and Merck KGaA occupy positions spanning reagent supply through bioproduction platforms. Lonza represents the contract manufacturing archetype with modular facility deployment capabilities. Agilent Technologies exemplifies analytical instrumentation specialization for protein quality attribute verification.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Merck KGaA |
| Lonza |
| Sartorius |
| QIAGEN |
| Bio-Rad Laboratories |
| Promega |
| Takara Bio |
| Others |
Supply & Pricing Matrix
EMA's Annex 1 revision on sterile manufacturing gates qualified supply access and premium-tier pricing for mammalian expression workflows. Biopharmaceutical sponsors now pay isolator-technology premiums to CMOs with pre-validated closed-system infrastructure, while legacy open-manipulation facilities face margin compression from retrofit cost burdens.
Pricing Analysis
Volume leadership in bacterial expression systems runs on commodity per-gram pricing, while mammalian antibody production commands project-based premiums tied to glycosylation fidelity and FDA prior-approval inspection histories. Price differentiation separates GMP-grade therapeutic campaigns from research-grade discovery material, with certification tier and volume scale as twin drivers. Cost compression in standard-grade bacterial enzymes is intensifying because Chinese and Indian CDMOs are expanding fermentation capacity. Academic research institutions exhibit highest price sensitivity; large-cap biopharmaceutical companies show lowest sensitivity due to technology transfer risk aversion.
Supply Chain Analysis
Bioprocessing engineer scarcity in Massachusetts, California, and Bavaria is constraining expansion timelines for high-titer mammalian facilities. GMP-grade plasmid DNA production concentrates in the United States, Germany, and China, while fetal bovine serum sourcing draws from Australia and New Zealand livestock markets. Single-source vulnerability in edited CHO cell line licensing creates bottleneck risk for CRISPR-engineered platforms. Distribution runs through direct CMO-sponsor partnerships with milestone-bearing technology transfer agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The protein expression market sits in a technology-transition phase as continuous bioprocessing displaces fed-batch infrastructure. Single-use bioreactor modularization is rendering legacy stainless steel plants economically obsolete.
For Market Incumbents: Cement regulatory track record advantages by accelerating prior-approval inspection history accumulation at US and EU facilities. Deepen backward integration into GMP-grade plasmid manufacturing to neutralize supply concentration risk. Incumbent CMOs with isolator-validated infrastructure should leverage EMA Annex 1 compliance as a pricing power anchor against retrofit-lagged competitors.
For New Entrants and Emerging Players: Enter via India's underdeveloped large-scale mammalian capacity, where CDSCO manufacturing license reforms compress facility approval timelines versus historical baselines. Target cell-free synthesis platforms for toxic protein targets where living cell constraints create white-space opportunity. Partner with synthetic biology tool providers to commercialize extract-based rapid screening workflows.
For Investors and Strategic Acquirers: FDA accelerated approval pathway expansion for monoclonal antibodies is the leading indicator that high-titer mammalian CMO capacity will command sustained pricing premiums. Platform developers with CRISPR-edited host cell line banks represent priority acquisition archetypes. Watch for force majeure premiums in long-term plasmid supply agreements as signals of tightening GMP-grade DNA bottlenecks.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Bioprocessing Adoption | Compresses facility footprints and batch cycle times for mammalian antibody campaigns. |
| CRISPR Host Cell Line Licensing | Edited CHO banks achieve human-compatible glycosylation under milestone-bearing agreements. |
| Single-Use Bioreactor Deployment | Enables Phase III material supply without steel plant capital commitments. |
| Isolator Technology Pre-Validation | EMA Annex 1 compliance disqualifies open-manipulation seed train expansion. |
| Dual-Source CMO Network Expansion | Multinational sponsors split expression campaigns across US and Chinese facilities. |
Research Methodology
SEC 10-K filings, FDA prior-approval inspection databases, and EMA centralized procedure outcome records formed the secondary backbone for capacity and regulatory track record assessment. Primary interviews with bioprocessing engineers, CMO business development leads, biopharmaceutical procurement directors, and regulatory affairs specialists validated platform adoption timelines and pricing benchmarks. Bottom-up facility capacity modeling triangulated against top-down therapeutic antibody demand projections.
Historical trendline analysis of mammalian expression titer improvements and batch cycle time compression informed the analytical framework across the projection horizon. Segmentation dimensions spanned expression system technology, product molecular complexity, application quality grade, and end-user procurement sophistication. CAGRs were derived from facility investment pipelines and regulatory pathway acceleration patterns. Forecast inputs incorporated CRISPR host cell line licensing velocity and single-use bioreactor installation rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under plasmid DNA supply disruption or Annex 1 retrofit cost overruns. Projections reflect assumptions regarding FDA and NMPA pathway continuity, CHO cell line editing regulatory acceptance, and serum-free media conversion timelines. Material deviation in GMP-grade plasmid supplier consolidation or EMA biosimilar comparability burden escalation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Recombinant Hormone Market
Biopharmaceuticals
North America Insulin Pens Market
Biopharmaceuticals
China Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Diabetes Drugs Market
Biopharmaceuticals
Global Vaccine Conjugate Market
Biopharmaceuticals
Italy Insulin Drugs and Delivery Devices Market
Biopharmaceuticals
Ovarian Cancer Drugs Market
Biopharmaceuticals
Immunotoxins Market
Biopharmaceuticals
Chemotherapy Drugs Market
Biopharmaceuticals
Biopharmaceutical Contract Research and Manufacturing Services (CRAMS) Market
Biopharmaceuticals
Global Bovine Blood Plasma Derivatives Market
Biopharmaceuticals
Biologics Contract Development Market
Biopharmaceuticals
Triclabendazole Market
Biopharmaceuticals
Metabolism Drugs Market
Biopharmaceuticals
Global Branded Generics Market
Biopharmaceuticals
Non-Receptor Tyrosine Kinase Inhibitors Market