
 Heparin API Market | 2026-2036
Heparin API Market Size, Share, and Industry Trends Forecast 2026-2036
Heparin API Market Analytics
Specialized biochemist talent is rotating from traditional chemical synthesis toward mammalian-derived and recombinant heparin production, tightening labor availability for conventional extraction methods. Pfizer Inc. sustains vertical integration across porcine sourcing and finished-dose formulation. Shenzhen Hepalink Pharmaceutical Co., Ltd. dominates global unfractionated heparin sodium output through captive pig intestine supply chains. Sanofi S.A. differentiates via Low Molecular Weight Heparin intellectual property depth and hospital channel control.
Heparin API comprises sulfated glycosaminoglycan polymers extracted primarily from porcine intestinal mucosa or produced through recombinant bacterial fermentation, with molecular weights ranging from 3 to 30 kDa for unfractionated forms and 4 to 6 kDa for depolymerized fractions; its anticoagulant function stems from binding antithrombin III to inhibit thrombin and Factor Xa, making it indispensable for thrombosis prophylaxis and cardiac intervention. Low Molecular Weight Heparin commands the dominant margin pool due to predictable pharmacokinetics and outpatient suitability, while Synthetic Heparin represents the fastest-growing category as recombinant technologies reduce immunogenicity risks and supply vulnerability to porcine herd fluctuations. Unfractionated Heparin remains entrenched in dialysis and surgical anticoagulation where rapid reversibility with protamine sulfate proves clinically essential.
FDA enforces stringent residual impurity limits under heparin monograph standards, while EMA's MDR and REACH frameworks govern device-drug combination products and raw material traceability respectively; China's NMPA and SAMR impose dual carbon goals and GB standards that elevate environmental compliance costs for domestic API manufacturers. Stakeholders must monitor regulatory divergence between US pharmacopeial purity requirements and emerging biosimilar heparin pathways in Europe, as compliance investment thresholds will determine which production technologies achieve scalable market access.
Market Dynamics
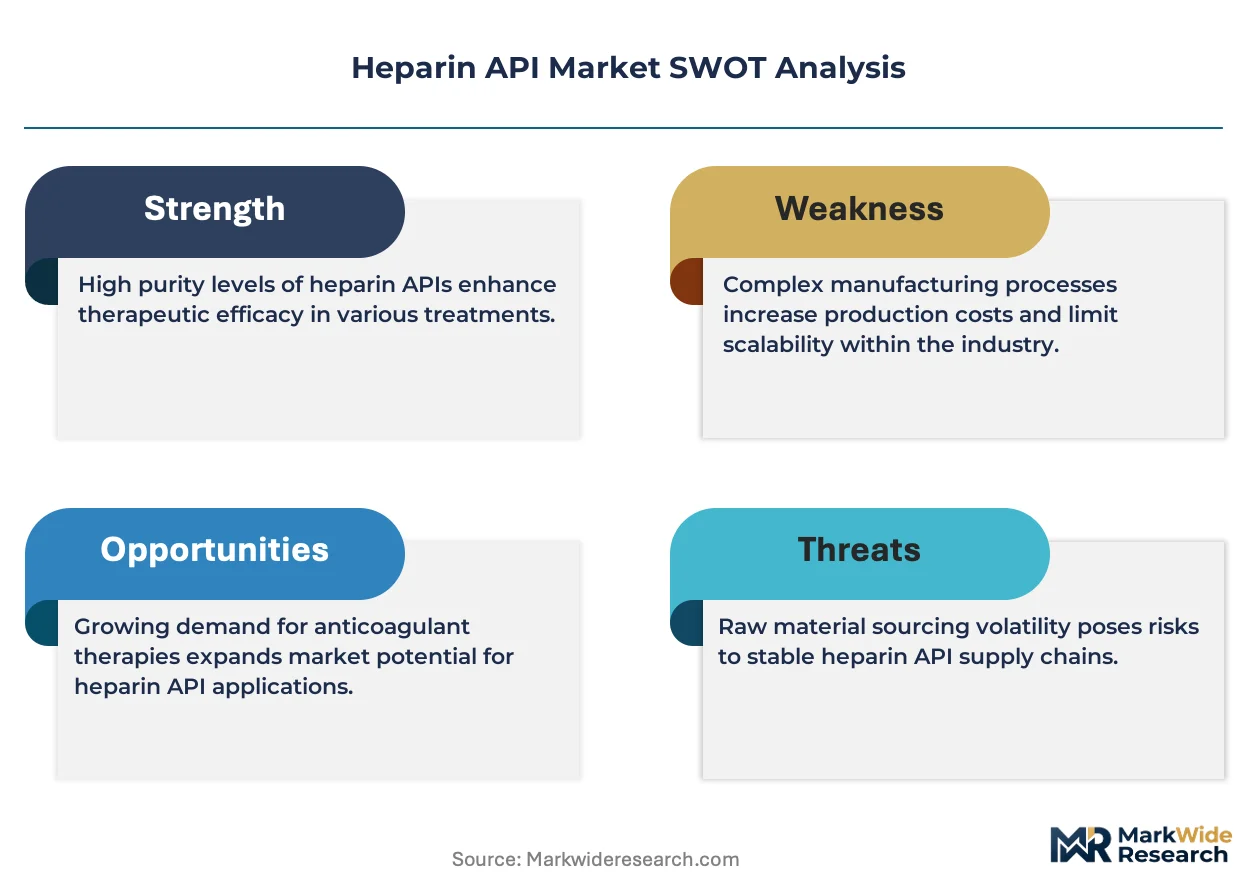
Porcine intestinal mucosa supply concentration in China and India is compressing manufacturing economics while FDA and EMA purity mandates force capital-intensive purification upgrades across all production tiers.
Growth Catalysts
- Thrombosis prophylaxis protocols:Hospital anticoagulant procurement for cardiac catheterization and orthopedic surgery is intensifying unfractionated heparin consumption in tertiary care centers.
- EMA MDR device-drug frameworks:Regulatory clarity for heparin-coated stents and catheters is expanding addressable applications beyond injectable therapeutics.
- Recombinant bacterial fermentation:Synthetic heparin production technologies are reducing immunogenicity risks and decoupling supply from livestock herd volatility.
Market Restraints
- Porcine raw material volatility:African swine fever outbreaks and feed cost inflation in Chinese pig farming regions are destabilizing intestinal mucosa pricing.
- Residual impurity compliance costs:FDA heparin monograph limits on oversulfated chondroitin sulfate and other contaminants require multi-stage chromatography investments.
- Direct oral anticoagulant substitution:Rivaroxaban and apixaban are capturing outpatient venous thromboembolism prophylaxis from low molecular weight heparin.
Strategic Opportunities
- Brazilian hospital channel expansion:ANVISA regulatory harmonization with ICH standards is opening import pathways for recombinant heparin APIs.
- Home dialysis anticoagulation:Portable heparin infusion systems for peritoneal dialysis patients are creating new outpatient demand pools.
- India PLI scheme incentives:Domestic production-linked incentives for critical APIs are attracting fermentation capacity investments away from Chinese supply chains.
Industry Challenges
- Mammalian cell culture biochemist scarcity:Talent migration from chemical synthesis to recombinant heparin production is constraining conventional extraction facility staffing.
- Batch-to-batch molecular weight consistency:Unfractionated heparin potency variation requires extensive in-process testing, extending release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heparin API Market |
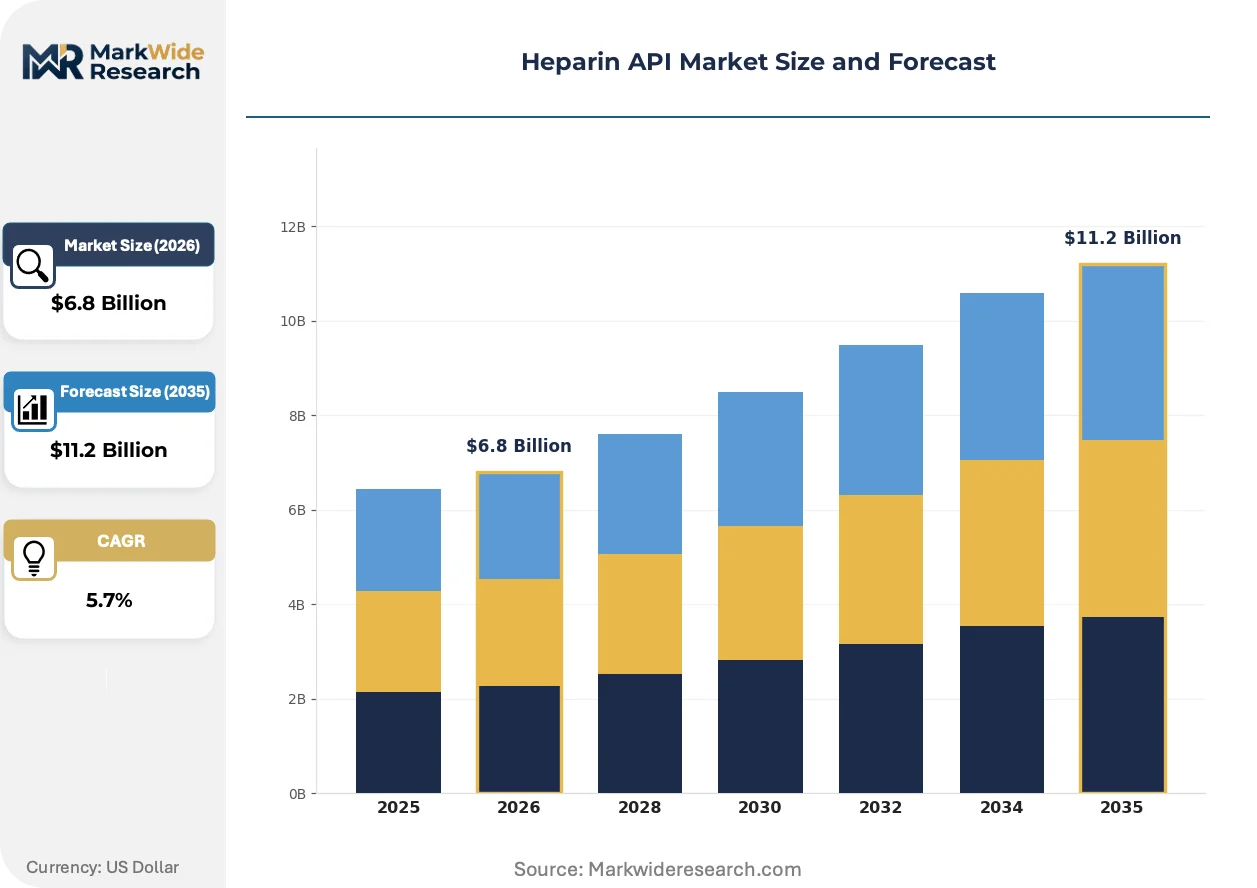
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unfractionated Heparin, Low Molecular Weight Heparin, Synthetic Heparin, Biosimilar Heparin Application: Treatment of Thrombosis, Cardiac Procedures, Dialysis, Surgical Procedures Delivery Mode: Injection, Oral, Intravenous, Subcutaneous End User: Hospitals, Clinics, Pharmacies, Home Healthcare |
| Companies Covered | Shenzhen Hepalink Pharmaceutical Co., Ltd., Pfizer Inc., Sanofi S.A., Fresenius Kabi AG, Changzhou Qianhong Bio-pharma Co., Ltd., Hebei Changshan Biochemical Pharmaceutical Co., Ltd., Bioiberica S.A.U., Teva Pharmaceutical Industries Ltd., Aspen Pharmacare Holdings Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heparin API Market Evolving Landscape
Recombinant manufacturing platforms and real-time release testing protocols are compressing production cycles while regulatory divergence between pharmacopeial standards and biosimilar pathways is fragmenting compliance strategies.
Enzymatic heparin synthesis using recombinant heparin lyases and sulfotransferases is supplanting chemical depolymerization for low molecular weight heparin production. Contract manufacturers serving European hospital networks are adopting these biocatalytic routes to meet EMA impurity specifications. The technology is enabling site-specific sulfation patterns that reduce batch rejection rates and accelerate regulatory filing timelines.
REACH raw material traceability mandates combined with EMA MDR device-drug combination rules are forcing heparin API suppliers to document porcine sourcing through slaughterhouse records. Manufacturers supplying heparin-coated medical devices must now maintain chain-of-custody documentation from farm to finished product. European contract manufacturers are responding by integrating backward into captive pig intestine processing or switching to recombinant sources entirely.
Hospital purchasing consortia in Germany and France are consolidating anticoagulant procurement through centralized tendering platforms, displacing traditional distributor relationships. These aggregated buying mechanisms are compressing price realization for unfractionated heparin while favoring suppliers with dual-source manufacturing capabilities. The shift is most pronounced in university hospital networks where pharmacy committees now mandate supply redundancy clauses in API contracts.
Heparin API Market Segmentation
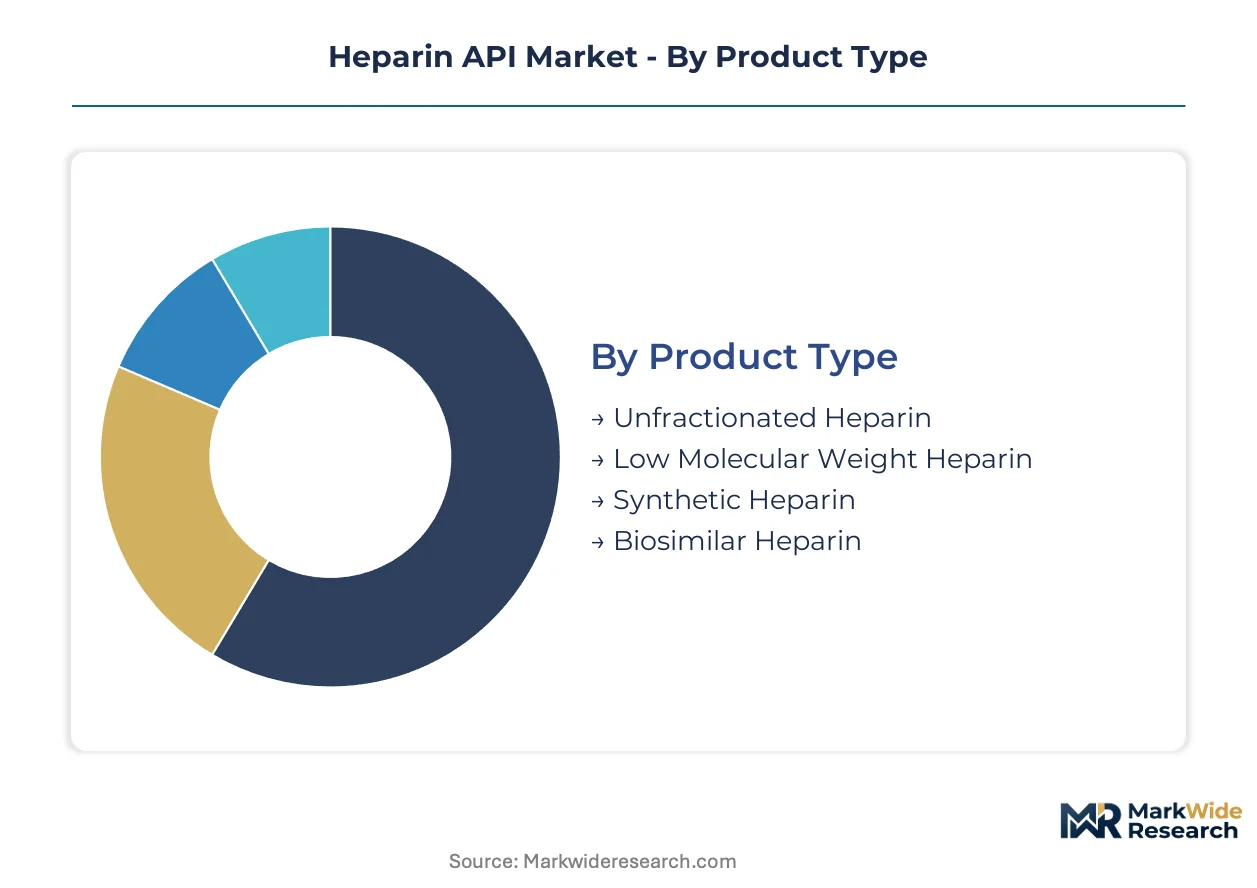
Heparin API segmentation reveals how regulatory pathways and clinical use cases fragment manufacturing requirements. Each dimension carries distinct compliance burdens and pricing power dynamics that determine competitive positioning.
Product Type:
FDA heparin monograph standards and EMA MDR frameworks impose divergent purity thresholds across molecular weight categories, forcing manufacturers to maintain separate production lines or purification protocols.
- Low Molecular Weight Heparin:Depolymerized fractions with 4-6 kDa molecular weight deliver predictable pharmacokinetics enabling outpatient administration. Hospital procurement consortia in Germany and France concentrate demand through centralized tendering, compressing margins while favoring dual-source suppliers. EMA device-drug combination rules expand addressable applications into coated stents and catheters.
- Unfractionated Heparin:Sulfated glycosaminoglycan polymers spanning 3-30 kDa require protamine sulfate reversibility in dialysis and surgical settings. Tertiary care centers in the US and China sustain consumption despite direct oral anticoagulant competition, driven by rapid anticoagulation reversal protocols in cardiac catheterization.
- Synthetic Heparin:Recombinant bacterial fermentation output reduces immunogenicity risks and livestock supply dependence.
- Biosimilar Heparin:Emerging European regulatory pathways for complex glycosaminoglycan copies are fragmenting compliance investment requirements.
Low Molecular Weight Heparin handles the majority of throughput; Synthetic Heparin is climbing the fastest on share.
Application:
Clinical setting determines dosing volume, reversibility requirements, and reimbursement pathways, creating tiered margin structures across therapeutic areas.
- Treatment of Thrombosis:Venous thromboembolism prophylaxis commands the largest patient volume across orthopedic surgery and medical ward admissions. Outpatient suitability drives preference toward low molecular weight formulations, though rivaroxaban and apixaban are capturing stable patients in the US and European markets.
- Cardiac Procedures:Cardiac catheterization and coronary intervention require rapid anticoagulation onset and reversal capability. Hospital networks in France and university medical centers in Germany mandate supply redundancy clauses in procurement contracts, elevating qualification barriers for single-source suppliers.
- Dialysis:Hemodialysis anticoagulation sustains unfractionated heparin demand through extracorporeal circuit patency requirements.
- Surgical Procedures:Intraoperative anticoagulation for vascular and cardiac surgery maintains consistent hospital consumption.
Treatment of Thrombosis captures the highest patient volume; Cardiac Procedures generate the steepest per-procedure revenue.
Delivery Mode:
Route of administration dictates formulation complexity, stability requirements, and patient self-administration feasibility, with direct implications for manufacturing scale and distribution infrastructure.
- Injection:Parenteral delivery dominates heparin administration across all clinical settings, requiring aseptic fill-finish capacity and cold chain integrity. Prefilled syringe formats are displacing vial-and-needle configurations in European hospital pharmacies, driving capital investment into automated assembly lines.
- Intravenous:Continuous infusion protocols in ICU and surgical settings demand precise concentration standardization and compatibility with standard infusion pumps. US hospital formularies specify heparin sodium in unit-dose bags, requiring contract manufacturers to maintain dedicated IV admixture suites.
- Subcutaneous:Self-administration for outpatient prophylaxis favors low molecular weight heparin with fixed dosing and minimal monitoring.
- Oral:No clinically viable oral heparin formulation exists; research-stage synthetic analogs face bioavailability barriers.
Injection handles the majority of throughput; Subcutaneous formats are expanding most quickly into home healthcare.
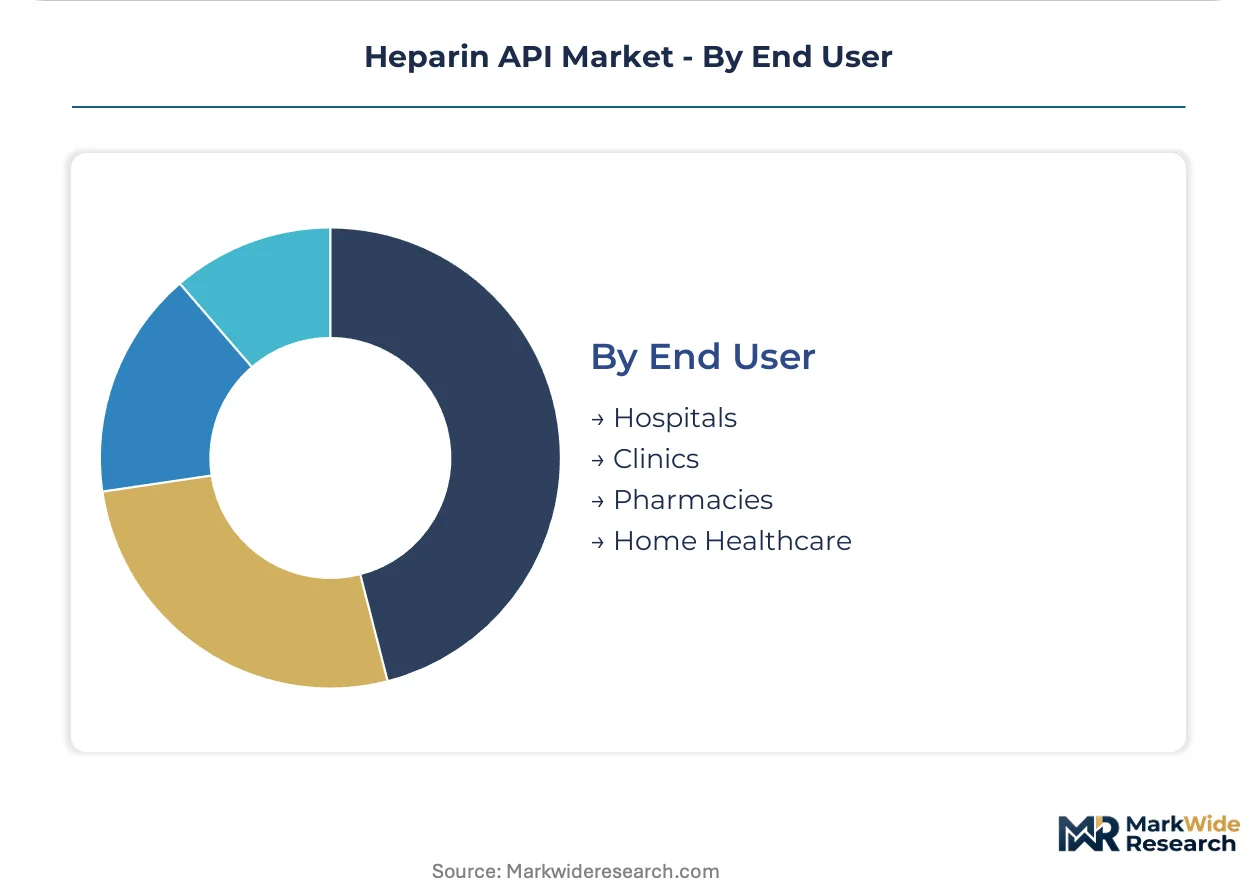
End User:
Purchasing concentration and formulary control authority vary sharply across care settings, determining price realization and contract structure.
- Hospitals:Tertiary care centers and academic medical centers concentrate anticoagulant procurement through pharmacy committees and therapeutics subcommittees. German hospital purchasing consortia and French university hospital networks have displaced traditional distributor relationships through centralized tendering platforms, aggregating volume and compressing price realization for unfractionated heparin.
- Home Healthcare:Peritoneal dialysis patients and post-surgical prophylaxis cases are creating new outpatient demand pools through portable infusion systems. ANVISA regulatory harmonization with ICH standards in Brazil is opening import pathways for recombinant heparin APIs targeting this channel.
- Clinics:Ambulatory surgery centers and anticoagulation clinics sustain steady low molecular weight heparin consumption.
- Pharmacies:Retail dispensing captures limited heparin volume due to parenteral administration requirements.
Hospitals handle the majority of throughput; Home Healthcare is gaining share fastest as dialysis shifts toward peritoneal modalities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement power in Germany compresses API margins below those achievable in Brazilian import markets. Chinese manufacturers face divergent compliance costs across FDA pharmacopeial standards versus ANVISA harmonization pathways. Indian PLI incentives are redirecting fermentation capacity investments away from traditional supply concentrations.
China
Porcine intestinal mucosa supply chains in Shandong and Henan provinces dominate global unfractionated heparin sodium output. NMPA and SAMR dual carbon goals elevate environmental compliance costs for domestic API manufacturers. Shenzhen-based producers maintain captive pig intestine processing through backward integration into slaughterhouse partnerships.
United States
Tertiary care centers in Texas and California sustain unfractionated heparin consumption through cardiac catheterization protocols. FDA heparin monograph standards enforce stringent residual impurity limits on oversulfated chondroitin sulfate. Boston-area hospital networks mandate supply redundancy clauses in procurement contracts for critical anticoagulants.
Germany
University hospital networks in Bavaria and North Rhine-Westphalia concentrate anticoagulant procurement through centralized tendering platforms. EMA MDR frameworks govern heparin-coated stents and catheters as device-drug combinations. Frankfurt purchasing consortia are displacing traditional distributor relationships through aggregated volume mechanisms.
India
Domestic production-linked incentives under the PLI scheme attract recombinant heparin fermentation capacity investments. CDSCO regulatory pathways for complex glycosaminoglycan APIs are harmonizing with ICH standards. Maharashtra-based contract manufacturers are expanding aseptic fill-finish capacity for parenteral heparin formulations.
Brazil
Home dialysis anticoagulation creates new outpatient demand pools through portable heparin infusion systems. ANVISA regulatory harmonization with ICH standards opens import pathways for recombinant heparin APIs. São Paulo hospital networks represent the primary addressable market for imported synthetic heparin products.
Heparin API Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the heparin API supply base. Mammalian-derived extraction specialists compete against recombinant fermentation platforms on immunogenicity risk profiles and supply security dimensions. The market structure separates into three strategic archetypes: vertically integrated porcine processors, recombinant technology licensors, and hospital channel specialists. Dominant competitive moves include backward integration into captive raw material supply and geographic diversification of manufacturing footprints to satisfy procurement redundancy requirements.
Among Chinese manufacturers, Shenzhen Hepalink Pharmaceutical Co., Ltd. exemplifies the vertically integrated archetype through porcine supply chain control. Pfizer Inc. and Sanofi S.A. occupy positions as multinational formulation specialists with differentiated intellectual property depth. These three companies represent contrasting strategic postures: regional supply concentration versus global hospital channel access versus recombinant technology positioning.
| Leading Market Players |
|---|
| Shenzhen Hepalink Pharmaceutical Co., Ltd. |
| Pfizer Inc. |
| Sanofi S.A. |
| Fresenius Kabi AG |
| Changzhou Qianhong Bio-pharma Co., Ltd. |
| Hebei Changshan Biochemical Pharmaceutical Co., Ltd. |
| Bioiberica S.A.U. |
| Teva Pharmaceutical Industries Ltd. |
| Aspen Pharmacare Holdings Limited |
| Others |
Value Network & Pricing Analysis
FDA heparin monograph standards gate both supply qualification and price differentiation simultaneously, with residual impurity limits on oversulfated chondroitin sulfate separating certified suppliers from commodity-grade producers while hospital procurement consortia exploit this bifurcation to extract tiered pricing concessions.
Pricing Analysis
The customization-premium spread between recombinant bacterial fermentation output and conventional porcine-derived heparin spans multiple certification tiers, with FDA-grade material commanding substantial markups over Chinese GB-standard product. Price differentiation rests on molecular weight consistency and EMA MDR device-drug combination compliance, with German hospital purchasing consortia driving the most aggressive cost compression. Pricing pressure stems from direct oral anticoagulant substitution in outpatient thrombosis prophylaxis, forcing low molecular weight heparin suppliers toward volume-based contracting. Outpatient clinics exhibit highest price sensitivity; cardiac catheterization centers demonstrate lowest sensitivity due to protamine sulfate reversibility requirements.
Supply Chain Analysis
Porcine intestinal mucosa availability in Shandong and Henan provinces underwrites global unfractionated heparin sodium output, with Indian fermentation capacity emerging as a recombinant alternative. Raw material dependencies center on slaughterhouse partnerships, feed grain pricing, and African swine fever surveillance protocols. Single-source vulnerability concentrates in Chinese pig farming regions, where herd volatility transmits directly to API pricing. Distribution runs through hospital purchasing consortia in Germany and France, displacing traditional pharmaceutical distributor networks with centralized tendering platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a substitution defense against direct oral anticoagulant capture of outpatient venous thromboembolism prophylaxis, requiring incumbents to fortify irreversible clinical use cases while recombinant technologies decouple supply from livestock volatility.
For Market Incumbents: Compound defensive positioning by deepening captive pig intestine supply through slaughterhouse partnerships in Shandong province, while accelerating recombinant heparin lyase biocatalytic capacity to meet EMA impurity specifications. Prioritize dual-source manufacturing qualifications to satisfy German university hospital network procurement redundancy clauses. Direct oral anticoagulant substitution in stable outpatient populations represents the primary volume threat.
For New Entrants and Emerging Players: Anchor in Brazilian home dialysis anticoagulation through ANVISA-harmonized recombinant API import pathways, where portable infusion system demand outpaces established supplier coverage. Target peritoneal dialysis patient populations with subcutaneous formulation specialization, leveraging regulatory clarity from ICH-aligned CDSCO frameworks. Pursue white-label contract manufacturing for European hospital networks seeking supply diversification beyond Chinese porcine dependence.
For Investors and Strategic Acquirers: EMA MDR device-drug combination rule implementation reshapes the acquisition landscape by elevating documentation capabilities for heparin-coated stent suppliers. Long-term viability favors recombinant fermentation platforms over mammalian extraction specialists, given decoupling from African swine fever exposure. Monitor Indian PLI scheme fermentation capacity commitments as the signal indicating supply chain reconfiguration momentum.
| Strategic Initiative | Industry Significance |
|---|---|
| Recombinant Fermentation Scale-Up | Synthetic heparin production reduces immunogenicity risks and livestock supply dependence for API manufacturers. |
| Backward Integration into Porcine Processing | Captive slaughterhouse partnerships in Shandong province secure intestinal mucosa supply against African swine fever volatility. |
| EMA MDR Compliance Investment | Device-drug combination documentation capabilities open heparin-coated catheter and stent addressable markets. |
| Dual-Source Manufacturing Qualification | Supply redundancy clauses in German hospital procurement contracts require geographic production diversification. |
| Enzymatic Depolymerization Adoption | Recombinant heparin lyase biocatalytic routes accelerate regulatory filing timelines and reduce batch rejection rates. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across this study, with primary interviews capturing perspectives from hospital pharmacy committee members, anticoagulant procurement managers at German purchasing consortia, CDSCO regulatory affairs leads, and fermentation facility operations directors at Indian PLI scheme beneficiaries. Secondary validation drew from FDA heparin monograph filings, EMA MDR submission databases, ANVISA ICH harmonization protocols, and Chinese SAMR environmental compliance disclosures. Bottom-up volume estimates triangulated against top-down market sizing from customs trade data and hospital procurement database aggregation.
Across the analysis window, forecasts incorporated molecular weight category segmentation, regional regulatory cluster differentiation, and delivery mode formulation complexity. CAGRs were derived from patient volume projections across cardiac catheterization, orthopedic surgery, and dialysis modalities, cross-referenced with API throughput data from fermentation capacity announcements and porcine slaughter statistics. Pricing trajectories integrated tender outcome analysis from French university hospital networks and German centralized purchasing platforms.
Material uncertainties — African swine fever resurgence, EMA biosimilar heparin pathway finalization, and direct oral anticoagulant label expansion — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory stability and livestock supply continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biopharmaceuticals
Gosling Plague Vaccine Market
Biopharmaceuticals
Insulin Market
Biopharmaceuticals
Glucagon Injectable Market
Biopharmaceuticals
Vaccine Adjuvants Market
Biopharmaceuticals
Global Biopharma Buffer Market
Biopharmaceuticals
Biological Drugs Market
Biopharmaceuticals
Global Carboprost Tromethamine Market
Biopharmaceuticals
Somatropin Market
Biopharmaceuticals
Global Biopharmaceuticals Contract Manufacturing Market
Biopharmaceuticals
Global Recombinant Proteins Market
Biopharmaceuticals
Amphotericin B Market
Biopharmaceuticals
Global Blood Product Market
Biopharmaceuticals
Global Topical Antibiotics Market
Biopharmaceuticals
Glycosylated Peptide Market
Biopharmaceuticals
Global Pegylated Proteins Market
Biopharmaceuticals
Levofloxacin Cyclized Ester Market