
 Spelt Milk Market | 2026-2036
Spelt Milk Market Size, Share, and Industry Trends Forecast 2026-2036
Spelt Milk Market Analytics
A shortage of trained plant-based beverage technologists is unwinding production capacity expansion across European processing facilities. The Bridge S.R.L. leverages its Italian sourcing network to secure heritage spelt grain supply from Emilia-Romagna cooperatives. Natumi Organic anchors its portfolio with long-standing organic certification that commands shelf placement in German health food stores. Provamel competes through refrigerated distribution reach that extends into Benelux retail chains.
Spelt milk is an aqueous extraction of Triticum spelta grain, typically containing 3-4% protein and 2-3% fat, produced through enzymatic hydrolysis and ultra-high-temperature pasteurization to achieve shelf stability without dairy proteins. Its primary commercial purpose is serving lactose-intolerant consumers and clean-label buyers seeking alternatives to nut-allergen and soy-based beverages. Unsweetened formulations dominate volume as diabetic-conscious households reject added sugars, while chocolate variants capture the fastest growth among pediatric-oriented purchasers in food service channels. Carton packaging sustains margin pools through economies of scale in aseptic filling lines, though pouches are gaining traction in German on-the-go consumption segments.
EFSA organic labeling standards and EU REACH compliance for food contact materials shape formulation and packaging decisions across the value chain. Germany's BfR and France's DGCCRF enforce divergent maximum residue limits for mycotoxins in cereal-based beverages, creating asymmetric market access conditions. Stakeholders must monitor evolving national interpretations of the EU Green Deal's Farm to Fork targets for heritage grain incentives.
Market Dynamics
EU organic certification requirements under EFSA are tightening ingredient traceability standards, forcing spelt milk processors to reconfigure supplier verification systems and documentation protocols across their sourcing networks.
Growth Catalysts
- EFSA Organic Labeling Standards:Heritage grain positioning commands premium shelf placement in German health food retail chains, accelerating clean-label adoption among diabetic-conscious households.
- Enzymatic Hydrolysis Advancement:Ultra-high-temperature pasteurization technology achieves shelf stability without dairy proteins, expanding food service channel penetration for lactose-intolerant consumers.
- Emilia-Romagna Sourcing Concentration:Italian cooperatives supply heritage spelt grain with established organic pedigree, anchoring supply security for artisanal beverage manufacturers.
Market Restraints
- Mycotoxin Residue Asymmetry:Germany's BfR and France's DGCCRF enforce divergent maximum residue limits, fragmenting cross-border formulation standardization and compliance costs.
- Technologist Shortage:European processing facilities lack trained plant-based beverage specialists, unwinding planned capacity expansion timelines and automation upgrades.
- Oat Milk Substitution:Established oat milk brands capture shelf space and consumer familiarity in specialty coffee chains, compressing spelt milk trial conversion rates.
Strategic Opportunities
- Pouch Packaging Innovation:German on-the-go consumption segments adopt flexible pouch formats, creating differentiation from carton-dominant competitors in convenience retail.
- Farm to Fork Incentives:EU Green Deal heritage grain targets channel agricultural subsidies toward spelt cultivation expansion in French and Italian traditional growing regions.
- Chocolate Variant Pediatric Positioning:Food service channels target pediatric-oriented purchasers with flavored formulations, capturing growth in institutional catering and school nutrition programs.
Industry Challenges
- Plant-Based Beverage Technologist Gap:European universities and technical institutes lack specialized training programs in enzymatic extraction and aseptic filling line operation.
- REACH Compliance Timeline:Food contact material certification for novel packaging formats extends product launch cycles and ties up regulatory affairs capacity.
- Cooperative Supply Integration:Smallholder Emilia-Romagna grain networks require aggregation and quality standardization investments to meet industrial-scale procurement volumes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spelt Milk Market |
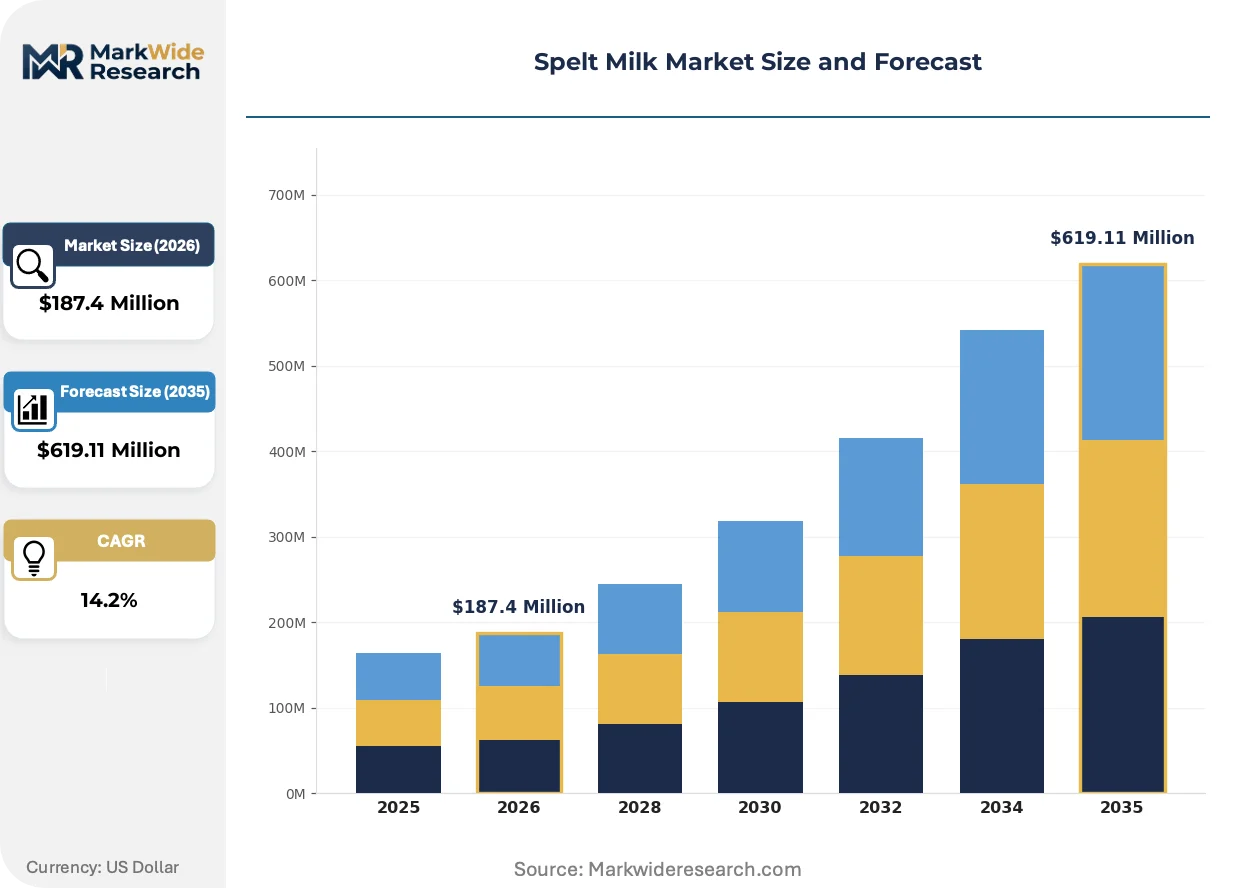
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Unsweetened, Sweetened, Chocolate, Vanilla End User: Households, Cafés, Restaurants, Food Manufacturers Packaging Type: Cartons, Bottles, Pouches, Tetra Packs Distribution Channel: Online, Supermarkets, Health Food Stores, Wholesale |
| Companies Covered | The Bridge S.R.L., Allos, Natumi Organic, Provamel, Ecomil, Isola Bio, Poggio Organic, BioSophia, Rude Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spelt Milk Market Evolving Landscape
Spelt milk processing is experiencing convergent pressures from enzymatic technology maturation, regulatory documentation intensification, and channel-specific packaging diversification. These forces are compressing traditional production timelines while opening differentiated positioning avenues.
Enzymatic hydrolysis systems are decomposing conventional extraction bottlenecks by enabling higher protein retention at lower thermal stress. German health food manufacturers are adopting these systems at accelerated replacement cycles. This technology is decomposing the historical trade-off between shelf stability and nutritional integrity that constrained clean-label formulation.
REACH compliance for food contact materials is reshaping packaging procurement decisions across the value chain. ECHA documentation requirements extend supplier qualification timelines and favor established polymer suppliers with existing substance dossiers. Aseptic carton filling lines face the most acute reformulation pressure as laminate barrier specifications tighten.
Specialty coffee chains in Germany are rotating procurement toward heritage grain alternatives as consumer education on ingredient provenance deepens. Oat and almond milk dominance in this channel is fragmenting as barista-grade spelt formulations demonstrate foam stability parity. French and Italian artisanal food manufacturers are accelerating this rotation through co-branded menu placement.
Spelt Milk Market Segmentation
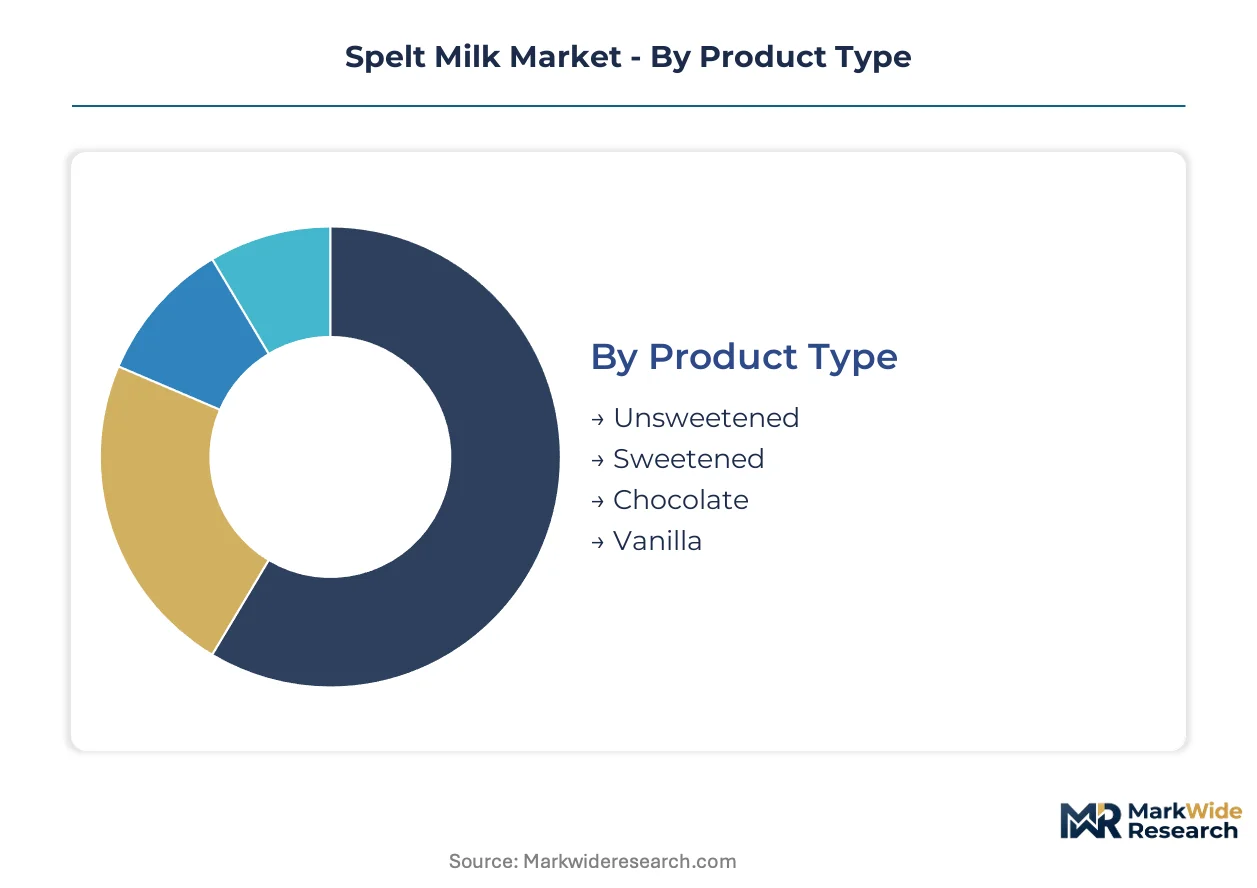
Spelt milk segmentation reveals divergent margin architectures across formulation complexity and channel access. Product type stratification separates commodity-adjacent volumes from premium positioning, while packaging and distribution choices determine working capital intensity and shelf-life economics.
Product Type:
Unsweetened formulations capture the deepest margin pools through diabetic-conscious household penetration and clean-label premiumization in German health food retail.
- Unsweetened:Contains 3-4% protein with zero added sugars, targeting diabetic-conscious households in France and Italy. German health food chains anchor volume through organic certification premiums.
- Sweetened:Added cane or agave syrup elevates palatability for mainstream conversion from dairy. French supermarkets drive trial through promotional placement alongside heritage grain messaging.
- Chocolate:Pediatric-oriented positioning in institutional catering and school nutrition programs. Food service channels in Germany are rotating procurement toward flavored variants for menu differentiation.
- Vanilla:Bakery and dessert applications favor this segment for recipe compatibility. Italian artisanal food manufacturers specify vanilla for clean-label dessert formulations.
The dominant share belongs to Unsweetened, while Chocolate is closing the gap fastest through food service channel expansion.
End User:
Channel concentration varies sharply by procurement scale, with institutional buyers commanding volume discounts and households absorbing premium shelf pricing.
- Households:Retail-packaged consumption concentrates in German diabetic-conscious segments. Unsweetened cartons dominate refrigerator stocking for daily cereal and coffee applications.
- Cafés:Specialty coffee chains in Germany are expanding spelt milk procurement as barista-grade foam stability achieves parity with oat alternatives. Heritage grain provenance commands menu premiumization.
- Restaurants:Fine dining establishments in France and Italy specify spelt for lactose-free course accommodations. Supply reliability constraints limit penetration versus established nut milks.
- Food Manufacturers:Industrial-scale procurement for bakery, confectionery, and ready-meal integration. Emilia-Romagna cooperatives supply heritage grain with established organic pedigree for this segment.
Households retain volume leadership, though Cafés are expanding most quickly through specialty coffee chain rotation toward heritage grain alternatives.
Packaging Type:
Capital equipment requirements and shelf-life engineering create tiered margin structures, with aseptic cartons sustaining economies of scale and pouches capturing convenience premiums.
- Cartons:Aseptic filling lines achieve shelf stability through ultra-high-temperature pasteurization without refrigeration. German supermarkets and health food stores anchor volume through economies of scale in laminate barrier packaging.
- Bottles:Refrigerated distribution requirements limit geographic reach. Benelux retail chains favor bottles for perceived freshness signaling in premium positioning.
- Pouches:Flexible formats gain traction in German on-the-go consumption segments. REACH compliance for food contact materials extends supplier qualification timelines for this emerging format.
- Tetra Packs:Established shelf-stable infrastructure supports export logistics from Italian processing facilities. EFSA organic labeling standards shape laminate specification for heritage grain positioning.
Cartons command installed base dominance, yet Pouches are gaining share fastest through convenience retail differentiation.
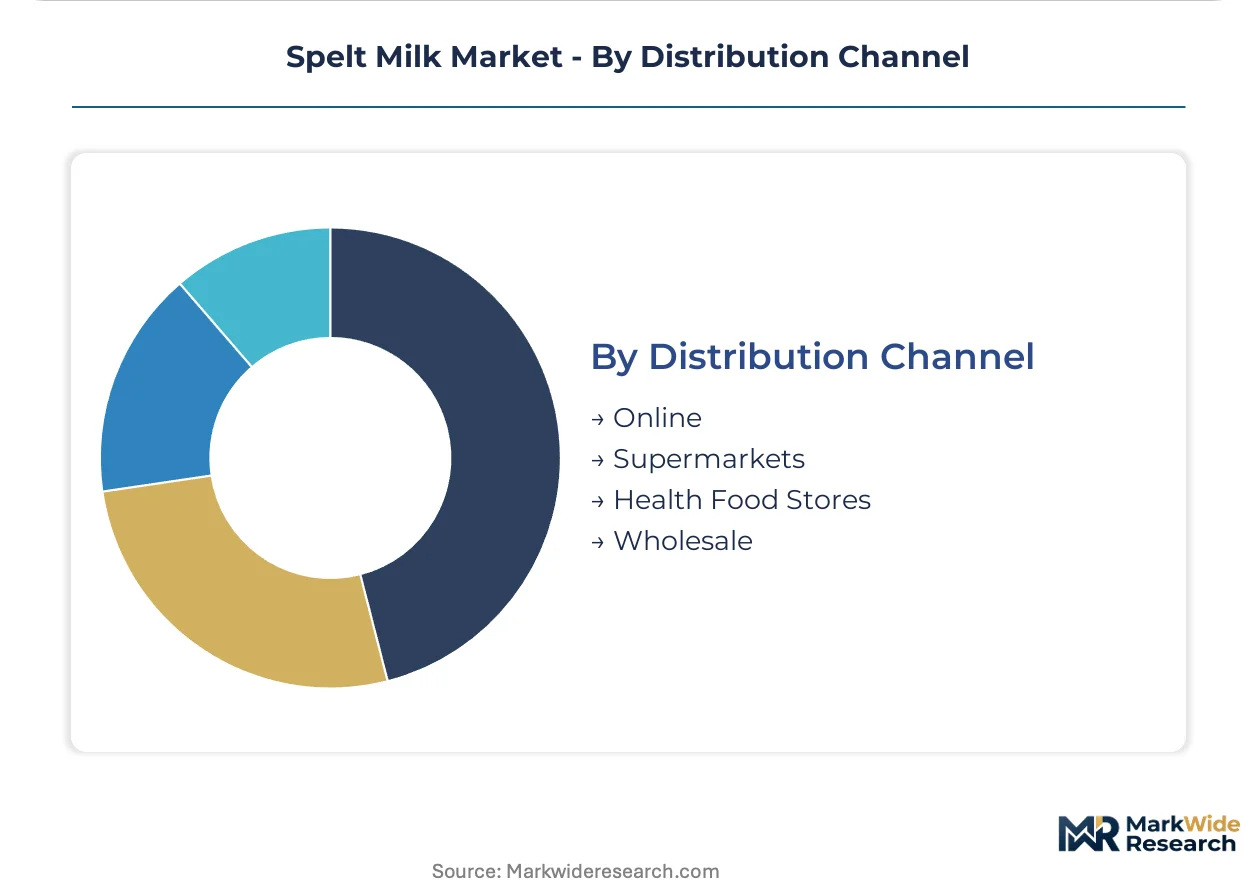
Distribution Channel:
Route-to-market economics fragment between high-touch specialty retail and scaled wholesale, with online emerging as a trial conversion mechanism.
- Online:Direct-to-consumer subscriptions build repeat purchase among German diabetic-conscious households. E-commerce logistics favor shelf-stable carton formats for shipping economics.
- Supermarkets:Mass retail placement in France and Italy requires promotional investment for shelf space against oat milk incumbents. Heritage grain storytelling supports premium price positioning.
- Health Food Stores:German health food retail chains anchor organic certification premiums. Natumi Organic and similar brands command placement through long-standing certification pedigree.
- Wholesale:Food service and institutional procurement concentrates volume for cafés and restaurants. Provamel extends refrigerated distribution reach into Benelux through this channel.
Health Food Stores retain the highest margin per liter, while Online is climbing the fastest through subscription model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German health food retail chains command 15-20% price premiums over Italian supermarket placements, while French organic certification requirements add compliance costs that compress margins versus Benelux counterparts.
Germany
Specialty coffee chains in Berlin and Hamburg are expanding spelt milk procurement as barista-grade foam stability achieves parity with oat alternatives. BfR mycotoxin residue limits enforce stricter quality thresholds than neighboring jurisdictions. Bavarian processing facilities concentrate enzymatic hydrolysis capacity for heritage grain formulations.
France
Artisanal food manufacturers in Île-de-France favor heritage grains for clean-label positioning in premium dairy alternatives. DGCCRF maximum residue limits for mycotoxins diverge from German standards, fragmenting cross-border formulation compliance. Provence-Alpes-Côte d'Azur hospitality clusters specify spelt for lactose-free fine dining accommodations.
Italy
Emilia-Romagna cooperatives supply heritage spelt grain with established organic pedigree to beverage manufacturers. EFSA organic labeling standards shape laminate specifications for export-oriented processing facilities. Lombardy-based industrial buyers aggregate procurement volumes from smallholder networks requiring quality standardization investments.
United Kingdom
Health-conscious households in London and Southeast England drive trial conversion through direct-to-consumer subscription models. REACH compliance for food contact materials extends supplier qualification timelines for novel packaging formats. Midlands-based distributors anchor refrigerated logistics networks extending into premium retail channels.
Netherlands
Benelux retail chains favor bottle formats for perceived freshness signaling in premium positioning against carton-dominant competitors. ECHA documentation requirements for polymer suppliers favor established players with existing substance dossiers. Randstad logistics clusters support cross-border distribution into German and French markets.
Spelt Milk Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the European spelt milk value chain. The vendor base concentrates among Italian heritage grain specialists, German organic certification incumbents, and Benelux refrigerated distribution networks. Three strategic archetypes dominate: cooperative-integrated processors with captive Emilia-Romagna supply, certification-anchored brands commanding health food retail placement, and scale-driven operators extending refrigerated reach across border markets. Competitive moves center on pouch packaging differentiation for German convenience segments and strategic partnerships with specialty coffee chains seeking menu premiumization.
Within the cooperative-integrated tier, The Bridge S.R.L. occupies a position exemplifying Italian heritage grain sourcing from Emilia-Romagna networks. Natumi Organic anchors the certification-driven archetype through long-standing organic pedigree that commands shelf placement in German health food retail. Provamel represents the scale-driven distribution model with refrigerated logistics extending into Benelux retail chains.
| Leading Market Players |
|---|
| The Bridge S.R.L. |
| Allos |
| Natumi Organic |
| Provamel |
| Ecomil |
| Isola Bio |
| Poggio Organic |
| BioSophia |
| Rude Health |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for heritage spelt grain concentrate pricing power among Emilia-Romagna cooperatives, while German health food retailers extract certification premiums that compress processor margins across the value chain.
Pricing Analysis
German health food chains command 15-20% shelf price premiums over Italian supermarket placements. Three-tier pricing structure across organic-certified premium, conventional standard, and private-label economy levels segments diabetic-conscious households from mainstream trial buyers. Cost compression in the conventional tier is intensifying because oat milk incumbents defend shelf space through promotional spending. Food manufacturers demonstrate least price sensitivity due to heritage grain provenance requirements, while household retail buyers absorb premiums for organic certification pedigree.
Supply Chain Analysis
Strategic stockpiling of heritage grain harvests prevails over just-in-time sourcing given annual cultivation cycles and mycotoxin quality variability. Supply concentrates in Italy, Germany, and France, with Emilia-Romagna cooperatives anchoring upstream grain procurement. Processing draws from enzymatic extraction equipment, aseptic filling lines, and laminate barrier packaging materials. Single-source vulnerability in trained plant-based beverage technologists threatens capacity expansion timelines. Distribution runs through refrigerated wholesale networks for food service penetration and shelf-stable retail channels for household stock-up purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
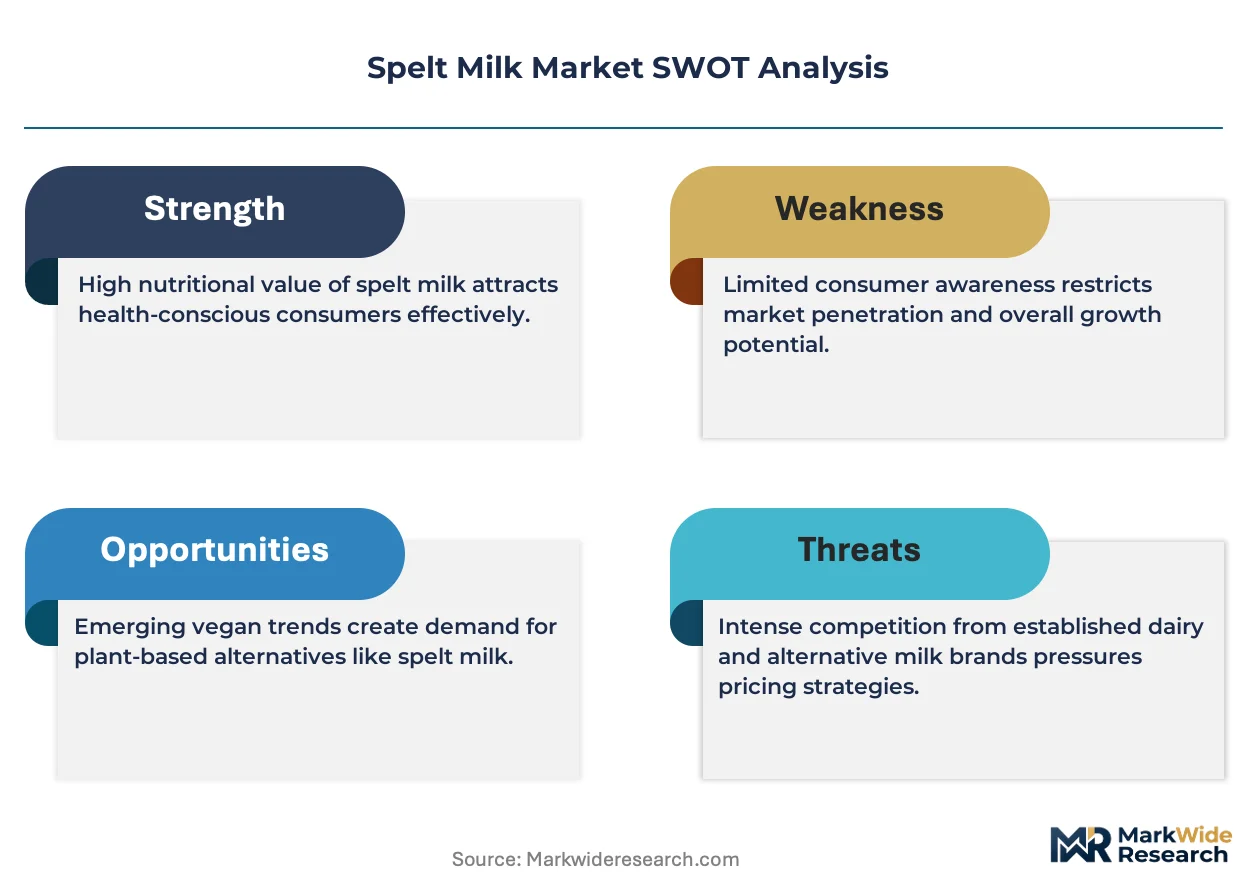
Spelt milk represents a high-growth disruption in European dairy alternatives, with EFSA organic certification tightening traceability standards that favor incumbent certification holders while creating compliance barriers for new entrants.
For Market Incumbents: Secure captive supply agreements with Emilia-Romagna cooperatives before Farm to Fork subsidies expand spelt cultivation competition. Invest in pouch packaging capacity for German convenience segments where carton-dominant competitors under-serve on-the-go demand. Oat milk substitution in specialty coffee chains threatens volume growth; defend through barista-grade foam stability R&D and co-branded menu placement with heritage grain storytelling.
For New Entrants and Emerging Players: Pediatric-oriented chocolate variant formulation presents a service-layer gap where incumbents under-serve institutional catering procurement. Target French and Italian artisanal food manufacturers seeking clean-label dessert ingredient integration. Enter through direct-to-consumer subscription models that build repeat purchase among diabetic-conscious households before attempting mass retail shelf placement against entrenched organic certification holders.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across aseptic filling line automation and REACH-compliant packaging development. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than brand equity alone. Acquisition target archetype: cooperative-integrated processors with captive heritage grain supply and existing EFSA organic pedigree. Signal to watch: BfR-DGCCRF mycotoxin standard harmonization negotiations as indicator of cross-border margin expansion potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Heritage Grain Supply Integration | Captive Emilia-Romagna cooperative agreements secure organic pedigree for EFSA compliance. |
| Pouch Packaging Capacity Addition | German on-the-go segments reward flexible format differentiation from carton incumbents. |
| Barista-Grade Formulation R&D | Foam stability parity with oat milk unlocks specialty coffee chain procurement rotation. |
| Chocolate Variant Line Extension | Pediatric-oriented positioning captures institutional catering and school nutrition program growth. |
| REACH Compliance Certification | ECHA documentation for novel packaging formats accelerates product launch timelines. |
Research Methodology
Operator-level perspectives from plant-based beverage technologists, health food retail category managers, Emilia-Romagna cooperative grain procurement leads, and EFSA regulatory affairs specialists anchored the qualitative base. Primary interview insights combined with secondary validation from EU organic certification databases, BfR mycotoxin monitoring reports, DGCCRF enforcement bulletins, and REACH substance dossier filings. Bottom-up volume modeling from processor capacity utilization and top-down demand triangulation from retail scanner data converged on segment-level estimates.
Sensitivity analysis tested forecast robustness across enzymatic hydrolysis adoption rates, Farm to Fork subsidy allocation scenarios, and mycotoxin standard harmonization outcomes over the projection horizon. Segmentation dimensions modeled include product type complexity, packaging format capital intensity, distribution channel route-to-market economics, and end-user procurement scale. CAGRs derived from installed base expansion curves and replacement cycle acceleration patterns in aseptic filling equipment. Industry-specific inputs encompassed heritage grain yield variability and organic certification audit pass-through timelines.
Underlying assumptions cover EFSA organic labeling standard continuity, Emilia-Romagna cooperative supply reliability, and specialty coffee chain procurement rotation velocity, with deviation risk concentrated in BfR-DGCCRF regulatory divergence and plant-based beverage technologist training pipeline constraints. Revision becomes warranted when oat milk incumbent promotional spending crosses thresholds that compress spelt milk trial conversion rates below sustainable processor margin floors.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dairy Alternatives
Australia Non-Dairy Milk Market
Dairy Alternatives
Organic Milk Replacers Market
Dairy Alternatives
Middle East and Africa Dairy Alternatives Market
Dairy Alternatives
Asia-Pacific Sour Milk Drinks Market
Dairy Alternatives
Cheese Analogue Market
Dairy Alternatives
Low-Calorie Cream Market
Dairy Alternatives
United States Oat Milk Market
Dairy Alternatives
Asia-Pacific Dairy Alternatives Market
Dairy Alternatives
Banana Milk Market
Dairy Alternatives
Non-Dairy Ice Cream Market
Dairy Alternatives
Chickpea Milk Market
Dairy Alternatives
Global Milk Replacers Market
Dairy Alternatives
Fat Free Yogurt Market
Dairy Alternatives
Flax Milk Market
Dairy Alternatives
Coconut Milk Powder Market
Dairy Alternatives
Asia-Pacific Walnut Milk Market