
 Asia Pacific Wheat Protein Market | 2026-2036
Asia Pacific Wheat Protein Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Wheat Protein Market Outlook
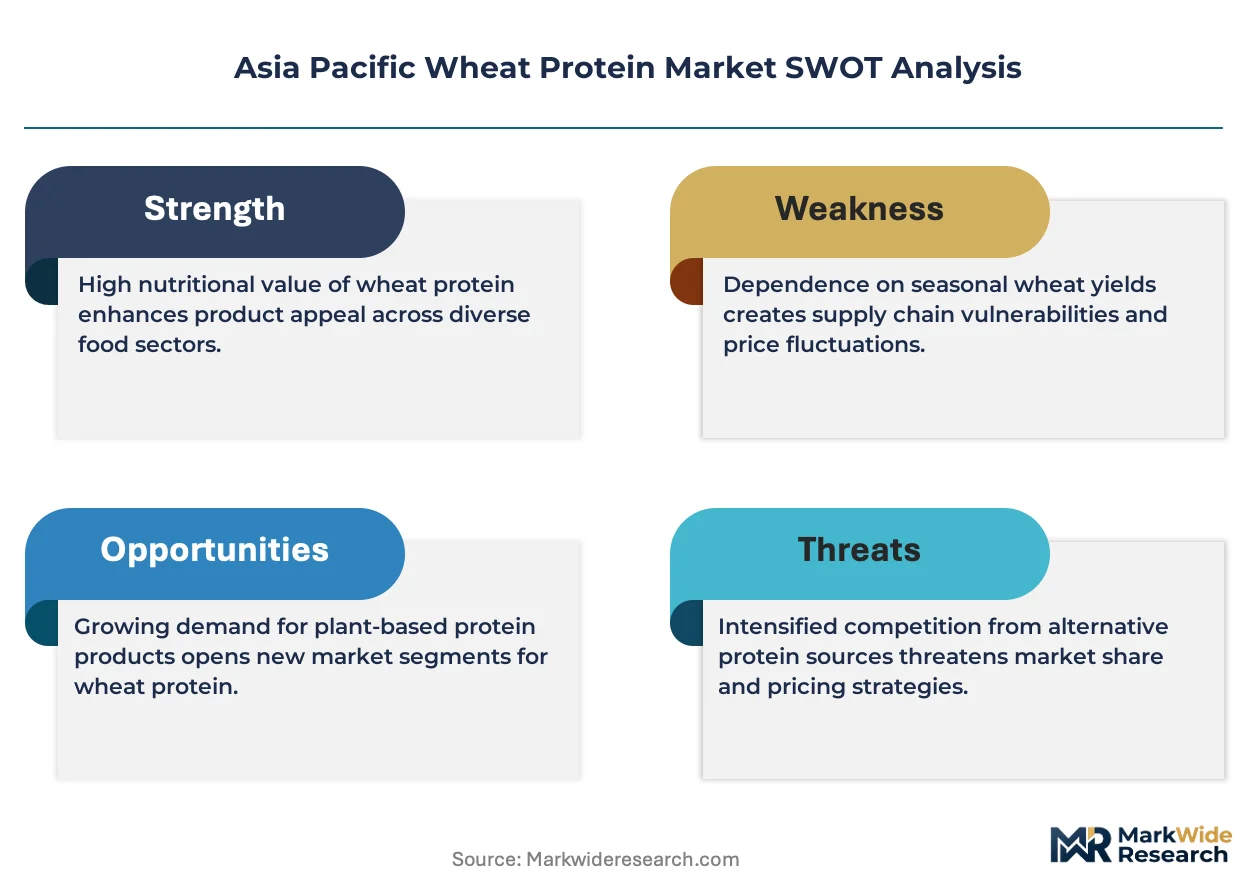
China's Shandong province is reshaping wheat protein supply dynamics through expanded wet-milling infrastructure and gluten extraction capacity. Cargill Incorporated leverages its coastal processing footprint to sustain bulk supply contracts with regional noodle and bakery chains. Shandong Qufeng Food Technology Co Ltd anchors domestic procurement networks, while Manildra Group competes on spray-dried isolate purity for premium meat-alternative formulations.
Asia Pacific wheat protein comprises glutenin and gliadin fractions extracted via aqueous washing of wheat flour dough, yielding viscoelastic concentrates with protein content ranging from 75% to 85% dry basis for food binding and texturization. Wheat gluten dominates volume flows into bakery applications where its film-forming properties secure dough structure in steamed breads across East Asian markets. Hydrolyzed wheat protein is gaining traction in personal care formulations as amino acid-derived humectants, while textured wheat protein occupies the fastest-expanding margin pool through extrusion technologies supplying plant-based meat analogues.
China's SAMR enforces GB standards on plant protein labeling and adulteration detection, while India's FSSAI mandates contaminant limits for wheat-derived ingredients entering packaged foods. Japan's METI oversees JIS-aligned specifications for functional proteins used in pharmaceutical and nutraceutical applications, creating compliance cost tiers that filter smaller traders. Stakeholders must monitor evolving allergen disclosure rules and carbon intensity benchmarks affecting import eligibility across the region's fragmented regulatory landscape.
Market Dynamics
China's dual carbon goals are compressing energy-intensive gluten extraction operations while India's FSSAI clean-label mandates force reformulation cycles across Southeast Asian bakery supply chains. These intersecting pressures are redrawing procurement geography and processing economics simultaneously.
Growth Catalysts
- Plant protein fortification mandates:China's GB standards for protein enrichment in processed foods are pulling wheat isolates into noodle and beverage applications. Domestic food conglomerates in Shandong and Jiangsu provinces are locking in multi-year supply contracts.
- Extrusion technology maturation:High-moisture extrusion systems are enabling meat-analogue processors to achieve fibrous textures previously requiring soy or pea protein bases. Equipment upgrades across East Asian contract manufacturers are expanding addressable formulation space.
- Halal certification expansion:Malaysia's JAKIM and Indonesia's BPJPH accreditation pathways are opening wheat gluten flows into Southeast Asian Muslim-majority markets previously served by animal-derived binders.
Market Restraints
- Wheat price volatility:Black Sea supply disruptions and Australian drought cycles are transmitting directly to gluten extraction margins. Processors lack hedging depth for feedstock exposure.
- Shandong supply concentration:Over half of regional wet-milling capacity clusters within 200 kilometers of Qingdao port infrastructure. Weather or logistics shocks at this node cascade through bakery and meat-alternative supply chains.
- Functional limitations in high-acid applications:Wheat protein's pH sensitivity restricts deployment in citrus-flavored beverages and acidified dairy alternatives. Formulators default to pectin or modified starch systems.
Strategic Opportunities
- Vietnam and Philippines bakery modernization:Industrial loaf production is displacing artisanal output in Ho Chi Minh City and Manila metro areas. Western-style bread penetration creates binding-agent demand without established local gluten supply.
- Personal care amino acid derivatives:Hydrolyzed wheat protein fractions are penetrating K-beauty and J-beauty humectant formulations. Cosmetic ingredient distributors in Seoul and Osaka are building dedicated plant-protein procurement desks.
- Japan's METI bioplastics incentives:Wheat gluten's film-forming properties align with biodegradable packaging development programs. Material science consortia in Kansai region are testing gluten-based barrier coatings.
Industry Challenges
- Allergen labeling complexity:Australia's FSANZ, Japan's Consumer Affairs Agency, and China's SAMR maintain divergent wheat allergen threshold definitions. Multi-market product registrations require parallel testing protocols.
- Skilled extrusion engineering shortage:High-moisture textured protein production demands operators capable of screw-profile optimization and die-design troubleshooting. Technical training pipelines lag equipment installation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Wheat Protein Market |
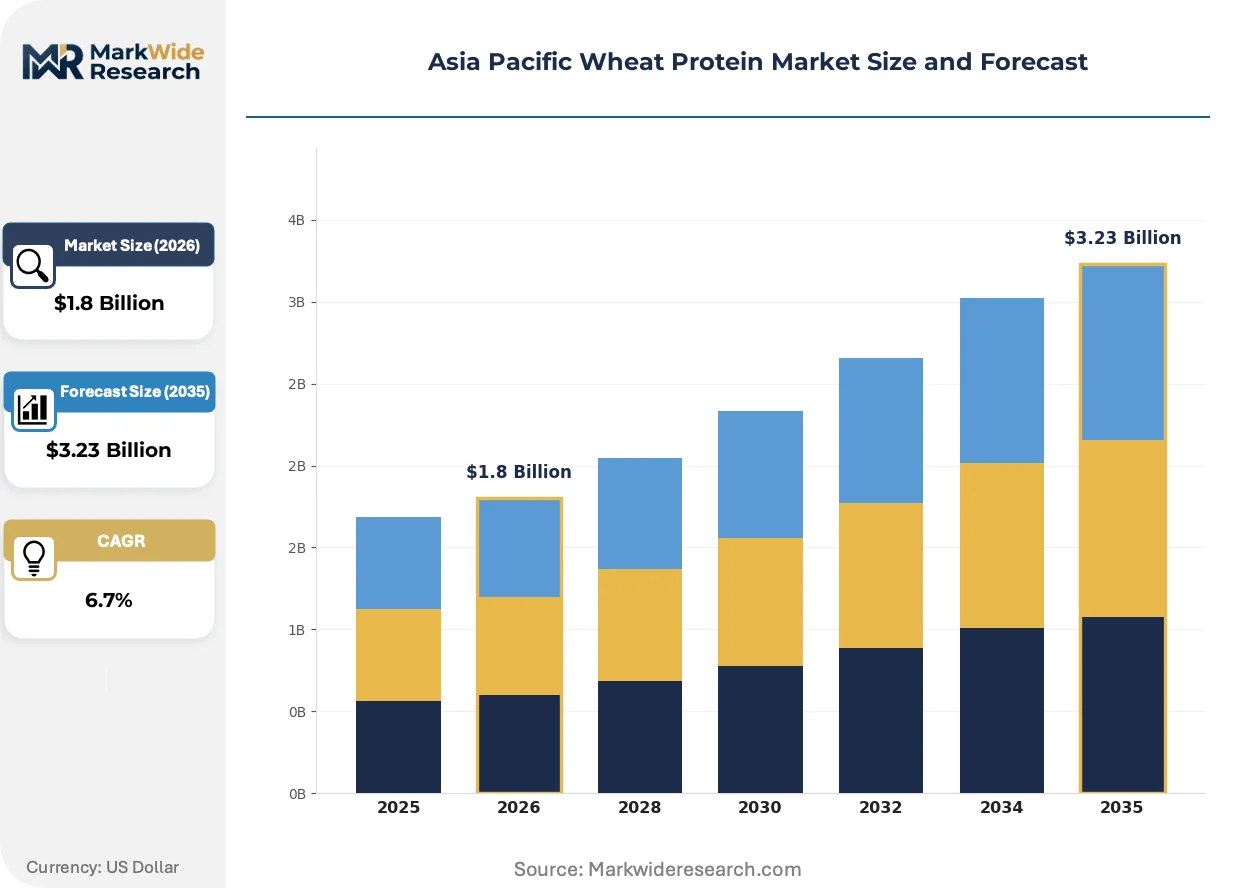
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textured Wheat Protein, Hydrolyzed Wheat Protein, Wheat Gluten, Wheat Protein Isolate Application: Bakery Products, Meat Alternatives, Nutritional Supplements, Beverages End User: Food Industry, Personal Care, Pharmaceutical, Animal Feed Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | The Archer-Daniels-Midland Company, Cargill Incorporated, Roquette Frères, MGP Ingredients Inc, Shandong Qufeng Food Technology Co Ltd, Manildra Group, Tereos, Anhui Ruifuxiang, Glico Nutrition Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Wheat Protein Market Strategic Shifts
Processing economics and regulatory stringency are jointly accelerating substitution of conventional gluten extraction with precision fermentation and enzyme-modified fractions. These shifts are compressing legacy capacity utilization while opening premium formulation tiers.
Enzymatic deamidation is collapsing the functional gap between wheat gluten and more expensive animal proteins in emulsification applications. Japanese sauce and dressing manufacturers are adopting these modified fractions for clean-label reformulations. The technology is collapsing premium pricing tiers that previously separated plant and animal-derived binders.
China's SAMR is tightening GB standards for plant protein adulteration detection and origin labeling. Laboratory testing costs are rising for importers sourcing from non-aligned jurisdictions. Australian and Canadian wheat protein exporters are investing in isotope-ratio verification capabilities to maintain market access.
Direct procurement relationships between bakery chains and gluten processors are displacing traditional ingredient distributor networks in Southeast Asia. Regional quick-service restaurant operators in Bangkok and Jakarta are establishing technical collaboration agreements with Shandong-based extractors. This channel compression is most visible where volume concentration permits dedicated supply chain engineering.
Asia Pacific Wheat Protein Market Segmentation
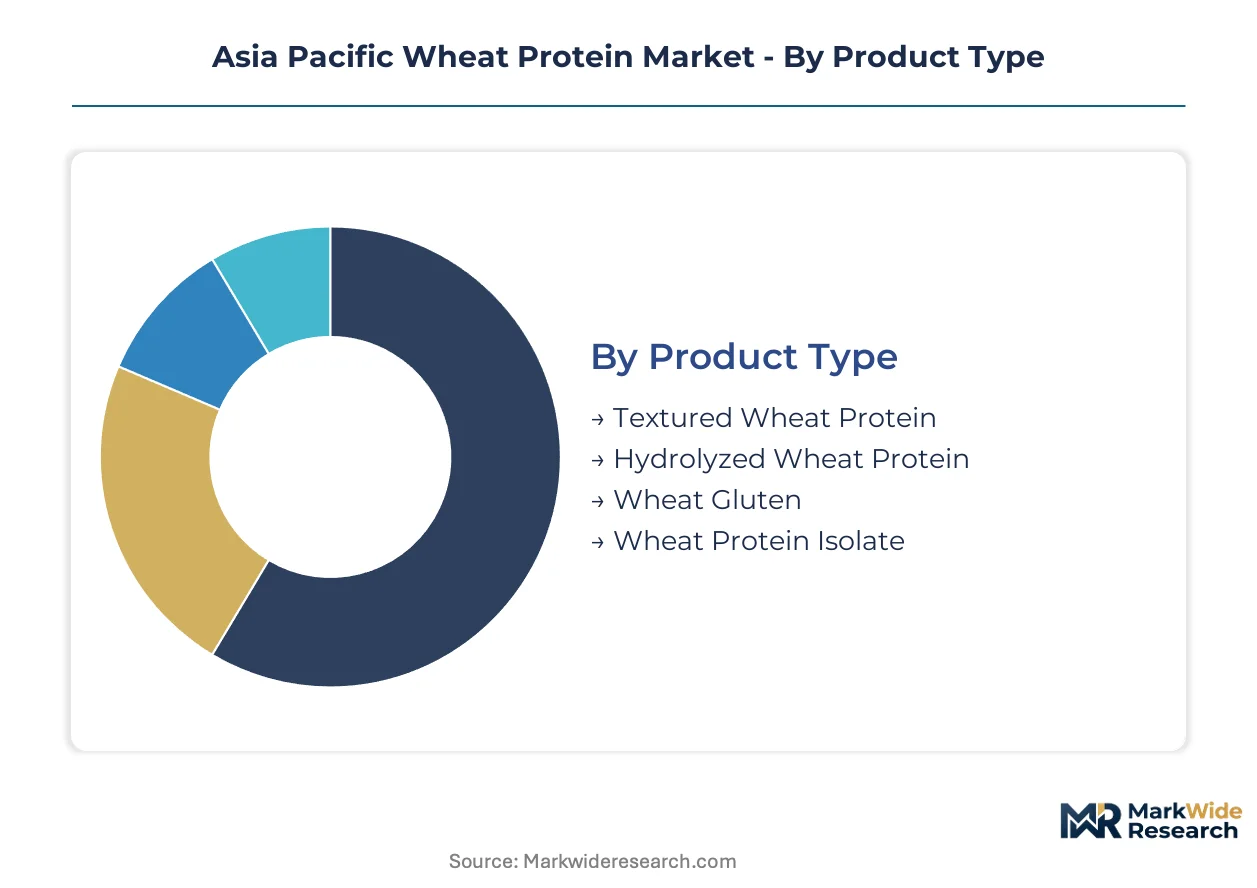
Wheat protein segmentation in Asia Pacific reflects divergent processing economics across extraction methods and end-use specifications. Product categories command distinct margin pools based on purity thresholds, while application segments split between commodity bakery volumes and premium meat-alternative formulations.
Product Type:
Cost tiers separate commodity gluten extraction from precision-fractionated isolates and modified derivatives. Each tier carries different capital intensity and regulatory compliance burdens.
- Wheat Gluten:Viscoelastic concentrates containing 75-85% protein dry basis extracted via aqueous washing of wheat flour dough. Demand concentrates in China's Shandong province noodle and steamed bread manufacturers where film-forming properties secure dough structure under SAMR GB standards.
- Wheat Protein Isolate:Higher-purity fractions exceeding 90% protein content achieved through additional centrifugation and membrane filtration steps. Premium meat-alternative processors in Japan's Kansai region specify isolate purity for extruded fibrous textures competing with soy and pea bases.
- Textured Wheat Protein:Extruded restructured forms created through thermomechanical processing of vital wheat gluten. Food industry purchasers in Vietnam and Philippines bakery modernization programs source textured grades for industrial loaf production.
- Hydrolyzed Wheat Protein:Enzymatically cleaved peptide fractions with reduced molecular weight for enhanced solubility. Personal care formulators in Seoul and Osaka deploy hydrolyzed grades as amino acid-derived humectants in K-beauty and J-beauty applications.
Wheat gluten holds installed capacity. Wheat protein isolate is rotating up the share rankings.
Application:
Volume distribution tracks protein functionality requirements against end-use processing conditions. pH tolerance and thermal stability filter segment suitability.
- Bakery Products:Dominant consumption channel leveraging gluten's unique viscoelasticity for gas retention and crumb structure. Malaysia's JAKIM and Indonesia's BPJPH halal certification expansion is redirecting bakery chain procurement from animal-derived binders toward certified wheat gluten supplies.
- Meat Alternatives:Fastest-expanding application segment driven by high-moisture extrusion technology maturation. East Asian contract manufacturers achieve fibrous textures previously requiring soy or pea protein bases, opening formulation space for wheat-derived texturates.
- Nutritional Supplements:Protein fortification powders and bars targeting fitness and senior nutrition demographics. India's FSSAI clean-label mandates are forcing reformulation cycles that favor wheat-derived isolates over synthetic amino acid blends.
- Beverages:Limited deployment due to wheat protein's pH sensitivity restricting use in acidified applications. Formulators default to pectin or modified starch systems for citrus-flavored and dairy-alternative beverages.
Bakery products anchor volume offtake. Meat alternatives are climbing the fastest among application segments.
End User:
Customer type determines specification stringency, with pharmaceutical and personal care segments imposing purity thresholds that filter commodity suppliers.
- Food Industry:Largest end-user category spanning bakery, processed meat, and meat-alternative manufacturers. Direct procurement relationships between Bangkok and Jakarta quick-service restaurant operators and Shandong-based extractors are displacing traditional distributor networks.
- Personal Care:Cosmetic ingredient distributors in Seoul and Osaka are building dedicated plant-protein procurement desks for hydrolyzed wheat protein fractions. K-beauty and J-beauty humectant formulations drive specification for low-molecular-weight peptide content.
- Pharmaceutical:Japan's METI oversees JIS-aligned specifications for functional proteins used in pharmaceutical applications, creating compliance cost tiers that filter smaller traders from this end-user segment.
- Animal Feed:Residual protein fractions from gluten extraction diverted to aquaculture and livestock nutrition applications. Price-sensitive procurement with lower protein purity requirements compared to food-grade specifications.
Food industry commands procurement scale. Personal care is gaining share fastest among end-user categories.
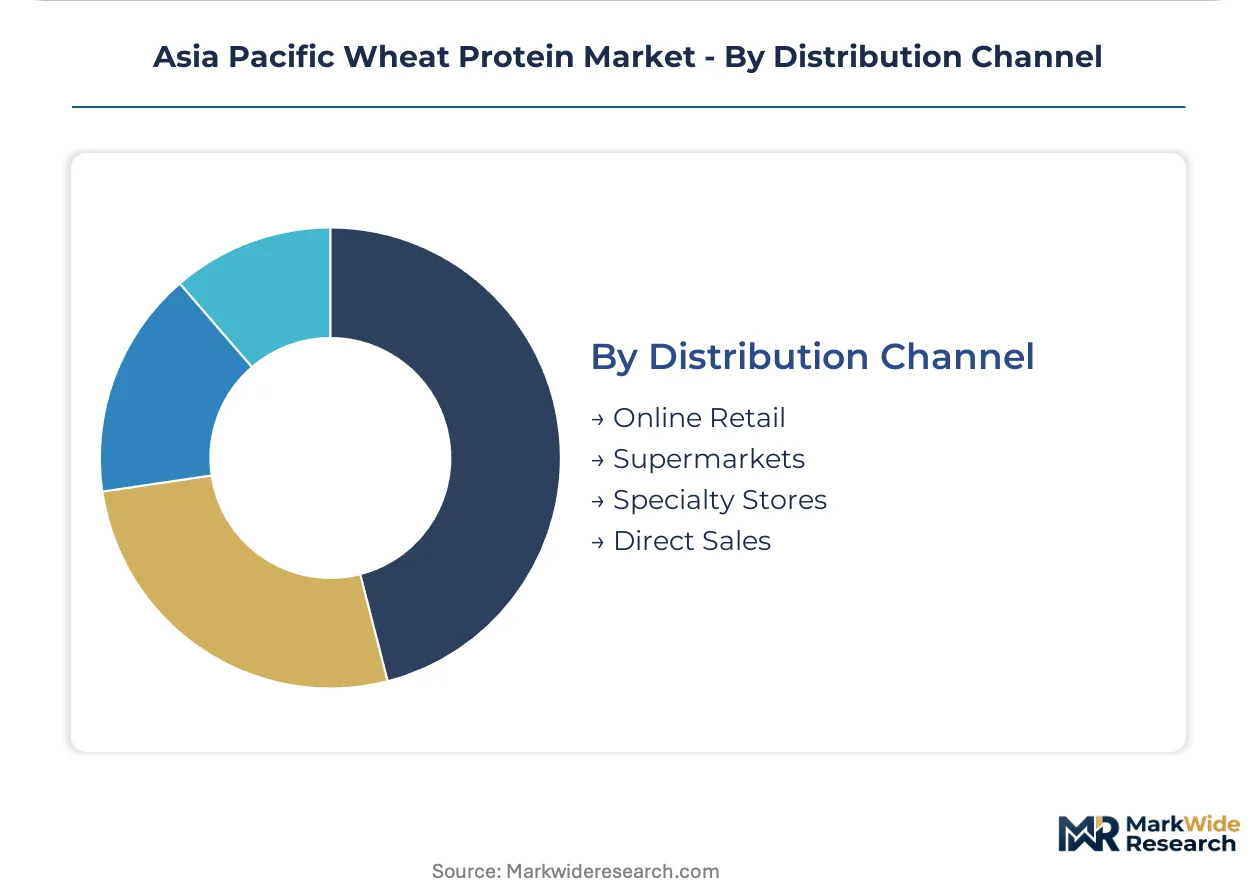
Distribution Channel:
Channel selection reflects order scale, technical service requirements, and geographic concentration of processing capacity.
- Direct Sales:Dominant channel for volume bakery and meat-alternative manufacturers. Technical collaboration agreements between regional processors and Shandong-based extractors enable dedicated supply chain engineering and quality alignment.
- Specialty Stores:Ingredient distributors serving mid-scale food manufacturers and nutraceutical compounders. Technical support for halal certification documentation and allergen testing protocols differentiates specialty channel value.
- Supermarkets:Limited wheat protein presence in retail-packaged formats for home baking enthusiasts. Consumer education gaps restrict penetration compared to established baking ingredient categories.
- Online Retail:Emerging channel for hydrolyzed wheat protein in personal care DIY formulations and small-scale nutraceutical blending. Seoul and Osaka cosmetic ingredient distributors test direct-to-formulator digital platforms.
Direct sales holds volume concentration. Specialty stores are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qingdao port infrastructure underwrites Shandong province's dominance in wheat protein extraction, with coastal wet-milling clusters feeding noodle and bakery supply chains across East Asia. This logistical anchor shapes procurement geography for the broader region.
China
Shandong and Jiangsu provinces concentrate over half of regional wet-milling capacity within 200 kilometers of Qingdao port. SAMR enforces GB standards on plant protein labeling and adulteration detection. Domestic ingredient processors in these provinces supply regional food conglomerates through multi-year supply contracts.
Japan
Kansai region meat-alternative processors specify wheat protein isolate purity for extruded fibrous textures competing with soy bases. METI oversees JIS-aligned specifications for functional proteins in pharmaceutical applications. Osaka cosmetic ingredient distributors are building dedicated plant-protein procurement desks for hydrolyzed fractions.
India
FSSAI clean-label mandates are forcing reformulation cycles across packaged food manufacturers. Wheat-derived isolates displace synthetic amino acid blends in protein fortification powders. Maharashtra and Gujarat house the primary bakery and nutraceutical processing clusters affected by these regulatory shifts.
Vietnam
Ho Chi Minh City metro areas are displacing artisanal bakery output with industrial loaf production. Western-style bread penetration creates binding-agent demand without established local gluten supply. Importers are establishing direct procurement relationships with Shandong-based extractors to secure volume.
Australia
Wheat protein exporters are investing in isotope-ratio verification capabilities to maintain China market access under tightening GB standards. Australian drought cycles transmit directly to gluten extraction margins for processors. Victorian and New South Wales grain belts supply the feedstock for these export-oriented operations.
Asia Pacific Wheat Protein Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream with narrower functional scope. The vendor base spans multinational agribusiness conglomerates, regional wet-milling operators, and precision-fractionation specialists. Three archetypes dominate: coastal infrastructure-leveraged bulk suppliers, purity-focused isolate processors, and extrusion-technology-integrated texturate manufacturers. Capacity expansion and direct procurement relationship-building represent the dominant competitive moves reshaping channel structures.
Among Asia-Pacific-based operators, Shandong Qufeng Food Technology Co Ltd and Anhui Ruifuxiang occupy positions within the domestic procurement network tier, while Cargill Incorporated represents the multinational infrastructure-leveraged archetype with coastal processing footprints. These entities exemplify the divergence between regional volume players and global supply chain integrators competing for bakery and meat-alternative formulation contracts.
| Leading Market Players |
|---|
| The Archer-Daniels-Midland Company |
| Cargill Incorporated |
| Roquette Frères |
| MGP Ingredients Inc |
| Shandong Qufeng Food Technology Co Ltd |
| Manildra Group |
| Tereos |
| Anhui Ruifuxiang |
| Glico Nutrition Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Shandong province's wet-milling cluster concentration anchors margin capture for wheat gluten extractors serving East Asian bakery chains. Black Sea feedstock volatility transmits directly to Qingdao port pricing, compressing extraction margins while isolate premiums in Japan's Kansai region widen.
Pricing Analysis
China's SAMR GB standards dictate the pricing tier structure across wheat protein grades. Three-tier pricing separates pharmaceutical-grade isolates under METI JIS specifications from food-grade gluten and feed-tier residuals. Price differentiation rests on certification stringency and volume scale, with halal-accredited gluten commanding premiums in Jakarta and Kuala Lumpur. Cost compression in commodity gluten is intensifying because Australian drought cycles restrict feedstock availability. Small-scale Vietnamese bakery importers exhibit highest price sensitivity; Japanese meat-alternative processors show lowest.
Supply Chain Analysis
Australian and Canadian wheat harvests feed Shandong's wet-milling infrastructure through Qingdao port intake. Wheat grain, process chemicals, and membrane filtration equipment constitute the critical input stack. Single-source vulnerability concentrates at the Qingdao logistics node where weather disruptions cascade through regional supply. Distribution runs through direct technical collaboration agreements between Shandong extractors and Bangkok quick-service restaurant operators, displacing traditional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions creates niche opportunities for specification-tailored suppliers. India's FSSAI clean-label mandates and China's SAMR adulteration detection rules force parallel compliance investments that filter commodity players.
For Market Incumbents: Entrench through backward integration into Australian grain origination and captive halal certification capacity for Southeast Asian Muslim-majority markets. Cargill's coastal infrastructure leverage and Shandong Qufeng's domestic procurement networks exemplify defensive positioning against precision-fermentation substitutes. Capacity addition in Jiangsu province secures proximity to noodle and steamed bread manufacturers under tightening GB standards. For New Entrants and Emerging Players: Establish a beachhead in Vietnam's industrial bakery modernization wave where Western-style bread penetration outruns local gluten supply development. The Philippines' Manila metro area presents comparable white-space conditions. Target personal care amino acid derivatives through Seoul and Osaka cosmetic ingredient distributors building dedicated plant-protein procurement desks. Technical service partnerships with high-moisture extrusion equipment vendors accelerate meat-alternative formulation access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional wet-milling operators in Shandong and Jiangsu provinces seeking exit liquidity against capital-intensive compliance upgrades. Five-to-ten year viability hinges on isolate purity capabilities and direct procurement relationship depth. Watch for METI bioplastics program funding decisions as signal for wheat gluten film-forming property demand inflection in Kansai region packaging applications.| Strategic Initiative | Industry Significance |
|---|---|
| Halal Certification Expansion | JAKIM and BPJPH accreditation unlocks Southeast Asian Muslim-majority bakery and processed meat markets. |
| High-Moisture Extrusion Capacity Buildout | Equipment upgrades across East Asian contract manufacturers expand addressable meat-analogue formulation space. |
| Isotope-Ratio Verification Investment | Australian exporters deploy traceability capabilities to maintain China market access under tightening SAMR origin labeling rules. |
| Direct Procurement Relationship Formation | Technical collaboration agreements between Shandong extractors and Bangkok quick-service operators compress distributor margins. |
| Enzymatic Deamidation Technology Adoption | Japanese sauce manufacturers adopt modified fractions to collapse premium pricing tiers separating plant and animal-derived binders. |
Study Parameters
A spread of perspectives from wheat gluten extraction plant managers, bakery procurement leads at regional food conglomerates, halal certification auditors, and personal care formulators in Seoul converged on the working assumptions. Secondary validation drew from SAMR GB standard filings, FSSAI contaminant limit notifications, JIS specification documents, and Australian Bureau of Agricultural and Resource Economics trade data. Bottom-up capacity assessments and top-down demand modeling triangulated volume estimates.
Demand-supply-balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product purity tier, application functionality requirements, end-user specification stringency, and regional regulatory cluster alignment. CAGRs were synthesized from installation capacity trajectories, contract visibility windows, and substitution elasticity parameters. Wheat price volatility bands and extrusion technology diffusion curves served as industry-specific forecast inputs.
Stress conditions across Black Sea supply disruptions, Australian drought frequency, and SAMR enforcement intensity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory stability and technology adoption rates. Substitution risk from precision fermentation and pea protein extrusion advances could materially revise trajectory. Cross-checking against Australian Bureau of Statistics grain export data and Japanese Ministry of Agriculture food manufacturing surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Grains
Mexico Rice Market
Grains
Organic Cereals Market
Grains
Millet Flour Market
Grains
North America Wheat Market
Grains
Oat Bran Market
Grains
Asia Pacific Maize Market
Grains
Tunisia Grain Market
Grains
Low Fat Rice Market
Grains
North America Oats Market
Grains
Ghana Grain Market
Grains
Basmati Rice Market
Grains
North America Wheat Flour Market
Grains
IQF Rice Market
Grains
Bangladesh Rice Market
Grains
Global Rice Market
Grains
Grain Augers Market