
 Postal Tubes Market | 2026-2036
Postal Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Postal Tubes Market Analytics
North American containerboard producers is rebalancing capacity toward lighter basis weights suitable for postal tube conversion. Sonoco Products Company leverages its integrated recycled paperboard mills to sustain cost-advantaged supply across the Midwest manufacturing corridor. Mondi anchors European production through kraftliner operations in Poland and Slovakia. International Paper competes on scale, operating fourteen containerboard facilities that feed independent tube converters throughout the southeastern United States.
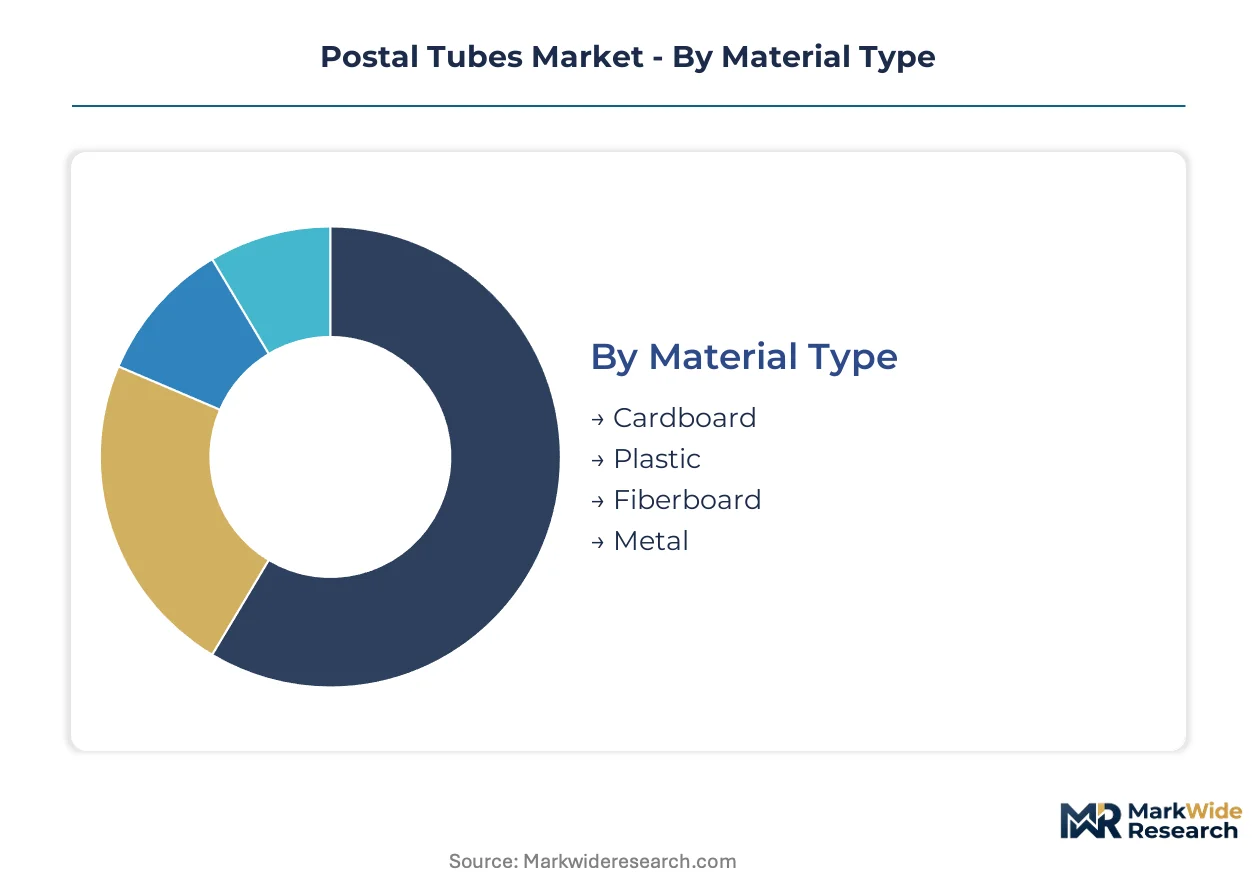
Postal tubes are cylindrical shipping containers manufactured from spirally wound paperboard layers, typically ranging from 0.5 to 8 inches in diameter with wall calipers between 0.06 and 0.25 inches, engineered to protect rolled documents, posters, and textiles during transit. Cardboard grades dominate unit volume due to favorable stiffness-to-weight ratios and established recovery infrastructure, while plastic variants capture premium applications requiring moisture barrier performance across the closure type dimension where snap lock mechanisms reduce per-unit labor in high-throughput fulfillment environments. The end user segment shows structural divergence: retailers drive standardized large-format demand, whereas artists and architects generate fragmented small-batch orders with higher margin profiles.
The United States Environmental Protection Agency maintains recycled content guidelines for federal procurement that directly shape tube converter material sourcing decisions, while the EU Packaging and Packaging Waste Regulation imposes extended producer responsibility fees modulated by recyclability scores. The Forest Stewardship Council chain-of-custody certification operates as a de facto market access requirement for tubes entering corporate supply chains across both jurisdictions. Stakeholders must monitor evolving state-level plastic restriction statutes in California and New York that could accelerate fiberboard substitution in protective packaging applications.
Market Dynamics
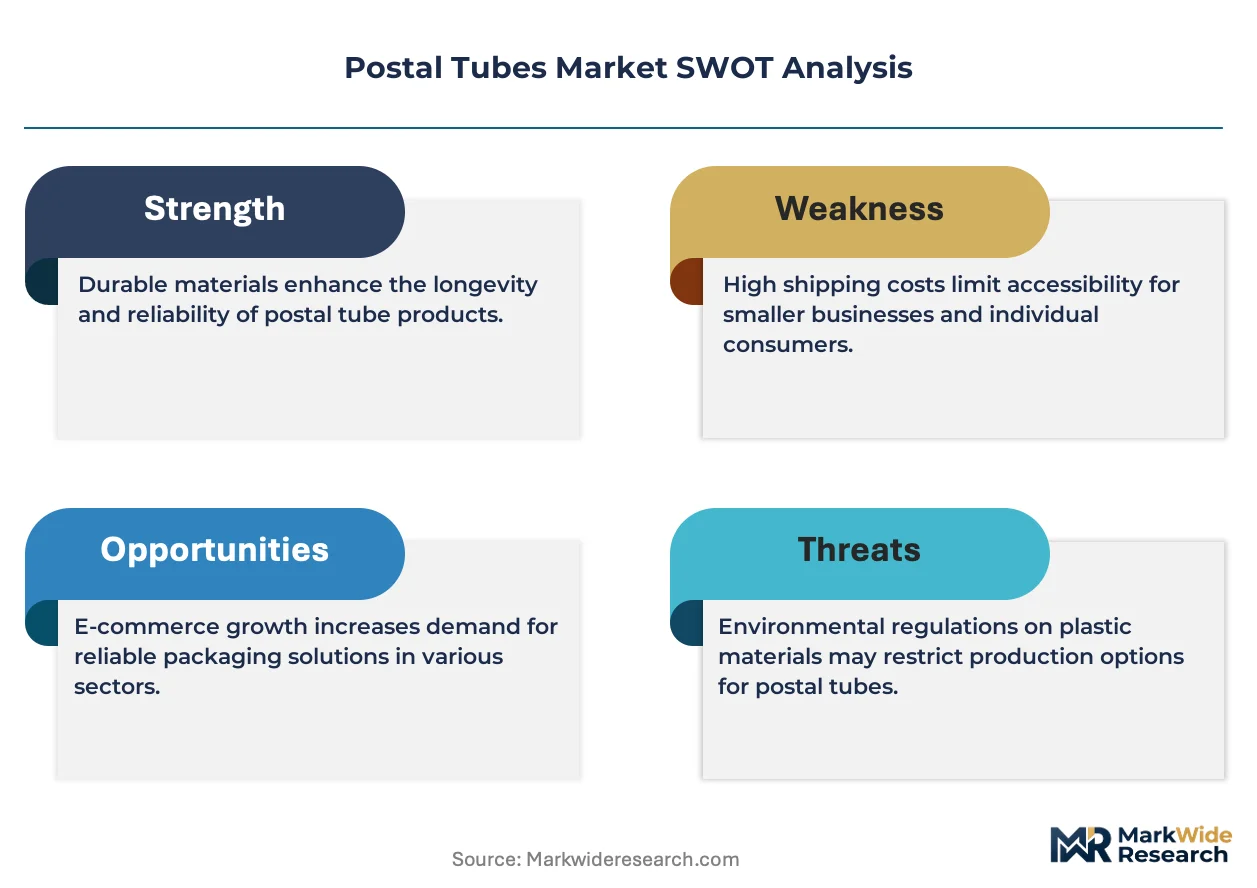
The EU Packaging and Packaging Waste Regulation mandates recycled fiber thresholds that force tube converters to requalify material grades across their supplier base, compressing lead times and squeezing margin structures for mid-sized producers.
Growth Catalysts
- E-commerce fulfillment velocity:Online art supply retailers in Germany and the United Kingdom generate sustained volume pull for medium-diameter fiberboard tubes as centralized distribution hubs expand SKU throughput.
- REACH-compliant material substitution:Extended producer responsibility fees modulated by recyclability scores accelerate post-consumer cardboard adoption over plastic variants in protective packaging applications.
- Lightweighting imperatives:North American containerboard producers rebalance capacity toward lighter basis weights that reduce per-unit shipping costs for postal tube converters serving direct-to-consumer channels.
Market Restraints
- OCC price volatility:Old corrugated container feedstock costs fluctuate with municipal collection program yields, exposing tube converters to margin compression when recovery rates dip below seasonal baselines.
- Midwest mill concentration:Integrated recycled paperboard operations cluster along the Ohio River valley, creating geographic supply risk for converters outside the manufacturing corridor.
- Moisture barrier limitations:Fiberboard tubes lack the vapor transmission resistance of polyethylene alternatives, excluding them from pharmaceutical document shipping where climatic stability is mandatory.
Strategic Opportunities
- Polish kraftliner expansion:Mondi's integrated operations in Central Europe offer tariff-advantaged supply access for converters targeting Nordic e-commerce fulfillment networks.
- FSC chain-of-custody certification:Corporate procurement policies increasingly require verified sustainable sourcing, creating a de facto market access gate that certified converters can monetize through premium positioning.
- Snap-lock closure automation:High-throughput fulfillment centers demand reduced per-unit labor, driving specification shifts toward integrated locking mechanisms that eliminate tape sealing steps.
Industry Challenges
- Spiral-winding technician scarcity:Skilled operators capable of calibrating multi-layer paperboard tension controls are retiring faster than vocational programs replenish the talent pool.
- California plastic restriction compliance:State-level statutes targeting single-use packaging create fragmented regulatory patchwork that national distributors must navigate through SKU proliferation.
- Extended producer responsibility fee administration:Modulated cost structures require real-time tracking of material recyclability scores across supplier tiers, strapping finance teams with reconciliation complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Postal Tubes Market |
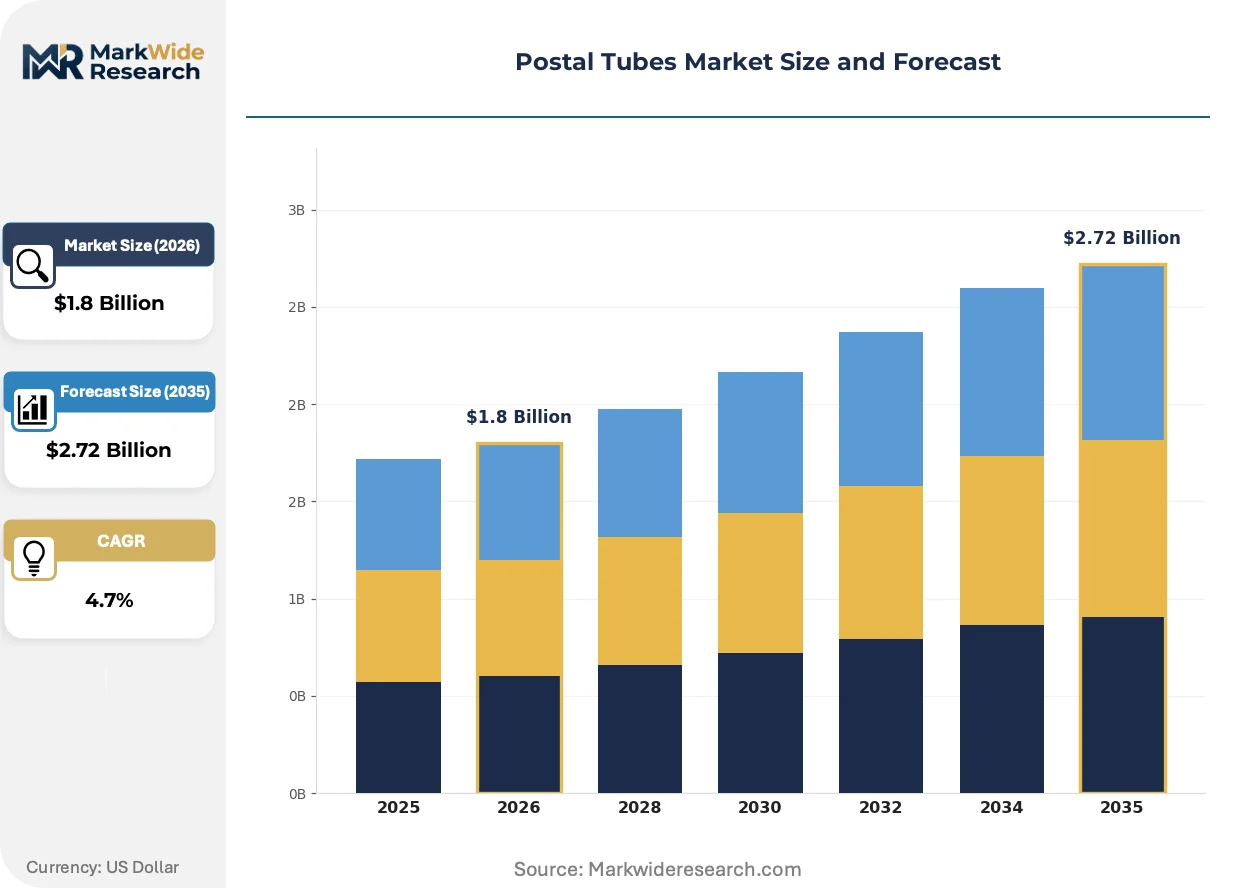
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Plastic, Fiberboard, Metal Size: Small, Medium, Large, Extra Large End User: Retailers, Artists, Architects, Educational Institutions Closure Type: Screw Cap, Snap Lock, End Plug, Adhesive |
| Companies Covered | Sonoco Products Company, Ace Paper Tube, Chicago Mailing Tube, Valk Industries, Western Container Corporation, Printec Group, Globe Packaging Group, International Paper, Mondi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Postal Tubes Market Evolving Landscape
Active reshaping in postal tube manufacturing centers on material science advances, regulatory compliance automation, and fulfillment-optimized design protocols that compress total cost of ownership for high-volume shippers.
Water-based barrier coatings are converging with fiberboard substrates to deliver moisture resistance without plastic lamination. Art supply retailers and textile shippers in the Netherlands and Belgium specify these grades for humid climate routes. The technology is converging with automated quality inspection systems that verify coating uniformity at line speed, enabling converters to guarantee performance thresholds previously associated with polyethylene tubes.
The EU Packaging and Packaging Waste Regulation imposes harmonized recyclability assessment protocols across member states. Tube converters must submit technical documentation to national compliance schemes before market placement. German and French packaging producers invest in laboratory certification infrastructure to accelerate approval timelines, while smaller converters outsource testing to accredited third-party facilities.
Direct procurement from converter to shipper is displacing distributor intermediation in the poster and document vertical. Large-format e-commerce merchants in the United Kingdom negotiate annual volume contracts that bypass traditional packaging wholesalers. This channel compression is most visible among online art marketplaces that consolidate fragmented artist demand into predictable batch orders with standardized diameter specifications.
Postal Tubes Market Segmentation
Postal tube procurement patterns diverge sharply across material grades, dimensional specifications, and end-user workflows. Understanding these fault lines reveals where converters can defend margin through specification capture versus where commoditization pressure dominates.
Material Type:
Cost tiers separate buyers seeking regulatory compliance from those prioritizing performance under environmental stress.
- Cardboard:Spirally wound post-consumer fiberboard layers deliver stiffness-to-weight ratios that satisfy EU Packaging and Packaging Waste Regulation recycled content thresholds. German e-commerce fulfillment networks specify these grades for document shipping where moisture exposure remains controlled.
- Plastic:Polyethylene and polypropylene extrusions provide vapor transmission resistance mandatory for pharmaceutical document transit and humid climate routes. REACH-compliant formulations attract extended producer responsibility fee discounts in French and Belgian procurement frameworks.
- Fiberboard:Heavier caliper kraftliner constructions serve industrial textile shipping requiring crush resistance beyond standard cardboard capabilities. Polish integrated mills supply this grade tariff-advantaged to Nordic converters.
- Metal:Aluminum and steel tubes protect high-value architectural blueprints and engineering drawings from crushing and moisture damage. Aerospace and defense contractors in the United Kingdom specify these for classified document transport.
Volume sits with Cardboard; growth tilts toward Plastic as REACH-compliant formulations penetrate pharmaceutical logistics.
Size:
Application scale determines whether buyers prioritize unit cost minimization or damage rate reduction.
- Medium:Diameters between 2 and 4 inches dominate art supply retailer procurement for poster and print shipping. United Kingdom centralized distribution hubs standardize on this specification to optimize SKU throughput across European fulfillment networks.
- Small:Sub-2-inch calipers serve architect and artist direct orders for technical drawings and photographic prints. Higher per-unit margins compensate converters for batch setup inefficiencies in fragmented demand.
- Large:4-to-6-inch diameters accommodate rolled textiles and carpet samples for interior design logistics. Moisture barrier specifications become critical for humid climate routes to Middle Eastern markets.
- Extra Large:Above-6-inch constructions protect industrial banners and exhibition graphics requiring structural rigidity. Custom spiral-winding equipment constraints limit supplier options to specialized converters.
Volume concentrates in Medium specifications; expansion accelerates fastest in Small diameters as artist marketplace platforms consolidate fragmented demand.
End User:
Customer type dictates whether procurement emphasizes standardization and scale or flexibility and premium positioning.
- Retailers:Online art supply merchants drive large-format standardization through annual volume contracts that bypass traditional packaging distributors. German and United Kingdom hubs generate sustained pull for medium-diameter fiberboard tubes.
- Artists:Individual practitioners and small studios generate unpredictable batch orders with higher margin profiles. Direct-to-consumer channels are displacing wholesale intermediation in this segment.
- Architects:Engineering firms require crush-resistant specifications for technical drawing transport, often specifying metal tubes for high-value contract documentation.
- Educational Institutions:Universities and museums purchase seasonal volumes for student project shipping and exhibition loan programs. Budget constraints favor cardboard grades with established recovery infrastructure.
Retailers command volume share; Artists deliver steepest expansion trajectory as online marketplaces aggregate previously fragmented procurement.
Closure Type:
Labor economics at the packing station determine specification preference in high-throughput environments.
- Snap Lock:Integrated plastic locking mechanisms eliminate tape sealing steps, reducing per-unit labor in automated fulfillment centers. United Kingdom e-commerce operators specify these for direct-to-consumer art print shipping.
- Screw Cap:Threaded plastic or metal closures provide resealable access for documents requiring repeated handling. Pharmaceutical logistics operators favor this specification for regulatory sample tracking.
- End Plug:Molded plastic or fiberboard inserts offer lowest unit cost for single-use shipping applications. Educational institutions prioritize this option for budget-constrained procurement.
- Adhesive:Pressure-sensitive tape sealing remains prevalent in artisanal and small-batch production environments where automation investment is uneconomical.
End Plug closures dominate unit volume; Snap Lock mechanisms gain share fastest as fulfillment center automation intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recovered fiber collection networks in the Ohio River valley anchor North American postal tube manufacturing, while integrated kraftliner mills in Central Europe supply converters serving Nordic e-commerce fulfillment networks.
United States
EPA recycled content guidelines for federal procurement shape converter material sourcing decisions across the Midwest manufacturing corridor. The Forest Stewardship Council chain-of-custody certification operates as de facto market access requirement for tubes entering corporate supply chains. Ohio River valley integrated mills feed independent converters throughout the southeastern states where containerboard capacity clusters.
Germany
Centralized distribution hubs for online art supply retailers generate sustained volume pull for medium-diameter fiberboard tubes across Bavaria and North Rhine-Westphalia. The EU Packaging and Packaging Waste Regulation imposes extended producer responsibility fees modulated by recyclability scores, accelerating post-consumer cardboard adoption. Frankfurt and Hamburg logistics zones concentrate specification demand for standardized closure mechanisms.
United Kingdom
London and Midlands fulfillment centers drive large-format standardization through annual volume contracts that bypass traditional packaging wholesalers. The same EU Packaging and Packaging Waste Regulation mandates recycled fiber thresholds that force tube converters to requalify material grades across their supplier base. Manchester and Birmingham industrial zones host converters serving direct-to-consumer art marketplace platforms.
Poland
Mondi's integrated kraftliner operations in Central Europe offer tariff-advantaged supply access for converters targeting Nordic e-commerce fulfillment networks. REACH-compliant material substitution accelerates as extended producer responsibility frameworks penalize plastic variants. Warsaw and Krakow manufacturing corridors attract mid-sized converters seeking proximity to German demand centers.
Netherlands
Rotterdam and Amsterdam logistics hubs specify water-based barrier coatings for humid climate routes to Middle Eastern markets. The EU harmonized recyclability assessment protocols require technical documentation submission to national compliance schemes before market placement. Eindhoven packaging innovation clusters pilot automated quality inspection systems that verify coating uniformity at line speed.
Postal Tubes Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue specialty coating and automation-adjacent spaces. The vendor base separates into integrated paperboard manufacturers with captive fiber supply, independent spiral-winding specialists serving regional markets, and diversified packaging conglomerates leveraging scale procurement. Three archetypes dominate: backward-integrated mills controlling OCC feedstock costs, certified converters monetizing FSC chain-of-custody premiums, and automation-focused fabricators engineering snap-lock closure systems. Capacity expansion and geographic repositioning toward Polish kraftliner supply constitute the dominant competitive moves.
Among North American integrated producers, Sonoco Products Company and International Paper exemplify the mill-control archetype, while Mondi anchors the European tariff-advantaged supply position. These three occupy positions where captive or proximate fiberboard production insulates margin structures from OCC price volatility.
| Leading Market Players |
|---|
| Sonoco Products Company |
| Ace Paper Tube |
| Chicago Mailing Tube |
| Valk Industries |
| Western Container Corporation |
| Printec Group |
| Globe Packaging Group |
| International Paper |
| Mondi |
| Others |
Value Network & Pricing Analysis
Backward integration into recycled paperboard mills anchors supply position and pricing power for postal tube converters serving the Midwest manufacturing corridor. Sonoco Products Company and International Paper leverage captive OCC feedstock to insulate margin structures from Old corrugated container price volatility that compresses independent converters when municipal collection yields dip below seasonal baselines.
Pricing Analysis
Warranty and performance guarantees remain unbundled from base tube pricing, with moisture resistance certifications and FSC chain-of-custody premiums priced as line-item add-ons. Contract-based annual volume offtake dominates procurement between large-format e-commerce merchants and integrated producers, while spot purchasing persists for fragmented artist and architect orders. Price differentiation hinges on certification tier and customization level, with REACH-compliant formulations commanding premiums in French and Belgian procurement frameworks. Cost compression in standard cardboard grades is intensifying as North American containerboard producers rebalance capacity toward lighter basis weights.
Supply Chain Analysis
Old corrugated container feedstock supply rests on municipal recovery programs concentrated in the United States, Germany, and Poland. Spiral-winding equipment and skilled technician labor constitute critical input dependencies alongside kraftliner grades from integrated mills. Single-source vulnerability concentrates around Midwest mill operations clustering along the Ohio River valley, exposing converters outside this corridor to geographic supply risk. Distribution runs through direct procurement channels displacing traditional packaging wholesalers, particularly among United Kingdom online art marketplaces consolidating fragmented demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Postal tube manufacturing operates under supply-constrained conditions where spiral-winding technician scarcity props pricing for certified converters. Skilled operator retirements outpace vocational program replenishment, creating a structural capacity bottleneck.
For Market Incumbents: Acquire automated quality inspection systems to reduce per-unit labor dependence and defend against snap-lock closure automation investments by competitors. Deepen backward integration into Polish kraftliner supply to capture tariff-advantaged access for Nordic e-commerce networks, while consolidating regional converter capacity to offset margin compression from OCC price volatility.
For New Entrants and Emerging Players: Art supply marketplace platforms represent the most penetrable channel partner type for bypassing traditional distributor intermediation. Target small-diameter specifications serving artist direct orders where higher per-unit margins compensate for batch setup inefficiencies, and pursue water-based barrier coating certifications to capture specification demand from Netherlands and Belgium textile shippers.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated paperboard manufacturers seeking regional converter networks. Long-term viability favors certified converters with FSC chain-of-custody infrastructure and automated closure system capabilities. Watch California and New York plastic restriction statute evolution as the inflection signal for accelerated fiberboard substitution timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Paperboard Mills | Sonoco and International Paper leverage captive OCC supply to insulate margins from feedstock volatility. |
| Water-Based Barrier Coating Certification | Netherlands and Belgium textile shippers specify these grades for humid climate routes to Middle Eastern markets. |
| Snap-Lock Closure Automation | United Kingdom fulfillment centers demand integrated locking mechanisms that eliminate tape sealing steps. |
| FSC Chain-of-Custody Investment | Corporate procurement policies in Germany and the United Kingdom require verified sustainable sourcing credentials. |
| Polish Kraftliner Capacity Expansion | Mondi's integrated operations offer tariff-advantaged supply access for converters targeting Nordic networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this postal tubes market assessment. Primary interviews with spiral-winding plant managers, e-commerce fulfillment procurement leads, art supply retailer category buyers, and paperboard mill technical directors combined with secondary validation from EPA guidelines, EU Packaging and Packaging Waste Regulation documentation, and Forest Stewardship Council certification databases. Bottom-up demand modeling across end-user segments triangulated with top-down containerboard capacity analysis.
Data-stream reconciliation across shipment volumes, capacity utilization rates, and pricing survey responses informed the analytical framework. Segmentation dimensions modeled include material grade, diameter specification, closure type, and end-user workflow pattern across the projection horizon. CAGRs were derived from trend extrapolation of e-commerce fulfillment velocity and regulatory compliance cost trajectories, with specific inputs from Old corrugated container recovery rate forecasts and automated packaging equipment adoption curves.
Caveats apply where spiral-winding technician training program expansion, state-level plastic restriction enforcement timing, or OCC collection program yield volatility could materially shift the outlook. Forecasts reflect assumptions about EU extended producer responsibility fee structures and REACH compliance cost trajectories. A small set of named triggers including California statute evolution and Polish kraftliner capacity additions warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Super Calendered Kraft Papers Market
Paper & Paperboard Packaging
Cellular Paper Cardboard Market
Paper & Paperboard Packaging
Freezer Paper Market
Paper & Paperboard Packaging
Paper Bubble Wrap Market
Paper & Paperboard Packaging
Australia Paper and Paperboard Packaging Market
Paper & Paperboard Packaging
Machine Glazed Paper Market
Paper & Paperboard Packaging
Global VCI Paper Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
PE Coated Sack Kraft Paper Market
Paper & Paperboard Packaging
Latin America Paper Packaging Market
Paper & Paperboard Packaging
Corrugated Packaging Market
Paper & Paperboard Packaging
Tea Filter Paper Market
Paper & Paperboard Packaging
Composite Paper Cans Market
Paper & Paperboard Packaging
Paper and Paperboard Trays Market
Paper & Paperboard Packaging
Qatar Paper Packaging Products Market
Paper & Paperboard Packaging
Paper Release Liners Market