
 Global Sports Insurance Market | 2026-2036
Global Sports Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sports Insurance Market Outlook
Multi-source underwriting partnerships between traditional carriers and specialty sports insurers is expanding as event liability exposures grow more complex. Munich Reinsurance Company leverages its catastrophe modeling expertise to price extreme sports coverage. Allianz SE anchors its position through long-term Olympic and Paralympic partnerships. Beazley plc specializes in niche amateur and youth sports segments where standard carriers retreat.
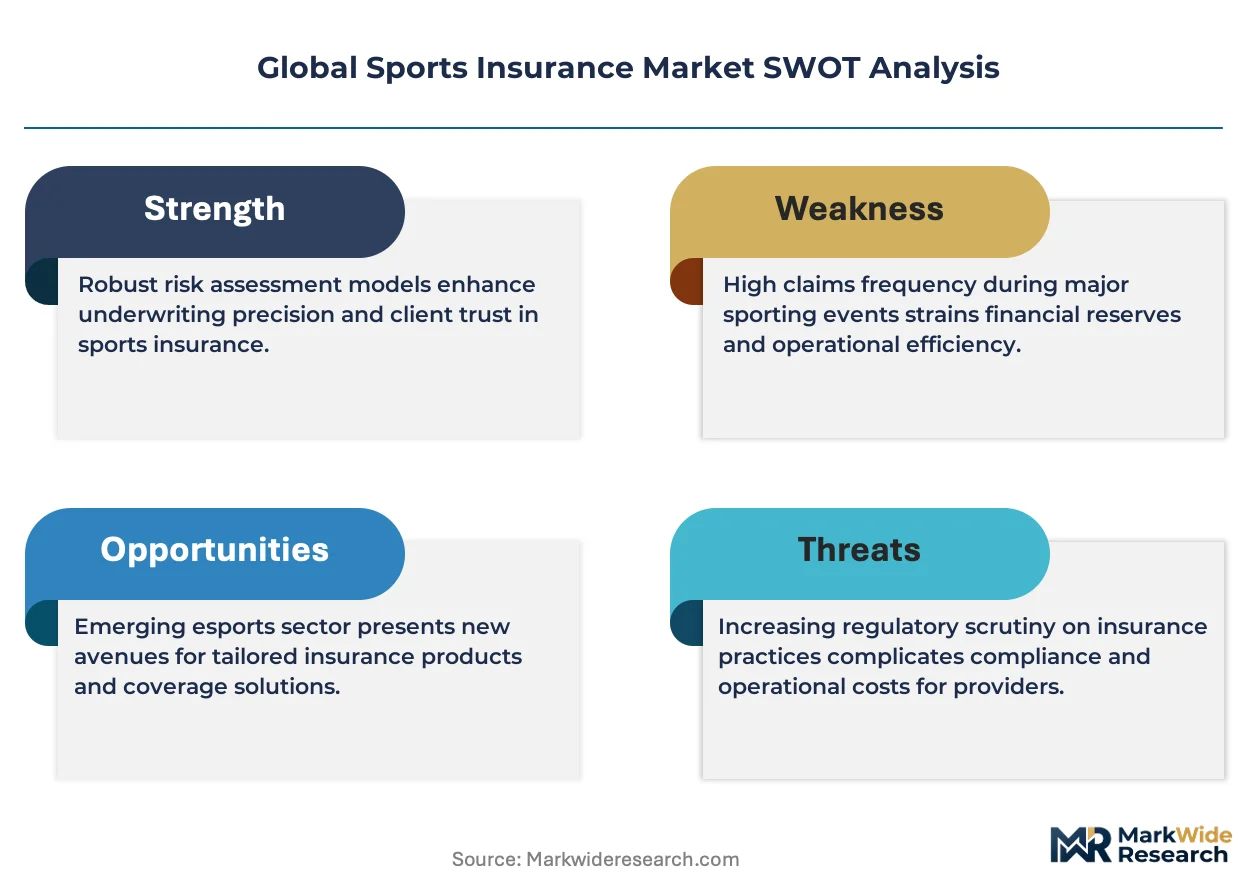
Sports insurance encompasses liability, accident, disability, and life coverage tailored to bodily injury risks inherent in athletic participation, with underwriting precision hinging on actuarial tables that incorporate sport-specific injury frequency, severity curves, and medical cost inflation indices. Its primary commercial purpose is to transfer financial risk from athletes, teams, and event organizers to capital-backed carriers, enabling sporting activity at scale without catastrophic balance-sheet exposure. Accident insurance commands the largest premium pool due to universal participation requirements across professional leagues, while pay-as-you-go premium structures represent the fastest-growing segment as episodic event coverage displaces annual policies for intermittent organizers. Liability insurance maintains mature, stable margins in established markets but faces pricing pressure from litigation frequency in contact sports.
The EU's GDPR and AI Act constrain how European carriers deploy wearable biometric data in underwriting decisions, while the US FDA regulates medical device classifications for injury-monitoring hardware that informs claims validation. China's SAMR enforces data localization requirements on health records used in policy pricing. Stakeholders must monitor diverging regulatory treatment of algorithmic risk scoring across jurisdictions to avoid coverage voids or enforcement actions.
Market Dynamics
Wearable biometric data streams from athlete-worn sensors are forcing underwriters to rebuild actuarial models around real-time injury probability rather than historical sport-class tables.
Growth Catalysts
- Mandatory League Coverage Expansion:Professional sports governing bodies in the United States and Germany are tightening minimum liability thresholds for athlete protection, compelling teams to upgrade policy limits.
- Wearable Technology Integration:Continuous glucose monitors and GPS load-tracking devices generate granular risk profiles that enable precision pricing for individual athletes.
- Extreme Sports Normalization:Olympic inclusion of skateboarding, sport climbing, and surfing creates standardized competition formats that carriers can underwrite with predictable frequency data.
Market Restraints
- Medical Cost Inflation:Orthopedic surgery and concussion rehabilitation expenses in the United States outpace premium rate adjustments, compressing loss ratios for accident carriers.
- Data Localization Mandates:China's SAMR and the EU's GDPR impose conflicting storage requirements on biometric health records, fragmenting underwriting infrastructure across jurisdictions.
- Litigation Frequency Surge:Chronic traumatic encephalopathy claims against contact sports leagues in North America drive liability reserve strengthening and capacity withdrawal.
Strategic Opportunities
- Amateur and Youth Sports Penetration:Brazil and India exhibit minimal insured participation rates in school athletics and community leagues, offering first-mover positioning for micro-premium products.
- Parametric Weather Coverage:Event cancellation policies triggered by automated rainfall or temperature thresholds reduce claims adjustment costs for outdoor tournament organizers.
- EU AI Act Compliance Services:European carriers can monetize algorithmic audit capabilities to competitors struggling with prohibited biometric scoring practices under the new artificial intelligence liability framework.
Industry Challenges
- Actuarial Talent Scarcity:Underwriters with expertise in both sports medicine and predictive modeling command compensation premiums that strain mid-tier carrier economics.
- Legacy System Integration:Real-time data ingestion from third-party wearable platforms requires API architecture overhauls that conflict with decades-old policy administration systems.
- Cross-Border Claims Jurisdiction:International athlete transfers trigger coverage gaps when medical treatment occurs in countries outside the original policy territory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sports Insurance Market |
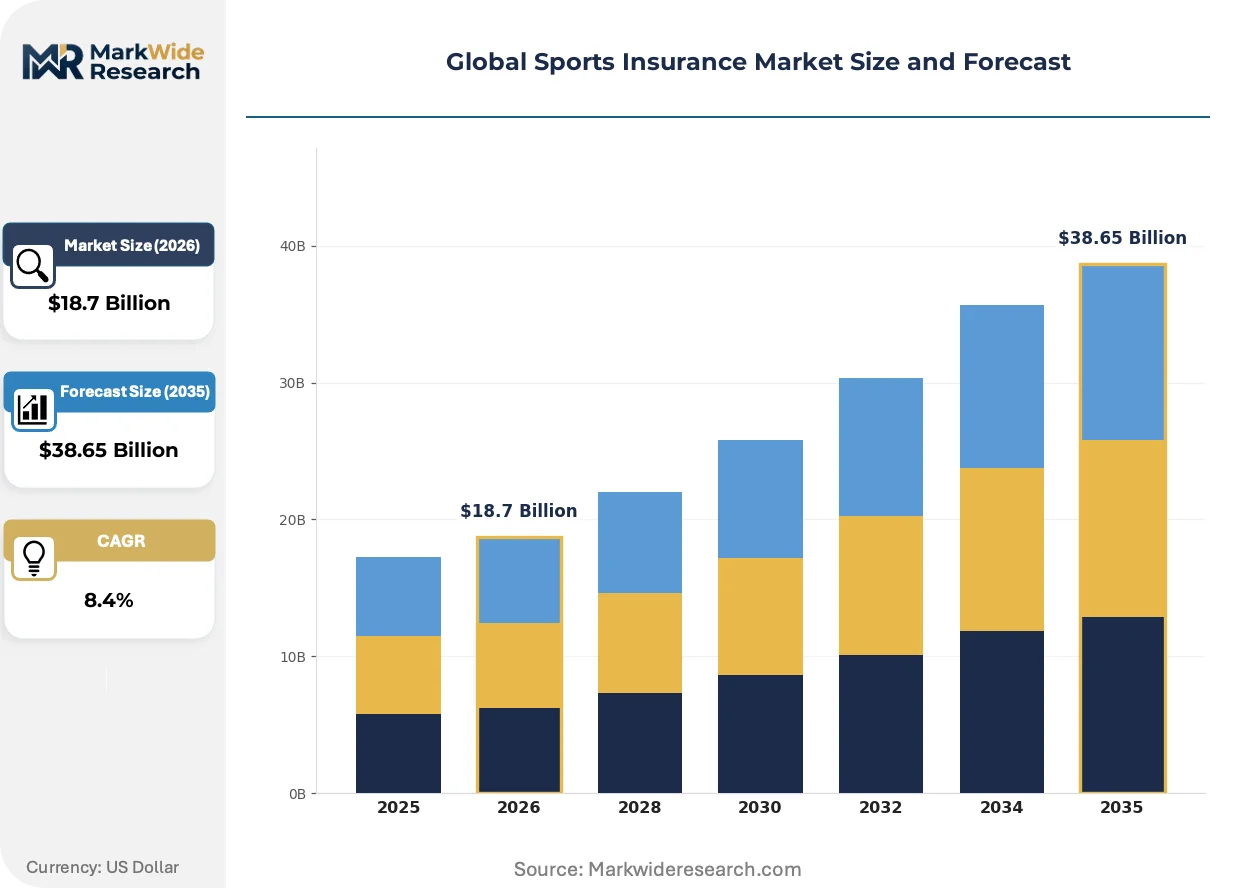
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Liability Insurance, Accident Insurance, Disability Insurance, Life Insurance Client Type: Professional Athletes, Amateur Athletes, Sports Teams, Event Organizers Coverage Area: Domestic, International, Regional, National Premium Structure: Fixed Premium, Variable Premium, Pay-As-You-Go, Comprehensive Coverage |
| Companies Covered | AXA SA, Munich Reinsurance Company, Allianz SE, Aon plc, Swiss Reinsurance Company Ltd, Chubb Limited, Zurich Insurance Group Ltd, Beazley plc, American International Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sports Insurance Market Strategic Shifts
Digital distribution platforms and algorithmic underwriting engines are compressing policy issuance cycles from weeks to hours, while regulatory fragmentation around biometric data forces product architecture divergence across markets.
Continuous biometric monitoring is expanding into standard risk assessment protocols for professional athlete coverage. Wearable devices transmitting heart rate variability, sleep quality metrics, and impact force data enable dynamic premium adjustments tied to demonstrated injury prevention behaviors. National basketball and football leagues in the United States now mandate such monitoring for contract-eligible players, compressing traditional annual policy structures into adjustable coverage periods.
The EU AI Act's prohibition on automated biometric inference in insurance decisions creates compliance architecture requirements for European carriers. Underwriters must now maintain human-in-the-loop review protocols for any algorithmic risk score influencing coverage terms or pricing. German and French regulators are enforcing this through periodic algorithmic impact assessments, forcing product teams to rebuild decision trees with auditable intervention points.
Episodic event organizers are abandoning annual master policies for on-demand coverage activated through mobile platforms. Marathon directors, esports tournament operators, and youth league administrators purchase liability protection for single weekends rather than maintaining twelve-month contracts. This behavioral shift concentrates in the United States and United Kingdom, where insurtech distribution platforms have achieved sufficient penetration to displace traditional broker relationships for sub-million-dollar events.
Global Sports Insurance Market Segmentation
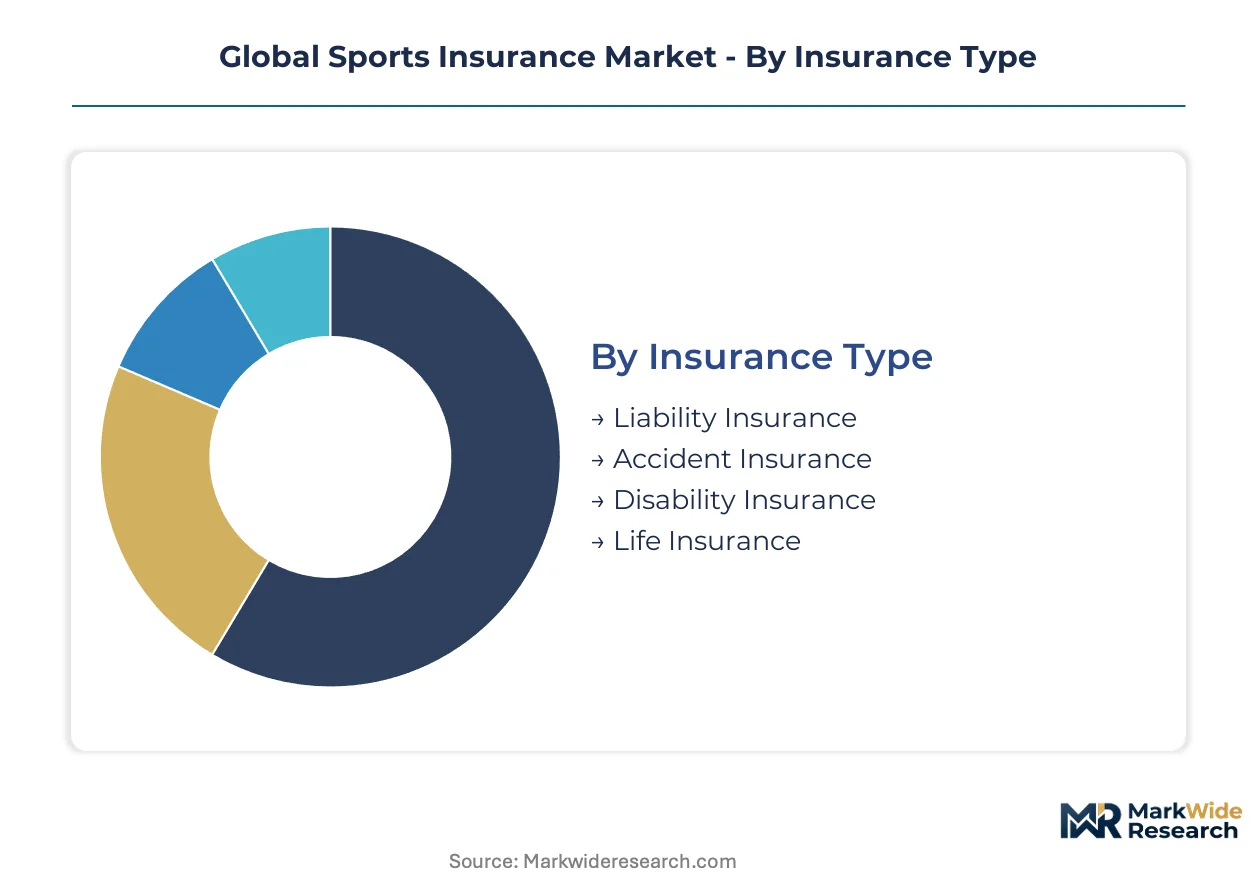
Segmentation in sports insurance determines capital allocation, pricing precision, and distribution architecture. Underwriters calibrate reserves and reinsurance treaties differently across liability, accident, and disability lines. Client type and coverage area variables dictate whether carriers deploy automated underwriting engines or maintain human-in-the-loop protocols.
Insurance Type:
Supply concentration among global reinsurers tilts toward accident and liability lines, where Munich Re and Swiss Re deploy catastrophe modeling infrastructure at scale.
- Liability Insurance:Covers bodily injury and property damage claims arising from athletic participation, spectator incidents, and venue operations. Demand concentrates in contact sports leagues across the United States and Germany, where litigation frequency and jury award inflation compel teams to carry excess layers above primary coverage.
- Accident Insurance:Provides medical expense reimbursement and accidental death benefits for injury events during training or competition. Professional leagues in the United States mandate this coverage as a condition of collective bargaining agreements, creating predictable premium pools with standardized benefit schedules.
- Disability Insurance:Replaces income lost to career-ending or temporary incapacitating injuries. Contracts specify own-occupation definitions for elite athletes, with benefit periods extending through age 65 for permanent disabilities.
- Life Insurance:Term and permanent products tailored to high-net-worth athletes with estate planning requirements. Underwriters impose aviation and motorsport exclusions unless supplemental premiums are accepted.
Accident insurance absorbs the bulk of installed capacity; pay-as-you-go structures within liability lines are expanding most quickly.
Client Type:
Premium volume clusters around professional athletes and major event organizers, while amateur segments present distribution cost challenges that favor digital platform partnerships.
- Professional Athletes:Individual policies supplement league-mandated coverage, addressing endorsement contract protection and career transition planning. Contracts in the United States, Germany, and Spain specify concussion protocol compliance as a condition of disability benefit eligibility.
- Amateur Athletes:Coverage gaps persist in school athletics and recreational leagues across Brazil and India, where micro-premium products distributed through mobile platforms are penetrating previously uninsured populations.
- Sports Teams:Master policies covering rostered players, coaching staff, and medical personnel. Fronting arrangements with captive insurers allow large-market franchises to retain predictable loss layers while ceding catastrophe exposure.
- Event Organizers:Liability protection for tournament directors, venue operators, and sanctioning bodies. Weather-triggered cancellation endorsements reduce claims adjustment costs for outdoor competitions.
Professional athlete coverage generates the highest premium density per account; amateur segments are climbing the fastest as insurtech distribution achieves scale.
Coverage Area:
Geographic scope determines regulatory compliance burdens, with international policies requiring multi-jurisdictional filings and data localization accommodations.
- Domestic:Single-country coverage subject to local solvency and consumer protection regimes. Policies issued in the United States exclude treatment abroad unless emergency evacuation riders are attached.
- International:Multi-territory protection for athletes competing in global tours or transfer markets. Underwriters must reconcile conflicting medical privacy laws when claims originate outside the policy jurisdiction.
- Regional:Coverage limited to defined geographic clusters, common in European Union competitions where freedom-of-movement principles simplify cross-border treatment authorization.
- National:Federally mandated coverage for Olympic and Paralympic delegations, with benefit schedules standardized by national Olympic committees.
International coverage commands premium multiples over domestic equivalents; regional structures are gaining share fastest among mid-tier professional leagues.
Premium Structure:
Pricing model selection reflects event frequency predictability and capital efficiency requirements for policyholders with irregular exposure patterns.
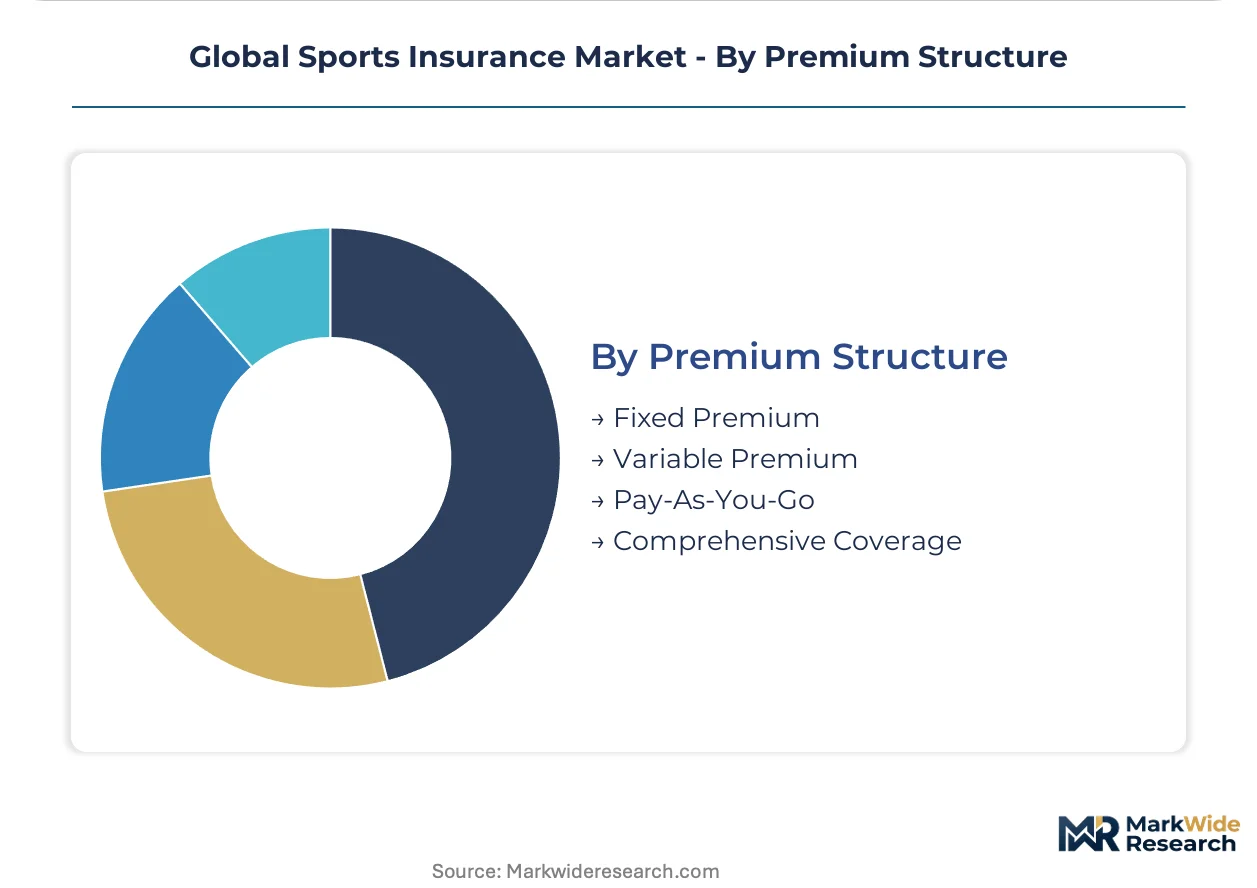
- Fixed Premium:Annual contracts with guaranteed rates regardless of claims experience. Established professional leagues in the United States prefer this structure for budget certainty and covenant compliance.
- Variable Premium:Rates adjusted retrospectively based on loss experience during the policy period. Large sports franchises with captive insurance subsidiaries utilize this to align premium outflows with actual risk retention.
- Pay-As-You-Go:Coverage activated per event through mobile distribution platforms. Marathon organizers and esports tournament operators in the United Kingdom and United States are displacing annual master policies with this structure.
- Comprehensive Coverage:Bundled policies combining liability, accident, and disability protection. Youth sports governing bodies negotiate these packages to simplify administration and reduce coverage gaps.
Fixed premium structures dominate current premium volume; pay-as-you-go models are expanding most quickly as episodic event coverage displaces annual contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's Lloyd's syndicates supply catastrophic capacity that underpins extreme sports coverage worldwide. Bermuda's reinsurance hubs price weather-linked event cancellation policies for outdoor tournaments. Zurich's specialty carriers dominate professional athlete disability lines across continental Europe.
United States
NFL and NBA collective bargaining agreements mandate escalating liability thresholds that compel teams to purchase excess layers. The FDA regulates wearable biometric devices used in claims validation protocols. New York and Los Angeles host the densest concentrations of sports franchise headquarters where captive insurance subsidiaries retain predictable loss layers.
Germany
Bundesliga clubs and Olympic training centers drive demand for precision-priced accident coverage. The KBA enforces strict data localization on health records used in underwriting algorithms. Munich anchors continental Europe's reinsurance infrastructure where specialty carriers model extreme sports frequency curves.
China
Shanghai and Beijing tournament operators purchase episodic liability coverage for international sporting events. SAMR mandates domestic storage of athlete biometric data, fragmenting underwriting infrastructure. The Yangtze River Delta concentration of esports venues generates novel demand for cyber-physical risk policies.
United Kingdom
London's Lloyd's market supplies catastrophe capacity for global extreme sports and event cancellation lines. The Financial Conduct Authority supervises algorithmic pricing transparency in pay-as-you-go platforms. Manchester and Birmingham football clubs utilize captive structures to retain predictable medical expense layers.
Australia
Australian Rules Football and rugby leagues mandate concussion protocol compliance as a condition of disability benefit eligibility. The TGA regulates medical device classifications for impact-monitoring hardware. Sydney and Melbourne host the largest concentrations of sports medicine clinics that validate claims for international underwriters.
Global Sports Insurance Market Competitive Environment
Global majors compete with regional champions across distribution architecture and risk modeling depth. The market structures around three tiers: multinational reinsurers deploying catastrophe infrastructure, mid-tier carriers specializing in amateur and youth segments, and insurtech platforms enabling episodic coverage activation. Strategic differentiation hinges on biometric data integration capabilities and regulatory compliance architecture across GDPR, SAMR, and FDA jurisdictions. Competitive moves concentrate on M&A targeting wearable analytics firms and partnerships with league governing bodies for mandatory coverage mandates.
Within the reinsurance tier, Munich Reinsurance Company and Swiss Reinsurance Company Ltd exemplify catastrophe modeling specialists that price extreme sports frequency curves. Allianz SE occupies a position as the archetypal Olympic partnership anchor, leveraging long-term International Olympic Committee relationships to secure event liability monopolies. Beazley plc represents the niche specialist archetype, focusing on amateur and youth sports segments where standard carriers have retreated due to distribution cost economics.
| Leading Market Players |
|---|
| AXA SA |
| Munich Reinsurance Company |
| Allianz SE |
| Aon plc |
| Swiss Reinsurance Company Ltd |
| Chubb Limited |
| Zurich Insurance Group Ltd |
| Beazley plc |
| American International Group, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU AI Act compliance mandates gate both qualified underwriting supply and premium-tier pricing access, as carriers investing in human-in-the-loop algorithmic audit capabilities capture pricing power while non-compliant competitors face coverage voids or enforcement withdrawals from German and French regulators.
Pricing Analysis
Warranty-style service bundling separates premium-tier carriers from unbundled economy competitors, with Munich Re and Allianz packaging catastrophe modeling expertise alongside policy coverage while mid-tier players strip out actuarial advisory to hit price points. Price differentiation hinges on biometric data integration depth and GDPR/SAMR/FDA certification tier, with wearable-validated policies commanding substantial premiums over standard sport-class tables. Pricing pressure stems from medical cost inflation in United States orthopedic and concussion rehabilitation outrunning rate adjustments. Amateur youth leagues in Brazil and India exhibit highest price sensitivity, while NFL and NBA franchises with captive insurance subsidiaries demonstrate lowest sensitivity due to budget certainty requirements.
Supply Chain Analysis
Dual-sourcing requirements from United States and German league risk managers mandate multi-carrier qualification for excess liability layers, preventing single-reinsurer dependency in catastrophic coverage towers. Geographic supply concentrates in Germany, United Kingdom, and United States, where Munich Re, Lloyd's syndicates, and AIG anchor global capacity. Raw material dependencies include actuarial talent pools, wearable biometric hardware, and cloud infrastructure for real-time data ingestion. Supply chain risk centers on single-source vulnerability in extreme sports catastrophe modeling expertise. Distribution runs through traditional broker networks for professional league master policies, while mobile-first insurtech platforms capture episodic amateur and event organizer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Sports Insurance Market functions as a cost-of-compliance story, with EU AI Act algorithmic audit requirements and SAMR data localization mandates creating barrier-to-entry moats that compound returns for carriers with pre-built regulatory architecture.
For Market Incumbents: Extend biometric data integration capabilities through API partnerships with wearable platform providers, defending against insurtech disintermediation in episodic coverage segments. Reinforce Germany and United States presence through captive insurance fronting arrangements with Bundesliga and NFL franchises, locking in predictable loss layer retention. Prioritize EU AI Act compliance monetization by offering algorithmic audit services to mid-tier European competitors lacking human-in-the-loop infrastructure.
For New Entrants and Emerging Players: Begin with amateur youth sports penetration in Brazil and India, where micro-premium mobile distribution achieves first-mover positioning in minimally insured school athletics and community leagues. Target pay-as-you-go liability coverage for marathon directors and esports tournament operators in United Kingdom and United States, displacing annual master policies through weekend-activated mobile platforms. Anchor go-to-market through league governing body partnerships for mandatory coverage mandates.
For Investors and Strategic Acquirers: FDA medical device classification approvals for injury-monitoring hardware is the leading indicator that wearable-validated underwriting models are achieving regulatory acceptance and scalable deployment. Long-term viability favors carriers with dual GDPR-SAMR compliance architecture spanning European and Chinese biometric data localization requirements. Acquisition target archetype: mid-tier specialty carriers with established extreme sports frequency curves but lacking real-time data ingestion capabilities. Watch for SAMR enforcement actions against non-compliant foreign carriers as signal of market consolidation opportunity.
| Strategic Initiative | Industry Significance |
|---|---|
| Wearable Biometric Platform Partnership | Enables precision pricing for individual athletes through continuous glucose monitors and GPS load-tracking integration. |
| EU AI Act Compliance Service Launch | Monetizes algorithmic audit capabilities to competitors struggling with prohibited biometric scoring practices under new liability framework. |
| Amateur Youth Sports Micro-Premium Expansion | Captures first-mover positioning in Brazil and India school athletics through mobile distribution platforms. |
| Parametric Weather Coverage Product Development | Reduces claims adjustment costs for outdoor tournament organizers via automated rainfall or temperature threshold triggers. |
| Captive Insurance Fronting Arrangement | Retains predictable loss layers for large-market franchises while ceding catastrophe exposure to reinsurance markets. |
Study Parameters
Independent corroboration across primary interviews with sports insurance underwriters, league risk managers, and wearable technology platform engineers, alongside secondary validation through Lloyd's market filings, SEC insurance subsidiary disclosures, and FDA medical device classification databases, underwrites the qualitative findings. Conversations with Bundesliga and NFL franchise captive insurance officers, Munich Re catastrophe modelers, and German KBA regulatory compliance leads supplied forward-looking capacity and pricing intelligence. Bottom-up policy issuance data triangulates against top-down reinsurance treaty disclosures to anchor market size estimates.
Comparable-period anchoring to historical sport-class actuarial tables and early wearable biometric pilot programs calibrates the forecast framework across the projection horizon. Segmentation dimensions modeled include insurance type, client archetype, coverage area scope, and premium structure, with biometric data integration depth as the industry-specific overlay. CAGRs derive from loss ratio trajectory analysis and premium volume elasticity to mandatory coverage mandate expansions. Forecast inputs incorporate medical cost inflation indices and litigation frequency curves for contact sports liability lines.
Underlying measurement precision varies by segment; professional athlete accident and disability coverage carries tighter precision than amateur youth penetration estimates due to standardized collective bargaining reporting requirements. Forecasts reflect assumptions around regulatory enforcement consistency across GDPR, SAMR, and FDA jurisdictions, with revision triggers including material shifts in biometric data privacy rulings or league mandatory coverage threshold adjustments. A model refresh is warranted upon material change in EU AI Act algorithmic impact assessment enforcement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
China Liability Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
India Electronic Gadget Insurance Market
Insurance
Aerospace Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
Europe Embedded Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
China Parametric Insurance Market
Insurance
UAE Property and Casualty Insurance Market
Insurance
Jewelry Insurance Market
Insurance
AI in Insurance Market
Insurance
Takaful Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Asia-Pacific Travel Insurance Market