
 Global Hydraulic Metering Pump Market | 2026-2036
Global Hydraulic Metering Pump Market Size, Share, and Industry Trends Forecast 2026-2036
Global Hydraulic Metering Pump Market Outlook
Direct-to-utility distribution is narrowing as regional water authorities consolidate vendor qualification lists. LEWA GmbH leverages its diaphragm expertise to anchor premium positioning in European chemical processing. Milton Roy competes through specialized alloy configurations for corrosive media applications. Grundfos Holding A/S extends its channel control via integrated digital monitoring packages bundled with pump hardware.
A hydraulic metering pump is a positive-displacement device that uses a reciprocating piston or diaphragm driven by hydraulic fluid to deliver precise, repeatable flow rates typically within ±1% accuracy, engineered for critical dosing of chemicals, polymers, and treatment additives in continuous industrial processes. Diaphragm pumps dominate installed bases due to their leak-free containment of hazardous or abrasive fluids, while piston pumps sustain higher-pressure applications in oilfield chemical injection. Electromechanical technology leads new order intake as plant operators prioritize variable-speed drives and remote telemetry integration over pneumatic alternatives.
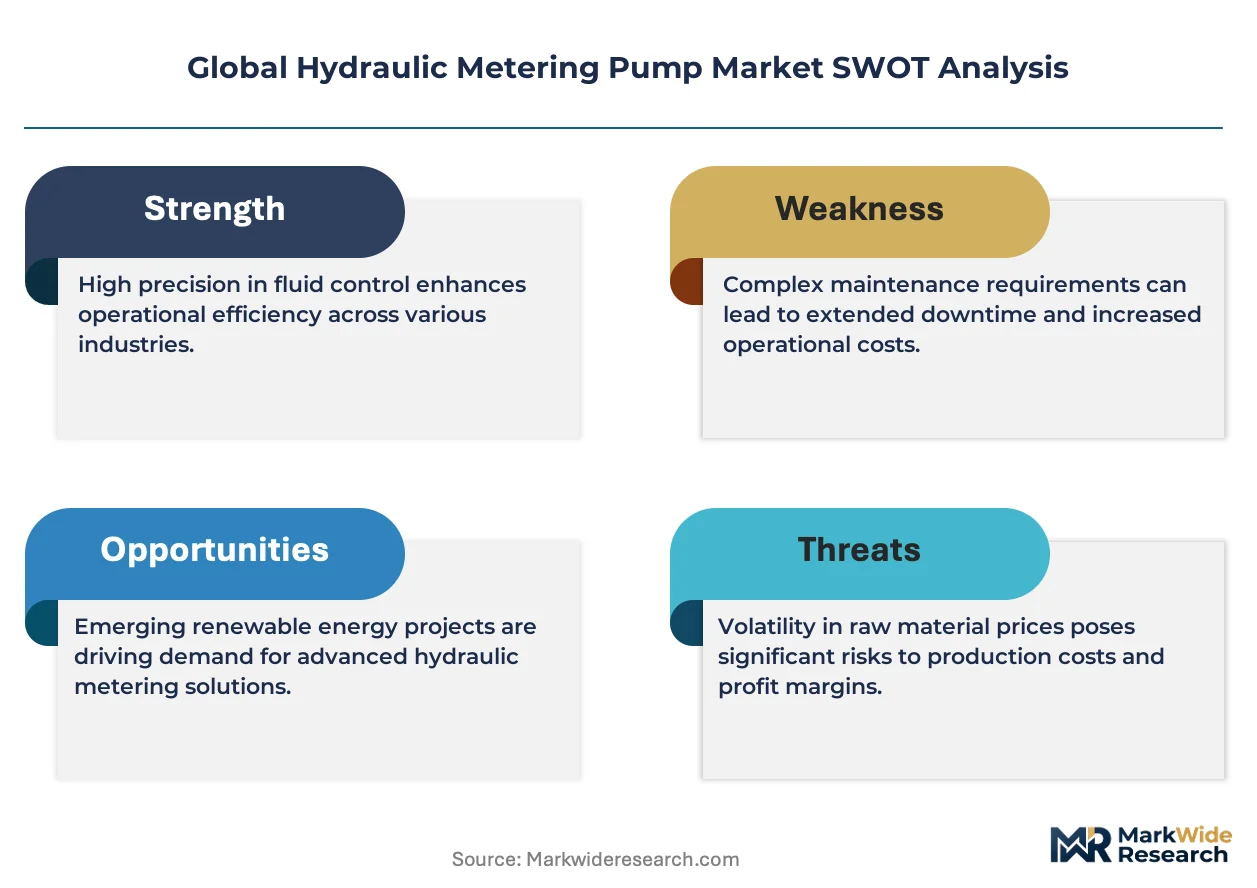
The EPA enforces Clean Water Act effluent limits that mandate accurate chemical dosing at municipal treatment facilities, while REACH and RoHS frameworks in Europe restrict elastomer compositions used in pump sealing systems. FDA cGMP guidelines for pharmaceutical manufacturing impose validation protocols on metering equipment used in active ingredient processing. Stakeholders must weigh material certification costs against the operational risk of non-compliance when specifying pump configurations for regulated environments.
Market Dynamics
Electromechanical variable-speed drives are displacing pneumatic actuation across municipal water treatment infrastructure, compressing replacement cycles and elevating telemetry integration from optional to baseline specification.
Growth Catalysts
- REACH and RoHS frameworks:European chemical processors face mandatory elastomer substitution in pump sealing systems, forcing wholesale equipment refresh cycles across Germany's Rhine-Ruhr industrial belt.
- Diaphragm leak-free containment:Hazardous fluid handling mandates at US petroleum refineries drive specification upgrades toward hydraulic diaphragm architectures over packed-plunger alternatives.
- Southeast Asian discharge standards:Municipal utilities in Thailand, Vietnam, and Indonesia are procuring precision dosing equipment to meet tightening effluent quality thresholds.
Market Restraints
- Specialized alloy input costs:Hastelloy and titanium formulations for corrosive media applications exhibit price volatility tied to nickel and titanium sponge supply concentration.
- Diaphragm material certification timelines:FDA cGMP validation protocols for pharmaceutical manufacturing impose 18-24 month approval cycles on new elastomer compositions.
- Peristaltic pump substitution:Low-pressure chemical dosing applications increasingly specify hose pumps for abrasive slurry handling, compressing addressable volume in mining and mineral processing.
Strategic Opportunities
- Digital monitoring convergence:Integration of vibration sensors and predictive analytics with pump hardware creates recurring revenue streams and vendor lock-in.
- EU F-Gas Regulation phase-down:Refrigeration and HVAC chemical dosing applications face equipment replacement mandates as hydrofluorocarbon service bans accelerate.
- India's municipal water infrastructure:Smart Cities Mission funding channels toward automated chemical dosing at secondary treatment facilities remain underpenetrated by precision pump suppliers.
Industry Challenges
- Hydraulics-mechatronics skill convergence:Maintenance technicians must bridge fluid power expertise with IoT diagnostics, creating recruitment friction for plant operators.
- Legacy SCADA integration complexity:Brownfield installations require protocol translation layers between modern pump controllers and decades-old distributed control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Hydraulic Metering Pump Market |
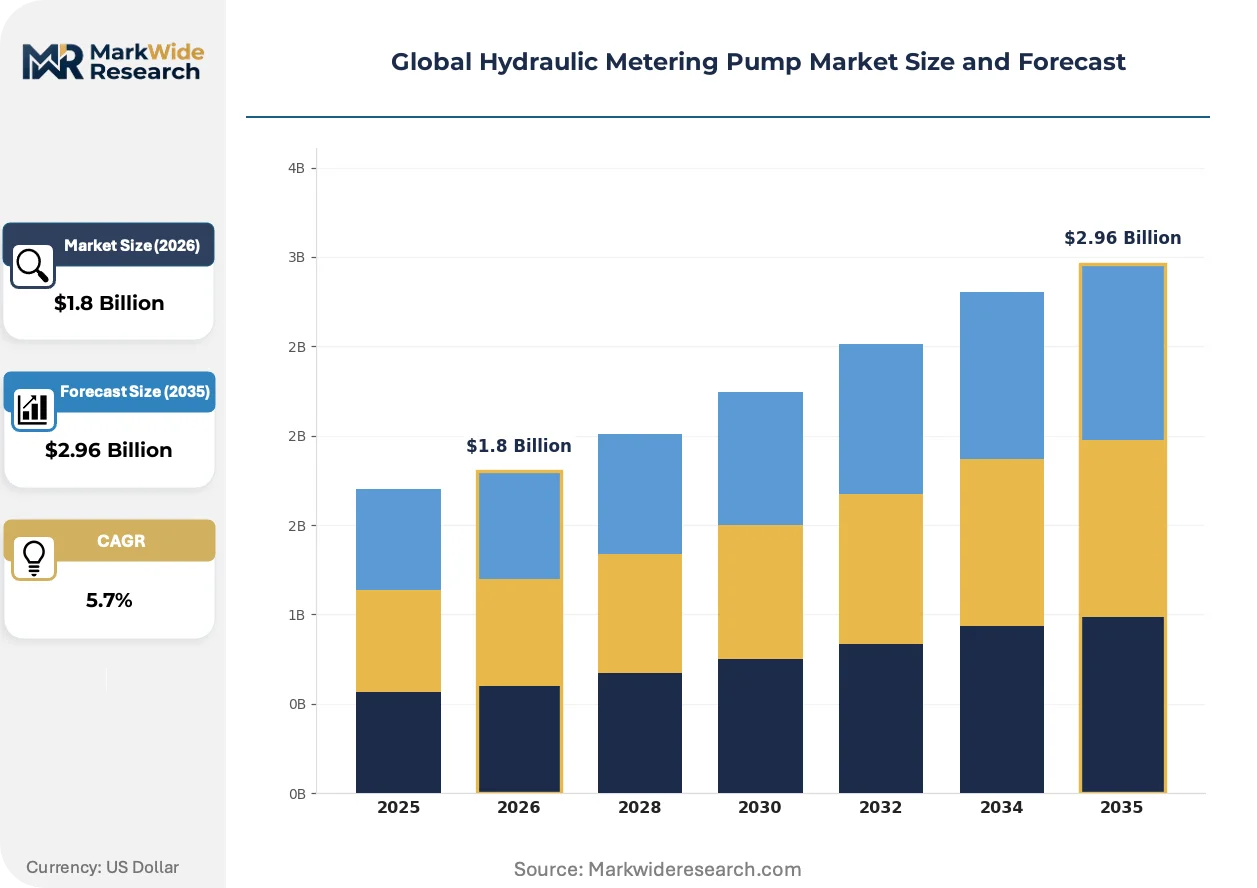
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diaphragm Pumps, Piston Pumps, Gear Pumps, Peristaltic Pumps Technology: Electromechanical, Pneumatic, Hydraulic, Mechanical Industry Vertical: Oil & Gas, Water Treatment, Chemical Processing, Pharmaceuticals End User: Manufacturers, Distributors, Contractors, Utility Companies |
| Companies Covered | IDEX Corporation, Milton Roy, ProMinent, Grundfos Holding A/S, Dover Corporation, LEWA GmbH, Nikkiso Co., Ltd., SPX Flow, Flowserve, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Hydraulic Metering Pump Market Strategic Shifts
Telemetry integration is redefining competitive differentiation as hardware margins compress and aftermarket service contracts become the primary profit pool for pump vendors.
Electromechanical actuation is hybridizing with traditional hydraulic power transmission, enabling stroke-length adjustment via servo motors while retaining the diaphragm's leak-free integrity. Water treatment utilities in the Netherlands and Denmark are specifying these architectures for remote setpoint adjustment. The convergence is compressing demand for pure pneumatic systems and elevating vendor requirements for embedded firmware development.
EPA Clean Water Act enforcement is tightening effluent limit compliance timelines for municipal treatment facilities, mandating redundant dosing accuracy verification. Secondary clarifier operations face the steepest compliance cost escalation. US utilities are responding by consolidating vendor qualification lists toward suppliers with integrated flow-verification instrumentation.
Regional water authority procurement consolidation is narrowing qualified vendor pools as technical specification complexity outstrips smaller manufacturers' certification capabilities. Direct-to-utility distribution is yielding to framework agreements with engineering-procurement-construction contractors. Germany's chemical corridor exhibits the most pronounced buyer concentration, with BASF and Bayer site engineering teams standardizing on pre-qualified pump skids.
Global Hydraulic Metering Pump Market Segmentation
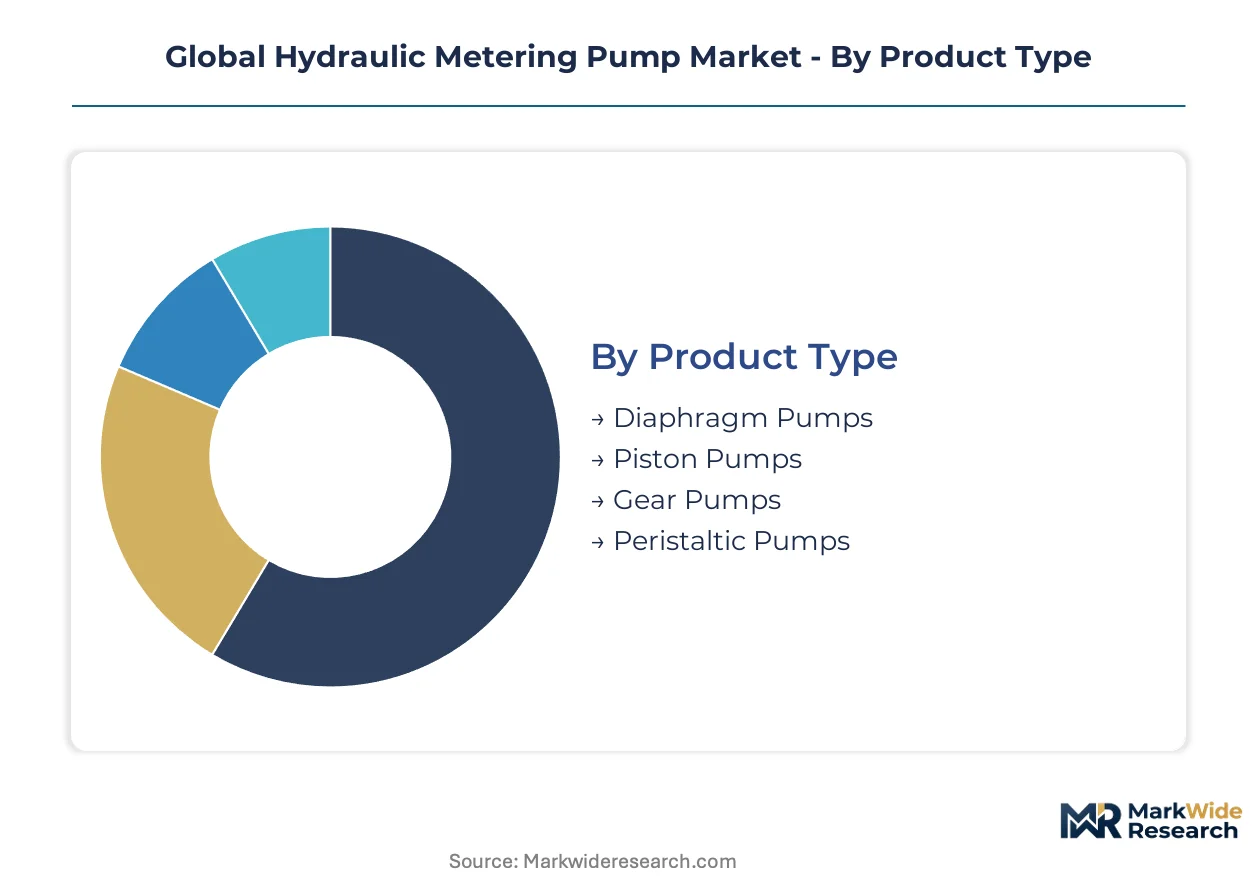
Hydraulic metering pump procurement splits across fluid handling architectures, actuation methods, and regulatory environments. Specification complexity varies sharply between hazardous chemical containment and municipal water dosing applications.
Product Type:
Fluid containment requirements span leak-free hazardous media handling to high-pressure precision injection across process industries.
- Diaphragm Pumps:Hydraulic-actuated diaphragm architectures isolate process fluid from drive mechanisms through elastomer or PTFE membranes. Water treatment utilities in Thailand and Vietnam specify these for chlorine and polymer dosing under tightening discharge standards. REACH and RoHS frameworks in Europe are forcing elastomer substitution cycles across Germany's chemical corridor.
- Piston Pumps:Reciprocating piston designs deliver precise volumetric displacement through hardened cylinder liners and ceramic plungers. Oilfield chemical injection in the US Permian Basin sustains demand for high-pressure configurations. Nickel alloy price volatility constrains specification flexibility for corrosive service.
- Gear Pumps:Positive-displacement rotary mechanisms suit viscous polymer and slurry handling at moderate pressures.
- Peristaltic Pumps:Hose compression designs address abrasive mining slurries but compress hydraulic pump addressability in low-pressure dosing.
Established volume favors diaphragm architectures; emerging adoption favors piston pumps in high-pressure hydrocarbon processing.
Technology:
Actuation method selection trades precision control against maintenance complexity and telemetry integration readiness.
- Electromechanical:Variable-speed servo motors enable stroke-length adjustment and remote setpoint control through embedded controllers. Dutch and Danish water utilities specify these architectures for automated clarifier chemical dosing. Plant operators prioritize these systems for predictive maintenance integration.
- Hydraulic:Traditional fluid power transmission retains dominance in explosive atmosphere classifications and legacy installations. US petroleum refineries maintain substantial installed bases under EPA hazardous fluid handling mandates. Skill convergence requirements between hydraulics and mechatronics create maintenance recruitment friction.
- Pneumatic:Compressed air actuation persists in explosion-proof environments lacking electrical infrastructure.
- Mechanical:Fixed-speed cam and linkage drives occupy cost-sensitive applications with limited adjustment requirements.
Procurement momentum concentrates in electromechanical configurations; pneumatic systems face accelerating displacement in municipal infrastructure.
Industry Vertical:
End-use regulatory intensity and process criticality determine specification grade and replacement cycle velocity.
- Water Treatment:Municipal and industrial effluent compliance drives precision dosing requirements across secondary clarification and disinfection stages. EPA Clean Water Act enforcement tightens redundant accuracy verification mandates. US utilities consolidate vendor qualification lists toward integrated flow-verification suppliers.
- Chemical Processing:Continuous reactor feed and additive injection demand ±1% repeatability under corrosive and high-temperature conditions. BASF and Bayer site engineering teams in Germany's Rhine-Ruhr belt standardize on pre-qualified pump skids. F-Gas Regulation phase-down accelerates equipment replacement in refrigeration chemical loops.
- Oil & Gas:Downstream refining and upstream chemical injection sustain demand for high-pressure containment.
- Pharmaceuticals:FDA cGMP validation protocols impose extended approval timelines on new elastomer compositions.
Replacement cycle velocity peaks in water treatment; validation burden concentrates in pharmaceutical specification.
End User:
Channel structure and procurement authority distribution reshape vendor access and contract economics.
- Utility Companies:Regional water authority consolidation narrows qualified vendor pools as technical specifications outstrip smaller manufacturer certification capabilities. Framework agreements with engineering-procurement-construction contractors displace direct-to-utility distribution. India's Smart Cities Mission channels automation funding toward underpenetrated secondary treatment facilities.
- Contractors:EPC firms aggregate procurement across multiple treatment plant projects, standardizing skid specifications to reduce engineering overhead.
- Manufacturers:Captive chemical processing operations internalize specification authority for integrated process systems.
- Distributors:Inventory and service networks face compression as vendor-direct digital monitoring bundles capture aftermarket value.
Procurement authority concentrates in contractor channels; vendor lock-in strategies target utility direct relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Germany's chemical corridor while Southeast Asian utilities negotiate on standardized specifications. This asymmetry reflects divergent regulatory stringency and procurement consolidation patterns. Manufacturers must calibrate regional strategies against these divergent margin environments.
United States
EPA Clean Water Act enforcement tightens effluent compliance timelines at municipal treatment facilities. Secondary clarifier operations face redundant dosing accuracy verification mandates. The Permian Basin sustains demand for high-pressure chemical injection configurations in upstream oilfield applications.
Germany
REACH and EU F-Gas Regulation frameworks force elastomer substitution cycles across pump sealing systems. BASF and Bayer engineering teams in Ludwigshafen and Leverkusen standardize on pre-qualified pump skids. The Rhine-Ruhr industrial belt exhibits pronounced buyer concentration toward integrated system suppliers.
Thailand
Municipal utilities expand procurement of precision dosing equipment to meet tightening discharge standards. National water authority consolidation narrows qualified vendor pools for chlorine and polymer dosing applications. Bangkok Metropolitan Administration channels infrastructure investment toward automated secondary treatment facilities.
India
Smart Cities Mission funding flows toward automated chemical dosing at underpenetrated secondary treatment facilities. Central Pollution Control Board mandates drive municipal utility modernization across tier-1 and tier-2 cities. Maharashtra and Gujarat industrial clusters generate process industry demand for corrosive media handling configurations.
Netherlands
Water treatment utilities specify electromechanical hybrid architectures for remote setpoint adjustment in clarifier operations. National climate adaptation programs accelerate coastal wastewater infrastructure investment. The Randstad concentration of treatment facilities drives framework contracting with engineering-procurement-construction integrators.
Global Hydraulic Metering Pump Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the value chain. The vendor base organizes around three strategic archetypes: diaphragm technology anchors, electromechanical convergence players, and corrosion-resistant alloy specialists. Consolidation pressure intensifies as telemetry integration requirements exceed smaller manufacturers' firmware development capabilities. Dominant competitive moves include backward integration into sensor hardware and geographic expansion through EPC contractor framework agreements.
Within the diaphragm expertise tier, LEWA GmbH and Milton Roy exemplify premium positioning through specialized material configurations. Grundfos Holding A/S anchors the digital monitoring convergence archetype, bundling predictive analytics with pump hardware to capture recurring revenue streams. These three firms represent distinct strategic vectors: German engineering heritage, alloy specialization for corrosive media, and Scandinavian digital integration leadership.
| Leading Market Players |
|---|
| IDEX Corporation |
| Milton Roy |
| ProMinent |
| Grundfos Holding A/S |
| Dover Corporation |
| LEWA GmbH |
| Nikkiso Co., Ltd. |
| SPX Flow |
| Flowserve |
| Others |
Value Chain & Pricing Dynamics
Ludwigshafen's chemical processing cluster anchors European supply capacity for precision diaphragm pump assemblies, with BASF and Bayer captive demand creating pricing power asymmetries that ripple through downstream distribution channels. REACH-mandated elastomer substitutions compress margins for standard configurations while elevating premiums for certified material grades.
Pricing Analysis
The customization-premium spread separates configured-to-order pump skids from catalog-standard units by a factor reflecting certification burden and engineering overhead. Three-tier pricing structure across premium, standard, and economy levels stratifies by diaphragm material grade and telemetry integration depth. Cost compression in municipal utility segments intensifies as regional water authorities consolidate framework agreements toward volume-discounted procurement. EPC contractors exhibit lowest price sensitivity due to project-margin buffering, while independent distributors face margin erosion from vendor-direct digital monitoring bundles.
Supply Chain Analysis
Export-control regimes on servo motor controllers and precision sensor components limit technology flows from Germany and Japan to certain end-use destinations. Manufacturing concentrates in Germany, China, and the United States, with each hub specializing in distinct performance tiers. Raw material dependencies center on nickel alloys for corrosive service, titanium sponge for high-purity pharmaceutical applications, and specialized elastomer formulations for diaphragm membranes. Single-source vulnerability in Hastelloy feedstock creates procurement risk for high-specification orders. Distribution runs through engineering-procurement-construction integrators for utility-scale projects, while process industry procurement favors direct manufacturer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telemetry platform economics are reshaping vendor-customer relationships as hardware commoditization shifts profit pools toward recurring analytics subscriptions and predictive maintenance contracts.
For Market Incumbents: Harden diaphragm material certification portfolios against REACH elastomer substitution mandates to defend premium positioning in European chemical processing. Deepen backward integration into sensor hardware manufacturing to capture telemetry value streams that would otherwise leak to third-party IIoT vendors. Peristaltic pump substitution in mining applications threatens addressable volume in abrasive slurry handling. For New Entrants and Emerging Players: Pursue India's Smart Cities Mission automation funding at underpenetrated secondary treatment facilities in tier-2 municipalities where incumbent qualification lists remain open. Electromechanical hybrid architectures for remote setpoint adjustment offer the most penetrable specification gap against legacy hydraulic installed bases. Partner with Dutch or Danish water technology integrators to bypass direct utility qualification barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electromechanical convergence players with embedded firmware capabilities over pure-play hydraulic specialists facing skill-recruitment friction. Long-term viability rests on recurring revenue attachment rates rather than unit shipment volumes. Monitor EPC contractor framework agreement consolidation as an inflection signal for vendor lock-in intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Hardware | Captures telemetry value streams that third-party IIoT vendors currently extract from pump deployments. |
| Diaphragm Material Certification Investment | REACH compliance timelines create 18-24 month barriers that certified suppliers exploit for premium pricing. |
| EPC Contractor Framework Agreements | Consolidated procurement authority in Germany's Rhine-Ruhr belt favors pre-qualified skid suppliers. |
| Electromechanical Hybrid Architecture Development | Dutch and Danish utilities specify remote setpoint adjustment capabilities for clarifier automation. |
| India Smart Cities Channel Partnership | Underpenetrated secondary treatment facilities in tier-2 municipalities offer first-mover positioning. |
Study Parameters
Operator-level perspectives from plant maintenance directors, OEM procurement teams, aftermarket service heads, and EPC project engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC 10-K filings, and chemical industry association reports. Bottom-up unit economics triangulated against top-down sector spending estimates to calibrate market sizing.
Scenario-bracketing around regulatory enforcement intensity and raw material price volatility shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include fluid handling architecture, actuation technology, industry vertical, and regional regulatory cluster. CAGRs derived from installed base turnover rates and replacement cycle compression factors, with electromechanical adoption curves and REACH-driven equipment refresh cycles serving as key forecast inputs.
Sensitivities concentrate around nickel alloy price volatility, FDA cGMP validation timeline extensions, and EPC contractor consolidation patterns. Forecasts reflect assumptions on regulatory enforcement continuity and technology substitution thresholds. Cross-checking against customs import data for precision pump classifications is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Grease Pump Market
Pumps and Control Devices
Turbomolecular Pumps Market
Pumps and Control Devices
Brine Tanks Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Asia Pacific Industrial Pumps Market
Pumps and Control Devices
Global Compressor Control Systems Market
Pumps and Control Devices
Seawater Pump Market
Pumps and Control Devices
Cooling Pump Market
Pumps and Control Devices
Water Pump Market
Pumps and Control Devices
Europe Positive Displacement Pumps Market
Pumps and Control Devices
Radial Flow Pump Market
Pumps and Control Devices
Chopper Pumps Market
Pumps and Control Devices
Axial Piston Pumps Market
Pumps and Control Devices
Global Hydrocyclone Market
Pumps and Control Devices
Gasketed Plate Heat Exchanger Market